
 Russia Diabetes Drugs Market | 2026-2036
Russia Diabetes Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Russia Diabetes Drugs Market Analytics
Specialized endocrinology nursing pools is reorganizing how regional clinics scale chronic care delivery across Russia's federal districts. Novo Nordisk A/S anchors its position through deep manufacturing partnerships with domestic API producers. Sanofi Aventis competes by sustaining broad portfolio coverage across both human and analog insulin formulations. Eli Lilly and Company differentiates via concentrated R&D investment in next-generation GLP-1 receptor agonist platforms.
Russia diabetes drugs encompass pharmaceutical agents formulated to regulate blood glucose levels through exogenous insulin replacement, incretin pathway modulation, or renal glucose reabsorption inhibition, with stability profiles typically requiring cold-chain distribution at two to eight degrees Celsius. These therapies serve to prevent microvascular and macrovascular complications in chronic diabetes management. Injectable administration forms retain dominant volume share due to established reimbursement pathways for insulin and GLP-1 agonists, while SGLT2 inhibitors represent the fastest-expanding drug type segment as nephrologists and cardiologists increasingly co-prescribe them for renal protection. Hospital distribution channels capture the largest margin pools through tender-based procurement of high-value analog insulin.
Russia's Ministry of Health and CDSCO-aligned local registration requirements govern market access through mandatory bioequivalence trials and escalating local content quotas. The country's national pharmaceutical regulator enforces GMP inspections that favor manufacturers with domestic fill-finish capabilities. Stakeholders must monitor how import-substitution enforcement alters API sourcing economics and which domestic production partnerships reshape competitive access to regional hospital tenders.
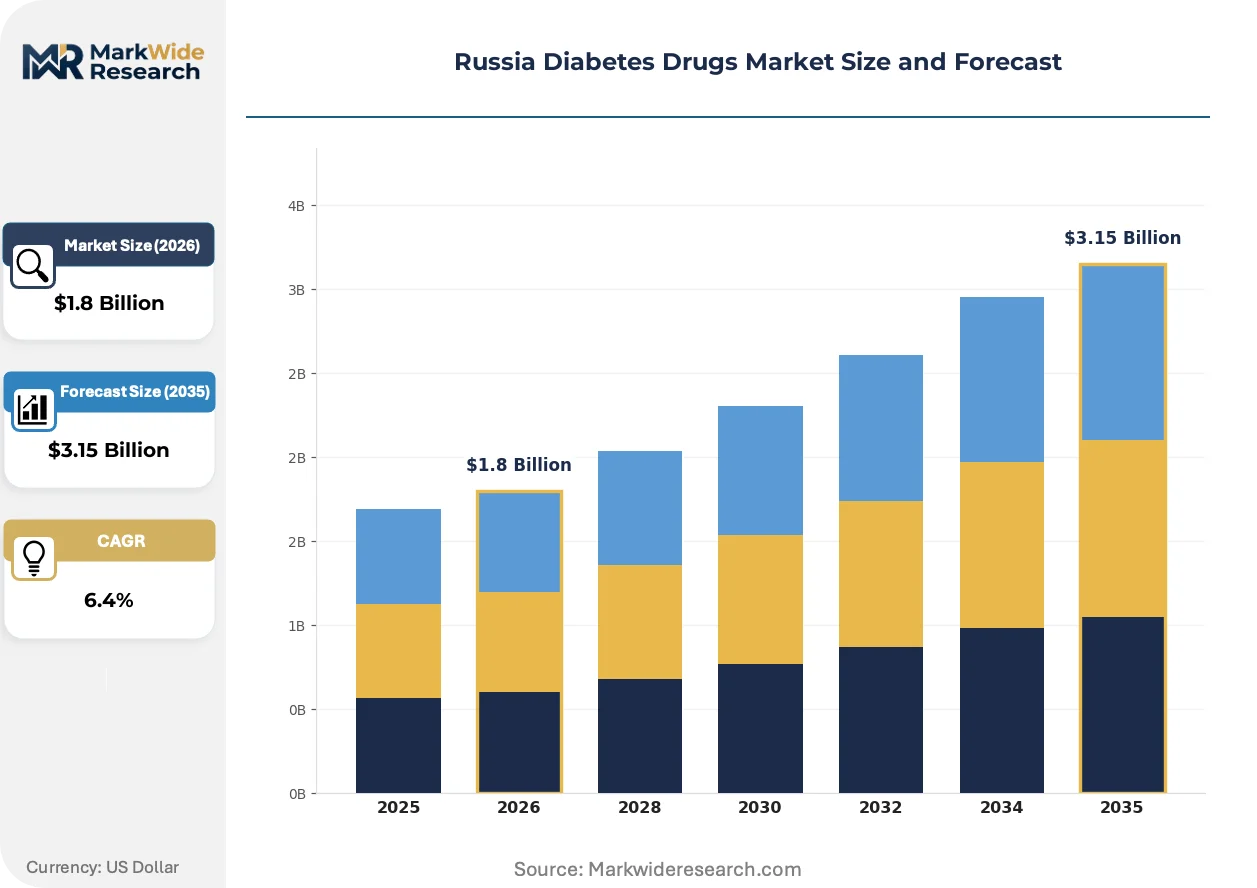
Market Dynamics
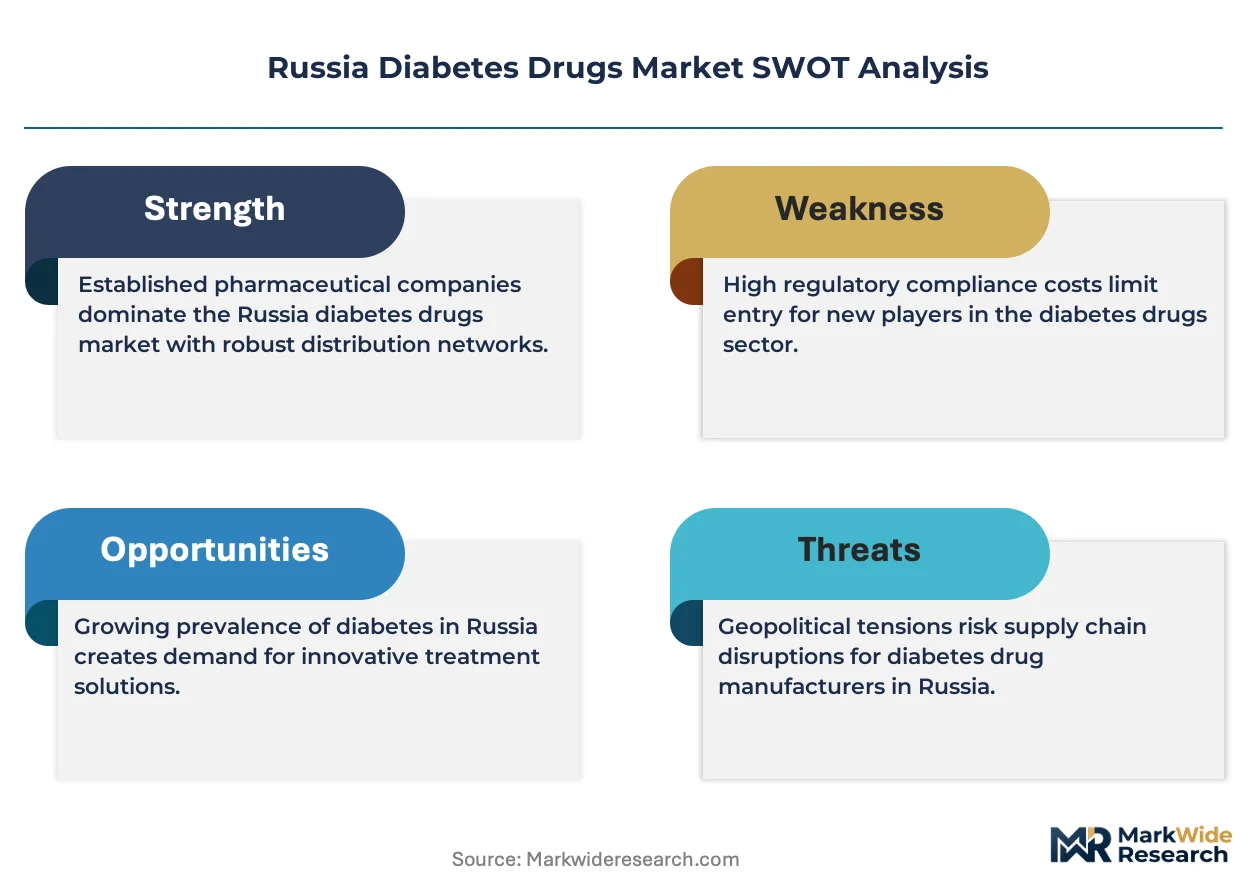
Pharmaceutical import-substitution mandates from Russia's Ministry of Health are forcing multinational manufacturers to restructure API sourcing and establish domestic fill-finish partnerships, compressing traditional import-reliant supply models.
Growth Catalysts
- Local Production Quotas:Escalating domestic content requirements under Ministry of Health directives compel foreign sponsors to partner with Russian API producers, accelerating technology transfer and captive manufacturing capacity.
- Endocrinology Clinic Expansion:Moscow and Saint Petersburg specialized centers are scaling patient intake infrastructure for chronic diabetes management, creating sustained demand pull for injectable therapies.
- GLP-1 Receptor Agonist Protocols:Cardiologists and nephrologists are co-prescribing incretin-based therapies for renal protection, expanding addressable patient pools beyond traditional endocrinology.
Market Restraints
- API Import Dependency:Active pharmaceutical ingredient sourcing concentrates among a limited pool of certified international suppliers, exposing fill-finish operations to customs clearance volatility and currency fluctuation risk.
- Cold-Chain Infrastructure Gaps:Temperature-controlled distribution at two to eight degrees Celsius remains uneven across Siberian and Far Eastern federal districts, limiting therapy access outside major urban clusters.
- Biological Registration Friction:Mandatory bioequivalence trials and CDSCO-aligned local registration requirements extend market entry timelines for novel biologics by eighteen to thirty-six months.
Strategic Opportunities
- Volga Federal District Penetration:Underpenetrated regional markets in Nizhny Novgorod and Kazan present whitespace for specialized endocrinology nursing networks and outpatient insulin delivery models.
- SGLT2 Inhibitor Cardiorenal Positioning:Nephrology and cardiology co-prescription protocols create expansion vectors for sodium-glucose cotransporter-2 inhibitors beyond diabetes monotherapy indications.
- Digital Therapeutics Integration:Remote glucose monitoring platforms and AI-driven dosing algorithms are converging with traditional pharmaceutical regimens, enabling outcome-based reimbursement pilots.
Industry Challenges
- Specialized Nursing Talent Scarcity:Endocrinology nursing pools capable of administering GLP-1 therapies and patient education remain concentrated in Moscow and Saint Petersburg, constraining regional clinic scaling.
- GMP Inspection Compliance Burden:Russia's national pharmaceutical regulator enforces manufacturing standards that favor established domestic fill-finish facilities, creating certification backlogs for new market entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Russia Diabetes Drugs Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Drug Type: Insulin, GLP-1 Agonists, DPP-4 Inhibitors, SGLT2 Inhibitors Administration Form: Injectable, Oral, Inhalable, Patch Patient Demographics: Type 1 Diabetes, Type 2 Diabetes, Gestational Diabetes, Pre-diabetes Distribution Channel: Hospitals, Pharmacies, Online, Clinics |
| Companies Covered | Merck & Co., Pfizer, Novo Nordisk A/S, Janssen Pharmaceuticals, Boehringer Ingelheim, Sanofi Aventis, AstraZeneca, Takeda, Eli Lilly and Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Russia Diabetes Drugs Market Evolving Landscape
Next-generation diabetes management is converging around device-drug integration, regulatory localization mandates, and shifting site-of-care economics that redistribute margin pools between hospital tenders and outpatient channels.
Continuous glucose monitoring systems paired with automated insulin delivery algorithms are supplanting conventional self-monitoring blood glucose protocols in high-volume endocrinology clinics. Moscow's leading hospital networks are adopting these closed-loop systems for Type 1 diabetes populations. The technology is compressing hypoglycemic event rates and enabling tighter glycemic control benchmarks that reshape reimbursement qualification criteria.
Russia's Ministry of Health has tightened GMP inspection protocols and local content quotas under pharmaceutical import-substitution frameworks. Foreign manufacturers must now demonstrate domestic fill-finish capabilities and API partnership documentation to qualify for regional hospital tenders. Analog insulin and GLP-1 agonist categories face the steepest compliance recalibration as established players restructure supply contracts.
Hospital procurement committees are consolidating insulin purchasing through centralized tender platforms, disintermediating traditional distributor networks. The Central Federal District's largest endocrinology centers are negotiating multi-year supply agreements directly with manufacturers possessing domestic production certificates. This concentration is most visible in Moscow's municipal health system, where volume commitments now determine formulary placement and pricing bandwidth.
Russia Diabetes Drugs Market Segmentation
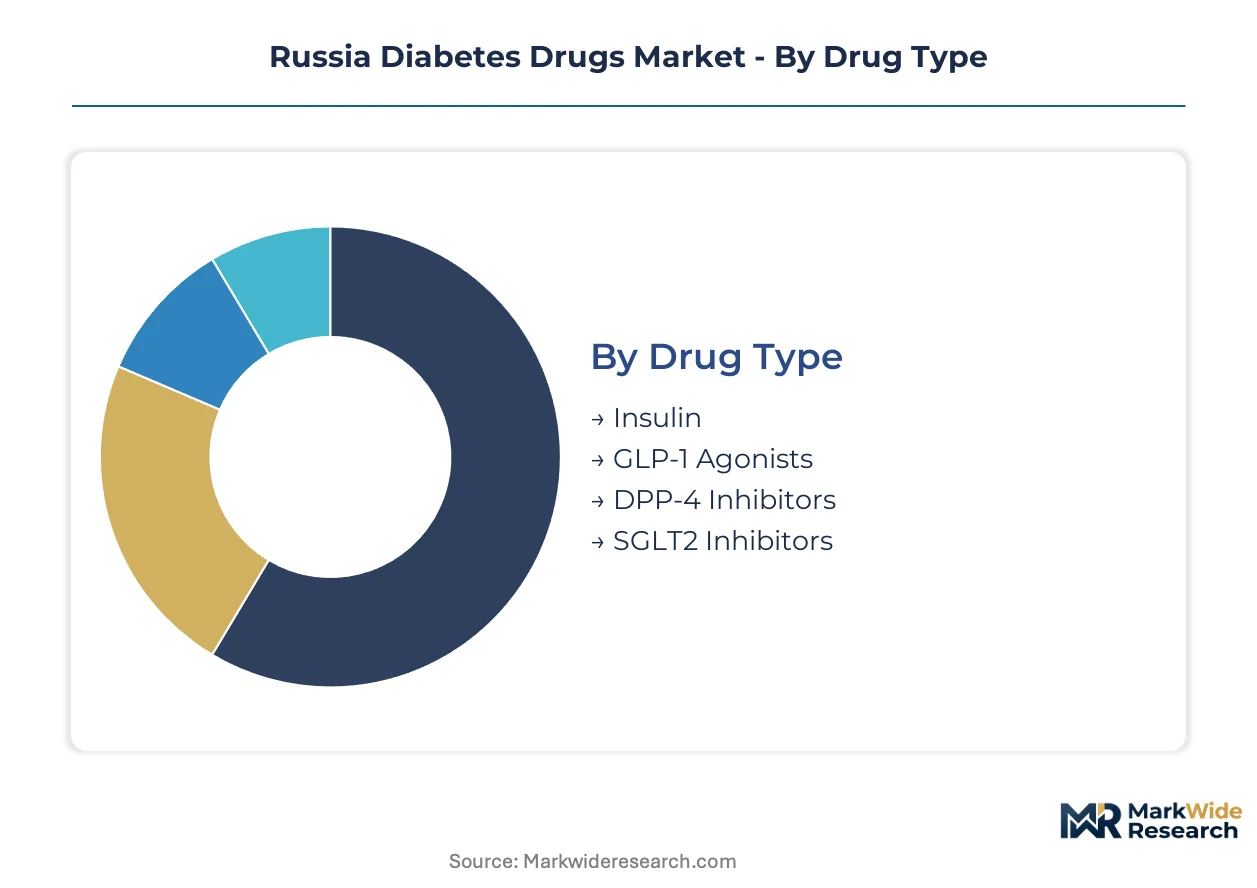
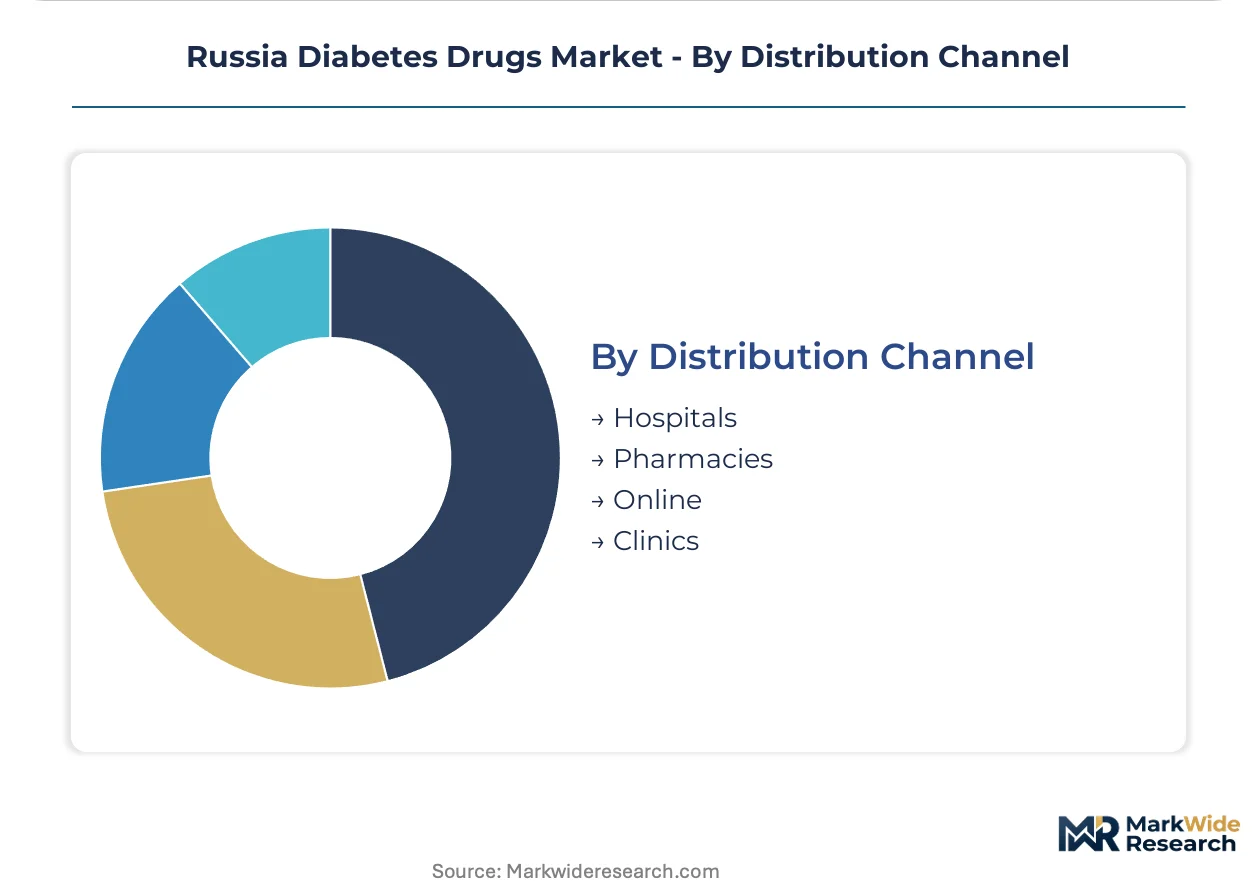
Pharmaceutical import-substitution mandates from Russia's Ministry of Health are reshaping segment-level economics across drug types and distribution channels. Manufacturers must align portfolio depth with domestic fill-finish capabilities and regional cold-chain reach.
Drug Type:
Substitute pressure concentrates most intensely where cardiology and nephrology co-prescription protocols expand therapeutic alternatives beyond traditional endocrinology pathways.
- Insulin:Human and analog formulations require cold-chain distribution at two to eight degrees Celsius. Moscow's municipal health system anchors procurement volume through centralized tender platforms that favor manufacturers with domestic production certificates.
- SGLT2 Inhibitors:Sodium-glucose cotransporter-2 inhibitors modulate renal glucose reabsorption. Cardiologists across the Central Federal District are expanding co-prescription for renal protection, driving the steepest demand expansion among all drug types.
- GLP-1 Agonists:Incretin-based therapies stimulate glucose-dependent insulin secretion. Regional clinic scaling in Saint Petersburg concentrates specialized nursing capacity for injectable administration.
- DPP-4 Inhibitors:Dipeptidyl peptidase-4 inhibitors extend endogenous incretin activity. Oral administration routes suit outpatient protocols in Siberian districts with limited cold-chain infrastructure.
Insulin anchors the volume base while SGLT2 inhibitors gain share at the steepest rate.
Administration Form:
Cost tier differentiation separates premium device-integrated delivery systems from economy vial-syringe formats across regional reimbursement schedules.
- Injectable:Vial and pen formulations dominate hospital procurement through established reimbursement pathways. The Central Federal District's endocrinology clinics are scaling patient intake infrastructure specifically for insulin and GLP-1 delivery.
- Oral:Tablet formulations of DPP-4 inhibitors and SGLT2 inhibitors bypass cold-chain constraints. Pharmacies in Nizhny Novgorod and Kazan are expanding shelf space for oral antidiabetic portfolios.
- Inhalable:Pulmonary insulin delivery systems require specialized patient training. Limited adoption concentrates in Moscow's premium private clinic networks.
- Patch:Transdermal delivery platforms integrate continuous glucose monitoring with automated dosing algorithms. Pilot programs are active in Saint Petersburg's leading hospital networks.
Injectable formats retain the dominant volume position while oral administration climbs fastest outside major urban clusters.
Patient Demographics:
Application severity stratifies treatment intensity from acute insulin dependence to preventive metabolic management across Russia's federal districts.
- Type 2 Diabetes:Progressive beta-cell dysfunction drives chronic pharmaceutical intervention. The Central Federal District concentrates the largest diagnosed patient pools requiring combination therapy protocols.
- Type 1 Diabetes:Absolute insulin deficiency mandates exogenous replacement. Closed-loop automated delivery systems are penetrating Moscow's pediatric endocrinology centers.
- Gestational Diabetes:Transient glucose intolerance during pregnancy requires short-term glycemic control. Regional obstetric clinics in the Volga Federal District are expanding screening capacity.
- Pre-diabetes:Impaired glucose tolerance precedes formal diagnosis. Lifestyle intervention programs in Saint Petersburg are integrating pharmacological prevention pilots.
Type 2 diabetes anchors the volume base while pre-diabetes represents the fastest-expanding addressable pool.
Distribution Channel:
Margin concentration favors direct manufacturer engagement with hospital procurement committees over traditional distributor networks.
- Hospitals:Tender-based procurement of high-value analog insulin captures the largest margin pools. The Central Federal District's municipal health system is negotiating multi-year supply agreements with domestic production certificate holders.
- Pharmacies:Retail dispensing of oral antidiabetics extends reach into secondary cities. Cold-chain gaps in Siberian and Far Eastern districts limit insulin availability through this channel.
- Clinics:Specialized endocrinology centers in Moscow and Saint Petersburg concentrate GLP-1 therapy administration. Nursing talent scarcity constrains regional clinic scaling.
- Online:Digital pharmacy platforms are piloting temperature-controlled last-mile delivery. Regulatory frameworks for biological product e-commerce remain under development by Russia's national pharmaceutical regulator.
Hospitals anchor the volume base while online channels are climbing fastest in pilot urban markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price negotiation leverage concentrates in Moscow's municipal health system while regional procurement committees in Siberia and the Far East accept higher per-unit costs due to cold-chain logistics constraints. This asymmetry redistributes manufacturer margin pools toward the Central Federal District.
Central Federal District
Moscow's endocrinology clinics anchor national demand for analog insulin and GLP-1 receptor agonists through centralized tender platforms. Russia's Ministry of Health enforces domestic production certificate requirements that disqualify import-reliant suppliers from municipal hospital contracts. The Moscow-Saint Petersburg corridor concentrates specialized nursing pools capable of administering complex injectable therapies.
Volga Federal District
Nizhny Novgorod and Kazan present underpenetrated addressable pools for oral antidiabetic expansion as cold-chain gaps limit insulin penetration. Regional health authorities are expanding outpatient clinic networks under federal chronic disease management programs. Pharmaceutical distributors are establishing temperature-controlled warehousing in Samara to bridge last-mile gaps.
Siberian Federal District
Novosibirsk anchors regional diabetes treatment capacity through its specialized endocrinology center, though patient volumes trail per-capita diagnosis rates in European Russia. The national pharmaceutical regulator has approved pilot programs for DPP-4 inhibitor substitution where cold-chain infrastructure cannot sustain insulin distribution. Krasnoyarsk is emerging as a regional hub for oral antidiabetic dispensing.
Northwestern Federal District
Saint Petersburg's hospital networks are adopting closed-loop automated insulin delivery systems for Type 1 diabetes populations. The city's procurement committees negotiate directly with manufacturers holding domestic fill-finish certificates, bypassing traditional distributor markups. Regional cardiology centers are expanding SGLT2 inhibitor co-prescription protocols for renal protection.
Southern Federal District
Rostov-on-Don and Krasnodar are scaling patient intake infrastructure for Type 2 diabetes combination therapies. Russia's import-substitution mandates have accelerated partnerships between regional distributors and domestic API producers. The district's pharmacy networks are expanding shelf space for SGLT2 inhibitors as nephrology referral pathways mature.
Russia Diabetes Drugs Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the Russia diabetes drugs market, creating a tiered competitive structure. The vendor base clusters around multinational innovators with biologic pipelines, generic manufacturers with domestic fill-finish capabilities, and regional distributors with cold-chain infrastructure. Three archetypes dominate: R&D-intensive biologics specialists, cost-optimized local production partners, and integrated hospital tender operators. Competitive moves concentrate on strategic partnerships for API sourcing and capacity expansion for domestic manufacturing certificates.
Within the multinational biologics tier, Novo Nordisk A/S and Eli Lilly and Company anchor positions through concentrated R&D investment in next-generation GLP-1 receptor agonist platforms. Sanofi Aventis occupies a position exemplifying broad portfolio coverage across human and analog insulin formulations. These players represent the technology leadership archetype, though their market access depends on restructuring supply contracts to satisfy Russia's escalating local content quotas.
| Leading Market Players |
|---|
| Merck & Co. |
| Pfizer |
| Novo Nordisk A/S |
| Janssen Pharmaceuticals |
| Boehringer Ingelheim |
| Sanofi Aventis |
| AstraZeneca |
| Takeda |
| Eli Lilly and Company |
| Others |
Value Network & Pricing Analysis
Ninety-day API inventory buffers now separate tender-qualified manufacturers from import-dependent competitors, concentrating pricing power with domestic fill-finish certificate holders while compressing margins for cold-chain-reliant suppliers across Russia's federal districts.
Pricing Analysis
Moscow's municipal health system commands a fifteen to twenty percent price discount versus Siberian regional procurement committees due to consolidated volume commitments and direct manufacturer negotiations. Three-tier pricing structure across premium analog insulin, standard human insulin, and economy vial formats stratifies reimbursement schedules. Cost compression in the economy tier is intensifying because regional distributors absorb cold-chain logistics premiums to maintain formulary access. Municipal hospital networks exhibit the lowest price sensitivity while Far Eastern district pharmacies face acute budget constraints.
Supply Chain Analysis
Domestic API inventory cycles stretching to one hundred twenty days expose fill-finish operations to customs clearance volatility at Russian border checkpoints. Active pharmaceutical ingredient sourcing concentrates in India, China, and selected European Union member states for certified insulin and GLP-1 agonist precursors. Supply chains rest on recombinant DNA fermentation substrates, specialized bioreactor components, and temperature-controlled packaging materials. Single-source vulnerability pervades certified excipient suppliers for biological stability profiles. Distribution runs through hospital tender platforms in the Central Federal District, pharmacy networks in secondary cities, and emerging digital pharmacy pilots in Moscow and Saint Petersburg.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Russia's pharmaceutical import-substitution mandates are disrupting traditional multinational supply models, creating acceleration windows for domestic manufacturing partnerships and technology-transfer arrangements.
For Market Incumbents: Secure domestic fill-finish certificate coverage across multiple federal districts before regional tender consolidation hardens. Anchor API partnerships with Russian producers to satisfy escalating local content quotas. Defensive positioning requires backward integration into fermentation capacity and captive cold-chain warehousing in Novosibirsk and Kazan. The threat of exclusion from Moscow's municipal health system tenders demands preemptive compliance investment. For New Entrants and Emerging Players: CDSCO-aligned bioequivalence fast-track pathways offer the most viable market entry vector for generic analog insulin and DPP-4 inhibitor portfolios. Whitespace concentrates in the Volga Federal District's outpatient clinic networks and Siberian oral antidiabetic substitution programs. Target nephrology co-prescription protocols for SGLT2 inhibitors as cardiorenal positioning separates premium from commodity positioning. Direct-to-clinic distribution partnerships bypass entrenched hospital tender barriers. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory arbitrage play because import-substitution enforcement creates captive demand for domestic manufacturing capacity. Acquisition targets center on mid-scale API producers with GMP inspection track records and established relationships with Russia's national pharmaceutical regulator. The signal to watch is Ministry of Health local content quota escalation rates, which determine technology transfer economics and partnership valuation multiples.| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Fill-Finish Certificate Acquisition | Qualifies manufacturers for Moscow municipal hospital tenders under Ministry of Health mandates. |
| API Partnership Documentation | Satisfies escalating local content quotas for regional procurement committee access. |
| Cold-Chain Warehousing Expansion | Bridges last-mile gaps in Siberian and Far Eastern federal districts for insulin distribution. |
| Cardiorenal Co-Prescription Protocol Development | Positions SGLT2 inhibitors for nephrology and cardiology expansion beyond endocrinology. |
| Digital Therapeutics Integration | Enables outcome-based reimbursement pilots with remote glucose monitoring platforms. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and formulary directors; and secondary validation against EMA submissions, ClinicalTrials.gov records, Russian Ministry of Health tender databases, and customs import data. Bottom-up patient volume modeling and top-down pharmaceutical expenditure triangulation anchored market sizing across drug type, administration form, and distribution channel dimensions.
Across the analysis window, the forecasting framework modeled treatment line progression, dosage form adoption curves, regional regulatory cluster variations, and patient demographic shifts. CAGRs were derived from segmented volume projections calibrated to tender award patterns and reimbursement schedule evolution. Industry-specific inputs included bioequivalence trial timelines, GMP inspection clearance rates, and cold-chain infrastructure deployment maps.
Underlying assumptions cover sustained import-substitution enforcement, stable API sourcing relationships, and incremental cold-chain investment in secondary cities, with deviation risk concentrated in currency fluctuation impacts on API costs and regulatory acceleration of local content quotas. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Global Pulmonary Drugs Market
Pharmaceuticals
Europe Alpha-Glucosidase Inhibitors Market
Pharmaceuticals
2-Valent HPV Vaccine (2vHPV) Market
Pharmaceuticals
Global Doxorubicin Market
Pharmaceuticals
Global Pneumococcal Vaccines Market
Pharmaceuticals
Bevacizumab Market
Pharmaceuticals
Cefdinir API Market
Pharmaceuticals
Small Molecules Contract Development and Manufacturing Organization Market
Pharmaceuticals
Over the Counter (OTC) Drugs Market
Pharmaceuticals
Fertility Drug and Surgery Market
Pharmaceuticals
United Kingdom OTC Drugs Market
Pharmaceuticals
Large Volume Parenteral (LVP) Market
Pharmaceuticals
Spain OTC Drugs Market
Pharmaceuticals
Germany Opioids Market
Pharmaceuticals
Global Lipid Disorder Treatment Market
Pharmaceuticals
Global Pharmacy Benefit Management (PBM) Market