
 Europe Textured Vegetable Protein Market | 2026-2036
Europe Textured Vegetable Protein Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Textured Vegetable Protein Market Foresight
Premium-grade extruded protein specifications is unwinding conventional commodity positioning across the European supply base. ADM leverages its continental crushing and extrusion network to secure non-GMO soybean supply corridors into the Netherlands and Germany. Roquette Freres anchors pea protein textured volumes through its Vic-sur-Aisne facility, while Beneo GmbH specializes in clean-label wheat protein isolates for Central European meat analog producers.
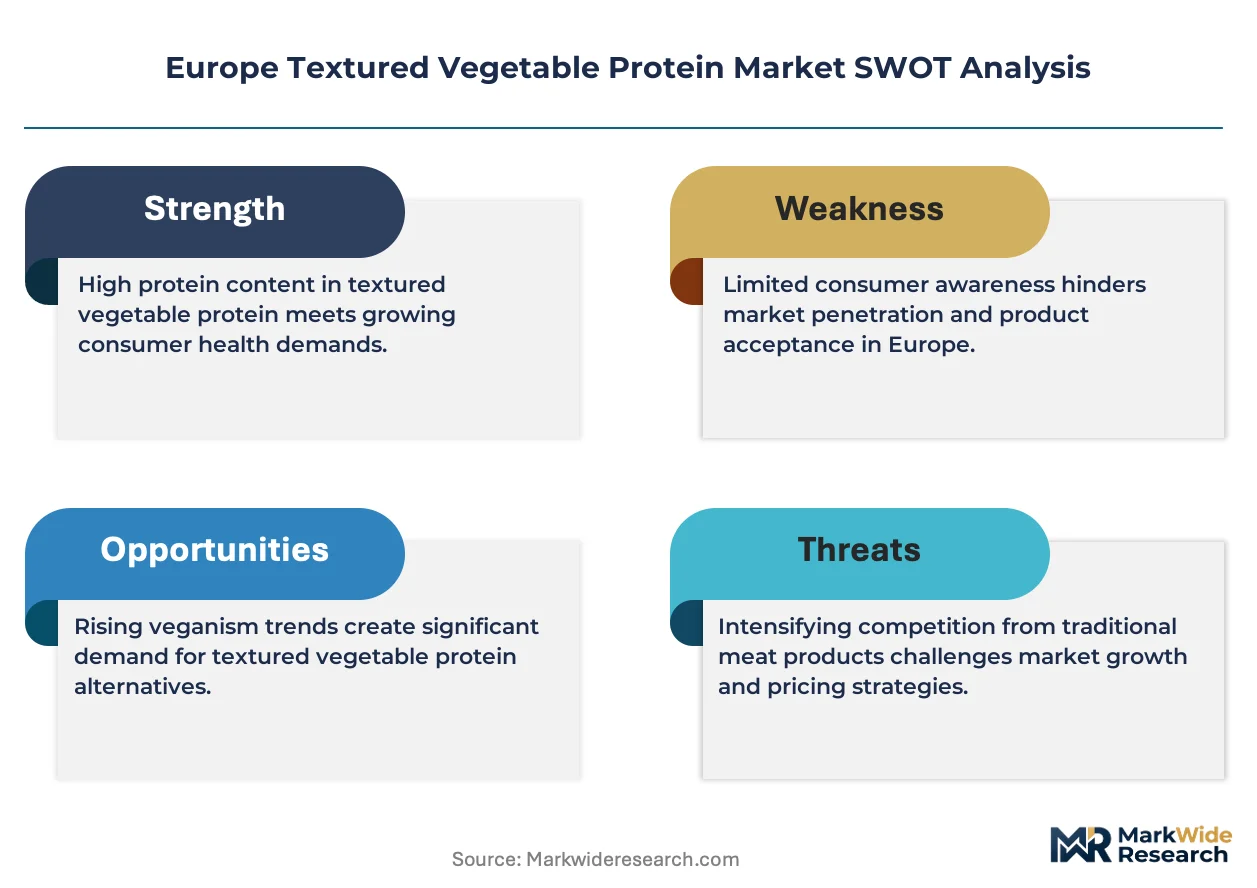
Textured vegetable protein denotes defatted and extruded plant matter, typically achieving 50-80% protein content on a dry basis through thermoplastic extrusion that aligns protein fibrils into meat-like matrices. Its primary commercial purpose is to replicate chew density and water-holding capacity in formulated meat alternatives and extended ground products. Soy protein chunks currently dominate institutional food service procurement across the region, while pea protein granules represent the fastest-growing form factor as allergen-free positioning gains traction among Nordic and British retail brands. Powdered wheat protein occupies a mature niche in bakery and snack applications where gluten functionality remains irreplaceable.
EFSA novel food assessments and EU Green Deal farm-to-fork targets shape ingredient approval timelines and carbon disclosure obligations for textured protein suppliers. REACH compliance on processing aids and the F-Gas Regulation governing extrusion cooling systems add layered compliance costs that favor scaled manufacturers with dedicated regulatory affairs teams. Stakeholders must monitor how the EU AI Act and impending digital product passport requirements will reshape traceability investments across oilseed-to-extrudate supply chains.
Market Dynamics
Carbon disclosure mandates under the EU Green Deal are rewiring procurement criteria across European food manufacturing, forcing textured protein suppliers to document farm-to-extrudate emissions or forfeit contracts with reformulating meat processors.
Growth Catalysts
- EU Green Deal farm-to-fork targets:Mandatory carbon footprint thresholds for food ingredients are accelerating textured protein adoption as meat analog manufacturers seek compliant supply chains.
- Clean-label reformulation:Consumer preference for short ingredient lists is pulling wheat and pea protein isolates into Central European meat processing facilities at the expense of synthetic binders.
- Netherlands-Germany corridor concentration:Proximity of extrusion capacity to oilseed crushing infrastructure is compressing logistics costs for textured soy protein deliveries to plant-based meat hubs.
Market Restraints
- Non-GMO soybean supply concentration:Dependence on certified Ukrainian and Black Sea origin soybeans creates input volatility when geopolitical disruptions constrain oilseed flows.
- REACH compliance costs:Registration requirements for extrusion processing aids and lubricants impose fixed regulatory burdens that disproportionately burden smaller extrusion operators.
- Gluten functionality limits:Wheat protein's irreversible allergen classification blocks penetration into Nordic free-from product lines where pea protein captures shelf space.
Strategic Opportunities
- Polish and Romanian food manufacturing:Underdeveloped textured protein penetration in Eastern European meat processing creates first-mover positioning for extruded pea protein suppliers.
- Digital product passport alignment:Early investment in blockchain-tracked supply chain documentation will satisfy impending EU traceability mandates before compliance becomes table stakes.
- High-moisture extrusion convergence:Integration of cooling die technology with traditional dry extrusion lines enables whole-muscle analog production previously confined to wet fractionation systems.
Industry Challenges
- Thermoplastic extrusion engineering talent:Scarcity of process engineers capable of optimizing protein fibril alignment under variable moisture conditions constrains capacity expansion timelines.
- F-Gas Regulation cooling system retrofits:Replacement of hydrofluorocarbon-based extrusion chillers with compliant alternatives demands capital outlays that erode marginal producer economics.
- EFSA novel food dossier preparation:Compilation of toxicology and digestibility data for emerging protein sources extends approval timelines beyond typical product development cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Textured Vegetable Protein Market |
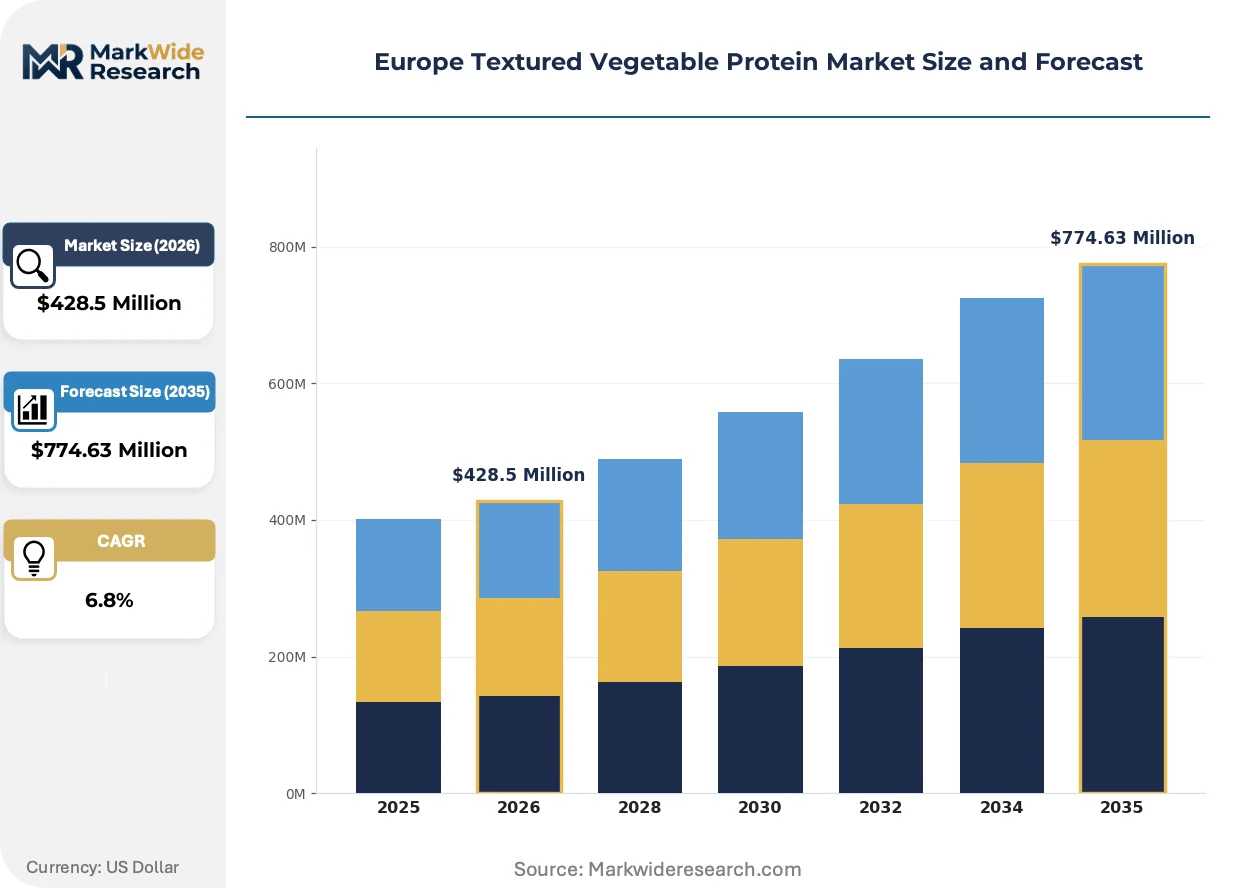
| Market Size in 2026 | $428.5 Million |
| Market Size in 2035 | $774.63 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Soy Protein, Pea Protein, Wheat Protein, Others Application: Meat Alternatives, Snacks, Protein Ingredients, Dairy Alternatives End User: Food Manufacturers, Retailers, Restaurants, Food Service Providers Form: Granules, Chunks, Flakes, Powder |
| Companies Covered | Ingredion Inc, ADM, GEMEF Industries, International Flavors & Fragrances Inc, Cargill Incorporated, Sudzucker AG, Beneo GmbH, ICL Group Ltd, Roquette Freres, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Textured Vegetable Protein Market Shifts & Advancements
Extrusion technology advancement and regulatory traceability requirements are converging to redefine competitive advantage in European textured protein supply, shifting value capture toward integrated processors with documented low-carbon supply chains.
High-moisture extrusion is decomposing the traditional separation between dry texturized concentrates and wet-processed isolates. Scandinavian meat analog manufacturers are retrofitting cooling die systems onto existing extrusion lines within eighteen-month implementation windows. This technology convergence is compressing the premium historically commanded by wet-fractionated protein ingredients.
REACH authorization timelines for processing aids are extending qualification periods for new extrusion lubricants and mold-release compounds. The F-Gas Regulation's phase-down schedule is forcing cooling system replacements ahead of typical equipment depreciation cycles. Central European extrusion facilities are responding by consolidating regulatory affairs functions across multi-site networks to amortize compliance overhead.
Retail buyer consolidation is compressing supplier negotiation cycles across British and German grocery chains. Direct contracting between supermarket own-label teams and extrusion processors is displacing traditional ingredient distributor intermediaries. This channel restructuring is most visible in the United Kingdom where Tesco and Sainsbury's sustainability procurement teams now specify farm-level carbon data as a mandatory bid requirement.
Europe Textured Vegetable Protein Market Segmentation
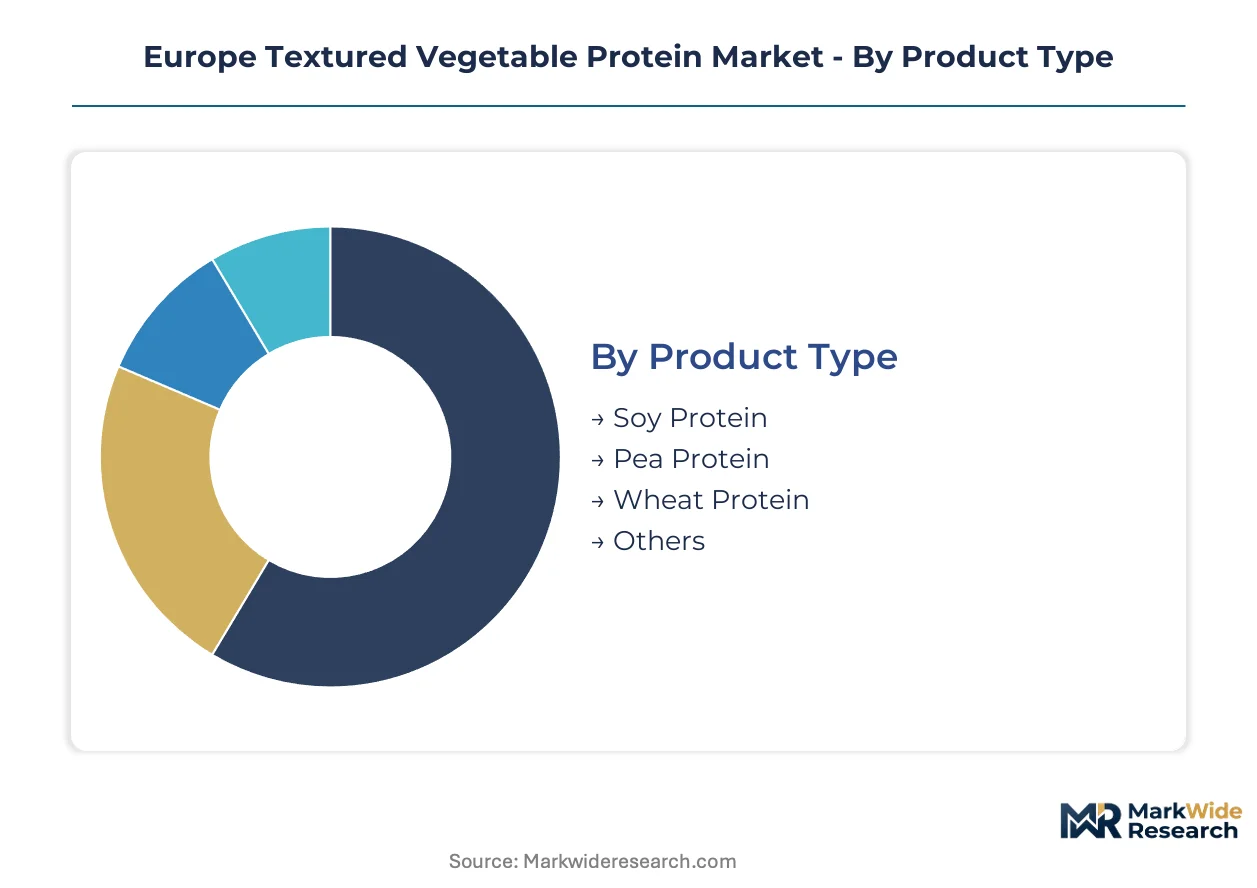
Segmentation in the Europe textured vegetable protein market reveals how regulatory frameworks, functional specifications, and procurement channels fragment supply strategies. Manufacturers must align extrusion capabilities with distinct end-use requirements while navigating EFSA novel food classifications and carbon disclosure mandates.
Product Type:
REACH registration thresholds and EFSA novel food dossier requirements differentiate compliance burdens across protein sources, favoring established supply chains with documented toxicology profiles.
- Soy Protein:Defatted soybean meal extruded into fibrous matrices achieves 50-80% protein content with established water-holding capacity. German and Dutch plant-based meat manufacturers anchor procurement volumes here, though non-GMO certification requirements from Black Sea origin soybeans create supply volatility during geopolitical disruptions.
- Pea Protein:Yellow pea isolate extrusion yields allergen-free fibril structures with neutral flavor profiles. Nordic and British retail brands concentrate demand here as clean-label positioning accelerates, with Roquette Freres' Vic-sur-Aisne facility anchoring continental supply.
- Wheat Protein:Vital wheat gluten extrusion leverages existing bakery supply infrastructure across Central Europe.
- Others:Emerging sources including fava bean and oat protein concentrates face extended EFSA approval timelines.
Established volume favors soy protein; emerging adoption favors pea protein.
Application:
Carbon footprint disclosure obligations under the EU Green Deal reshape procurement priorities, with meat analog applications commanding the most stringent farm-to-extrudate documentation.
- Meat Alternatives:High-moisture extrusion of soy and pea proteins into whole-muscle analogs requires cooling die technology investments. British and German supermarket sustainability teams now mandate supplier carbon data, compressing negotiation cycles and displacing traditional distributors.
- Snacks:Dry-extruded protein crisps and puffed formats utilize lower-cost concentrates with shorter ingredient lists. Central European co-manufacturers favor wheat protein here for gluten functionality in savory applications.
- Protein Ingredients:Intermediate textured concentrates supply bakery and nutrition bar formulators seeking fortification without full meat replication.
- Dairy Alternatives:Textured proteins in fermented analogs remain niche due to solubility constraints versus isolate preferences.
Margin concentration sits with meat alternatives; volume expansion runs through snacks.
End User:
Direct contracting patterns diverge sharply between consolidated retail buyers and fragmented food service procurement channels.
- Food Manufacturers:Industrial meat processors across Germany and the Netherlands drive specification-grade procurement with reformulation mandates tightening. These buyers integrate textured proteins into extended ground products and analog lines, requiring consistent fibril alignment and documented carbon footprints.
- Retailers:Tesco and Sainsbury's sustainability teams in the United Kingdom specify farm-level traceability as mandatory bid criteria, collapsing traditional distributor intermediaries.
- Restaurants:Quick-service chains in France and Spain test limited plant-based menu items with commodity-grade soy chunks.
- Food Service Providers:Institutional caterers across Nordic countries prioritize allergen-free pea protein for school and hospital contracts.
Procurement leverage concentrates with retailers; technical specification depth favors food manufacturers.
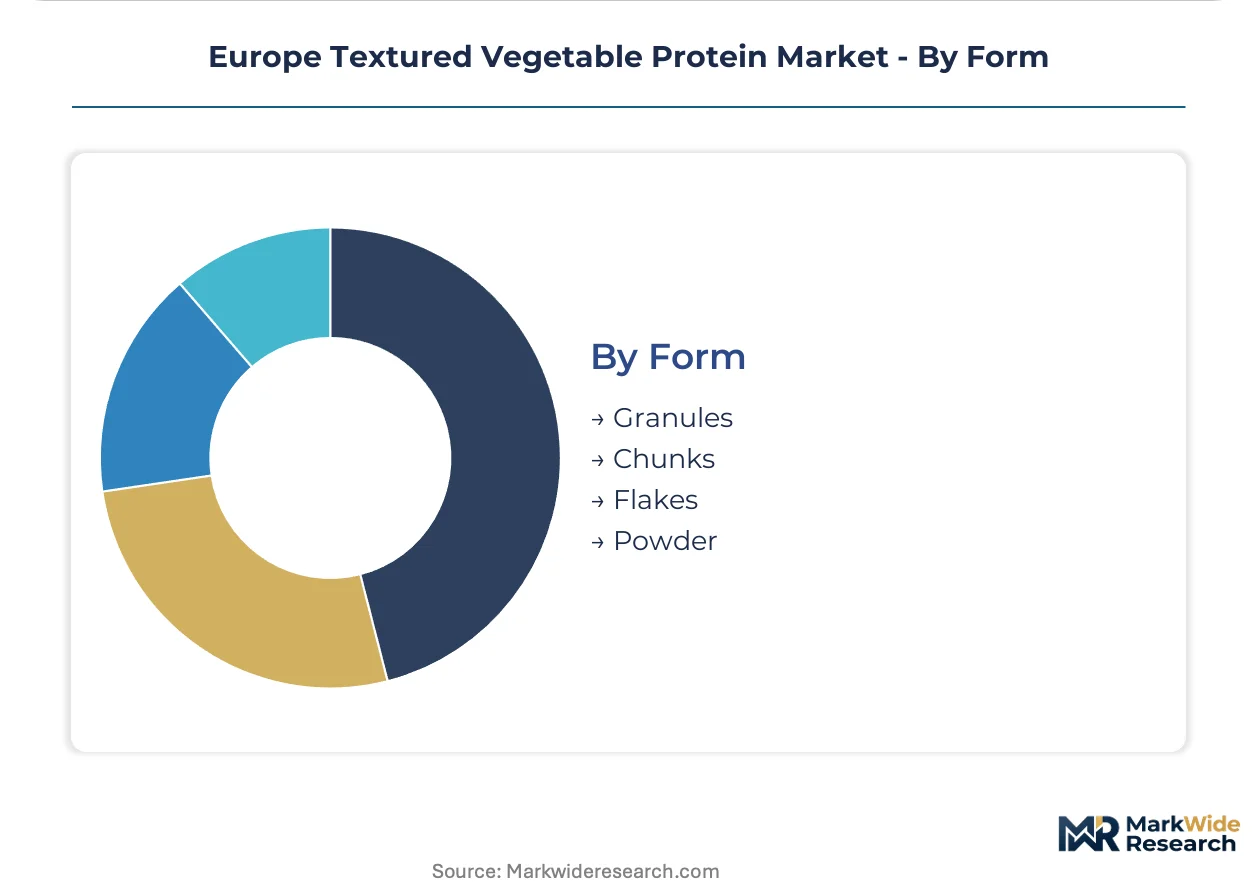
Form:
Extrusion die configurations and downstream rehydration requirements segment equipment investment and logistics economics.
- Granules:Pea protein granules rehydrate rapidly for minced meat analogs, gaining shelf space in Nordic and British free-from product lines where allergen positioning commands premium placement.
- Chunks:Soy protein chunks dominate institutional food service procurement across the region, offering established chew density and water absorption ratios for extended ground meat formulations.
- Flakes:Wheat protein flakes serve bakery and cereal applications where gluten network formation remains irreplaceable.
- Powder:Fine-milled concentrates supply nutrition bar and beverage fortification with minimal texture contribution.
Operational scale favors chunks; premium positioning favors granules.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity for textured vegetable protein varies sharply across European procurement channels. German food manufacturers absorb premium pricing for documented low-carbon supply chains, while Spanish food service buyers remain highly price-sensitive to commodity soy chunks.
Germany
Industrial meat processors in North Rhine-Westphalia and Bavaria anchor continental demand for specification-grade textured proteins. The EU Green Deal's carbon disclosure mandates force suppliers to document farm-to-extrudate emissions or forfeit contracts with reformulating processors. The Cologne-Düsseldorf corridor concentrates extrusion capacity adjacent to oilseed crushing infrastructure, compressing logistics costs for plant-based meat hubs.
Netherlands
Plant-based meat startups and established food manufacturers in the Randstad region drive premium-grade pea protein procurement. EFSA novel food assessments shape ingredient approval timelines for emerging protein sources, while REACH compliance on processing aids adds layered regulatory costs. Wageningen's food innovation cluster feeds technical specification development for high-moisture extrusion applications.
United Kingdom
Tesco and Sainsbury's sustainability procurement teams mandate farm-level carbon data as a compulsory bid requirement, collapsing traditional distributor intermediaries. The F-Gas Regulation's phase-down schedule forces cooling system retrofits at extrusion facilities ahead of typical depreciation cycles. The East Midlands and Greater Manchester areas concentrate co-manufacturing capacity for retail own-label meat analog lines.
France
Quick-service chains test limited plant-based menu items with commodity-grade soy chunks, while artisanal charcuterie producers resist protein substitution in traditional formulations. CSRD reporting obligations extend carbon traceability requirements to mid-sized food manufacturers previously exempt from detailed disclosure. The Hauts-de-France region hosts brewing and ingredients infrastructure that supplies wheat protein derivatives for Central European meat processors.
Poland
Underdeveloped textured protein penetration in meat processing creates first-mover positioning for extruded pea protein suppliers targeting reformulating sausage manufacturers. The country's national food safety regulator enforces hygiene standards that align with EU baseline requirements but lack the granular carbon accounting demanded by Western retail buyers. The Łódź and Wrocław industrial zones attract contract manufacturing investment from German and Dutch plant-based brands seeking labor cost advantages.
Europe Textured Vegetable Protein Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the European textured protein supply base. Scaled agribusiness conglomerates with continental crushing networks dominate volume supply of commodity-grade soy concentrates, while specialized extrusion operators capture premium positioning through clean-label and allergen-free certifications. Three archetypes structure competition: integrated oilseed processors with captive extrusion assets, standalone protein specialists focused on high-value isolates, and regional toll manufacturers serving private-label demand. Dominant competitive moves include backward integration into non-GMO oilseed origination and strategic partnerships with retail sustainability procurement teams.
Among Netherlands-based specialists, Roquette Freres anchors continental pea protein supply through its Vic-sur-Aisne facility positioning. ADM represents the integrated processor archetype with crushing and extrusion network control across Germany and the Netherlands. Beneo GmbH exemplifies the clean-label specialist tier with wheat protein isolate capabilities for Central European meat analog producers.
| Leading Market Players |
|---|
| Ingredion Inc |
| ADM |
| GEMEF Industries |
| International Flavors & Fragrances Inc |
| Cargill Incorporated |
| Sudzucker AG |
| Beneo GmbH |
| ICL Group Ltd |
| Roquette Freres |
| Others |
Supply & Pricing Matrix
Continental-scale crushing and extrusion assets in the Netherlands-Germany corridor compress unit economics for textured protein suppliers while establishing price floors that smaller Eastern European toll manufacturers struggle to match. Carbon disclosure mandates under the EU Green Deal are layering compliance costs onto supply chains, forcing buyers to absorb premiums for documented low-carbon origination or forfeit contracts with reformulating meat processors.
Pricing Analysis
REACH registration thresholds dictate the pricing tier structure across European textured protein supply, separating established soy and wheat protein processors with grandfathered dossiers from emerging pea protein entrants facing extended qualification timelines. Three-tier pricing structure across premium, standard, and economy levels aligns with certification grade—non-GMO and organic command 15-25% premiums over conventional—while volume scale and after-sales technical service differentiate mid-tier positioning. Cost compression in commodity soy chunks is intensifying because Black Sea supply volatility and energy-intensive extrusion are squeezing marginal producer economics. Quick-service chains in France and Spain exhibit highest price sensitivity to commodity-grade inputs, whereas British and German retail sustainability teams absorb premiums for farm-level carbon traceability.
Supply Chain Analysis
Danube River transit corridors and Rotterdam port throughput underwrite raw material flows for Central European extrusion facilities, creating chokepoint vulnerability when inland waterway disruptions constrain oilseed deliveries. Geographic supply concentrates in Germany, the Netherlands, and Poland—where crushing infrastructure, extrusion capacity, and contract manufacturing clusters align—while raw material dependencies rest on certified non-GMO soybeans from Black Sea origins, yellow peas from France and Belgium, and wheat gluten from Central European milling networks. Single-source vulnerability in Ukrainian soybean origination exposes processors to geopolitical supply interruptions. Distribution runs through direct contracting between retail sustainability procurement teams and extrusion processors, displacing traditional ingredient distributors in the United Kingdom and Germany.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Interoperability between high-moisture extrusion systems and traditional dry extrusion lines is creating platform-economics dynamics where equipment compatibility and shared technical standards determine supplier switching costs and buyer lock-in.
For Market Incumbents: Fortify carbon documentation capabilities and backward integration into non-GMO oilseed origination to defend against emerging Polish and Romanian toll manufacturers capturing labor-cost advantages. EFSA novel food approval timelines for emerging protein sources threaten to commoditize established soy and wheat protein positions unless incumbents accelerate clean-label certification investments.
For New Entrants and Emerging Players: EFSA novel food fast-track pathways for pea protein isolates open immediate positioning opportunities in Nordic and British allergen-free product lines where established suppliers face capacity constraints. Polish sausage manufacturers and Romanian meat processors represent the most penetrable geography, with reformulation mandates tightening but textured protein adoption still nascent. Go-to-market through direct technical service partnerships with mid-sized processors bypasses consolidated retail buyer gatekeeping.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized extrusion operators with cooling die capabilities and documented low-carbon supply chains over integrated agribusiness conglomerates with commodity-grade exposure. Long-term viability across the projection horizon hinges on regulatory traceability mandate compliance and high-moisture extrusion equipment ownership. Acquisition target archetype: mid-cap extrusion specialists with EFSA-approved novel food dossiers and established retail sustainability procurement relationships. Signal to watch: F-Gas Regulation cooling system retrofit completion rates as indicator of regulatory compliance capacity and capital access differentiation.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Non-GMO Oilseed Origination | Secures Black Sea soybean supply corridors against geopolitical disruption and EU Green Deal carbon accountability requirements. |
| High-Moisture Extrusion Equipment Retrofit | Enables whole-muscle analog production previously confined to wet fractionation systems, compressing premium capture timelines. |
| Blockchain-Tracked Supply Chain Documentation | Satisfies impending EU digital product passport mandates before compliance becomes table stakes for retail procurement. |
| EFSA Novel Food Dossier Acceleration | Extends approval timelines for fava bean and oat protein concentrates beyond typical product development cycles, favoring early movers. |
| Direct Retail Sustainability Procurement Partnerships | Collapses traditional distributor intermediaries as Tesco and Sainsbury's mandate farm-level carbon data as compulsory bid criteria. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with extrusion process engineers, regulatory affairs leads at textured protein suppliers, meat processor procurement directors, and retail sustainability category managers; and secondary validation against EFSA novel food registers, REACH authorization databases, EU Green Deal farm-to-fork implementation reports, and customs trade flow data for oilseed and protein concentrate shipments. Bottom-up capacity and utilization estimates across German, Dutch, and Polish extrusion facilities were triangulated against top-down demand projections from meat analog formulation trends and reformulation mandate timelines.
Across the analysis window, the forecasting framework modeled volume and value trajectories by protein source, application segment, end-user channel, and extrusion form factor, with CAGRs derived from elasticity-adjusted demand curves and capacity expansion timelines. Industry-specific inputs included EFSA approval pipeline velocity for emerging protein sources, F-Gas Regulation cooling system retrofit schedules, and carbon disclosure mandate compliance cost curves.
Decision-makers should treat outputs as directional under base assumptions of sustained EU Green Deal implementation and stable Black Sea oilseed trade flows; material deviation in regulatory enforcement or geopolitical supply access would warrant model refresh. Practitioners should keep alternative scenarios live as EFSA novel food assessment timelines and digital product passport technical specifications evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plant Based Food
Burdock Root Extract Market
Plant Based Food
Vegan Asian Food Market
Plant Based Food
Vegan Cookies Market
Plant Based Food
South America Soy Beverages Market
Plant Based Food
Black Rice Protein Market
Plant Based Food
Europe Meat Substitutes Market
Plant Based Food
United Kingdom Plant Protein Market
Plant Based Food
Pea Protein Market
Plant Based Food
Plant Based Collagen Market
Plant Based Food
Vegan Protein Concentrate Market
Plant Based Food
Chicory Roots Market
Plant Based Food
Plant-Based Tzatziki and Labneh Ferment Bases Market
Plant Based Food
Indonesia Plant-Based Food and Beverages Market
Plant Based Food
Global Tofu Market
Plant Based Food
Pea Protein Isolate Market
Plant Based Food
Soy Protein Market