
 Europe Tofu Market | 2026-2036
Europe Tofu Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Tofu Market Insights
Single-serve vacuum packs is repositioning household purchase patterns across European retail. Taifun-Tofu GmbH anchors artisanal production credentials in German-speaking markets. The Tofoo Co. Ltd leverages scale manufacturing to dominate British supermarket shelves. Pulmuone Corporate extends its chilled logistics network to compete across northern European capitals.
Tofu denotes coagulated soy milk pressed into blocks with protein content typically ranging from eight to fifteen percent and moisture levels distinguishing firm from silken grades; manufacturers deploy calcium sulfate or nigari to set curds for culinary applications spanning frying, blending, and direct consumption. Firm Tofu commands the largest production volume owing to its versatility across European foodservice frying and grilling applications, while Marinated Tofu captures expanding margin pools as flavor-infused formats reduce consumer preparation barriers. Vacuum Packs outpace Plastic Containers in growth velocity as extended shelf life supports centralized distribution to continental retail networks.
EFSA governs novel food safety assessments for innovative soy processing methods entering European commerce, while EU Green Deal agricultural transition funds incentivize domestic protein crop cultivation that tightens feedstock supply chains. REACH compliance shapes packaging material specifications, particularly for vacuum-seal films contacting moist tofu surfaces. Stakeholders must monitor EU Deforestation Regulation traceability deadlines for imported soybeans, as compliance costs will restructure sourcing economics for processors dependent on South American supply.
Market Dynamics
EU protein diversification mandates and EFSA novel food streamlining are compressing approval timelines for soy-based alternatives while plant-forward procurement in foodservice channels is electrifying volume commitments across northern European capitals.
Growth Catalysts
- EU Green Deal agricultural transition:Dedicated funding tightens domestic protein crop cultivation, shortening feedstock supply chains for processors operating within the bloc.
- Plant-forward menu development:European foodservice channels accelerate tofu procurement as institutional kitchens and restaurant groups reformulate protein portfolios.
- Vacuum packaging innovation:Extended shelf-life formats enable centralized distribution to continental retail networks, expanding addressable geography for chilled tofu.
Market Restraints
- South American soybean concentration:EU Deforestation Regulation traceability deadlines impose compliance cost burdens on processors dependent on imported feedstock.
- Calcium sulfate and nigari input volatility:Coagulant chemical markets expose margins to energy-intensive production swings in European industrial chemical supply.
- Fresh dairy and fermented alternatives:Yogurt and kefir cultures capture overlapping consumer segments seeking high-protein, low-preparation refrigerated options.
Strategic Opportunities
- Polish and Romanian retail penetration:Underdeveloped chilled vegetarian sections in Warsaw and Bucharest supermarket chains offer first-mover positioning for vacuum-packed formats.
- Marinated tofu flavor platforms:Pre-infused variants reduce consumer preparation barriers and command margin premiums in time-constrained urban households.
- High-pressure processing convergence:HPP technology extends refrigerated shelf life without thermal degradation, unlocking foodservice bulk procurement previously blocked by spoilage risk.
Industry Challenges
- EFSA novel food dossier preparation:Specialized regulatory affairs capacity scarcity delays market entry for innovative soy processing methods and fermentation-derived variants.
- REACH-compliant vacuum-seal film sourcing:Packaging material specifications for moist tofu contact surfaces constrain supplier pools and extend qualification timelines.
- Cold chain integrity across fragmented logistics:Temperature excursion risk multiplies as chilled distribution extends into southern European markets with less developed refrigerated infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Tofu Market |
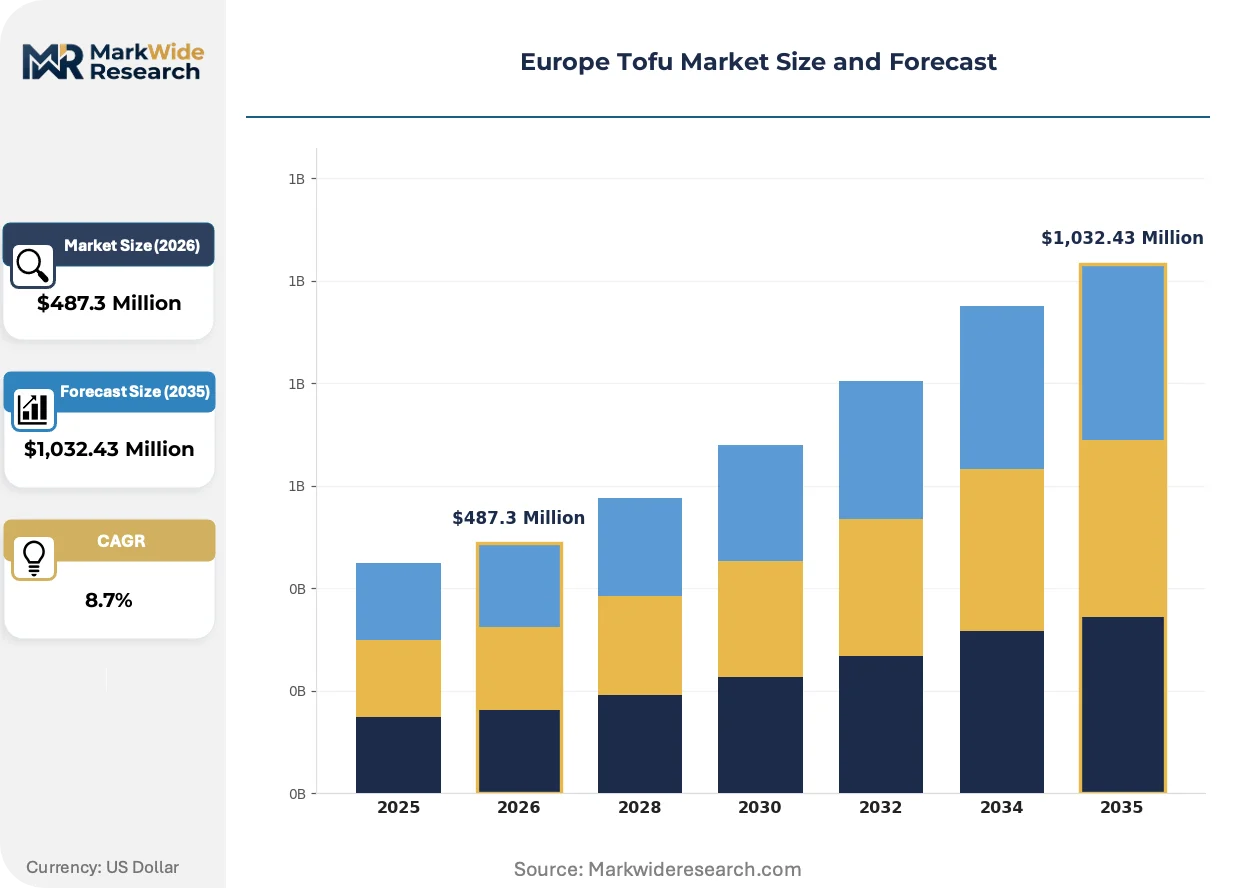
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,032.43 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Firm Tofu, Silken Tofu, Smoked Tofu, Marinated Tofu End User: Restaurants, Households, Food Manufacturers, Health Food Stores Packaging Type: Plastic Containers, Vacuum Packs, Cans, Tubs Distribution Channel: Supermarkets, Online Retail, Specialty Stores, Wholesale Distributors |
| Companies Covered | Clearspring Limited, House Foods Group Inc., Pulmuone Corporate, Taifun-Tofu GmbH, The Tofoo Co. Ltd, Dragonfly Foods Ltd., Morinaga Milk Industry Co. Ltd, LE SOJAMI, Tazaki Foods Limited, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Tofu Market Trends and Innovations
Product format diversification and processing technology advancement are compressing the gap between artisanal positioning and industrial scale in European tofu supply.
High-pressure processing is electrifying shelf-life extension for refrigerated tofu without thermal pasteurization. German and Dutch foodservice distributors adopt HPP-treated blocks for extended delivery cycles to institutional kitchens. This technology is compressing spoilage risk premiums and enabling centralized production hubs to serve peripheral markets previously uneconomical for chilled distribution.
EFSA novel food safety assessments streamline approval pathways for innovative soy processing methods entering European commerce. Manufacturers gain clarity on data requirements for fermentation-derived and enzyme-modified variants. German-speaking markets exhibit fastest uptake of novel-process tofu as local regulators align interpretation with EFSA guidance.
Single-serve vacuum packs displace plastic containers in household purchase patterns across British and Scandinavian retail. Urban consumers with limited refrigeration capacity favor portion-controlled formats. This shift concentrates volume with processors possessing aseptic filling and modified-atmosphere packaging capabilities.
Europe Tofu Market Segmentation
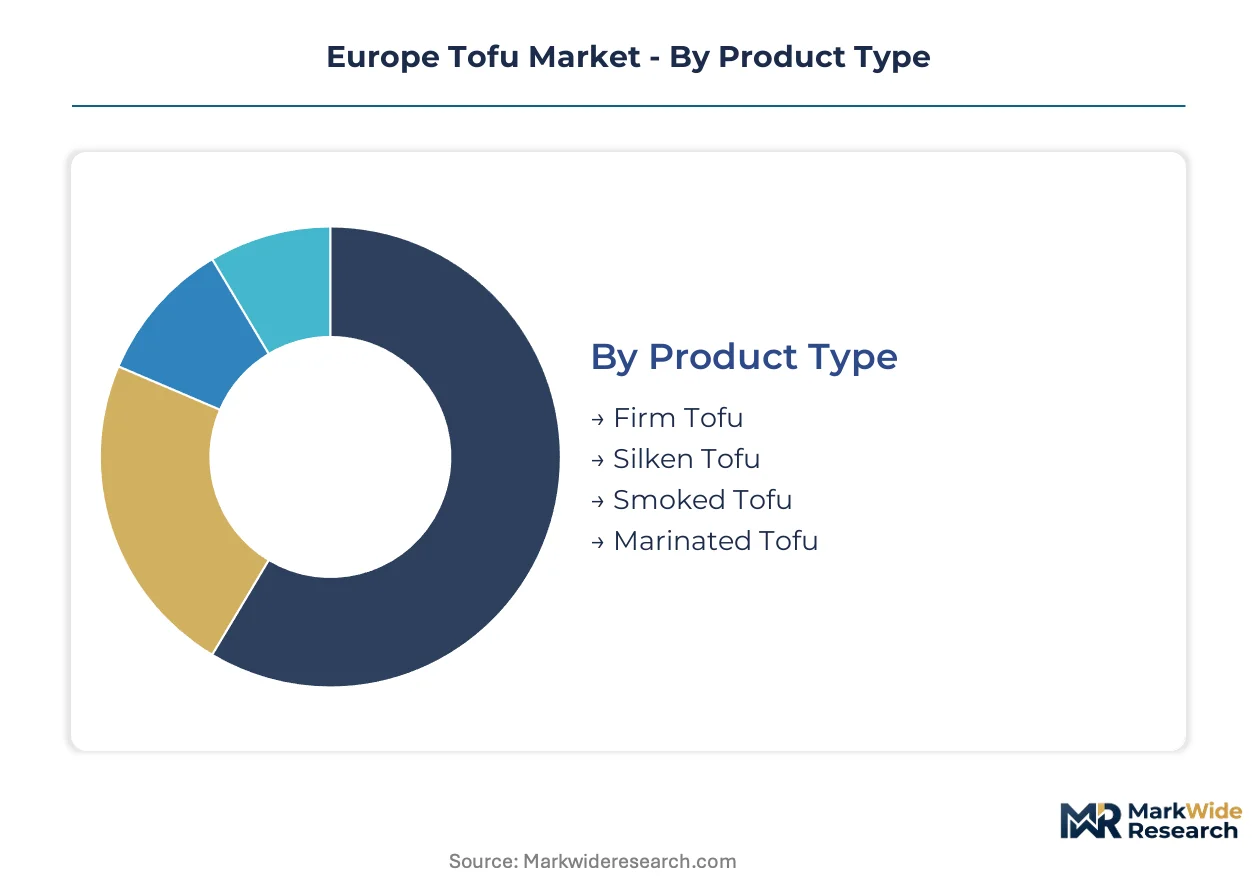
Segmentation in the Europe Tofu Market reveals how protein diversification policies and foodservice procurement patterns reshape demand across formats. Manufacturers calibrate production lines to match distinct moisture specifications, packaging durability requirements, and channel-specific shelf-life needs.
Product Type:
Upgrade cycles in European kitchens are accelerating as consumers replace basic blocks with specialized formats that reduce preparation time and expand culinary applications.
- Firm Tofu:Pressed to 12-15% protein content with low moisture retention, this format withstands frying and grilling without structural collapse. German foodservice distributors in Berlin and Hamburg move the highest volumes as institutional kitchens standardize on blocks that hold shape across batch cooking.
- Marinated Tofu:Pre-infused variants incorporate tamari, ginger, or smoked paprika brines that penetrate the curd matrix. Urban households in London and Amsterdam pay premium shelf prices for ready-to-cook proteins that eliminate marination time, compressing the gap between purchase and plate.
- Silken Tofu:High-moisture, unpressed curds with custard-like texture serve blending applications in smoothies and desserts across Scandinavian retail.
- Smoked Tofu:Beechwood or alder cold-smoked blocks command specialty positioning in Bavarian and Alpine retail circuits.
Firm Tofu sits at the top of the volume ranking, with Marinated Tofu climbing the fastest.
End User:
Cost tier differentiation separates commodity procurement from premium positioning, with each user type demanding distinct certification, labeling, and logistics specifications.
- Restaurants:High-volume accounts in Paris, Copenhagen, and Vienna specify calibrated block dimensions and consistent moisture content for menu standardization. EFSA-compliant allergen labeling and HACCP documentation requirements filter supplier pools to established processors with dedicated foodservice sales teams.
- Households:Single-serve and family-format purchasing splits along refrigeration capacity and meal-planning frequency, with British consumers showing highest penetration of vacuum-packed convenience sizes.
- Food Manufacturers:Industrial buyers source bulk chilled or frozen curd for further processing into ready meals and meat analogues.
- Health Food Stores:Independent retailers in German university towns prioritize organic-certified and locally-produced artisanal blocks.
Restaurants capture the highest absolute tonnage, while Food Manufacturers expand most quickly as ingredient sourcing diversifies beyond meat and dairy.
Packaging Type:
Geographic expansion of chilled distribution networks is forcing packaging technology investments that balance shelf-life extension against REACH compliance costs.
- Vacuum Packs:Modified-atmosphere sealing with nitrogen flush extends refrigerated life to 45-60 days. Dutch and Danish processors deploy this format to reach southern European markets through centralized production hubs, compressing spoilage risk that previously blocked long-haul chilled distribution.
- Plastic Containers:Rigid PET or PP tubs with resealable lids dominate German and Austrian retail where consumers prioritize portion visibility and reuse potential.
- Cans:Aseptically processed and shelf-stable formats serve emergency preparedness and outdoor recreation segments in Alpine regions.
- Tubs:Bulk foodservice containers with tamper-evident seals support institutional procurement in Swedish and Finnish school feeding programs.
Vacuum Packs sit at the top of the volume ranking, with Tubs climbing the fastest as foodservice bulk procurement expands.
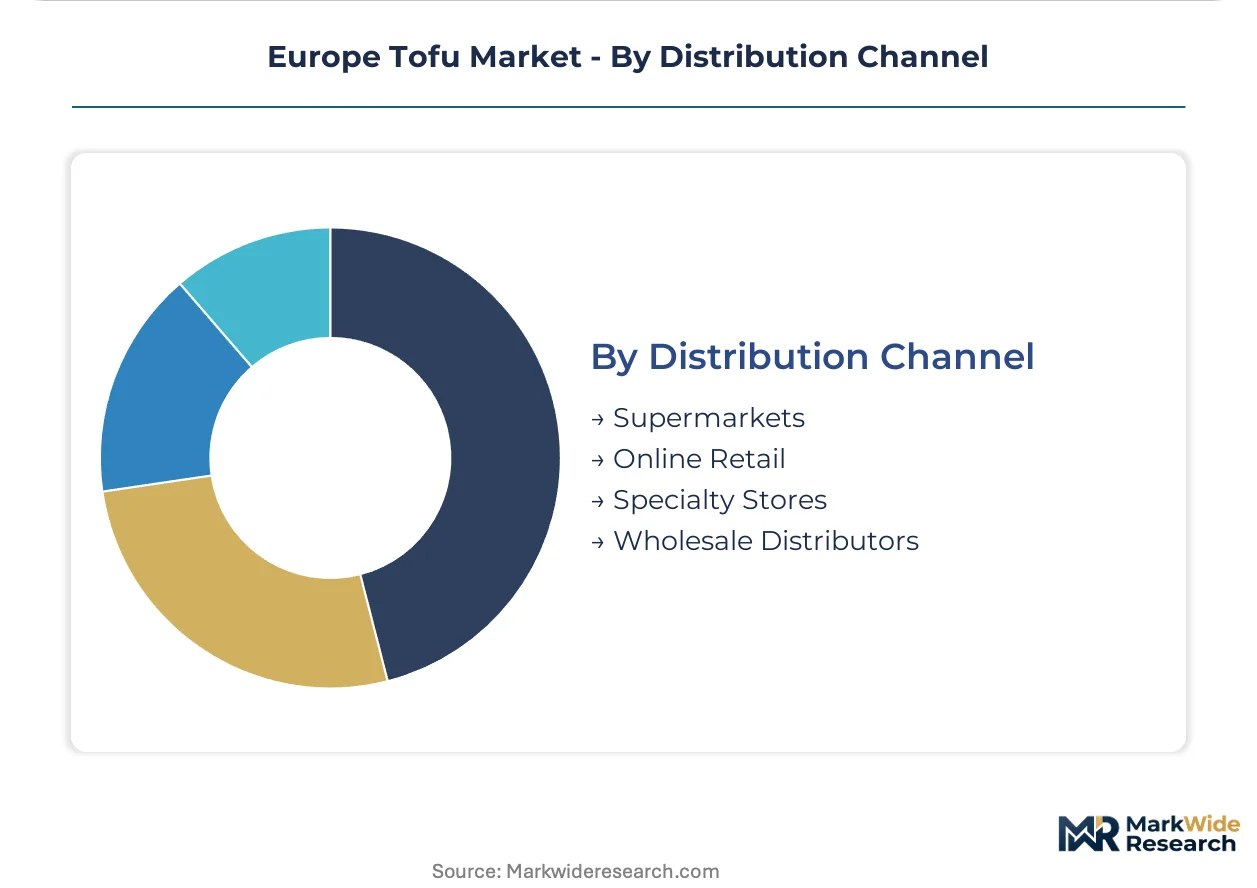
Distribution Channel:
Supply concentration in northern European logistics hubs is reshaping channel economics, with each route demanding distinct cold-chain integrity and margin structures.
- Supermarkets:Discounters and premium chains in Germany, Britain, and the Netherlands control the majority of retail volume. Listing fees and promotional calendar compliance favor processors with scale manufacturing and dedicated category management teams.
- Online Retail:Direct-to-door chilled delivery requires insulated packaging and time-definite logistics that concentrate with specialized e-grocers in London, Amsterdam, and Berlin.
- Specialty Stores:Independent organic and Asian-food retailers in Brussels, Milan, and Barcelona curate artisanal and import-origin selections.
- Wholesale Distributors:Cash-and-carry and delivered wholesale serve restaurant and catering accounts across the Benelux and northern France.
Supermarkets sit at the top of the volume ranking, with Online Retail climbing the fastest as urban delivery infrastructure matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Soy-based protein production first achieved industrial scale in Dutch and German food technology corridors during the 1980s, establishing processing expertise that now serves pan-European distribution networks.
Germany
Berlin and Hamburg sustain Europe's densest vegetarian retail and foodservice infrastructure, with institutional kitchens standardizing on firm tofu blocks for batch cooking. EU Green Deal agricultural transition funds support domestic protein crop cultivation in Brandenburg and Mecklenburg-Vorpommern, shortening feedstock supply chains for processors. Taifun-Tofu GmbH anchors artisanal production credentials from its Freiburg base, supplying organic-certified blocks across German-speaking markets.
United Kingdom
London and Manchester drive vacuum-packed single-serve penetration among urban renters with limited refrigeration capacity. EFSA novel food rulings streamline approval pathways for innovative soy processing methods entering British commerce. The Tofoo Co. Ltd leverages scale manufacturing to dominate supermarket shelves across England and Scotland, compressing price points for mainstream adoption.
Netherlands
Amsterdam and Rotterdam function as chilled logistics hubs extending modified-atmosphere packaged tofu into southern European markets. REACH compliance shapes packaging material specifications for vacuum-seal films contacting moist surfaces, constraining supplier pools. High-pressure processing adoption concentrates with Dutch foodservice distributors serving extended delivery cycles to Belgian and French institutional accounts.
France
Parisian restaurant groups accelerate plant-forward procurement, specifying calibrated block dimensions and consistent moisture content for menu standardization. ANSM and DGCCRF enforcement of EFSA-compliant allergen labeling filters supplier pools to established processors. LE SOJAMI occupies a position within the French artisanal tier, supplying flavored and organic variants through specialty retail channels in Île-de-France.
Poland
Warsaw supermarket chains present underdeveloped chilled vegetarian sections, offering first-mover positioning for vacuum-packed formats as protein diversification policies penetrate Eastern Europe. EU Deforestation Regulation traceability deadlines impose compliance cost burdens on processors dependent on South American soybean imports. Cold chain infrastructure gaps in southern regions create temperature excursion risks that centralized distribution from northern hubs must mitigate.
Europe Tofu Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification status and distribution reach, with organic and locally-sourced positioning commanding shelf price multiples. The vendor base fragments across scale manufacturers, artisanal specialists, and Asian-import distributors, each serving distinct channel requirements. Three archetypes dominate: German-speaking organic specialists, British scale processors, and Korean-Japanese chilled logistics operators. Competitive moves concentrate on geographic expansion into underpenetrated Eastern European retail and flavor platform diversification to reduce consumer preparation barriers.
Within the scale-manufacturing tier, Pulmuone Corporate and The Tofoo Co. Ltd exemplify operations leveraging centralized production and chilled distribution networks to serve mass retail. Among artisanal specialists, Taifun-Tofu GmbH occupies a position representing organic-certified, small-batch positioning in German-speaking markets. Clearspring Limited and House Foods Group Inc. sit within the import-distributor archetype, bridging Asian processing expertise with European regulatory compliance and channel access.
| Leading Market Players |
|---|
| Clearspring Limited |
| House Foods Group Inc. |
| Pulmuone Corporate |
| Taifun-Tofu GmbH |
| The Tofoo Co. Ltd |
| Dragonfly Foods Ltd. |
| Morinaga Milk Industry Co. Ltd |
| LE SOJAMI |
| Tazaki Foods Limited |
| Others |
Pricing and Supply Chain Analysis
Foodservice procurement concentration in northern European capitals anchors a three-tier pricing structure across premium, standard, and economy levels. German institutional kitchens and Parisian restaurant groups command volume discounts that compress mid-tier margins, while organic-certified artisanal blocks from Freiburg suppliers capture shelf price multiples in specialty retail.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates organic-certified artisanal blocks from conventional vacuum-packed formats and private-label economy tiers. Price differentiation rests on certification grade and geographic delivery cost, with Berlin and Hamburg foodservice distributors extracting volume leverage. Cost compression in the economy tier is intensifying because South American soybean traceability compliance adds feedstock overhead. Quick-service restaurant chains exhibit highest price sensitivity; premium organic retailers show least.
Supply Chain Analysis
Dual-sourcing requirements from EFSA novel food dossier preparation constrain processors to qualify multiple coagulant and film suppliers simultaneously. Feedstock draws from Germany, the Netherlands, and France for domestic protein crops, with South American soybean imports feeding scale manufacturers. Calcium sulfate and nigari chemical markets expose margins to energy-intensive production swings. Single-source vulnerability concentrates in REACH-compliant vacuum-seal film qualification. Distribution runs through Dutch and Danish chilled logistics hubs serving pan-European retail networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between established northern European chilled infrastructure and underdeveloped cold chains in Warsaw and Bucharest, where EU protein diversification subsidies offset logistics investment costs.
For Market Incumbents: Deploy high-pressure processing capacity additions in Dutch distribution hubs to extend shelf life for southern European market penetration. Consolidate backward integration into Brandenburg protein crop cultivation to reduce South American feedstock exposure. Taifun-Tofu GmbH's organic certification moat faces erosion from scaled competitors; reinforce channel control through dedicated foodservice sales teams in Vienna and Copenhagen. For New Entrants and Emerging Players: The premium-to-economy price-point gap in Polish and Romanian retail creates entry space for vacuum-packed standard-tier formats. Target Warsaw supermarket chains with modified-atmosphere packaging capabilities absent from current chilled vegetarian sections. Bucharest foodservice distributors offer first-mover positioning for marinated tofu flavor platforms that eliminate consumer preparation barriers. For Investors and Strategic Acquirers: Korean-Japanese chilled logistics operators are the most active acquirer in this space, seeking European regulatory compliance capabilities and channel access. Five-to-ten-year viability hinges on EU Deforestation Regulation traceability infrastructure investment. Acquisition targets cluster around Dutch HPP technology specialists and German organic-certified artisanal processors. The signal to watch is EFSA novel food approval velocity for fermentation-derived variants as margin expansion catalyst.| Strategic Initiative | Industry Significance |
|---|---|
| High-Pressure Processing Adoption | Dutch foodservice distributors deploy HPP blocks to extend delivery cycles to Belgian institutional kitchens. |
| Backward Integration into Protein Crops | EU Green Deal agricultural transition funds tighten Brandenburg feedstock supply chains for German processors. |
| Marinated Flavor Platform Expansion | Pre-infused variants reduce London and Amsterdam household preparation barriers while capturing margin premiums. |
| Vacuum-Pack Format Penetration | Centralized production hubs in the Netherlands serve Warsaw and Bucharest through modified-atmosphere distribution. |
| EFSA Novel Food Dossier Investment | Streamlined approval pathways for fermentation-derived tofu accelerate German-speaking market uptake. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary engagement covered tofu processing plant managers, chilled logistics coordinators at Dutch and Danish distributors, supermarket category buyers in Berlin and London, foodservice procurement leads at Parisian restaurant groups, and EFSA regulatory affairs specialists. Secondary validation drew from EFSA novel food safety assessments, EU Green Deal agricultural transition fund disclosures, REACH compliance documentation for packaging materials, and customs data on South American soybean imports. Bottom-up volume modeling triangulated against top-down protein diversification policy expenditure analysis.
Comparable historical periods anchored projections across the analysis window, with growth rates derived from segment-level elasticity modeling. Segmentation dimensions spanned product moisture grade, packaging durability tier, end-user channel classification, and regional cold-chain maturity cluster. Forecast inputs incorporated EFSA approval timeline assumptions, EU Deforestation Regulation compliance cost trajectories, and high-pressure processing adoption curves in foodservice distribution.
The model assumes a particular technology adoption path; alternative pathways for high-pressure processing would alter the outlook if HPP equipment costs fail to decline as projected. Forecasts reflect documented assumptions on protein crop yield improvements and chilled logistics infrastructure buildout in Eastern Europe. Deviation in EFSA novel food dossier approval velocity or EU Deforestation Regulation enforcement intensity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plant Based Food
Asia Pacific Plant-Based Milk Market
Plant Based Food
Plant-Based Protein Food Market
Plant Based Food
Pea Protein Market
Plant Based Food
Vegan Margarine Market
Plant Based Food
Plant-Based Bars Market
Plant Based Food
Hemp-Based Food Market
Plant Based Food
China Pea Protein Market
Plant Based Food
Targeting Pod Market
Plant Based Food
Brazil Soy Beverages Market
Plant Based Food
Plant Based Ice Cream Market
Plant Based Food
United Kingdom Soy Protein Market
Plant Based Food
India Meat Substitutes Market
Plant Based Food
Plant Based Meat Market
Plant Based Food
Packed Vegan Foods Market
Plant Based Food
United Kingdom Plant Protein Market
Plant Based Food
Extruded Soy Products Market