
 Brazil Soy Beverages Market | 2026-2036
Brazil Soy Beverages Market Size, Share, and Industry Trends Forecast 2026-2036
Brazil Soy Beverages Market Outlook
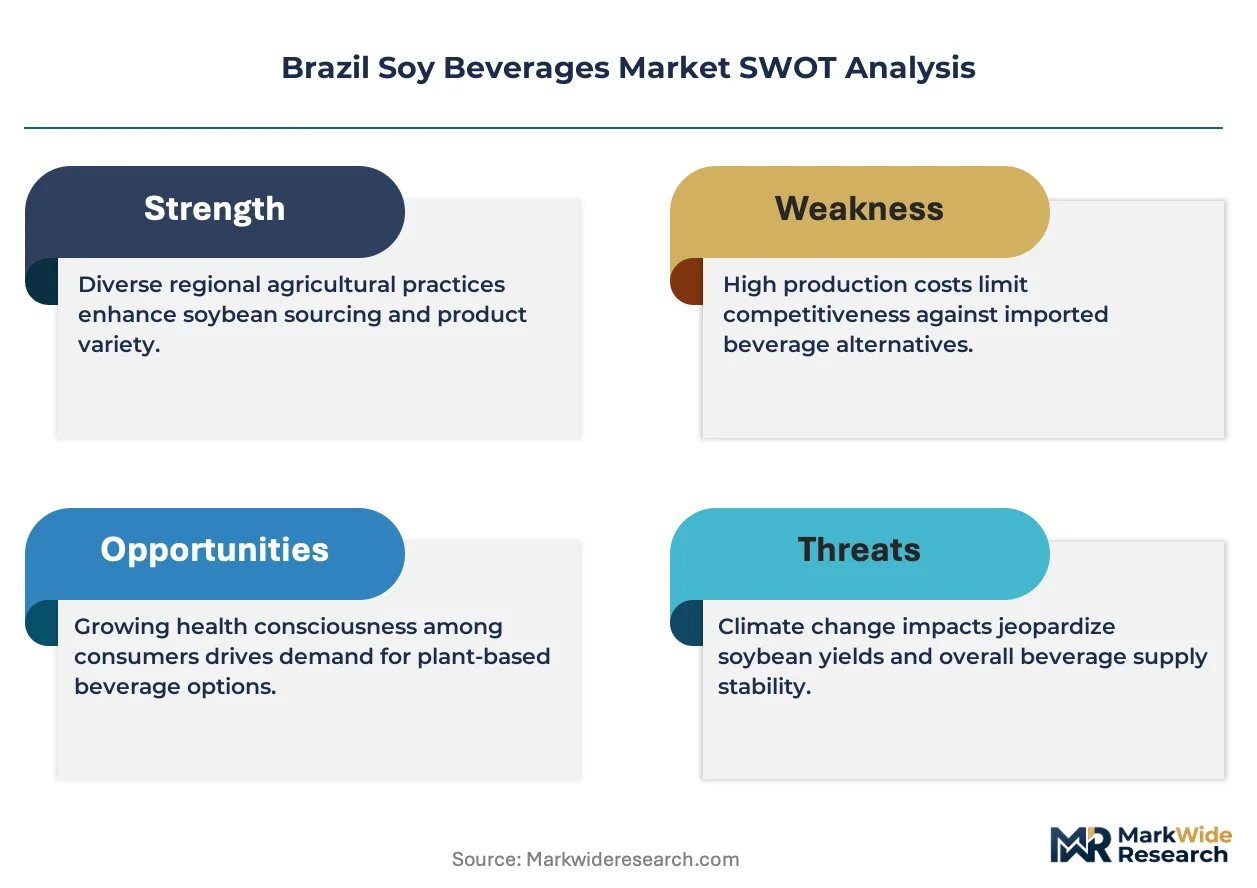
Asset-light leasing models for UHT processing equipment are reshaping competitive entry in Brazil's soy beverage sector. Jussara SA leverages its Paraná-based dairy infrastructure to control chilled distribution networks across southern Brazil. Danone S.A anchors its position through specialized soy-based yogurt R&D aligned with local taste profiles. Piracanjuba competes via backward integration into soybean crushing, securing captive supply of non-GMO raw material.
Soy beverages comprise aqueous extracts of whole or dehulled soybeans, typically standardized to protein levels between 2.5% and 3.5% and processed through either ultra-high temperature sterilization or pasteurization for shelf-stable or refrigerated distribution. These formulations serve as lactose-free alternatives in foodservice and retail channels where dairy intolerance or plant-based preference drives substitution. Chilled soy milk occupies the dominant margin pool due to premium positioning in São Paulo and Rio de Janeiro supermarkets, while soy protein drinks gain traction among fitness center channels seeking post-workout recovery positioning. UHT soy milk sustains volume leadership in Brazil's Northeast where cold chain limitations restrict refrigerated alternatives.
ANVISA governs nutrition claims and allergen labeling for soy beverages sold in Brazil, while the Ministry of Agriculture enforces dairy-alternative identity standards that restrict misleading protein equivalence statements. Mercosur technical regulations on food additives and fortification levels further constrain formulation flexibility for cross-border suppliers. Stakeholders must monitor pending updates to Brazil's front-of-package warning label law, which could recast consumer perception of flavored or sweetened soy drink variants.
Market Dynamics
ANVISA's pending front-of-package warning label law is compressing formulation flexibility for sweetened soy drink variants while simultaneously opening premium positioning for unsweetened, high-protein alternatives. This regulatory inflection point is accelerating portfolio restructuring across Brazilian manufacturers.
Growth Catalysts
- Fitness center channel expansion:São Paulo and Rio de Janeiro gym chains are standardizing post-workout soy protein recovery drinks as core amenities, creating institutional volume anchors for specialized formulations.
- ANVISA nutrition labeling alignment:Clarified protein equivalence standards enable precise lactose-free positioning against dairy alternatives, reducing consumer confusion in retail environments.
- Northeast Brazil cold chain gaps:Persistent refrigeration infrastructure limitations sustain demand pull for UHT-stable soy milk formats that bypass chilled distribution requirements.
Market Restraints
- Non-GMO soybean supply concentration:Paraná and Rio Grande do Sul states control premium non-GMO crushing capacity, creating geographic supply vulnerability for formulations targeting health-conscious urban consumers.
- Mercosur additive harmonization delays:Divergent fortification level approvals between Brazil and Argentina complicate cross-border formulation standardization for multinational suppliers.
- Dairy-alternative protein equivalence restrictions:Ministry of Agriculture identity standards limit comparative marketing claims, constraining competitive messaging against fluid milk.
Strategic Opportunities
- Amazon region cold chain underpenetration:Manaus and Belém metropolitan areas lack chilled soy beverage distribution, creating first-mover advantage for ambient-stable fortified formats.
- Soy-based yogurt R&D convergence:Fermentation technology transfer from dairy cultures to soy substrates enables texture and taste profiles that capture premium refrigerated margins.
- Direct-to-fitness-center procurement:Institutional bulk purchasing agreements bypass traditional retail slotting fees, improving unit economics for specialized high-protein formulations.
Industry Challenges
- ANVISA allergen labeling compliance timelines:Revised declaration requirements for soy protein isolates demand reformulation and repackaging cycles that compress product launch windows.
- UHT equipment leasing contract renegotiation:Asset-light processing models require continuous lessor relationship management amid interest rate volatility and currency fluctuation exposure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brazil Soy Beverages Market |
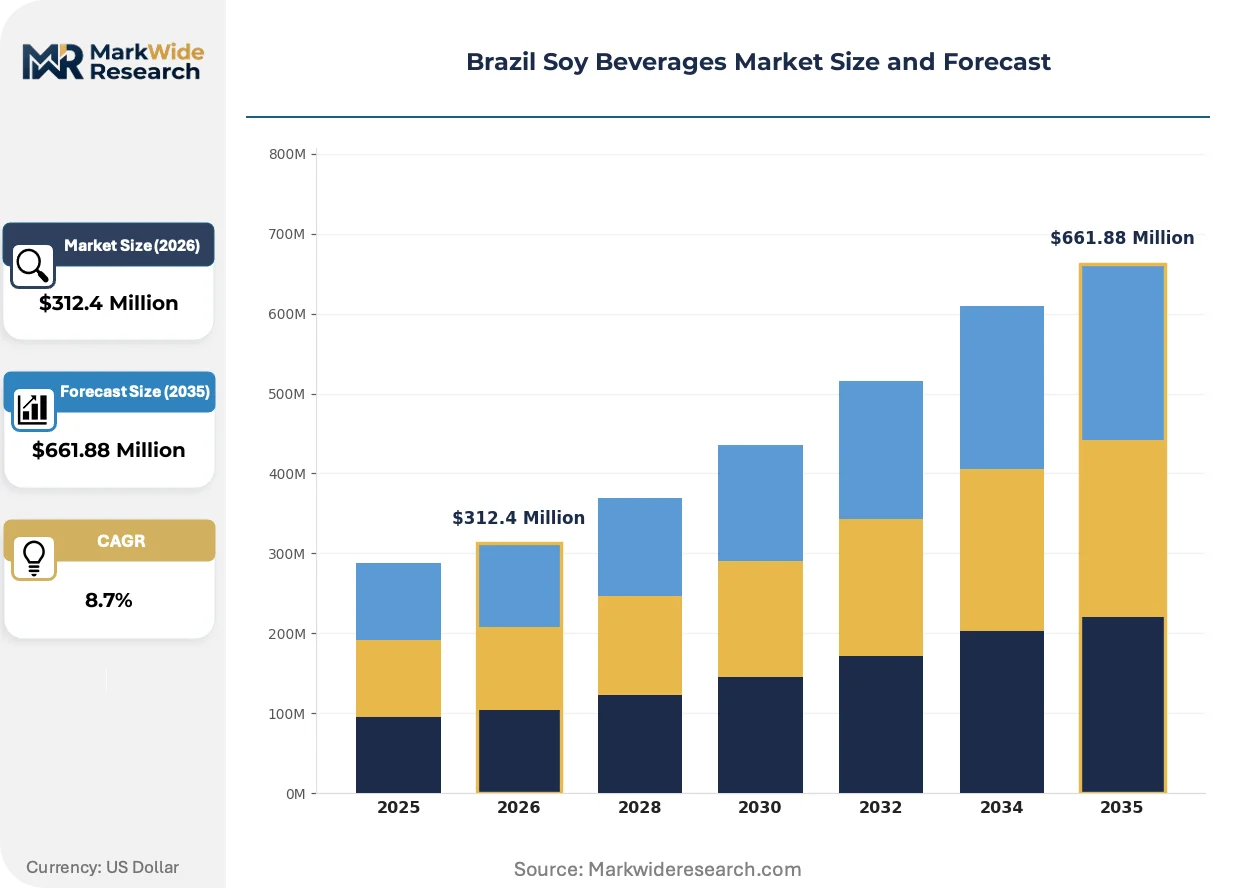
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $661.88 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chilled Soy Milk, UHT Soy Milk, Soy-based Yogurt, Soy Protein Drink End User: Households, Cafes, Restaurants, Fitness Centers Distribution Channel: Supermarkets, Health Food Stores, Online Retail, Convenience Stores Packaging Type: Bottles, Packs, Tetra Paks, Cans |
| Companies Covered | Jussara SA, Kikkoman Corporation, The Hain Celestial Group, Pureharvest, Campbell Soup Company, Danone S.A, Lactalis, Piracanjuba, The Coca-Cola Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brazil Soy Beverages Market Strategic Shifts
Processing technology and distribution infrastructure are diverging across Brazil's regional temperature gradients, creating parallel innovation tracks for ambient-stable and chilled formats. Manufacturers are responding with segmented R&D investment rather than universal platform strategies.
Ultra-high temperature sterilization is migrating from standard tubular systems to indirect plate heat exchangers with flash cooling stages. São Paulo-based processors are adopting this configuration to reduce thermal degradation of isoflavones while maintaining 12-month ambient shelf stability. The technology is migrating from dairy-industry origins into dedicated soy beverage lines as equipment lessors expand specialized asset portfolios.
ANVISA's front-of-package warning label framework for added sugars is forcing reformulation of flavored soy drink variants. Manufacturers are accelerating stevia and monk fruit adoption to maintain palatability without triggering octagonal warning symbols. Sweetened soy beverages targeting adolescent consumers face the most acute compliance pressure, with portfolio managers prioritizing unsweetened base formulations.
Foodservice procurement is consolidating through specialized dairy-alternative distributors that aggregate demand across independent coffee chains and bakery networks. These intermediaries are displacing direct manufacturer relationships in Rio de Janeiro and Curitiba metro areas, capturing volume through consolidated logistics and technical service bundling. The channel shift is most visible in specialty coffee segments where barista-grade foamability specifications dominate supplier selection criteria.
Brazil Soy Beverages Market Segmentation
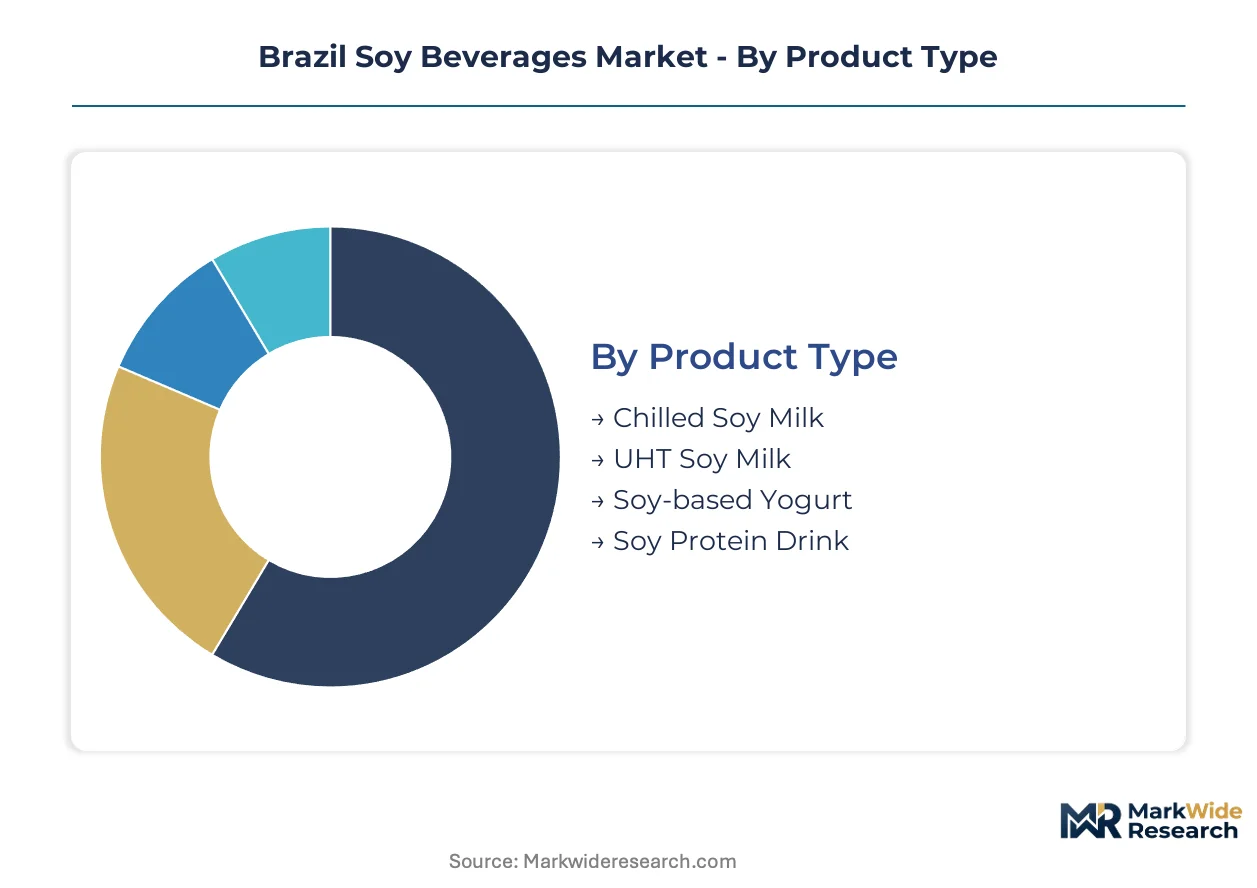
Brazil's soy beverage market fragments across four structural dimensions that determine margin capture and capital deployment cycles. Product format and packaging choices govern refrigerated versus ambient distribution economics, while end-user concentration in São Paulo's fitness ecosystem reshapes formulation priorities.
Product Type:
Chilled soy milk commands the shortest replenishment cycles among all formats, with supermarket shelf turns driving weekly production scheduling. UHT soy milk operates on quarterly inventory rhythms tied to Northeast Brazil's distribution logistics.
- Chilled Soy Milk:Aqueous soybean extract standardized to 2.5-3.5% protein, pasteurized and distributed under continuous refrigeration. São Paulo and Rio de Janeiro supermarkets anchor demand, where health-conscious households pay premium prices for fresh-positioned alternatives to dairy.
- UHT Soy Milk:Ultra-high temperature sterilized extract achieving 12-month ambient stability through indirect plate heat exchange processing. Northeast Brazil's cold chain gaps sustain volume leadership, with Maranhão and Ceará states relying on shelf-stable formats for household penetration.
- Soy-based Yogurt:Fermented soy substrates employing dairy culture technology transfer for texture replication. Danone S.A.'s specialized R&D investments target this segment's premium refrigerated margins.
- Soy Protein Drink:Fortified formulations with elevated protein content for post-workout recovery positioning. Fitness center chains in São Paulo metro area standardize these as core amenities.
UHT soy milk dominates installed base through Northeast Brazil's infrastructure constraints. Chilled soy milk is where expansion concentrates as cold chain investment accelerates in southern states.
End User:
Cost tier stratification separates institutional procurement from retail purchasing, with fitness centers and foodservice operators negotiating bulk supply agreements that bypass traditional retail markups.
- Households:Individual consumers purchasing through supermarkets and online channels for lactose-free daily consumption. São Paulo state's urban density concentrates this segment's premium-format demand.
- Fitness Centers:Gym chains procuring specialized high-protein formulations for post-workout recovery amenities. Rio de Janeiro and São Paulo operators are consolidating procurement through direct manufacturer agreements.
- Cafes:Specialty coffee shops requiring barista-grade foamability specifications for dairy-alternative beverages. Curitiba and Rio de Janeiro metro areas show concentrated adoption through specialized distributors.
- Restaurants:Foodservice operators integrating soy beverages into lactose-free menu options. Independent bakery networks in southern Brazil drive regional volume.
Households dominate installed base through retail channel penetration. Fitness centers are where expansion concentrates as institutional procurement bypasses slotting fee structures.
Distribution Channel:
Volume concentration varies sharply by geography, with supermarkets controlling southern Brazil while convenience stores capture Northeast demand for ambient formats.
- Supermarkets:Multi-format retailers commanding chilled soy milk distribution in São Paulo and Rio de Janeiro. Premium positioning depends on refrigerated display space allocation.
- Online Retail:E-commerce platforms capturing subscription-based household replenishment. São Paulo metro logistics infrastructure enables same-day chilled delivery services.
- Health Food Stores:Specialized retailers targeting organic and non-GMO positioning. Curitiba and Porto Alegre show concentrated channel presence.
- Convenience Stores:Small-format retailers sustaining UHT soy milk availability in cold chain-constrained regions. Northeast Brazil depends on this channel for ambient product access.
Supermarkets dominate installed base through southern Brazil's refrigerated infrastructure. Online retail is where expansion concentrates as delivery logistics mature in metropolitan corridors.
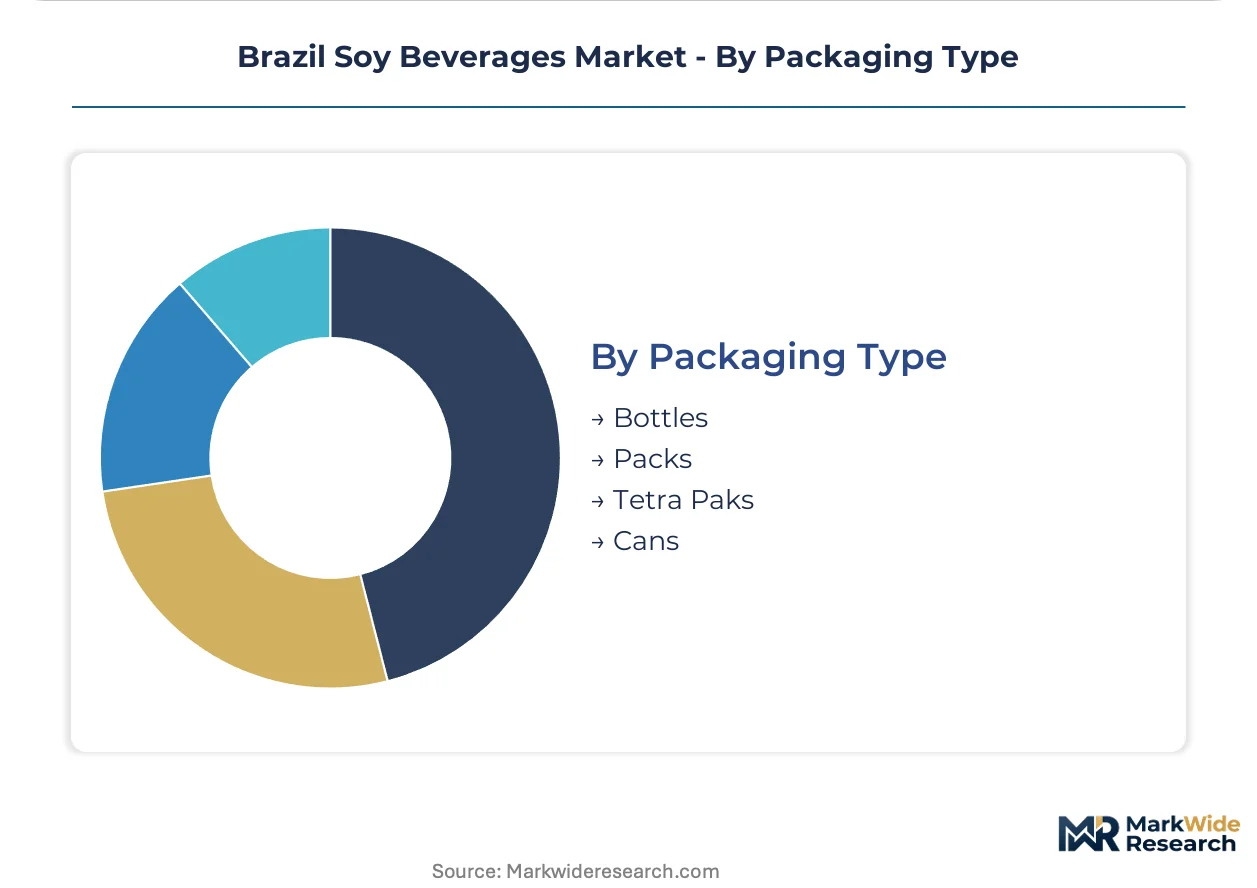
Packaging Type:
Supply concentration for packaging materials shapes regional manufacturing location decisions, with Tetra Pak availability influencing plant siting in southeastern Brazil.
- Tetra Paks:Aseptic carton systems enabling ambient distribution without refrigeration. UHT soy milk relies on this format for Northeast Brazil market access.
- Bottles:PET and HDPE containers for chilled soy milk requiring cold chain maintenance. São Paulo supermarkets prefer transparent formats for visual freshness cues.
- Packs:Multi-unit configurations for household bulk purchasing. Online retail channels favor this format for subscription delivery economics.
- Cans:Metal packaging for single-serve convenience and foodservice portion control. Limited adoption concentrated in institutional channels.
Tetra Paks dominate installed base through UHT volume leadership. Bottles are where expansion concentrates as chilled format growth accelerates in southern metropolitan markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil's soy beverage trade flows reflect domestic crushing capacity advantages, with surplus non-GMO soybean meal exports financing beverage ingredient imports. Regional consumption patterns diverge sharply between southern states with mature cold chains and northern territories dependent on shelf-stable formats.
São Paulo
Metropolitan São Paulo generates premium demand for chilled soy milk through health-conscious households and fitness center chains. ANVISA's front-of-package labeling rules receive strictest enforcement here, pushing manufacturers toward unsweetened formulations. The city's supermarket density enables weekly replenishment cycles that sustain fresh-positioned margins.
Rio de Janeiro
Rio de Janeiro's specialty coffee culture drives barista-grade soy milk procurement through consolidated dairy-alternative distributors. The state's coastal tourism corridor sustains foodservice volume for single-serve ambient formats. ANVISA nutrition claim standards shape competitive positioning in retail channels.
Paraná
Paraná's soybean crushing infrastructure supplies captive non-GMO raw material to adjacent beverage processors. The state's dairy heritage enables technology transfer into fermented soy substrates. Curitiba's health food store concentration anchors organic positioning for premium brands.
Northeast Region
Maranhão and Ceará states depend on UHT soy milk due to persistent cold chain gaps across the region. Mercosur technical regulations on food additives constrain fortification options for cross-border suppliers. Convenience stores capture household penetration through ambient distribution networks.
Amazon Region
Manaus and Belém metropolitan areas present first-mover opportunity for ambient-stable fortified formats. The region's isolation from southern supply chains necessitates localized production or long-haul logistics investment. ANVISA allergen labeling compliance adds complexity to product launch timelines.
Brazil Soy Beverages Market Competitive Environment
On the supply side, the industry is consolidating around three structural tiers: dairy-origin diversifiers leveraging chilled distribution infrastructure, soybean processors integrating downstream into beverage production, and multinational specialists deploying R&D platforms for fermented formats. Strategic archetypes include backward-integrated crushers, asset-light equipment lessees, and culture-technology licensors. Competitive moves concentrate on captive non-GMO supply contracts and direct-to-fitness-center procurement agreements that bypass retail slotting structures.
Among Brazil-based dairy-origin diversifiers, Jussara SA and Piracanjuba exemplify the infrastructure-leverage archetype, converting Paraná and Minas Gerais chilled networks toward plant-adjacent portfolios. Danone S.A anchors the multinational specialist tier, representing fermentation technology transfer from dairy cultures into soy substrates. These three occupy positions across distinct competitive vectors rather than direct confrontation.
| Leading Market Players |
|---|
| Jussara SA |
| Kikkoman Corporation |
| The Hain Celestial Group |
| Pureharvest |
| Campbell Soup Company |
| Danone S.A |
| Lactalis |
| Piracanjuba |
| The Coca-Cola Company |
| Others |
Value Chain & Pricing Dynamics
Paraná and Rio Grande do Sul's non-GMO soybean crushing concentration feeds directly into premium margin capture for chilled soy milk in São Paulo supermarkets. This upstream geographic lock shapes downstream pricing power, with captive supply contracts enabling formulation premiums that ambient-stable competitors cannot match.
Pricing Analysis
Fitness center procurement managers anchor a bifurcated pricing structure across Brazil's soy beverage market. Three-tier pricing stratifies across premium organic positioning, standard refrigerated formats, and economy UHT alternatives, with ANVISA's pending front-of-package warning labels compressing margins on sweetened variants. Cost compression in flavored segments is intensifying as stevia reformulation expenses accumulate, while institutional buyers in gym chains exhibit lowest price sensitivity due to amenity bundling economics.
Supply Chain Analysis
Single-source vulnerability around Tetra Pak aseptic carton supply dominates risk exposure for Northeast Brazil's UHT-dependent markets. Manufacturing draws from Paraná crushing infrastructure, São Paulo processing equipment lessors, and Minas Gerais dairy-origin distribution networks. Distribution runs through Jussara SA's chilled logistics footprint in southern states alongside convenience store aggregation in Maranhão and Ceará.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Brazil's soy beverage market sits in early-cycle expansion, with fitness center channel standardization and ANVISA labeling clarity accelerating household penetration beyond traditional lactose-free niches.
For Market Incumbents: Insulate premium positioning by locking multi-year non-GMO supply contracts with Paraná crushers before capacity constraints tighten. Accelerate R&D allocation toward unsweetened base formulations that bypass ANVISA's octagonal warning triggers, while defending refrigerated shelf space against emerging oat-based substitutes through direct store delivery investments.
For New Entrants and Emerging Players: Pursue Amazon region white space through ambient-stable fortified formats targeting Manaus and Belém's distribution isolation. The institutional procurement channel offers lowest barrier-to-entry, with direct-to-fitness-center agreements bypassing supermarket slotting fees that incumbent dairy-origin players dominate.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with soybean processors holding captive crushing capacity but lacking downstream beverage expertise. Long-term viability hinges on cold chain infrastructure convergence across southern Brazil, with the signal to monitor being supermarket chilled display allocation rates in Rio de Janeiro metro expansion corridors.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Non-GMO Crushing | Captive soybean supply from Paraná crushers secures formulation differentiation against commodity UHT competitors. |
| Direct-to-Fitness-Center Procurement Agreements | Institutional bulk contracts with São Paulo gym chains bypass retail slotting fee structures entirely. |
| Stevia Reformulation Investment | Natural sweetener adoption maintains palatability while avoiding ANVISA's front-of-package sugar warnings. |
| Amazon Region Production Footprint | Localized Manaus manufacturing addresses Belém distribution isolation and long-haul logistics cost premiums. |
| Soy-Based Yogurt R&D Platform | Fermentation technology transfer from dairy cultures captures premium refrigerated margins in Curitiba health food channels. |
Study Parameters
Cross-validation between ANVISA regulatory filings and supermarket chain category buyer interviews anchors the qualitative findings. Primary fieldwork encompassed beverage formulation scientists, chilled distribution logistics managers, fitness center procurement directors, and Paraná soybean crushing operations heads. Secondary sources included ANVISA nutrition labeling guidance documents, Mercosur technical regulations on food additives, customs records for soybean meal trade flows, and Nielsen retail audit data from São Paulo and Rio de Janeiro metro areas. Bottom-up volume estimates from individual processor capacity triangulated against top-down household penetration models.
Calibration against historical cold chain investment cycles and UHT equipment leasing contract structures shaped the analytical framework across the analysis window. Segmentation dimensions encompassed product format, end-user concentration, distribution channel density, and packaging technology availability. CAGRs derived from installed base growth rates adjusted for regulatory inflection points, with forecast inputs including ANVISA compliance timeline probabilities and fitness center chain expansion announcements.
The forecast holds incumbent behavior within observed patterns; aggressive moves by multinational dairy diversifiers would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plant Based Food
Australia Plant Protein Market
Plant Based Food
Canada Plant Protein Market
Plant Based Food
Global Vegan Fast Foods Market
Plant Based Food
North America Textured Vegetable Protein Market
Plant Based Food
Packed Vegan Foods Market
Plant Based Food
Europe Rice Protein Market
Plant Based Food
Vegan Protein Blend Market
Plant Based Food
Vegan Steak Market
Plant Based Food
Vegan Dips Market
Plant Based Food
Fermented Plant-Based Ingredient Market
Plant Based Food
Plant-Based Sausages Market
Plant Based Food
Vegan Bacon Market
Plant Based Food
Vegan Alternatives Market
Plant Based Food
Vegan Noodles Market
Plant Based Food
North America Tofu Market
Plant Based Food
Africa Pea Protein Market