
 North America Nuclear Power Plant and Equipment Market | 2026-2036
North America Nuclear Power Plant and Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
North America Nuclear Power Plant and Equipment Market Analytics
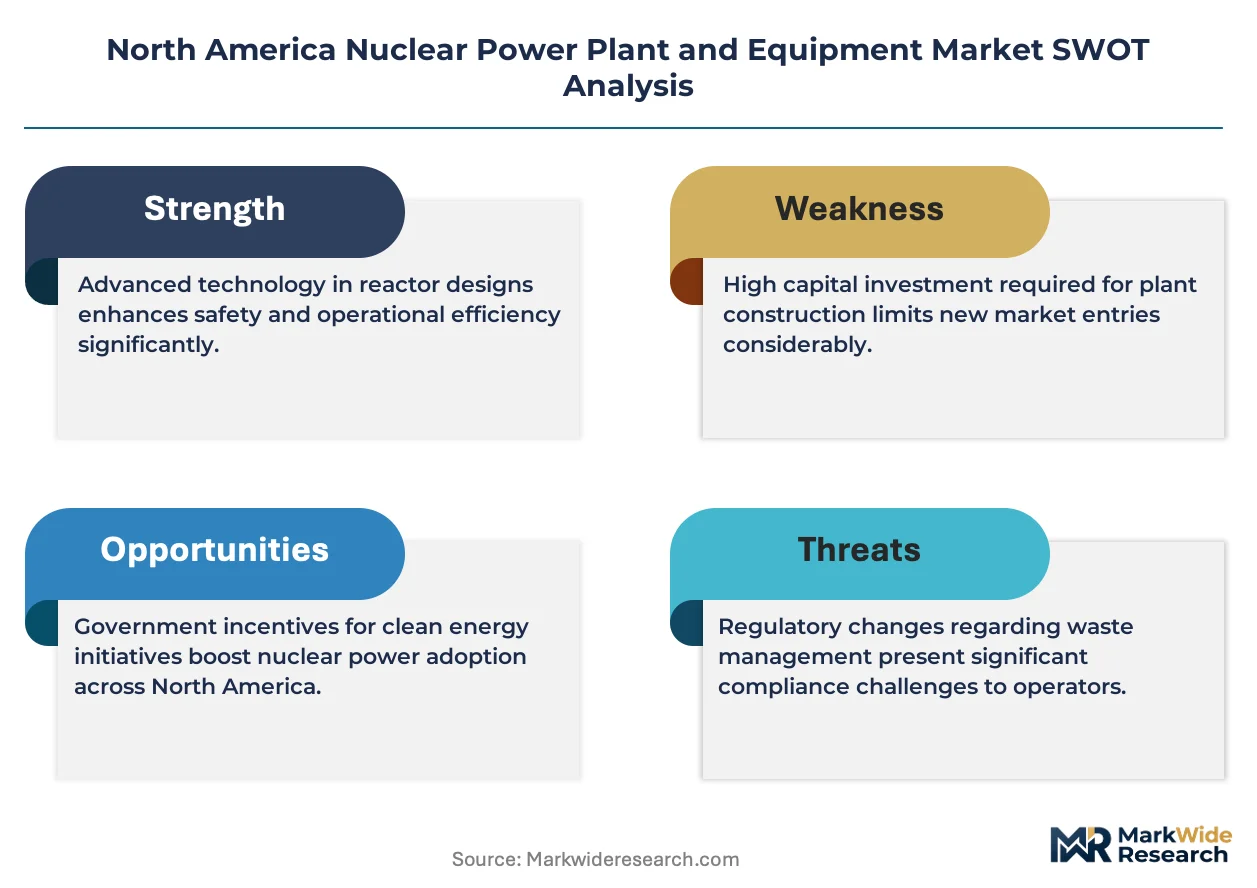
Utility procurement priorities is recalibrating as independent power producers and government entities diversify baseload portfolios toward carbon-free generation. Westinghouse Electric Company LLC leverages its AP1000 reactor platform and extensive U.S. licensing history to anchor large-scale project pipelines. GE-Hitachi Nuclear Energy competes through its BWRX-300 small modular reactor design, targeting cost reductions through standardized manufacturing. NuScale differentiates as the first SMR design to receive U.S. Nuclear Regulatory Commission design certification, positioning early-mover advantage in a tightening regulatory queue.
North America nuclear power plant and equipment encompasses the engineered systems, pressure-boundary components, and control mechanisms required to sustain controlled fission reactions, with reactor pressure vessels forged from SA-508 Grade 3 steel to contain primary coolant at approximately 15.5 MPa and 320°C. Steam generators transfer thermal energy to secondary loops, driving turbine-generator sets for grid-scale electricity delivery. PWR technology dominates installed capacity across the region, reflecting decades of operational maturity and established supply chains for replacement steam generators and reactor vessel heads. SMR technology represents the fastest-expanding segment, with engineering services and modular fabrication attracting capital as developers seek factory-built deployment models. Fuel assembly demand sustains recurring revenue pools tied to operating reactor fleets, while decommissioning services accumulate contract backlogs as first-generation plants reach end-of-life.
The U.S. Nuclear Regulatory Commission enforces 10 CFR Part 50 and Part 52 licensing pathways, with Part 52's combined construction and operating license reducing regulatory uncertainty for new reactor investments. Canada's Canadian Nuclear Safety Commission oversees vendor design reviews under its pre-licensing framework, creating parallel market access requirements for equipment suppliers serving Ontario Power Generation and Bruce Power refurbishment programs. The U.S. Inflation Reduction Act production tax credits for existing and advanced nuclear facilities directly shape utility investment timelines and equipment procurement schedules. Stakeholders must monitor NRC rulemaking on advanced reactor emergency preparedness and CNSC updates to the Nuclear Safety and Control Act regulations to anticipate compliance-driven equipment specification changes.
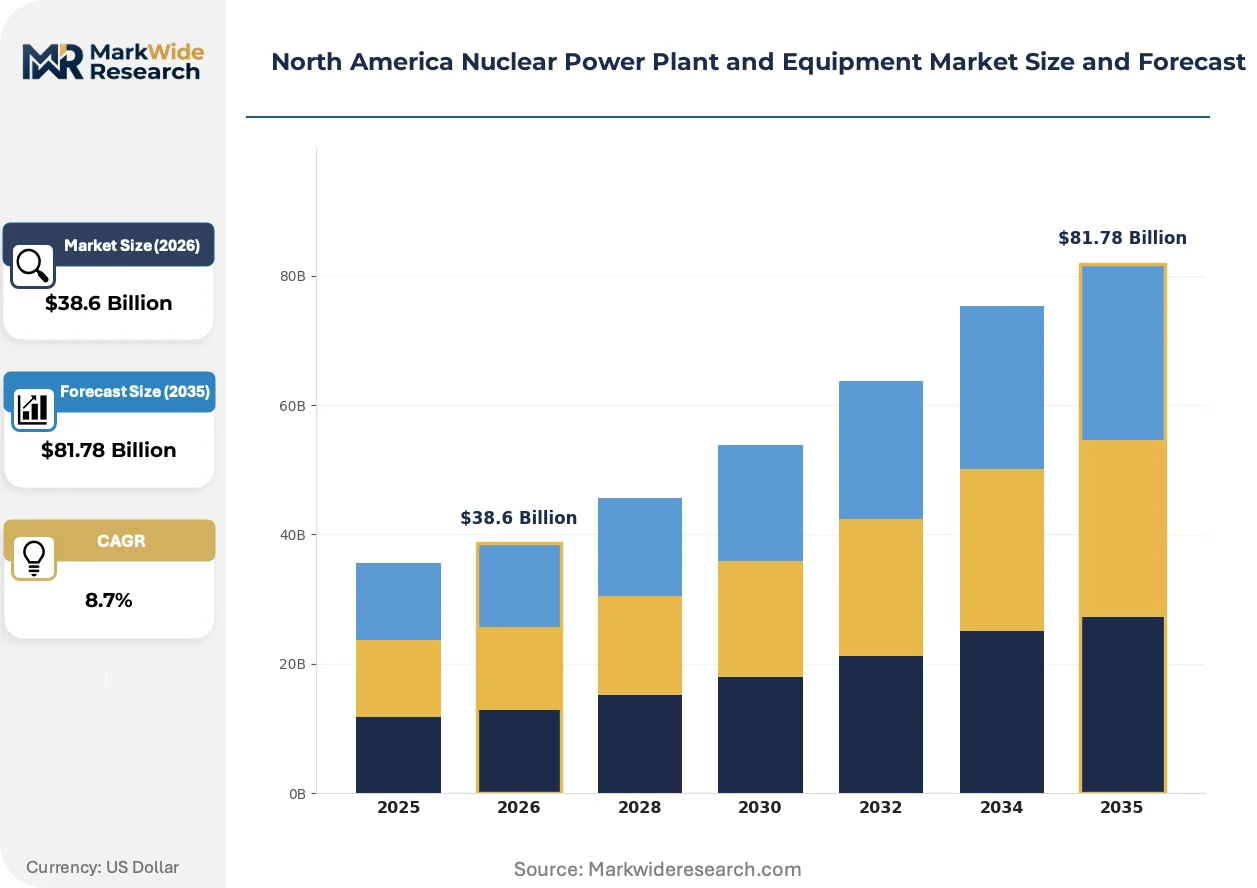
Market Dynamics
The U.S. Nuclear Regulatory Commission's Part 52 licensing framework for small modular reactors is compressing deployment timelines and redirecting capital toward factory-fabricated pressure vessel forgings and modular steam generator assemblies.
Growth Catalysts
- Production Tax Credits:The U.S. Inflation Reduction Act extends credits to existing and advanced nuclear facilities, directly accelerating utility procurement schedules for replacement steam generators and reactor vessel heads.
- Carbon-Free Baseload Mandates:Utility companies across the U.S. Southeast are expanding capacity commitments to replace retiring coal assets, concentrating demand for PWR technology and associated pressure-boundary equipment.
- SMR Design Certification:The NRC's streamlined review pathway for standardized small modular reactor designs reduces regulatory uncertainty and enables multi-unit order books for modular fabrication facilities.
Market Restraints
- SA-508 Steel Supply Concentration:Reactor pressure vessel forgings depend on a limited number of heavy forge facilities capable of meeting ASME Section III specifications, creating single-source vulnerability for 15.5 MPa containment components.
- Extended NRC Review Queues:The regulatory backlog for new reactor licenses stretches equipment procurement timelines and compresses vendor cash conversion cycles.
- Natural Gas Price Volatility:Competing baseload generation from combined-cycle gas turbines creates dispatch uncertainty that delays utility commitment to nuclear capacity additions.
Strategic Opportunities
- Canadian Refurbishment Programs:Ontario Power Generation and Bruce Power are executing multi-year reactor life extension projects, opening procurement windows for replacement fuel channels and steam generator tubing.
- Decommissioning Services Backlog:First-generation U.S. plants reaching end-of-life are accumulating contracts for segmentation equipment, waste handling systems, and site remediation technology.
- Digital Instrumentation Convergence:Integration of advanced sensor networks with legacy reactor protection systems creates demand for cybersecurity-hardened control platforms in both new-build and retrofit applications.
Industry Challenges
- Welding Inspector Certification Bottlenecks:ASME Section IX qualified welders and NDE technicians for SA-508 Grade 3 vessel fabrication remain scarce, extending manufacturing lead times at heavy forge facilities.
- Legacy Control System Integration:Analog-to-digital instrumentation upgrades at operating PWR facilities require complex licensing amendments and hardware qualification testing under 10 CFR Part 50.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Nuclear Power Plant and Equipment Market |
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $81.78 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reactor Pressure Vessel, Steam Generator, Control Rod, Fuel Assembly Technology: PWR, BWR, SMR, Advanced Gas-Cooled End User: Utility Companies, Independent Power Producers, Government Entities, Research Institutions Service Type: Maintenance, Operation, Engineering, Decommissioning |
| Companies Covered | Westinghouse Electric Company LLC, GE-Hitachi Nuclear Energy, Babcock & Wilcox Company, Doosan Corporation, Mitsubishi Heavy Industries Ltd, BWX Technologies, Dongfang Electric Corp Limited, Framatome, NuScale Power, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Nuclear Power Plant and Equipment Market Evolving Landscape
Digital twin technology and additive manufacturing are converging to reshape how pressure-boundary components are fabricated, inspected, and deployed across North American nuclear fleets.
Advanced manufacturing is unifying design, simulation, and production workflows for reactor pressure vessel components. Forge operators are adopting electron beam welding and cold spray deposition to reduce lead times for SA-508 Grade 3 forgings. This unifying capability is compressing the traditional 24-36 month vessel delivery cycle and enabling just-in-sequence modular assembly.
The U.S. Nuclear Regulatory Commission is finalizing guidance on risk-informed emergency preparedness for advanced reactor designs. This regulatory evolution reduces offsite emergency planning zone requirements for SMR deployments. Developers in the U.S. Southeast are responding by siting projects closer to industrial load centers previously excluded by 10-mile exclusion zone constraints.
Utility engineering departments are consolidating procurement authority for multi-unit reactor projects under centralized technical specifications teams. Traditional equipment specification by individual plant engineering groups is yielding to fleet-standardized procurement packages negotiated at the holding company level. This concentration is most visible at utilities operating six or more PWR units across the U.S. Southeast and Texas.
North America Nuclear Power Plant and Equipment Market Segmentation
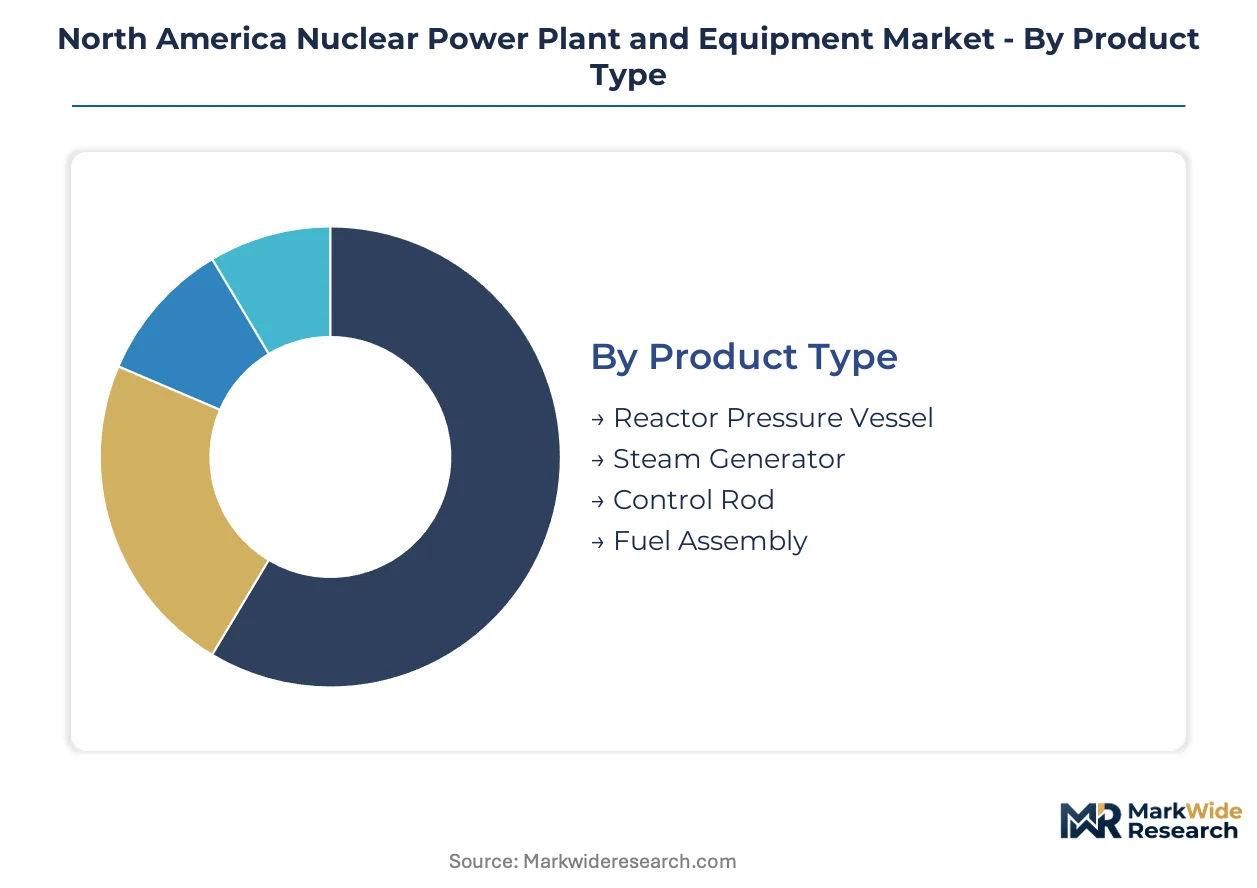
Equipment segmentation in the North America nuclear market reveals how capital flows concentrate around pressure-boundary components and how technology choices reshape procurement patterns across utility fleets. Understanding these divisions exposes where forge capacity bottlenecks and modular fabrication opportunities intersect.
Product Type:
Heavy forge capacity concentrates around a handful of facilities capable of producing ASME Section III-certified pressure-boundary components, creating supply-side gatekeepers for the most capital-intensive equipment categories.
- Reactor Pressure Vessel:Forged from SA-508 Grade 3 steel to contain primary coolant at approximately 15.5 MPa and 320°C. Demand concentrates at U.S. Southeast utilities pursuing reactor life extensions, where replacement vessel heads require 24-36 month lead times and single-source procurement from domestic heavy forge facilities.
- Steam Generator:Heat exchangers transferring thermal energy from primary to secondary loops, with Alloy 690 tubing specified for corrosion resistance. Ontario Power Generation and Bruce Power refurbishment programs in Canada drive replacement demand, while U.S. utilities schedule tube bundle replacements during refueling outages.
- Control Rod:Neutron-absorbing assemblies regulating fission rates through silver-indium-cadmium or boron carbide materials.
- Fuel Assembly:Zirconium-alloy structured bundles containing ceramic uranium dioxide pellets, sustaining recurring revenue tied to operating fleet refueling cycles.
Reactor pressure vessels absorb the bulk of installed capacity capital allocation; steam generators are expanding most quickly through refurbishment-driven replacement cycles.
Technology:
Technology selection across North American fleets reflects decades of operational learning and emerging factory-fabrication economics that favor standardized designs over bespoke engineering.
- PWR:Pressurized water reactors dominate installed capacity across the region, using separate primary and secondary coolant loops. U.S. Southeast utilities rely on established PWR supply chains for replacement steam generators and reactor vessel heads, with operational maturity reducing technical risk for life extension investments.
- SMR:Small modular reactors leverage factory fabrication and standardized manufacturing to compress deployment timelines. The U.S. Nuclear Regulatory Commission's Part 52 licensing framework enables multi-unit order books, with developers targeting cost reductions through modular pressure vessel and steam generator assemblies.
- BWR:Boiling water reactors operate with a single coolant loop, reducing component count but requiring specialized pressure vessel specifications.
- Advanced Gas-Cooled:Helium-cooled designs with graphite moderation, representing early-stage deployment with limited North American supply chain infrastructure.
PWR technology commands the dominant share of operating fleet investment; SMR designs are climbing the fastest as developers secure design certification and utility offtake agreements.
End User:
Procurement authority is consolidating under centralized technical specifications teams as multi-unit operators seek fleet-standardized equipment packages and volume-based supplier negotiations.
- Utility Companies:Vertically integrated electric utilities across the U.S. Southeast and Texas operate six or more PWR units, consolidating procurement authority under holding-company engineering departments. Carbon-free baseload mandates drive capacity expansion commitments, concentrating demand for replacement components and new-build equipment.
- Independent Power Producers:Merchant generators and competitive wholesale market participants diversifying baseload portfolios toward carbon-free generation. IPPs lack the fleet scale of integrated utilities, requiring flexible procurement structures and equipment financing arrangements.
- Government Entities:Federal and state agencies pursuing direct ownership or power purchase agreements for advanced reactor demonstrations.
- Research Institutions:National laboratories and university reactors requiring specialized fuel and control systems for experimental programs.
Utility companies channel the majority of equipment procurement volume; independent power producers are gaining share fastest as competitive wholesale markets open to nuclear capacity.
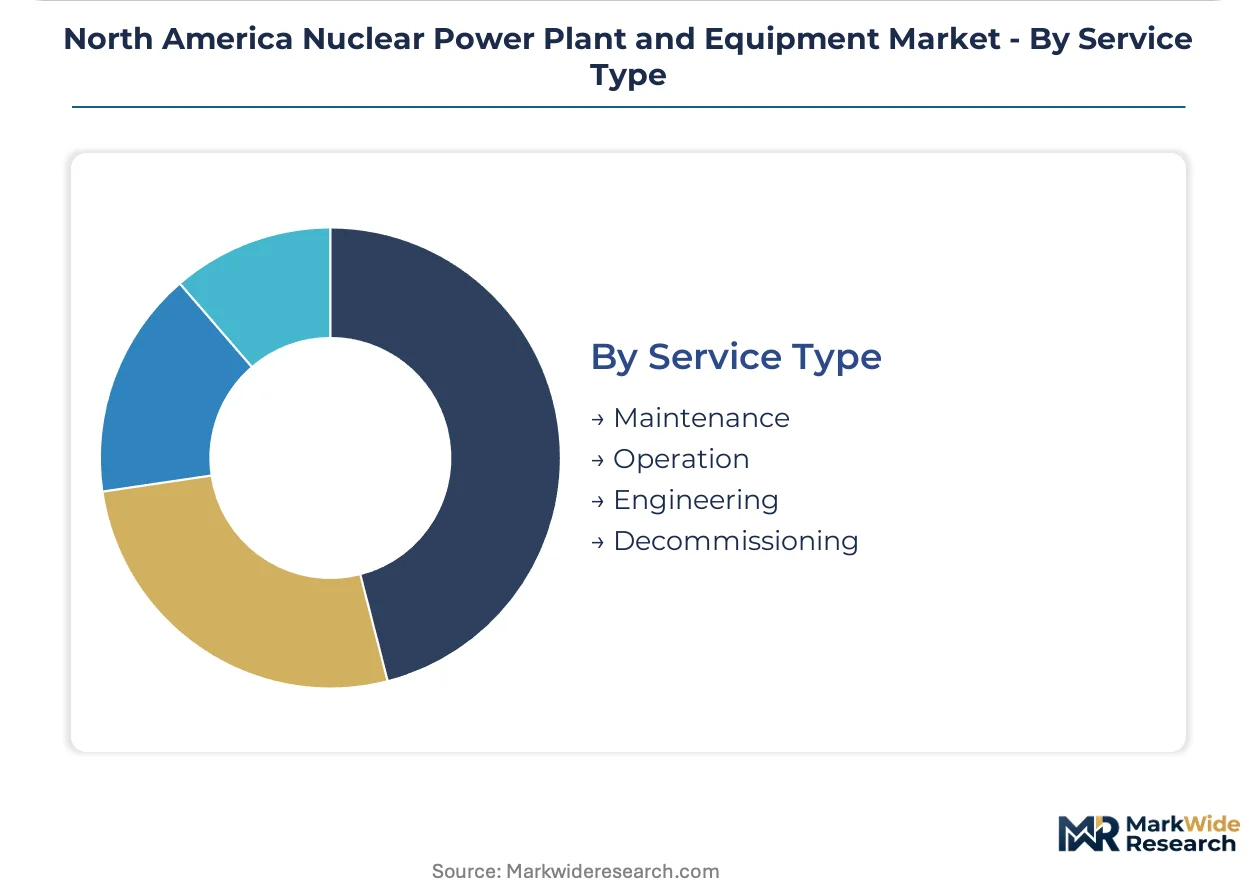
Service Type:
Service segmentation tracks the operational lifecycle from commissioning through end-of-life, with decommissioning services accumulating contract backlogs as first-generation plants reach retirement age.
- Maintenance:Scheduled and corrective activities preserving pressure-boundary integrity, including steam generator tube inspections, reactor vessel head replacements, and control rod drive mechanism overhauls. Refueling outage windows concentrate demand for specialized tooling and qualified welding services.
- Decommissioning:End-of-life segmentation, waste handling, and site remediation for first-generation U.S. plants reaching license expiration. Contractors accumulate backlogs for reactor vessel segmentation equipment, spent fuel dry storage systems, and radiological survey technology.
- Operation:Licensed operator staffing and routine system monitoring sustaining continuous generation.
- Engineering:Design services, licensing support, and plant modifications requiring 10 CFR Part 50 amendment approvals.
Maintenance services capture the largest ongoing revenue pool; decommissioning is expanding most steeply as initial reactor cohorts approach permanent shutdown.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment production concentrates in heavy forge corridors while reactor deployment clusters around carbon-free baseload commitments. Consumption patterns split between U.S. Southeast life extensions and Canadian refurbishment cycles.
United States
Utility procurement for replacement steam generators and reactor vessel heads dominates equipment demand across the Southeast. The U.S. Nuclear Regulatory Commission's Part 52 licensing framework accelerates small modular reactor deployment timelines. Texas and the Carolinas anchor multi-unit operator consolidation under holding-company engineering specifications.
Canada
Ontario Power Generation and Bruce Power drive demand through multi-year reactor life extension programs targeting fuel channel replacements. The Canadian Nuclear Safety Commission's vendor design review pre-licensing framework shapes equipment qualification pathways. The Great Lakes corridor concentrates heavy fabrication and engineering services for pressure-boundary component supply.
Mexico
Federal utility CFE evaluates baseload diversification options as natural gas price volatility disrupts dispatch economics. The national energy regulator oversees grid interconnection standards for potential nuclear capacity additions. Laguna Verde in Veracruz state remains the sole operating facility, with equipment procurement tied to maintenance cycles.
North America Nuclear Power Plant and Equipment Market Competitive Landscape
Top-tier vendors anchor integrated reactor platform supply, while specialized fabricators and modular technology developers populate lower tiers. The structure reflects decades of consolidation around pressure-boundary forging capacity and licensing heritage. Strategic archetypes include full-scope reactor vendors, heavy forge specialists, and SMR technology disruptors. Competitive moves center on design certification acceleration and multi-unit procurement package negotiations.
Among established reactor platform providers, Westinghouse Electric Company LLC and GE-Hitachi Nuclear Energy exemplify the integrated vendor archetype with extensive licensing histories. NuScale Power occupies a position within the emerging SMR tier as the first design to achieve U.S. Nuclear Regulatory Commission certification. These three anchors represent divergent strategic vectors: large-scale proven platforms, cost-reduced modular designs, and first-mover regulatory advantage in factory-fabricated deployment.
| Leading Market Players |
|---|
| Westinghouse Electric Company LLC |
| GE-Hitachi Nuclear Energy |
| Babcock & Wilcox Company |
| Doosan Corporation |
| Mitsubishi Heavy Industries Ltd |
| BWX Technologies |
| Dongfang Electric Corp Limited |
| Framatome |
| NuScale Power |
| Others |
Value Network & Pricing Analysis
ASME Section III certification tiers bifurcate equipment procurement into premium-qualified and non-qualified supply pools, with NRC-accepted heavy forge capacity commanding substantial premiums while uncertified fabricators compete on spot availability for non-safety-grade components. This tier divergence concentrates pricing power among SA-508 Grade 3 vessel forgers in the U.S. and Japan while channeling commodity-grade procurement toward Korean and Chinese secondary suppliers.
Pricing Analysis
Lead-time premiums dominate nuclear equipment pricing, with 12-18 month expedited delivery slots for reactor pressure vessels commanding substantial markups over standard 24-36 month cycles. Project-based long-term offtake contracts anchor utility procurement, with price differentiation driven by ASME certification grade and bundled installation services. Pricing pressure stems from natural gas price volatility compressing utility capital allocation timelines. Merchant IPPs exhibit highest price sensitivity due to financing constraints, while integrated utilities with fleet-scale procurement absorb premium tiers for schedule certainty.
Supply Chain Analysis
Reverse-logistics flows for reactor vessel heads and steam generator components create secondary refurbishment markets, with segmented pressure boundaries re-entering supply chains through certified remanufacturing facilities. Geographic supply concentrates in the United States, Japan, and South Korea for heavy forge capacity, while France and Canada anchor specialized tubing and control system fabrication. Raw material dependencies center on SA-508 Grade 3 steel ingots, Alloy 690 tubing, and boron carbide neutron absorbers. Single-source vulnerability at heavy forge facilities constitutes the primary structural risk. Distribution runs through EPC contractor-led project structures with utility direct procurement for replacement cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Forge capacity scarcity and NRC certification backlogs are forcing consolidation among second-tier fabricators unable to secure ASME Section III accreditation or multi-year utility offtake commitments.
For Market Incumbents: Anchor defensive positioning through captive control of SA-508 Grade 3 steel supply arrangements and accelerated NRC design certification pipelines for SMR platforms. Threats from Korean and Chinese state-backed entrants with subsidized forge capacity require countering via fleet-standardized procurement alliances with U.S. Southeast utilities. Vertical integration into modular fabrication facilities represents the critical capacity lever. For New Entrants and Emerging Players: Begin with digital instrumentation and cybersecurity-hardened control platforms, the most penetrable segment given legacy analog-to-digital upgrade mandates across operating PWR fleets. White-space targets include decommissioning segmentation technology and spent fuel dry storage systems where incumbent concentration remains lowest. Go-to-market execution should prioritize direct contracting with Ontario Power Generation and Bruce Power refurbishment programs. For Investors and Strategic Acquirers: Re-rating potential sits with heavy forge specialists holding active ASME N-stamp certifications given IRA production tax credit acceleration of utility procurement schedules. Long-term viability across the projection horizon favors vendors with demonstrated NRC Part 52 licensing success. Acquisition targets should display multi-unit SMR order book visibility. The signal to watch is NRC rulemaking on advanced reactor emergency preparedness zone reductions enabling industrial co-location projects.| Strategic Initiative | Industry Significance |
|---|---|
| SMR Design Certification Acceleration | NRC Part 52 approval unlocks multi-unit utility order books for factory-fabricated reactor platforms. |
| Heavy Forge Capacity Expansion | Domestic SA-508 Grade 3 forging investment reduces single-source vulnerability for pressure vessel supply. |
| Digital Control System Integration | Cybersecurity-hardened platforms capture analog-to-digital retrofit demand across operating PWR fleets. |
| Decommissioning Services Buildout | Segmentation equipment and waste handling contracts accumulate as first-generation plants reach license expiration. |
| Canadian Refurbishment Partnership | Ontario Power Generation and Bruce Power life extension programs open procurement windows for fuel channel replacements. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews involving utility engineering directors, NRC licensing project managers, heavy forge procurement leads, and EPC contractor executives. Secondary sources included NRC docket filings, EIA electricity market data, Canadian Nuclear Safety Commission vendor design review records, and World Nuclear Association reactor databases. Bottom-up equipment procurement tracking and top-down utility capital expenditure analysis enabled triangulation across data streams.
Data-stream reconciliation across utility announced projects, forge order backlogs, and regulatory approval timelines shaped the analytical framework. Segmentation dimensions modeled encompass reactor technology type, equipment product category, end-user procurement authority structure, and service lifecycle phase. CAGRs derived from equipment unit demand projections and capital cost trajectories across the modeling period. Industry-specific forecast inputs included NRC licensing queue progression rates and Canadian refurbishment outage scheduling.
Underlying measurement precision varies by segment; operating fleet maintenance and established PWR technology carry tighter precision than SMR deployment timelines and advanced reactor development. Forecasts reflect assumptions regarding regulatory approval velocity, utility creditworthiness for project financing, and forge capacity expansion execution. Practitioners should monitor NRC Part 52 certification completions and Ontario Power Generation refurbishment milestone achievements for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nuclear Energy
Nuclear Fuels Market
Nuclear Energy
United States Nuclear Power Plant Equipment Market
Nuclear Energy
Uranium Enrichment Market
Nuclear Energy
Europe Nuclear Reactor Construction Market
Nuclear Energy
Thorium Market
Nuclear Energy
Nuclear Energy Market
Nuclear Energy
North America Nuclear Power Reactor Decommissioning Market
Nuclear Energy
Europe Nuclear Reactor Decommissioning Market
Nuclear Energy
South America Nuclear Reactor Construction Market
Nuclear Energy
Asia-Pacific Nuclear Power Plant and Equipment Market
Nuclear Energy
Germany Nuclear Power Reactor Decommissioning Market
Nuclear Energy
North America Nuclear Reactor Construction Market
Nuclear Energy
Global Molten Salt Reactor Market
Nuclear Energy
Helium-3 Market
Nuclear Energy
Asia-Pacific Nuclear Reactor Construction Market
Nuclear Energy
United Kingdom Nuclear Power Reactor Decommissioning Market