
 Global Nuclear Reactor Construction Market | 2026-2036
Global Nuclear Reactor Construction Market Size, Share, and Industry Trends Forecast 2026-2036
Global Nuclear Reactor Construction Market Analysis
Utility buyer concentration is consolidating as national energy champions bundle reactor orders into multi-unit fleet contracts rather than single-project awards. Rosatom State Nuclear Energy Corporation leverages its integrated project delivery model to anchor turnkey contracts across emerging nuclear markets. Framatome sustains specialized fuel and reactor component supply positions in European refurbishment programs. China National Nuclear Corporation dominates domestic build schedules while extending engineering services to overseas state clients.
Nuclear reactor construction encompasses the engineering, procurement, and assembly of fission-based power generation systems requiring containment structures rated for pressures exceeding 0.5 MPa and seismic Category I foundations. Pressurized water reactor technology occupies the largest installed base, while small modular reactor project types represent the fastest-expanding segment due to shortened construction timelines and lower capital thresholds. Brownfield upgrades and refurbishments concentrate mature margin pools in North America and Western Europe, where license extensions require steam generator replacements and digital instrumentation retrofits.
The International Atomic Energy Agency sets baseline safety standards that national regulators including the US Nuclear Regulatory Commission and France's ASN transpose into binding construction codes and operating licenses. China's National Nuclear Safety Administration and India's Atomic Energy Regulatory Board enforce localization requirements that shape supplier qualification and component sourcing rules. Stakeholders must monitor regulatory divergence between established Western frameworks and emerging market adaptations as SMR deployment scales across jurisdictions with varying indigenous supply chain maturity.
Market Dynamics
State-backed fleet procurement in China and India is compressing project timelines while Western markets grapple with regulatory ratcheting and supply chain requalification burdens. This bifurcation between accelerated deployment zones and permitting-constrained regions defines current competitive positioning.
Growth Catalysts
- China's National Nuclear Safety Administration localization mandates:Domestic content requirements above seventy percent for Generation III reactor builds are cultivating captive forging and heavy component industries. Indigenous supply maturation reduces foreign currency exposure for state utilities.
- Baseload power procurement:Grid operators in India and the United Arab Emirates are prioritizing firm capacity contracts over intermittent renewable PPAs. Nuclear's capacity factor advantages secure multi-decade offtake agreements.
- Small modular reactor standardization:Factory fabrication protocols are collapsing site construction durations from six years to thirty-six months. Design certification reciprocity between the US Nuclear Regulatory Commission and the United Kingdom's Office for Nuclear Regulation accelerates multi-jurisdiction deployment.
Market Restraints
- Specialized steel and large forging supply concentration:Japan Steel Works and Framatome's Le Creusot facility control ninety percent of reactor pressure vessel ingot capacity. Geographic concentration creates single-point vulnerability for project scheduling.
- France's ASN post-Fukushima safety requalification:Enhanced seismic margin requirements and third-party inspection mandates have extended Flamanville EPR commissioning by four years. Regulatory friction inflates capital recovery timelines.
- Natural gas combined-cycle substitution:US shale gas at sub-three-dollar-per-mmbtu pricing undercuts nuclear levelized cost of electricity in deregulated markets. Merchant generators defer nuclear commitments where gas infrastructure exists.
Strategic Opportunities
- Saudi Arabia's National Renewable Energy Program nuclear carve-out:The Kingdom's 2030 diversification targets seventeen gigawatts of atomic capacity. First-mover engineering contractors can anchor decades-long fuel and service relationships.
- Digital twin integration with predictive maintenance:Convergence of physics-based modeling and machine learning analytics enables condition-based component replacement. This shifts revenue from episodic outages to continuous monitoring subscriptions.
- Poland's PGE and ZE PAK coal replacement auctions:Government-backed contracts for difference guarantee strike prices for six to nine gigawatts of new nuclear. Regulatory tailwinds de-risk developer equity returns.
Industry Challenges
- Welding inspector and nuclear-grade certification scarcity:ASME Section III qualified welders and NDE technicians require eight-thousand-hour apprenticeship tracks. Workforce pipelines lag deployment schedules by four to six years.
- First-of-a-kind engineering cost overruns:Novel reactor designs require integrated system validation before commercial operation licenses issue. Capex intensity for initial units frequently doubles reference estimates.
- Spent fuel interim storage licensing:US Nuclear Regulatory Commission dry cask storage certifications face local jurisdiction opposition and environmental review litigation. Intergenerational liability allocation remains unresolved.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Nuclear Reactor Construction Market |
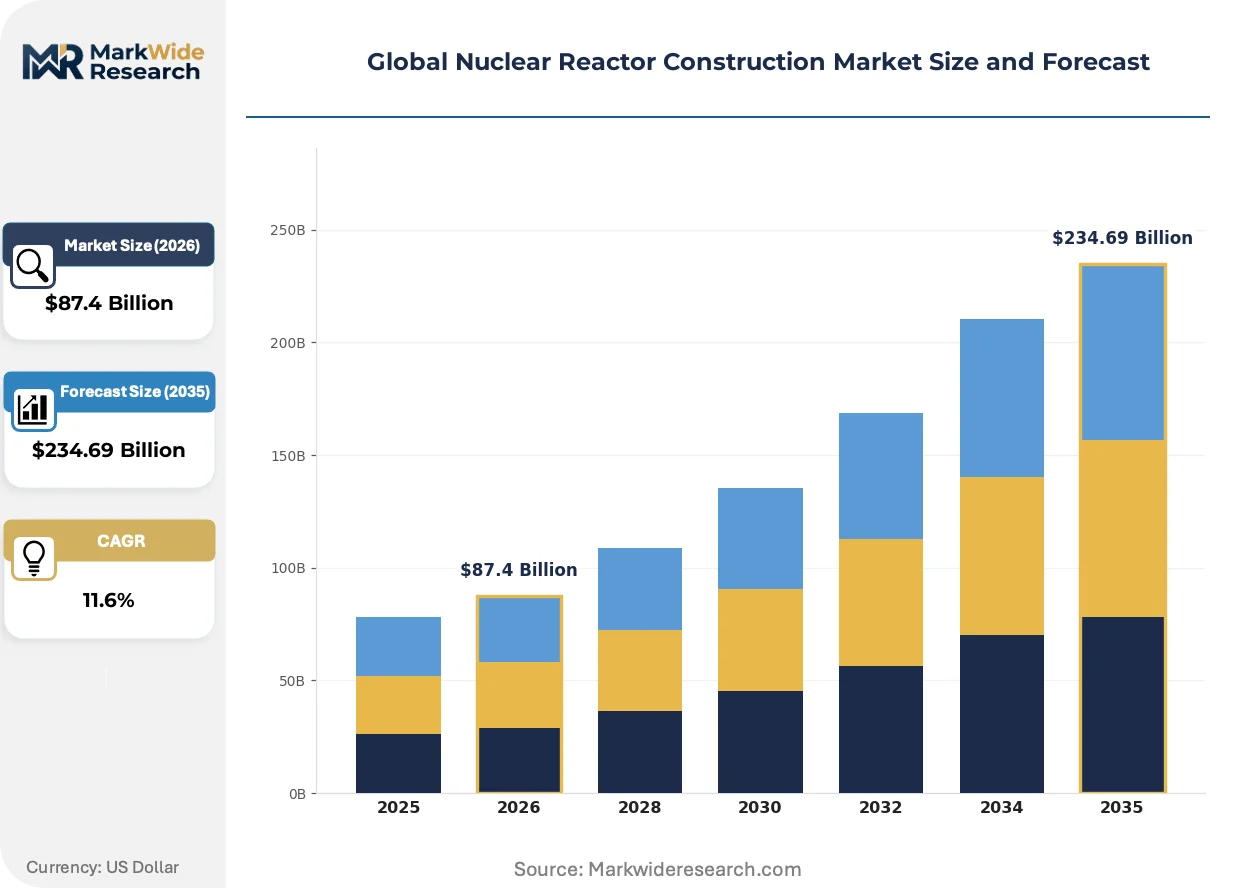
| Market Size in 2026 | $87.4 Billion |
| Market Size in 2035 | $234.69 Billion |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: PWR, BWR, SMR, FBR Project Type: Greenfield, Brownfield, Upgrades, Refurbishments End User: Utilities, Government, Private Sector, Research Institutions Fuel Type: Uranium, MOX, Thorium, Others |
| Companies Covered | Mitsubishi Heavy Industries, Framatome, Rosatom State Nuclear Energy Corporation, BWX Technologies, Doosan Heavy Industries & Construction, Westinghouse Electric Company, Electricite de France, China National Nuclear Corporation, GE-Hitachi Nuclear Energy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Nuclear Reactor Construction Market Emerging Trajectories
Advanced manufacturing and modular construction techniques are collapsing traditional site labor intensity while digital instrumentation retrofits extend operating license viability. These shifts reconfigure supplier value capture and owner-operator cost structures simultaneously.
Passive safety systems employing gravity-driven coolant injection and natural circulation are consolidating Generation III+ reactor designs. Westinghouse AP1000 and Rosatom VVER-1200 deployments in China and Turkey demonstrate elimination of active pump dependencies. This architecture reduces emergency power requirements and containment volumes, compressing capital cost per megawatt by fifteen to twenty percent versus Generation II equivalents.
The European Union's CSRD sustainability reporting mandates and taxonomy classification for nuclear as transitional green finance are reshaping institutional capital access. ESG-constrained pension funds and sovereign wealth vehicles now include atomic generation in eligible infrastructure allocations. French and Swedish utilities leverage this regulatory tailwind to secure green bond financing for refurbishment programs previously excluded from climate-aligned portfolios.
Fleet-scale engineering-procurement-construction contracts are displacing single-unit project awards as the dominant commercial structure. China's State Power Investment Corporation and India's Nuclear Power Corporation of India Limited bundle four-to-six reactor orders under master agreements with fixed escalation clauses. This procurement compression transfers design maturity risk to vendors while securing volume discounts on long-lead forgings and steam generators.
Global Nuclear Reactor Construction Market Segmentation
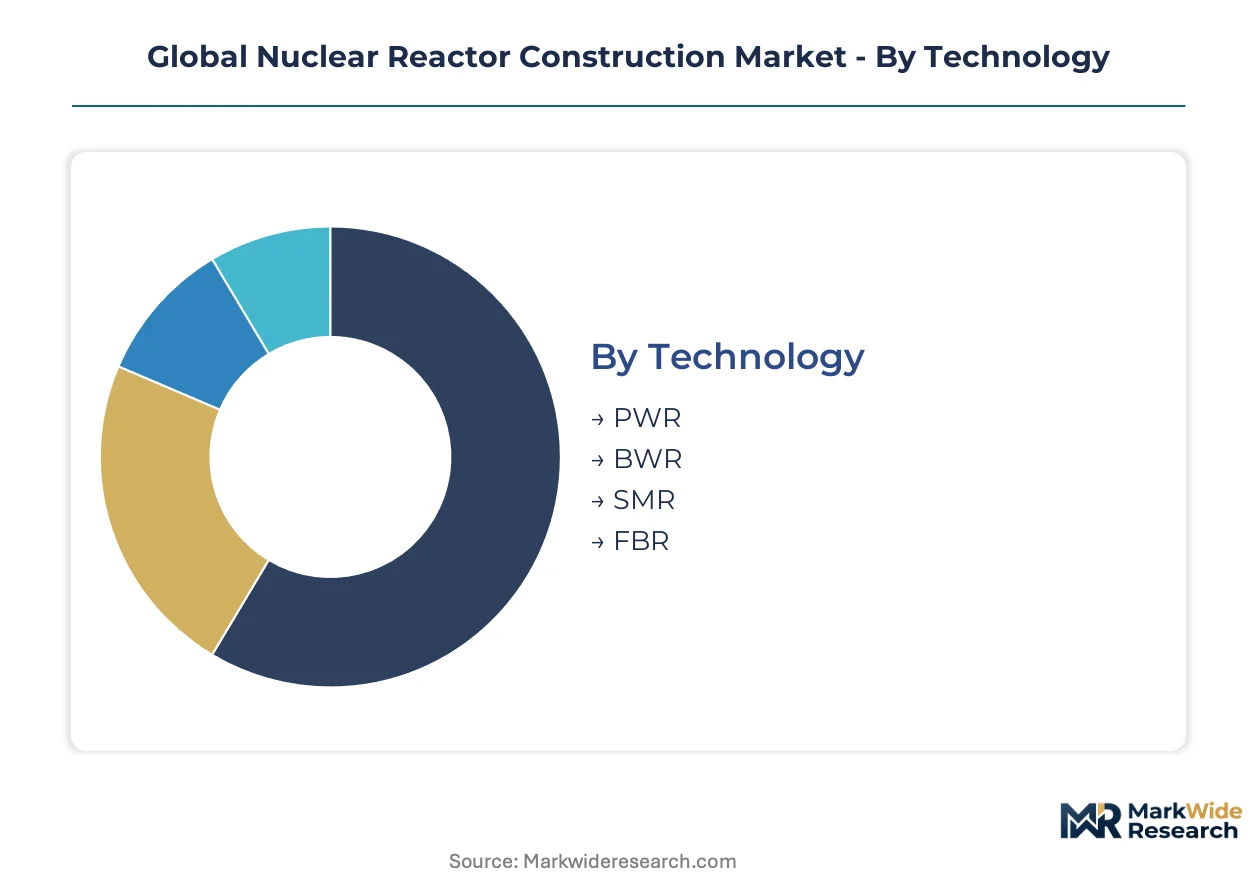
Reactor construction segmentation reveals divergent capital intensity profiles across technology generations and project archetypes. Technology choice determines containment specifications and regulatory pathways, while project type governs construction duration and supply chain mobilization requirements.
Technology:
Upgrade cycles and replacement demand concentrate in mature pressurized water reactor fleets, while emerging designs reshape deployment economics through modular fabrication.
- PWR:Pressurized water reactor technology employs light water coolant and enriched uranium fuel within forged steel pressure vessels rated for 15.5 MPa operating pressure. China's State Power Investment Corporation and France's EDF anchor demand through multi-unit fleet orders spanning Generation III+ deployments. Regulatory harmonization between the US Nuclear Regulatory Commission and France's ASN accelerates design certification reciprocity.
- SMR:Small modular reactors integrate factory-fabricated power modules with capacities below 300 MWe, collapsing site construction from sixty months to thirty-six months through standardized skid mounting. Deployment concentrates in Canada and the United Kingdom where remote industrial loads and district heating applications justify distributed baseload configurations. Canada's SMR Action Plan and the UK's Great British Nuclear program provide dedicated licensing frameworks.
- BWR:Boiling water reactor designs utilize direct steam generation, eliminating steam generators and reducing component count.
- FBR:Fast breeder reactors employ liquid sodium coolant and closed fuel cycles for plutonium breeding.
Volume placements concentrate in PWR technology; the faster expansion belongs to SMR configurations.
Project Type:
Capital allocation patterns split between greenfield megaprojects requiring decade-long construction horizons and brownfield interventions capturing margin in amortized asset bases.
- Greenfield:New site developments encompass complete civil infrastructure including seismic Category I foundations, containment structures, and auxiliary buildings. Saudi Arabia's National Renewable Energy Program and Poland's PGE coal replacement auctions anchor demand through sovereign-backed offtake guarantees. Site preparation and long-lead forging orders precede nuclear concrete pours by eighteen to twenty-four months.
- Refurbishments:Life extension programs replace steam generators, reactor pressure vessel heads, and digital instrumentation systems within licensed operating periods. Canada's Bruce Power and Ontario Power Generation sustain demand through CANDU reactor retubing and feeder replacement campaigns. Canada's CNSC relicensing framework enables sixty-year operating extensions.
- Brownfield:Existing site expansions leverage permitted land buffers and grid interconnection capacity.
- Upgrades:Power uprate modifications increase licensed thermal output through turbine and cooling system enhancements.
Capital deployment concentrates in greenfield projects; the steepest expansion trajectory belongs to refurbishment programs.
End User:
Procurement authority determines risk allocation structures and financing instrument selection across public and private capital pools.
- Utilities:State-owned and investor-owned power companies bundle reactor orders into master engineering-procurement-construction agreements with fixed escalation clauses. India's Nuclear Power Corporation of India Limited and the Emirates Nuclear Energy Corporation anchor demand through sovereign credit-backed project finance. Multi-decade power purchase agreements transfer demand risk to offtakers.
- Government:Direct state procurement supports naval propulsion, research reactors, and strategic isotope production facilities. Russia's Rosatom State Nuclear Energy Corporation and China's China National Nuclear Corporation integrate civilian and military supply chains through vertically controlled procurement.
- Private Sector:Independent power developers and industrial energy consumers pursue captive generation for data centers and hydrogen production.
- Research Institutions:National laboratories and universities commission experimental reactors for materials testing and medical isotope production.
Contract volume concentrates in utility procurement; the fastest share gains belong to government-direct programs.
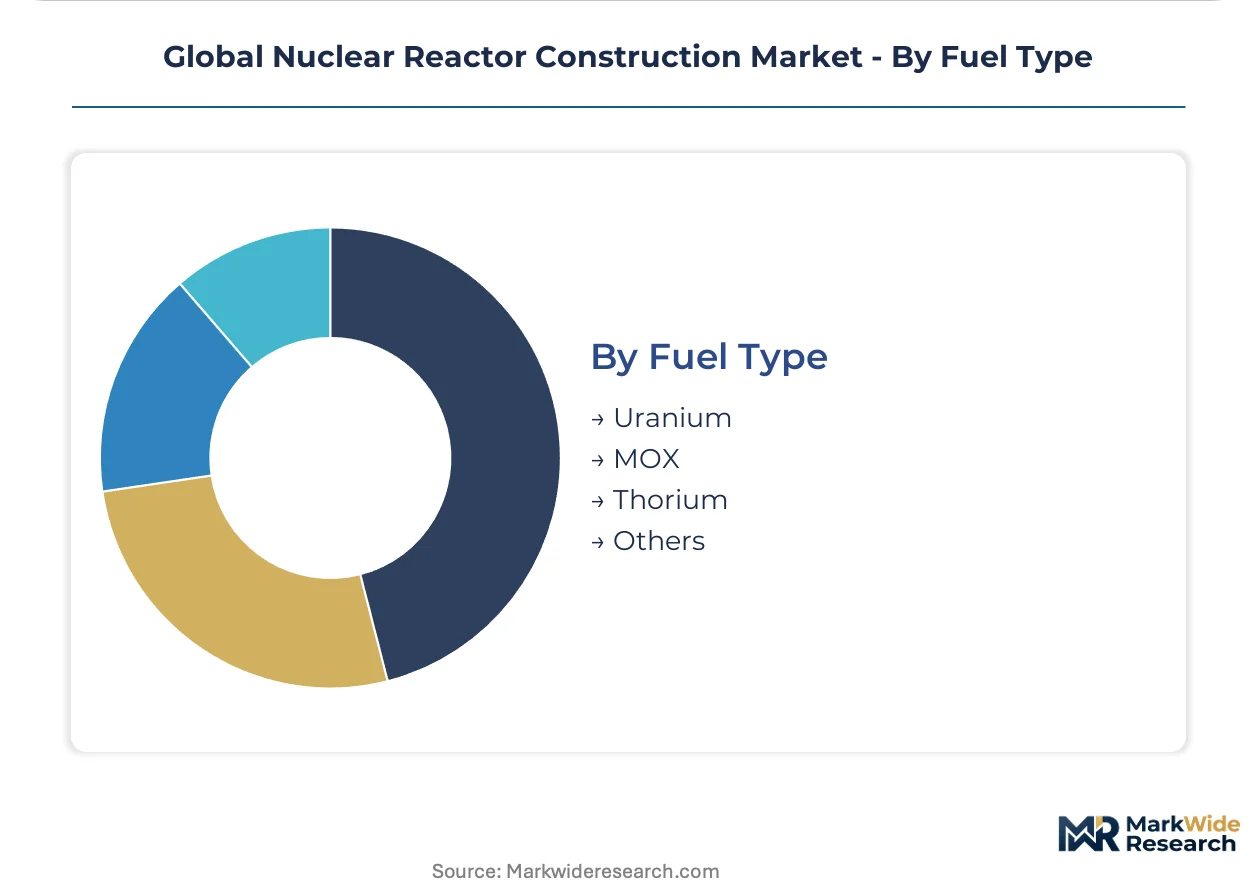
Fuel Type:
Fuel cycle configuration shapes enrichment services demand and spent fuel management liability structures across reactor operating lifetimes.
- Uranium:Low-enriched uranium fuel dominates commercial light water reactor fleets, requiring conversion and enrichment services from Kazakhstan's Kazatomprom and Canada's Cameco. Kazakhstan's uranium mining concentration and Russia's Tenex enrichment services shape supply security planning.
- MOX:Mixed oxide fuel blends plutonium from reprocessed spent fuel with depleted uranium, closing the fuel cycle in France's La Hague and the UK's Sellafield facilities. France's ASN and the UK's ONR regulate fabrication and transport licensing.
- Thorium:Thorium-uranium fuel cycles offer proliferation resistance and reduced transuranic waste profiles.
- Others:High-assay low-enriched uranium and accident-tolerant fuel compositions address enhanced safety margins.
Fuel loadings concentrate in uranium cycles; the most rapid technology maturation belongs to MOX fabrication.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China and India concentrate the majority of new reactor demand through state-backed fleet procurement programs. Construction timelines in these markets compress against permitting-constrained Western jurisdictions.
United States
The US Nuclear Regulatory Commission certifies designs including Westinghouse AP1000 and GE-Hitachi BWRX-300 for domestic deployment. Vogtle Units 3 and 4 in Georgia represent the first new commercial reactors in three decades. Texas and the Southeast host merchant generators evaluating SMR configurations for industrial offtake.
China
State Power Investment Corporation and China National Nuclear Corporation execute multi-unit Hualong One deployments across coastal provinces. The National Nuclear Safety Administration enforces localization mandates exceeding seventy percent domestic content. Taishan and Sanmen clusters anchor Generation III+ construction with accelerated commissioning schedules.
France
Electricite de France pursues Flamanville EPR completion and Penly new-build preparations under ASN oversight. Post-Fukushima seismic margin requirements extended regulatory review timelines. Le Creusot forging facilities and Normandy nuclear clusters sustain component supply for domestic and export programs.
India
Nuclear Power Corporation of India Limited bundles indigenous PHWR builds with imported light water reactor partnerships. The Atomic Energy Regulatory Board licenses Kudankulam VVER units and forthcoming Jaitapur EPR installations. Gujarat and Tamil Nadu host operational fleets with Rajasthan and Haryana targeted for expansion.
United Arab Emirates
Emirates Nuclear Energy Corporation commissioned Barakah's four APR-1400 units as the Arab world's first commercial nuclear fleet. The Federal Authority for Nuclear Regulation licenses operations and oversees fuel procurement security. Abu Dhabi anchors regional capacity with potential Gulf Cooperation Council export of engineering services.
Global Nuclear Reactor Construction Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue small modular reactor specialization and digital service integration. The vendor structure concentrates around integrated project delivery specialists, component fabricators with forging capabilities, and fuel cycle service providers. Three archetypes dominate: state-owned energy champions bundling turnkey contracts, heavy industrial conglomerates with pressure vessel manufacturing assets, and technology licensors monetizing design certification across multiple jurisdictions. Competitive positioning depends on regulatory reciprocity agreements and long-lead forging queue access.
Within the state-owned champion tier, Rosatom State Nuclear Energy Corporation and China National Nuclear Corporation exemplify vertically integrated project delivery models spanning engineering, procurement, and fuel services. Framatome occupies a specialized position in European fuel fabrication and component supply. Westinghouse Electric Company and GE-Hitachi Nuclear Energy represent technology licensors pursuing SMR certification reciprocity between the US Nuclear Regulatory Commission and international regulators. Mitsubishi Heavy Industries and Doosan Heavy Industries anchor Asian fabrication capacity for pressure vessels and steam generators.
| Leading Market Players |
|---|
| Mitsubishi Heavy Industries |
| Framatome |
| Rosatom State Nuclear Energy Corporation |
| BWX Technologies |
| Doosan Heavy Industries & Construction |
| Westinghouse Electric Company |
| Electricite de France |
| China National Nuclear Corporation |
| GE-Hitachi Nuclear Energy |
| Others |
Supply Flow & Price Mechanics
Utility fleet procurement consolidation into multi-unit master agreements is forcing vendors to absorb design maturity risk and commit to fixed escalation clauses, compressing margins on long-lead forgings while elevating premium capture for certified component suppliers.
Pricing Analysis
Volume placements concentrate in standardized Generation III+ reactor packages where scale economies offset thin per-unit margins, while bespoke engineering-procurement-construction contracts for first-of-a-kind designs command substantial risk premiums. Price differentiation hinges on ASME Section III certification tier and domestic content compliance ratios, with China National Nuclear Corporation localization mandates above seventy percent reshaping supplier qualification costs. Pricing pressure stems from natural gas combined-cycle substitution in deregulated markets where shale gas pricing undercuts nuclear baseload economics. State-owned utilities exhibit lowest price sensitivity given sovereign credit backing, while merchant generators in competitive markets defer commitments absent contract-for-difference guarantees.
Supply Chain Analysis
Single-source vulnerability sits with Japan Steel Works and Framatome's Le Creusot facility, which anchor reactor pressure vessel ingot capacity for Western-deployed fleets. Geographic supply concentration centers on China, Japan, and France for heavy forgings, with South Korea's Doosan Heavy Industries expanding steam generator fabrication. Raw material dependencies draw from specialized steel alloys, zirconium tubing, and enriched uranium conversion services. Supply chain risk manifests through seismic requalification delays at forging facilities extending delivery queues. Distribution runs through engineering-procurement-construction contractors bundling component procurement under turnkey contracts with fixed escalation clauses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Reactor pressure vessel forging queue scarcity props pricing power for qualified suppliers, with Japan Steel Works and Le Creusot capacity fully committed through the mid-projection horizon.
For Market Incumbents: Anchor market position through backward integration into heavy forging capacity or exclusive long-lead component queue reservations with Japan Steel Works and Doosan Heavy Industries. Defend against small modular reactor entrants by accelerating Generation III+ design certification reciprocity between the US Nuclear Regulatory Commission and emerging market regulators. Prioritize digital twin service bundling to shift revenue from episodic outages toward continuous monitoring subscriptions. For New Entrants and Emerging Players: Capture white-space in small modular reactor factory fabrication protocols where site construction duration compression from sixty months to thirty-six months resets competitive economics. Target Canada's SMR Action Plan and the United Kingdom's Great British Nuclear program where dedicated licensing frameworks reduce regulatory friction. Pursue district heating and remote industrial load configurations as anchor applications bypassing transmission interconnection bottlenecks. For Investors and Strategic Acquirers: Re-rating potential sits with specialized fuel fabricators and digital instrumentation providers given EU CSRD taxonomy classification for nuclear as transitional green finance unlocking institutional capital access. Long-term viability favors suppliers with demonstrated regulatory reciprocity across US, French, and British frameworks. Monitor US Nuclear Regulatory Commission SMR design certification velocity as inflection indicator for factory fabrication scale economics.| Strategic Initiative | Industry Significance |
|---|---|
| Long-lead Forging Queue Reservation | Japan Steel Works capacity commitments lock in component delivery priority for fleet-scale deployments. |
| Digital Twin Platform Integration | Physics-based modeling convergence with machine learning analytics enables predictive maintenance subscription revenues. |
| Regulatory Reciprocity Expansion | Design certification harmonization between US NRC and UK ONR accelerates multi-jurisdiction SMR deployment. |
| Domestic Content Localization | China's National Nuclear Safety Administration mandates above seventy percent cultivate captive forging industries. |
| Green Bond Financing Access | EU CSRD taxonomy inclusion enables French and Swedish utilities to secure climate-aligned infrastructure capital. |
Methodological Framework
Independent corroboration across utility procurement officers, EPC contractor project directors, and nuclear regulatory affairs specialists underwrites the qualitative findings. Primary fieldwork with reactor vendor business development leads and forging facility operations managers combined with secondary validation from IAEA safety standards documentation, national regulatory commission licensing databases, and project finance disclosure records. Bottom-up segmentation modeling triangulated against top-down macro demand projections from grid operator capacity expansion filings.
Rate-of-change decomposition across technology generation transitions, regulatory framework adaptations, and supply chain localization mandates shaped the analytical framework. Segmentation dimensions modeled span reactor technology, project archetype, procurement authority structure, and regional regulatory cluster. CAGRs derived from installed capacity build schedules, fleet order pipelines, and refurbishment campaign timelines. Forecast inputs incorporated long-lead forging queue durations and design certification reciprocity velocity between national regulators.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to seismic requalification delays, welding inspector certification pipeline gaps, and spent fuel interim storage licensing litigation. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nuclear Energy
United Kingdom Nuclear Power Reactor Decommissioning Market
Nuclear Energy
Nuclear Power Market
Nuclear Energy
China Nuclear Power Plant Equipment Market
Nuclear Energy
Germany Nuclear Power Reactor Decommissioning Market
Nuclear Energy
Uranium Enrichment Market
Nuclear Energy
Nuclear Power Plant Equipment Market
Nuclear Energy
North America Nuclear Power Reactor Decommissioning Market
Nuclear Energy
Europe Nuclear Reactor Decommissioning Market
Nuclear Energy
North America Nuclear Reactor Construction Market
Nuclear Energy
Small Modular Reactor (SMR) Market
Nuclear Energy
Helium-3 Market
Nuclear Energy
United States Nuclear Power Plant Equipment Market
Nuclear Energy
Fusion Power Market
Nuclear Energy
Thorium Market
Nuclear Energy
Middle-East and Africa Nuclear Power Plant Equipment Market
Nuclear Energy
Nuclear Power Pump Market