
 United Kingdom Nuclear Power Reactor Decommissioning Market | 2026-2036
United Kingdom Nuclear Power Reactor Decommissioning Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Nuclear Power Reactor Decommissioning Market Analytics
Specialist contractor networks is reconfiguring as tier-one engineering groups consolidate decommissioning partnerships across Magnox and advanced gas-cooled reactor sites. Babcock International Group PLC leverages its submarine reactor heritage to anchor naval and civil decommissioning capabilities. Sellafield Ltd dominates high-hazard legacy pond retrieval and vitrification operations at the Cumbria complex. James Fisher & Sons PLC specializes in underwater engineering and containment solutions for flooded reactor vessels.
United Kingdom nuclear power reactor decommissioning encompasses the engineered dismantling, waste conditioning, and site release of ceased fission plants, typically involving graphite core removal, irradiated fuel extraction, and structural segmentation of reinforced concrete bioshields with radiation exposure limits below 20 millisieverts per worker annually. The primary purpose is to achieve regulatory delicensing and unrestricted site end-states for alternative land use. Waste management services capture the largest revenue pool given the decades-long storage and disposal obligations for intermediate-level wastes at the Geological Disposal Facility programme. Robotics technology is expanding fastest as autonomous systems penetrate high-radiation compartments previously inaccessible to human workers. Mechanical dismantling remains the mature baseline for pressure vessel and steam generator breakdown.
The Office for Nuclear Regulation enforces site licence conditions and security-approved arrangements that dictate decommissioning sequence approvals and funding adequacy. The Environment Agency regulates radioactive discharge authorisations and environmental permit compliance for land remediation. Health and Safety Executive standards govern worker dose limits and asbestos management during reactor demolition. Stakeholders must monitor Geological Disposal Facility siting decisions and their impact on waste packaging specifications and transport logistics.
Market Dynamics
Robotics deployment in high-radiation compartments is collapsing the cost structure of manual intervention, forcing contractor networks to reconfigure around autonomous capabilities rather than labour-intensive dismantling crews.
Growth Catalysts
- Magnox Decommissioning Programme:The Nuclear Decommissioning Authority's accelerated site closure schedule generates sustained procurement for reactor segmentation and waste packaging services across England and Wales.
- Geological Disposal Facility Development:Progress on sub-surface repository siting creates decades-long demand for intermediate-level waste conditioning and transport logistics infrastructure.
- Remote Handling Advancement:Autonomous robotic systems penetrate previously inaccessible reactor compartments, expanding addressable scope for decommissioning contractors.
Market Restraints
- Graphite Core Complexity:Irradiated graphite removal requires specialized thermal treatment and disposal pathways, constraining project velocity at advanced gas-cooled reactor sites.
- Specialized Labour Pool:The concentration of certified radiation workers and nuclear engineers in Cumbria and Gloucestershire creates geographic supply bottlenecks.
- Regulatory Approval Cycles:Office for Nuclear Regulation licensing condition amendments for novel dismantling techniques extend project timelines.
Strategic Opportunities
- Scottish Reactor Fleet:Hunterston and Torness decommissioning preparations offer early-mover positioning ahead of station closure declarations.
- Waste Vitrification Expansion:Sellafield's high-activity liquor processing creates demand for engineered container systems and shielded transport flasks.
- Digital Twin Integration:Convergence of radiation mapping sensors with predictive maintenance platforms enables pre-intervention pathway optimization.
Industry Challenges
- Radiation Protection Expertise:The scarcity of qualified health physics professionals and ALARA planning specialists constrains workforce scaling.
- Legacy Documentation Gaps:Incomplete as-built records from 1960s-era reactor construction complicate structural segmentation planning.
- Cross-Site Waste Routing:The absence of centralized intermediate storage capacity forces project-specific logistics arrangements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Nuclear Power Reactor Decommissioning Market |
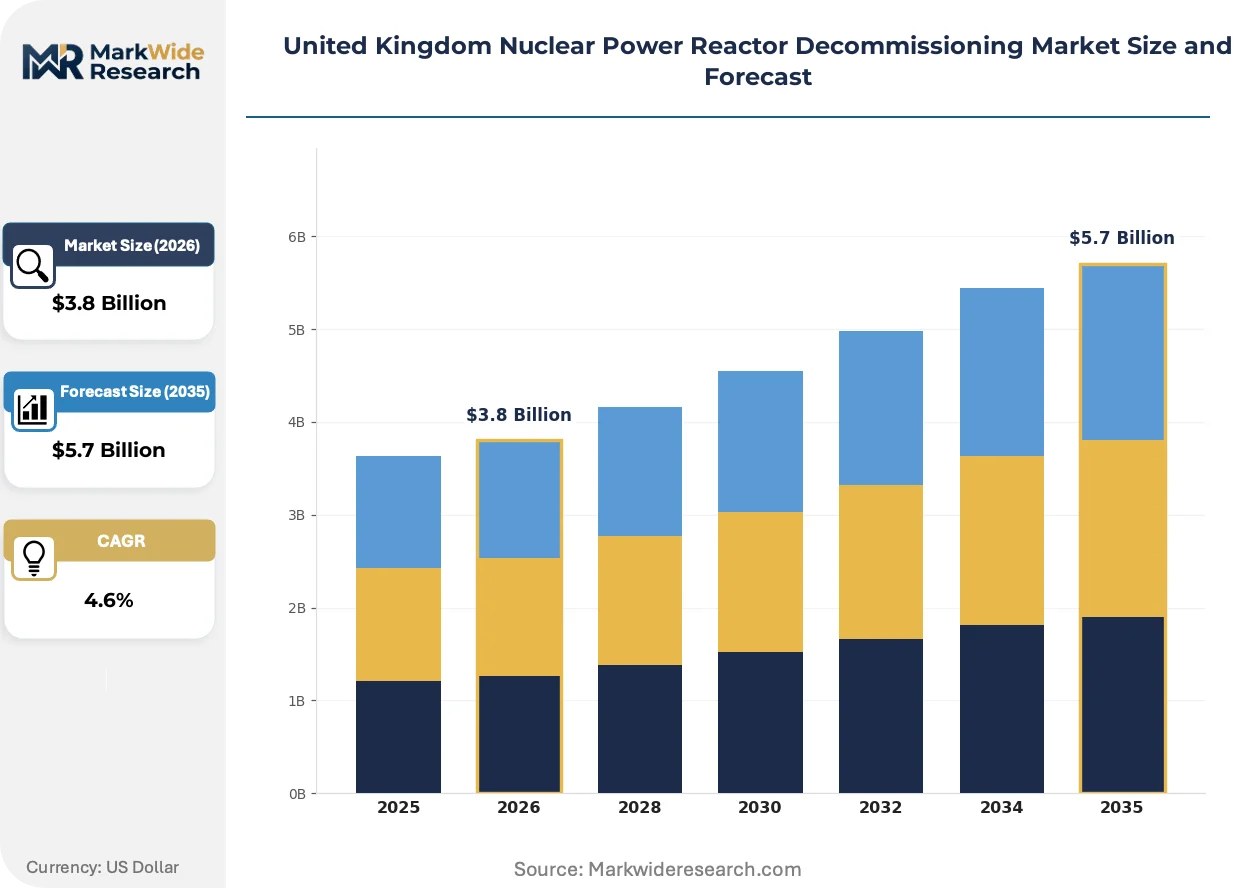
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Decommissioning, Dismantling, Waste Management, Site Restoration Technology: Mechanical, Chemical, Robotics, Remote Handling End User: Government Agencies, Private Firms, Contractors, Environmental Groups Regulatory Framework: Nuclear Licensing, Health & Safety, Environmental Protection, Quality Assurance |
| Companies Covered | EDF Energy, James Fisher & Sons PLC, Nuclear Decommissioning Authority, Studsvik AB, Fluor Corporation, Nuclear Restoration Services, Babcock International Group PLC, Orano Group, Sellafield Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Nuclear Power Reactor Decommissioning Market Evolving Landscape
Decommissioning execution is pivoting from conventional mechanical dismantling toward sensor-guided autonomous systems, compressing radiation exposure windows and redefining contractor capability requirements.
Autonomous robotic platforms equipped with laser scanning and gamma spectroscopy is collapsing the distinction between inspection and intervention phases. Sellafield Ltd deploys these systems for pond sludge retrieval and vessel segmentation planning. The technology compresses project schedules by eliminating sequential human entry protocols.
The Environment Agency's revised radioactive discharge authorisation framework tightens effluent limits for aqueous and gaseous releases during demolition phases. Operators must retrofit enhanced filtration and monitoring systems prior to concrete bioshield breach. Coastal sites face additional scrutiny on marine impact assessments.
Long-term service contracting is displacing discrete project awards as the dominant procurement mode. The Nuclear Decommissioning Authority bundles Magnox site remediation into multi-decade performance contracts with single consortium leadership. This concentrates risk with tier-one engineering groups and marginalizes specialist sub-contractors lacking balance sheet depth.
United Kingdom Nuclear Power Reactor Decommissioning Market Segmentation
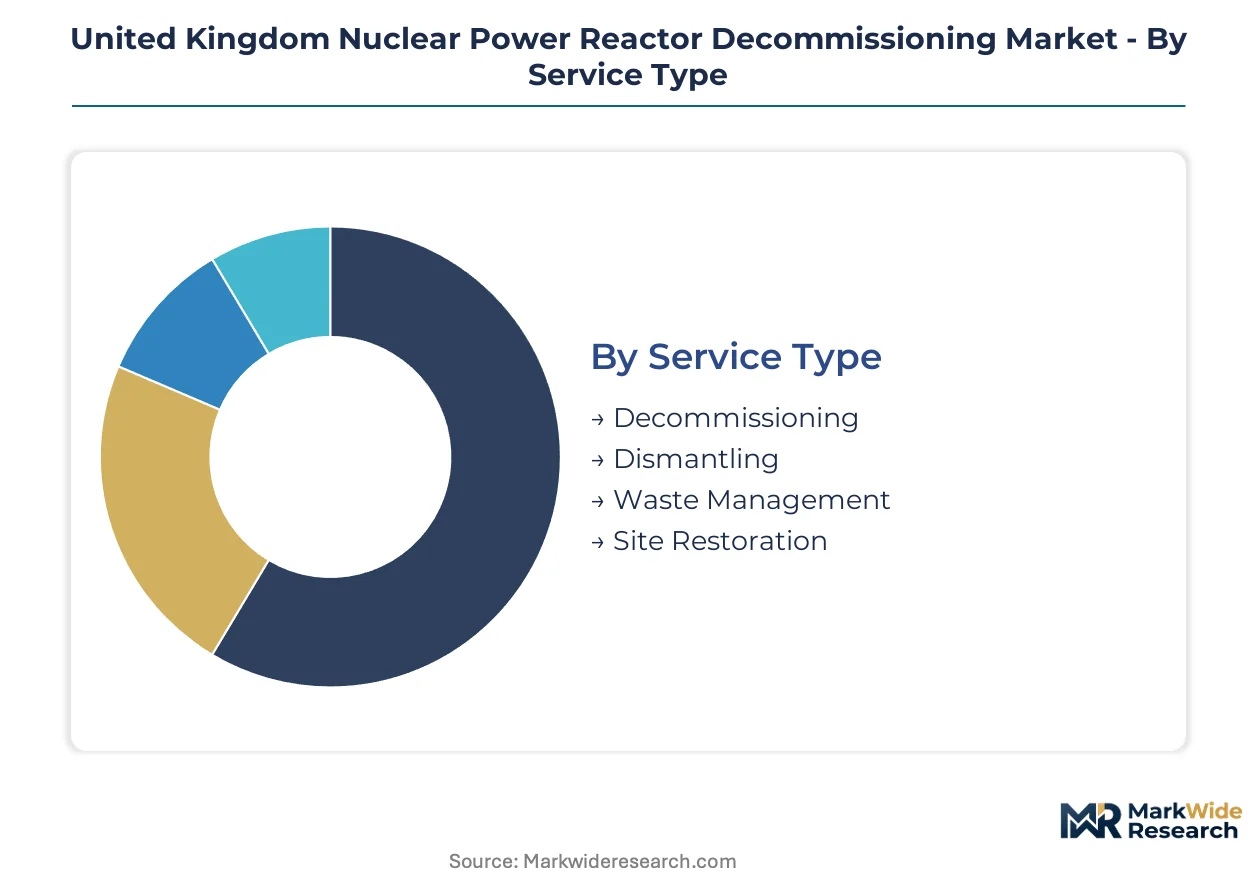
Decommissioning procurement patterns diverge sharply across service modalities, with waste management obligations extending decades beyond physical dismantling. Technology selection determines contractor eligibility for high-hazard compartments, while regulatory compliance costs structure competitive positioning across England and Wales.
Service Type:
Use-case spectrum spans immediate hazard reduction through long-term stewardship, with each phase demanding distinct technical competencies and liability structures.
- Decommissioning:Comprehensive project management integrating safety case preparation, regulatory submissions, and staged site release protocols. The Nuclear Decommissioning Authority bundles Magnox site closures into multi-decade performance contracts, concentrating procurement with tier-one engineering consortia possessing balance sheet depth for liability retention.
- Waste Management:Conditioning, packaging, and interim storage of intermediate-level wastes pending Geological Disposal Facility availability. Sellafield's high-activity liquor vitrification operations and engineered container fabrication capture sustained revenue across the forecast window, constrained by repository siting timelines.
- Dismantling:Physical segmentation of reactor pressure vessels, steam generators, and biological shield concrete. Mechanical cutting and controlled explosive demolition predominate at Trawsfynydd and other Magnox sites where radiation fields permit human-accessible techniques.
- Site Restoration:Final land remediation, groundwater monitoring, and unrestricted end-state certification. The Environment Agency's discharge authorisation compliance and asbestos management protocols govern completion timelines.
Established volume favors Waste Management; emerging adoption favors Robotics-integrated Decommissioning.
Technology:
Cost tier stratification separates mature mechanical methods from capital-intensive autonomous systems penetrating previously inaccessible zones.
- Robotics:Autonomous platforms equipped with laser scanning and gamma spectroscopy eliminate sequential human entry protocols. Sellafield deploys these systems for pond sludge retrieval and vessel segmentation planning, compressing radiation exposure windows and redefining contractor capability requirements.
- Mechanical:Conventional cutting, grinding, and lifting equipment remains the baseline for pressure vessel breakdown and structural demolition. Hunterston and Torness preparatory works rely on established mechanical techniques where dose rates permit direct human intervention.
- Remote Handling:Master-slave manipulators and teleoperated tooling bridge the gap between autonomous robotics and manual methods. Cumbria cluster operations deploy these systems for intermediate-radiation compartments where full autonomy remains uneconomical.
- Chemical:Decontamination solutions and oxidative treatments for surface radioactivity reduction. Limited application scope concentrates on secondary waste streams and tool decontamination rather than primary structural dismantling.
Mechanical methods retain volume dominance; Robotics climbs the fastest as autonomous capabilities displace labour-intensive crews.
End User:
Customer type concentration reflects the UK's state-funded decommissioning liability model, with procurement authority centralised under the Nuclear Decommissioning Authority.
- Government Agencies:The Nuclear Decommissioning Authority directs site-specific delivery through Sellafield Ltd and Magnox Ltd, controlling procurement scope and funding allocation across England and Wales.
- Contractors:Tier-one engineering groups and specialist sub-contractors execute physical dismantling, waste conditioning, and transport logistics under performance-based contracting frameworks.
- Private Firms:Limited direct involvement given state liability retention; private capital concentrates on waste transport, container fabrication, and ancillary equipment supply.
- Environmental Groups:Stakeholder engagement participants influencing discharge authorisation conditions and marine impact assessment scrutiny at coastal sites.
Government procurement dominates current spend; contractor capability consolidation shapes competitive access.
Regulatory Framework:
Compliance burden stratification aligns with hazard classification, with nuclear licensing obligations imposing the steepest qualification barriers.
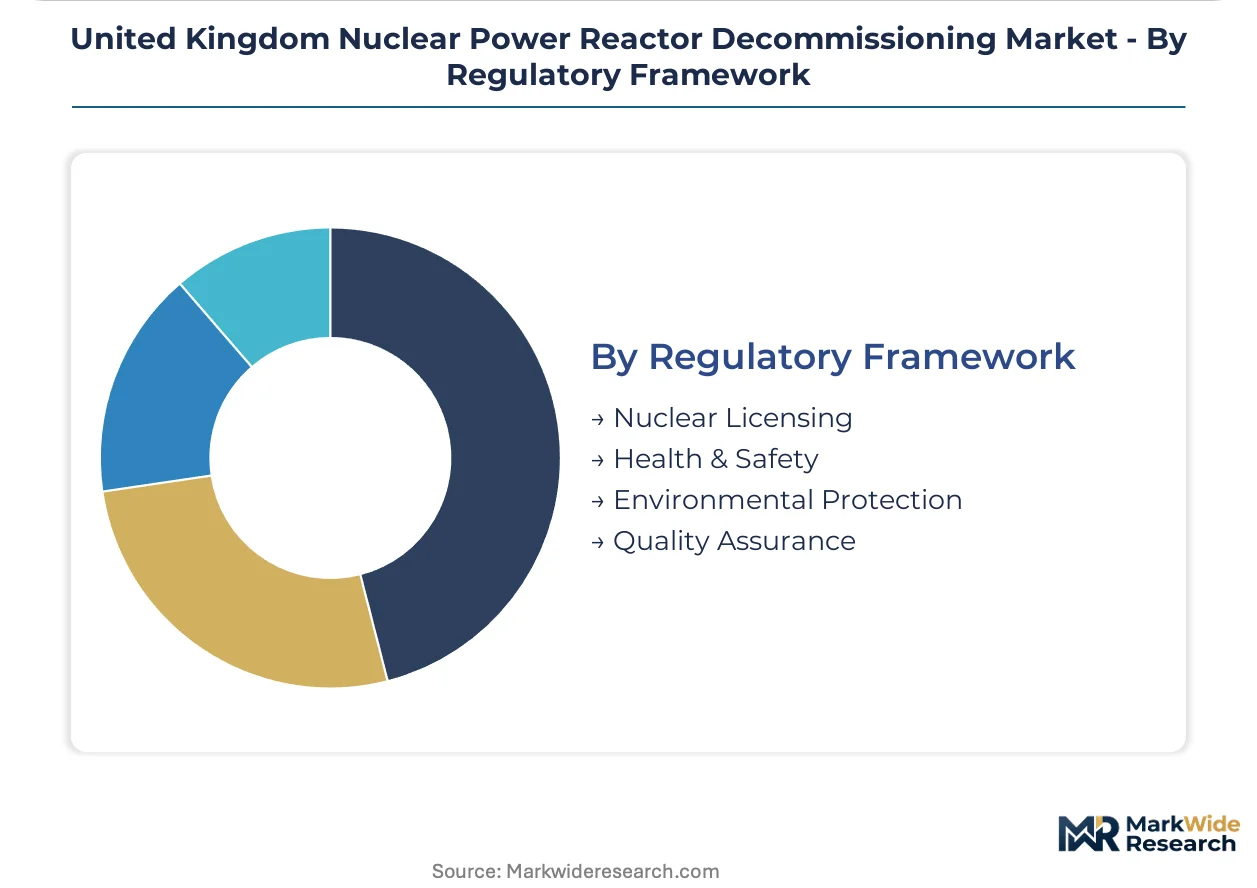
- Nuclear Licensing:Office for Nuclear Regulation site licence conditions dictate decommissioning sequence approvals, funding adequacy verification, and security-approved arrangements. Amendment cycles for novel dismantling techniques extend project timelines.
- Environmental Protection:Environment Agency radioactive discharge authorisations and effluent limits govern aqueous and gaseous releases during demolition phases. Coastal sites face additional marine impact assessment requirements.
- Health & Safety:Health and Safety Executive standards enforce worker dose limits below 20 millisieverts annually and asbestos management protocols during reactor demolition.
- Quality Assurance:Documentation and verification standards addressing legacy record gaps from 1960s-era reactor construction that complicate structural segmentation planning.
Nuclear Licensing captures the steepest compliance burden; Environmental Protection requirements are expanding most quickly under tightened discharge frameworks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Nuclear Decommissioning Authority's accelerated site closure schedule channels procurement toward England's Cumbria cluster and Wales's Magnox facilities. Scotland's Hunterston and Torness preparations signal emerging demand beyond the core decommissioning geography.
England
The Cumbria cluster anchors national decommissioning capacity, with Sellafield's high-hazard legacy ponds and vitrification operations commanding sustained investment. The Office for Nuclear Regulation enforces site licence conditions that dictate sequence approvals and funding verification across the complex. Remote handling technologies penetrate previously inaccessible compartments at Sellafield, compressing radiation exposure windows for dismantling crews.
Wales
Trawsfynydd's Magnox decommissioning programme generates procurement for reactor segmentation and waste packaging services under Nuclear Decommissioning Authority direction. The Environment Agency's radioactive discharge authorisations govern aqueous releases during concrete bioshield breach operations. Mechanical dismantling techniques predominate where dose rates permit direct human intervention at the Snowdonia-adjacent site.
Scotland
Hunterston and Torness advanced gas-cooled reactors approach end-of-life, creating early-mover positioning for contractors ahead of closure declarations. The Scottish Government's energy transition framework influences decommissioning timeline coordination with renewable infrastructure deployment. Dounreay's fast reactor decommissioning legacy concentrates specialist expertise in the Highland region alongside civil nuclear preparations.
Gloucestershire
Berkeley and Oldbury Magnox sites concentrate certified radiation workers and nuclear engineering talent in the southwest England corridor. The Health and Safety Executive's asbestos management protocols govern reactor demolition sequencing across the Severn estuary cluster. Tier-one engineering groups maintain established partnerships with the Nuclear Decommissioning Authority for multi-decade performance contracting.
United Kingdom Nuclear Power Reactor Decommissioning Market Competitive Landscape
On the supply side, the industry is consolidating around tier-one engineering consortia capable of absorbing multi-decade liability exposure and performance contract risk. The vendor base stratifies between balance-sheet-heavy prime contractors, specialist technology providers, and state-affiliated site management entities. Three archetypes dominate: submarine reactor heritage groups leveraging naval-civil capability transfer, high-hazard legacy site operators with pond retrieval expertise, and underwater engineering specialists with containment solutions. Competitive positioning hinges on strategic partnership consolidation and autonomous technology integration rather than price-based rivalry.
Within the state-affiliated tier, the Nuclear Decommissioning Authority and Sellafield Ltd occupy central procurement and delivery positions. Among diversified engineering groups, Babcock International Group PLC exemplifies submarine-to-civil capability extension, while James Fisher & Sons PLC represents underwater engineering specialization for flooded vessel applications. These entities anchor contractor networks through multi-decade performance frameworks that marginalize balance-sheet-constrained specialists.
| Leading Market Players |
|---|
| EDF Energy |
| James Fisher & Sons PLC |
| Nuclear Decommissioning Authority |
| Studsvik AB |
| Fluor Corporation |
| Nuclear Restoration Services |
| Babcock International Group PLC |
| Orano Group |
| Sellafield Ltd |
| Others |
Value Network & Pricing Analysis
Overcapacity in Cumbria's contractor labor pool is compressing bid margins for mechanical dismantling services while simultaneously concentrating pricing power with tier-one engineering consortia that can absorb multi-decade performance contract risk. The Nuclear Decommissioning Authority's bundled procurement model rewards balance sheet depth over unit cost, reshaping supplier behavior toward consortium formation rather than standalone competition.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs decommissioning service awards. Premium tiers capture robotics-integrated pond retrieval and vitrification operations at Sellafield where certification to Office for Nuclear Regulation standards commands substantial markups. Standard tiers cover mechanical dismantling at Magnox sites with established safety cases. Economy tiers concentrate on site restoration and asbestos remediation where subcontractor competition is fiercest. Pricing pressure stems from the Nuclear Decommissioning Authority's cost-cap enforcement on legacy site budgets, squeezing margins most acutely in labor-intensive mechanical segments. Government agencies exhibit lowest price sensitivity given state liability retention, while specialist sub-contractors face acute margin compression.
Supply Chain Analysis
Upstream feedstock for radiation-hardened robotics and engineered waste containers draws from Germany, Japan, and the United States. Specialized manipulator arms and gamma spectroscopy sensors originate from German industrial automation clusters. High-integrity stainless steel forgings for transport flasks source from Japanese and American foundries certified to ASME pressure vessel standards. Single-source vulnerability concentrates in laser scanning modules for autonomous platforms, where replacement timelines extend procurement cycles. Distribution runs through tier-one engineering consortia that bundle sub-contractor networks under Nuclear Decommissioning Authority performance contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
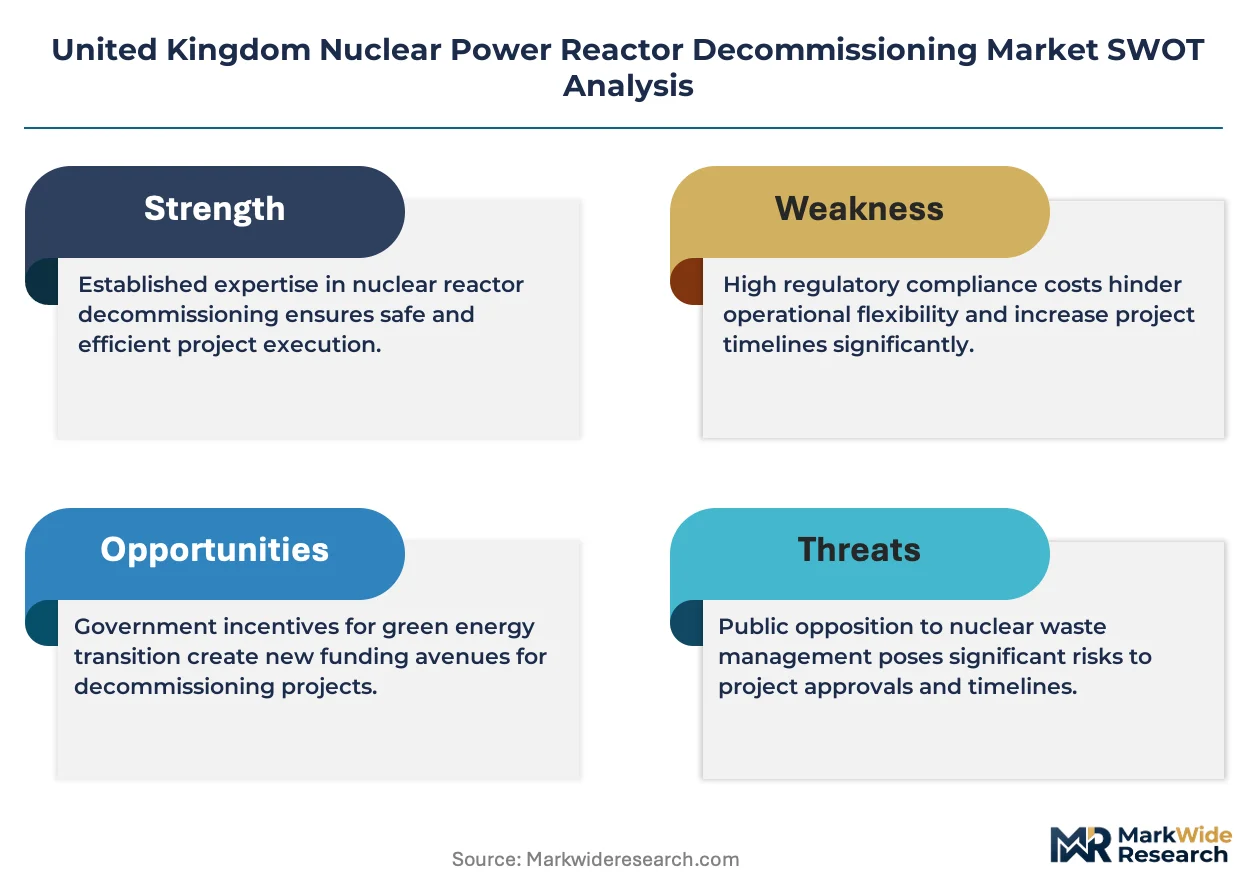
This market functions as a regulatory entrenchment story where decades-long site licenses and security-cleared workforce pools create formidable barriers to competitive displacement.
For Market Incumbents: Build switching-cost moats through captive training pipelines for health physics professionals and ALARA planning specialists. Deepen backward integration into robotics manufacturing to reduce dependency on German and Japanese sensor suppliers. Consolidate around Sellafield and Magnox site partnerships before the Scottish reactor fleet advances to decommissioning phases. Threat substitution from autonomous platform vendors demands accelerated in-house capability development. For New Entrants and Emerging Players: Pursue white-space positioning in Scotland's Hunterston and Torness preparatory works ahead of closure declarations. Target the Geological Disposal Facility transport logistics segment where specialized flask fabrication and routing optimization remain underdeveloped. Penetration concentrates in digital twin integration for radiation mapping, where incumbent capability gaps create entry pathways. Go-to-market leverage rests on partnerships with Cumbria-based certified radiation worker pools. For Investors and Strategic Acquirers: Capital is best deployed toward underwater engineering specialists with flooded vessel containment expertise and established Nuclear Decommissioning Authority relationships. Long-term viability across the analysis window hinges on repository siting progress and waste conditioning backlog depth. Acquisition targets should demonstrate balance sheet capacity for multi-decade liability retention. Signal to monitor: Office for Nuclear Regulation licensing condition amendments for novel dismantling techniques that could accelerate or delay project velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Robotics Capability Acquisition | Autonomous platform integration compresses radiation exposure windows at Sellafield high-hazard ponds. |
| Multi-Decade Performance Contracting | Consortium leadership of Magnox site remediation bundles liability and concentrates procurement authority. |
| Health Physics Workforce Pipeline | Captive training for ALARA specialists and certified radiation workers locks in scarce talent pools. |
| Geological Disposal Facility Positioning | Engineered container and shielded transport flask fabrication captures decades-long waste conditioning demand. |
| Scottish Early-Mover Deployment | Hunterston and Torness preparatory works establish contractor presence before closure-driven procurement accelerates. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of Office for Nuclear Regulation licensing databases, Environment Agency discharge authorisation records, and Nuclear Decommissioning Authority procurement disclosures. Primary interviews engaged decommissioning project directors, health physics consultants, robotics engineering leads, and waste logistics coordinators across England, Wales, and Scotland. Secondary validation incorporated Health and Safety Executive enforcement notices, European Commission radioactive waste management directives, and customs records for radiation-hardened equipment imports. Bottom-up project pipeline analysis triangulated against top-down funding allocation models from government expenditure reviews.
Forecast inputs span service type segmentation across decommissioning, waste management, dismantling, and site restoration modalities, with technology stratification between robotics, mechanical, remote handling, and chemical methods. End-user concentration weights government agency procurement against contractor execution networks. Modeled CAGRs derive from project timeline acceleration assumptions tied to Magnox closure schedules and Geological Disposal Facility development milestones. Industry-specific inputs include graphite core removal complexity coefficients and regulatory approval cycle durations for novel dismantling techniques.
Sensitivities concentrate around Geological Disposal Facility siting decisions, Office for Nuclear Regulation licensing condition amendment timelines, and robotics technology substitution rates for manual dismantling crews. Forecasts embed assumptions regarding continued state funding adequacy and security-cleared workforce availability. Cross-checking against Nuclear Decommissioning Authority annual reports and parliamentary committee evidence sessions is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nuclear Energy
Global Nuclear Reactor Construction Market
Nuclear Energy
Nuclear Power Market
Nuclear Energy
Nuclear Power Plant Equipment Market
Nuclear Energy
China Nuclear Power Plant Equipment Market
Nuclear Energy
North America Nuclear Reactor Construction Market
Nuclear Energy
Helium-3 Market
Nuclear Energy
Global Thorium Reactor Market
Nuclear Energy
Europe Nuclear Reactor Decommissioning Market
Nuclear Energy
Global Power Plant Uranium Market
Nuclear Energy
Asia-Pacific Nuclear Power Reactor Decommissioning Market
Nuclear Energy
Asia-Pacific Nuclear Reactor Construction Market
Nuclear Energy
Nuclear Fuels Market
Nuclear Energy
Germany Nuclear Power Reactor Decommissioning Market
Nuclear Energy
France Nuclear Power Reactor Decommissioning Market
Nuclear Energy
Europe Nuclear Power Plant and Equipment Market
Nuclear Energy
Middle-East and Africa Nuclear Power Plant Equipment Market