
 France Nuclear Power Reactor Decommissioning Market | 2026-2036
France Nuclear Power Reactor Decommissioning Market Size, Share, and Industry Trends Forecast 2026-2036
France Nuclear Power Reactor Decommissioning Market Foresight
Utility operator procurement is realigning toward immediate dismantling contracts as EDF advances closure timelines for aging pressurized water reactor units. Orano Group leverages its integrated fuel cycle expertise to anchor positions in waste retrieval and conditioning operations. Veolia Environnement SA competes through specialized environmental remediation capabilities that extend across contaminated site restoration. Framatome sustains technology leadership in reactor vessel segmentation tooling and remote handling systems for high-radiation environments.
France nuclear power reactor decommissioning encompasses the engineered dismantling, decontamination, and site restoration of shutdown fission plants, requiring robotic cutting systems capable of operating in dose rates exceeding 10,000 Sv/h and producing waste packages compliant with ANDRA's deep geological disposal specifications. The immediate dismantling segment dominates committed expenditure as operators pursue site release for alternative industrial use rather than decades-long safe enclosure periods. Mechanical cutting and remote handling technologies capture the largest equipment procurement volumes, though robotics is gaining share for tasks in confined reactor pressure vessel internals where human access is prohibited.
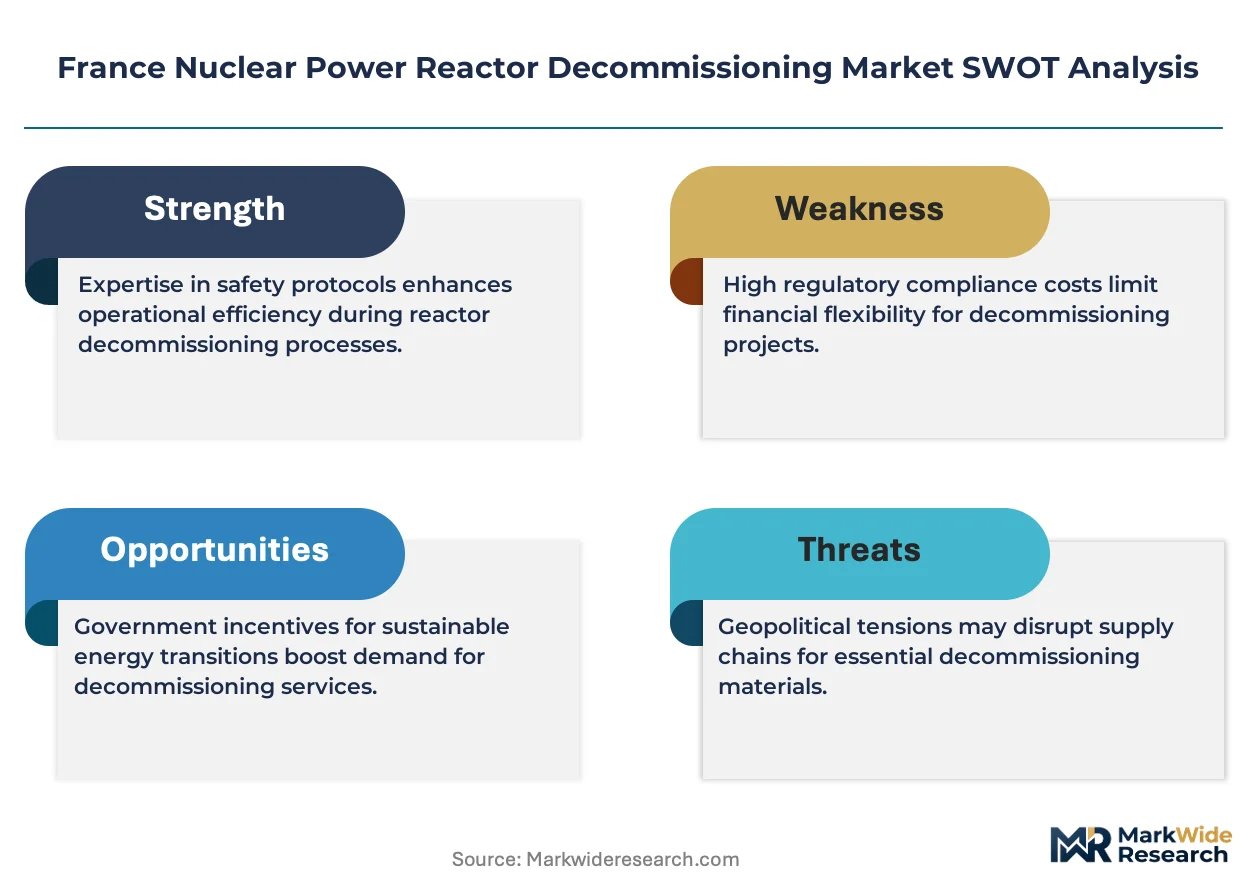
ASN, the French nuclear safety authority, enforces decommissioning license conditions that mandate progressive waste clearance and fund sufficiency verification, while ANDRA's national waste management plan dictates acceptance criteria for all radioactive material streams. The EU Waste Directive transposition through French environmental code provisions imposes additional characterization and traceability obligations on contractors. Stakeholders must monitor ASN's evolving technical guidelines on graphite reactor dismantling as France prepares for the unprecedented challenge of decommissioning its UNGG gas-cooled units at Bugey and Chinon.
Market Dynamics
France's accelerated reactor closure schedule under the national energy transition strategy is compressing decommissioning timelines from decades to years, forcing utility operators to restructure procurement around immediate dismantling rather than extended safe enclosure periods.
Growth Catalysts
- ASN License Conditions:The French nuclear safety authority mandates progressive waste clearance and fund sufficiency verification, compelling operators to advance dismantling expenditures ahead of original schedules.
- ANDRA Deep Geological Disposal:France's national radioactive waste management agency has finalized acceptance criteria for high-level waste packages, enabling contractors to proceed with definitive conditioning operations.
- Grand Est Regional Clustering:Multiple reactor sites at Chooz and Cattenom entering active dismantling phases simultaneously is concentrating specialized labor pools and equipment deployment.
Market Restraints
- Graphite Reactor Complexity:The UNGG gas-cooled units at Bugey and Chinon present unprecedented technical challenges for waste characterization, as no commercial-scale dismantling of this reactor type exists worldwide.
- Specialized Labor Scarcity:France's nuclear engineering workforce is aging rapidly, with insufficient replacement rates for radiation protection officers and remote handling technicians.
- Waste Acceptance Bottlenecks:ANDRA's limited operational storage capacity for intermediate-level long-lived waste is constraining the pace of site clearance operations.
Strategic Opportunities
- Normandy Site Repurposing:The Paluel and Flamanville sites offer contiguous industrial zones suitable for offshore wind component manufacturing, accelerating operator interest in rapid site release.
- Robotics-Converged Segmentation:Integration of laser cutting with autonomous underwater vehicle platforms is opening vessel internals dismantling in flooded reactor cavities previously deemed inaccessible.
- EU Waste Directive Transposition:Enhanced characterization and traceability obligations under French environmental code provisions are creating demand for integrated digital waste tracking systems.
Industry Challenges
- Remote Handling Technician Pipeline:The specialized skill set combining robotics operation with radiological safety certification requires training programs that currently graduate fewer than fifty specialists annually.
- Legacy System Integration:Reactor pressure vessel segmentation tooling must interface with forty-year-old containment structures never designed for robotic access, requiring bespoke engineering for each unit.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Nuclear Power Reactor Decommissioning Market |
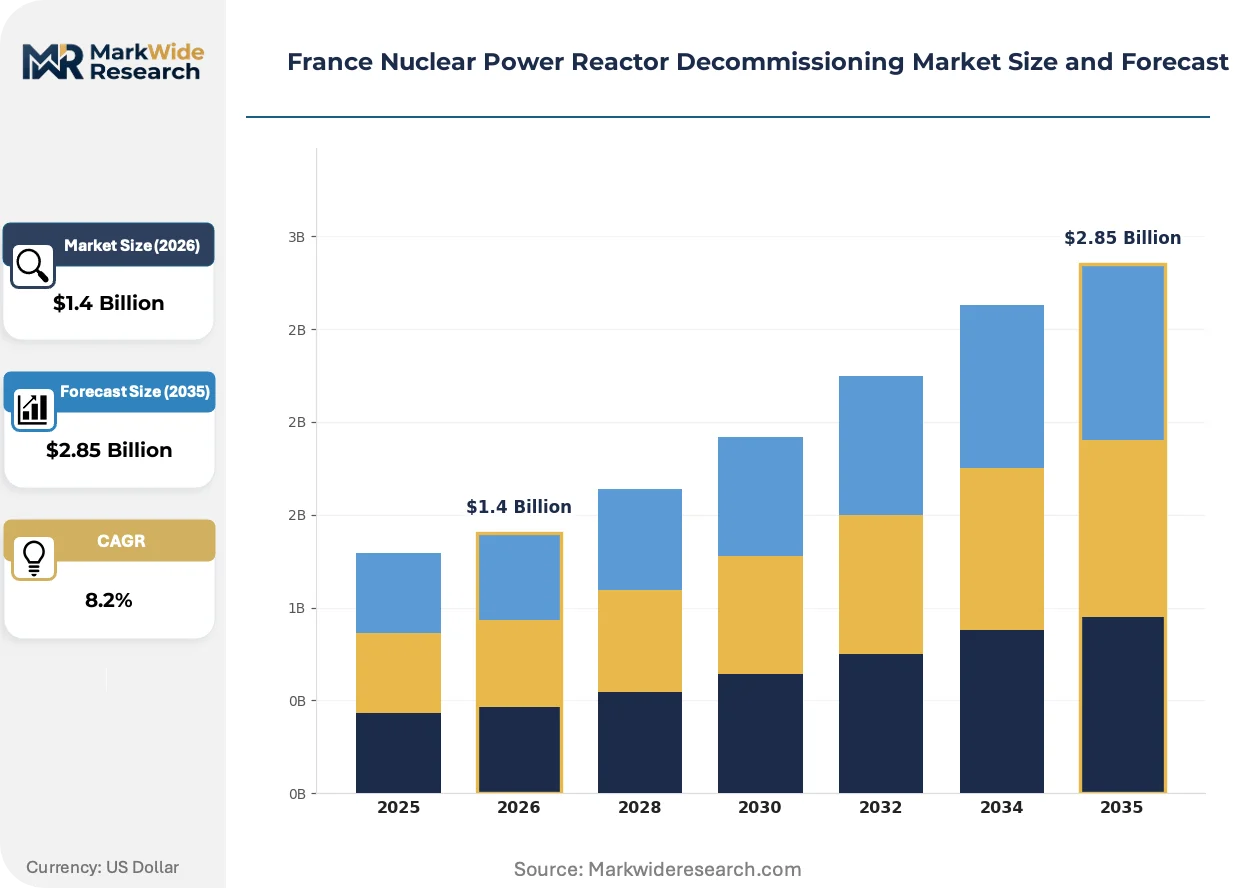
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.85 Billion |
| CAGR (2026 – 2036) | 8.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Decommissioning Stage: Immediate Dismantling, Safe Enclosure, Entombment, Deferred Dismantling Technology Used: Mechanical Cutting, Laser Cutting, Chemical Decontamination, Remote Handling, Robotics Type of Reactor: Pressurized Water Reactor, Boiling Water Reactor, Heavy Water Reactor, Fast Breeder Reactor End User: Utility Operators, Specialized Contractors, Regulatory Bodies, Waste Management Firms |
| Companies Covered | Electricite de France SA (EDF), Orano Group, Veolia Environnement SA, Assystem SA, French Alternative Energies and Atomic Energy Commission (CEA), ONET Technologies, Orano Démantèlement et Services, Framatome, ANDRA, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Nuclear Power Reactor Decommissioning Market Shifts & Advancements
Decommissioning operations in France are pivoting from manual intervention toward autonomous systems capable of sustained operation in extreme radiation environments, compressing project timelines while reducing personnel exposure.
Laser cutting systems paired with fiber-optic beam delivery are automating reactor vessel segmentation in dose rates that would incapacitate conventional plasma cutting crews. EDF's procurement specifications now prioritize robotic platforms with demonstrated performance above 10,000 Sv/h. This automation is collapsing the traditional trade-off between dismantling speed and worker safety.
ASN's evolving technical guidelines on graphite reactor dismantling are mandating novel characterization protocols for irradiated graphite waste streams. Industrial consequence includes mandatory pre-treatment sampling campaigns that extend project front-ends by eighteen to twenty-four months. The UNGG units at Bugey and Chinon are most affected, with operators commissioning dedicated graphite laboratories ahead of active dismantling.
Utility procurement is consolidating dismantling and waste conditioning contracts under single-responsibility frameworks, displacing the historical separation between mechanical demolition and waste management specialists. Tier-one environmental service groups are absorbing specialized robotics subcontractors to offer integrated site release guarantees. This consolidation is most visible in Grand Est, where EDF has awarded turnkey contracts covering Chooz B through final site clearance.
France Nuclear Power Reactor Decommissioning Market Segmentation
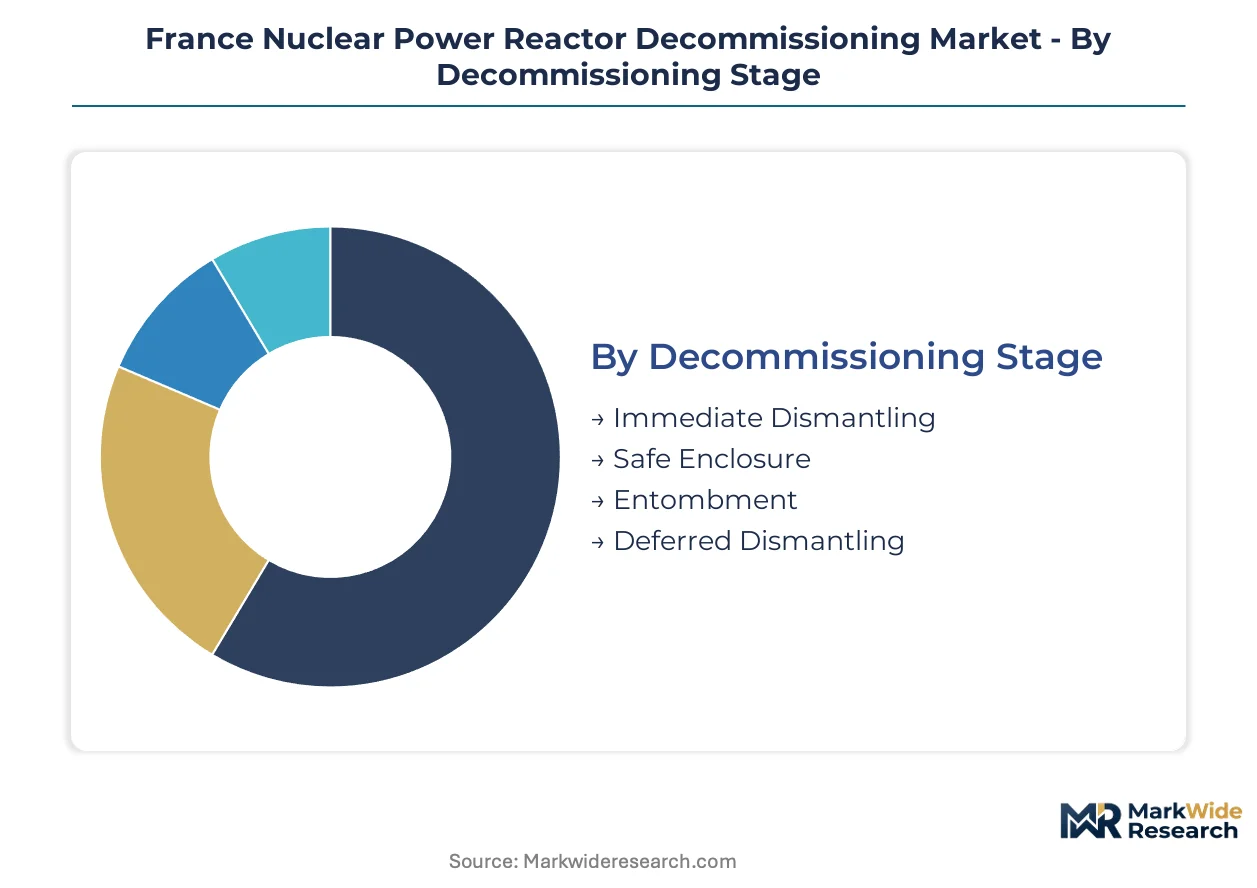
Decommissioning procurement in France fragments across reactor technology generations, dismantling methodologies, and contractor specialization levels. Each segmentation dimension carries distinct regulatory obligations under ASN licensing and ANDRA waste acceptance protocols that reshape vendor selection criteria and project economics.
Decommissioning Stage:
France's accelerated closure schedule is compressing upgrade cycles from multi-decade safe enclosure toward immediate site release, restructuring capital deployment timelines and contractor engagement models.
- Immediate Dismantling:Active dismantling begins within months of final shutdown, deploying robotic cutting systems and remote handling platforms to achieve site clearance. EDF's procurement concentrates in Grand Est and Normandy where contiguous reactor clusters enable equipment reuse and labor mobility between Chooz, Cattenom, Paluel, and Flamanville sites.
- Safe Enclosure:Reactor containment maintains radiological isolation for decades before deferred dismantling, requiring sustained surveillance infrastructure and periodic integrity assessments. ASN fund sufficiency verification now pressures operators to accelerate beyond original safe enclosure timelines, reducing committed expenditure share.
- Deferred Dismantling:Extended latency periods between shutdown and active dismantling allow radioactivity decay but impose intergenerational liability transfer. ANDRA's evolving waste acceptance criteria are narrowing the rationale for prolonged deferral.
- Entombment:In-situ concrete encapsulation of reactor vessels and contaminated structures, restricted to exceptional cases where dismantling proves technically infeasible or cost-prohibitive. ASN licensing constraints limit applicability in France.
Volume placements concentrate in Immediate Dismantling; the faster expansion belongs to Safe Enclosure conversion programs as operators abandon multi-decade deferral strategies.
Technology Used:
Procurement patterns track the displacement of manual intervention by autonomous systems capable of sustained operation in dose rates exceeding human tolerance thresholds.
- Mechanical Cutting:Plasma arc and diamond wire systems segment reactor pressure vessels and internals, dominating equipment procurement volumes due to proven reliability in PWR dismantling. Grand Est regional clustering at Chooz and Cattenom sustains concentrated demand for mechanical cutting tool deployment and refurbishment cycles.
- Remote Handling:Master-slave manipulators and teleoperated platforms execute tasks in confined high-radiation zones where human access is prohibited. ASN technical guidelines mandate remote handling for graphite reactor dismantling at Bugey and Chinon UNGG units, accelerating specialized platform procurement.
- Laser Cutting:Fiber-optic beam delivery enables automated vessel segmentation without electrical conductivity constraints that limit plasma systems. EDF specifications prioritize laser platforms with demonstrated performance above 10,000 Sv/h.
- Robotics:Autonomous underwater vehicles and crawler platforms navigate flooded reactor cavities and complex geometries. Integration with laser cutting is opening vessel internals previously deemed inaccessible.
- Chemical Decontamination:Acidic and oxidative formulations dissolve surface contamination to reduce waste classification and enable material clearance. ANDRA acceptance criteria constrain effluent discharge pathways.
Mechanical Cutting retains the largest committed expenditure; Robotics is climbing the fastest as EDF procurement specifications harden automation requirements.
Type of Reactor:
Reactor technology generations impose distinct dismantling challenges based on coolant chemistry, structural materials, and irradiated component inventories.
- Pressurized Water Reactor:EDF's dominant fleet technology with standardized vessel geometries that facilitate repetitive dismantling methodologies. Immediate dismantling procurement concentrates at Chooz, Cattenom, Paluel, and Flamanville where multiple PWR units enter sequential closure.
- Fast Breeder Reactor:Sodium-cooled designs with unique material activation profiles and pyrophoric coolant handling requirements. The Superphénix decommissioning at Creys-Malville established specialized contractor capabilities now dormant pending future FBR closures.
- Boiling Water Reactor:Absent from EDF's operational fleet; limited relevance to French decommissioning procurement.
- Heavy Water Reactor:No commercial-scale deployment in France; excluded from committed expenditure projections.
PWR dismantling commands overwhelming volume share; Fast Breeder Reactor decommissioning represents the steepest technical learning curve with few transferable precedents.
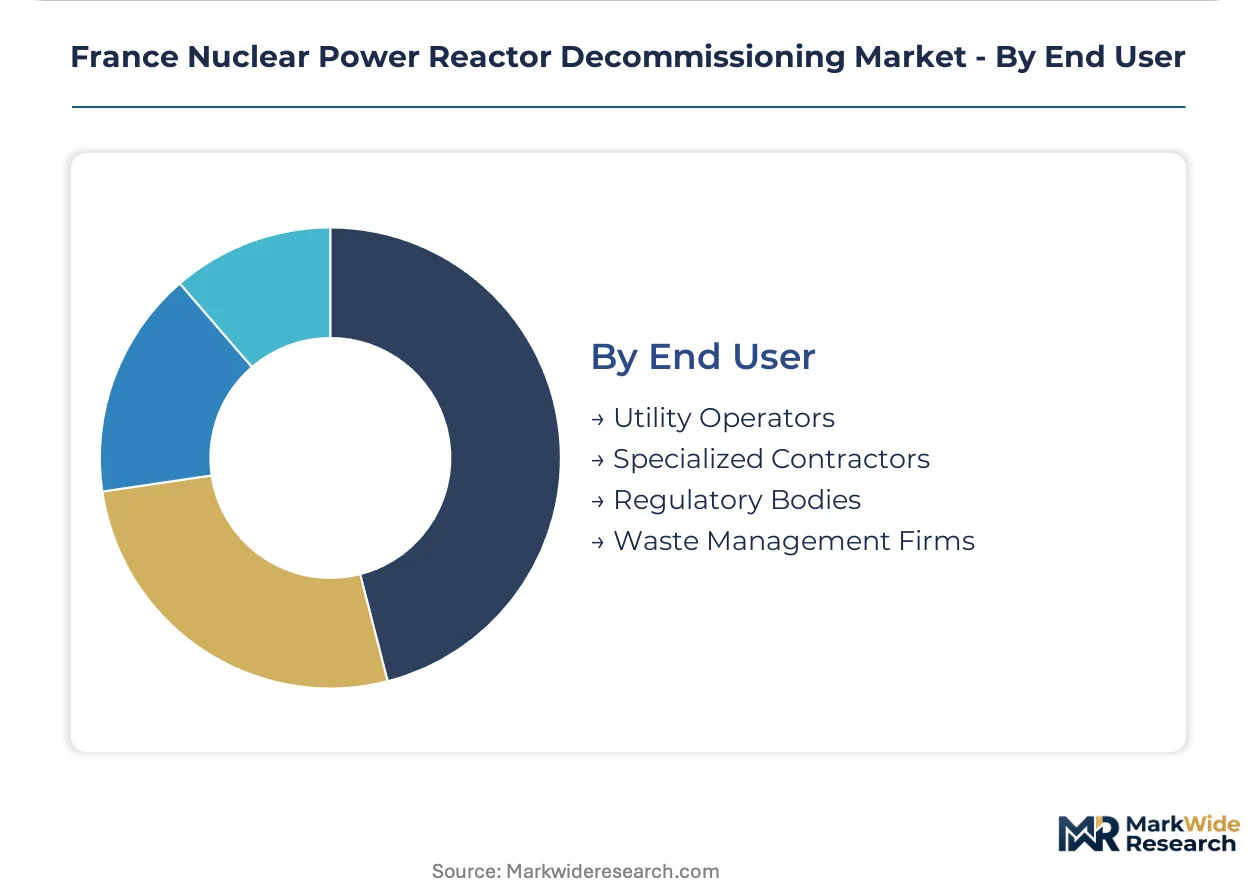
End User:
Contractual responsibility distribution is consolidating under single-responsibility frameworks that displace historical separation between mechanical demolition and waste management functions.
- Utility Operators:EDF retains decommissioning liability and fund sufficiency obligations under ASN oversight, driving procurement consolidation across dismantling and waste conditioning scopes. Turnkey contracting now spans Chooz B through final site clearance.
- Specialized Contractors:Robotics subcontractors and radiological protection specialists face absorption by tier-one environmental service groups seeking integrated site release guarantees. Labor scarcity for remote handling technicians constrains expansion capacity.
- Waste Management Firms:ANDRA's operational storage capacity limitations constrain clearance pacing, forcing conditioning contractors to manage extended on-site interim storage.
- Regulatory Bodies:ASN license condition enforcement and technical guideline evolution reshape contractor qualification requirements and project front-end durations.
Utility Operators dominate committed expenditure; Specialized Contractors are gaining share fastest through consolidation into integrated service platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Grand Est nuclear zone drives concentration through EDF's contiguous reactor clustering at Chooz and Cattenom, enabling equipment reuse and specialized labor mobility across multiple PWR units entering simultaneous dismantling phases.
Grand Est
Chooz B and Cattenom nuclear power stations anchor procurement volumes as EDF advances sequential reactor closures under ASN-mandated timelines. The French nuclear safety authority enforces progressive waste clearance obligations that compress dismantling schedules from decades to years. Specialized robotics contractors concentrate around the Ardennes-Meurthe-et-Moselle corridor where remote handling technicians rotate between active sites.
Normandy
Paluel and Flamanville sites accelerate interest in rapid site release for offshore wind component manufacturing. ASN license conditions require fund sufficiency verification that pressures operators toward immediate dismantling rather than extended safe enclosure. The Cotentin Peninsula hosts concentrated waste conditioning infrastructure serving multiple reactor decommissioning projects simultaneously.
Centre-Val de Loire
Chinon UNGG gas-cooled units present unprecedented graphite reactor dismantling challenges with no commercial-scale precedents worldwide. The French Alternative Energies and Atomic Energy Commission operates dedicated graphite characterization laboratories ahead of active dismantling. ANDRA's evolving waste acceptance criteria for irradiated graphite streams extend project front-ends by eighteen to twenty-four months.
Auvergne-Rhône-Alpes
Bugey nuclear site shares the UNGG technical complexity burden with Chinon, requiring novel characterization protocols for irradiated graphite waste. ASN technical guidelines mandate pre-treatment sampling campaigns that reshape contractor qualification requirements. The Rhône corridor sustains specialized environmental remediation capabilities extending across contaminated site restoration.
France Nuclear Power Reactor Decommissioning Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with utility-affiliated entities and independent environmental service groups forming a tiered structure around project scale and technical specialization. The vendor base concentrates among integrated fuel cycle operators, specialized decommissioning contractors, and waste management agencies. Three archetypes dominate: state-linked energy incumbents with captive decommissioning liabilities, environmental engineering conglomerates with radiological remediation capabilities, and niche robotics providers absorbed into turnkey platforms. Competitive dynamics center on single-responsibility contract consolidation and specialized technician workforce capture.
Within the state-affiliated tier, Electricite de France SA retains decommissioning liability and fund sufficiency obligations under ASN oversight, driving procurement consolidation across dismantling and waste conditioning scopes. Orano Group and Veolia Environnement SA exemplify the integrated service archetype, with the former anchoring positions in waste retrieval and conditioning operations and the latter competing through specialized environmental remediation capabilities. Framatome occupies a position sustaining technology leadership in reactor vessel segmentation tooling and remote handling systems for high-radiation environments.
| Leading Market Players |
|---|
| Electricite de France SA (EDF) |
| Orano Group |
| Veolia Environnement SA |
| Assystem SA |
| French Alternative Energies and Atomic Energy Commission (CEA) |
| ONET Technologies |
| Orano Démantèlement et Services |
| Framatome |
| ANDRA |
| Others |
Supply & Pricing Matrix
Laser cutting automation is collapsing the historical trade-off between dismantling speed and worker safety, simultaneously compressing project economics and concentrating procurement power among vendors with demonstrated performance above 10,000 Sv/h. EDF's specification tightening is reshaping supplier tiers as tier-one environmental service groups absorb specialized robotics subcontractors to offer integrated site release guarantees.
Pricing Analysis
Premium pricing attaches to short-lead-time deployment of remote handling platforms certified for graphite reactor dismantling at Bugey and Chinon, while spot inventory of refurbished mechanical cutting tools trades at discounts. Project-based contracting dominates, with price differentiation resting on ASN certification tier and after-sales service bundling. Cost compression in standard PWR dismantling packages is intensifying because EDF's turnkey consolidation reduces vendor count. Municipal utility buyers in Grand Est exhibit highest price sensitivity; Orano Group and Framatome face lowest sensitivity due to captive technology positions.
Supply Chain Analysis
Freight costs for oversized reactor pressure vessel segmentation tooling from Germany and Japan feed into total project economics, with specialized transport permits adding non-trivial lead time. Manufacturing concentrates in Germany, Japan, and the United States for high-integrity remote handling systems. Raw material dependencies include radiation-hardened optical fibers, tungsten cutting electrodes, and borated concrete formulations. Single-source vulnerability runs through laser beam delivery subsystem suppliers. Distribution runs through EDF's centralized procurement at Grand Est and Normandy regional clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race where control over remote handling technician training pipelines and graphite waste characterization laboratories determines contract capture. Backward integration into specialized robotics manufacturing represents the decisive upstream lever.
For Market Incumbents: Hedge against labor scarcity by acquiring remote handling training institutes in the Ardennes-Meurthe-et-Moselle corridor. Lock in graphite reactor dismantling expertise through dedicated pre-treatment sampling infrastructure at Chinon and Bugey before ASN technical guidelines harden qualification barriers.
For New Entrants and Emerging Players: Launch via sub-contractor absorption to EDF's turnkey procurement frameworks, targeting the robotics-converged segmentation white space where laser cutting meets autonomous underwater platforms. The most penetrable entry point lies in digital waste tracking systems mandated by EU Waste Directive transposition through French environmental code provisions.
For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to tier-one environmental service groups seeking integrated site release capabilities. Long-term viability hinges on positioning ahead of France's UNGG reactor decommissioning wave, a 5-10 year window with no commercial-scale precedents worldwide. Monitor ANDRA's operational storage capacity expansion announcements as the critical inflection signal for clearance pacing acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Remote Handling Technician Pipeline Acquisition | Captures scarce labor pools ASN mandates for graphite reactor dismantling at Bugey and Chinon. |
| Laser Cutting Platform Certification | Unlocks EDF procurement specifications prioritizing demonstrated performance above 10,000 Sv/h. |
| Graphite Characterization Laboratory Buildout | Positions ahead of eighteen-to-twenty-four-month project front-end extensions for UNGG units. |
| Turnkey Contract Consolidation | Mirrors EDF's single-responsibility framework covering Chooz B through final site clearance. |
| Digital Waste Tracking System Development | Addresses EU Waste Directive traceability obligations reshaping contractor qualification requirements. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with EDF decommissioning procurement officers, ASN licensing specialists, Orano Group project directors, and ANDRA waste acceptance engineers. Bottom-up and top-down triangulation validated expenditure projections against EDF's published reactor closure schedules and France's national radioactive waste management plan disclosures.
Segmentation granularity modeled decommissioning stage, technology used, reactor type, and end user at the project-contract level across the analysis window. CAGRs derived from expenditure pacing tied to ASN-mandated timelines and ANDRA waste acceptance criteria evolution. Forecast inputs incorporated robotics adoption curves in high-radiation environments and graphite reactor dismantling learning curve assumptions.
Regulatory guideline acceleration, specialized labor graduation rates, and ANDRA storage capacity bottlenecks are the dominant revision risks to expenditure projections. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nuclear Energy
Europe Nuclear Reactor Decommissioning Market
Nuclear Energy
Nuclear Powered Merchant Vessel Market
Nuclear Energy
Germany Nuclear Power Reactor Decommissioning Market
Nuclear Energy
Asia-Pacific Nuclear Power Reactor Decommissioning Market
Nuclear Energy
Nuclear Spent Fuel Market
Nuclear Energy
North America Nuclear Power Reactor Decommissioning Market
Nuclear Energy
Nuclear Decommissioning Services Market
Nuclear Energy
Asia-Pacific Nuclear Power Plant and Equipment Market
Nuclear Energy
Global Molten Salt Reactor Market
Nuclear Energy
Small Modular Reactor (SMR) Market
Nuclear Energy
Middle-East and Africa Nuclear Power Plant Equipment Market
Nuclear Energy
Uranium Enrichment Market
Nuclear Energy
Nuclear Fuels Market
Nuclear Energy
Helium-3 Market
Nuclear Energy
Asia-Pacific Nuclear Reactor Construction Market
Nuclear Energy
United States Nuclear Power Reactor Decommissioning Market