
 Thorium Market | 2026-2036
Thorium Market Size, Share, and Industry Trends Forecast 2026-2036
Thorium Market Analysis
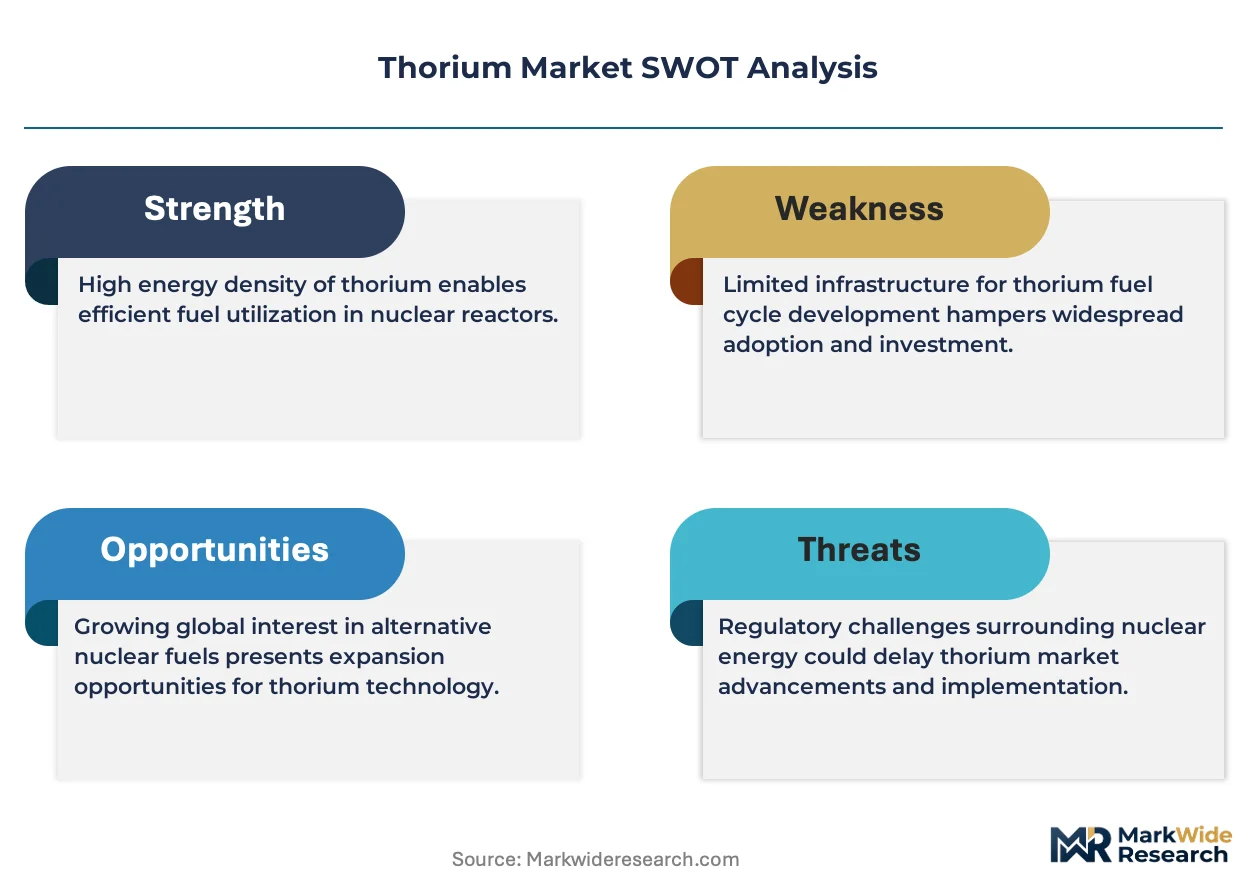
Multi-source procurement from uranium-dominant supply chains is pivoting toward thorium-inclusive strategies as utilities diversify nuclear fuel portfolios. Flibe Energy leverages molten salt reactor expertise to anchor early-stage thorium commercialization in North American markets. China National Nuclear Corporation dominates domestic thorium reserve development through state-coordinated mining and reactor integration programs. General Atomics competes in advanced reactor design, sustaining research pipelines that incorporate thorium fuel cycles alongside uranium alternatives.
Thorium is a naturally occurring radioactive actinide metal with atomic number 90, typically refined from monazite sands containing thorium oxide concentrations between three and nine percent, and serves primarily as a fertile material for breeding uranium-233 in nuclear reactors. Thorium oxide formulations lead current product demand due to established chemical stability and compatibility with high-temperature reactor environments, while thorium nitrate segments expand fastest in medical imaging isotope production where supply chain reliability matters. Aerospace radiation shielding applications occupy specialized margin pools, with defense contractors prioritizing thorium's density properties over cost-sensitive civilian alternatives.
The US Nuclear Regulatory Commission and Department of Energy shape domestic thorium demand through licensing frameworks for alternative fuel reactors, while China's Ministry of Ecology and Environment and National Nuclear Safety Administration govern thorium mining and molten salt reactor trials under national carbon neutrality mandates. India's Atomic Energy Regulatory Board controls market access through its three-stage program approvals, restricting private thorium processing to public sector entities. Stakeholders must monitor regulatory divergence between Western safeguard requirements and state-controlled thorium development models when assessing long-term supply partnerships.
Market Dynamics
State-coordinated thorium reserve development is converging with molten salt reactor commercialization timelines to reshape competitive positioning across nuclear fuel supply chains. Utilities now face binding procurement decisions between uranium-dominant portfolios and thorium-inclusive diversification strategies as regulatory frameworks mature.
Growth Catalysts
- India's three-stage nuclear program:Domestic thorium reserves accelerate breeder reactor deployment under Atomic Energy Regulatory Board oversight, restricting private processing to public sector entities while building technical capacity.
- Carbon neutrality mandates:China's Ministry of Ecology and Environment drives molten salt reactor trials through national dual carbon goals, creating state-backed demand corridors for thorium utilization technology.
- Fertile material breeding:Thorium oxide's chemical stability enables uranium-233 production in high-temperature reactor environments, attracting aerospace radiation shielding applications from defense contractors prioritizing density properties.
Market Restraints
- Regulatory fragmentation:Divergent safeguard requirements between Western licensing frameworks and state-controlled development models complicate long-term supply partnerships for international utilities.
- Monazite supply concentration:Thorium refining depends on mineral sands containing three-to-nine percent thorium oxide, with processing infrastructure concentrated in limited geographic jurisdictions.
- Uranium fuel cycle lock-in:Established uranium supply chains and reactor designs create switching costs for utilities evaluating thorium alternatives, delaying commercial adoption timelines.
Strategic Opportunities
- Medical isotope production:Thorium nitrate segments expand in radiopharmaceutical supply chains where reliability constraints favor alternative sourcing for imaging isotope generation.
- Molten salt reactor convergence:Liquid fuel designs enable continuous thorium feeding and online reprocessing, creating technical differentiation from solid-fuel uranium reactors.
- US licensing pathway development:The Nuclear Regulatory Commission's alternative fuel reactor frameworks create regulatory tailwinds for domestic thorium commercialization beyond demonstration phases.
Industry Challenges
- Specialized metallurgical expertise:Thorium fuel fabrication requires handling protocols distinct from uranium cycles, constraining workforce availability across reactor engineering and materials science functions.
- Prolonged certification timelines:Novel reactor designs face extended safety review processes under national nuclear regulators, compressing returns on capital-intensive development programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thorium Market |
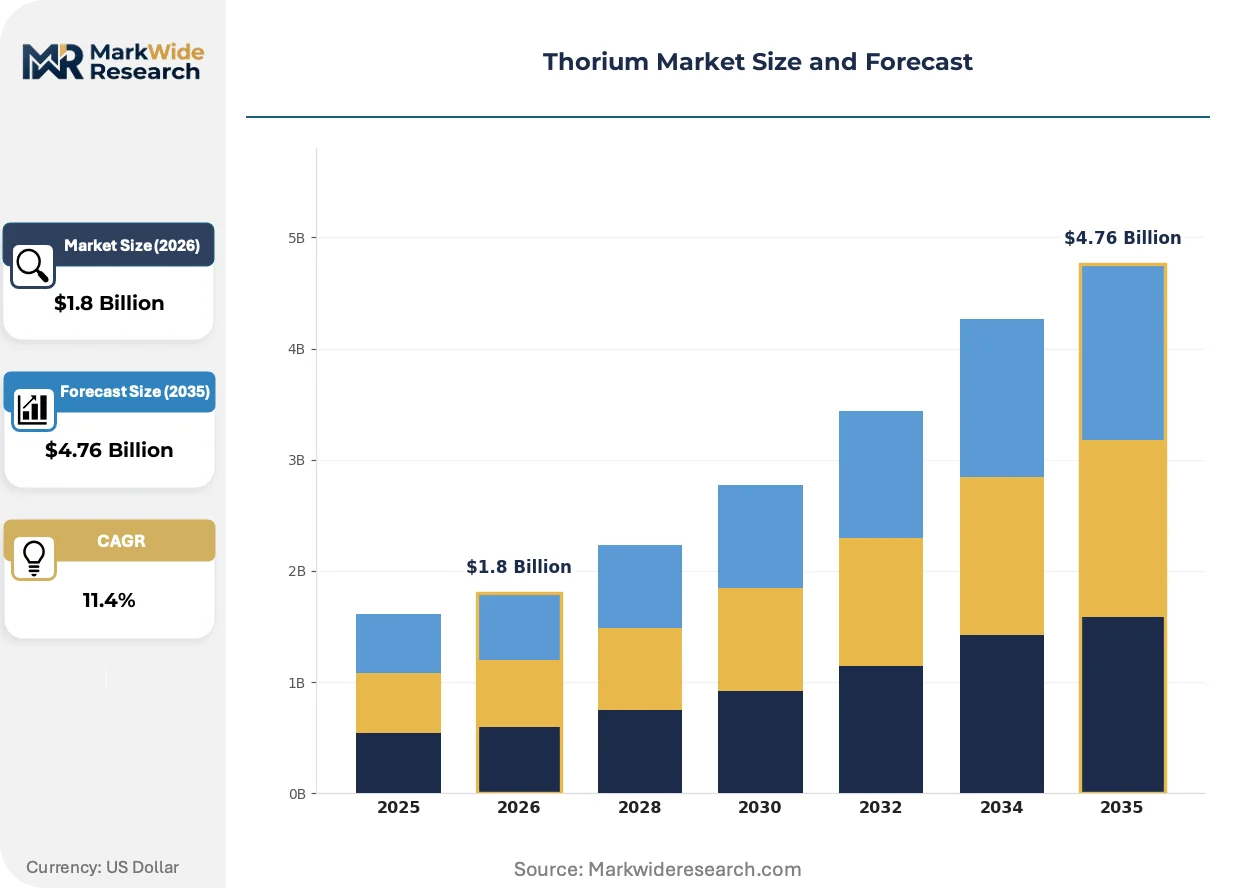
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thorium Oxide, Thorium Nitrate, Thorium Carbonate, Thorium Sulfate Application: Nuclear Fuel, Medical Imaging, Radiation Shielding, Aerospace End User: Energy Sector, Research Institutions, Defense, Manufacturing Distribution Channel: Wholesale, Direct Sales, Online Platforms, Retail |
| Companies Covered | Flibe Energy, Centrus Energy Corporation, China National Nuclear Corporation, Mitsubishi Heavy Industries, General Atomics, Cameco Corporation, American Rare Earths Limited, Rolls-Royce, TerraPower, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thorium Market Emerging Trajectories
Molten salt reactor architectures are actively displacing conventional solid-fuel designs as the dominant technical pathway for thorium commercialization. Three interconnected developments are compressing development timelines and reshaping competitive positioning across nuclear fuel markets.
Liquid fluoride thorium reactor technology is converging with high-temperature gas-cooled reactor materials science to enable corrosion-resistant containment systems. State-backed institutes in China and private developers in North America are advancing parallel demonstration programs. This convergence is compressing the gap between laboratory-scale validation and utility-scale deployment.
China's National Nuclear Safety Administration has issued specific guidance for thorium-fueled molten salt reactor trials under national carbon neutrality mandates. The policy creates expedited licensing pathways for state-coordinated projects while maintaining safeguard requirements for international technology transfer. Domestic thorium mining and reactor integration programs are capturing first-mover advantage in regulatory precedent-setting.
Energy utilities are consolidating procurement decisions under centralized fuel strategy offices rather than decentralized reactor operations teams. Long-term offtake agreements for thorium-inclusive portfolios are displacing spot-market uranium purchasing in markets with carbon pricing mechanisms. This shift is most visible in European and East Asian utilities with net-zero commitments and existing nuclear infrastructure.
Thorium Market Segmentation
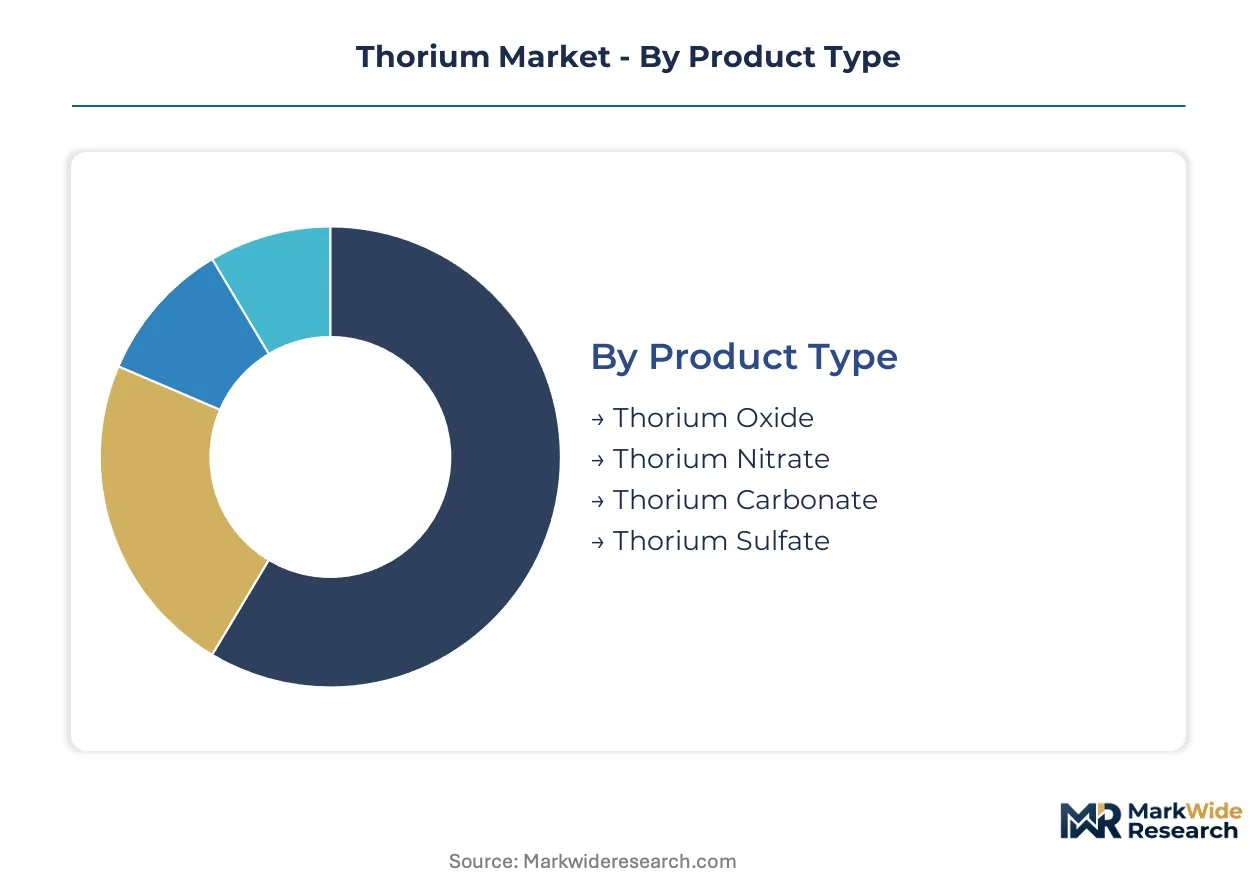
Thorium market segmentation reveals distinct technical specifications and regulatory pathways that shape procurement decisions across nuclear fuel, medical, and defense applications. Product chemistry determines reactor compatibility and shielding performance, while end-user concentration in state-controlled energy sectors creates divergent commercialization timelines.
Product Type:
Customization intensity varies sharply across this category, from standardized oxide formulations for reactor environments to specialized nitrate grades demanding batch-specific certification.
- Thorium Oxide:Ceramic-grade formulations with exceptional thermal stability above 3,000°C serve as the primary fertile material in high-temperature gas-cooled reactors. Demand concentrates in China's molten salt reactor corridor where state-backed institutes prioritize chemical compatibility with fluoride salt coolants.
- Thorium Nitrate:Soluble salt specifications enable precise isotope extraction protocols for radiopharmaceutical production. Medical imaging isotope manufacturers in India and Europe are diversifying supply chains away from reactor-dependent molybdenum-99 toward thorium-derived alternatives.
- Thorium Carbonate:Intermediate compound used in precursor synthesis for specialized ceramic applications and metallurgical research programs.
- Thorium Sulfate:Legacy processing reagent employed in rare earth co-extraction flowsheets at monazite refining facilities.
Leading the category by volume: Thorium Oxide. Expanding most quickly: Thorium Nitrate.
Application:
Application maturity spans decades-old radiation shielding deployments against experimental reactor designs still navigating licensing frameworks.
- Nuclear Fuel:Fertile material breeding cycles convert thorium-232 to uranium-233 through neutron capture in thermal and fast reactor spectra. India's three-stage program anchors procurement volume through public sector breeder deployment under Atomic Energy Regulatory Board jurisdiction.
- Medical Imaging:Thorium-229 decay chains yield actinium-225 and bismuth-213 for targeted alpha therapy, with supply reliability concerns driving alternative production investments. Research institutions in Germany and the US are establishing non-reactor extraction capabilities.
- Radiation Shielding:High-density formulations exploit thorium's 11.7 g/cm³ specific gravity for compact gamma attenuation in aerospace and defense applications.
- Aerospace:Specialized shielding configurations for satellite electronics and crewed mission architectures prioritize mass efficiency over cost optimization.
Dominant by procurement value: Nuclear Fuel. Steepest expansion trajectory: Medical Imaging.
End User:
Customer concentration ranges from consolidated state utilities to fragmented research consortia with divergent technical requirements and contracting protocols.
- Energy Sector:National nuclear corporations in China, India, and Russia coordinate thorium procurement through centralized fuel cycle organizations with multi-decade planning horizons.
- Research Institutions:University and national laboratory programs advance molten salt reactor physics, materials corrosion studies, and fuel fabrication techniques.
- Defense:Aerospace contractors and naval propulsion programs specify thorium shielding for radiation-hardened electronics and compact reactor architectures.
- Manufacturing:Rare earth processors and specialized ceramics producers consume thorium as a byproduct recovery stream from monazite sand processing.
Primary volume concentration: Energy Sector. Fastest contract diversification: Research Institutions.
Distribution Channel:
Channel selection reflects security classification levels and batch traceability requirements rather than conventional logistics cost optimization.
- Wholesale:Bulk oxide and nitrate shipments move through nuclear fuel brokers with NRC or equivalent licensing for radioactive material transport and custody transfer.
- Direct Sales:Long-term offtake agreements connect mining consortia directly to reactor operators, eliminating intermediary markup for strategic reserve programs.
- Online Platforms:Limited to non-radioactive thorium compounds and research-grade reagents with exempt quantity thresholds under national regulator guidelines.
- Retail:Specialty chemical distributors serve educational institutions and analytical laboratories with gram-scale certified reference materials.
Channel leadership by tonnage: Wholesale. Fastest digital infrastructure development: Direct Sales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for thorium concentrates in state-controlled nuclear programs across China, India, and Russia, with procurement decisions flowing through centralized national fuel cycle organizations rather than private market mechanisms.
China
Molten salt reactor trials under the Ministry of Ecology and Environment's dual carbon mandate are accelerating thorium reserve development. The National Nuclear Safety Administration has issued expedited licensing guidance for thorium-fueled demonstration projects. Shanghai and Gansu host parallel research corridors where state-backed institutes advance liquid fluoride reactor designs toward utility-scale deployment.
India
The three-stage nuclear program anchors procurement volume through breeder reactor deployment targeting domestic thorium reserves. The Atomic Energy Regulatory Board restricts private processing to public sector entities while building technical capacity. Kalpakkam and Trombay serve as concentrated hubs for fuel fabrication and materials research under Department of Atomic Energy jurisdiction.
United States
The Nuclear Regulatory Commission's alternative fuel reactor frameworks are creating regulatory pathways for thorium commercialization beyond demonstration phases. Advanced reactor developers are consolidating licensing strategies around molten salt architectures. Oak Ridge and Idaho National Laboratory anchor federal research programs with legacy thorium experience from prior breeder programs.
Russia
Rosatom coordinates thorium procurement through centralized fuel cycle planning with multi-decade horizons for fast reactor deployment. The national nuclear corporation integrates mining consortia directly with reactor operators through strategic reserve programs. Obninsk and Dimitrovgrad host specialized institutes advancing thorium-uranium fuel cycle physics.
Thorium Market Vendor Landscape
Strategic partnerships dominate the current landscape as reactor developers align with fuel cycle specialists and rare earth processors. The market exhibits tiered concentration with state nuclear corporations commanding reserve development, mid-scale technology licensors occupying demonstration-phase niches, and specialized materials firms serving medical and defense applications. Three archetypes define competitive positioning: state-coordinated integrated fuel cycle operators, private molten salt reactor technology licensors, and rare earth byproduct recovery specialists. Portfolio diversification into thorium-inclusive fuel strategies and technology licensing agreements represent the dominant competitive moves.
Among North American technology developers, Flibe Energy and TerraPower exemplify the private reactor design archetype, leveraging molten salt expertise to anchor early-stage commercialization pathways. State-coordinated positioning is represented by China National Nuclear Corporation, which occupies a centralized role in domestic reserve development and reactor integration. General Atomics sits within the diversified defense-industrial tier, sustaining research pipelines that incorporate thorium fuel cycles alongside established uranium alternatives.
| Leading Market Players |
|---|
| Flibe Energy |
| Centrus Energy Corporation |
| China National Nuclear Corporation |
| Mitsubishi Heavy Industries |
| General Atomics |
| Cameco Corporation |
| American Rare Earths Limited |
| Rolls-Royce |
| TerraPower |
| Others |
Supply Flow & Price Mechanics
China's dual carbon mandate gates qualified thorium supply and premium-tier pricing access, restricting reactor-grade oxide procurement to state-coordinated developers while medical-grade nitrate commands certification premiums from radiopharmaceutical manufacturers.
Pricing Analysis
Volume concentrates in long-term offtake agreements for nuclear fuel oxide, while margin pools sit in medical-grade nitrate batches with batch-specific isotope certification. Pricing stratifies across reactor-grade, medical-grade, and research-grade tiers, with differentiation driven by purity certification and safeguard documentation. Cost compression in standard oxide grades is intensifying because state utilities consolidate procurement under centralized fuel strategy offices. Research institutions exhibit highest price sensitivity due to grant-dependent budgets, while defense contractors accept density premiums for aerospace shielding specifications.
Supply Chain Analysis
India's domestic-content mandates for thorium processing are reshaping sourcing, requiring public sector entity status for monazite refining and fuel fabrication. Geographic supply concentration centers on India, China, and Russia, with raw material dependencies on monazite sands, rare earth co-extraction flowsheets, and fluoride salt coolant systems. Single-source vulnerability runs through concentrated monazite processing infrastructure. Distribution runs through nuclear fuel brokers with NRC-equivalent licensing for radioactive material custody transfer.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around state-coordinated fuel cycle operators, with regulatory fragmentation forcing private developers toward technology licensing rather than integrated supply chain competition.
For Market Incumbents: Anticipate molten salt reactor licensing delays by securing dual-jurisdiction certification pathways under both NRC frameworks and China's National Nuclear Safety Administration guidance. Anchor backward integration into monazite processing through rare earth joint ventures, mitigating feedstock concentration risk from India's public sector processing restrictions.
For New Entrants and Emerging Players: Capture medical isotope production white space by establishing thorium-229 decay chain extraction capabilities outside reactor-dependent supply chains. Target German and US research institutions with non-reactor actinium-225 production protocols, leveraging supply reliability concerns from molybdenum-99 shortages.
For Investors and Strategic Acquirers: First commercial molten salt reactor grid connection is the leading indicator that thorium-inclusive fuel portfolios will displace spot-market uranium purchasing in carbon-priced markets. Position for five-to-ten year viability through technology licensors with demonstrated corrosion-resistant containment systems rather than mining-stage exposure. Watch for expedited licensing guidance from China's Ministry of Ecology and Environment as the inflection signal for state-backed demand corridor maturation.
| Strategic Initiative | Industry Significance |
|---|---|
| Molten Salt Reactor Licensing | NRC alternative fuel frameworks create regulatory precedent for thorium commercialization beyond demonstration phases. |
| Medical Isotope Supply Agreement | Radiopharmaceutical manufacturers diversify from reactor-dependent molybdenum-99 toward thorium-derived actinium-225. |
| Rare Earth Joint Venture | Monazite co-extraction partnerships secure captive thorium feedstock while capturing rare earth byproduct value. |
| Dual-Jurisdiction Certification | Parallel NRC and National Nuclear Safety Administration approvals compress global deployment timelines for reactor designs. |
| Non-Reactor Extraction Scale-Up | Research institutions in Germany and the US establish thorium-229 decay chain capabilities independent of reactor infrastructure. |
Methodological Framework
Multi-period observation of molten salt reactor trial progress, licensing guidance issuance, and centralized utility procurement patterns anchored the trend analysis, supplemented by interviews with nuclear fuel strategy officers, reactor engineering directors, rare earth processing plant managers, and radiopharmaceutical supply chain specialists. Secondary validation drew from IEA nuclear energy outlooks, NRC docket filings, China National Nuclear Corporation annual disclosures, and monazite trade flow databases. Bottom-up segment sizing triangulated against top-down national nuclear program capacity announcements.
Segment-weighting across product chemistry, application maturity, and end-user concentration shaped the analytical framework over the projection horizon. Modeled dimensions included oxide versus nitrate formulations, nuclear fuel versus medical imaging applications, and state utility versus research institution end users. CAGRs derived from utility-scale deployment timelines, medical isotope demand elasticity, and carbon pricing mechanism adoption curves. Industry-specific inputs incorporated breeder reactor physics validation schedules and fluoride salt corrosion data from demonstration programs.
The model holds under continued state coordination of thorium reserve development and stable dual carbon policy enforcement; deviation in safeguard requirement harmonization or rare earth processing capacity constraints would shift commercialization timelines. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nuclear Energy
Fusion Power Market
Nuclear Energy
Nuclear Power Market
Nuclear Energy
Asia-Pacific Nuclear Reactor Construction Market
Nuclear Energy
Nuclear Power Pump Market
Nuclear Energy
United Kingdom Nuclear Power Reactor Decommissioning Market
Nuclear Energy
Asia-Pacific Nuclear Power Plant and Equipment Market
Nuclear Energy
United States Nuclear Power Reactor Decommissioning Market
Nuclear Energy
Global Thorium Reactor Market
Nuclear Energy
South America Nuclear Reactor Construction Market
Nuclear Energy
North America Nuclear Reactor Construction Market
Nuclear Energy
Asia-Pacific Nuclear Power Reactor Decommissioning Market
Nuclear Energy
France Nuclear Power Reactor Decommissioning Market
Nuclear Energy
China Nuclear Power Plant Equipment Market
Nuclear Energy
Nuclear Steam Generator Market
Nuclear Energy
Uranium Enrichment Market
Nuclear Energy
Small Modular Reactor (SMR) Market