
 Fusion Power Market | 2026-2036
Fusion Power Market Size, Share, and Industry Trends Forecast 2026-2036
Fusion Power Market Foresight
Project finance tied to reactor demonstration milestones is tilting competitive access toward well-capitalized entrants. Commonwealth Fusion Systems leverages its MIT-derived magnet technology to anchor the most advanced tokamak construction timeline in the private sector. TAE Technologies sustains its position through sustained venture backing and a distinct field-reversed configuration approach that differentiates its reactor physics from mainstream magnetic confinement rivals. Helion Energy competes with a pulsed non-tokamak design and direct electricity capture architecture that controls capital intensity relative to steam-cycle alternatives.
Fusion power denotes the energy released when light atomic nuclei combine under extreme temperature and pressure conditions exceeding 100 million degrees Celsius, producing helium and high-energy neutrons that transfer thermal energy to conventional steam or direct-conversion generators. Torus-based tokamak configurations currently dominate experimental deployment and absorb the majority of public research funding, while inertial confinement approaches occupy niche defense and materials-testing roles with limited commercial scaling pathways. Electricity generation applications lead investment flows due to grid-connected revenue potential, though hydrogen production represents the fastest-growing adjacent demand segment as industrial offtakers seek carbon-free feedstock alternatives.
The US Department of Energy and the Nuclear Regulatory Commission jointly shape market access through construction permitting frameworks and fuel-cycle security standards that determine reactor licensing timelines. Europe's Fusion for Energy agency and the ITER Organization coordinate procurement standards that influence supplier qualification and component interoperability across participating nations. Stakeholders must monitor regulatory divergence between national nuclear regimes and fusion-specific exemption pathways that will determine where first commercial plants achieve operational clearance.
Market Dynamics
Milestone-based federal funding from the US Department of Energy is compressing reactor demonstration timelines and concentrating capital flows toward private developers with proven magnet technology. This financing structure privileges entrants that can front-load engineering validation before commercial offtake agreements crystallize.
Growth Catalysts
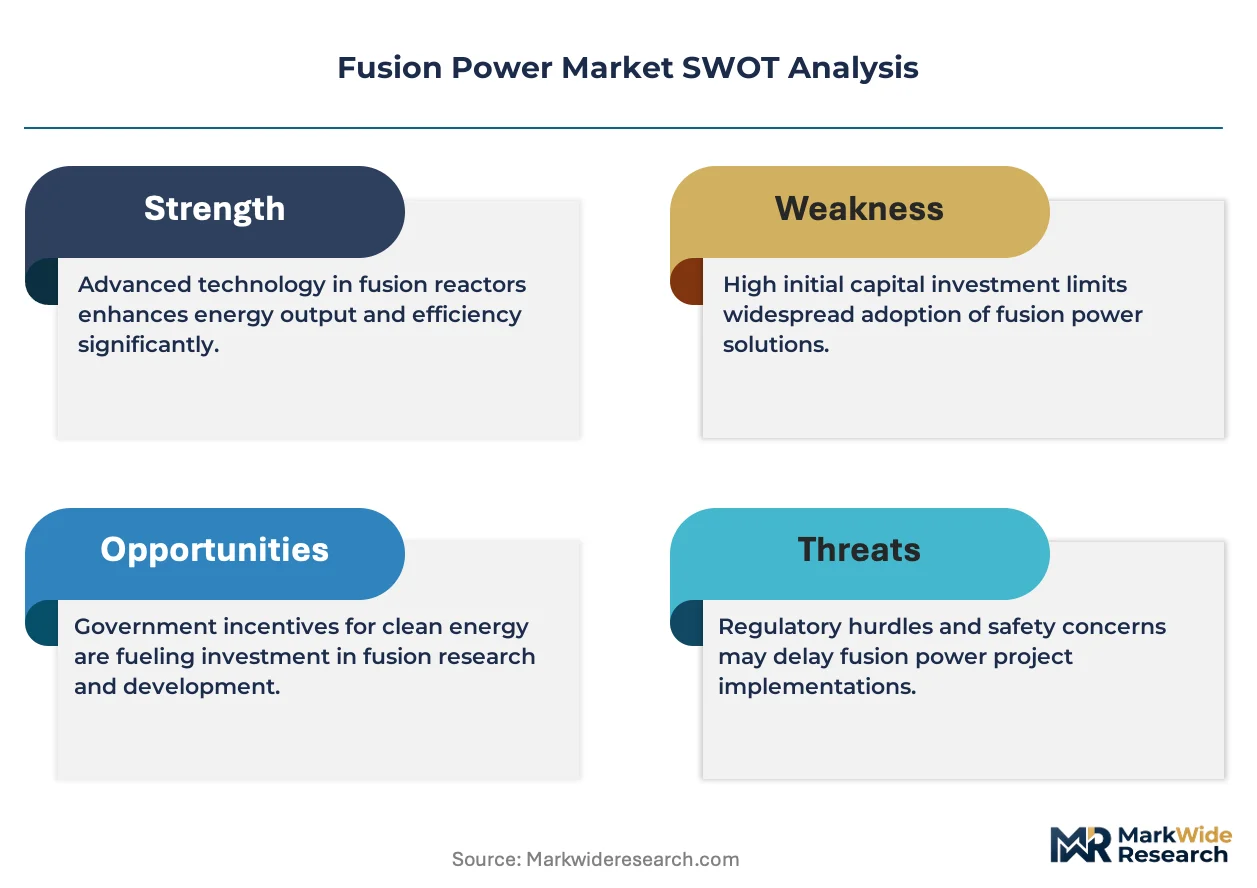
- Baseload Clean Power Mandates:Utilities facing decarbonization deadlines under state renewable portfolio standards are procuring firm zero-carbon capacity that solar and wind cannot provide.
- High-Temperature Superconductor Advances:Rare-earth barium copper oxide tape manufacturing scaling is reducing magnet capital intensity for compact tokamak architectures.
- Fuel Security Diversification:Tritium breeding blanket development programs in Canada and Australia are de-risking fuel-cycle dependencies for future reactor fleets.
Market Restraints
- Neutron-Resistant Materials Bottleneck:Reduced-activation ferritic-martensitic steel supply chains remain concentrated in Japanese and Korean specialty foundries with limited surge capacity.
- Regulatory Licensing Uncertainty:The US Nuclear Regulatory Commission's evolving fusion-specific framework creates timeline opacity for first-mover permitting.
- Capital Intensity Thresholds:Demonstration reactor builds require billion-dollar commitments before plasma-first operation validates physics performance.
Strategic Opportunities
- Industrial Hydrogen Feedstock:Ammonia and steel producers in the US Gulf Coast are evaluating fusion-derived process heat for carbon-free reduction chemistry.
- Grid-Scale Storage Integration:Pulsed reactor architectures pair naturally with liquid metal thermal storage for dispatchable electricity arbitrage.
- Defense Microreactor Contracts:The Department of Defense's mobile energy programs are soliciting compact fusion designs for forward operating base power.
Industry Challenges
- Plasma Control Specialist Scarcity:The talent pool for computational magnetohydrodynamics and real-time control systems remains shallow relative to deployment ambitions.
- Component Qualification Timelines:Vacuum vessel and divertor certification under ASME Boiler and Pressure Vessel Code Section III extends procurement cycles beyond reactor construction schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fusion Power Market |
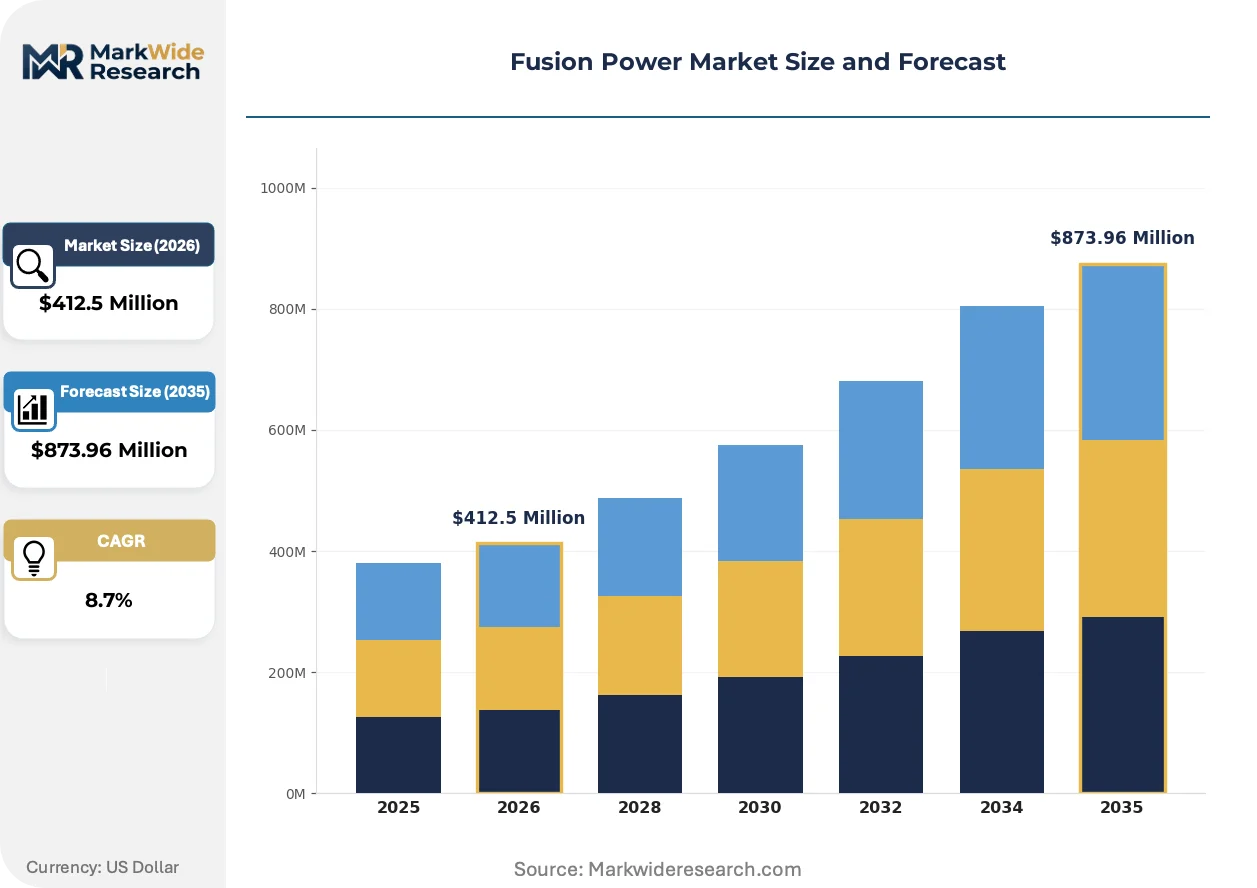
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $873.96 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Torus, Stellarator, Inertial Confinement, Magnetic Mirror, Z-Pinch, Field-Reversed Configuration Application: Electricity Generation, Desalination, Space Propulsion, Hydrogen Production, High-Energy Physics, Material Testing End User: Utilities, Research Institutions, Space Agencies, Defense Organizations, Industrial Manufacturers, Energy Cooperatives Deployment: Experimental Reactors, Pilot Plants, Commercial Facilities, Demonstration Projects, Mobile Units, Remote Installations |
| Companies Covered | Commonwealth Fusion Systems, Helion Energy, TAE Technologies, Tokamak Energy, General Fusion, China Fusion Energy Co. Ltd, First Light Fusion, Zap Energy, Marvel Fusion, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fusion Power Market Shifts & Advancements
Digital twin architectures are displacing physical prototyping for plasma-facing component design, compressing iteration cycles while neutron flux testing capacity remains scarce. This virtualization wave is redrawing competitive boundaries between hardware incumbents and simulation-native entrants.
High-field magnet technology is virtualizing the economic tradeoffs between reactor scale and plasma confinement performance. Commonwealth Fusion Systems and parallel ventures are deploying copper-stabilized REBCO magnets at 20 Tesla field strengths, enabling compact tokamak footprints that slash civil construction costs. Utilities with constrained siting permits are prioritizing these reduced-landfall designs for interconnection queue positions.
The US Department of Energy's Fusion Energy Sciences program is expanding cost-share mechanisms for private-sector reactor construction, redirecting national laboratory capabilities toward industry-led engineering validation. This policy reorientation accelerates technology transfer from public research infrastructure while tightening milestone accountability. Developers with existing magnet or laser facilities in Massachusetts and California are capturing disproportionate facility access.
Industrial offtakers are unbundling electricity procurement from capacity payments, seeking firm power purchase agreements that isolate fusion developers from merchant price volatility. Data center operators with 24/7 clean energy commitments in Northern Virginia and Phoenix are negotiating take-or-pay structures that de-risk first-plant financing. This contract innovation is concentrating early commercial demand among hyperscale computing loads rather than traditional utility ratebases.
Fusion Power Market Segmentation
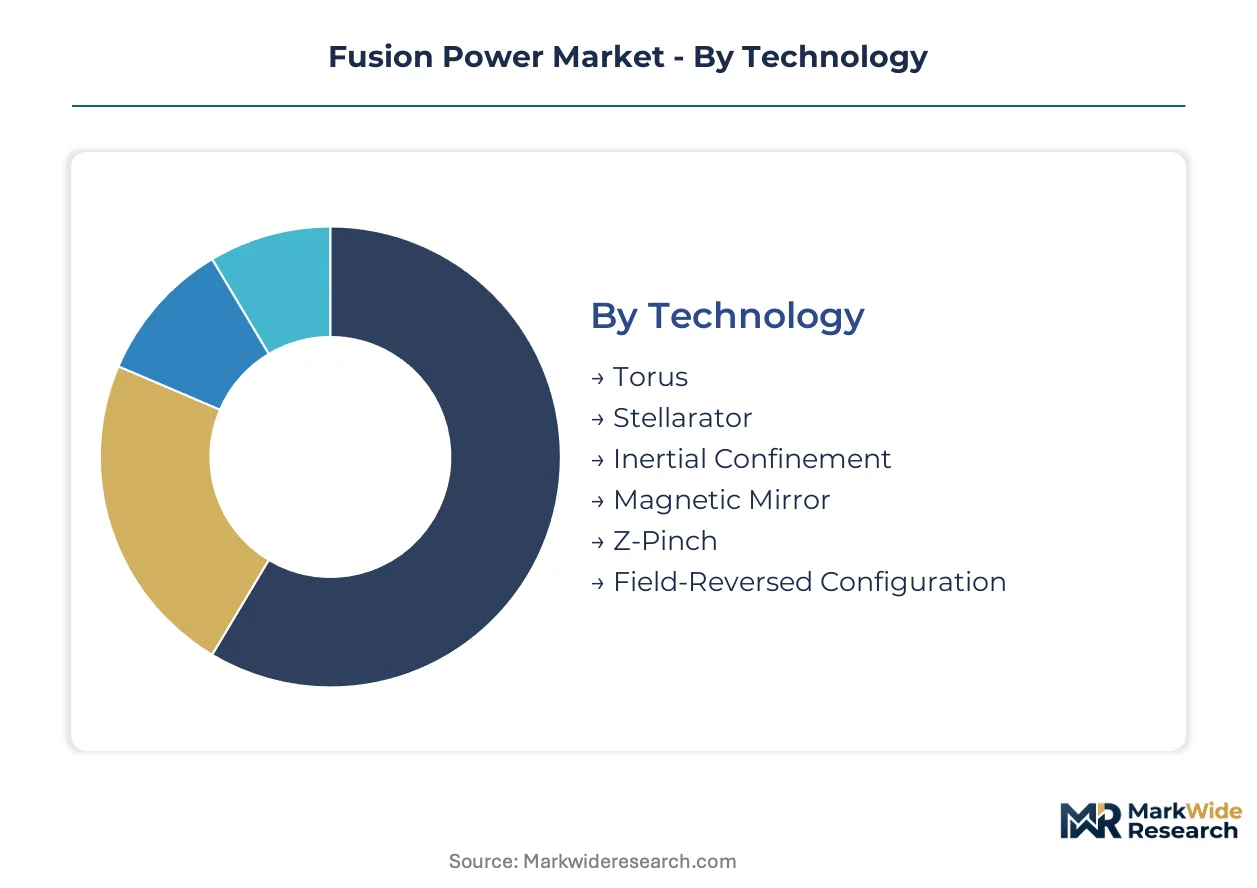
Fusion power market segmentation reveals how reactor physics, application requirements, and deployment maturity intersect to shape procurement patterns. Technology choice determines capital intensity and regulatory pathway, while end-user priorities range from baseload grid integration to specialized defense applications.
Technology:
The use-case spectrum spans continuous grid-connected electricity to pulsed defense applications, with each confinement approach trading off plasma stability against engineering complexity.
- Torus:Tokamak configurations employ toroidal magnetic fields to confine superheated plasma in a doughnut-shaped vacuum vessel. Commonwealth Fusion Systems and ITER anchor development in Massachusetts and southern France, driven by decades of public research infrastructure and established magnet supply chains.
- Field-Reversed Configuration:Compact toroidal plasmas without central solenoids enable simpler maintenance access and direct energy conversion potential. TAE Technologies in California pursues this trajectory for aneutronic proton-boron fuel cycles, attracting venture capital seeking reduced neutron damage liabilities.
- Stellarator:Twisted magnetic coils provide intrinsic plasma stability without active current drive, though manufacturing precision demands elevate capital costs. Germany's Wendelstein 7-X facility validates component tolerances for future commercial designs.
- Inertial Confinement:Laser or particle beam compression of fuel pellets achieves ignition in nanosecond pulses, suited primarily for stockpile stewardship and materials science rather than continuous electricity generation. Lawrence Livermore National Laboratory's National Ignition Facility dominates this category.
- Magnetic Mirror:Open-ended magnetic bottles confine plasma along field lines, offering simpler geometry but suffering from end losses that limit energy gain. Russian research programs and private ventures in the United States explore hybrid configurations.
- Z-Pinch:Axial electrical currents generate magnetic fields that radially compress plasma, achieving high densities with compact hardware footprints. Sandia National Laboratories maintains the primary experimental program, with pulsed power applications for defense and fusion-fission hybrid concepts.
The dominant share belongs to Torus architectures, while Field-Reversed Configuration is closing the gap fastest on private investment velocity.
Application:
Cost tier differentiation separates billion-dollar grid baseload projects from modular systems serving niche industrial heat demands.
- Electricity Generation:Grid-connected baseload power plants targeting 24/7 clean energy supply for utilities and data center operators. Northern Virginia and Phoenix hyperscale computing clusters are negotiating firm power purchase agreements that de-risk first-plant financing.
- Hydrogen Production:High-temperature process heat for steam methane reforming replacement or thermochemical water splitting. US Gulf Coast ammonia and steel producers evaluate fusion-derived feedstocks for carbon-free reduction chemistry.
- Desalination:Thermal distillation or reverse osmosis powered by reactor waste heat, addressing water scarcity in coastal regions with constrained freshwater resources.
- Space Propulsion:High specific impulse thrusters for deep-space missions and rapid transit to Mars, pursued by NASA and private launch ventures seeking alternatives to chemical rocket limitations.
- High-Energy Physics:Neutron sources for materials discovery and fundamental research, leveraging fusion plasma conditions unattainable in conventional accelerators.
- Material Testing:Controlled neutron flux environments for radiation damage studies on reactor structural components and electronics.
Electricity Generation commands the largest committed capital, though Hydrogen Production exhibits the steepest expansion trajectory as industrial offtakers unbundle clean feedstock procurement.
End User:
Customer type fragmentation spans rate-regulated utilities with long-term planning horizons to agile defense agencies seeking mobile energy solutions.
- Utilities:Investor-owned and public power entities procuring firm zero-carbon capacity under state renewable portfolio standards. Siting constraints in California and Texas favor compact high-field reactor designs for interconnection queue access.
- Research Institutions:Universities and national laboratories advancing plasma physics, materials science, and tritium breeding blanket development. MIT's Plasma Science and Fusion Center and Princeton Plasma Physics Laboratory anchor US academic leadership.
- Space Agencies:NASA and international counterparts evaluating fusion propulsion for crewed Mars missions and outer planet exploration.
- Defense Organizations:Department of Defense mobile energy programs soliciting compact designs for forward operating base power, prioritizing fuel logistics reduction over grid parity economics.
- Industrial Manufacturers:Steel, cement, and chemical producers seeking carbon-free process heat for reduction reactions and thermal processing.
- Energy Cooperatives:Member-owned utilities in rural regions exploring distributed generation models with smaller reactor footprints.
Utilities anchor current procurement pipelines, while Defense Organizations are gaining share fastest on accelerated acquisition timelines.
Deployment:
Maturity stage determines financing structure, with experimental facilities relying on government cost-share and commercial projects pursuing project finance.
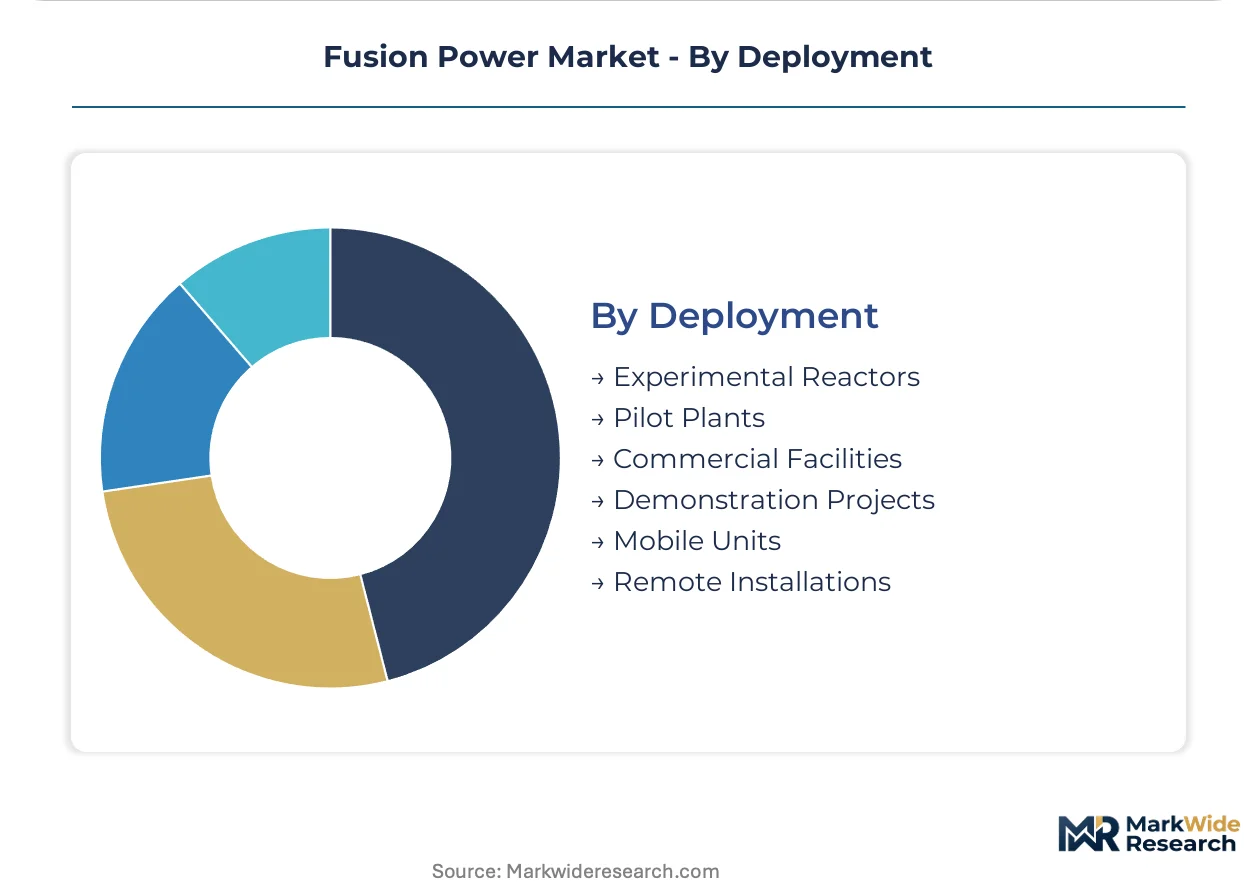
- Experimental Reactors:Plasma physics validation platforms without electricity generation, absorbing the majority of public research funding. ITER in France and Commonwealth Fusion Systems' SPARC in Massachusetts represent contrasting public-private models.
- Demonstration Projects:Net-energy-gain prototypes integrating full tritium fuel cycle and electricity conversion systems, requiring billion-dollar commitments before operational validation.
- Pilot Plants:Limited commercial operation with partial grid connection, testing maintenance protocols and regulatory compliance at reduced scale.
- Commercial Facilities:Full-scale baseload plants with firm offtake agreements and standard project finance structures, targeting operational availability above 80 percent.
- Mobile Units:Transportable reactor systems for defense and disaster response applications, trading efficiency for deployment flexibility.
- Remote Installations:Off-grid power for mining operations, polar research stations, and island communities with limited transmission infrastructure.
Experimental Reactors hold the dominant share of installed investment, though Demonstration Projects are expanding most quickly as milestone-based federal funding compresses private development timelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in fusion reactor development concentrates disproportionately in the United States, where milestone-based federal funding compresses timelines, while European procurement standardization through ITER spreads investment across multiple national budgets without equivalent concentration effects.
United States
Data center operators in Northern Virginia and Phoenix are negotiating firm power purchase agreements that de-risk first-plant financing. The US Department of Energy's milestone-based funding programs redirect national laboratory capabilities toward private-sector reactor construction. Commonwealth Fusion Systems anchors development in Massachusetts with SPARC, while TAE Technologies sustains California operations through sustained venture backing.
United Kingdom
Tokamak Energy pursues spherical tokamak commercialization from Oxfordshire, leveraging proximity to Culham Centre for Fusion Energy research infrastructure. The UK Atomic Energy Authority coordinates regulatory frameworks with the Environment Agency for future fusion plant licensing. Industrial clusters in the Oxford-Cambridge arc concentrate magnet supply chain development and plasma physics talent pools.
China
China Fusion Energy Co. Ltd advances indigenous tokamak capabilities through national laboratory networks in Hefei and Chengdu. The Ministry of Science and Technology directs funding toward EAST and CFETR demonstration programs under state technology sovereignty priorities. Eastern coastal manufacturing zones scale high-temperature superconductor tape production for magnet winding applications.
Germany
Max Planck Institute for Plasma Physics validates stellarator physics at Wendelstein 7-X in Greifswald, informing commercial design tolerances. The Federal Ministry of Education and Research coordinates EU-wide procurement standards through Fusion for Energy agency participation. Bavarian precision engineering clusters supply twisted magnetic coil fabrication for next-generation stellarator architectures.
Canada
General Fusion pursues magnetized target fusion development in British Columbia with private capital backing from energy majors. Natural Resources Canada funds tritium breeding blanket research to de-risk fuel-cycle dependencies for future reactor fleets. Vancouver's clean technology cluster concentrates alternative confinement approach development outside mainstream tokamak paradigms.
Fusion Power Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying magnets, vacuum vessels, and tritium handling systems. The vendor base stratifies between well-capitalized reactor developers with billion-dollar project pipelines and specialized engineering firms qualifying components under ASME Boiler and Pressure Vessel Code. Three archetypes dominate: MIT-derived academic spinouts with magnet technology advantages, venture-sustained physics ventures pursuing alternative confinement configurations, and national laboratory contractors executing government-funded demonstration programs. Competitive moves concentrate on strategic partnerships with industrial offtakers and geographic positioning for regulatory pathway access.
Within the academic spinout tier, Commonwealth Fusion Systems exemplifies platform integration by leveraging MIT-derived magnet technology for compact tokamak construction. TAE Technologies occupies a distinct position through sustained California-based venture backing and field-reversed configuration differentiation from mainstream magnetic confinement rivals. Helion Energy represents the pulsed non-tokamak archetype with direct electricity capture architecture that controls capital intensity relative to steam-cycle alternatives.
| Leading Market Players |
|---|
| Commonwealth Fusion Systems |
| Helion Energy |
| TAE Technologies |
| Tokamak Energy |
| General Fusion |
| China Fusion Energy Co. Ltd |
| First Light Fusion |
| Zap Energy |
| Marvel Fusion |
| Others |
Supply & Pricing Matrix
The Port of Long Beach container corridor carries rare-earth barium copper oxide tape from Japanese specialty foundries to Commonwealth Fusion Systems' Massachusetts magnet winding facilities, with freight cost volatility translating directly into capital intensity spreads between compact tokamak developers and conventional reactor architectures. This logistics artery concentrates pricing power among magnet supply chain incumbents while forcing downstream developers into long-term offtake structures that lock in component costs before plasma-first operation.
Pricing Analysis
Industrial OEM buyers anchor project-based contract structures that tie reactor component procurement to plasma physics milestones rather than commodity spot markets. Price differentiation rests on magnet field strength certification and ASME Boiler and Pressure Vessel Code Section III compliance tier, with premium-tier superconducting tape commanding substantial markups over standard industrial grades. Cost compression in vacuum vessel fabrication is intensifying because Japanese and Korean foundries face capacity constraints on reduced-activation ferritic-martensitic steel. Data center operators with 24/7 clean energy commitments exhibit the least price sensitivity, while rural energy cooperatives exploring distributed generation models face the tightest procurement budgets.
Supply Chain Analysis
Specialized contract manufacturers in Japan, South Korea, and Germany hold concentrated capacity for high-temperature superconductor tape winding and precision stellarator coil fabrication. Raw material dependencies draw from Chinese rare-earth processing, Australian lithium for tritium breeding blanket thermal management systems, and Canadian heavy water reserves. Single-source vulnerability runs through Japanese specialty steel foundries with limited surge capacity for neutron-resistant structural components. Distribution feeds from magnet component suppliers through national laboratory qualification programs to reactor developers pursuing NRC licensing pathways.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The fusion power sector rewards entities that control scarce plasma control specialist talent pools and magnet technology IP ahead of demonstration reactor completion. Organizations must secure these assets before milestone-based federal funding concentrates capital among proven entrants.
For Market Incumbents: Harden magnet supply chain positions through captive partnerships with REBCO tape manufacturers in Japan and Korea, insulating against foundry capacity constraints that threaten SPARC-class construction timelines. Deepen regulatory engagement with the NRC's evolving fusion-specific framework to secure permitting pathway clarity before competitor submissions queue. Prioritize tritium breeding blanket development partnerships with Canadian and Australian fuel cycle programs to de-risk future fleet dependencies. For New Entrants and Emerging Players: Establish a beachhead in industrial hydrogen feedstock applications serving US Gulf Coast ammonia and steel producers, where carbon-free process heat procurement lacks incumbent fusion supplier relationships. Target defense microreactor contracts through the Department of Defense's mobile energy programs, where accelerated acquisition timelines bypass grid-connected electricity market barriers. Lead with pulsed reactor architectures paired with liquid metal thermal storage to differentiate from baseload tokamak competitors. For Investors and Strategic Acquirers: Physics-native engineering firms with computational magnetohydrodynamics capabilities and existing national laboratory subcontracts represent the most defensible acquisition archetype for long-term positioning across the technology maturation window. Monitor Department of Energy cost-share award announcements as the primary inflection signal for which private developers will secure disproportionate facility access and construction timeline compression.| Strategic Initiative | Industry Significance |
|---|---|
| High-Field Magnet Supply Agreement | REBCO tape procurement from Japanese foundries secures compact tokamak construction timelines against capacity bottlenecks. |
| Tritium Breeding Blanket Partnership | Canadian and Australian fuel cycle collaboration de-risks long-term fleet dependencies for commercial reactor operators. |
| Data Center PPA Structuring | Firm take-or-pay contracts with Northern Virginia hyperscale operators de-risk first-plant project finance commitments. |
| NRC Pre-Application Engagement | Early regulatory pathway dialogue with the Nuclear Regulatory Commission compresses licensing opacity for first-mover plants. |
| Plasma Control Talent Acquisition | Computational magnetohydrodynamics specialist recruitment addresses critical scarcity constraining reactor control system development. |
Research Methodology
Initial hypotheses were tested against primary input from fusion reactor developers, utility planning officers, national laboratory program directors, and superconducting magnet procurement leads, and refined through secondary validation against Department of Energy funding announcements, NRC regulatory dockets, ITER procurement records, and ASME code revision proceedings. Bottom-up triangulation across project development databases and top-down reconciliation with federal budget appropriations shaped market sizing outputs.
Demand-supply balance modeling across the analysis window integrated technology segmentation by confinement approach, application tier from grid electricity to industrial hydrogen, end-user type from utilities to defense agencies, and deployment maturity from experimental reactors through commercial facilities. CAGRs were derived from project pipeline aggregation and milestone-based funding trajectory analysis, with high-temperature superconductor manufacturing scaling curves and plasma control specialist labor market tightness serving as key forecast modifiers.
Sensitivities concentrate around NRC licensing timeline revisions, Japanese foundry capacity expansion decisions, and tritium breeding blanket technical validation schedules. Forecasts embed assumptions regarding federal cost-share continuity and magnet technology transfer velocity from public research infrastructure. Quarterly review of Department of Energy award announcements, NRC guidance document releases, and REBCO tape production capacity indicators is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nuclear Energy
Germany Nuclear Power Reactor Decommissioning Market
Nuclear Energy
Nuclear Power Plant Equipment Market
Nuclear Energy
South America Nuclear Reactor Construction Market
Nuclear Energy
Nuclear Powered Merchant Vessel Market
Nuclear Energy
Nuclear Fuels Market
Nuclear Energy
Asia-Pacific Nuclear Reactor Construction Market
Nuclear Energy
North America Nuclear Power Reactor Decommissioning Market
Nuclear Energy
Asia-Pacific Nuclear Power Reactor Decommissioning Market
Nuclear Energy
Global Nuclear Fusion Market
Nuclear Energy
Europe Nuclear Power Plant and Equipment Market
Nuclear Energy
China Nuclear Power Plant Equipment Market
Nuclear Energy
Japan Nuclear Power Reactor Decommissioning Market
Nuclear Energy
Europe Nuclear Reactor Decommissioning Market
Nuclear Energy
United States Nuclear Power Plant Equipment Market
Nuclear Energy
Nuclear Fuel Fabrication Market
Nuclear Energy
North America Nuclear Power Plant and Equipment Market