
 India Floor Covering Market | 2026-2036
India Floor Covering Market Size, Share, and Industry Trends Forecast 2026-2036
India Floor Covering Market Foresight
Subscription-based maintenance and replacement coverage for commercial flooring installations is pivoting how building operators budget lifecycle costs. Kajaria Ceramics Ltd leverages its extensive dealer network to dominate tier-two and tier-three city distribution. Asian Granito India Ltd anchors its competitiveness through integrated tile and sanitaryware manufacturing capabilities. Responsive Industries Ltd specializes in vinyl-based resilient flooring for healthcare and education infrastructure buyers.
Floor covering encompasses surface materials installed to protect substrates, enhance aesthetics, and provide functional properties such as slip resistance, acoustic dampening, and thermal insulation; ceramic tiles typically measure 300x300 mm to 800x1200 mm with water absorption rates below 0.5% for vitrified grades, while vinyl compositions incorporate PVC wear layers rated for commercial traffic classes 23-34 under EN ISO 10874. The residential application segment leads volume absorption across India's urbanizing corridors, though hospitality-grade installations command superior margin pools due to specification complexity and shorter replacement cycles. Wood and textile materials occupy premium positioning in metropolitan luxury housing, whereas plastic-based vinyl and laminate alternatives capture cost-sensitive commercial retrofit demand.
BIS standards for ceramic tiles and resilient flooring mandate dimensional consistency and chemical emission limits that filter sub-scale suppliers from formal procurement channels. The Plastic Waste Management Rules and state-level green building codes in Maharashtra and Tamil Nadu are redirecting specification preferences toward recycled-content and low-VOC product lines. Stakeholders must monitor evolving state municipal corporation tender norms and BIS amendment schedules to anticipate compliance-driven product redesign cycles.
Market Dynamics
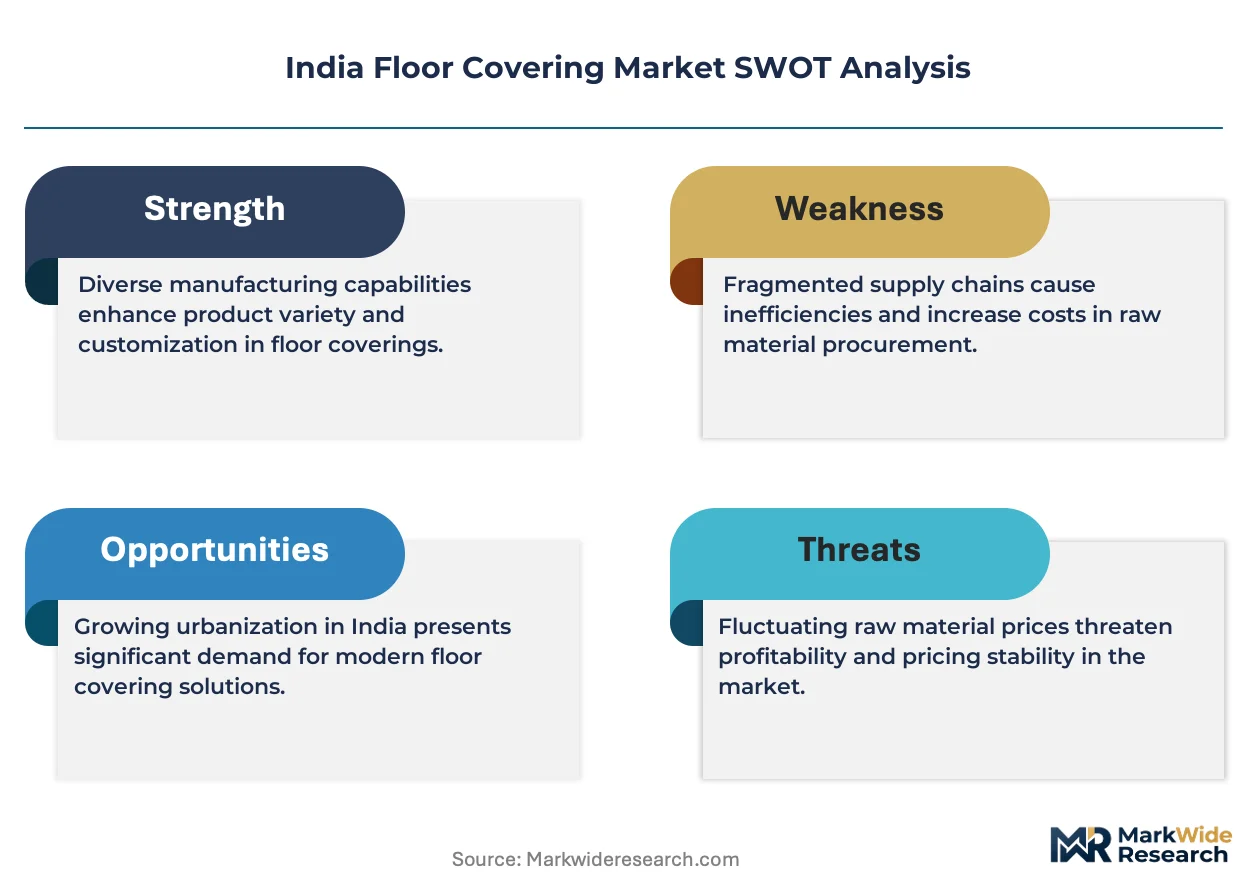
BIS certification tightening for ceramic tiles and vinyl products is filtering sub-scale suppliers from formal procurement channels, concentrating supply among integrated manufacturers capable of absorbing compliance redesign cycles.
Growth Catalysts
- Maharashtra-Gujarat manufacturing corridor:Overlapping tile production clusters and real estate development in these states generate dense logistics networks and specification pull-through from adjacent construction activity.
- BIS quality mandates:Dimensional consistency and chemical emission thresholds under revised ceramic tile standards are professionalizing procurement and rewarding certified producers with tender access.
- Healthcare infrastructure expansion:Vinyl-based resilient flooring specifications for hospitals and diagnostic centers are accelerating due to infection control and acoustic dampening requirements.
Market Restraints
- Feldspar and clay input volatility:Ceramic tile margins compress when Gujarat and Rajasthan mineral feedstock prices spike, particularly for vitrified grades requiring high-purity inputs.
- Single-region supply concentration:Morbi in Gujarat hosts over 80 percent of domestic ceramic tile capacity, exposing buyers to localized power shortages and freight bottlenecks.
- Plastic Waste Management Rules friction:Recycled-content mandates for vinyl flooring create formulation complexity and testing overhead that slows product line refresh cycles.
Strategic Opportunities
- Tier-three city retail penetration:Dealer network expansion into Uttar Pradesh and Madhya Pradesh secondary cities captures first-mover advantage as housing stock modernizes.
- Green building code alignment:Maharashtra and Tamil Nadu low-VOC and recycled-material preferences open specification windows for compliant product portfolios.
- Digital templating convergence:Integration of 3D visualization software with dealer inventory systems reduces specification friction for residential renovation buyers.
Industry Challenges
- Skilled installation labor scarcity:Vitrified tile large-format handling and epoxy grout application require trained crews that remain concentrated in metropolitan markets.
- Multi-standard certification timelines:Simultaneous BIS, ISO, and state green code compliance testing extends product launch windows by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Floor Covering Market |
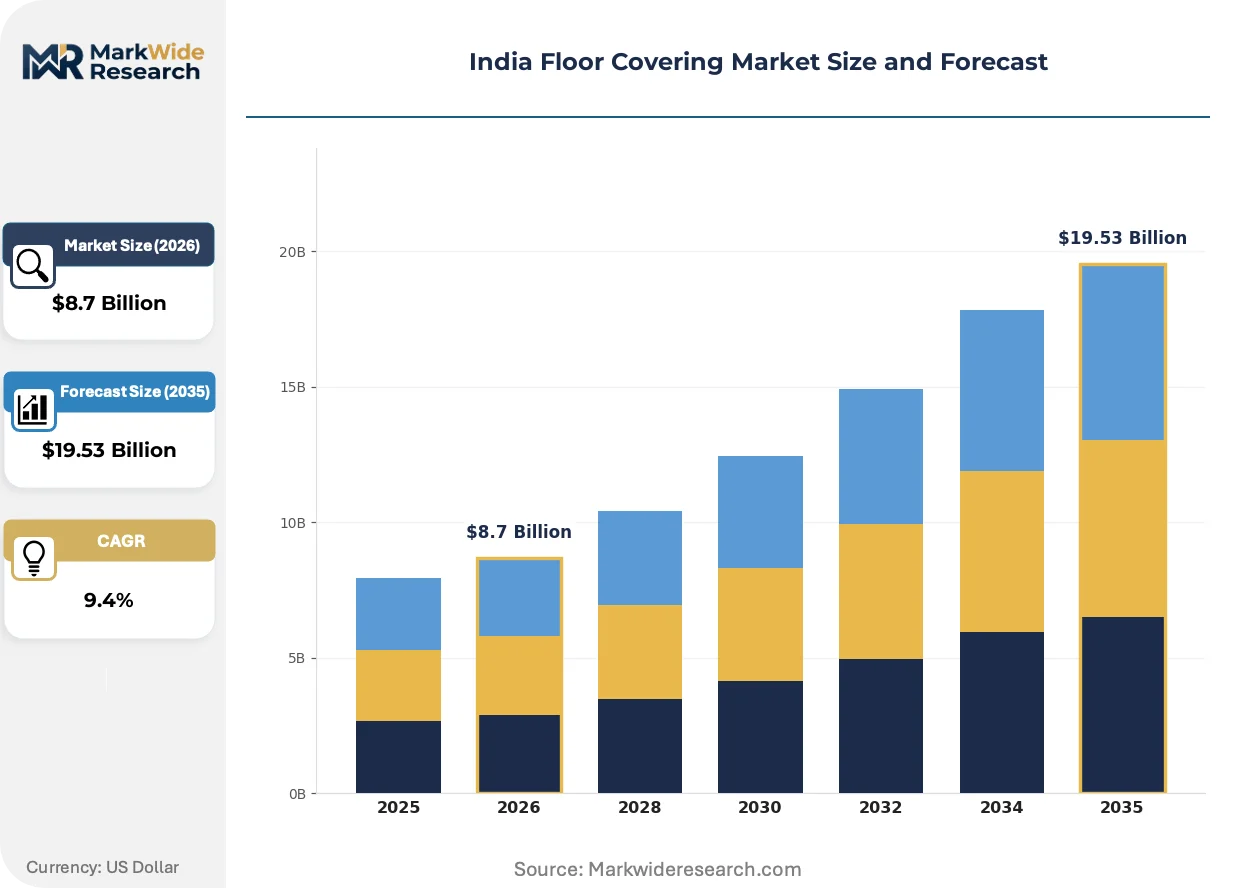
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
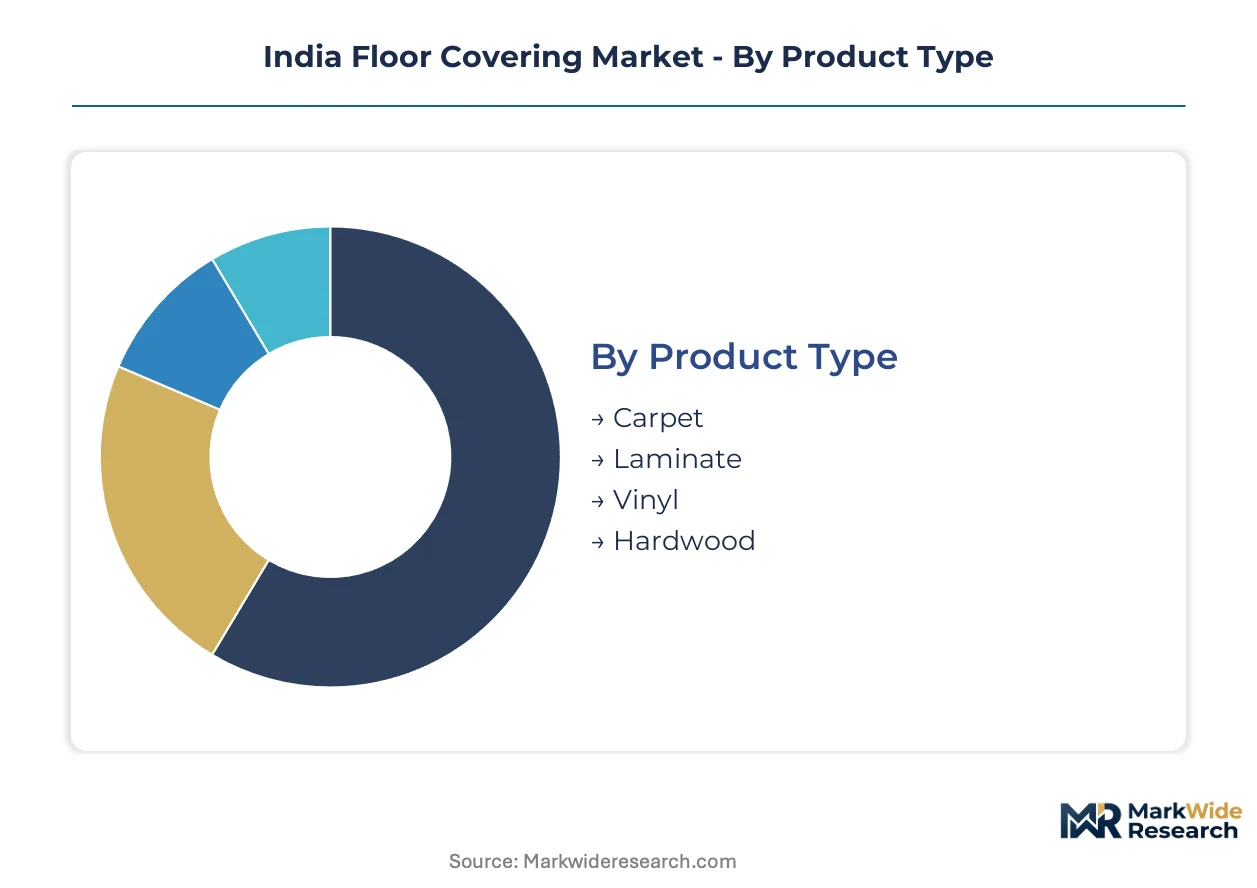
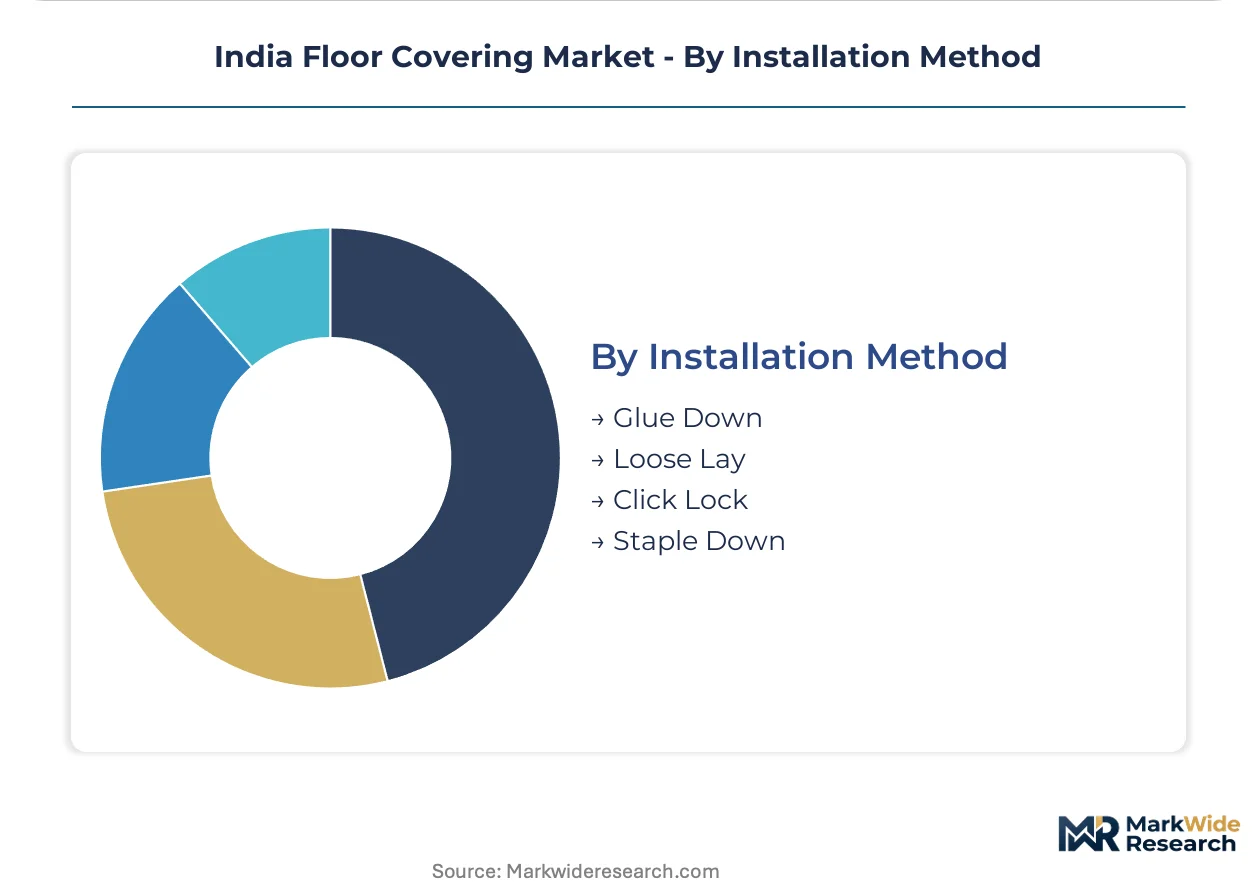
| Segmentation | Product Type: Carpet, Laminate, Vinyl, Hardwood Application: Residential, Commercial, Industrial, Hospitality Material: Wood, Plastic, Textile, Rubber Installation Method: Glue Down, Loose Lay, Click Lock, Staple Down |
| Companies Covered | Asian Granito India Ltd, RAK Ceramics India Pvt. Ltd., Kajaria Ceramics Ltd, Responsive Industries Ltd, Welspun Flooring Ltd, Somany Ceramics Ltd, Nitco Limited, H & R Johnson, Orient Bell Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Floor Covering Market Shifts & Advancements
Digital specification tools and material science advances are compressing the gap between aesthetic preference and performance validation, reshaping how architects and contractors finalize surface material selections.
Thin large-format vitrified tiles are expanding into high-rise residential towers as developers seek weight reduction on structural slabs without sacrificing surface durability. Mumbai and Bangalore housing complexes specify 1200x2400 mm panels at 6mm thickness to enable faster installation and reduced dead load. This format shift is expanding into mid-premium segments previously served by standard 800x800 mm ceramic, compressing price positioning across thickness categories.
BIS amendment schedules for ceramic tiles and resilient flooring are accelerating compliance-driven product redesign cycles among integrated manufacturers. The 2023-2024 revision tranche introduced stricter water absorption testing protocols and formaldehyde emission limits that forced laboratory retesting of existing SKUs. Gujarat-based producers with captive testing facilities adapted fastest, while smaller Morbi units faced extended validation queues.
Subscription-based maintenance contracts for commercial flooring installations are displacing capital-heavy replacement budgeting among hospital and education facility operators. Building managers in Maharashtra and Karnataka negotiate 7-10 year service agreements that bundle installation, periodic deep cleaning, and damage replacement. This model concentrates vendor relationships with full-service providers capable of maintaining dedicated maintenance crews across multiple properties.
India Floor Covering Market Segmentation
Floor covering procurement in India fragments across material science, installation logistics, and end-use performance requirements. Specification decisions hinge on replacement cycle economics, BIS compliance pathways, and regional installer availability rather than aesthetic preference alone.
Product Type:
Upgrade cycles vary dramatically by product category, with commercial-grade vinyl demanding 7-10 year replacement planning while residential laminate stretches toward 15-year horizons.
- Vinyl:PVC wear-layer compositions rated for commercial traffic classes under EN ISO 10874 dominate hospital and education specifications. Maharashtra healthcare infrastructure tenders specify anti-microbial topcoats and acoustic backing layers that filter non-certified suppliers.
- Ceramic Tile:Vitrified grades with water absorption below 0.5% anchor residential and hospitality volume. Morbi manufacturing clusters supply large-format 1200x2400 mm panels to Mumbai high-rise developers seeking structural load reduction.
- Carpet:Nylon and wool-pile textiles retain premium positioning in metropolitan luxury housing despite maintenance-intensive profiles.
- Laminate:HDF-core products with AC3-AAC4 durability ratings capture cost-sensitive residential retrofit demand across tier-two cities.
- Hardwood:Engineered oak and teak installations concentrate in Bangalore and Delhi-NCR luxury segments where tropical climate stability concerns limit solid-wood specification.
Vinyl sits at the top of the volume ranking, with ceramic tile climbing the fastest as vitrified large-format adoption penetrates mid-premium housing.
Application:
Cost tier stratification separates specification pools, with hospitality and healthcare commanding 40-60% premium pricing over residential equivalents due to performance certification requirements.
- Residential:Volume concentration in Maharashtra and Gujarat urban corridors drives ceramic tile and laminate procurement. First-time homebuyers in Pune and Ahmedabad prioritize BIS-certified vitrified products with 10-year manufacturer warranties.
- Commercial:Office and retail fit-outs in Mumbai and Bangalore specify vinyl and carpet tile for modular replacement flexibility. Lease-term alignment with flooring lifecycle drives 5-7 year depreciation budgeting.
- Hospitality:Hotel and resort developers source imported marble-look porcelain and engineered hardwood for lobby and guest room differentiation. Shorter 3-5 year refresh cycles sustain premium supplier relationships.
- Industrial:Epoxy-coated concrete and rubber flooring dominate factory and warehouse specifications where chemical resistance and static control override aesthetic considerations.
Residential commands absolute volume leadership, though hospitality delivers the steepest margin expansion trajectory per square meter installed.
Material:
Supply concentration geography dictates procurement lead times and freight economics, with Gujarat plastic resin clusters and Rajasthan clay deposits shaping material availability.
- Plastic:PVC and vinyl compositions incorporate recycled-content mandates under Plastic Waste Management Rules that extend formulation testing timelines. Responsive Industries and integrated polymer processors in Gujarat control upstream resin access.
- Wood:Engineered timber imports from Southeast Asia and domestic rubberwood processing face FSSAI-adjacent import documentation and moisture-content certification for tropical climate stability.
- Textile:Carpet pile manufacturing concentrates in Panipat and Bhadohi weaving clusters where wool and nylon fiber processing integrates with domestic upholstery supply chains.
- Rubber:Industrial flooring and gymnasium specifications source SBR and EPDM compounds from Kerala and Tamil Nadu rubber belt processors with captive carbon-black blending capabilities.
Plastic-based materials dominate volume throughput, with wood-based alternatives gaining share fastest in premium residential segments.
Installation Method:
Customer type stratification separates professional contractor specifications from retail DIY channels, with skill scarcity in large-format handling creating installation-method lock-in.
- Glue Down:Permanent adhesive application dominates commercial vinyl and carpet installations where subfloor preparation and moisture barrier compliance filter uncertified contractors. Maharashtra hospital tenders mandate epoxy-based systems with 10-year bond warranties.
- Click Lock:Floating floor systems for laminate and engineered wood accelerate residential renovation timelines. Bangalore and Hyderabad housing societies specify click-lock for tenant turnover minimization.
- Loose Lay:Friction-fit vinyl planks enable rapid commercial retrofit without subfloor remediation, popular in leased retail spaces with 3-5 year occupancy horizons.
- Staple Down:Traditional carpet and hardwood fastening retains share in wood-substrate residential construction where concrete slab prevalence in urban towers limits applicability.
Glue Down methods retain volume leadership in commercial specifications, with Click Lock expanding most quickly in tier-two city residential stock modernization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping production geography as manufacturers migrate toward states with lower compliance friction and denser raw material access. BIS certification costs and state-level green building codes create uneven playing fields that concentrate investment in Gujarat and Maharashtra while pushing marginal producers toward secondary clusters.
Maharashtra
Mumbai's high-rise residential towers drive demand for thin large-format vitrified tiles that reduce structural dead load. The state's green building code mandates low-VOC flooring specifications that filter non-compliant suppliers from municipal tenders. Pune and Nashik manufacturing corridors host integrated tile producers with captive testing facilities that accelerate BIS amendment adaptation.
Gujarat
Morbi's ceramic tile cluster supplies over 80 percent of domestic capacity, creating freight and power redundancy risks for national buyers. BIS water absorption testing protocols introduced in 2023-2024 forced laboratory retesting that favored Gujarat-based producers with in-house facilities. The state's plastic resin processing infrastructure supports vinyl flooring formulation for healthcare and education infrastructure buyers.
Karnataka
Bangalore's technology corridor generates commercial office fit-out demand for modular carpet tile and resilient vinyl systems. The state's municipal corporation tender norms increasingly reference BIS-certified products that professionalize procurement channels. Mysuru and Hubli-Dharwad secondary cities are attracting dealer network expansion as housing stock modernizes.
Tamil Nadu
Chennai's hospitality and healthcare infrastructure drives premium flooring specifications with shorter replacement cycles. State-level green building codes align with Maharashtra in prioritizing recycled-content and low-emission product lines. Coimbatore's industrial flooring market sources rubber compounds from Kerala processors for factory and warehouse applications.
Delhi-NCR
The National Capital Region's luxury residential segment specifies engineered hardwood and imported porcelain for climate-stable performance. NCR municipal authorities enforce BIS dimensional consistency standards that exclude sub-scale suppliers from formal procurement. Faridabad and Ghaziabad distribution hubs connect Morbi manufacturing output to North Indian retail channels.
India Floor Covering Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated producers capturing tender access through BIS certification while smaller Morbi units serve informal retail channels. The market structures around three tiers: national brands with dealer networks, regional fabricators with cost advantages, and import-dependent specialists in premium niches. Dominant competitive moves include backward integration into mineral feedstock and captive testing infrastructure, alongside geographic expansion of dealer networks into tier-three cities.
Among integrated manufacturers, Kajaria Ceramics Ltd, Asian Granito India Ltd, and Responsive Industries Ltd occupy positions that exemplify distinct strategic archetypes. Kajaria Ceramics Ltd represents the dealer-network-driven model with penetration into secondary cities. Asian Granito India Ltd anchors the integrated tile-sanitaryware manufacturing approach. Responsive Industries Ltd exemplifies specialization in vinyl-based resilient flooring for institutional buyers. These companies illustrate how compliance capability and distribution depth separate sustainable competitors from marginal suppliers.
| Leading Market Players |
|---|
| Asian Granito India Ltd |
| RAK Ceramics India Pvt. Ltd. |
| Kajaria Ceramics Ltd |
| Responsive Industries Ltd |
| Welspun Flooring Ltd |
| Somany Ceramics Ltd |
| Nitco Limited |
| H & R Johnson |
| Orient Bell Limited |
| Others |
Supply & Pricing Matrix
Certification-grade bifurcation between BIS-compliant integrated manufacturers and sub-scale Morbi units manifests in divergent pricing power and procurement channel access. Premium producers command tender participation rights that commodity suppliers forfeit, while supply chain configurations concentrate mineral feedstock proximity in Gujarat and Maharashtra corridors.
Pricing Analysis
Distributor margins absorb compliance testing overhead for certified product lines, compressing netbacks for manufacturers without captive laboratory facilities. Three-tier pricing structure across premium, standard, and economy levels separates hospitality-grade specifications from residential retrofit segments, with BIS certification tier and volume scale as primary differentiation drivers. Cost compression in vitrified large-format categories intensifies as Morbi cluster capacity expansion outpaces demand absorption. First-time homebuyers in tier-two cities exhibit highest price sensitivity, while hospital procurement committees prioritize performance certification over unit economics.
Supply Chain Analysis
Direct-to-dealer channels handle residential volume distribution, while project-direct relationships serve Mumbai and Bangalore high-rise developers. Supply concentrates in India, with feldspar and clay feedstock drawn from Rajasthan and Gujarat mineral belts, PVC resin from Gujarat polymer processors, and engineered timber imports from Southeast Asia. Single-region manufacturing concentration in Morbi exposes buyers to localized power disruption risks. Distribution runs through tier-one distributor hubs in Delhi-NCR, Mumbai, and Bangalore before penetrating secondary city retail networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
BIS compliance cost differentials between Gujarat-based integrated producers and marginal suppliers create geographic-arbitrage opportunities for manufacturing footprint optimization. Regulatory friction in Maharashtra and Tamil Nadu green building codes accelerates specification shifts that favor prepared portfolios.
For Market Incumbents: Cement dealer network loyalty through exclusive territory arrangements and captive installation crew deployment. Threats from thin large-format import substitution and emerging vinyl specialists in healthcare segments demand backward integration into Rajasthan feldspar deposits and in-house BIS testing infrastructure to compress amendment adaptation cycles. For New Entrants and Emerging Players: The premium-economy price-point gap in tier-three city vinyl flooring opens white-space targeting for modular click-lock systems with anti-microbial topcoats. Uttar Pradesh and Madhya Pradesh secondary cities represent most penetrable geography, with digital templating partnerships as primary go-to-market angle for specification influence. For Investors and Strategic Acquirers: Consolidation pressure builds where BIS retesting queues strand sub-scale Morbi units without laboratory access. Five-to-ten year viability favors integrated manufacturers with captive mineral supply and multi-state dealer networks. Acquisition target archetype: regional fabricators with established contractor relationships and pending certification pipelines. Watch BIS amendment schedules as inflection signal for compliance-driven market share redistribution.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Testing Infrastructure Investment | Gujarat-based laboratories accelerate BIS amendment adaptation ahead of Morbi competitors. |
| Dealer Network Expansion into Tier-Three Cities | Uttar Pradesh and Madhya Pradesh penetration captures housing stock modernization demand. |
| Backward Integration into Rajasthan Feldspar | Upstream mineral control insulates vitrified margins from feedstock price volatility. |
| Green Building Code Compliance Repositioning | Maharashtra and Tamil Nadu low-VOC certification opens municipal tender access. |
| Subscription-Based Maintenance Service Launch | Seven-to-ten year hospital contracts concentrate vendor relationships with full-service providers. |
Research Methodology
Coverage spans Maharashtra, Gujarat, Karnataka, Tamil Nadu, and Delhi-NCR, with primary inputs from each region's manufacturing clusters and procurement channels. Triangulation combines interviews with tile plant managers, hospital facilities directors, dealer network heads, and municipal procurement officers alongside secondary validation through BIS certification records, state green building code amendments, and customs trade data for engineered timber imports. Bottom-up volume estimates from product category shipments reconcile with top-down construction spend allocations.
Rate-of-change decomposition separates volume drivers from price-mix effects across the projection horizon. Segmentation dimensions modeled include product type, application end-use, material composition, and installation method complexity. CAGRs derive from historical trajectory analysis adjusted for regulatory inflection points and infrastructure investment pipelines. Forecast inputs incorporate Morbi cluster capacity utilization trends and state-level municipal corporation tender norm evolution.
Caveats apply where BIS amendment acceleration or Plastic Waste Management Rules enforcement could materially shift the outlook. Forecasts reflect assumptions around mineral feedstock price stability and power supply continuity in Gujarat. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flooring, Carpets, and Rugs
Wood Plastic Composite (WPC) Floorings Market
Flooring, Carpets, and Rugs
Laminate Flooring Market
Flooring, Carpets, and Rugs
Textured Variegates Market
Flooring, Carpets, and Rugs
Germany Flooring Market
Flooring, Carpets, and Rugs
China Non-Resilient Floor Covering Market
Flooring, Carpets, and Rugs
Wood Flooring Market
Flooring, Carpets, and Rugs
Luxury Vinyl Plank (LVP) Market
Flooring, Carpets, and Rugs
Hard Surface Flooring Market
Flooring, Carpets, and Rugs
Rugs Market
Flooring, Carpets, and Rugs
Carpet Floor Mats Market
Flooring, Carpets, and Rugs
Canada Terrazzo Flooring Market
Flooring, Carpets, and Rugs
India Laminate Flooring Market
Flooring, Carpets, and Rugs
Entrance Matting Market
Flooring, Carpets, and Rugs
Rigid Core Flooring Market
Flooring, Carpets, and Rugs
Fiberglass Flooring Market
Flooring, Carpets, and Rugs
Flooring for Tile and Stone Market