
 Sickle Bar Mower Market | 2026-2036
Sickle Bar Mower Market Size, Share, and Industry Trends Forecast 2026-2036
Sickle Bar Mower Market Insights
Modular attachment systems that pair sickle bars with quick-connect three-point hitch frames are recalibrating how mixed-operation farms configure their equipment fleets. John Deere leverages its dealer network density to sustain parts availability in remote agricultural counties. Farm King anchors its position through price-competitive compact models tailored to hobby farms and estate properties. Enorossi differentiates via European-centric haymaking specialization with emphasis on olive grove and vineyard compatibility.
A sickle bar mower employs a reciprocating blade assembly mounted on a cutter bar, typically spanning 1.5 to 2.5 meters, where triangular knife sections oscillate against stationary guard fingers to sever grass, hay, or light brush at controlled stubble heights. The mechanism suits uneven terrain and delicate crops where rotary cutters would pulverize material or scalp the ground. PTO-driven units dominate commercial hay operations for their reliable power transfer from tractor flywheels, while hydraulic systems gain traction among landscaping contractors seeking independent operation without dedicated tractor pairing. Compact mowers occupy the fastest-expanding margin pool as small-acreage producers and municipal parks departments prioritize maneuverability over throughput.
Farm equipment safety standards enforced by OSHA and the EU Machinery Directive shape blade guard specifications and emergency stop requirements, compelling manufacturers to redesign cutter bar shields and operator presence systems. EPA Tier 4 emissions rules indirectly influence demand by extending tractor replacement intervals, which in turn delays attached implement purchases. Stakeholders must monitor how electrification of compact utility tractors reshapes power take-off compatibility standards and whether battery-electric platforms can deliver the sustained torque that reciprocating knife mechanisms require for clean cutting through dense alfalfa stands.
Market Dynamics
Hydraulic actuator efficiency gains and revised EU Machinery Directive safety guard mandates are compressing equipment refresh cycles while recalibrating procurement priorities among pasture-rich agricultural corridors.
Growth Catalysts
- Precision Guidance Integration:Compact mower configurations bundled with GPS-assisted steering systems are pulling demand from small-scale hay producers seeking reduced operator fatigue and consistent cutting paths.
- OSHA Safety Compliance:Blade guard redesigns and emergency stop requirements under US workplace safety rules are compelling fleet upgrades among commercial hay contractors.
- Organic Dairy Expansion:Cooperatives in Wisconsin and Bavaria are replacing aging rotary equipment with sickle bar units to preserve forage quality for premium milk certification.
Market Restraints
- Steel Input Volatility:Cutter bar and guard finger fabrication depends on specialized alloy steel grades whose price swings compress manufacturer margins unpredictably.
- PTO Standard Fragmentation:Inconsistent power take-off specifications between compact utility tractor brands create compatibility friction and inventory complexity for implement dealers.
- Rotary Mower Substitution:Drum and disc mowers deliver higher throughput per hour, limiting sickle bar penetration among large-acreage operators prioritizing speed over terrain adaptability.
Strategic Opportunities
- Municipal Parks Channel:Landscaping contractors seeking tractor-independent operation represent an underdeveloped segment for hydraulic-powered walk-behind and self-propelled configurations.
- Battery-Electric Convergence:Electrification of compact utility tractors creates white space for redesigned cutter bar drives compatible with sustained torque delivery from battery platforms.
- Olive Grove Specialization:Narrow-profile sickle bars engineered for vineyard and tree-crop row spacing command premium positioning in Mediterranean and Californian specialty agriculture.
Industry Challenges
- Reciprocating Mechanism Servicing:Knife section sharpening and guard finger replacement demand specialized skills scarce among younger equipment technicians, elevating dealer service dependency.
- Legacy PTO Integration:Retrofitting modern cutter bar electronics with decades-old tractor flywheel interfaces creates warranty exposure and field failure risk.
- EPA Tier 4 Compliance Lag:Extended tractor replacement intervals under emissions rules delay attached implement purchases, elongating sales cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sickle Bar Mower Market |
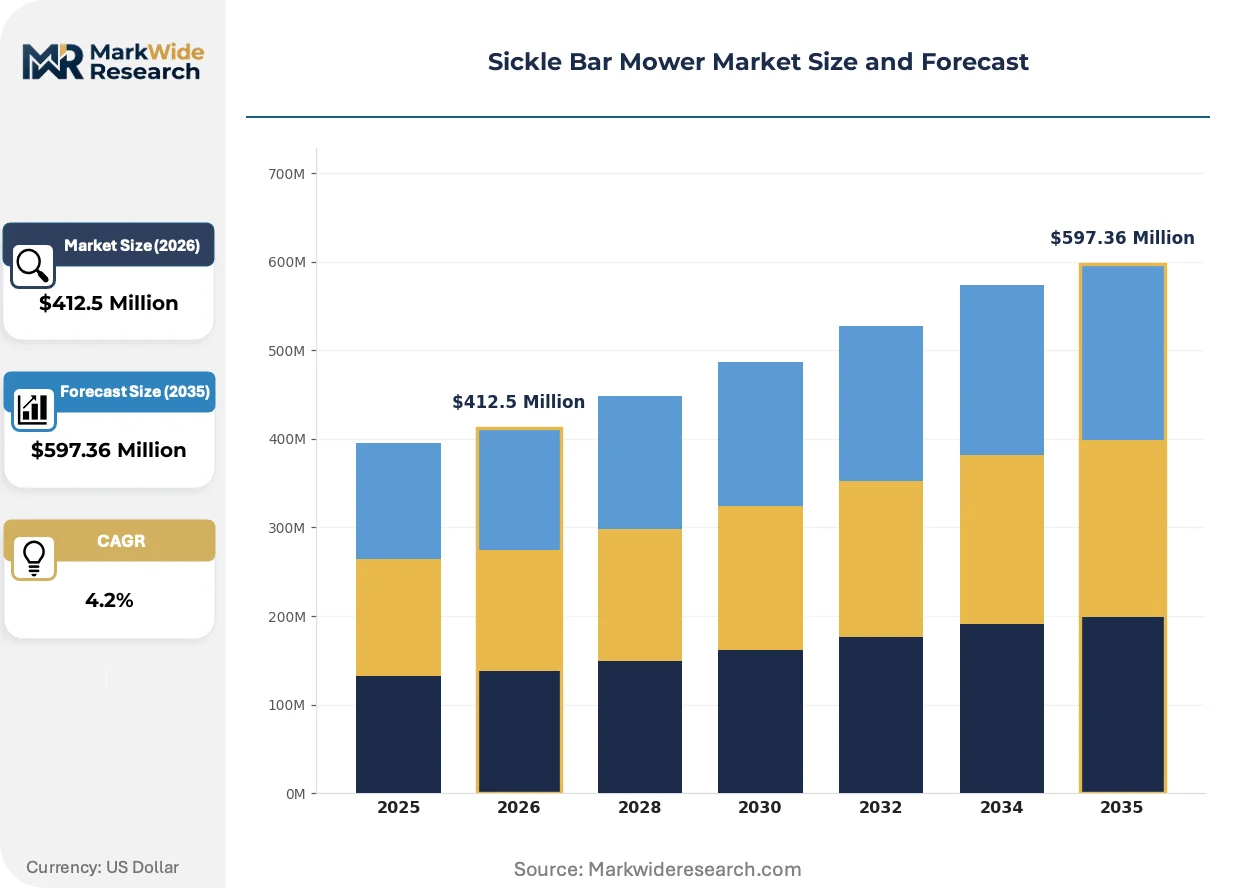
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $597.36 Million |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Mowers, Compact Mowers, Specialty Mowers, Industrial Mowers Application: Agricultural Use, Landscaping, Municipal Services, Grounds Maintenance End User: Farmers, Landscapers, Government Agencies, Contractors Technology: Manual, Hydraulic, Electric, PTO |
| Companies Covered | John Deere, New Holland, Rowse, Frontier, I & J Manufacturing, Farm King, Enorossi, Farm Maxx, Massey Ferguson, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sickle Bar Mower Market Trends and Innovations
Equipment architecture is fragmenting into interoperable subsystems as manufacturers race to accommodate electrified powertrains and precision agriculture data requirements.
Quick-connect three-point hitch frames with standardized hydraulic couplings are modularizing how mixed-operation farms configure seasonal equipment fleets. Small-acreage producers in the American Midwest and estate property managers in southern Germany are adopting these configurations fastest. This shift is compressing capital deployment into discrete seasonal purchases rather than dedicated mower ownership.
The EU Machinery Directive's revised safety guard specifications and OSHA blade shield mandates are forcing cutter bar enclosure redesigns across European and North American supply chains. Manufacturers must integrate interlocked operator presence systems and improved debris deflection geometry. Commercial hay contractors face the steepest compliance costs, while hobby farm segments delay purchases pending certified model availability.
Service unbundling is disrupting traditional dealer bundled maintenance contracts. Independent mobile technicians equipped with OEM diagnostic tools are capturing aftermarket revenue in Wisconsin dairy corridors and Bavarian cooperative networks. This pattern is most visible where farm equipment density supports technician route efficiency and where seasonal downtime costs exceed dealer transport premiums.
Sickle Bar Mower Market Segmentation
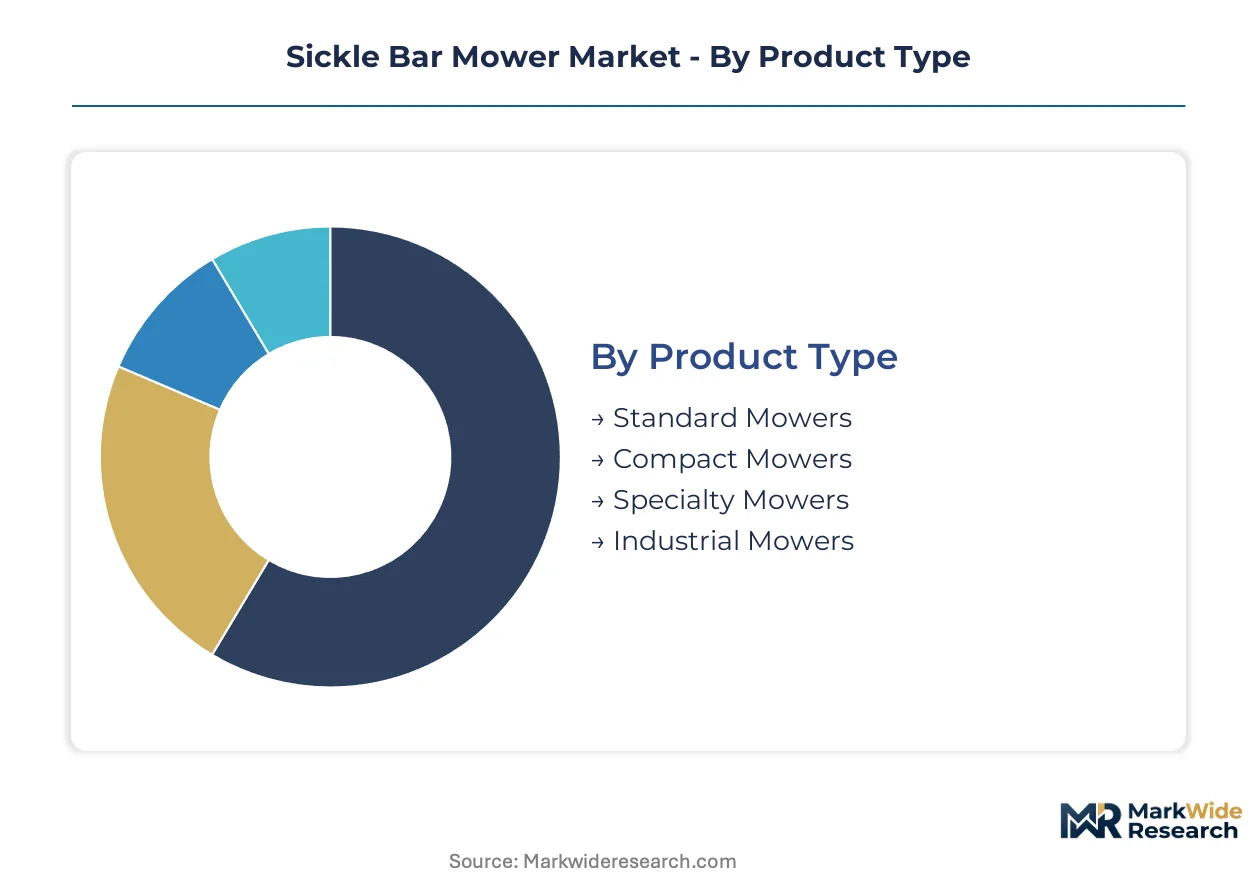
Sickle bar mower procurement patterns diverge sharply across operational scales and power interfaces. Equipment specifications must align with tractor fleets, terrain constraints, and seasonal duty cycles that vary by end-use intensity.
Product Type:
Supply concentration tilts toward compact configurations as manufacturers redirect fabrication capacity from legacy platforms.
- Standard Mowers:Cutter bars spanning 1.8 to 2.5 meters dominate commercial hay operations in Wisconsin and Bavaria. Dairy cooperatives prioritize these units for consistent stubble height control required by organic certification protocols.
- Compact Mowers:Sub-1.5-meter configurations integrate with quick-connect three-point hitch frames for mixed-operation farms. Hobby producers and estate managers in southern Germany adopt these fastest for maneuverability in confined paddocks.
- Specialty Mowers:Narrow-profile designs engineered for vineyard row spacing command premium positioning in Mediterranean specialty agriculture.
- Industrial Mowers:Heavy-duty cutter bars withstand continuous operation in municipal corridor maintenance and roadside vegetation management.
Today's leader: Standard Mowers. Tomorrow's challenger: Compact Mowers.
Application:
Cost tier stratification separates premium precision-guided units from price-competitive fleet configurations.
- Agricultural Use:Alfalfa and grass hay production drives specification requirements for clean cutting through dense stands without pulverization. PTO-driven units dominate this segment for reliable power transfer from tractor flywheels.
- Landscaping:Hydraulic-powered walk-behind configurations gain traction among contractors seeking tractor-independent operation for estate properties and commercial grounds.
- Municipal Services:Parks departments prioritize maneuverability over throughput for median and berm maintenance in urban corridors.
- Grounds Maintenance:Educational campuses and healthcare facilities specify low-noise electric alternatives for noise-restricted operating windows.
Agricultural Use commands current volume. Landscaping holds the steepest expansion trajectory as hydraulic autonomy reduces tractor dependency.
End User:
Customer type determines warranty exposure and service bundling preferences across the aftermarket.
- Farmers:Small-scale hay producers in the American Midwest refresh equipment on extended intervals tied to tractor replacement cycles under EPA Tier 4 emissions compliance.
- Landscapers:Seasonal cash flow patterns compress capital deployment into discrete rental or lease arrangements rather than dedicated ownership.
- Government Agencies:Municipal procurement runs through formal bidding processes with multi-year fleet standardization mandates.
- Contractors:Commercial hay operators face steepest OSHA blade guard compliance costs, accelerating refresh cycles for certified model availability.
Current procurement concentration: Farmers. Emerging volume shift: Contractors responding to safety mandate deadlines.
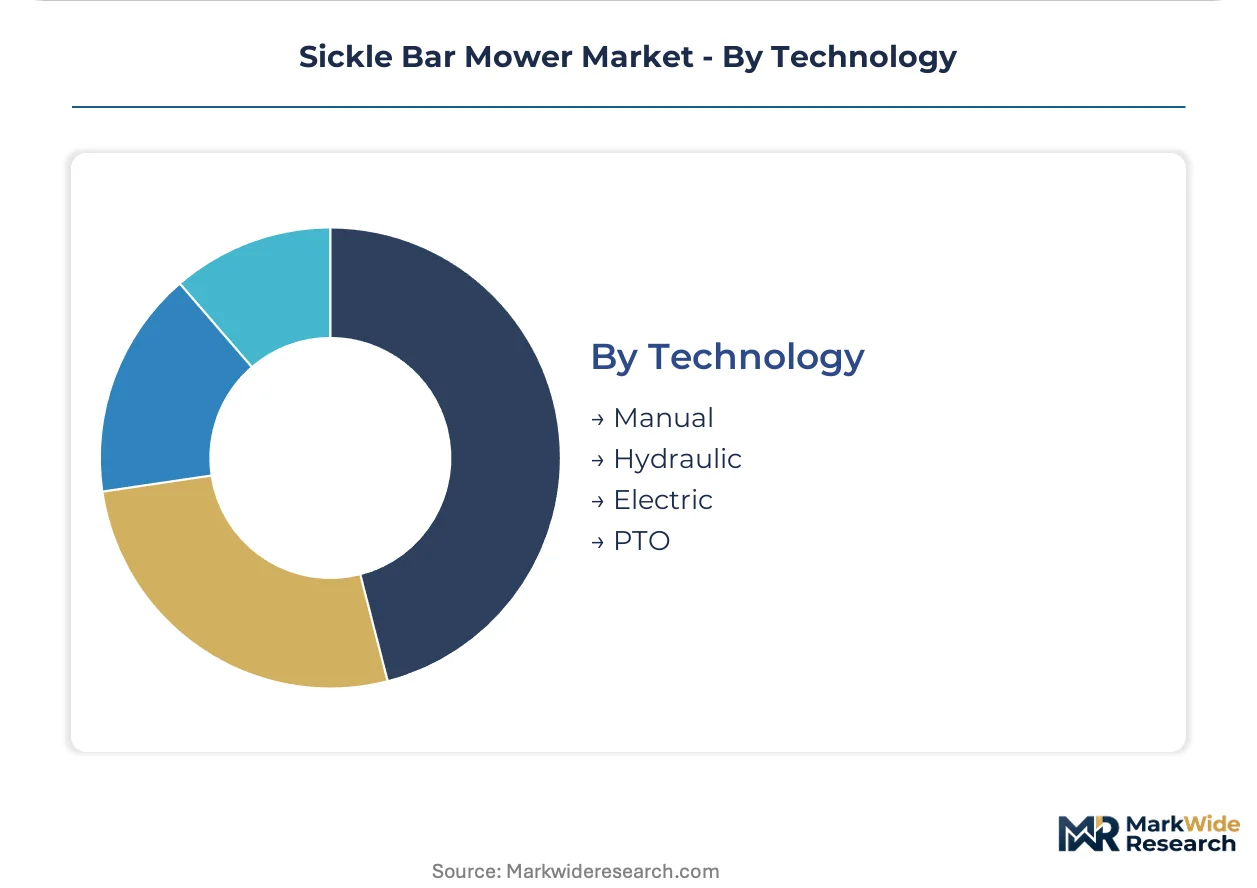
Technology:
Power interface maturity varies across electrification readiness and legacy tractor fleet compatibility.
- Manual:Walk-behind push configurations persist in ultra-small-acreage operations and developing markets with limited tractor penetration.
- Hydraulic:Independent power systems enable operation without dedicated tractor pairing, expanding addressable market for landscaping contractors and municipal fleets.
- Electric:Battery-electric platforms create white space for redesigned cutter bar drives, though sustained torque delivery for dense alfalfa stands remains unproven at commercial scale.
- PTO:Power take-off from tractor flywheels maintains dominance in commercial hay operations for reliable reciprocating knife mechanism performance.
Established standard: PTO. Technology transition pressure point: Electric as compact utility tractor electrification reshapes compatibility requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The sickle bar mower industry traces its commercial origins to European haymaking traditions, with mechanization scaling first across the grassland belts of Germany and France before diffusing into North American dairy corridors during the mid-twentieth century.
United States
Wisconsin dairy cooperatives drive organic forage equipment procurement as premium milk certification protocols demand clean stubble height control. OSHA blade guard mandates and emergency stop requirements compel fleet upgrades among commercial hay contractors. The American Midwest pasture corridor concentrates demand, with small-scale producers refreshing equipment on tractor replacement cycles tied to EPA Tier 4 emissions compliance.
Germany
Bavarian organic dairy networks anchor European demand for precision-guided compact configurations that navigate confined paddocks. The EU Machinery Directive's revised safety guard specifications force cutter bar enclosure redesigns across domestic supply chains. Southern Germany's grassland belts exhibit fastest adoption of quick-connect three-point hitch frames for mixed-operation seasonal fleet configuration.
France
Specialized hay production in Normandy and Brittany sustains demand for standard-width cutter bars serving export-oriented dairy operations. REACH compliance obligations shape alloy steel sourcing for guard finger fabrication. The Massif Central region's rugged terrain favors sickle bar adaptability where rotary cutters risk ground scalping on uneven pastures.
Italy
Mediterranean olive grove and vineyard compatibility requirements create premium positioning for narrow-profile specialty mowers. CE marking obligations under the EU Machinery Directive constrain small-fabricator market access. Emilia-Romagna's agricultural machinery cluster concentrates engineering expertise for tree-crop row spacing adaptations.
Canada
Prairie province hay exporters specify PTO-driven units for reliable power transfer through dense alfalfa stands during compressed harvest windows. Health Canada's machinery safety standards parallel OSHA requirements, easing cross-border equipment certification. Ontario's dairy heartland mirrors Wisconsin procurement patterns for organic forage quality preservation.
Sickle Bar Mower Market Competitive Landscape
The competitive structure tilts toward diversified agricultural equipment conglomerates with established dealer networks and captive parts distribution. Three strategic archetypes dominate: full-line manufacturers leveraging integrated tractor-implement compatibility, regional specialists optimizing for terrain-specific crop systems, and compact equipment pure-plays targeting hobby farm price sensitivity. Consolidation pressure operates through dealership network density expansion and seasonal fleet rental service bundling rather than horizontal merger activity.
Among North American full-line manufacturers, John Deere anchors premium-tier positioning through dealer network density in remote agricultural counties, while Farm King occupies the compact equipment archetype with price-competitive configurations for estate properties. Enorossi represents European-centric specialization, with Italian engineering heritage signaling olive grove and vineyard compatibility expertise.
| Leading Market Players |
|---|
| John Deere |
| New Holland |
| Rowse |
| Frontier |
| I & J Manufacturing |
| Farm King |
| Enorossi |
| Farm Maxx |
| Massey Ferguson |
| Others |
Pricing and Supply Chain Analysis
Commercial hay contractors concentrated in Wisconsin and Bavaria operate on equipment refresh cycles that compress pricing power into seasonal procurement windows, forcing manufacturers toward three-tier pricing structures that separate precision-guided premium configurations from standard PTO-driven units and compact economy models.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates sickle bar mower procurement, with John Deere and Enorossi commanding brand premiums for dealer network density and European specialization respectively. Price differentiation hinges on certification tier—OSHA-compliant blade guard systems and EU Machinery Directive CE marking—and after-sales service bundling. Cost compression in economy tiers is intensifying because Farm King and compact equipment pure-plays compete on bare-unit pricing for hobby farm segments. Municipal parks departments exhibit highest price sensitivity due to formal bidding processes, while organic dairy cooperatives prioritize stubble height precision over unit cost.
Supply Chain Analysis
Refurbishment flows for cutter bar assemblies and knife sections create secondary parts markets that extend equipment lifecycles and dampen new-unit demand in saturated dairy corridors. Manufacturing concentrates in Germany, Italy, and the American Midwest, with Emilia-Romagna's agricultural machinery cluster anchoring European specialty mower engineering. Raw material dependencies center on specialized alloy steel grades for guard finger fabrication and hydraulic actuator components. Single-source vulnerability in precision-machined cutter bar alloys elevates warranty exposure when field failures occur. Distribution runs through captive dealer networks for full-line manufacturers and independent implement dealers for compact specialists.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in sickle bar mowers rests on hydraulic actuator efficiency gains and the premium-tier shift toward precision-guided compact configurations that command positioning above commodity PTO-driven units.
For Market Incumbents: Lock in dealer network density through exclusive territory arrangements and captive parts distribution that raise switching costs for commercial hay contractors facing OSHA compliance deadlines. Deepen backward integration into cutter bar alloy steel sourcing to buffer margin compression from commodity price swings. Defend against hydraulic walk-behind entrants by bundling seasonal fleet rental services that reduce capital deployment friction for municipal parks departments. For New Entrants and Emerging Players: The mid-tier price gap between John Deere premium positioning and Farm King economy models creates entry space for precision-guided compact configurations targeting small-scale hay producers in the American Midwest. Municipal landscaping contractors seeking tractor-independent operation represent the most penetrable segment. Pursue quick-connect three-point hitch compatibility certification to bypass PTO standard fragmentation friction. For Investors and Strategic Acquirers: Full-line agricultural equipment conglomerates are the most active acquirer in this space, seeking compact equipment pure-plays to fill portfolio gaps in hobby farm price tiers. Long-term viability favors targets with olive grove and vineyard specialization expertise that commands Mediterranean premium positioning. Monitor EPA Tier 4 emissions compliance lag effects on tractor replacement intervals as an inflection indicator for attached implement purchase velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Guidance Integration | GPS-assisted steering systems pull demand from Wisconsin organic dairy cooperatives seeking consistent cutting paths. |
| Hydraulic System Expansion | Tractor-independent operation opens municipal parks and landscaping contractor channels beyond traditional agricultural users. |
| Backward Integration into Alloy Sourcing | Captive supply of specialized cutter bar steel buffers margin compression from commodity price volatility. |
| Service Unbundling | Independent mobile technicians with OEM diagnostic tools capture aftermarket revenue in Bavarian cooperative networks. |
| Battery-Electric Platform Development | Redesigned cutter bar drives compatible with compact utility tractor electrification create white space for sustained torque delivery. |
Research Methodology
Bottom-up agricultural end-use modeling reconciled against top-down implement manufacturer supply-side tracking forms the analytical core of this study. Primary interviews with commercial hay contractors, municipal parks procurement officers, dealer network managers, and aftermarket service technicians were validated against secondary sources including OSHA enforcement databases, EU Machinery Directive compliance registries, and EPA Tier 4 emissions certification filings. Trade flow analysis of alloy steel inputs and customs records for cutter bar assemblies provided cross-verification of production concentration assumptions.
Input-output matrices map tractor fleet replacement cycles to attached implement demand across product type, power interface technology, and regional regulatory clusters. Segmentation dimensions modeled include mower configuration scale, end-use intensity, and customer type warranty exposure. CAGRs were derived from equipment refresh cycle compression rates and organic dairy cooperative expansion patterns. Forecast inputs incorporate hydraulic actuator efficiency improvement curves and precision agriculture adoption diffusion rates in pasture-rich corridors.
Caveats apply where steel input volatility, PTO standard fragmentation, or rotary mower substitution acceleration could materially shift the outlook. Practitioners should monitor EPA Tier 4 compliance lag duration and battery-electric tractor platform torque specifications for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Machinery
Crawler Tractors Market
Agricultural Machinery
Agricultural Electric Tractor Market
Agricultural Machinery
Electric Farm Tractor Market
Agricultural Machinery
Agricultural Harvester Market
Agricultural Machinery
North America Agricultural Tractors Market
Agricultural Machinery
Cambodia Agricultural Machinery Market
Agricultural Machinery
Autonomous Agricultural Machinery Market
Agricultural Machinery
Garden and Orchard Tractors Market
Agricultural Machinery
Germany Agricultural Machinery Market
Agricultural Machinery
Cow Milking Machine Market
Agricultural Machinery
Garden Tractor Market
Agricultural Machinery
United Kingdom Agricultural Machinery Market
Agricultural Machinery
Brazil Agricultural Machinery Market
Agricultural Machinery
Agriculture Sprayers Market
Agricultural Machinery
South America Agricultural Sprayers Market
Agricultural Machinery
Australia Agricultural Machinery Market