
 Planting Equipment Market | 2026-2036
Planting Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Planting Equipment Market Analysis
Aftermarket service revenue for precision planting systems is fragmenting across dealer networks, independent technicians, and manufacturer-direct programs. Deere & Company leverages its integrated operations center to sustain recurring revenue from subscription-based planting prescriptions. AGCO Corporation anchors its aftermarket position through Fuse Connected Services, which monitors planter performance across mixed fleets. Kinze Manufacturing competes on retrofit compatibility, offering aftermarket row-unit upgrades that extend equipment life without full replacement.
Planting equipment comprises mechanized devices engineered to deposit seeds, seedlings, or bulbs at controlled depth, spacing, and population rates, with pneumatic metering systems achieving placement accuracy within two-centimeter tolerances at speeds exceeding fifteen kilometers per hour. The primary commercial purpose centers on optimizing germination uniformity and yield potential across row-crop agriculture. Planters equipped with hydraulic downforce systems command premium positioning, as real-time soil engagement compensates for field variability and protects margin pools on high-value seed corn. Pneumatic seeders represent the fastest-growing technology segment, displacing mechanical plate systems in mid-scale operations across Eastern Europe and the Black Sea region.
EPA Tier 4 Final emissions standards constrain engine specifications for self-propelled planters, while EU F-Gas Regulation phases out hydrofluorocarbon-based hydraulic systems in favor of sealed electro-hydraulic alternatives. USDA conservation compliance requirements tie planting equipment specifications to crop insurance eligibility, directly shaping farmer procurement decisions. Stakeholders must monitor evolving carbon intensity scoring frameworks, as equipment fuel efficiency and tillage integration become embedded in grain procurement contracts and farm sustainability certifications.
Market Dynamics
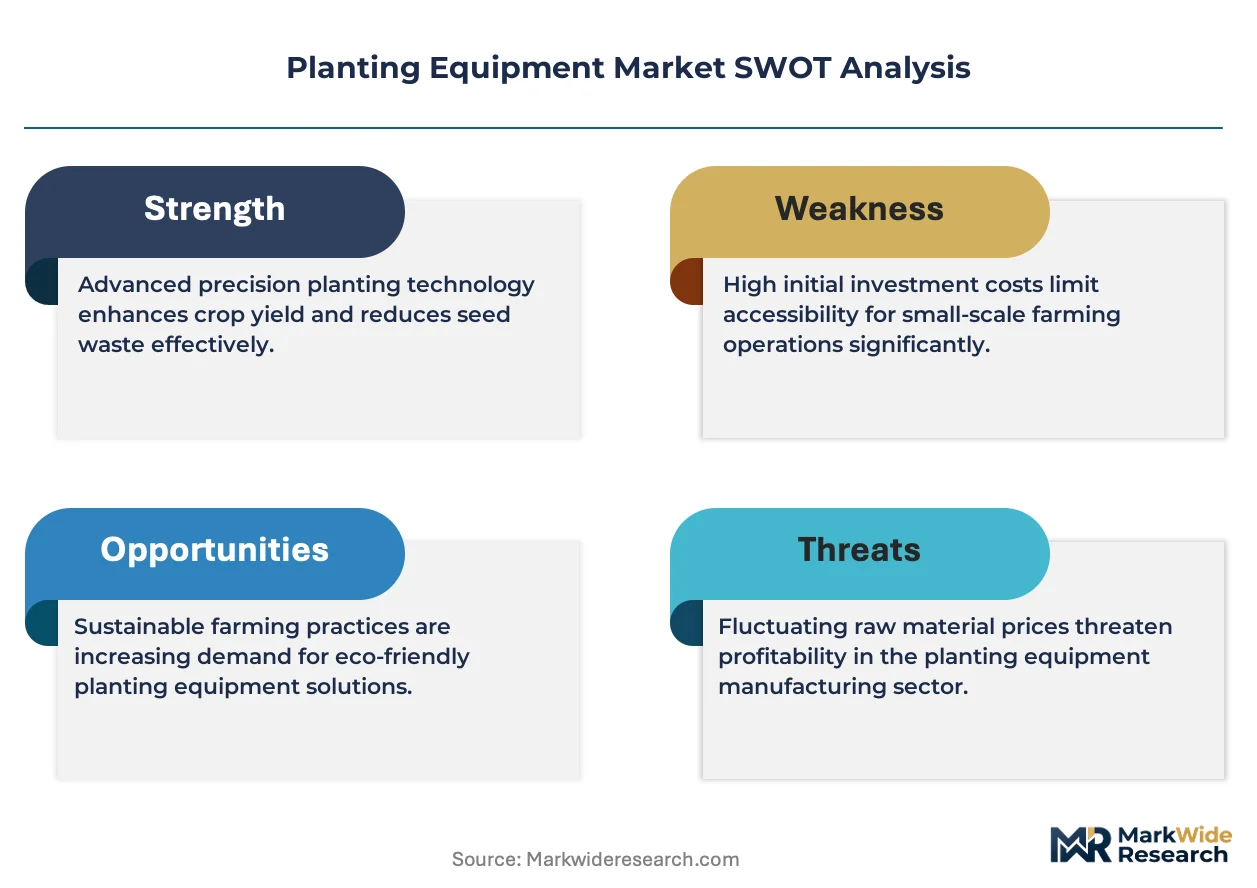
Precision pneumatic metering systems are compressing mechanical plate planter margins while hydraulic downforce technology captures premium positioning in high-value seed corn operations across the US Corn Belt and Ukraine's grain belt.
Growth Catalysts
- EPA Tier 4 Final emissions standards:These constraints are accelerating engine technology upgrades in self-propelled planter fleets, forcing equipment refreshes that favor compliant Tier 4 Final powertrains over legacy Tier 3 inventory.
- Ukraine's grain belt consolidation:Large-scale operations in Ukraine's grain belt are prioritizing throughput and seed placement accuracy, driving fleet standardization on pneumatic seeders capable of fifteen-kilometer-per-hour operation.
- USDA conservation compliance requirements:These rules tie planting equipment specifications directly to crop insurance eligibility, creating procurement mandates that shape farmer equipment decisions regardless of commodity price cycles.
Market Restraints
- Steel and aluminum input volatility:Planter frame and row-unit manufacturing faces margin compression from fluctuating base metal prices, particularly affecting mid-scale equipment producers without captive foundry operations.
- Hydraulic component supply concentration:Sealed electro-hydraulic downforce system production clusters in German and Italian component suppliers, creating bottleneck risk for premium planter assembly.
- Mechanical plate system entrenchment:Eastern European smallholders retain mechanical plate planters due to limited technical service infrastructure, slowing pneumatic seeder penetration in sub-thousand-hectare operations.
Strategic Opportunities
- Romania and Bulgaria smallholder upgrade cycles:EU Common Agricultural Policy machinery modernization grants are unlocking replacement demand among Black Sea region mid-scale grain producers currently operating pre-2015 mechanical equipment.
- Carbon intensity scoring frameworks:Emerging grain procurement contracts in the Netherlands and Denmark are embedding equipment fuel efficiency specifications, creating preference premiums for planters with integrated tillage reduction capabilities.
- Retrofit telemetry convergence:Aftermarket ISOBUS-compatible row-unit controllers are enabling mixed-fleet precision planting without full equipment replacement, opening service revenue streams for independent technician networks.
Industry Challenges
- Electro-hydraulic systems integration:Sealed hydraulic downforce technology requires diagnostic capabilities that dealer technician training programs have not uniformly deployed, creating service coverage gaps in rural territories.
- EU F-Gas Regulation compliance timeline:Phased hydrofluorocarbon phaseout deadlines are compressing hydraulic system redesign cycles, forcing concurrent engineering of sealed alternatives while maintaining existing planter production.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Planting Equipment Market |
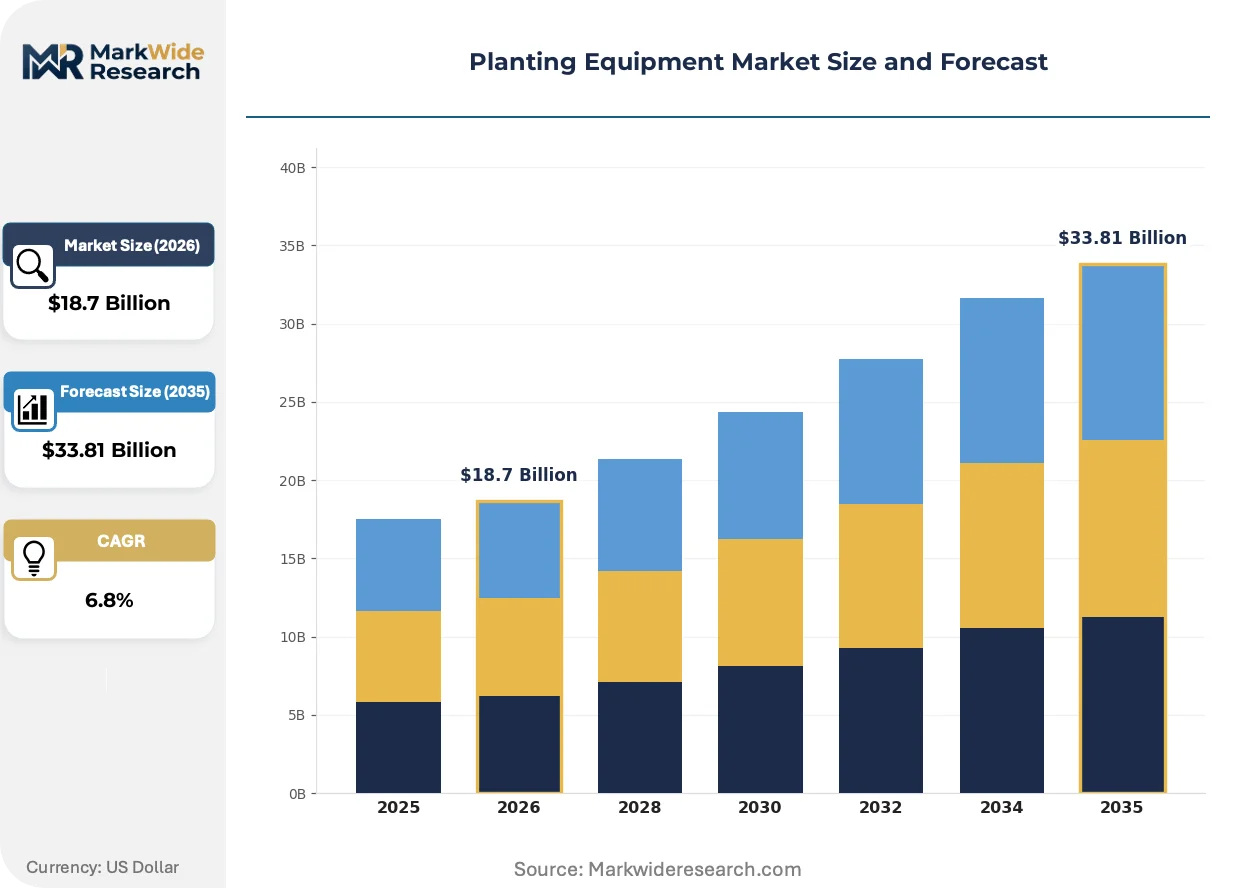
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Seeders, Planters, Transplanters, Drills Technology: Manual, Mechanical, Pneumatic, Hydraulic End User: Agricultural Producers, Commercial Growers, Home Gardeners, Research Institutions Distribution Channel: Online Retail, Agricultural Stores, Wholesale Distributors, Direct Sales |
| Companies Covered | Deere & Company, AGCO Corporation, CNH Industrial, Kubota Corporation, Kinze Manufacturing, CLAAS, Amazone, Mahindra & Mahindra, Buhler Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Planting Equipment Market Emerging Trajectories
Real-time soil sensing and prescription-based planting are virtualizing agronomic decision-making, compressing the traditional split between equipment manufacturers and agronomic service providers into integrated performance contracts.
Variable-rate seeding technology is virtualizing field-specific population management by embedding prescription maps directly into planter control systems. Commercial growers in Iowa and Illinois are adopting these systems at replacement-cycle pace, treating seeding prescriptions as operational inputs rather than capital equipment features. This virtualization is collapsing the distinction between equipment purchase and agronomic subscription, locking buyers into recurring data-service relationships.
EU F-Gas Regulation phaseout mandates are forcing hydraulic system architecture redesigns across European planter manufacturers. The prohibition on hydrofluorocarbon-based hydraulic fluids is accelerating sealed electro-hydraulic downforce development, with Italian and German component suppliers capturing incremental value from sealed-system intellectual property. Self-propelled planter assemblies destined for EU markets are absorbing the bulk of compliance engineering resources, diverting development bandwidth from mechanical simplicity improvements.
Aftermarket service unbundling is fragmenting precision planting support across competing channels. Dealer networks in Indiana and Ohio are losing exclusive service relationships as independent technicians gain ISOBUS diagnostic tool access, while manufacturer-direct subscription programs capture recurring prescription revenue. This channel disintermediation is most visible in the US Corn Belt, where large-scale operators with mixed fleets prioritize service flexibility over single-brand loyalty.
Planting Equipment Market Segmentation
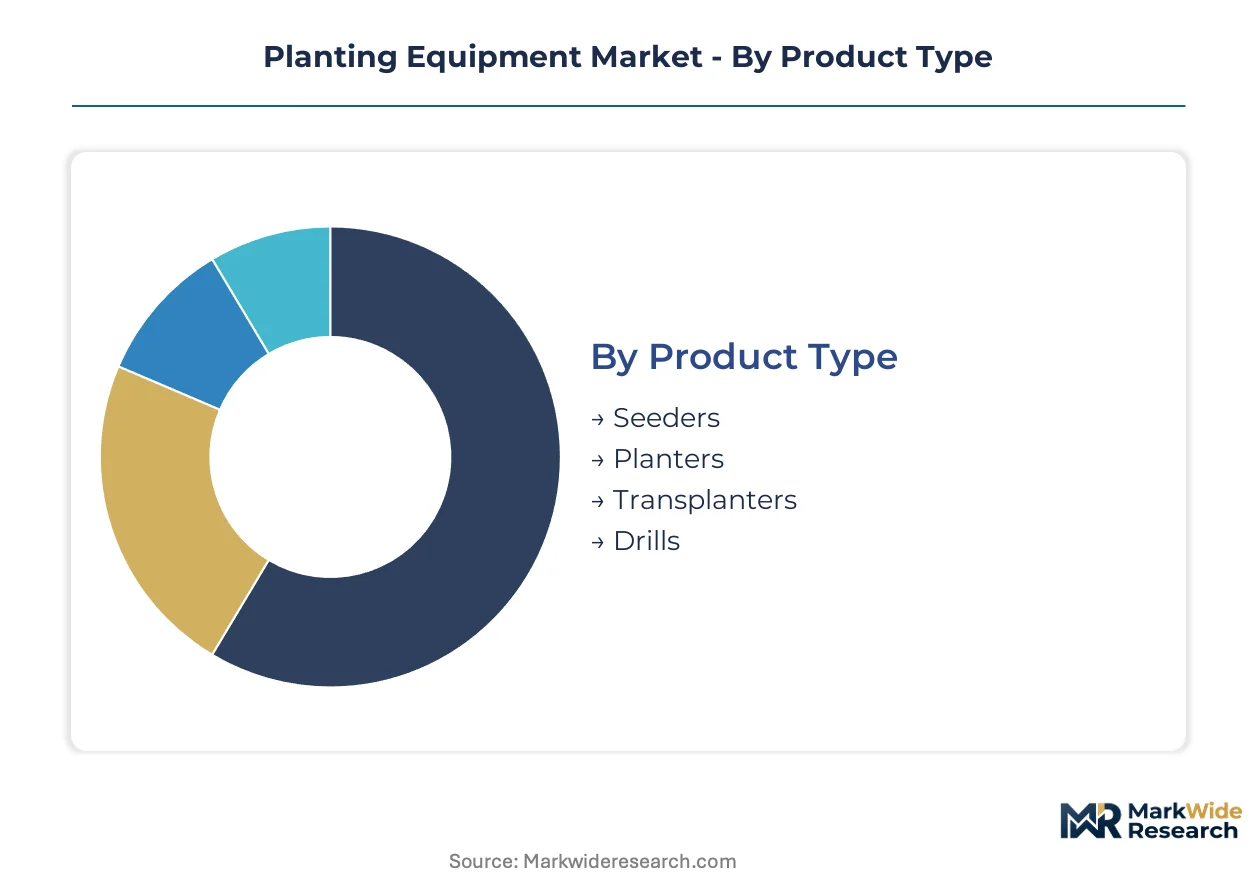
Planting equipment segmentation reveals how precision technology premiums concentrate in commercial row-crop operations while mechanical systems retain footholds in price-sensitive smallholder markets. Equipment specification tiers align directly with farm scale, cropping intensity, and regulatory compliance obligations across divergent agricultural economies.
Product Type:
Mature mechanical designs coexist with emerging precision platforms as commercial operators balance replacement economics against performance gains.
- Planters:Precision pneumatic row units with hydraulic downforce systems achieve two-centimeter placement accuracy at speeds exceeding fifteen kilometers per hour. Demand concentrates across Iowa and Illinois corn operations where seed corn margin protection justifies premium equipment expenditure.
- Seeders:Pneumatic metering systems are displacing mechanical plate configurations in mid-scale Eastern European grain operations. Ukraine's consolidating grain belt prioritizes throughput-capable pneumatic seeders for fifteen-kilometer-per-hour field speeds.
- Transplanters:Specialized vegetable and tobacco transplanting equipment serves high-value horticultural producers with limited geographic concentration.
- Drills:Small grain and cover crop seeding systems retain mechanical simplicity for broad-acre cereal operations in price-sensitive markets.
Planters retain volume leadership; seeders hold the steepest expansion curve.
Technology:
Cost tier stratification separates premium electro-hydraulic platforms from mechanical legacy systems as regulatory compliance accelerates technology turnover.
- Pneumatic:Vacuum and pressure-based seed metering achieves population accuracy within two-centimeter tolerances. Commercial growers across the US Corn Belt and Ukraine's grain belt standardize fleet procurement on pneumatic systems for high-value seed corn operations.
- Hydraulic:Real-time downforce modulation compensates for field variability through sealed electro-hydraulic architectures. EU F-Gas Regulation compliance requirements are forcing hydrofluorocarbon phaseout redesigns among German and Italian component suppliers.
- Mechanical:Plate and finger pickup systems retain installed base among Eastern European smallholders with limited technical service infrastructure.
- Manual:Hand-operated equipment serves home gardening and research plot applications with minimal commercial relevance.
Pneumatic systems command revenue leadership; hydraulic platforms are climbing the fastest on precision agriculture integration.
End User:
Customer type determines specification intensity as commercial operations absorb technology premiums unavailable to smaller-scale producers.
- Commercial Growers:Large-scale row-crop operations across Indiana and Ohio prioritize prescription-based planting with subscription telemetry services. USDA conservation compliance requirements tie equipment specifications directly to crop insurance eligibility, mandating precision-capable platforms regardless of commodity price cycles.
- Agricultural Producers:Mid-scale grain operations in Romania and Bulgaria access EU Common Agricultural Policy modernization grants for pre-2015 mechanical equipment replacement. Black Sea region upgrade cycles favor pneumatic seeder adoption over full precision planter platforms.
- Research Institutions:Plot-scale equipment with experimental flexibility serves breeding programs and agronomic trial networks.
- Home Gardeners:Consumer-grade seeders and manual transplanters address non-commercial vegetable production with minimal equipment investment.
Commercial growers retain volume leadership; agricultural producers hold the steepest expansion curve on EU subsidy-enabled upgrade cycles.
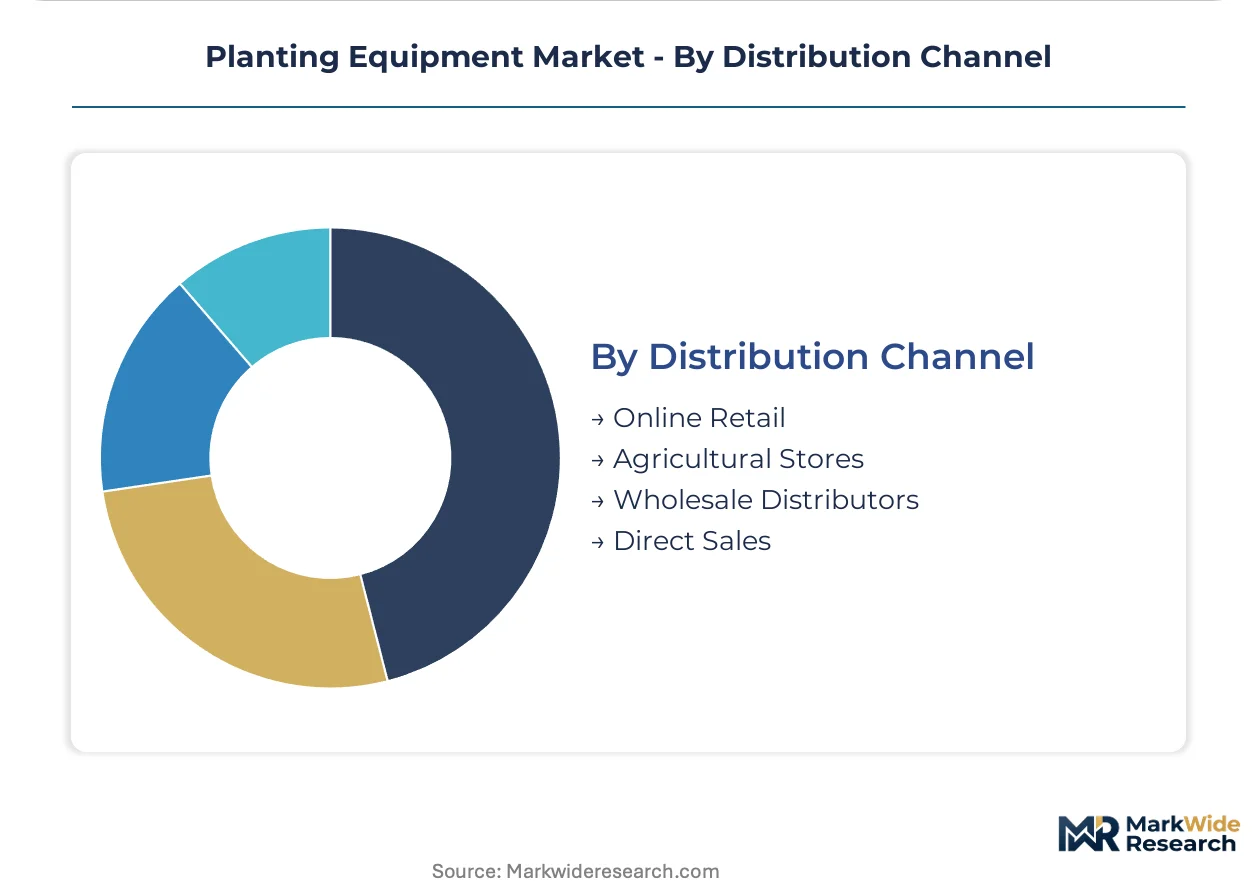
Distribution Channel:
Supply concentration shapes channel power as manufacturer-direct programs capture recurring service revenue from traditional dealer networks.
- Direct Sales:Manufacturer subscription programs capture recurring prescription revenue through integrated operations centers. Deere and AGCO deploy direct channels for precision planting telemetry and agronomic data services across mixed-fleet operators.
- Agricultural Stores:Dealer networks in Indiana and Ohio retain equipment placement relationships while losing exclusive service monopolies to independent technician ISOBUS diagnostic access.
- Wholesale Distributors:Regional equipment aggregators serve mid-scale producers with inventory financing and trade-in programs for mechanical-to-pneumatic upgrades.
- Online Retail:E-commerce channels address replacement parts and aftermarket row-unit controllers for mixed-fleet precision retrofit installations.
Direct sales retain revenue leadership; agricultural stores face the steepest channel compression from service unbundling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commercial growers in the United States deploy precision pneumatic planters for high-value seed corn operations, while Eastern European grain producers prioritize throughput-capable seeders over full precision platforms. This consumption-mix differential separates premium technology absorption in North American row-crop agriculture from mechanization upgrade cycles across EU accession states.
United States
Iowa and Illinois corn operations drive demand for hydraulic downforce planters capable of fifteen-kilometer-per-hour speeds. USDA conservation compliance requirements tie equipment specifications directly to crop insurance eligibility, mandating precision-capable platforms. The Corn Belt concentration anchors fleet standardization on subscription-based telemetry services.
Ukraine
Consolidating grain belt operations prioritize pneumatic seeder throughput over precision planting subscriptions. National agricultural modernization programs support fleet upgrades from mechanical plate systems. Black Sea region procurement concentrates on Odessa and Dnipro industrial zones for equipment distribution.
Germany
EU F-Gas Regulation compliance deadlines force sealed electro-hydraulic system redesigns among component suppliers. German engineering clusters in Baden-Württemberg and Bavaria capture value from sealed-system intellectual property. Stuttgart-area manufacturers absorb the bulk of hydraulic architecture engineering resources.
Romania
EU Common Agricultural Policy machinery modernization grants unlock replacement demand among mid-scale grain producers. Sub-thousand-hectare operations transition from pre-2015 mechanical equipment to pneumatic seeders. Bucharest-Ploiești distribution corridors serve Black Sea region upgrade cycles.
India
Maharashtra and Gujarat agricultural mechanization programs support smallholder planter adoption for cotton and soybean operations. Bureau of Indian Standards certification requirements shape equipment import specifications. Pune-Nashik manufacturing clusters produce domestically assembled pneumatic metering systems.
Planting Equipment Market Vendor Landscape
Capability concentration sits with integrated technology providers; scale advantage sits with diversified agricultural equipment conglomerates. The vendor base stratifies across three tiers: precision telemetry specialists commanding recurring service revenue, diversified manufacturers leveraging distribution density, and regional fabricators competing on retrofit compatibility. Consolidation pressure favors M&A activity among mid-scale pneumatic system engineers, while strategic partnerships between component suppliers and planter assemblers accelerate sealed electro-hydraulic development cycles.
Among North American integrated equipment providers, Deere & Company and Kinze Manufacturing exemplify divergent competitive positioning. Deere anchors the telemetry-integrated tier through subscription-based agronomic services. Kinze occupies the retrofit-specialist position, extending equipment life through aftermarket row-unit upgrades without requiring full fleet replacement. AGCO Corporation represents the diversified multinational archetype, monitoring mixed-fleet performance through connected service platforms.
| Leading Market Players |
|---|
| Deere & Company |
| AGCO Corporation |
| CNH Industrial |
| Kubota Corporation |
| Kinze Manufacturing |
| CLAAS |
| Amazone |
| Mahindra & Mahindra |
| Buhler Industries |
| Others |
Supply Flow & Price Mechanics
Steel and aluminum input volatility compresses planter frame manufacturing margins while simultaneously widening price spreads between premium hydraulic downforce systems and mechanical legacy platforms across Eastern European and North American procurement channels.
Pricing Analysis
Long-term equipment financing contracts dominate commercial grower procurement across Iowa and Illinois corn operations, embedding subscription-based telemetry services into capital expenditure structures. Price differentiation separates hydraulic downforce planters with real-time soil engagement from pneumatic seeders without active compensation systems, with premium tiers commanding positioning based on seed corn margin protection capabilities. Cost compression in mid-scale mechanical segments is intensifying because Romanian and Bulgarian producers access EU Common Agricultural Policy grants that cap out-of-pocket equipment expenditure. Smallholder operations across India's Maharashtra cotton belt exhibit highest price sensitivity, while US Corn Belt commercial growers prioritize performance specifications over capital cost minimization.
Supply Chain Analysis
Export-control restrictions on precision navigation and sensor technologies limit component flows from US and German engineering clusters to certain end markets, constraining telemetry-integrated planter assembly for specific regional destinations. Manufacturing concentration centers on Germany, Italy, and the United States for sealed electro-hydraulic downforce systems, while steel frame fabrication draws from Chinese and Turkish metalworking capacity. Supply chain risk rests on single-source vulnerability for proprietary pneumatic metering intellectual property held by select component suppliers in Baden-Württemberg. Distribution runs through manufacturer-direct subscription programs capturing recurring agronomic service revenue alongside traditional agricultural equipment dealer networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ISOBUS interoperability standardization is collapsing equipment-brand silos into platform-based ecosystem competition where telemetry data portability determines buyer switching costs and supplier lock-in intensity.
For Market Incumbents: Insulate subscription revenue streams by deepening captive control over prescription algorithm development and cloud-based agronomic analytics infrastructure. Defensive consolidation of independent telemetry providers prevents emerging competitors from assembling comparable data-network scale. Priority investment in sealed electro-hydraulic system diagnostic training programs closes service coverage gaps that independent technician networks currently exploit.
For New Entrants and Emerging Players: Ukraine's consolidating grain belt offers accessible white-space for pneumatic seeder platforms without full precision telemetry integration, serving large-scale operators prioritizing throughput over subscription services. Romania and Bulgaria mid-scale upgrade cycles present secondary entry path through EU grant-enabled mechanical-to-pneumatic conversion demand. Go-to-market execution through regional wholesale distributors with inventory financing capabilities bypasses entrenched dealer network relationships.
For Investors and Strategic Acquirers: The market sits at a technology-substitution phase that favors precision telemetry specialists with recurring revenue visibility over capital-equipment manufacturers dependent on replacement-cycle timing. Long-term viability across the projection horizon rests on data-platform economics rather than hardware shipment volumes. Acquisition target archetype: ISOBUS-compatible aftermarket controller developers with established independent technician channel relationships. Signal to monitor: carbon intensity scoring framework adoption rates in Netherlands and Danish grain procurement contracts as indicator of fuel-efficiency specification premium expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Sealed Electro-Hydraulic System Development | EU F-Gas Regulation compliance deadlines force hydraulic architecture redesigns among German and Italian component suppliers. |
| ISOBUS Retrofit Controller Launch | Aftermarket telemetry convergence enables mixed-fleet precision planting without full equipment replacement across Indiana and Ohio. |
| Subscription Agronomy Platform Expansion | Prescription-based planting virtualization locks commercial growers into recurring data-service relationships beyond hardware transactions. |
| Regional Distribution Partnership | Bucharest-Ploiești corridor access captures EU Common Agricultural Policy machinery modernization grant flows in Romania. |
| Diagnostic Technician Certification Program | Dealer training deployment closes service coverage gaps for sealed hydraulic downforce systems in rural US Corn Belt territories. |
Methodological Framework
Initial hypotheses were tested against primary input from planter fleet managers at large-scale row-crop operations, aftermarket service technicians, agricultural equipment dealer principals, and precision agriculture subscription program directors, then refined through secondary validation against USDA conservation compliance documentation, EPA Tier 4 Final emissions filings, EU F-Gas Regulation implementation guidance, and customs trade data on steel and aluminum inputs. Bottom-up equipment shipment estimates triangulated against top-down agricultural machinery expenditure surveys.
Demand-supply-balance framing anchored the analytical framework across the analysis window, modeling segmentation dimensions spanning product type tiers, technology platforms, end-user scale categories, and distribution channel structures. CAGRs were derived from replacement-cycle timing analysis, subsidy program enrollment trajectories, and regulatory compliance deadline clustering. Industry-specific forecast inputs incorporated EPA emissions standard phaseout schedules and EU Common Agricultural Policy machinery grant allocation patterns.
The forecast holds incumbent behavior within observed patterns; aggressive moves by precision-telemetry pure-plays or hyperscaler-backed agricultural data platforms would shift outcomes beyond modeled ranges. Material shifts in carbon intensity scoring framework adoption rates or hydrofluorocarbon phaseout acceleration timelines would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Equipment & Machinery
Seed Drill and Broadcast Seeder Machinery Market
Agricultural Equipment & Machinery
Global Agriculture and Farm Equipment Market
Agricultural Equipment & Machinery
Africa Agricultural Machinery Market
Agricultural Equipment & Machinery
Seed Drill Machines Market
Agricultural Equipment & Machinery
Grain Silos and Ancillary Equipment Market
Agricultural Equipment & Machinery
Global Agricultural Equipment Market
Agricultural Equipment & Machinery
Lawn and Garden Equipment Market
Agricultural Equipment & Machinery
India Combine Harvester Market
Agricultural Equipment & Machinery
Planting and Fertilizing Machinery Market
Agricultural Equipment & Machinery
Asia-Pacific Haying and Forage Machinery Market
Agricultural Equipment & Machinery
Hammer Mill Market
Agricultural Equipment & Machinery
Beekeeping Equipment Market
Agricultural Equipment & Machinery
Agriculture Equipment Market
Agricultural Equipment & Machinery
Asia-Pacific Agricultural Sprayer Market
Agricultural Equipment & Machinery
Europe Haying and Forage Machinery Market
Agricultural Equipment & Machinery
South Africa Agricultural Machinery Market