
 Africa Agricultural Machinery Market | 2026-2036
Africa Agricultural Machinery Market Size, Share, and Industry Trends Forecast 2026-2036
Africa Agricultural Machinery Market Outlook
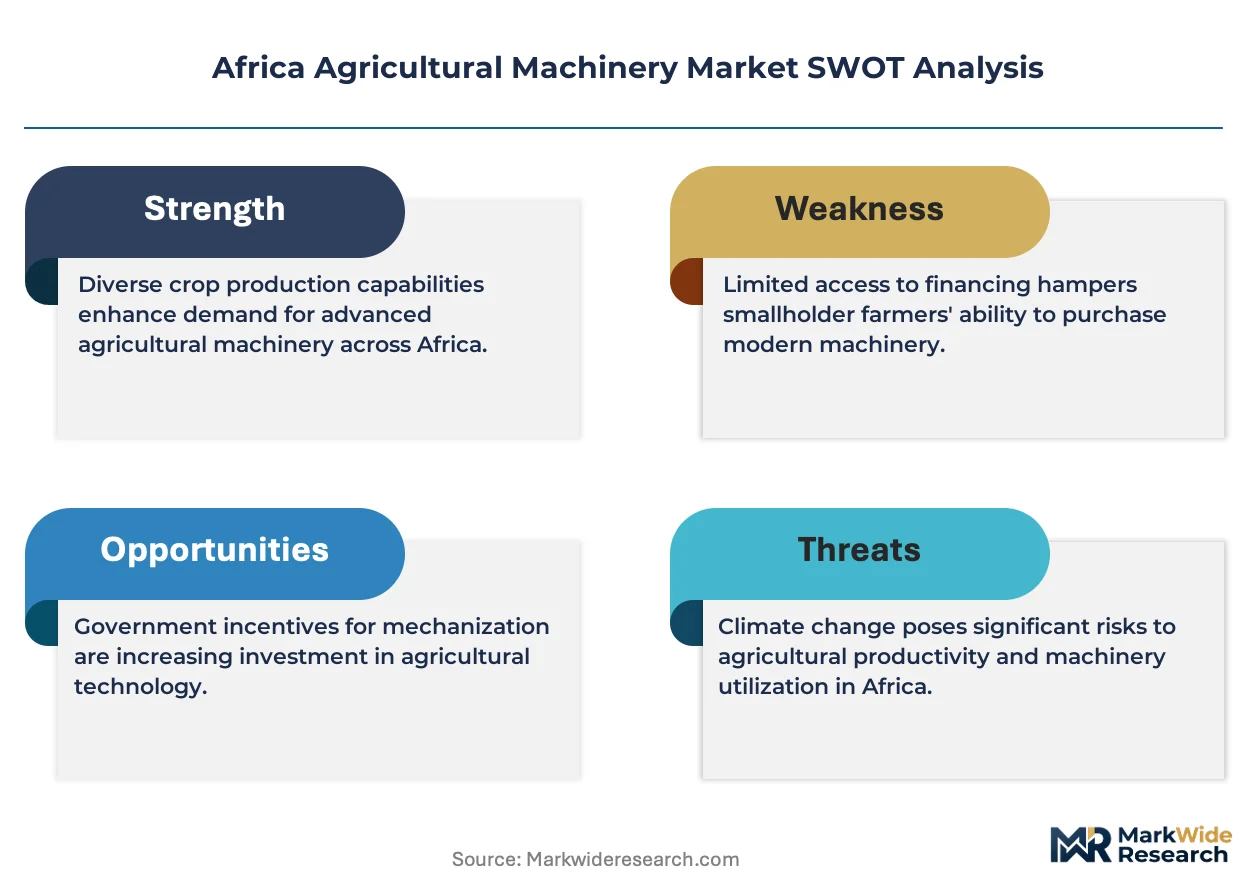
Smallholder cooperatives are gaining share as commercial farms is bifurcating the buyer base into precision-oriented large operators and cost-sensitive collective buyers. Mahindra & Mahindra Limited leverages its compact tractor portfolio to dominate entry-level segments across East Africa. Deere & Company anchors premium positions through precision agriculture technology and dealer network density. AGCO Corporation differentiates via multi-brand distribution covering Massey Ferguson and Fendt lines.
Africa agricultural machinery encompasses tractors, tillage implements, harvesters, and seeding equipment powered by diesel, electric, hydraulic, or autonomous systems, typically engineered to withstand abrasive soils and irregular terrain while performing soil preparation, planting, and crop harvesting functions. Diesel technology still leads installed base volumes due to fuel accessibility and repair infrastructure, though electric prototypes are emerging in peri-urban zones with grid reliability. Tractors command the largest product category by unit shipments, while harvesters capture disproportionate margin pools given seasonal utilization rates and technical complexity.
Kenya's Agricultural Finance Corporation, South Africa's Department of Agriculture, and Nigeria's Central Bank anchor equipment financing frameworks that determine credit access for machinery acquisition. BIS-equivalent national standards bodies in Egypt and Morocco enforce safety and emissions compliance for imported equipment. Stakeholders must monitor how carbon border adjustments and local content rules reshape supplier eligibility across African customs unions.
Market Dynamics
Commercial farm expansion across Nigeria, Ethiopia, and Kenya is concentrating capital deployment into precision equipment while smallholder cooperatives simultaneously scale collective purchasing, bifurcating demand into two distinct buyer archetypes with incompatible service requirements.
Growth Catalysts
- CAADP Implementation:The African Union's Comprehensive Africa Agriculture Development Programme channels national budget allocations toward mechanization subsidies in member states, creating predictable procurement pipelines for equipment suppliers.
- Ethiopia's Large-Scale Farming Zones:Government-designated agricultural investment corridors attract foreign capital deploying automated irrigation and precision planting systems at scale.
- Mobile-Enabled Equipment Sharing:Digital platforms connecting tractor owners to smallholders across Kenya's Rift Valley reduce idle capacity and accelerate payback periods for machinery investments.
Market Restraints
- Diesel Import Dependency:Fuel supply chains remain vulnerable to currency volatility and port congestion in coastal economies, elevating operating cost uncertainty for fleet operators.
- Spare Parts Concentration:Critical components for hydraulic systems and transmissions flow through limited distributor networks based in South Africa and Morocco, extending downtime for remote farms.
- Abrasive Soil Wear Rates:Silica-rich soils in Sahelian zones accelerate implement degradation, compressing replacement cycles beyond what standard warranty terms accommodate.
Strategic Opportunities
- Peri-Urban Electric Prototypes:Grid-reliable zones around Lagos and Nairobi present testbeds for battery-powered compact tractors serving vegetable cooperatives with predictable daily duty cycles.
- Equipment-as-a-Service Models:Pay-per-hectare arrangements bypassing traditional collateral requirements open access to mechanization for land-title-constrained smallholders.
- Carbon Credit Stacking:Precision agriculture data streams from connected implements may qualify for voluntary carbon market protocols, generating supplemental revenue for commercial operators.
Industry Challenges
- Technician Certification Gaps:National vocational frameworks in most African markets lack standardized curricula for electronic diagnostics and precision agriculture system maintenance, forcing manufacturers to internalize training costs.
- Cross-Border Harmonization Delays:Divergent emissions and safety standards between ECOWAS, EAC, and SADC customs unions fragment product portfolios and inflate compliance overhead for suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Africa Agricultural Machinery Market |
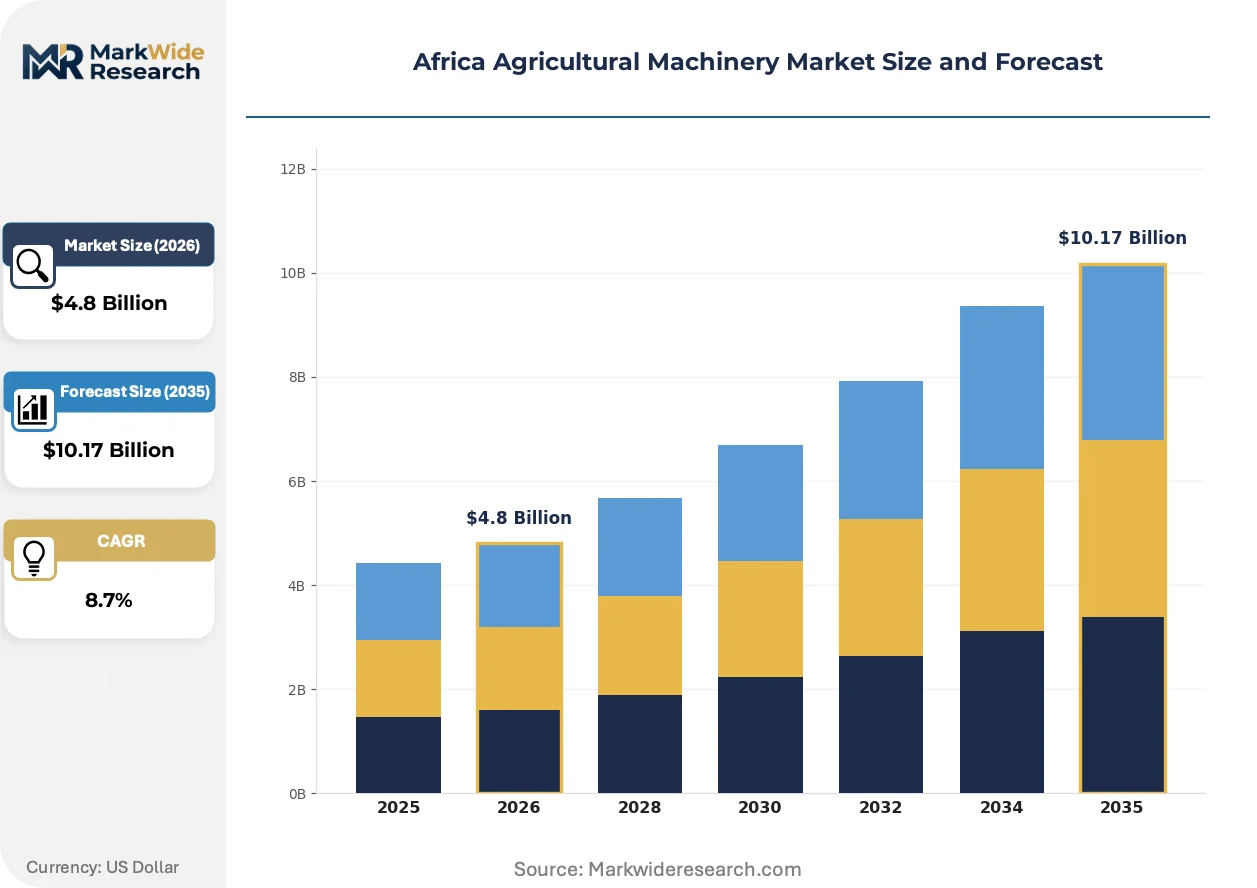
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tractors, Plows, Harvesters, Seeders End User: Commercial Farms, Cooperatives, Smallholder Farmers, Agribusinesses Technology: Electric, Diesel, Hydraulic, Autonomous Application: Tillage, Planting, Irrigation, Soil Preparation |
| Companies Covered | Mahindra & Mahindra Limited, Tractors and Farm Equipment Limited (TAFE), Deere & Company, Weichai Lovol Intelligent Agricultural Technology Co., Ltd., Claas KGaA mbH, CNH Industrial N.V., Kubota Corporation, Yanmar Holdings Co., Ltd., AGCO Corporation, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Africa Agricultural Machinery Market Strategic Shifts
Telematics integration and autonomous guidance systems are migrating from premium North American and European equipment into mid-range platforms adapted for African operating conditions, compressing the technology lag between global product tiers.
Autonomous guidance kits retrofitted to conventional tractors is decomposing the historical link between farm scale and precision capability. Smallholder cooperatives in Kenya's grain belt now access sub-inch accuracy for planting and spraying without full fleet replacement. This technology diffusion is compressing the performance gap between commercial estates and organized smallholders.
Nigeria's Central Bank equipment financing guidelines now mandate traceability systems for beneficiary verification, embedding IoT connectivity as a loan conditionality. This regulatory architecture accelerates connected machinery penetration beyond what pure commercial adoption would achieve. Tier-2 suppliers without telemetry integration face effective exclusion from formal credit channels.
Cooperative procurement consortia are consolidating fragmented smallholder demand into volume contracts with standardized service level agreements. These aggregators displace traditional dealer relationships in Ethiopia's Amhara and Oromia regions, capturing aftermarket revenue pools previously dispersed across informal repair networks. Equipment suppliers must now architect dual-channel strategies serving both direct commercial accounts and cooperative intermediaries.
Africa Agricultural Machinery Market Segmentation
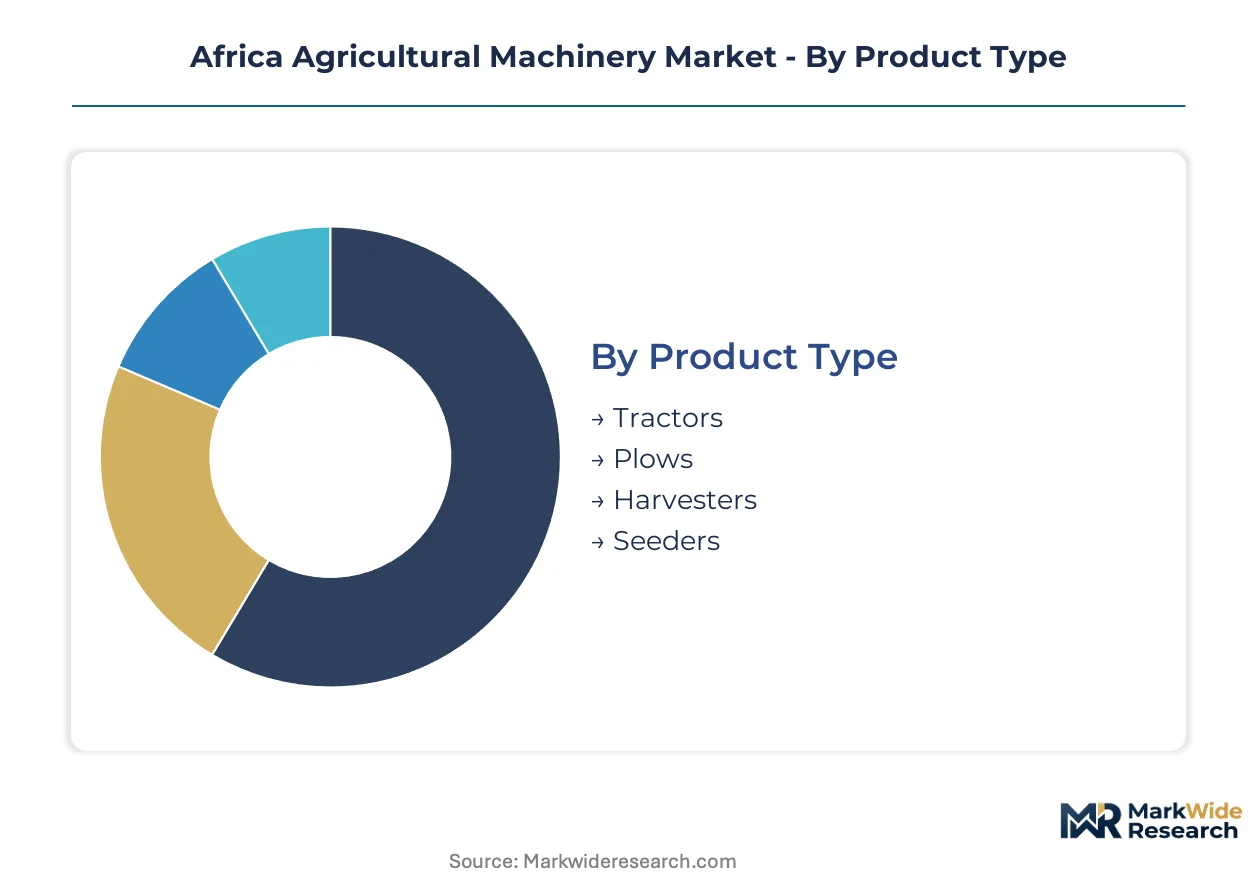
Equipment segmentation in African agricultural machinery reflects divergent capital access, infrastructure constraints, and regulatory frameworks across buyer archetypes. Understanding these divisions enables suppliers to align product portfolios with distinct financing channels and service requirements.
Product Type:
BIS-equivalent standards bodies in Egypt and Morocco enforce divergent safety certifications for tillage implements versus self-propelled equipment, fragmenting import eligibility across North and Sub-Saharan customs zones.
- Tractors:Diesel-powered units with 25-75 horsepower dominate unit shipments across Nigeria's mechanization corridors. Ethiopian commercial zones concentrate demand for higher-horsepower platforms with three-point hitch compatibility for mounted implements.
- Harvesters:Combine harvesters with axial-flow threshing systems capture disproportionate margin pools due to seasonal utilization compression and technical complexity. Kenya's grain belt drives replacement cycles for tracked platforms handling abrasive silica-rich soils.
- Plows:Moldboard and disc configurations engineered for abrasive Sahelian terrain accelerate wear rates beyond standard warranty terms.
- Seeders:Precision planting equipment with variable-rate capability penetrates peri-urban vegetable zones around Lagos and Nairobi.
Established volume favors tractors; emerging adoption favors harvesters.
End User:
Credit access patterns bifurcate sharply between collateralized commercial operators and land-title-constrained collectives.
- Commercial Farms:Large-scale operators in Ethiopia's designated investment corridors deploy automated irrigation and precision planting systems. Nigeria's Central Bank equipment financing guidelines mandate IoT traceability for beneficiary verification, embedding connectivity as a loan conditionality.
- Cooperatives:Procurement consortia in Ethiopia's Amhara and Oromia regions consolidate fragmented smallholder demand into volume contracts with standardized service agreements, displacing traditional dealer relationships.
- Smallholder Farmers:Mobile-enabled equipment sharing platforms across Kenya's Rift Valley reduce tractor idle capacity and accelerate payback periods.
- Agribusinesses:Vertically integrated operators with captive processing facilities prioritize fleet standardization to simplify maintenance protocols.
Capital concentration favors commercial farms; collective scale favors cooperatives.
Technology:
Fuel infrastructure density and grid reliability determine viable powertrain architectures across operating zones.
- Diesel:Dominates installed base volumes due to fuel accessibility and repair infrastructure penetration. Port congestion and currency volatility in coastal economies elevate operating cost uncertainty for fleet operators dependent on imported fuel.
- Electric:Battery-powered compact tractors serve vegetable cooperatives in grid-reliable peri-urban zones with predictable daily duty cycles.
- Hydraulic:Critical system components flow through limited distributor networks based in South Africa and Morocco, extending downtime for remote farms.
- Autonomous:Guidance kits retrofitted to conventional tractors decompose the historical link between farm scale and precision capability in Kenya's grain belt.
Installed base dominance favors diesel; steepest expansion trajectory favors autonomous retrofit kits.
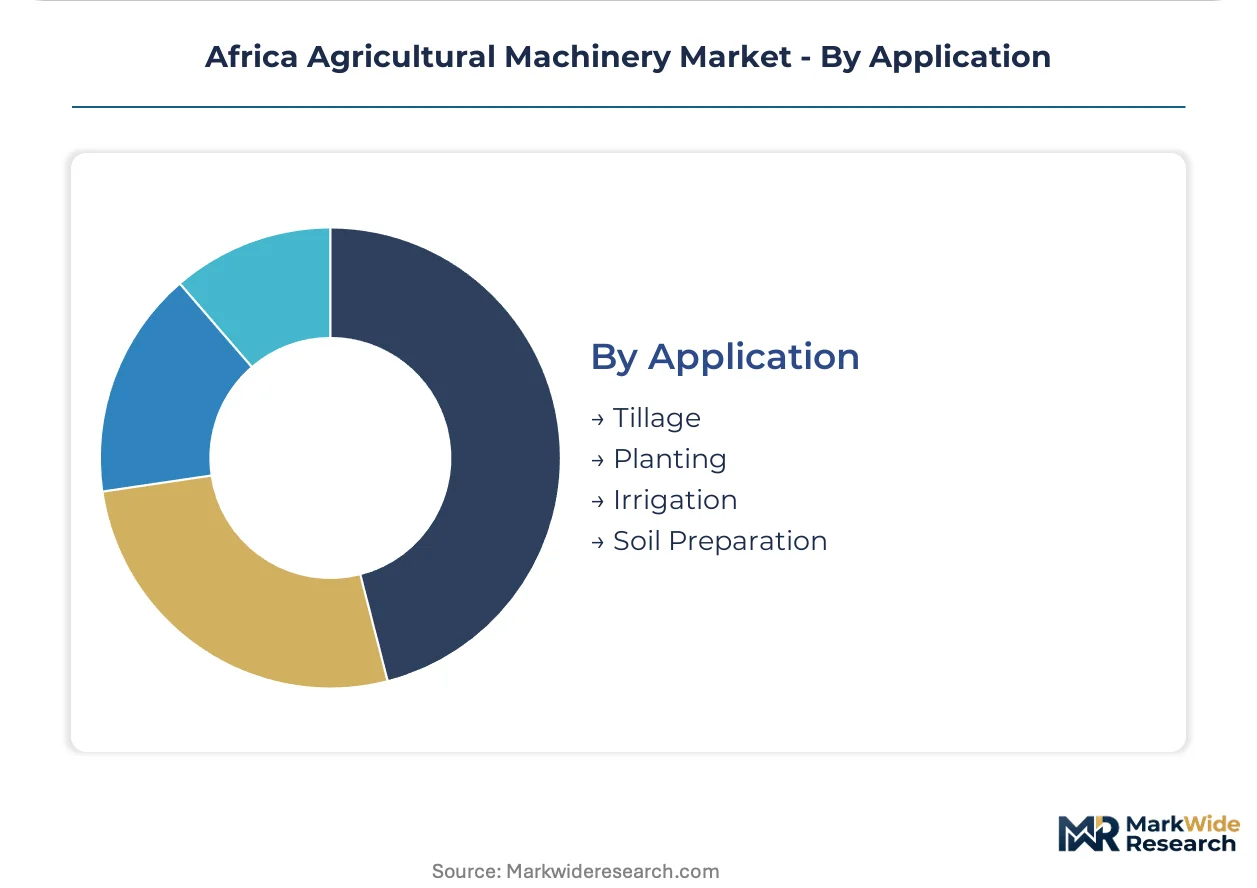
Application:
Soil preparation commands the highest equipment utilization hours annually across African farming systems.
- Tillage:Primary and secondary cultivation implements face accelerated degradation in silica-rich Sahelian soils, compressing replacement cycles.
- Planting:Precision seeding with sub-inch accuracy migrates from premium platforms into mid-range equipment accessible to Kenyan smallholder cooperatives.
- Irrigation:Automated systems concentrate in Ethiopia's government-designated agricultural investment corridors attracting foreign capital.
- Soil Preparation:Land clearing and conditioning equipment serves commercial expansion across Nigeria's northern farming zones.
Utilization intensity favors tillage; technology upgrade cycles favor planting.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South African manufacturers export precision implements to Zimbabwean commercial estates while Nigerian assembly plants source diesel powertrains from Indian suppliers. East African logistics corridors channel Kenyan-made implements into Ethiopian highland farming zones.
Nigeria
Central Bank equipment financing guidelines mandate IoT traceability systems for beneficiary verification, embedding connectivity as a loan conditionality for mechanization subsidies. Large-scale farming investments in the northern grain belt accelerate tractor replacement cycles. Lagos peri-urban vegetable cooperatives test battery-powered compact tractors where grid reliability supports predictable daily duty cycles.
Ethiopia
Government-designated agricultural investment corridors attract foreign capital deploying automated irrigation and precision planting systems at scale. The African Union's CAADP implementation channels national budget allocations toward mechanization subsidies, creating predictable procurement pipelines. Amhara and Oromia regions host cooperative procurement consortia consolidating fragmented smallholder demand into volume contracts with standardized service agreements.
Kenya
Mobile-enabled equipment sharing platforms across the Rift Valley reduce tractor idle capacity and accelerate payback periods for machinery investments. The Agricultural Finance Corporation anchors equipment financing frameworks determining credit access for acquisition. Autonomous guidance kits retrofitted to conventional tractors in the grain belt decompose the historical link between farm scale and precision capability.
South Africa
The Department of Agriculture anchors equipment financing frameworks that determine credit access for machinery acquisition across the region. Critical hydraulic system components flow through distributor networks based in Johannesburg and Cape Town, extending downtime for remote farms. Precision agriculture technology migrates from premium platforms into mid-range equipment serving commercial estates in the Western Cape.
Morocco
BIS-equivalent national standards bodies enforce safety and emissions compliance for imported equipment entering North African customs zones. Carbon border adjustments and local content rules reshape supplier eligibility across regional customs unions. Casablanca-based distributors coordinate spare parts flows for hydraulic systems serving Sahelian farming zones with silica-rich soils accelerating implement degradation.
Africa Agricultural Machinery Market Competitive Environment
Player mix skews toward diversified machinery conglomerates with multi-brand distribution networks and specialized compact tractor manufacturers serving cost-sensitive entry segments. Structure consolidates around three strategic archetypes: premium precision-technology suppliers, volume-focused compact equipment specialists, and multi-brand portfolio operators. Dominant competitive moves include strategic partnerships with mobile-enabled equipment sharing platforms and geographic expansion through cooperative procurement consortia.
Among India-based manufacturers, Mahindra & Mahindra Limited and Tractors and Farm Equipment Limited exemplify the compact tractor archetype dominating entry-level segments across East African markets. Deere & Company anchors the premium-tier position through precision agriculture technology deployment. Within the diversified machinery tier, AGCO Corporation occupies a position representing multi-brand distribution strategies covering distinct price-performance segments.
| Leading Market Players |
|---|
| Mahindra & Mahindra Limited |
| Tractors and Farm Equipment Limited (TAFE) |
| Deere & Company |
| Weichai Lovol Intelligent Agricultural Technology Co., Ltd. |
| Claas KGaA mbH |
| CNH Industrial N.V. |
| Kubota Corporation |
| Yanmar Holdings Co., Ltd. |
| AGCO Corporation |
| Others |
Value Chain & Pricing Dynamics
Take-or-pay contracts with Indian diesel engine suppliers lock in both powertrain access and price visibility for Nigerian and Ethiopian tractor assemblers, insulating fleet operators from currency volatility while committing capital regardless of utilization swings.
Pricing Analysis
Current-generation precision agriculture platforms command substantial premiums over prior-generation mechanical systems, while next-generation electric prototypes remain priced at experimental tiers inaccessible to mainstream buyers. Three-tier pricing structure across premium, standard, and economy levels separates Deere's telematics-integrated tractors from Mahindra's compact diesel units and Chinese gray-market equipment. Price differentiation hinges on after-sales service bundling and precision technology certification. Cost compression in the economy tier is intensifying because Ethiopian cooperative consortia consolidate volume purchasing power. Smallholder cooperatives exhibit highest price sensitivity; commercial estates with CAADP subsidy access show lowest.
Supply Chain Analysis
Port congestion at Durban and Mombasa creates chokepoints extending hydraulic component lead times for remote Sahelian farms. Manufacturing concentrates in India, China, and South Africa, with diesel powertrains drawing from Indian suppliers and precision electronics resting on Chinese component flows. Raw material dependencies span steel forgings, hydraulic seals, and semiconductor controllers. Single-source vulnerability concentrates in South African distributor networks controlling critical transmission parts. Distribution runs through cooperative procurement consortia in Ethiopia's highlands and dealer networks anchored in Nairobi and Lagos.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where dealer network density creates switching costs that lock commercial farms into established service relationships and parts availability guarantees.
For Market Incumbents: Secure exclusive distribution rights with Ethiopia's cooperative procurement consortia before aggregator platforms consolidate aftermarket revenue pools. Anchor spare parts inventory in Nairobi and Casablanca distribution hubs to compress downtime for remote farms facing abrasive soil wear. Vertical integration into hydraulic component remanufacturing counters South African distributor concentration risk. For New Entrants and Emerging Players: Lead with battery-powered compact tractors targeting Lagos and Nairobi peri-urban vegetable cooperatives where grid reliability supports predictable duty cycles. Kenya's Rift Valley equipment-sharing platforms represent the most penetrable entry vector, bypassing traditional collateral barriers through pay-per-hectare service models. Partner with mobile-enabled aggregators rather than building dealer networks from scratch. For Investors and Strategic Acquirers: Regional telematics integrators with proven IoT connectivity deployments represent the priority acquisition archetype, given Nigeria's Central Bank mandate embedding traceability as a loan conditionality. Long-term viability hinges on regulatory entrenchment deepening across ECOWAS and EAC customs unions. Watch for carbon border adjustment announcements reshaping supplier eligibility as the inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Dealer Network Consolidation | Captures aftermarket revenue pools previously dispersed across informal repair networks in Ethiopia's highlands. |
| Telematics Platform Integration | Satisfies Nigeria's Central Bank IoT traceability mandates for equipment financing beneficiary verification. |
| Backward Integration into Powertrains | Reduces exposure to Indian diesel engine supplier currency volatility and port congestion delays. |
| Cooperative Procurement Partnership | Displaces traditional dealer relationships through volume contracts with standardized service level agreements. |
| Peri-Urban Electric Prototype Deployment | Tests battery-powered compact tractors in Lagos and Nairobi grid-reliable zones with predictable duty cycles. |
Study Parameters
Two parallel data streams informed the analysis: structured interviews with agricultural equipment distributors, cooperative procurement managers, and maintenance technicians across Nigeria, Ethiopia, and Kenya; and secondary validation through customs import records, African Union CAADP implementation reports, and national agricultural bank lending disclosures. Bottom-up equipment shipment tallies triangulated against top-down national mechanization budget allocations.
Across the analysis window, forecasts model product type segmentation by horsepower tier and technology generation, end-user archetype bifurcation between commercial estates and cooperative collectives, and regional adoption patterns across North, East, West, and Southern African customs zones. CAGRs derive from equipment replacement cycle compression in abrasive soil zones and subsidy pipeline visibility through CAADP national budget commitments. Key inputs include diesel fuel price volatility indices and mobile platform penetration rates for equipment-sharing services.
The analysis sits within stated boundaries; outcomes outside sustained CAADP funding continuity or abrupt customs union harmonization would require recalibration. Practitioners should keep alternative scenarios live as carbon border adjustment mechanisms and local content rule evolution reshape supplier eligibility across African markets.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Equipment & Machinery
Global Seed Processing Machinery Market
Agricultural Equipment & Machinery
Planting Equipment Market
Agricultural Equipment & Machinery
Global Powered Agriculture Equipment Market
Agricultural Equipment & Machinery
South Africa Agricultural Machinery Market
Agricultural Equipment & Machinery
Hammer Mill Market
Agricultural Equipment & Machinery
Global Fishery Machinery Manufacturing Market
Agricultural Equipment & Machinery
Beekeeping Equipment Market
Agricultural Equipment & Machinery
Agriculture Equipment Market
Agricultural Equipment & Machinery
Grain Silos and Ancillary Equipment Market
Agricultural Equipment & Machinery
Global Agricultural Equipment Market
Agricultural Equipment & Machinery
Europe Haying and Forage Machinery Market
Agricultural Equipment & Machinery
Global Agriculture and Farm Equipment Market
Agricultural Equipment & Machinery
Asia-Pacific Planting Machinery Market
Agricultural Equipment & Machinery
Lawn and Garden Equipment Market
Agricultural Equipment & Machinery
Seed Drill and Broadcast Seeder Machinery Market
Agricultural Equipment & Machinery
Global Tillage Equipment Market