
 India Combine Harvester Market | 2026-2036
India Combine Harvester Market Size, Share, and Industry Trends Forecast 2026-2036
India Combine Harvester Market Foresight
Punjab's farm equipment manufacturing base is consolidating as regional producers scale assembly operations to serve northwestern India's grain belt. Mahindra & Mahindra Ltd. leverages its tractor dealership network to cross-sell combine platforms across Maharashtra and Gujarat. Escorts Kubota Limited sustains engineering focus on paddy-specific threshing mechanisms for eastern Indian conditions. International Tractors Limited anchors its position through price-competitive tractor-mounted units tailored to smallholder budgets.
A combine harvester integrates cutting, threshing, cleaning, and grain-handling functions into a single mobile system, typically powered by diesel engines rated between 100-200 horsepower for Indian field conditions. The machine reduces crop loss to under 2% while cutting harvest timelines from weeks to days during critical weather windows. Self-propelled units command the dominant share of value given their higher throughput and operator comfort, while tractor-mounted variants address cost-sensitive smallholder segments in Bihar and Uttar Pradesh. Smart harvesting technology featuring GPS guidance and yield mapping represents the fastest-expanding technology tier as agri-businesses pursue precision agriculture metrics.
The Ministry of Agriculture's Sub-Mission on Agricultural Mechanization channels subsidy flows toward combine purchases, while BIS certification mandates safety and emission compliance for domestic sales. CEA guidelines on agricultural diesel engine standards shape manufacturer product roadmaps and import component sourcing. Stakeholders must track how FAME scheme extensions toward off-road equipment alter electrification feasibility for compact harvester categories.
Market Dynamics
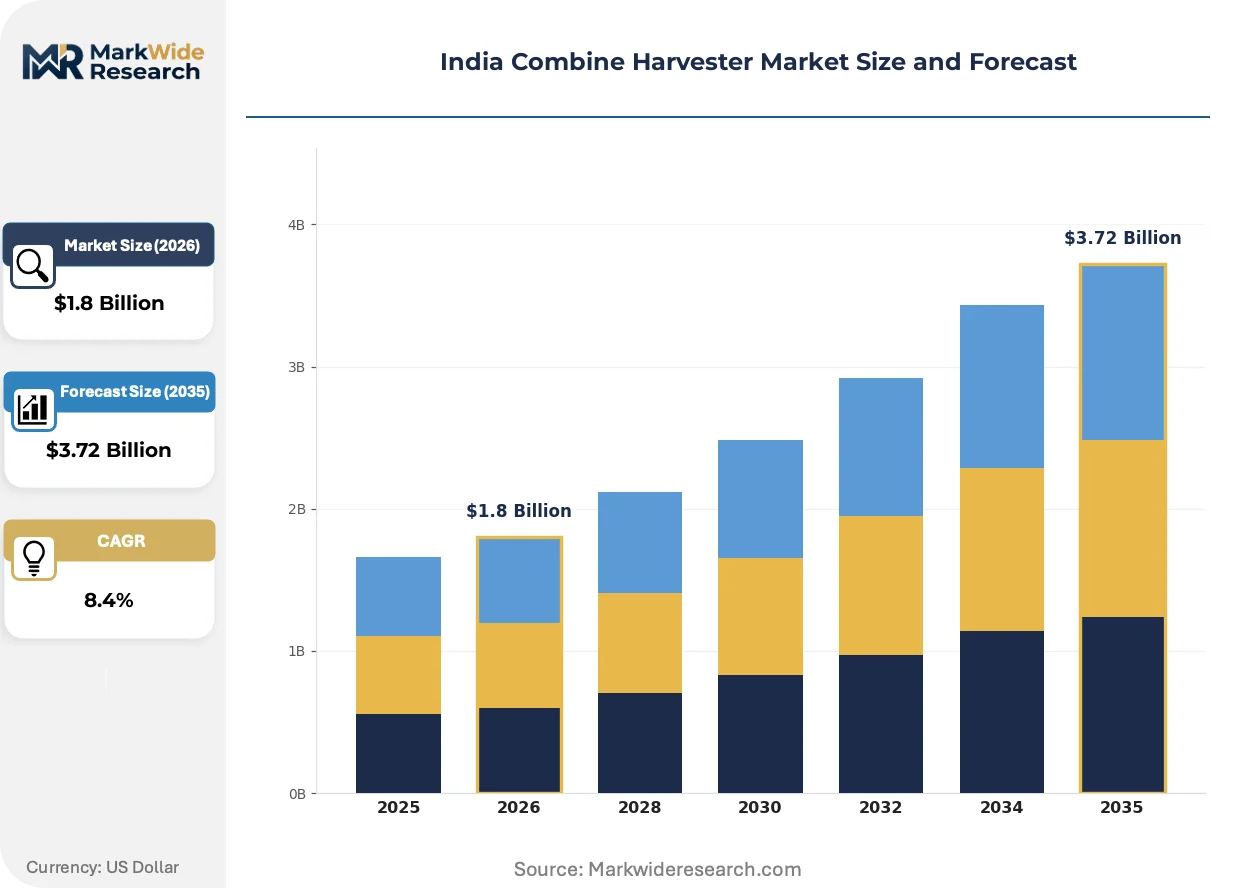
The PLI scheme for farm machinery manufacturing is redirecting capital toward domestic assembly capacity, compressing import dependence for critical powertrain components while accelerating land consolidation in Punjab and Haryana drives self-propelled unit penetration.
Growth Catalysts
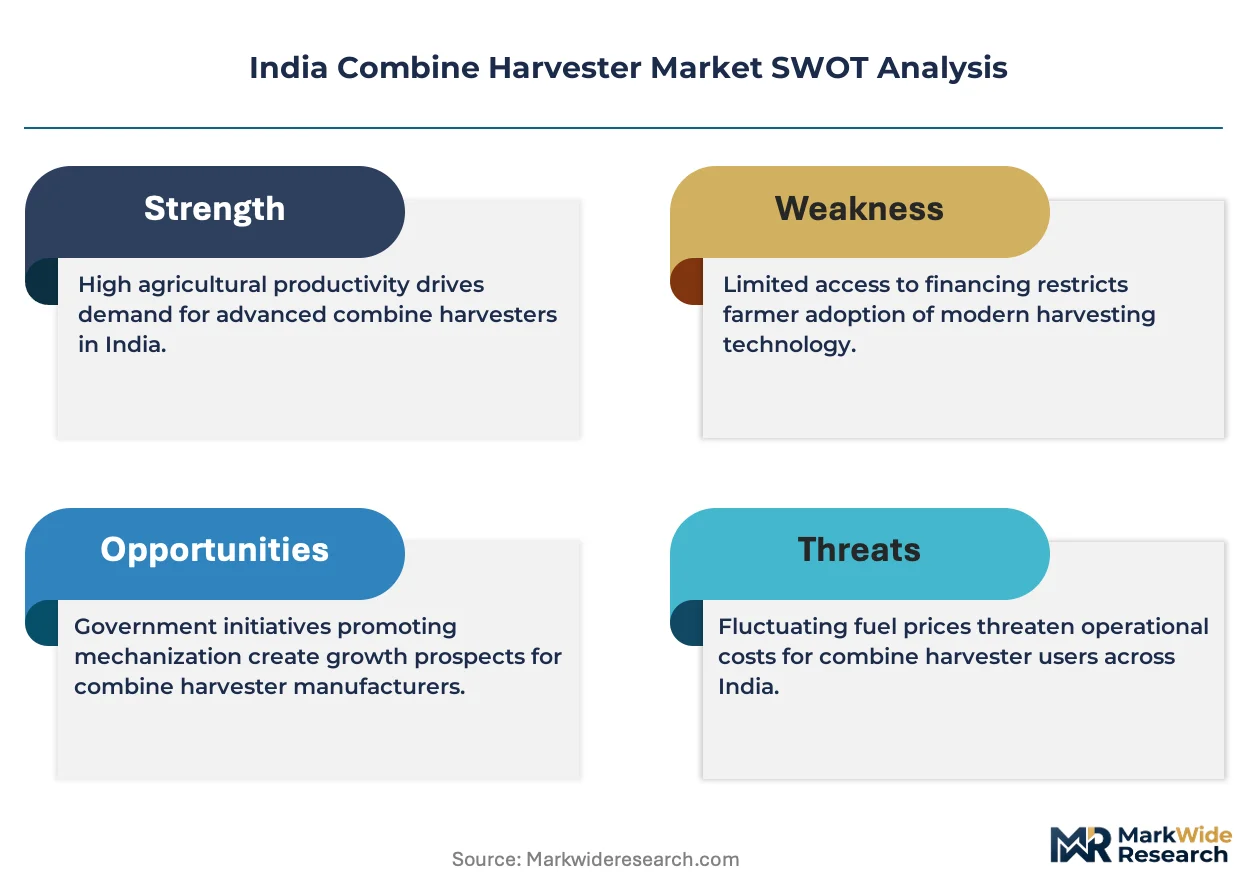
- Sub-Mission on Agricultural Mechanization:Subsidy flows channel directly toward combine purchases, reducing effective acquisition costs for wheat and paddy farmers in the northwestern Indo-Gangetic Plain.
- Land consolidation acceleration:Large-scale farming operations in Punjab and Haryana generate sufficient acreage and capital to justify high-throughput self-propelled harvester deployment.
- Smart harvesting adoption:GPS guidance and yield mapping systems penetrate agri-business operations seeking precision agriculture metrics for crop management optimization.
Market Restraints
- Diesel engine cost volatility:Powertrain input exposure to petroleum price swings compresses manufacturer margin buffers and destabilizes farm-level total cost of ownership calculations.
- Component import concentration:Critical hydraulic and transmission assemblies source from concentrated East Asian supplier bases, creating vulnerability to trade flow disruptions.
- Smallholder acreage fragmentation:Bihar and Uttar Pradesh land parcel sizes fall below economic thresholds for self-propelled unit deployment, capping addressable market expansion.
Strategic Opportunities
- Eastern paddy belt penetration:West Bengal and Odisha present underpenetrated demand for paddy-specific threshing configurations adapted to high-moisture grain conditions.
- FAME scheme extension:Off-road equipment electrification feasibility opens white space for compact harvester categories in emission-sensitive peri-urban farming zones.
- Telematics-channel convergence:Remote diagnostics and predictive maintenance platforms enable equipment-as-a-service models, shifting revenue from unit sales to uptime guarantees.
Industry Challenges
- Skilled operator scarcity:Self-propelled unit complexity outpaces rural labor pool technical training depth, constraining effective machine utilization rates.
- BIS certification timelines:Safety and emission compliance testing creates product launch delays, compressing seasonal sales windows for harvest equipment.
- Legacy fleet integration friction:Smart harvesting retrofits face compatibility barriers with decade-old mechanical control systems prevalent in secondary ownership markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Combine Harvester Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.72 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Self-Propelled, Tractor-Mounted, Pull-Type, Compact Application: Cereals, Pulses, Oilseeds, Grains End User: Farmers, Agricultural Cooperatives, Contractors, Agri-Businesses Technology: Conventional, Smart Harvesting, Autonomous, Hybrid |
| Companies Covered | Deere & Company, International Tractors Limited, Kartar Agro Industries Private Limited, Dasmesh Group, Yanmar Holdings Co., Ltd., PREET Group, Escorts Kubota Limited, KS Agrotech PVT.LTD, Mahindra & Mahindra Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Combine Harvester Market Shifts & Advancements
Digital automation layers are overlaying mechanical harvesting platforms, compressing operator skill requirements while expanding data capture capabilities for farm management systems.
Precision guidance systems are converging with real-time soil moisture sensors to enable variable-rate harvesting protocols. Agri-business operators in Haryana deploy these integrated platforms to optimize grain quality across field moisture gradients. The technology stack is converging with fleet management software to compress coordination costs for multi-machine operations during narrow weather windows.
CEA guidelines on agricultural diesel engine standards are mandating emission tier upgrades for domestic sales eligibility. Manufacturers reconfigure supply chains to source compliant powertrain components, accelerating local engine assembly investments. The Punjab-Haryana manufacturing corridor absorbs the bulk of compliance-driven product roadmap adjustments given its concentration of assembly capacity.
Service unbundling is separating equipment ownership from operational execution across large landholding aggregators. Custom hiring centers in Maharashtra and Gujarat displace direct ownership for mid-scale farmers seeking harvest capacity without capital commitment. This model compresses seasonal utilization risk while concentrating fleet purchasing power among platform operators.
India Combine Harvester Market Segmentation
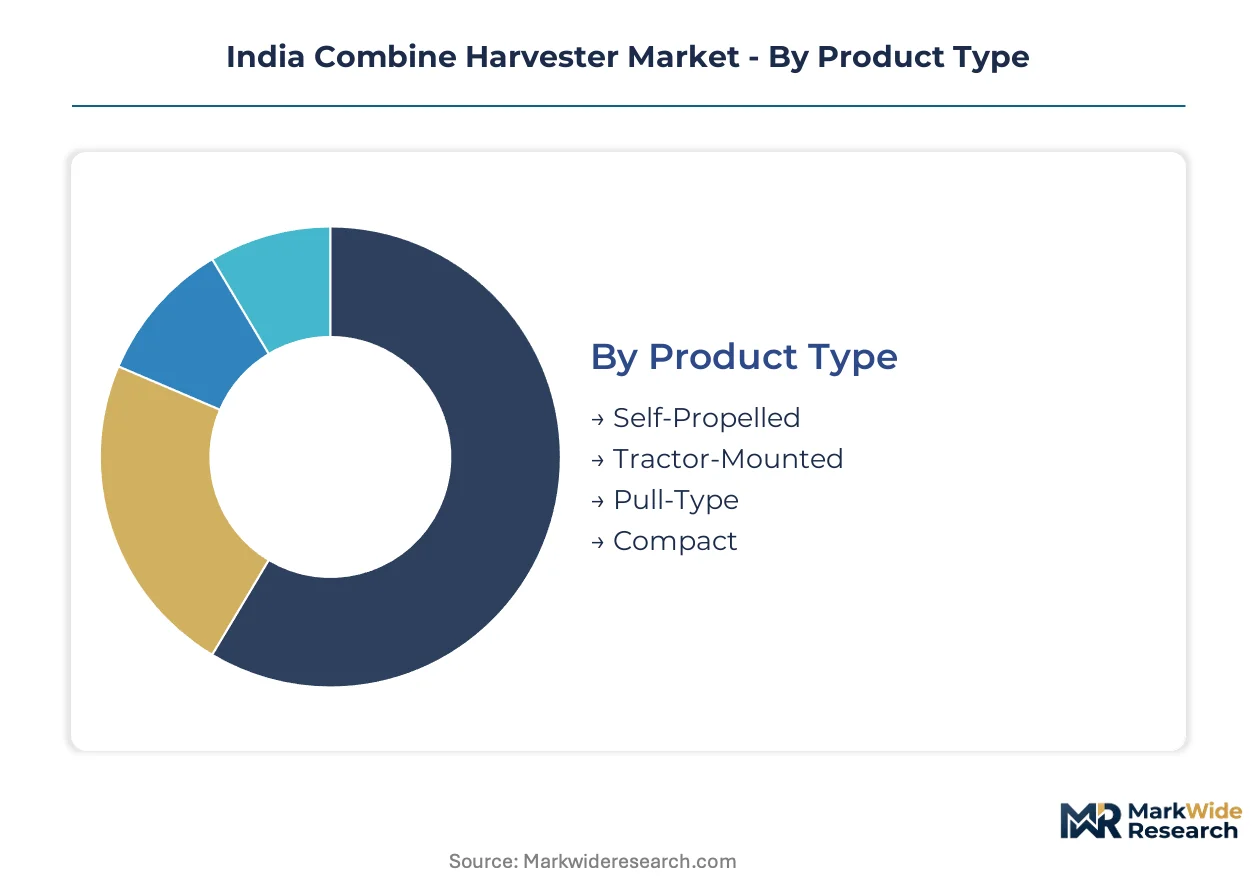
Segmentation in the India combine harvester market reveals how capital intensity, farm scale, and crop specificity drive purchasing patterns across the northwestern grain belt and emerging eastern markets. Buyers optimize acquisition decisions against landholding size, seasonal labor availability, and subsidy eligibility thresholds established under the Sub-Mission on Agricultural Mechanization.
Product Type:
Capital deployment capacity and operational acreage determine platform selection, with self-propelled units commanding premium positioning for consolidated landholdings while tractor-mounted configurations address budget-constrained smallholder segments.
- Self-Propelled:These diesel-powered platforms integrate cutting, threshing, and cleaning systems into a single chassis rated at 100-200 horsepower. Punjab and Haryana's large-scale wheat and paddy operations generate concentrated demand where harvest window compression justifies capital intensity.
- Tractor-Mounted:Modular attachments leverage existing tractor power units, reducing acquisition cost by 40-60% versus self-propelled alternatives. Bihar and Uttar Pradesh smallholders favor this configuration where land parcel fragmentation caps throughput requirements.
- Pull-Type:Towed configurations suit custom hiring operators serving dispersed smallholder clusters with intermittent utilization patterns.
- Compact:Narrow-width designs navigate fragmented plots and peri-urban vegetable zones where maneuverability outweighs throughput metrics.
Self-propelled units lead on scale; compact configurations lead on momentum as peri-urban mechanization accelerates.
Application:
Crop-specific threshing mechanics and moisture handling requirements segment demand across India's diverse agro-climatic zones, with grain characteristics dictating rotor speed, concave clearance, and cleaning fan specifications.
- Cereals:Wheat and rice dominate installed base utilization, with paddy-specific threshing mechanisms from Escorts Kubota penetrating West Bengal and Odisha's high-moisture conditions. Cereal harvesters absorb the bulk of PLI scheme manufacturing incentives given volume concentration.
- Pulses:Chickpea and lentil harvesting demands gentler threshing action to prevent seed coat damage, with specialized concave configurations emerging for Madhya Pradesh's pulse belt expansion.
- Oilseeds:Mustard and soybean applications require modified header designs for podded crops, with regional manufacturers in Rajasthan adapting platforms for local oilseed profiles.
- Grains:Maize and sorghum harvesting integrates shelling mechanisms, with demand clustering in Maharashtra's rainfed zones where multi-crop flexibility commands premium positioning.
Cereals anchor revenue concentration; pulses gain share fastest as crop diversification policies redirect procurement support.
End User:
Ownership structure versus operational execution models separate direct purchasers from service-based access, with capital constraints and seasonal utilization risk driving unbundling across Maharashtra and Gujarat.
- Farmers:Direct ownership concentrates among Punjab and Haryana landholders exceeding 10 hectares where annual utilization rates justify depreciation schedules. Subsidy flows under SMAM reduce effective acquisition costs by 40-50% for eligible beneficiaries.
- Agricultural Cooperatives:Pooled procurement spreads capital burden across member holdings, with Haryana's cooperative network deploying fleet-scale operations during compressed wheat harvest windows.
- Contractors:Custom hiring centers displace ownership for mid-scale farmers, compressing seasonal risk while concentrating purchasing power among platform operators.
- Agri-Businesses:Corporate farming ventures deploy smart harvesting platforms with GPS guidance and yield mapping, prioritizing data capture for precision agriculture optimization.
Farmers retain volume leadership; contractors expand most quickly as service unbundling penetrates secondary ownership markets.
Technology:
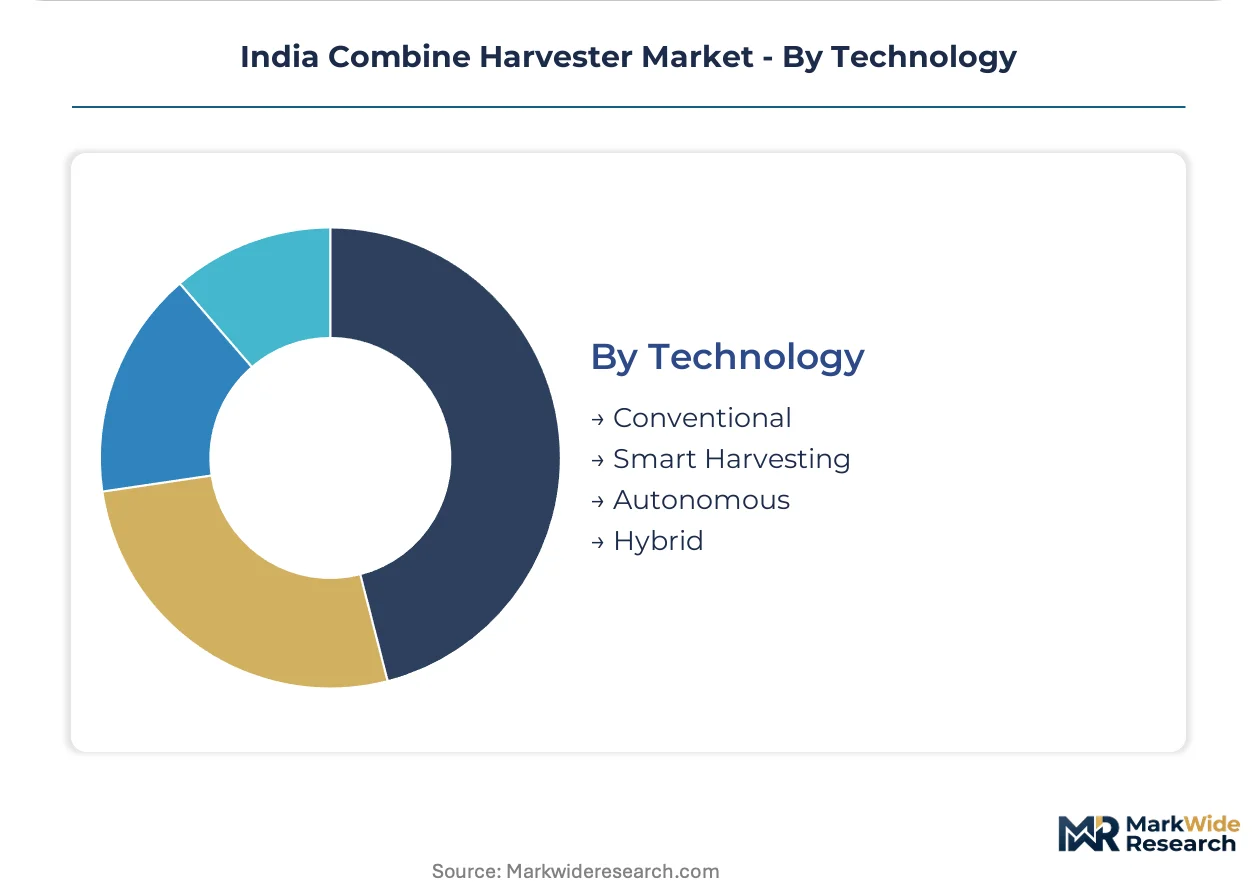
Digital automation layers overlay mechanical platforms along a maturity curve from mechanical control systems through precision guidance toward autonomous operation, with regulatory compliance timelines shaping manufacturer roadmaps.
- Conventional:Mechanical control systems dominate secondary ownership markets and tractor-mounted configurations, with decade-old fleets prevalent in Bihar and Uttar Pradesh where retrofit compatibility barriers constrain upgrade pathways.
- Smart Harvesting:GPS guidance, yield mapping, and real-time moisture sensing penetrate agri-business operations seeking precision agriculture metrics. Haryana operators deploy these integrated platforms for variable-rate protocols across field moisture gradients.
- Autonomous:Limited commercial deployment concentrates in research pilots and corporate demonstration projects, with CEA emission compliance timelines and BIS safety certification creating product launch friction.
- Hybrid:Dual-power architectures combining diesel prime movers with electric auxiliaries emerge as FAME scheme extensions toward off-road equipment alter electrification feasibility for compact categories.
Conventional systems retain installed base dominance; smart harvesting climbs the fastest as fleet management software converges with precision guidance platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Domestic assembly capacity migrates toward states with favorable PLI scheme implementation and established component supplier ecosystems, compressing cost-of-compliance gaps between manufacturing zones.
Punjab
Wheat and paddy consolidation across large landholdings drives self-propelled harvester penetration. The Sub-Mission on Agricultural Mechanization channels subsidy flows toward eligible beneficiaries, reducing effective acquisition costs. The Ludhiana-Jalandhar manufacturing corridor anchors domestic assembly operations for northwestern grain belt supply.
Haryana
Agri-business operators deploy smart harvesting platforms with GPS guidance for variable-rate protocols across field moisture gradients. CEA guidelines on agricultural diesel engine standards mandate emission tier upgrades for domestic sales eligibility. The Karnal-Ambala belt concentrates cooperative fleet procurement and custom hiring center networks.
Maharashtra
Multi-crop flexibility for maize and sorghum commands premium positioning in rainfed zones. FAME scheme extensions toward off-road equipment alter electrification feasibility for compact harvester categories in peri-urban farming zones. The Nagpur-Pune corridor absorbs service unbundling trends as custom hiring centers displace direct ownership.
West Bengal
High-moisture paddy conditions generate underpenetrated demand for specialized threshing configurations. BIS certification mandates safety and emission compliance for domestic sales, creating product launch timelines. The Burdwan-Midnapore belt presents expansion opportunities for paddy-specific platform adaptations.
Gujarat
Tractor-mounted configurations serve cost-sensitive smallholder segments through cross-selling networks. DGFT trade policy frameworks shape component import sourcing for hydraulic and transmission assemblies. The Rajkot-Surendranagar cluster supports regional fabrication capacity for budget-tier equipment.
India Combine Harvester Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue compact and electrification vectors. The vendor base stratifies across three tiers: diversified agricultural equipment conglomerates, specialized harvester fabricators, and regional tractor-mounted assemblers. Strategic archetypes include dealership-network cross-sellers, paddy-specialist engineers, and price-competitive smallholder targeted manufacturers. Competitive moves concentrate on capacity expansion in the Punjab-Haryana corridor and strategic partnerships for smart harvesting technology licensing.
Among diversified conglomerates, Mahindra & Mahindra Ltd. and Escorts Kubota Limited occupy positions reflecting divergent specialization strategies. International Tractors Limited exemplifies the price-competitive archetype targeting smallholder budgets. Deere & Company anchors the premium-tier vector through established brand positioning. These entities represent distinct strategic postures without implying specific market share claims or operational details beyond naming conventions.
| Leading Market Players |
|---|
| Deere & Company |
| International Tractors Limited |
| Kartar Agro Industries Private Limited |
| Dasmesh Group |
| Yanmar Holdings Co., Ltd. |
| PREET Group |
| Escorts Kubota Limited |
| KS Agrotech PVT.LTD |
| Mahindra & Mahindra Ltd. |
| Others |
Supply & Pricing Matrix
CEA emission tier upgrades for agricultural diesel engines are compressing powertrain cost structures while concentrating compliant component sourcing within the Punjab-Haryana manufacturing corridor. This regulatory-driven technology transition simultaneously elevates factory-gate pricing for self-propelled units and rewards assemblers with localized supply networks.
Pricing Analysis
Distributor margins on tractor-mounted configurations absorb the steepest compression as International Tractors Limited and regional assemblers compete for Bihar and Uttar Pradesh smallholder budgets. Three-tier pricing structure across premium, standard, and economy levels separates GPS-enabled smart harvesting platforms from mechanical-control units and basic tractor attachments. Price differentiation hinges on CEA emission certification tier and after-sales service bundling. Cost compression in economy-tier tractor-mounted units is intensifying because of hydraulic component import volatility. Custom hiring contractors exhibit lowest price sensitivity; fragmented smallholders in eastern states face acute budget constraints.
Supply Chain Analysis
BIS certification for safety and emission compliance gates domestic market entry, forcing manufacturers to reconfigure supplier qualifications around certified powertrain and hydraulic assembly sources. Critical transmission and precision hydraulic components draw from concentrated East Asian supplier bases in China, Japan, and South Korea. Raw material dependencies center on high-grade steel for threshing rotors, specialized rubber for tracks and belts, and electronic control modules for smart harvesting platforms. Single-source vulnerability in precision hydraulic valve assemblies creates disruption exposure. Distribution runs through Mahindra's tractor dealership network and regional cooperative procurement channels serving the northwestern grain belt.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The India combine harvester market functions as a geographic-arbitrage play where Punjab-Haryana manufacturing scale advantages offset eastern states' land fragmentation constraints, with PLI scheme subsidies amplifying returns on domestic assembly capacity.
For Market Incumbents: Hedge against eastern paddy belt entry costs by securing paddy-specific threshing IP through engineering partnerships with Escorts Kubota's established platforms. Expand captive forging capacity in the Ludhiana-Jalandhar corridor to offset hydraulic component import exposure. Prioritize BIS pre-certification investments to compress seasonal launch windows before rival product approvals.
For New Entrants and Emerging Players: Enter via compact harvester electrification pathways opened by FAME scheme extensions toward off-road equipment, targeting peri-urban vegetable zones around Pune and Nagpur where maneuverability premiums exceed throughput requirements. Partner with existing tractor distribution networks in Gujarat to bypass direct dealership buildout costs.
For Investors and Strategic Acquirers: Valuations sit cheapest among regional tractor-mounted assemblers lacking smart harvesting telemetry stacks but holding established smallholder channel relationships. Long-term viability favors platforms with service-unbundling revenue models shifting from unit sales to uptime guarantees. Watch CEA emission tier advancement timelines as the critical inflection signal for compliance-driven consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Paddy-Specific Threshing Platform Development | Captures West Bengal and Odisha expansion opportunities where high-moisture conditions demand specialized rotor configurations. |
| CEA Tier-Compliant Powertrain Localization | Secures BIS certification eligibility while reducing exposure to East Asian hydraulic assembly import volatility. |
| Telematics-Enabled Equipment-as-a-Service Launch | Shifts revenue model toward uptime guarantees for Maharashtra and Gujarat custom hiring center operators. |
| FAME Scheme Electrification Pilot | Opens peri-urban compact harvester categories in emission-sensitive zones around Nagpur and Pune. |
| Cooperative Fleet Procurement Partnership | Concentrates seasonal purchasing power through Haryana's established agricultural cooperative network. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with farm equipment manufacturing executives, agricultural cooperative procurement heads, aftermarket service network managers, and CEA regulatory affairs officers with secondary validation against BIS certification records, DGFT trade policy frameworks, and Ministry of Agriculture SMAM subsidy disbursement data. Bottom-up unit shipment modeling triangulated against top-down addressable acreage calculations.
Segment-weighting approaches distributed value projections across self-propelled, tractor-mounted, pull-type, and compact product configurations, with crop-specific application mix and technology tier adoption curves modeled throughout the forecast period. CAGRs derived from machinery replacement cycles, land consolidation trajectories, and subsidy flow elasticity. Diesel engine cost volatility and hydraulic component lead time fluctuations fed into scenario bands.
Inputs from cooperative procurement managers and CEA technical committees were available through the study window; gaps in real-time smallholder financing access data introduce uncertainty bands around eastern state penetration timelines. Deviation in FAME scheme extension scope or PLI scheme disbursement velocity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Equipment & Machinery
Europe Haying and Forage Machinery Market
Agricultural Equipment & Machinery
China Haying and Forage Machinery Market
Agricultural Equipment & Machinery
Global Powered Agriculture Equipment Market
Agricultural Equipment & Machinery
Planting Equipment Market
Agricultural Equipment & Machinery
Commercial Oil Extraction Machine Market
Agricultural Equipment & Machinery
Agriculture Equipment Market
Agricultural Equipment & Machinery
Germany Haying and Forage Machinery Market
Agricultural Equipment & Machinery
Global Agricultural Equipment Market
Agricultural Equipment & Machinery
Asia-Pacific Planting Machinery Market
Agricultural Equipment & Machinery
Lawn and Garden Equipment Market
Agricultural Equipment & Machinery
Asia-Pacific Agricultural Sprayer Market
Agricultural Equipment & Machinery
Seed Drill Machines Market
Agricultural Equipment & Machinery
Asia-Pacific Haying and Forage Machinery Market
Agricultural Equipment & Machinery
Africa Agricultural Machinery Market
Agricultural Equipment & Machinery
Europe Planting Machinery Market
Agricultural Equipment & Machinery
Global Seed Processing Machinery Market