
 China Financial Services Software Market | 2026-2036
China Financial Services Software Market Size, Share, and Industry Trends Forecast 2026-2036
China Financial Services Software Market Insights
Project finance through state-backed technology modernization funds is tilting competitive dynamics toward vendors capable of absorbing multi-year implementation cycles. Tencent leverages its super-app ecosystem to embed financial services software directly into consumer workflows. Ant Group anchors its position through blockchain-enabled trade finance infrastructure developed under PBOC supervision. Industrial and Commercial Bank of China sustains dominance by operating one of the largest privately managed cloud deployments among state-owned lenders.
China Financial Services Software comprises modular applications for transaction processing, regulatory reporting, customer relationship management, and risk quantification, typically architected on distributed computing frameworks with real-time data pipeline integration. The primary commercial purpose is enabling financial institutions to automate operations while satisfying prudential oversight requirements. Core banking platforms retain the largest installed base among product types, though wealth management modules are attracting disproportionate investment as household savings migrate toward structured products. Cloud-based deployment models are expanding fastest among joint-stock banks seeking to bypass capital-intensive data center builds, while on-premise installations persist at policy banks where data sovereignty mandates prevail.
SAMR enforces cybersecurity review protocols for financial software vendors processing cross-border data flows, effectively filtering market access. The PBOC's fintech certification program and MIIT's GB standards for financial cloud infrastructure establish mandatory technical baselines that elevate compliance costs for foreign suppliers. Stakeholders must monitor how the central bank's digital yuan middleware specifications reshape core banking upgrade priorities across provincial and city commercial banks.
Market Dynamics
SAMR's cybersecurity review protocols and PBOC's digital yuan middleware specifications are forcing state-owned and joint-stock banks into simultaneous core system overhauls, compressing vendor qualification timelines and elevating compliance costs for foreign suppliers.
Growth Catalysts
- Digital Currency Infrastructure:PBOC's e-CNY rollout mandates middleware upgrades across provincial banks, creating captive demand for certified core banking modules that interface with central bank ledgers.
- Wealth Management Migration:Household savings rotation into structured products drives disproportionate investment in portfolio analytics and risk quantification software among Yangtze River Delta retail lenders.
- Cloud-Native Procurement:State-backed technology modernization funds in Shanghai and Beijing accelerate multi-year implementation cycles for distributed computing frameworks at policy banks.
Market Restraints
- Input Cost Escalation:GB standards compliance for financial cloud infrastructure elevates certification expenses, particularly for foreign vendors navigating MIIT technical baselines.
- Supply Concentration:Domestic vendor dominance in blockchain-enabled trade finance creates dependency risk for joint-stock banks seeking alternative core platform suppliers.
- Technical Limitation:Real-time data pipeline integration with legacy on-premise installations at policy banks constrains cloud migration velocity despite sovereignty mandates.
Strategic Opportunities
- Underpenetrated Western Provinces:City commercial banks in Sichuan and Shaanxi lag Yangtze River Delta peers in wealth management module deployment, presenting white space for compliance-forward vendors.
- Regulatory Tailwind:Dual carbon goals embedded in SAMR data governance rules create preference for energy-efficient distributed architectures in new procurement criteria.
- Channel Convergence:Super-app ecosystem embedding enables financial services software to bypass traditional enterprise sales cycles and capture consumer workflow integration directly.
Industry Challenges
- Talent Scarcity:Shortage of engineers certified in both PBOC fintech standards and cloud-native architecture extends implementation timelines for core banking migrations.
- Integration Complexity:Middleware specifications for digital yuan compatibility require extensive reconfiguration of existing transaction processing modules at provincial banks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Financial Services Software Market |
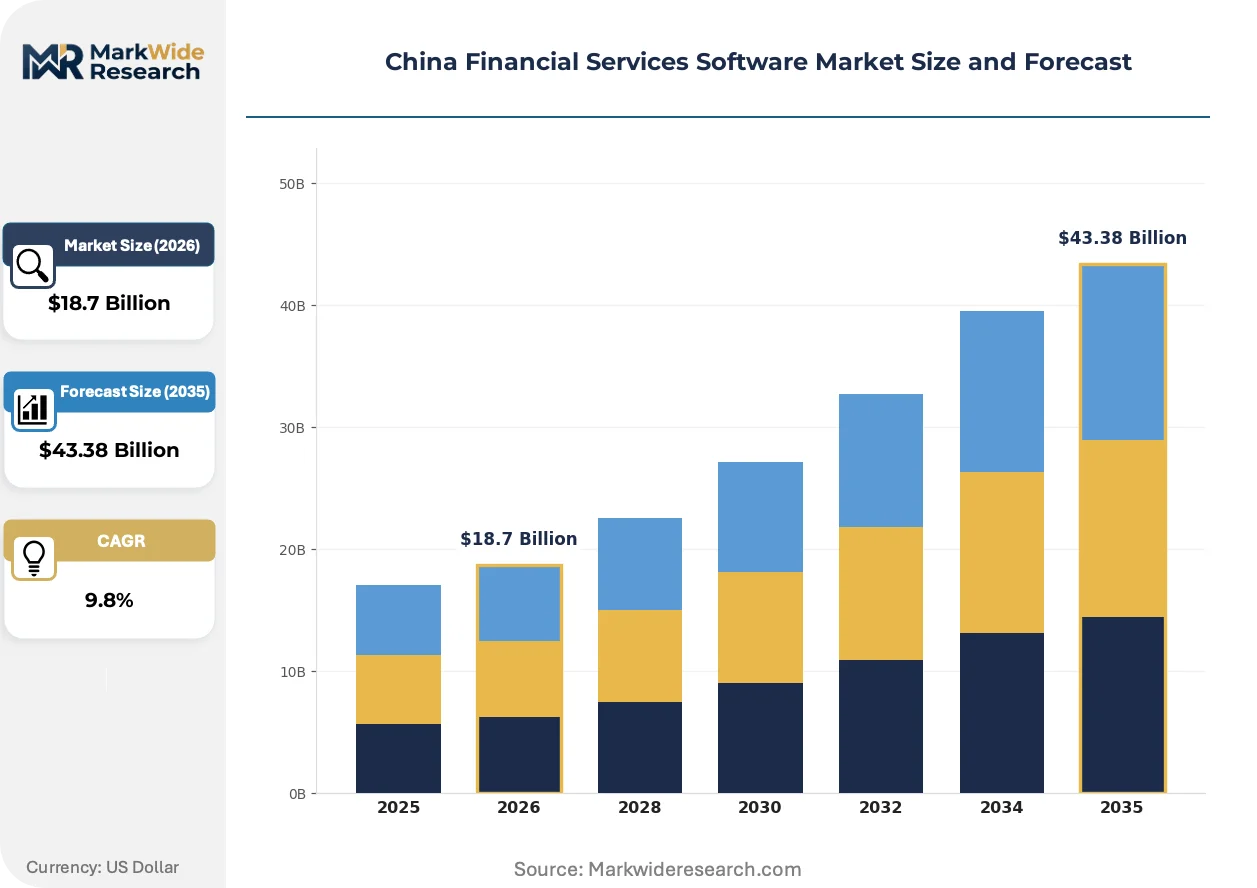
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $43.38 Billion |
| CAGR (2026 – 2036) | 9.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Core Banking, Risk Management, Wealth Management, Compliance Solutions Client Type: Retail Banks, Investment Firms, Insurance Companies, Credit Unions Deployment Model: On-Premise, Cloud-Based, Hybrid, SaaS Technology: Blockchain, Artificial Intelligence, Big Data Analytics, Robotic Process Automation |
| Companies Covered | China Merchants Bank, China Construction Bank, Tencent, Ant Group, China Life Insurance, Alibaba Group Holding, Industrial and Commercial Bank of China, FintechOS, Ping An Insurance Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Financial Services Software Market Trends and Innovations
Distributed ledger architectures and real-time regulatory reporting engines are compressing the gap between transaction execution and prudential oversight, reshaping how financial institutions architect their software stacks.
Blockchain-enabled trade finance infrastructure is digitizing documentary credit workflows previously dependent on paper-based verification. Joint-stock banks in Guangdong and Fujian are deploying these platforms at accelerated pace to capture cross-border renminbi settlement volume. The technology is digitizing correspondent banking relationships and compressing reconciliation cycles from days to minutes.
MIIT's GB standards for financial cloud infrastructure mandate encryption protocols and data residency controls that elevate technical baselines for all market participants. Foreign suppliers face disproportionate compliance burden as SAMR enforces cybersecurity review for cross-border data flows. Provincial banks in Jiangsu and Zhejiang are responding by prioritizing domestic vendors with pre-certified distributed computing frameworks.
Household savings migration toward structured products is altering procurement priorities across retail banking segments. Wealth management modules now attract investment allocations previously reserved for core transaction processing platforms. Joint-stock banks in the Pearl River Delta are unbundling after-sales service contracts and shifting toward subscription-based software licensing to align vendor incentives with portfolio performance outcomes.
China Financial Services Software Market Segmentation
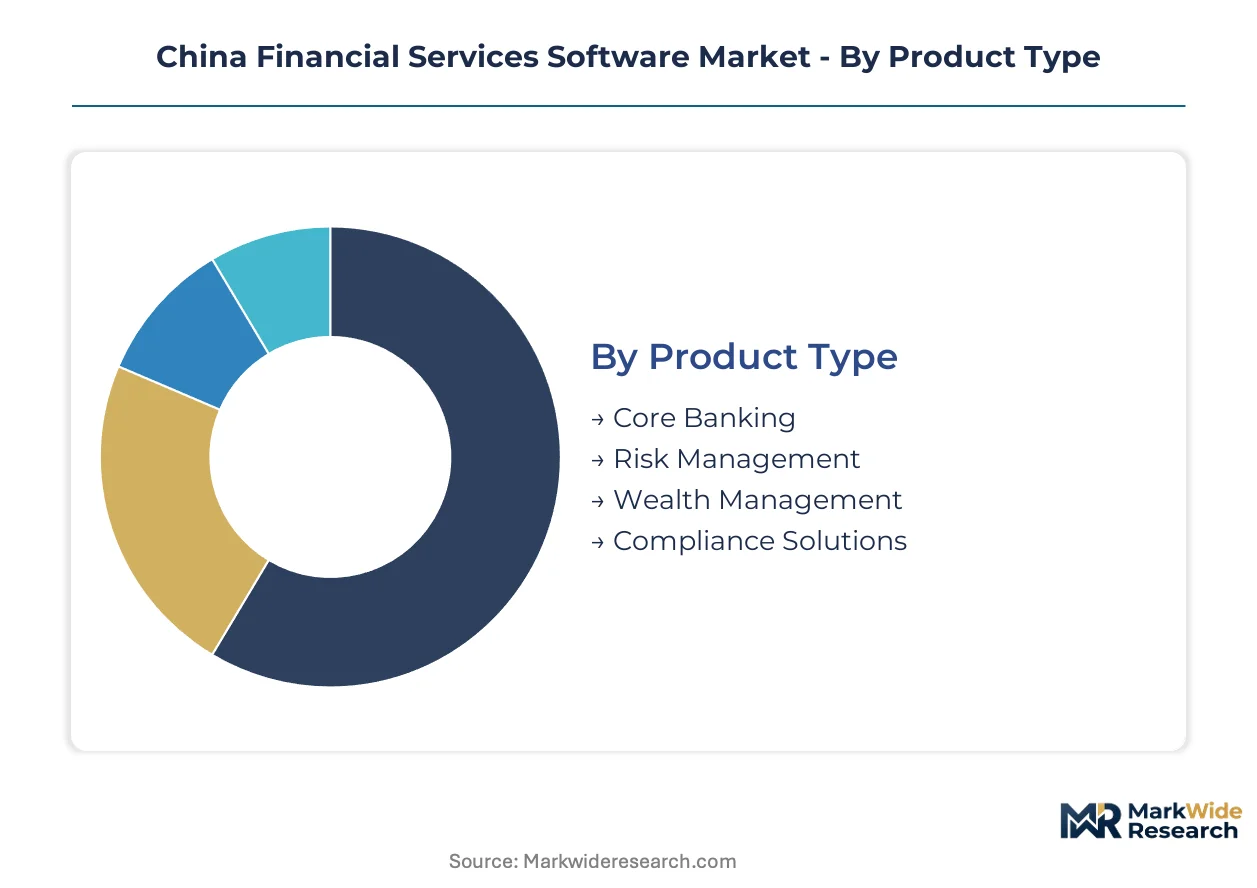
Procurement cycles vary dramatically across software categories in China's financial sector, with compliance-driven modules refreshing faster than core infrastructure. SAMR certification timelines and PBOC middleware specifications create divergent replacement rhythms that vendors must navigate.
Product Type:
Core banking platforms turn over slowest due to implementation complexity, while compliance solutions refresh fastest under regulatory pressure.
- Core Banking:Distributed computing frameworks process transaction ledgers across branch networks. State-owned commercial banks in Beijing and Shanghai prioritize these platforms for digital yuan middleware integration mandated by PBOC specifications.
- Risk Management:Real-time quantification engines monitor credit exposure and market volatility. Joint-stock banks in the Yangtze River Delta deploy these modules fastest as household savings migrate toward structured products.
- Wealth Management:Portfolio analytics software serving retail advisory workflows.
- Compliance Solutions:Regulatory reporting automation for SAMR data governance and cross-border flow protocols.
Core Banking dominates installed base. Compliance Solutions is where expansion concentrates.
Client Type:
Retail banks absorb the majority of procurement spend, while credit unions present the longest sales cycles due to governance complexity.
- Retail Banks:Transaction processing and customer-facing digital channels constitute the primary demand source. Provincial and city commercial banks in Jiangsu and Zhejiang drive cloud-native procurement for wealth management modules.
- Investment Firms:Algorithmic trading infrastructure and portfolio management systems.
- Insurance Companies:Policy administration and actuarial modeling platforms.
- Credit Unions:Member-owned cooperatives with constrained IT budgets and extended vendor qualification timelines.
Retail Banks capture volume leadership. Investment Firms are climbing the fastest as asset management liberalization deepens.
Deployment Model:
Cost tiering separates capital-intensive on-premise builds from operational expenditure models favored by mid-tier institutions.
- Cloud-Based:Distributed computing frameworks eliminate data center capital requirements. Joint-stock banks bypass infrastructure builds fastest under state-backed technology modernization fund incentives.
- On-Premise:Privately managed installations at policy banks where data sovereignty mandates prevail and SAMR cybersecurity review protocols impose strictest controls.
- Hybrid:Split architectures balancing sensitive core systems with scalable customer-facing layers.
- SaaS:Subscription licensing for standardized compliance and reporting functions.
On-Premise retains the largest footprint. Cloud-Based is gaining share fastest among joint-stock banks.
Technology:
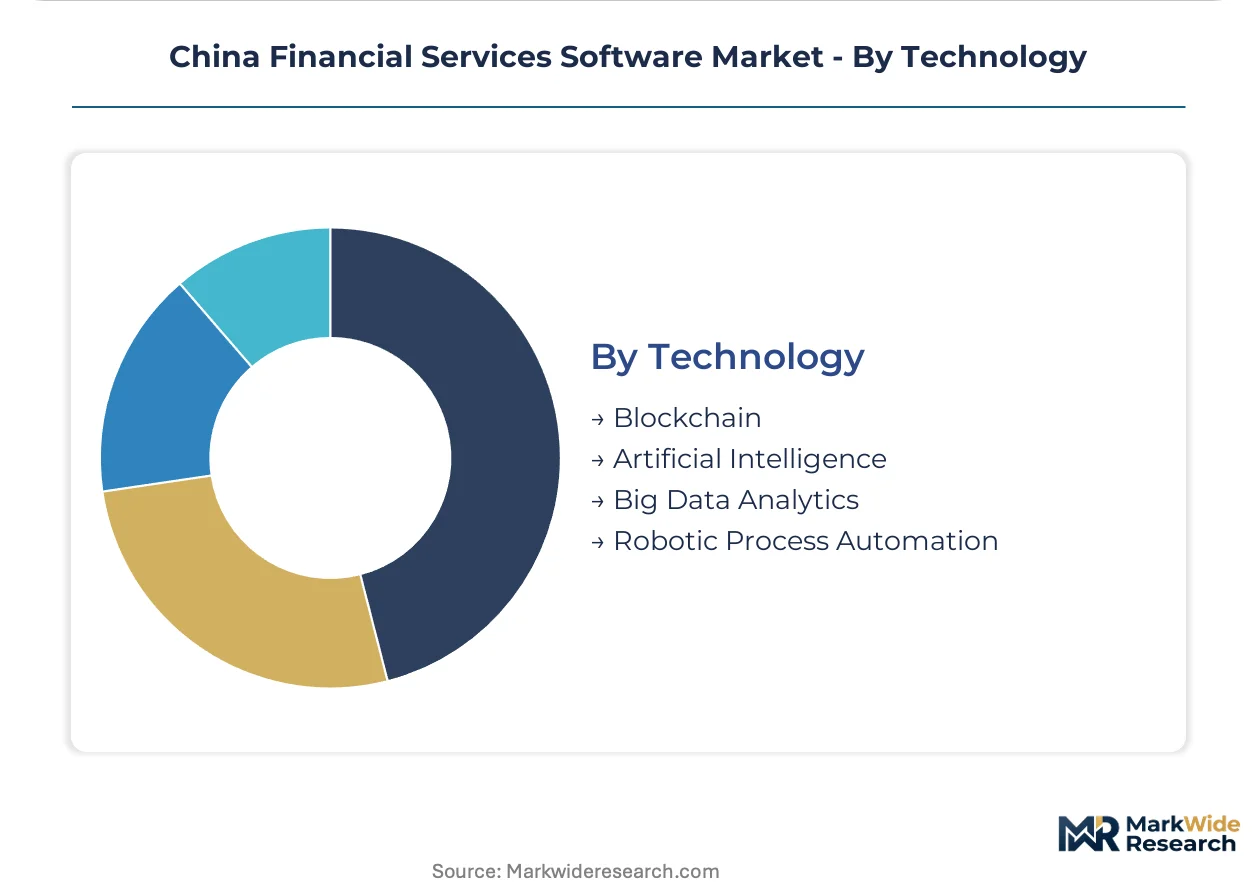
Maturity curves separate production-grade implementations from pilot-phase innovations awaiting regulatory clarity.
- Blockchain:Distributed ledger infrastructure digitizes trade finance workflows and correspondent banking relationships. Guangdong and Fujian joint-stock banks deploy these platforms to capture cross-border renminbi settlement volume.
- Artificial Intelligence:Machine learning models for credit scoring and fraud detection.
- Big Data Analytics:Real-time pipeline integration for customer segmentation and predictive risk modeling.
- Robotic Process Automation:Workflow automation for back-office reconciliation and regulatory reporting.
Big Data Analytics anchors current procurement. Blockchain shows the steepest expansion trajectory as PBOC supervised trade finance infrastructure matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
State-owned commercial banks and joint-stock lenders concentrate procurement authority in coastal megacities, while provincial banks in interior regions lag in cloud-native adoption. SAMR data governance enforcement and PBOC digital yuan specifications create divergent upgrade timelines across sub-regional banking clusters.
Yangtze River Delta
Shanghai and Hangzhou retail banks drive wealth management software procurement as household savings rotate into structured products. SAMR cybersecurity review protocols filter vendor access for cross-border data processing. Jiangsu and Zhejiang joint-stock banks prioritize domestic cloud-native core platforms certified under MIIT GB standards.
Pearl River Delta
Guangdong joint-stock banks accelerate blockchain-enabled trade finance deployment to capture cross-border renminbi settlement volume. PBOC fintech certification programs mandate middleware upgrades for digital yuan compatibility. Shenzhen and Guangzhou institutions unbundle after-sales contracts toward subscription licensing models.
Beijing-Tianjin-Hebei
Policy banks in Beijing maintain on-premise installations under strict data sovereignty mandates despite cloud migration pressure. State-backed technology modernization funds accelerate multi-year implementation cycles for distributed computing frameworks. Tianjin city commercial banks lag state-owned peers in core banking platform refresh rates.
Sichuan-Chongqing
City commercial banks in Chengdu and Chongqing underpenetrate wealth management module deployment relative to coastal peers. SAMR dual carbon goals embedded in procurement criteria favor energy-efficient distributed architectures. Local lenders present white space for compliance-forward vendors with PBOC-certified middleware.
Shandong Peninsula
Qingdao and Jinan retail banks absorb standardized compliance and reporting functions through SaaS deployment models. MIIT technical baselines for financial cloud infrastructure elevate certification costs for foreign suppliers. Provincial institutions balance sensitive core systems with scalable customer-facing layers via hybrid architectures.
China Financial Services Software Market Competitive Landscape
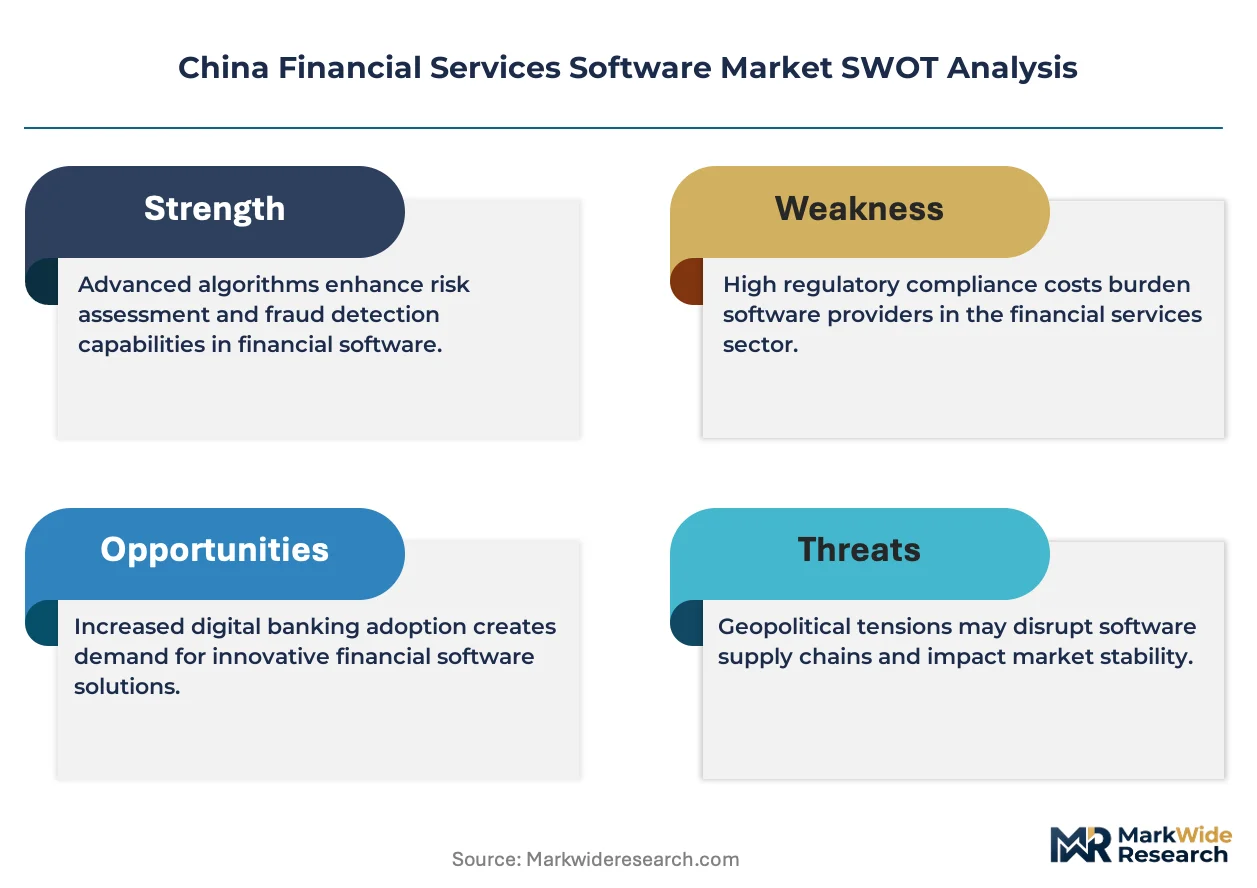
Channel-controlling players compete with product-specialist players across a tiered structure where super-app ecosystems and state-backed banking groups dominate procurement influence. The vendor base separates into three strategic archetypes: ecosystem-embedded technology platforms, state-owned bank captive technology units, and independent core banking specialists. Competitive dynamics center on multi-year implementation cycle absorption capacity and PBOC fintech certification pre-qualification. M&A activity concentrates on blockchain trade finance capability acquisition, while strategic partnerships proliferate around cloud infrastructure certification.
Within the ecosystem-embedded tier, Tencent and Ant Group anchor positions through super-app workflow integration and PBOC-supervised infrastructure development respectively. Industrial and Commercial Bank of China occupies a scale-driven position as a state-owned lender operating privately managed cloud deployments. These three entities exemplify how vendor qualification in China increasingly depends on regulatory relationship depth and captive distribution channel control rather than standalone product differentiation.
| Leading Market Players |
|---|
| China Merchants Bank |
| China Construction Bank |
| Tencent |
| Ant Group |
| China Life Insurance |
| Alibaba Group Holding |
| Industrial and Commercial Bank of China |
| FintechOS |
| Ping An Insurance Group |
| Others |
Pricing and Supply Chain Analysis
Shanghai-Nanjing freight corridors carry cloud infrastructure hardware from Yangtze River Delta manufacturing clusters to Beijing-Tianjin-Hebei policy banks, with logistics cost pass-through intensifying price differentiation between MIIT-certified domestic vendors and foreign suppliers absorbing SAMR cybersecurity review expenses.
Pricing Analysis
Cost-plus contracts with MIIT GB standard indexation dominate procurement for core banking platforms, with state-owned commercial banks negotiating multi-year implementation cycles that bundle customization services. Price differentiation separates PBOC fintech-certified vendors from uncertified competitors, while volume scale discounts favor joint-stock banks in Jiangsu and Zhejiang. Cost compression in SaaS-tiered compliance modules is intensifying because provincial banks are unbundling after-sales contracts toward subscription licensing.
Supply Chain Analysis
Supplier-financing facilities from state-backed technology modernization funds extend payment terms to 36 months for cloud-native core platform deployments, easing cash flow for domestic vendors. Hardware concentrates in China, Taiwan, and South Korea. Software development draws from distributed engineering teams across Beijing, Shanghai, and Hangzhou. Single-source vulnerability sits with Ant Group's blockchain-enabled trade finance infrastructure. Distribution runs through direct enterprise sales teams and super-app ecosystem embedding.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges as PBOC digital yuan specifications force simultaneous core system overhauls across provincial and city commercial banks, creating vendor qualification niches for compliance-forward specialists.
For Market Incumbents: Build regulatory relationship moats through PBOC fintech certification pre-qualification and MIIT GB standard compliance investment. Deepen vertical integration into cloud infrastructure certification to capture state-backed technology modernization fund flows. Acquire blockchain trade finance capability to defend against Ant Group's infrastructure dominance. For New Entrants and Emerging Players: Sichuan and Shaanxi city commercial banks present underpenetrated wealth management module deployment relative to Yangtze River Delta peers. Target compliance solutions for SAMR dual carbon procurement criteria in western provinces. Bypass traditional enterprise sales cycles through super-app ecosystem embedding partnerships. For Investors and Strategic Acquirers: Carve-out targets emerge from state-owned bank captive technology units seeking operational independence from parent lenders. Five-to-ten year viability hinges on multi-year implementation cycle absorption capacity. Monitor PBOC digital yuan middleware specification releases as inflection indicator for core banking upgrade demand.| Strategic Initiative | Industry Significance |
|---|---|
| PBOC Fintech Certification Investment | Pre-qualifies vendors for digital yuan middleware integration mandates across provincial banks. |
| Blockchain Trade Finance Acquisition | Captures cross-border renminbi settlement volume in Guangdong and Fujian joint-stock banks. |
| Cloud-Native Core Platform Launch | Addresses state-backed fund incentives for distributed computing frameworks in Beijing and Shanghai. |
| Super-App Ecosystem Partnership | Embeds financial services software directly into Tencent's consumer workflow infrastructure. |
| Western Province Geographic Expansion | Targets Sichuan-Chongqing white space in wealth management module deployment. |
Research Methodology
Initial hypotheses were tested against primary input from chief technology officers at state-owned commercial banks, IT procurement officers at joint-stock banks, PBOC fintech certification specialists, and cloud infrastructure engineers, and refined through secondary validation against SAMR regulatory filings, MIIT GB standard documentation, PBOC digital yuan technical specifications, and provincial bank annual procurement disclosures. Bottom-up vendor revenue aggregation and top-down banking IT spend allocation were triangulated.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, with segmentation modeled across deployment model, client type, product category, and regional adoption pattern. CAGRs were derived from installed base turnover rates and replacement cycle compression under regulatory pressure. Forecast inputs incorporated PBOC middleware specification timelines and SAMR cybersecurity review protocol expansion.
The forecast holds incumbent behavior within observed patterns; aggressive ecosystem embedding moves by Tencent or Ant Group would shift outcomes. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Financial Services
Intellectual Property Valuation Market
Financial Services
Debt Collection Software and Service Market
Financial Services
India Payroll Services Market
Financial Services
Hong Kong Trade Finance Market
Financial Services
China Trade Finance Market
Financial Services
E-KYC Market
Financial Services
Check Cashing Services Market
Financial Services
White Glove Services Market
Financial Services
Hyperinflation System Market
Financial Services
Global Management Consulting Services Market
Financial Services
Asia-Pacific Factoring Services Market
Financial Services
E-Brokerage Market
Financial Services
Middle East Financial Consulting Software Market
Financial Services
Cash Flow Market
Financial Services
Spain E-Brokerage Market
Financial Services
Virtual Account Management Software Market