
 White Glove Services Market | 2026-2036
White Glove Services Market Size, Share, and Industry Trends Forecast 2026-2036
White Glove Services Market Insights
Healthcare logistics is restructuring the White Glove Services landscape as hospital systems demand temperature-controlled medical equipment delivery with real-time chain-of-custody documentation. XPO leverages specialized fleet assets to dominate high-value medical freight corridors. FedEx sustains brand strength through premium residential installation networks. Werner Enterprises anchors long-haul capacity for regional white-glove redistribution.
White glove services constitute premium logistics solutions involving specialized handling, inside delivery, assembly, installation, and debris removal—typically requiring two-person crews, padded vehicles, and real-time customer communication protocols with appointment windows narrowed to two-hour slots. The service spans fragile electronics, medical imaging equipment, and custom furniture where damage tolerance approaches zero. Installation services command the deepest margin pools as technical competency requirements rise. Subscription delivery models are expanding fastest among commercial clients seeking predictable cadence for recurring equipment refreshes. The hospitality vertical remains mature, with established protocols limiting pricing flexibility.
FDA device-handling regulations and DOT hours-of-service rules shape crew scheduling and vehicle certification requirements across interstate operations. EPA emissions standards are accelerating fleet turnover toward alternative-power vehicles in urban delivery zones. OSHA workplace safety mandates govern two-person lift protocols and residential entry procedures. Stakeholders must weigh capital allocation between autonomous routing investments and specialized technician training pipelines.
Market Dynamics
Hospital procurement consolidation is forcing white-glove providers to restructure fleet deployment around multi-site delivery windows and unified chain-of-custody platforms. EPA emissions mandates for last-mile vehicles are simultaneously accelerating capital turnover toward electric and alternative-fuel chassis.
Growth Catalysts
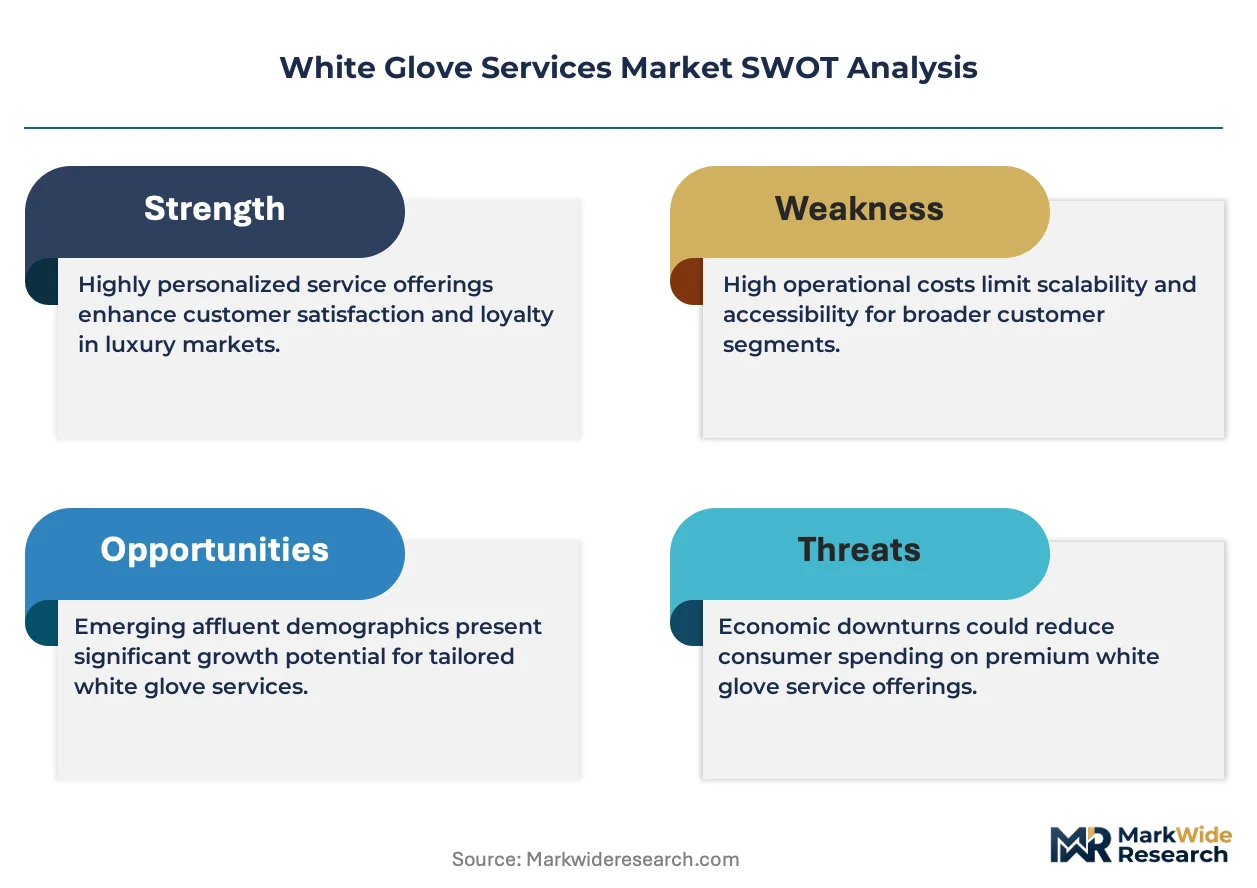
- FDA device-handling regulations:Stringent chain-of-custody requirements for medical imaging equipment create mandatory demand for certified two-person crews and temperature-monitored vehicles.
- Germany's precision manufacturing corridor:Industrial clusters around Stuttgart and Munich generate sustained demand for specialized handling protocols for fragile production equipment.
- Real-time GPS and IoT sensor integration:Fleet telematics enable two-hour appointment windows with live customer communication, expanding addressable market for premium residential delivery.
Market Restraints
- Specialized technician labor scarcity:Two-person crew certification requirements and OSHA lift protocols constrain workforce scalability across interstate operations.
- Alternative-power vehicle capital intensity:EPA urban emissions standards force premature fleet turnover before diesel asset depreciation cycles complete.
- DOT hours-of-service compliance:Interstate crew scheduling limitations compress daily delivery throughput and extend route completion timelines.
Strategic Opportunities
- Subscription commercial delivery models:Recurring equipment refresh cycles among healthcare networks create predictable revenue streams with higher lifetime value than transactional freight.
- India's expanding hospital infrastructure:Greenfield medical facility construction in tier-2 cities generates demand for inaugural equipment installation services with training components.
- EU Green Deal fleet incentives:Member-state subsidies for electric commercial vehicles reduce capital barriers for zero-emission last-mile operations in urban zones.
Industry Challenges
- Technician training pipeline gaps:Medical equipment installation competency requires manufacturer-specific certification timelines that lag demand growth.
- Legacy warehouse management integration:Real-time customer communication platforms must interface with existing hospital inventory systems without disrupting procurement workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | White Glove Services Market |
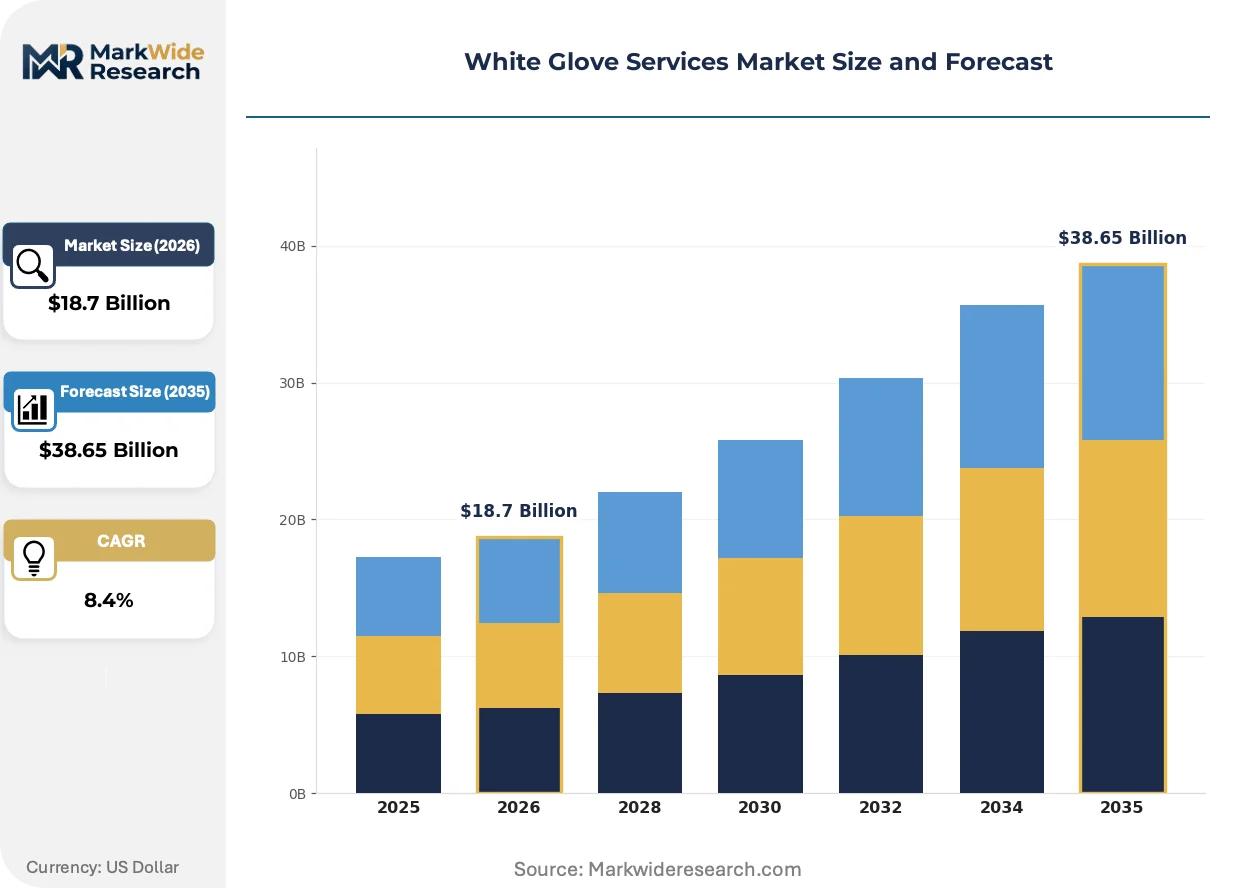
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Installation, Transportation, Packaging, Maintenance Client Type: Residential, Commercial, Hospitality, Retail Industry Vertical: Healthcare, IT, Furniture, Logistics Delivery Model: On-Demand, Subscription, One-Time, Contractual |
| Companies Covered | Fidelitone Last Mile Inc, Werner Enterprises, XPO, UPS, FedEx, SEKO Logistics, J.B. Hunt Transport, DB Schenker Logistics, Ryder, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
White Glove Services Market Trends and Innovations
Fleet electrification and modular service architectures are restructuring how white-glove providers configure crew deployment and customer-facing technology stacks. Regulatory pressure on emissions and medical device handling is simultaneously accelerating equipment turnover and compliance investment.
Telematics platforms with predictive routing algorithms are modularizing how dispatchers allocate two-person crews across fragmented delivery windows. Hospital networks and furniture retailers are adopting these systems fastest, compressing route density requirements and forcing smaller operators to consolidate or exit metropolitan markets.
EPA emissions standards for urban last-mile fleets are mandating alternative-power vehicle procurement ahead of natural replacement cycles. California's Advanced Clean Trucks regulation and pending federal standards are redirecting capital toward electric chassis and charging infrastructure. Medical equipment corridors face the steepest compliance costs due to payload and range requirements.
Healthcare procurement teams are consolidating vendor relationships around integrated delivery-installation-training bundles. Single-source contracts are displacing fragmented freight-plus-installation arrangements. This concentration is most visible in US hospital network RFPs, where total cost of ownership metrics now subsume pure transportation pricing.
White Glove Services Market Segmentation
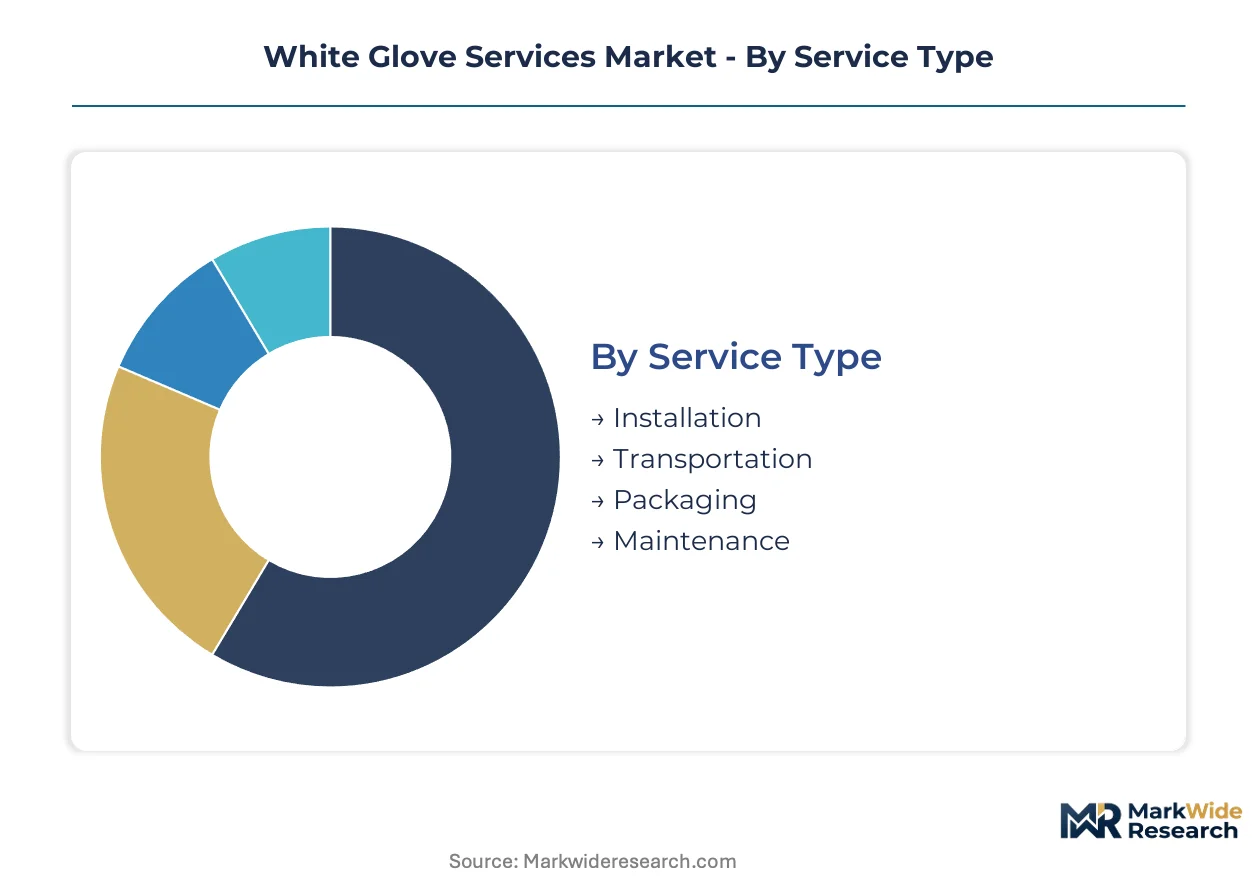
White glove providers configure crew certification, vehicle specifications, and customer communication protocols around distinct service archetypes. Segmentation determines capital allocation between specialized medical fleets and flexible residential assets.
Service Type:
FDA chain-of-custody requirements apply selectively across service types, with medical equipment segments demanding temperature-monitored vehicles and two-person certified crews.
- Installation:Technical assembly of medical imaging equipment and custom furniture demands manufacturer-specific technician certification. Hospital procurement consolidation around single-source contracts elevates this segment's margin profile and credential requirements.
- Transportation:Padded vehicle fleets with real-time GPS tracking handle fragile electronics and precision manufacturing equipment. Germany's Stuttgart-Munich industrial corridor generates sustained demand for specialized handling protocols with zero damage tolerance.
- Packaging:Custom crating and debris removal services support high-value residential deliveries. EPA emissions standards for last-mile urban fleets constrain vehicle selection for packaging crews operating in metropolitan zones.
- Maintenance:Recurring service contracts for medical equipment and hospitality assets require predictive scheduling platforms. Subscription models expand fastest among healthcare networks seeking predictable equipment refresh cadences.
Installation sits at the top of the volume ranking, with Maintenance climbing the fastest.
Client Type:
Cost tier stratification separates enterprise healthcare contracts from transactional residential deliveries, with hospitality occupying a mature pricing band.
- Residential:Premium inside delivery with two-hour appointment windows and debris removal. Real-time customer communication protocols and IoT sensor integration compress delivery windows and expand addressable market.
- Commercial:Hospital networks and corporate campuses demand unified chain-of-custody platforms across multi-site delivery windows. Procurement consolidation forces providers to restructure fleet deployment around consolidated vendor relationships.
- Hospitality:Established protocols for furniture and fixture installation limit pricing flexibility. Mature service standards constrain differentiation opportunities compared to healthcare verticals.
- Retail:High-value electronics and appliance delivery with assembly services. Telematics platforms enable route density optimization across fragmented metropolitan delivery zones.
Commercial commands the deepest revenue pools, with Residential gaining share fastest.
Industry Vertical:
Application-specific requirements determine crew training pipelines, with medical equipment installation requiring the steepest certification timelines.
- Healthcare:Temperature-controlled medical equipment delivery with FDA-mandated chain-of-custody documentation. DOT hours-of-service rules and OSHA two-person lift protocols constrain crew scheduling across interstate hospital networks.
- IT:Fragile server and networking equipment handling for data center deployments. Precision requirements align with capabilities developed for medical imaging logistics.
- Furniture:Custom residential and commercial installation with assembly and debris removal. Established competitive dynamics limit margin expansion compared to technical verticals.
- Logistics:Regional redistribution and last-mile fulfillment partnerships. Werner Enterprises anchors long-haul capacity feeding into specialized white-glove final delivery.
Healthcare anchors vertical demand, with IT expanding most quickly.
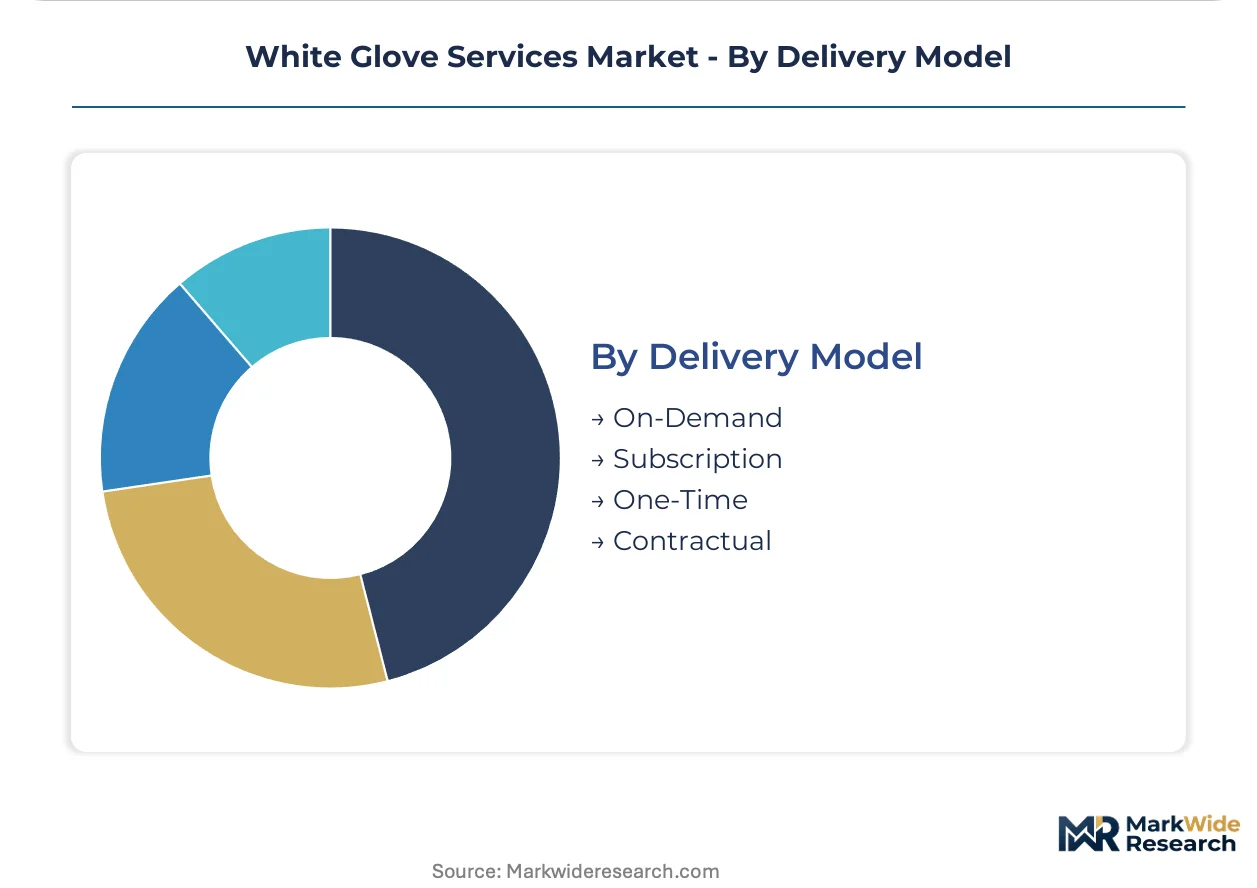
Delivery Model:
Volume concentration favors contractual arrangements, while subscription architectures reshape customer lifetime value calculations.
- On-Demand:Expedited response for critical medical equipment failures and emergency hospitality replacements. Premium pricing reflects crew availability constraints and compressed scheduling windows.
- Subscription:Recurring equipment refresh cycles among healthcare networks create predictable revenue streams. EU Green Deal fleet incentives reduce capital barriers for zero-emission subscription operations in urban zones.
- One-Time:Transactional residential and retail deliveries with limited customer retention value. Telematics investment proves difficult to amortize across sporadic demand patterns.
- Contractual:Multi-year agreements with hospital networks and hospitality chains covering integrated delivery-installation-training bundles. India's greenfield medical facility construction generates demand for inaugural installation services with training components.
Contractual arrangements dominate volume, with Subscription climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage in fleet emissions compliance is redirecting white-glove investment toward jurisdictions with phased EPA mandates and EU Green Deal subsidies. Cost-of-compliance gaps between California's Advanced Clean Trucks regulation and Midwestern state timelines are reshaping where specialized medical logistics fleets deploy capital.
United States
Hospital procurement consolidation across IDN networks is forcing white-glove providers to restructure around multi-site delivery windows. FDA chain-of-custody requirements for medical imaging equipment intersect with DOT hours-of-service rules to constrain interstate crew scheduling. The Boston-Cambridge medical corridor generates concentrated demand for temperature-monitored pharmaceutical deliveries with real-time documentation.
Germany
Precision manufacturing clusters around Stuttgart and Munich sustain demand for specialized handling protocols with zero damage tolerance. EU Green Deal fleet incentives reduce capital barriers for electric commercial vehicles in urban last-mile zones. The Baden-Württemberg industrial belt anchors specialized freight corridors serving automotive and medical device producers with certified two-person crews.
China
Tier-2 city hospital infrastructure expansion is generating inaugural equipment installation demand with training components. National dual carbon goals are accelerating alternative-power vehicle procurement ahead of natural replacement cycles. The Yangtze River Delta medical device manufacturing belt concentrates outbound white-glove logistics for domestic hospital networks.
India
Greenfield medical facility construction in tier-2 cities is creating demand for integrated delivery-installation-training bundles. PLI scheme incentives for medical device manufacturing are expanding the addressable market for certified handling services. The Delhi-Mumbai Industrial Corridor anchors regional redistribution networks feeding specialized last-mile operations.
United Kingdom
NHS procurement consolidation around single-source logistics contracts is displacing fragmented freight-plus-installation arrangements. CSRD reporting requirements are pressuring fleet operators to accelerate zero-emission vehicle transitions. The Greater London metropolitan zone concentrates premium residential white-glove demand with compressed two-hour appointment windows.
White Glove Services Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated logistics networks commanding hospital procurement contracts while regional specialists retain residential installation niches. The vendor base organizes into three tiers: national parcel carriers with white-glove extensions, dedicated last-mile specialists, and asset-light technology platforms. Dominant competitive moves include fleet electrification partnerships and technician certification pipeline investments.
Within the integrated carrier tier, FedEx and UPS occupy positions exemplifying premium residential network scale, while XPO represents specialized medical freight corridor dominance. Werner Enterprises anchors long-haul capacity feeding regional white-glove redistribution. SEKO Logistics sits within the dedicated specialist archetype, reflecting contract logistics configurations serving healthcare verticals with unified chain-of-custody platforms.
| Leading Market Players |
|---|
| Fidelitone Last Mile Inc |
| Werner Enterprises |
| XPO |
| UPS |
| FedEx |
| SEKO Logistics |
| J.B. Hunt Transport |
| DB Schenker Logistics |
| Ryder |
| Others |
Pricing and Supply Chain Analysis
EPA emissions mandates for last-mile urban fleets gate qualified supply to providers with electric chassis procurement capacity, simultaneously filtering premium-tier pricing access to operators who absorb accelerated capital turnover before diesel depreciation cycles complete. Hospital procurement consolidation around single-source contracts reinforces this bifurcation, concentrating margin pools with certified medical logistics specialists while transactional residential tiers face cost compression.
Pricing Analysis
Distributor margin compression runs through fragmented residential installation networks as telematics platforms enable route density optimization. Three-tier pricing structure across premium certified medical, standard commercial, and economy residential levels separates FDA-chain-of-custody installations from basic inside delivery. Pricing pressure stems from alternative-power vehicle capital intensity as EPA urban mandates force premature fleet replacement. Hospital networks exhibit lowest price sensitivity due to total-cost-of-ownership procurement metrics, while furniture retailers face acute margin compression.
Supply Chain Analysis
Single-source vulnerability sits with lithium-ion battery cell production concentrated in China, South Korea, and Japan for electric commercial vehicle chassis deployed in urban last-mile zones. Specialized padded vehicle bodies draw from regional coachwork manufacturers in Germany and the United States. Supply chain risk centers on semiconductor allocation constraints for telematics and IoT sensor integration. Distribution runs through integrated carrier networks feeding dedicated last-mile specialists with unified chain-of-custody platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
White glove services present a margin-expansion trajectory anchored by subscription commercial models that convert transactional freight into predictable recurring revenue with embedded installation training bundles.
For Market Incumbents: Anticipate technician certification pipeline gaps as FDA device-handling regulations tighten manufacturer-specific competency requirements. Defensive consolidation moves include captive training academy investments and backward integration into electric chassis procurement partnerships. Threat concentration sits with asset-light technology platforms modularizing crew dispatch algorithms. For New Entrants and Emerging Players: EU Green Deal fleet incentives in Germany open a window for zero-emission last-mile operations with subsidized electric commercial vehicle deployment. White-space targets include India's tier-2 city hospital infrastructure and precision manufacturing corridors around Stuttgart demanding specialized handling protocols. Go-to-market angle centers on inaugural equipment installation with embedded clinical training components. For Investors and Strategic Acquirers: Valuations sit cheapest among regional residential specialists lacking unified chain-of-custody platforms or certified medical equipment competencies. Long-term viability favors operators with subscription revenue concentration above transactional mix. Acquisition target archetype: dedicated healthcare logistics providers with FDA-certified crew pipelines. Signal to watch is hospital procurement RFP language shifting from transportation pricing to total-cost-of-ownership metrics.| Strategic Initiative | Industry Significance |
|---|---|
| Electric Fleet Transition | EPA emissions mandates force alternative-power chassis procurement ahead of natural replacement cycles. |
| Technician Certification Pipeline | FDA device-handling regulations require manufacturer-specific competency timelines that lag demand growth. |
| Subscription Model Expansion | Healthcare network equipment refresh cycles convert transactional freight into predictable recurring revenue streams. |
| Unified Chain-of-Custody Platform | Hospital procurement consolidation displaces fragmented freight-plus-installation arrangements with single-source contracts. |
| Telematics Integration Partnership | Real-time GPS and IoT sensor deployment compresses appointment windows and expands premium residential addressable market. |
Research Methodology
Multiple input streams — hospital procurement database analysis, fleet operator financial disclosures, and regulatory filing review — were reconciled with primary interviews conducted across logistics operations directors, biomedical engineering managers, GPO contracts administrators, and EPA compliance officers. Secondary validation drew from DOT hours-of-service enforcement data, FDA medical device handling guidance, EU Green Deal implementation documents, and customs records for specialized vehicle chassis trade flows. Bottom-up crew deployment modeling and top-down market sizing triangulated volume estimates.
Data-stream reconciliation across service type, client tier, industry vertical, and delivery model dimensions structured the analytical framework throughout the projection horizon. CAGRs were derived from segmented growth rate reconciliation against macroeconomic freight demand indicators. Industry-specific forecast inputs included hospital capital expenditure cycles for medical equipment refresh and precision manufacturing output trajectories in Germany's industrial corridor.
Revisions become necessary when EPA emissions standard implementation timelines accelerate, battery cell supply constraints deepen, or hospital procurement consolidation patterns shift toward insourced logistics operations. Forecasts reflect assumptions about technician certification pipeline expansion rates and electric vehicle charging infrastructure deployment density. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Financial Services
E-Invoicing Market
Financial Services
Source to Pay Market
Financial Services
Germany E-Brokerage Market
Financial Services
Cash Logistics Market
Financial Services
Saas Escrow Services Market
Financial Services
Banking Cloud Services Market
Financial Services
Direct Selling Market
Financial Services
Germany Factoring Services Market
Financial Services
Spain E-Brokerage Market
Financial Services
North America B2B Legal Services Market
Financial Services
Solar Powered ATM Market
Financial Services
Mobile Notary Public Market
Financial Services
Global Treasury Software Market
Financial Services
US Healthcare Finance Solutions Market
Financial Services
Liquidation Service Market
Financial Services
Outsource Debt Collection Services Market