
 Check Cashing Services Market | 2026-2036
Check Cashing Services Market Size, Share, and Industry Trends Forecast 2026-2036
Check Cashing Services Market Analysis
A capital-intensity divergence between branch-heavy incumbents and digital-first entrants is redrawing competitive boundaries in check cashing. Wells Fargo & Company leverages its existing branch infrastructure to sustain low-cost check cashing at scale, while ACE Cash Express anchors its position through dense urban storefront networks in underserved neighborhoods. Green Dot Corporation differentiates via prepaid card-linked mobile channels that reduce physical overhead.
Check cashing services convert paper instruments into immediately available funds through verification, risk assessment, and liquidity provision against payroll, government, personal, and business checks. Providers typically charge flat fees or percentage-based rates, with settlement speed ranging from instant to 24 hours depending on verification protocols and check type. In-store service still dominates transaction volume, though mobile and online channels capture the fastest growth as smartphone penetration deepens among underbanked populations; fee structures increasingly stratify around membership models that improve retention. Payroll and government checks represent the most mature, high-frequency segments, while business check cashing commands premium pricing due to higher average ticket sizes and specialized verification requirements.
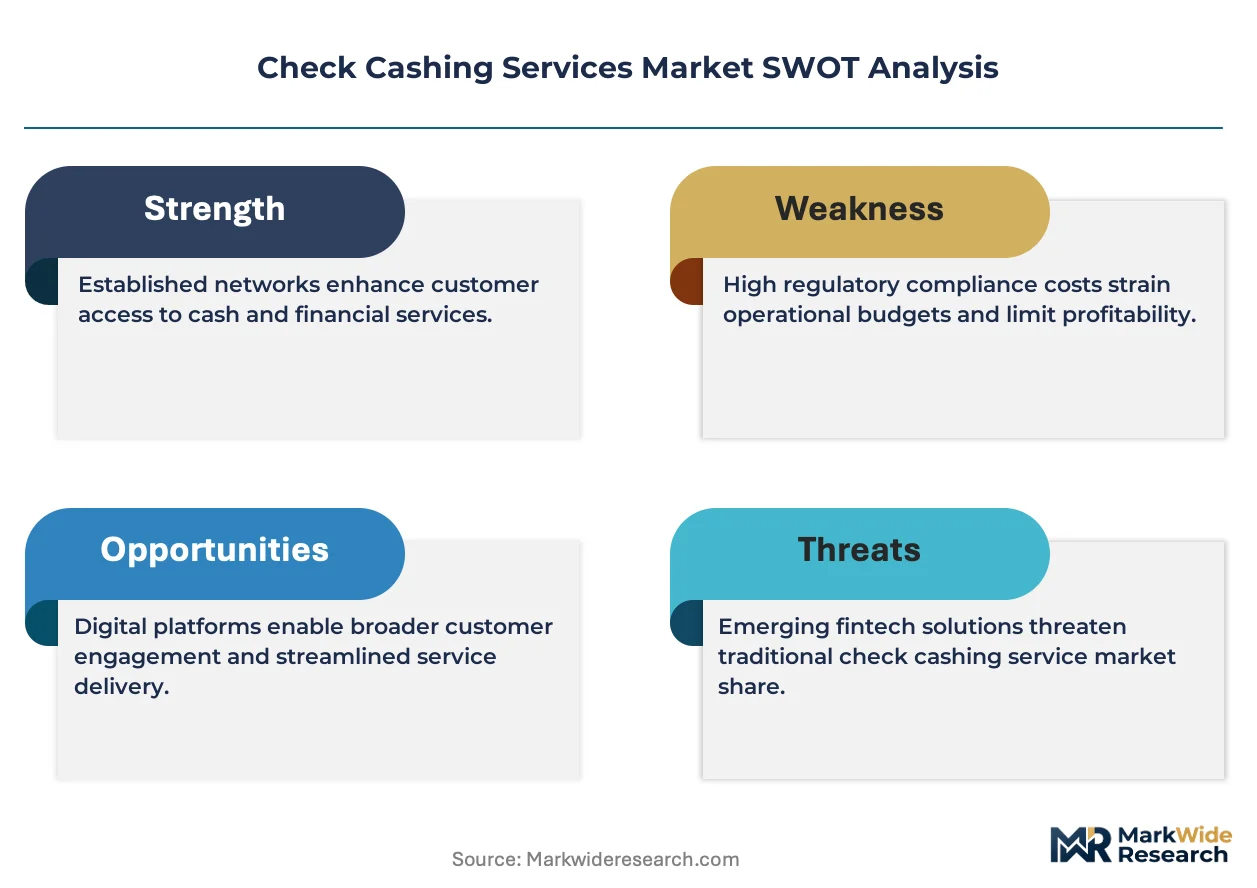
The US market navigates overlapping oversight from state banking regulators, the Financial Crimes Enforcement Network under anti-money laundering protocols, and the Consumer Financial Protection Bureau on fee transparency and fair lending practices. State-level money transmitter licensing creates fragmented compliance burdens that favor multi-state operators with dedicated legal infrastructure. Stakeholders must monitor evolving real-time payment adoption at the Federal Reserve and competing fintech entrants that could disintermediate traditional check cashing with lower-cost instant settlement alternatives.
Market Dynamics
Real-time payment rails and mobile wallet integration are compressing settlement timelines for check cashing providers, forcing incumbents to digitize verification workflows or surrender volume to fintech alternatives with instant liquidity.
Growth Catalysts
- Unbanked Population Expansion:Federal Reserve real-time payment infrastructure reduces interbank settlement friction, enabling providers to offer faster fund availability that attracts underbanked consumers away from traditional banking.
- Payroll Check Modernization:Employers in high-turnover sectors continue issuing paper checks to temporary workers, sustaining transaction volume at urban storefront locations.
- Regulatory Clarity on Digital Channels:State-level money transmitter licensing frameworks are gradually harmonizing around mobile-first verification standards, reducing compliance barriers for digital entrants.
Market Restraints
- Anti-Money Laundering Compliance Burden:Financial Crimes Enforcement Network reporting requirements impose fixed operational costs that disproportionately burden small, single-location operators.
- Check Volume Decline:Direct deposit adoption and earned wage access apps are structurally displacing paper payroll instruments in middle-income demographics.
- Banking Deserts Concentration:Branch closures by major depository institutions have concentrated demand in specific urban corridors, creating geographic dependency risk for storefront networks.
Strategic Opportunities
- Embedded Finance Partnerships:Retailers and gig economy platforms present white-label check cashing integration opportunities that bypass standalone storefront costs.
- Government Benefit Distribution:State-level social service agencies are exploring public-private partnerships for instant benefit check conversion.
- Biometric Verification Convergence:Facial recognition and document authentication technologies are converging to enable remote check deposit with fraud rates comparable to in-person verification.
Industry Challenges
- Legacy Core System Integration:Incumbent providers face execution complexity when retrofitting decades-old transaction processing infrastructure to support real-time settlement APIs.
- Specialized Compliance Talent Scarcity: Recruiting professionals with expertise in both state money transmitter law and federal Bank Secrecy Act protocols strains human resources functions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Check Cashing Services Market |
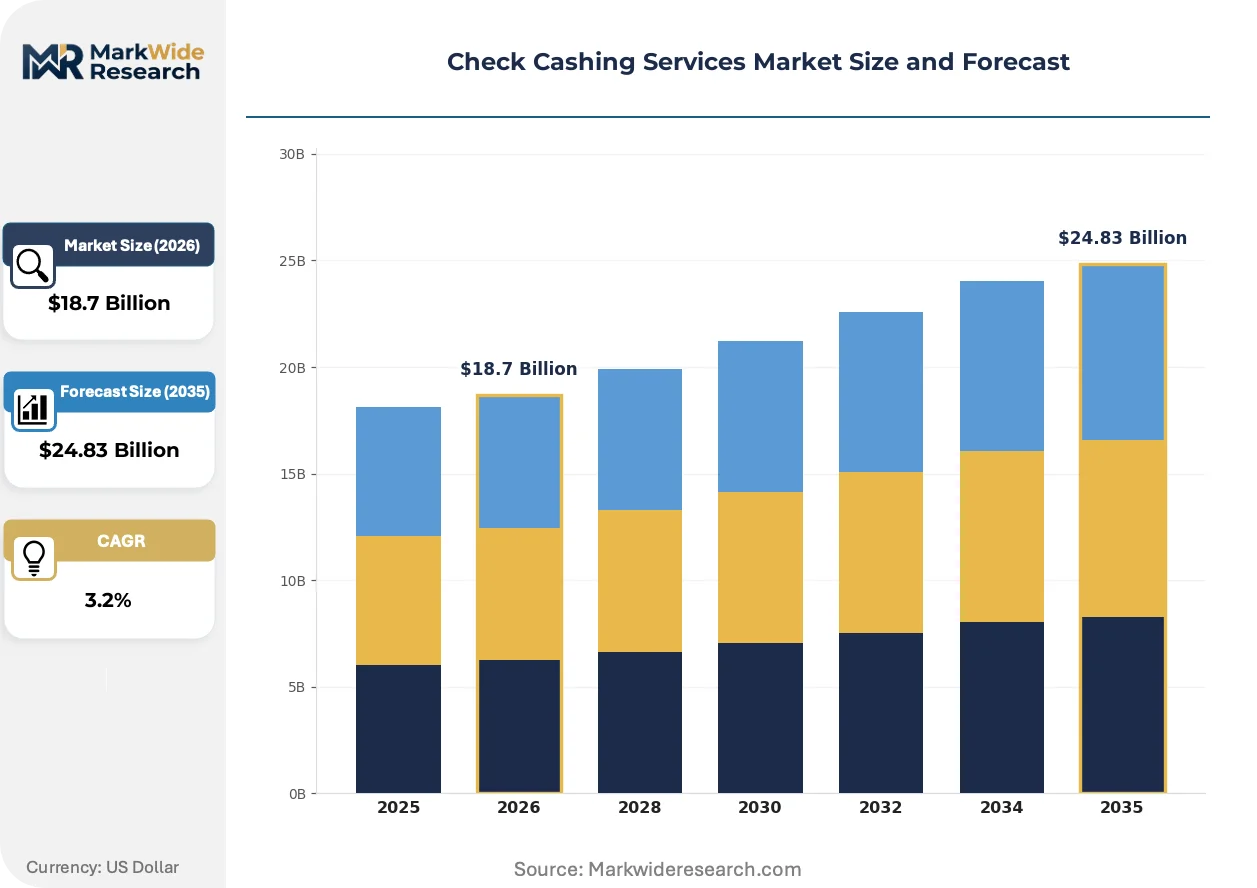
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $24.83 Billion |
| CAGR (2026 – 2036) | 3.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: In-Store, Online, Mobile, Kiosk Customer Type: Individual Consumers, Small Businesses, Corporates, Nonprofits Fee Structure: Flat Fee, Percentage of Check, Membership Fee, Subscription Check Type: Payroll Checks, Government Checks, Personal Checks, Business Checks |
| Companies Covered | Wells Fargo & Company, Truist Financial Corporation, ACE Cash Express, PLS Financial Services, The PNC Financial Services Group, Check Into Cash, U.S. Bancorp, Green Dot Corporation, Speedy Cash, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Check Cashing Services Market Emerging Trajectories
Artificial intelligence and biometric authentication are compressing identity verification timelines, while regulatory pressure on fee transparency is forcing providers to unbundle pricing and compete on disclosed cost structures rather than obscured margins.
Mobile check capture with AI-powered fraud detection is fragmenting the traditional branch-based model. Underbanked consumers with limited banking relationships are adopting smartphone deposit at accelerating rates. This technology is fragmenting geographic capture of transactions away from fixed storefront locations toward distributed, app-based origination.
The Consumer Financial Protection Bureau's scrutiny of fee disclosure practices is intensifying compliance requirements. Providers must now itemize verification, processing, and expedited settlement charges separately. Small multi-state operators are responding by consolidating legal infrastructure to manage fragmented state-level transparency mandates.
Subscription-based membership models are displacing per-transaction pricing among frequent users. Check cashing providers in high-volume urban corridors are bundling unlimited processing with prepaid card loyalty programs. This shift is most visible in Texas and Florida metro areas where payroll check concentration supports recurring revenue economics.
Check Cashing Services Market Segmentation
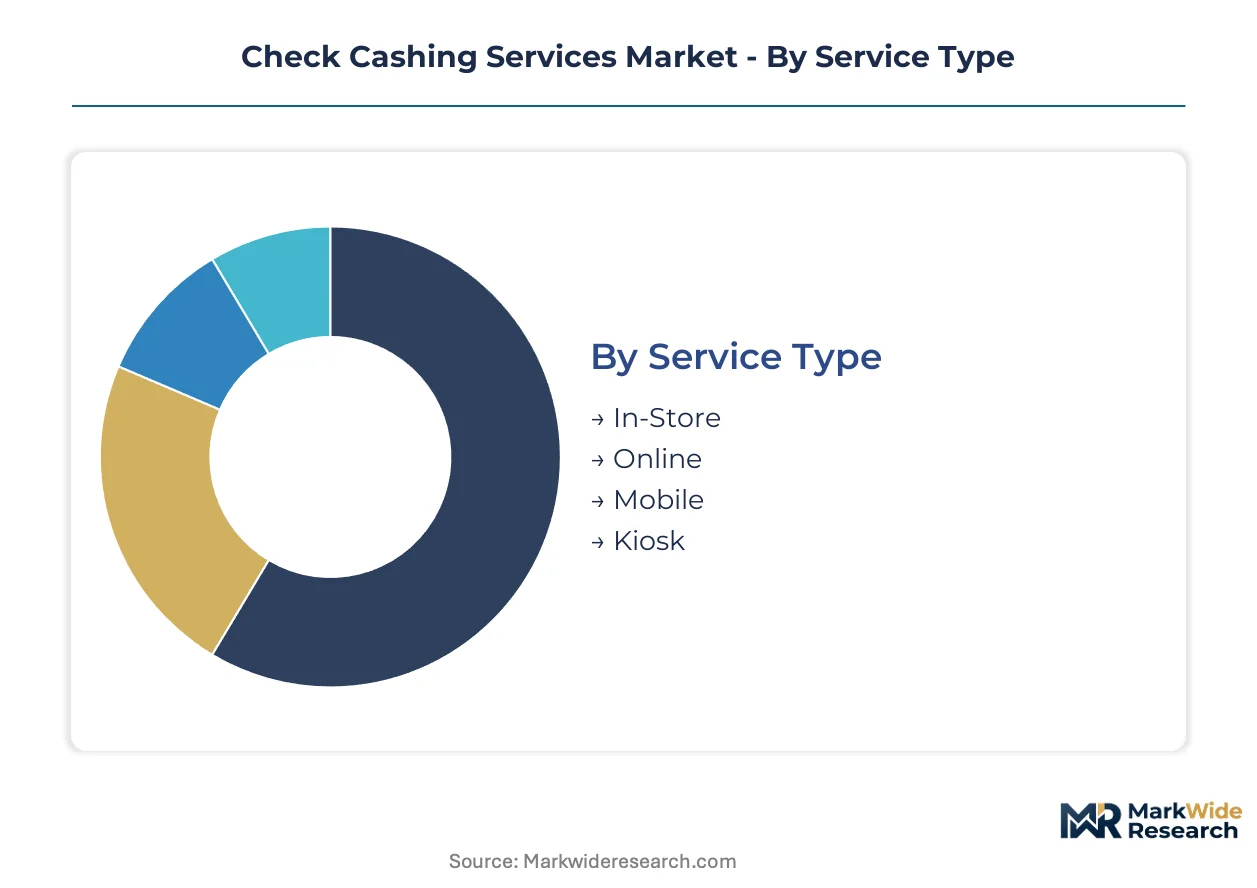
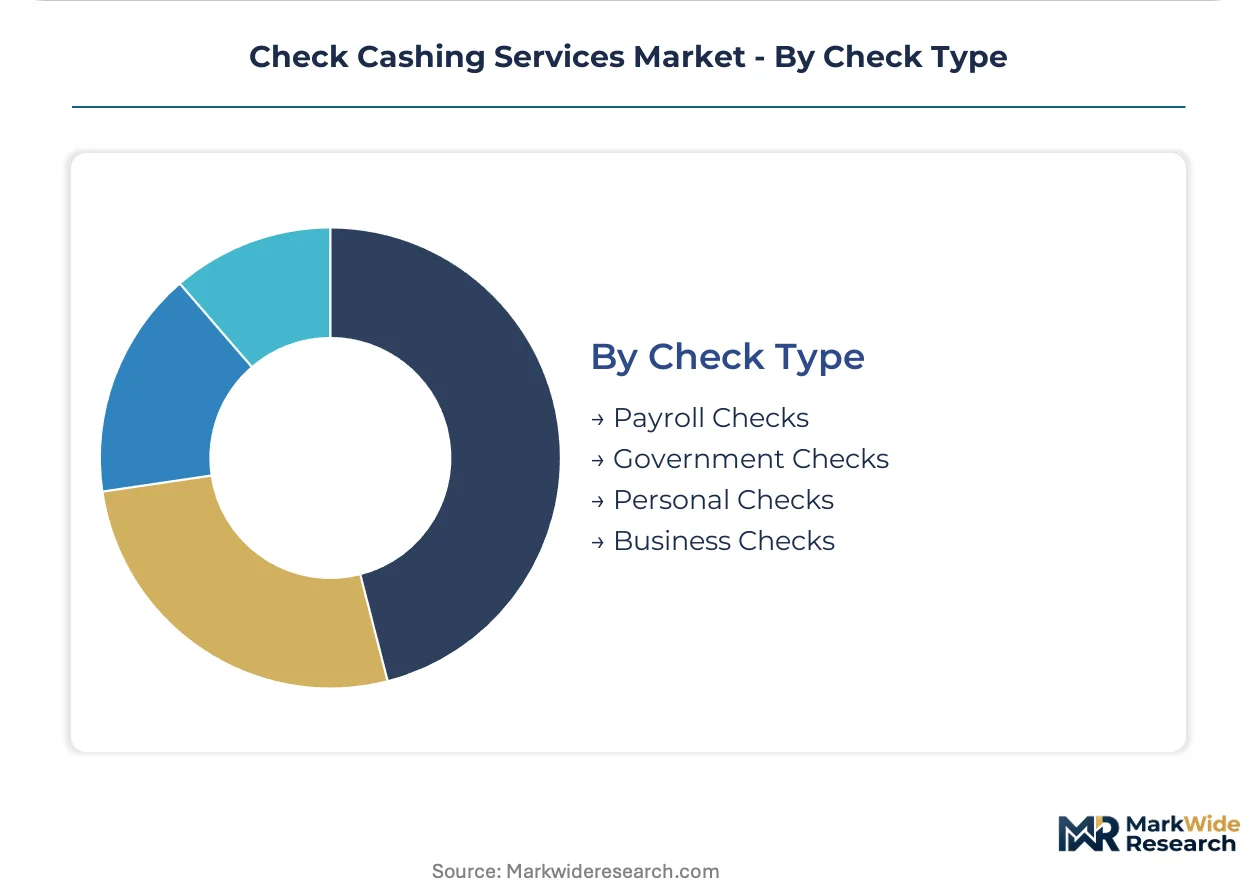
Check cashing services fragment across four distinct dimensions that shape how providers configure operations, price risk, and deploy capital. Service type determines physical versus digital infrastructure requirements. Customer type governs compliance intensity and average transaction values. Fee structure and check type together define margin profiles and fraud exposure curves.
Service Type:
Channel mix varies sharply by customer liquidity needs and smartphone penetration, with urban storefronts retaining dominance for unbanked cash-seekers while mobile capture expands fastest among younger demographics.
- In-Store:Physical branch locations deliver immediate cash disbursement against verified paper instruments. Demand concentrates in Texas and Florida metro corridors where payroll check volume sustains dense storefront networks and banking deserts limit alternatives.
- Mobile:Smartphone-based capture with AI-powered fraud detection enables remote deposit and prepaid card loading. This channel is expanding most quickly among underbanked populations with limited traditional banking relationships, fragmenting geographic transaction capture away from fixed locations.
- Online:Web-based portals support check upload and ACH transfer to linked accounts, serving customers with existing bank relationships seeking faster clearing.
- Kiosk:Self-service terminals in retail environments offer limited-hour cash access with reduced staffing overhead, common in grocery and convenience store deployments.
By volume, In-Store leads. By growth pace, Mobile is ahead.
Customer Type:
Cost tier stratification separates high-frequency low-margin retail processing from specialized commercial verification with premium pricing.
- Individual Consumers:Unbanked and underbanked households seeking immediate liquidity against payroll or government instruments. This segment commands the largest transaction count but faces margin pressure from regulatory fee disclosure requirements.
- Small Businesses:Cash-intensive enterprises lacking traditional banking relationships, generating higher average ticket sizes with specialized verification needs for business instrument authenticity.
- Corporates:Large employers and payment processors requiring bulk check conversion services, typically negotiated on volume-based pricing with dedicated account management.
- Nonprofits:Social service organizations handling donor checks and grant disbursements, often with irregular volume patterns and compliance documentation requirements.
Individual Consumers generate the highest transaction velocity. Small Businesses deliver the strongest per-unit economics.
Fee Structure:
Margin architecture shifts from transactional to recurring revenue as providers compete on retention rather than single-visit extraction.
- Flat Fee:Fixed per-check charges common for standardized payroll instruments, offering price certainty that appeals to occasional users.
- Percentage of Check:Variable pricing tied to instrument face value, standard for large-ticket business checks where absolute fee caps protect customer acceptance.
- Membership Fee:Annual or monthly access charges bundling unlimited processing, gaining traction in high-volume urban corridors where frequent users value predictable costs.
- Subscription:Tiered recurring models combining check cashing with prepaid card loyalty programs and expedited settlement, displacing per-transaction pricing among retained customer bases.
Percentage-based pricing still dominates revenue dollars. Subscription models are climbing the fastest as retention economics improve.
Check Type:
Application-specific risk profiles and verification complexity drive fee differentiation and operational specialization.
- Payroll Checks:Employer-issued wage instruments with standardized formats and established verification databases. This category sustains the highest transaction frequency and lowest fraud rates, anchoring volume for storefront networks.
- Government Checks:Federal and state benefit distributions including tax refunds and social security payments, carrying sovereign backing that reduces risk but requires specialized compliance handling.
- Personal Checks:Individual-to-individual instruments with highest verification burden and return risk, typically commanding premium pricing or extended hold periods.
- Business Checks:Corporate payment instruments with variable formats and higher average values, requiring enhanced authentication protocols and supporting premium fee structures.
Payroll Checks anchor volume throughput. Business Checks command the steepest expansion trajectory in revenue per transaction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in check cashing services remain domestically contained, with minimal cross-border service provision due to regulatory fragmentation. The United States dominates transaction volume and revenue generation, while other developed markets show limited comparable infrastructure. Emerging economies present nascent alternative financial service growth.
United States
Banking deserts across Texas and Florida metro corridors sustain dense storefront networks serving unbanked payroll check recipients. State-level money transmitter licensing under the Bank Secrecy Act creates compliance complexity that favors multi-state operators with dedicated legal infrastructure. Los Angeles and Houston anchor the highest transaction density, where ACE Cash Express and PLS Financial Services maintain overlapping urban coverage.
Canada
Underbanked populations in Toronto and Vancouver drive demand for alternative financial services despite higher traditional banking penetration than the US. The Financial Consumer Agency of Canada oversees fee transparency mandates that exceed US disclosure requirements. Ontario's Greater Toronto Area concentrates provider activity, where Money Mart and Cash Money operate extensive retail networks.
Mexico
Remittance-linked financial inclusion programs expand formal banking access while informal check cashing persists in northern border states. The National Banking and Securities Commission regulates non-bank financial service providers under fintech-specific licensing frameworks. Ciudad Juárez and Tijuana cluster demand from cross-border workers receiving US payroll instruments.
United Kingdom
Post-office based financial services and credit union networks reduce pure check cashing demand compared to North American markets. The Financial Conduct Authority governs consumer credit and payment services with stricter affordability assessments than US counterparts. London's outer boroughs retain limited specialty providers serving immigrant communities with irregular banking documentation.
Australia
High traditional banking penetration and declining paper check usage compress standalone check cashing to niche remittance corridors. The Australian Securities and Investments Commission licenses non-cash payment facilities under the National Consumer Credit Protection Act. Sydney's western suburbs host the remaining concentration of storefront providers serving Pacific Islander communities.
Check Cashing Services Market Vendor Landscape
Concentration sits with diversified financial institutions that leverage existing branch infrastructure to subsidize low-margin check cashing. The market exhibits tiered structure: national banks with captive deposit bases, dedicated alternative financial service chains with urban storefront density, and fintech-enabled platforms with mobile-first distribution. Strategic archetypes include branch-heavy incumbents exploiting fixed cost absorption, storefront specialists optimizing for banking desert geography, and digital entrants capturing smartphone-native underbanked users. Dominant competitive moves encompass embedded finance partnerships with retailers and prepaid card ecosystem integration.
Among national banking incumbents, Wells Fargo & Company and Truist Financial Corporation occupy positions that exemplify branch-network leverage for low-cost service provision. Within the alternative financial service specialist tier, ACE Cash Express represents storefront density strategy in underserved urban corridors. Green Dot Corporation anchors the digital-first archetype through mobile wallet and prepaid card-linked channels that reduce physical overhead while expanding geographic reach beyond fixed locations.
| Leading Market Players |
|---|
| Wells Fargo & Company |
| Truist Financial Corporation |
| ACE Cash Express |
| PLS Financial Services |
| The PNC Financial Services Group |
| Check Into Cash |
| U.S. Bancorp |
| Green Dot Corporation |
| Speedy Cash |
| Others |
Supply Flow & Price Mechanics
Mobile wallet substitution for physical cash disbursement is redrawing supply geography toward cloud infrastructure providers while compressing per-transaction pricing power at brick-and-mortar nodes.
Pricing Analysis
The customization-premium spread separates standardized payroll processing from biometric-enabled remote verification with expedited settlement. Subscription membership models now compete against flat-fee and percentage-based structures across Texas and Florida metro corridors. Price differentiation hinges on verification speed tier and prepaid card integration depth. Pricing pressure stems from real-time payment rails lowering consumer willingness to pay for delayed settlement. Individual consumers exhibit highest price sensitivity, while small businesses accept premium rates for specialized business check authentication.
Supply Chain Analysis
Just-in-time liquidity provisioning dominates storefront operations, though strategic stockpiling of prepaid card inventory buffers demand spikes in high-volume urban corridors. Supply concentrates in the United States, with secondary nodes in Canada and Mexico serving cross-border worker populations. Core inputs encompass check verification databases, biometric authentication APIs, and Federal Reserve settlement access. Single-source vulnerability sits with real-time payment rail dependencies. Distribution runs through dual-track structures: physical branch networks for cash-seekers and mobile app stores for smartphone-native users.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Real-time payment infrastructure deployment by the Federal Reserve is compressing settlement timelines and threatening traditional check cashing margins, forcing strategic repositioning across all market participants.
For Market Incumbents: Consolidate storefront density in banking deserts across Houston and Los Angeles corridors while retrofitting legacy core systems to support API-based instant settlement. ACE Cash Express and PLS Financial Services must absorb fixed compliance costs through volume concentration before fintech alternatives capture smartphone-native underbanked users. Backward integration into prepaid card issuance preserves customer wallet share. For New Entrants and Emerging Players: Anchor in embedded finance partnerships with gig economy platforms and retailers seeking white-label check cashing without standalone storefront investment. Government benefit distribution contracts present the most penetrable white-space, with state social service agencies exploring public-private instant conversion partnerships. Green Dot Corporation's mobile-first architecture offers a replicable go-to-market template. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed storefront networks facing refinancing pressure amid digital displacement. Long-term viability favors operators with hybrid physical-digital infrastructure capable of serving persistent unbanked demand while capturing mobile growth. Monitor Federal Reserve real-time payment adoption velocity as the critical inflection signal for traditional model obsolescence risk.| Strategic Initiative | Industry Significance |
|---|---|
| Biometric Verification Deployment | Facial recognition integration reduces fraud rates to in-person levels for mobile capture. |
| Embedded Finance Partnership | Retailer white-label integration bypasses standalone storefront capital requirements. |
| Prepaid Card Ecosystem Integration | Loyalty-linked subscription models improve retention economics in high-volume corridors. |
| Real-Time Payment Rail Adoption | Federal Reserve infrastructure access enables instant settlement competing with fintech alternatives. |
| Regulatory Compliance Consolidation | Multi-state legal infrastructure absorbs fragmented state money transmitter licensing burdens. |
Methodological Framework
The analysis maps in-store, mobile, online, and kiosk service channels, each validated through primary interviews with check cashing operations directors, state banking regulators, prepaid card program managers, and underbanked consumer focus groups. Secondary sources encompass Financial Crimes Enforcement Network guidance documents, state money transmitter licensing databases, Consumer Financial Protection Bureau complaint filings, and Federal Reserve payment system reports. Bottom-up transaction volume modeling triangulates against top-down market sizing from alternative financial service revenue disclosures.
Consistency checks validated volume and value outputs against external benchmarks across the projection horizon. The analytical framework segments by service type, customer tier, fee structure, and check instrument category, with geographic clustering by state-level banking access metrics. CAGRs derive from regression analysis of historical transaction velocity correlated with unbanked population trends and smartphone penetration curves. Real-time payment adoption rates and regulatory harmonization progress serve as industry-specific forecast modifiers.
Decision-makers should treat outputs as directional under assumptions of sustained unbanked population levels and gradual real-time payment diffusion; material deviation would warrant model refresh. Revision becomes warranted when Federal Reserve instant settlement penetration crosses thresholds that structurally displace paper instrument demand.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Financial Services
United States Credit Agency Market
Financial Services
Peer-To-Peer (P2P) Market
Financial Services
Outsource Debt Collection Services Market
Financial Services
Germany Factoring Services Market
Financial Services
Global Alternative Data Market
Financial Services
Australia Online Trading Platform Market
Financial Services
Canada Credit Cards Market
Financial Services
North America Financial Advisory Services Market
Financial Services
Pawn Shop Market
Financial Services
UK Islamic Finance Market
Financial Services
Capital Restructuring Services Market
Financial Services
Europe B2C Legal Services Market
Financial Services
Online Lottery Market
Financial Services
Reverse Factoring Market
Financial Services
Asia-Pacific Factoring Services Market
Financial Services
Currency Management Market