
 Asia-Pacific Factoring Services Market | 2026-2036
Asia-Pacific Factoring Services Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Factoring Services Market Insights
Asset-light supply chain finance models is fragmenting traditional banking dominance across Asia-Pacific trade corridors. HSBC Holdings plc leverages its correspondent network across ASEAN manufacturing hubs to originate receivables from multi-currency exporters. ICICI Bank Limited anchors domestic factoring volume in India through its specialized SME desks and warehouse-receipt-linked structures. Mitsubishi UFJ Financial Group competes on cross-border yen-denominated programs serving Japanese automotive component suppliers.
Asia-Pacific factoring services encompass the purchase of trade receivables at a discount, where financiers assume collection risk against invoices typically maturing in 30 to 180 days, providing immediate liquidity to sellers without collateral beyond the underlying debt. The primary commercial purpose centers on accelerating cash conversion cycles for businesses facing payment gaps between delivery and settlement. Non-recourse factoring commands premium pricing due to credit-protection bundling, while recourse structures dominate transaction volume among established corporate clients. Invoice discounting retains fastest growth velocity as technology platforms enable confidential, undisclosed arrangements preserving supplier-buyer relationships.
Reserve Bank of India factoring regulation and China's NMPA-aligned commercial credit guidelines shape product structuring and capital adequacy requirements across the region. TRAI data-localization mandates in India and China's SAMR fintech licensing rules constrain cross-border platform architectures and foreign participant market access. Stakeholders must monitor evolving central-bank digital currency pilots and open-banking frameworks that could disintermediate traditional factor roles entirely.
Market Dynamics
Digital onboarding platforms and real-time credit scoring APIs are compressing approval timelines from weeks to hours across Asia-Pacific trade corridors, fundamentally restructuring how working capital reaches SME exporters.
Growth Catalysts
- China's NMPA-aligned commercial credit guidelines:Standardized receivables documentation enables faster invoice verification and risk assessment for domestic factors.
- Automotive component supply chains:Extended payment terms between Japanese tier-1 suppliers and ASEAN assembly plants generate sustained demand for cross-border factoring structures.
- Blockchain-enabled invoice verification:Distributed ledger pilots in Singapore and Hong Kong reduce duplicate financing fraud and accelerate multi-party settlement.
Market Restraints
- TRAI data-localization mandates:India's requirement for domestic server storage increases platform infrastructure costs for foreign factoring entrants.
- China's SAMR fintech licensing rules:Capital adequacy thresholds and joint-venture requirements constrain direct market access for non-domestic operators.
- Fragmented SME credit data:Inconsistent bureau coverage across Indonesia, Vietnam and Philippines elevates default estimation uncertainty.
Strategic Opportunities
- Vietnam's manufacturing export corridor:Underpenetrated factoring penetration among electronics and textile subcontractors offers origination volume expansion.
- Central bank digital currency pilots:China's e-CNY and India's digital rupee programs could enable programmable invoice settlement with embedded smart-contract triggers.
- Open banking frameworks:Australia's Consumer Data Right and Singapore's FinTech Regulatory Sandbox create API-based credit data sharing for real-time borrower assessment.
Industry Challenges
- Legacy ERP integration complexity:SME exporters operating on fragmented accounting systems require costly custom API development for platform connectivity.
- Multi-jurisdiction compliance staffing:Cross-border programs demand specialists fluent in India's RBI factoring regulation, China's commercial credit guidelines and ASEAN contractual frameworks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Factoring Services Market |
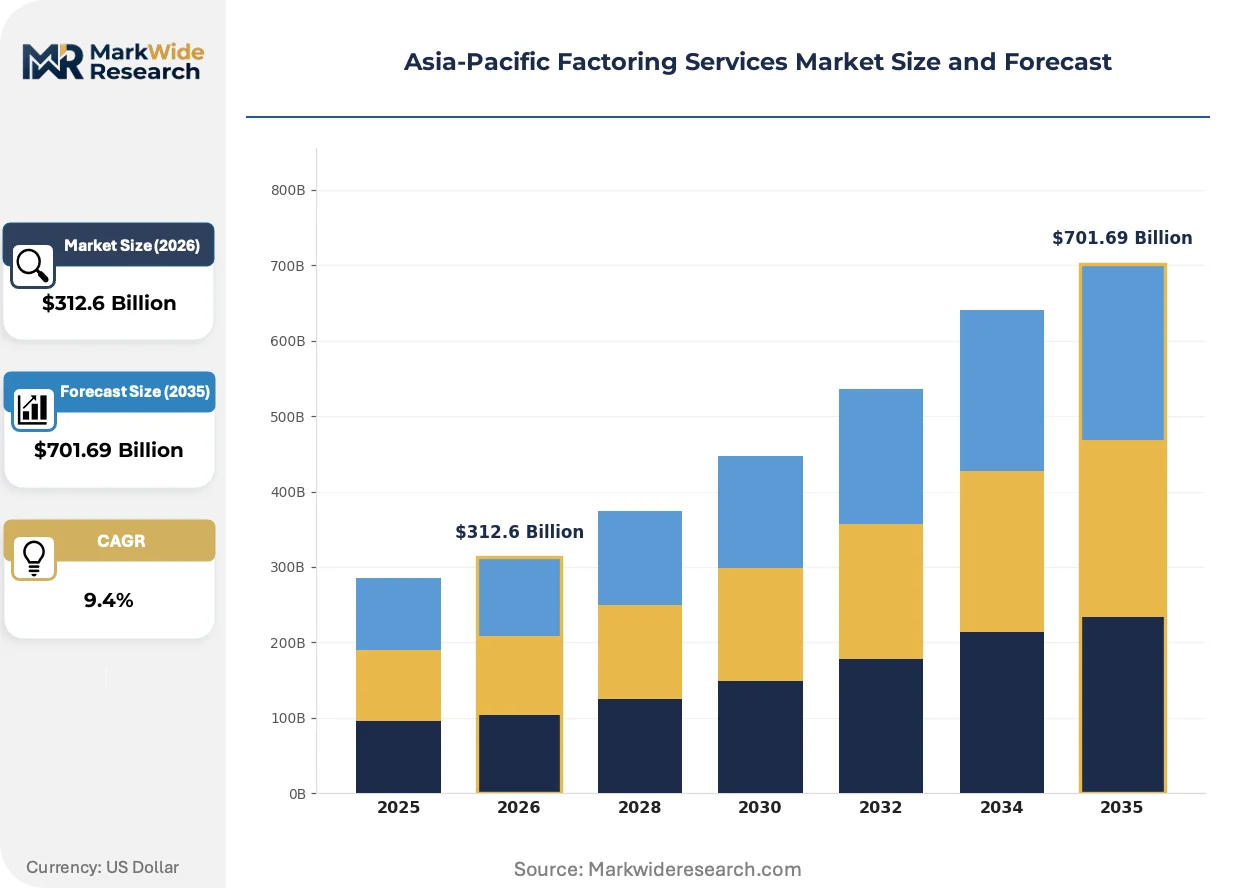
| Market Size in 2026 | $312.6 Billion |
| Market Size in 2035 | $701.69 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Recourse Factoring, Non-Recourse Factoring, Invoice Discounting, Asset-Based Lending Client Type: SMEs, Large Enterprises, Corporates, Startups Industry Vertical: Manufacturing, Retail, Construction, Transportation Transaction Size: Small Value, Medium Value, Large Value, High Volume |
| Companies Covered | HSBC Holdings plc, BNP Paribas SA, Standard Chartered plc, DBS Bank Ltd, Mitsubishi UFJ Financial Group, Industrial and Commercial Bank of China Limited, Bank of China Limited, China Construction Bank Corporation, ICICI Bank Limited, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Factoring Services Market Trends and Innovations
Technology convergence between artificial intelligence and distributed ledger infrastructure is reconfiguring risk assessment workflows and settlement architectures across Asia-Pacific factoring operations.
Machine learning algorithms trained on trade-flow patterns and payment behavior histories are digitizing credit-scoring processes previously dependent on manual document review and relationship-based underwriting. Mid-tier exporters in India and China are adopting these platforms at accelerating velocity as competitive pressure forces faster liquidity access. The structural consequence is a compression of factor pricing spreads as automated risk assessment reduces operational overhead and enables thinner margin structures.
India's RBI factoring regulation amendments and China's evolving commercial credit reporting standards are mandating enhanced disclosure of receivables assignments to prevent double-financing and improve creditor transparency. These frameworks require factors to register transactions with centralized registries, increasing compliance infrastructure investment but reducing systemic fraud exposure. Domestic banks with existing regulatory relationships are adapting faster than platform-native entrants, creating a temporary competitive asymmetry in origination capacity.
Buyer-led supply chain finance programs are displacing traditional seller-initiated factoring as large manufacturers consolidate working capital management across their supplier bases. Automotive and electronics assemblers in Japan and South Korea are deploying captive reverse-factoring structures that capture supplier liquidity demand within proprietary platforms. This concentration is most visible in China's Pearl River Delta and India's Tamil Nadu industrial clusters, where anchor buyers now control payment timing and financing terms for tier-2 and tier-3 component vendors.
Asia-Pacific Factoring Services Market Segmentation
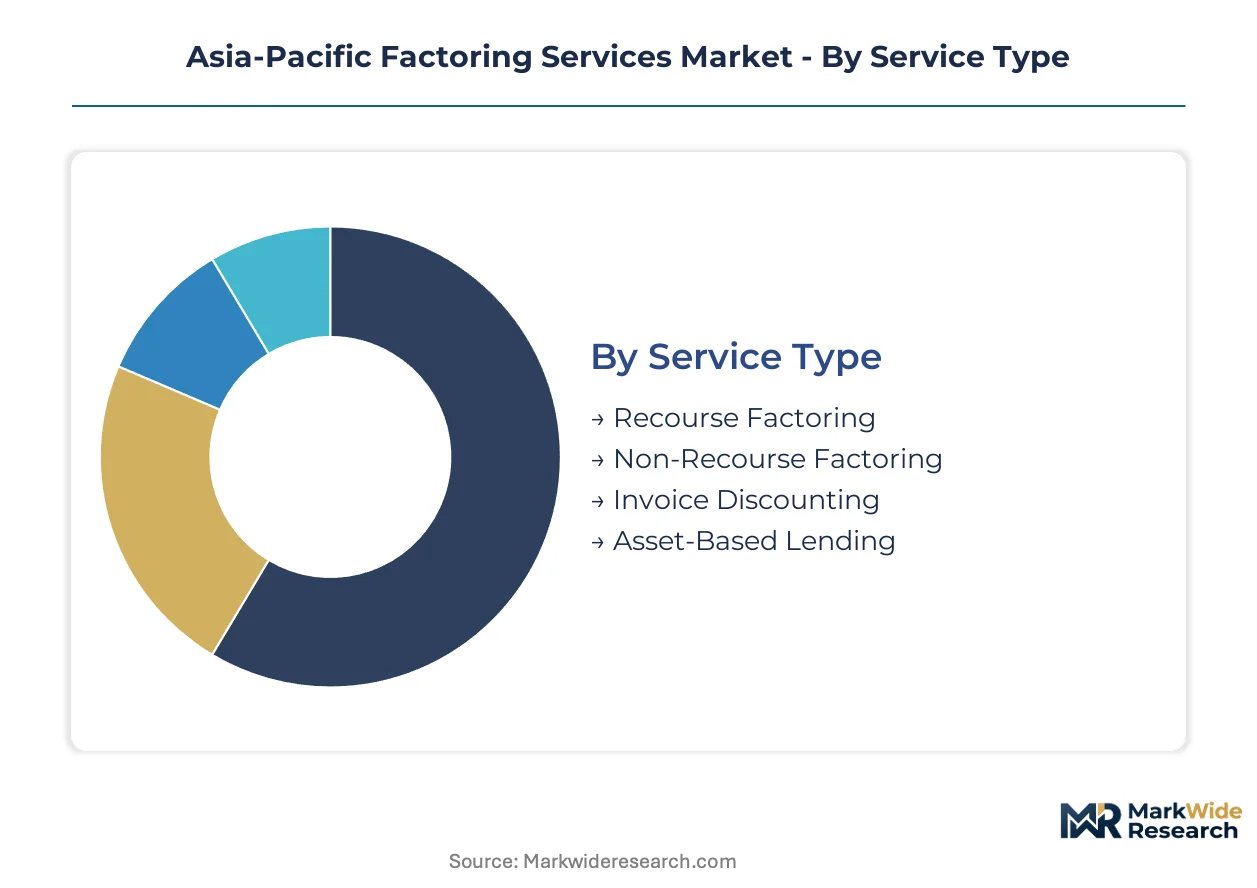
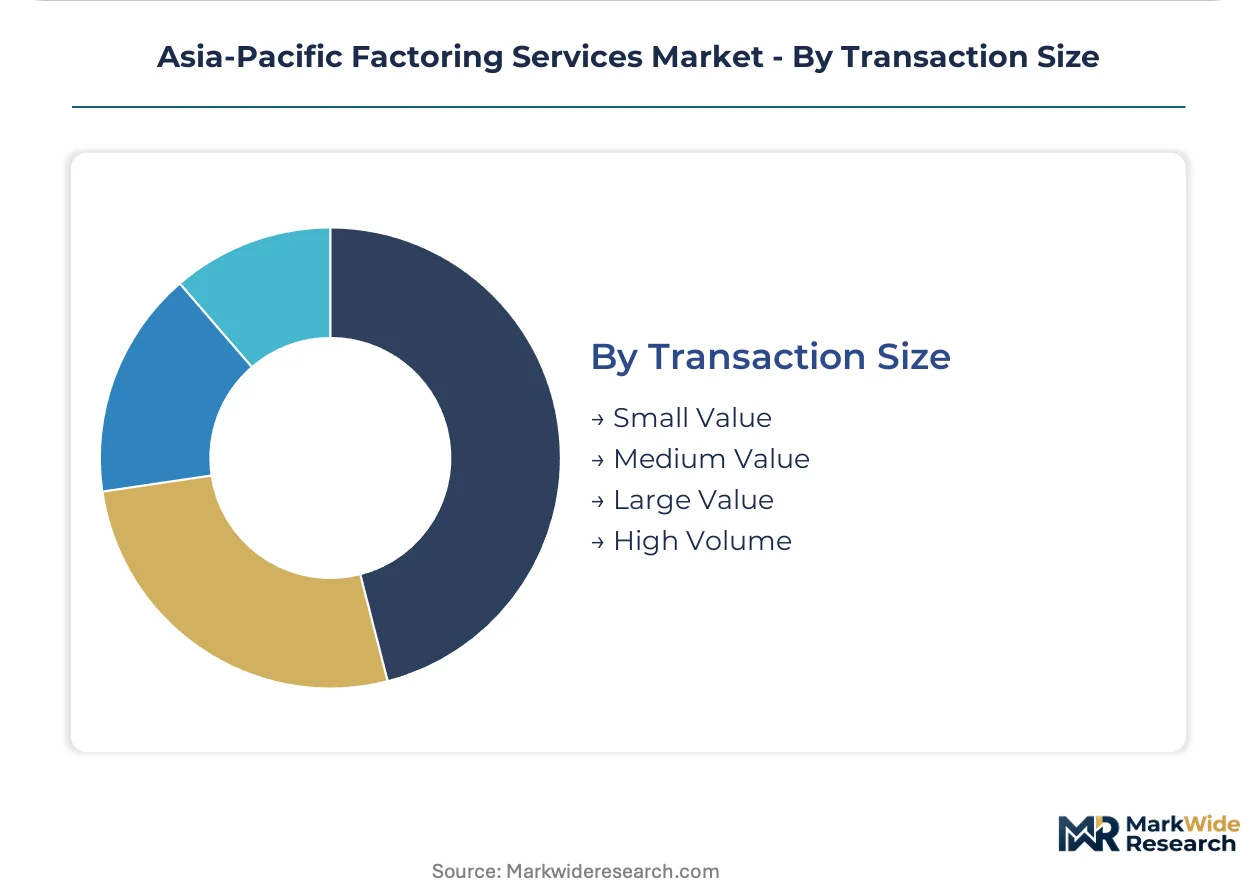
Asia-Pacific factoring services fragment across service structures, client scale, industry exposure, and transaction velocity. Each dimension shapes risk pricing, operational workflow design, and platform technology requirements differently across the region's trade corridors.
Service Type:
After-sales credit protection intensity varies sharply across service structures, driving divergent staffing models and capital allocation strategies among Asia-Pacific factors.
- Recourse Factoring:Sellers retain default liability on purchased receivables, enabling thinner pricing spreads and streamlined documentation. Chinese manufacturing exporters in the Pearl River Delta favor this structure for established buyer relationships with predictable payment histories.
- Non-Recourse Factoring:Factors assume full credit risk, bundling collection services with trade credit insurance. Premium pricing reflects this risk transfer, attracting Indian textile exporters selling to European retailers where buyer default exposure concentrates.
- Invoice Discounting:Confidential arrangements preserve supplier-buyer relationships while unlocking liquidity against unpaid invoices. Singaporean platforms automate this through API-linked accounting systems, compressing approval cycles to under four hours.
- Asset-Based Lending:Revolving credit facilities secured against pooled receivables plus inventory or equipment. Australian mid-market manufacturers deploy this for seasonal working capital swings tied to agricultural commodity processing cycles.
By volume, Recourse Factoring leads. By growth pace, Invoice Discounting is ahead.
Client Type:
Customer sophistication tiers dictate onboarding complexity, with digital-native entrants forcing platform redesign away from relationship-heavy legacy processes.
- SMEs:Fragmented supplier bases across Vietnam and Indonesia generate high transaction counts with smaller average ticket sizes. Automated credit scoring APIs reduce per-unit processing costs to economically viable thresholds.
- Large Enterprises:Sophisticated treasury functions demand multi-currency programs and cross-border settlement integration. Japanese automotive assemblers in Thailand anchor captive reverse-factoring volumes exceeding smaller client aggregates.
- Corporates:Listed entities with audited financials access confidential invoice discounting at benchmarked spreads. South Korean electronics conglomerates in Gyeonggi Province dominate this segment through centralized procurement platforms.
- Startups:Venture-backed growth companies trade equity dilution avoidance for receivables-backed liquidity. Fintech-enabled originators in Bangalore and Shenzhen specialize in thin-file underwriting against marketplace sales data.
SMEs generate the highest transaction frequency. Startups show the steepest expansion trajectory in platform onboarding rates.
Industry Vertical:
Sector-specific payment term conventions and documentation standards shape product-market fit across vertical-specialized factor desks.
- Manufacturing:Extended supplier payment cycles in automotive and electronics assembly create structural liquidity demand. Tamil Nadu component vendors supply this volume through bank-led programs anchored by Japanese and Korean OEMs.
- Retail:Seasonal inventory builds and promotional receivables concentration require flexible facility sizing. Australian department store suppliers in Sydney and Melbourne utilize asset-based structures against mixed collateral pools.
- Construction:Progress billing milestones and retention clauses complicate receivables verification. Philippine infrastructure subcontractors face elevated documentation burdens under local contracting law.
- Transportation:Freight bills and logistics documentation standardize more readily for automated processing. Singaporean port-linked trucking operators pioneer blockchain-verified invoice registries.
Manufacturing commands the largest committed facility volumes. Retail is climbing the fastest as e-commerce marketplace sellers adopt platform-embedded financing.
Transaction Size:
Ticket scale determines operational economics, with threshold effects separating platform-automated flows from relationship-managed bespoke structures.
- Small Value:Individual invoices under fifty thousand dollars dominate count but strain unit economics without straight-through processing. Indonesian textile micro-exporters in Bandung cluster here.
- Medium Value:The operational sweet spot for automated origination, balancing verification depth with processing efficiency. Indian SME manufacturing in Gujarat and Maharashtra concentrates in this band.
- Large Value:Single-invoice transactions requiring bespoke credit committee review and buyer direct confirmation. Australian mining equipment suppliers to Mongolian projects exemplify this category.
- High Volume:Programmatic facilities against pooled receivables with dynamic borrowing base certificates. Chinese cross-border e-commerce aggregators in Shenzhen deploy this structure for marketplace settlement acceleration.
Medium Value transactions anchor platform profitability. High Volume facilities are gaining share fastest as embedded finance penetrates digital trade ecosystems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import imbalances across Asia-Pacific manufacturing corridors are intensifying demand for invoice-backed liquidity solutions. Extended payment terms between ASEAN component suppliers and Japanese and Korean assembly plants create structural working capital gaps. Central bank digital currency pilots and open-banking frameworks are reshaping settlement infrastructure across the region.
China
Cross-border e-commerce aggregators in Shenzhen and Guangzhou are driving high-volume receivables pooling against marketplace settlement data. SAMR fintech licensing rules enforce capital adequacy thresholds and joint-venture requirements for foreign operators. The Pearl River Delta manufacturing cluster anchors domestic recourse factoring volume for established electronics exporters.
India
Tamil Nadu automotive component vendors supply sustained demand through bank-led reverse-factoring programs anchored by Japanese and Korean OEMs. RBI factoring regulation amendments mandate enhanced disclosure of receivables assignments to centralized registries. Gujarat and Maharashtra SME manufacturing clusters concentrate medium-value transaction origination through automated credit scoring platforms.
Japan
Tier-1 automotive suppliers extend payment terms to ASEAN assembly plants, generating cross-border yen-denominated program demand. METI-aligned commercial guidelines standardize receivables documentation for faster invoice verification. The Nagoya industrial corridor houses captive reverse-factoring structures consolidating supplier liquidity management.
Singapore
Port-linked logistics operators pioneer blockchain-verified invoice registries for freight bill standardization. The FinTech Regulatory Sandbox creates API-based credit data sharing frameworks for real-time borrower assessment. Maritime trade finance concentration attracts multi-currency factoring platforms serving Indonesian and Vietnamese exporters.
Vietnam
Electronics and textile subcontractors in the northern manufacturing corridor face underpenetrated factoring adoption despite accelerating export velocity. The country's national banking regulator enforces foreign ownership caps on domestic financial institutions. Ho Chi Minh City and Binh Duong industrial zones concentrate origination opportunity for platform-native entrants.
Asia-Pacific Factoring Services Market Competitive Landscape
On the supply side, the industry is consolidating around three strategic tiers: universal banking networks with correspondent infrastructure, domestic champions with regulatory relationships, and platform-native fintechs with automated origination engines. Market structure favors institutions combining multi-currency settlement capability with localized credit assessment. Dominant competitive moves include strategic partnerships anchoring buyer-led supply chain programs and technology licensing agreements embedding factoring APIs into enterprise procurement platforms.
Among universal banking networks, HSBC Holdings plc and Standard Chartered plc occupy positions spanning ASEAN manufacturing hubs with multi-currency receivables origination. Domestic champions exemplified by ICICI Bank Limited sit within specialized SME desk structures and warehouse-receipt-linked product offerings. Mitsubishi UFJ Financial Group anchors the cross-border yen-denominated program segment serving Japanese automotive component suppliers.
| Leading Market Players |
|---|
| HSBC Holdings plc |
| BNP Paribas SA |
| Standard Chartered plc |
| DBS Bank Ltd |
| Mitsubishi UFJ Financial Group |
| Industrial and Commercial Bank of China Limited |
| Bank of China Limited |
| China Construction Bank Corporation |
| ICICI Bank Limited |
| Others |
Pricing and Supply Chain Analysis
Shenzhen's cross-border e-commerce aggregators anchor Asia-Pacific factoring pricing power through high-volume receivables pooling against marketplace settlement data. Their capacity to standardize invoice documentation compresses verification costs and enables thinner spread structures across the Pearl River Delta manufacturing corridor.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing differentiation across recourse, non-recourse, and confidential invoice discounting structures. Premium spreads attach to non-recourse arrangements bundling credit protection, while recourse factoring commands baseline pricing for established corporate relationships. Cost compression in automated origination tiers is intensifying because machine-learning credit scoring reduces per-unit processing overhead. SMEs exhibit highest price sensitivity due to thin operating margins, whereas large automotive assemblers prioritize multi-currency settlement capability over spread minimization.
Supply Chain Analysis
Extended payment terms between Japanese tier-1 suppliers and ASEAN assembly plants feed demand for supply-chain finance facilities bridging working capital gaps. Concentrated manufacturing capacity rests on China, Vietnam, and India as primary origination hubs for electronics and automotive component exporters. Critical dependencies include real-time credit scoring APIs, blockchain-verified invoice registries, and centralized receivables assignment databases. Single-source vulnerability concentrates around India's TRAI data-localization mandates constraining foreign platform architectures. Distribution runs through bank-led reverse-factoring programs, platform-native automated originators, and captive buyer-led structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating as automotive and electronics assemblers consolidate supplier liquidity management within captive reverse-factoring platforms across Tamil Nadu and the Pearl River Delta.
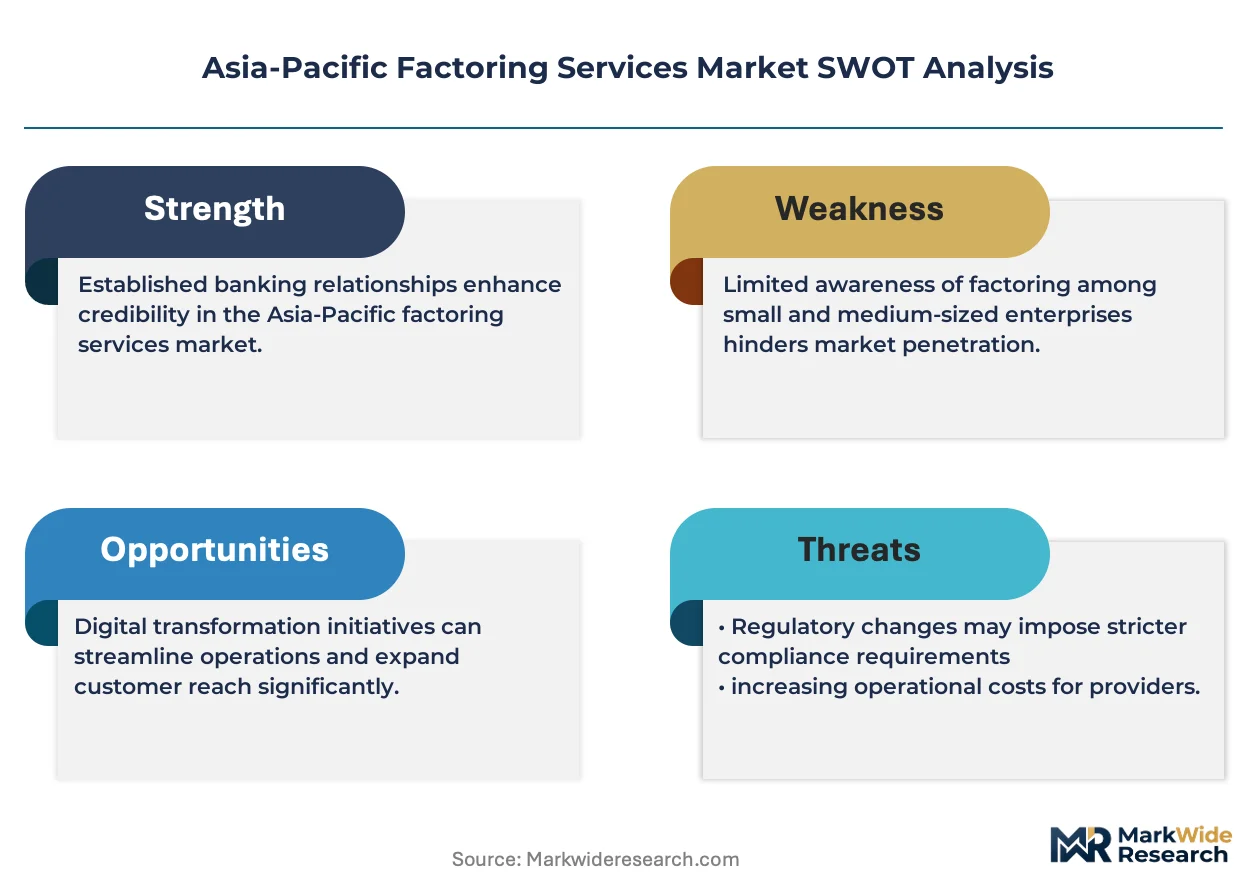
For Market Incumbents: Harden regulatory relationships with India's RBI and China's SAMR to defend origination capacity against platform-native entrants. Deepen API integration with enterprise ERP systems to lock in supplier data flows. Vertical integration into blockchain-verified invoice registries addresses duplicate-financing fraud exposure threatening margin structures. For New Entrants and Emerging Players: Pursue Vietnam's northern electronics and textile manufacturing corridor where factoring penetration remains underdeveloped relative to export velocity. Target Indonesian SME micro-exporters in Bandung lacking straight-through processing access from incumbent banks. Embed financing APIs into accounting software platforms serving fragmented supplier bases. For Investors and Strategic Acquirers: Long-term, this sits as a financial infrastructure consolidation play because automated origination engines are displacing relationship-heavy legacy processes. Acquisition targets center on platform-native fintechs with proven credit-scoring algorithms and existing SAMR or RBI licensing. Watch central bank digital currency pilot expansion as the signal for programmable settlement disintermediating traditional factor roles.| Strategic Initiative | Industry Significance |
|---|---|
| API Integration with Enterprise ERP Systems | HSBC and ICICI Bank lock supplier data flows through seamless accounting platform connectivity. |
| Blockchain-Verified Invoice Registry Deployment | Singaporean logistics operators reduce duplicate-financing fraud via distributed ledger pilots. |
| Regulatory Licensing Acceleration | Domestic champions adapt faster to RBI and SAMR compliance requirements than foreign entrants. |
| Captive Reverse-Factoring Structure Launch | Japanese automotive OEMs in Thailand consolidate tier-2 supplier liquidity management internally. |
| Central Bank Digital Currency Partnership | Early alignment with China's e-CNY and India's digital rupee enables programmable settlement triggers. |
Research Methodology
Initial hypotheses were tested against primary input from factoring operations executives, SME treasury managers, regulatory compliance officers, and platform engineering leads and refined through secondary validation. Trade finance databases, central bank regulatory filings, customs receivables documentation, and SEC disclosures from listed financial institutions anchored quantitative triangulation. Bottom-up transaction volume estimates and top-down banking sector credit allocation data converged through iterative reconciliation.
Demand-supply balance modeling across the projection horizon incorporated service type segmentation, client sophistication tiers, industry vertical exposure, and transaction velocity bands. CAGRs derived from historical origination growth patterns adjusted for regulatory implementation timelines and technology adoption curves. Forecast inputs included API penetration rates among SME exporters and central bank digital currency pilot expansion trajectories.
Sensitivities concentrate around SAMR licensing enforcement intensity, TRAI data-localization compliance costs, and open-banking framework implementation pace across ASEAN markets. Forecasts reflect documented assumptions regarding regulatory stability and technology platform scalability. Macroeconomic contraction, abrupt regulatory restriction, or distributed ledger infrastructure failure would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Financial Services
Global Treasury Management System (TMS) Market
Financial Services
Southeast Asia E-Invoicing Market
Financial Services
Intellectual Property Valuation Market
Financial Services
Outsource Debt Collection Services Market
Financial Services
Financial Services Operational Risk Management Solution Market
Financial Services
India Payroll Services Market
Financial Services
Saas Escrow Services Market
Financial Services
BFSI A2P SMS Market
Financial Services
Mobile Notary Service Market
Financial Services
South Korea Trade Finance Market
Financial Services
Debt Settlement Solution Market
Financial Services
Africa Lottery Market
Financial Services
US Healthcare Finance Solutions Market
Financial Services
India Legal Services Market
Financial Services
White Glove Services Market
Financial Services
CFD Trading Affiliate Programs Market