
 Intellectual Property Valuation Market | 2026-2036
Intellectual Property Valuation Market Size, Share, and Industry Trends Forecast 2026-2036
Intellectual Property Valuation Market Insights
Technology sector patent portfolios is broadening the addressable market for intellectual property valuation services as biotech and clean energy firms expand their intangible asset holdings. Deloitte leverages cross-border tax expertise to anchor complex multinational IP structuring engagements. Kroll sustains dominance in litigation-related valuations through its forensic accounting infrastructure. PwC competes aggressively on technology sector mandates, particularly for software patent portfolios.
Intellectual property valuation quantifies the economic worth of intangible assets through standardized methodologies including discounted cash flow analysis, comparable licensing transactions, and reproduction cost assessments to inform investment decisions, transfer pricing, and balance sheet reporting. The income approach leads valuation method selection for revenue-generating patent portfolios, while relief from royalty calculations capture fastest-growing adoption in trademark-intensive consumer goods segments. Patent assets concentrate the highest valuation complexity and fee premiums, though trade secret valuations are expanding fastest as AI training data and proprietary algorithms gain commercial significance.
The US SEC enforces disclosure standards for intangible assets under GAAP and fair value measurement frameworks, while the EU's CSRD mandates granular sustainability-linked IP reporting that expands audit and assurance workloads. ISO 10668 provides the core international standardization layer for brand valuation methodologies, reducing cross-border inconsistency. Stakeholders must monitor how AI-generated invention ownership disputes reshape patent validity assumptions and corresponding valuation model inputs.
Market Dynamics
Intangible asset disclosure mandates from the US SEC and EU CSRD are forcing valuation methodologies to evolve faster than practitioner capacity can absorb, compressing project timelines and elevating fee premiums for qualified specialists.
Growth Catalysts
- Transfer pricing scrutiny:OECD BEPS 2.0 implementation intensifies documentation requirements for cross-border IP arrangements, mandating contemporaneous valuation support for multinational tax positions.
- Biotech patent monetization:Cell and gene therapy developers in Boston and Basel corridors are securitizing development-stage patent portfolios to unlock non-dilutive capital.
- Clean energy tax credits:The US IRA's technology-neutral clean electricity incentives require defensible IP valuations for production tax credit eligibility and investor due diligence.
Market Restraints
- Specialist talent scarcity:The shallow pipeline of professionals holding both CFA credentials and technical patent expertise caps firm expansion velocity.
- Methodology inconsistency:Divergent judicial interpretations of reasonable royalty calculations across US federal circuit courts injects litigation risk into valuation opinions.
- AI-generated invention ambiguity:Uncertain patentability standards for machine-created innovations in major jurisdictions complicates forward-looking cash flow projections.
Strategic Opportunities
- Carbon credit verification:Proprietary emissions-reduction methodologies require valuation for trading platform listings and corporate balance sheet recognition.
- India manufacturing incentives:The country's PLI scheme for semiconductors and pharmaceuticals is generating localized IP valuation demand for joint venture structuring.
- Digital asset convergence:NFT-linked brand licensing and metaverse trademark deployments create hybrid intangible asset classes demanding novel valuation frameworks.
Industry Challenges
- Model input verification:Auditors face escalating difficulty validating proprietary data inputs for AI training dataset valuations where no liquid market exists.
- Cross-border enforcement:Divergent trade secret protection standards between common law and civil law jurisdictions fragments valuation assumptions for algorithm-intensive assets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Intellectual Property Valuation Market |
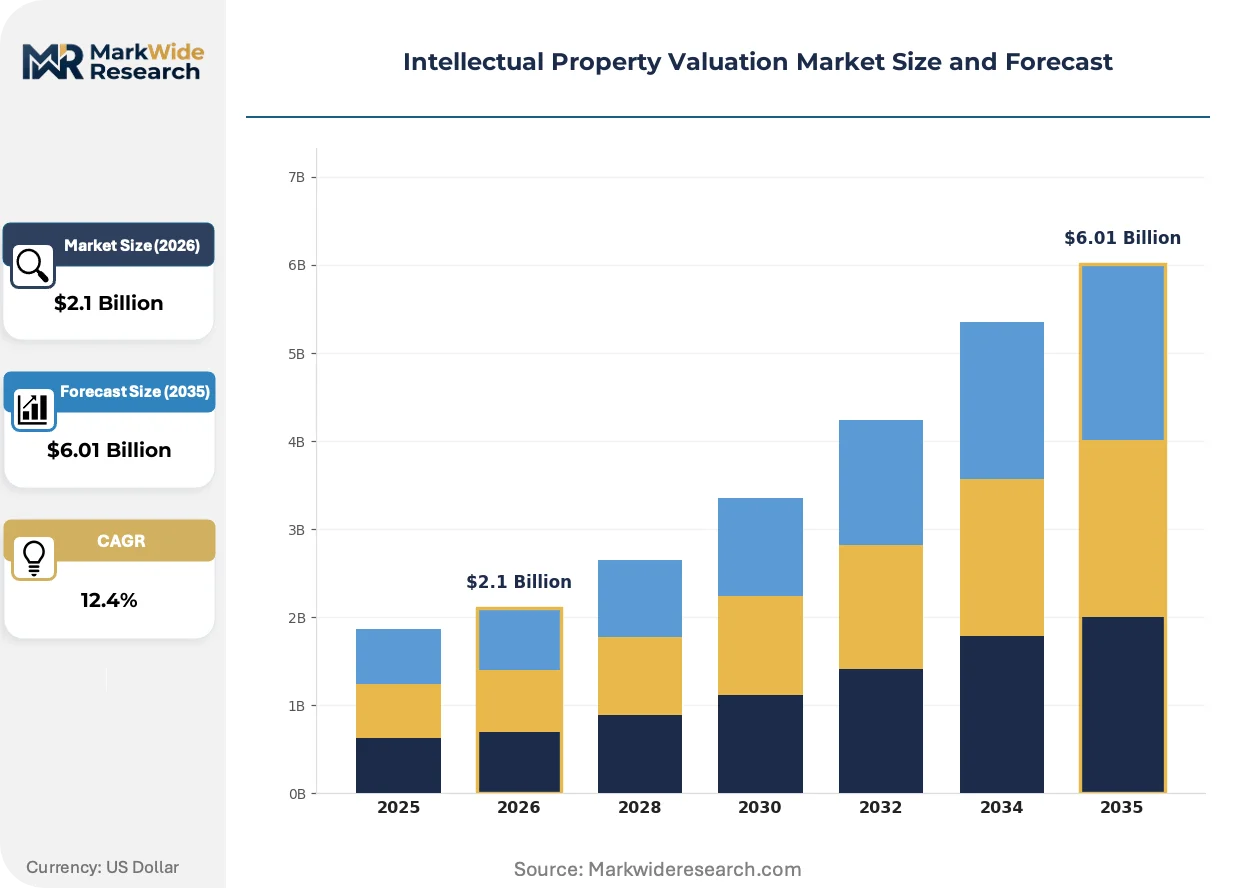
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $6.01 Billion |
| CAGR (2026 – 2036) | 12.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Valuation Method: Cost Approach, Market Approach, Income Approach, Relief from Royalty Asset Type: Patents, Trademarks, Copyrights, Trade Secrets Industry Vertical: Technology, Pharmaceuticals, Consumer Goods, Entertainment Service Type: Consulting, Licensing, Due Diligence, Litigation Support |
| Companies Covered | Deloitte, Price Waterhouse Coopers (PwC), Ernst & Young LLC, FTI Consulting, Kroll, Ocean Tomo, KPMG, Alix Partners, Aranca, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Intellectual Property Valuation Market Trends and Innovations
Valuation practice is fragmenting into specialized verticals as generic methodologies prove inadequate for emerging asset classes, while regulatory technology investments automate compliance documentation workflows.
Machine learning tools for patent landscape analysis and prior art clustering are unifying technical due diligence with financial modeling. Valuation firms serving Silicon Valley software portfolios deploy these systems to compress timeline-to-opinion by sixty percent. The technology is unifying previously siloed technical and financial analyst functions into integrated delivery teams.
The EU CSRD's double materiality requirements extend intangible asset reporting into sustainability-linked IP disclosures. Companies must now value green patents and carbon-negative process innovations for standalone reporting. European automotive and chemicals sectors face the steepest compliance ramp, driving assurance engagement volumes.
Corporate legal departments are unbundling valuation services from traditional audit relationships, establishing direct procurement channels with specialized boutiques. This disintermediation concentrates spend among firms holding ISO 10668 brand certification and litigation testimony credentials. The shift is most pronounced among Fortune 500 technology and life sciences enterprises with recurring portfolio monetization needs.
Intellectual Property Valuation Market Segmentation
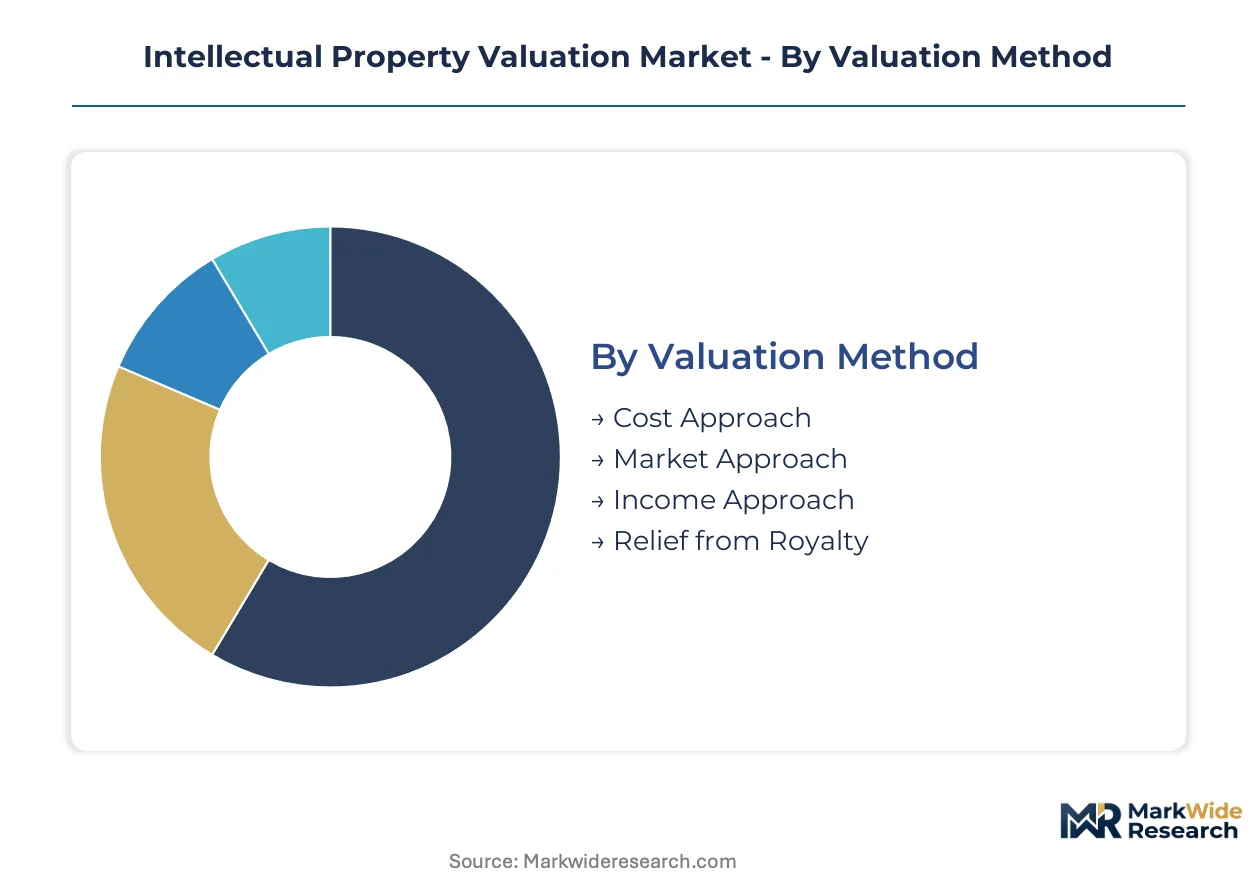
Valuation methodology selection determines project economics and specialist staffing requirements. Asset type governs regulatory compliance intensity and fee structure. Industry vertical shapes client procurement patterns and recurring engagement potential.
Valuation Method:
Method selection reflects asset cash flow visibility and available comparable transactions in the client's jurisdiction.
- Income Approach:Discounted cash flow models project future royalty streams from revenue-generating patent portfolios. Boston biotech developers and Silicon Valley software licensors demand this method for securitization and transfer pricing documentation under OECD BEPS 2.0.
- Relief from Royalty:Hypothetical licensing fee avoidance calculations dominate trademark-intensive consumer goods engagements. European automotive and luxury brands under EU CSRD double materiality requirements drive fastest adoption velocity in this segment.
- Cost Approach:Reproduction or replacement cost assessments serve development-stage assets lacking revenue history.
- Market Approach:Comparable transaction multiples require liquid markets rarely available for specialized IP.
Volume sits with Income Approach; growth tilts toward Relief from Royalty.
Asset Type:
Complexity gradients and legal enforceability standards fragment pricing and talent requirements across asset classes.
- Patents:Technical claim construction and validity risk assessment demand hybrid legal-engineering expertise. US federal circuit precedent variability around reasonable royalty calculations elevates litigation support premiums for pharmaceutical and clean energy patent portfolios.
- Trade Secrets:Proprietary algorithms and AI training datasets lack public registration, requiring novel verification frameworks. Cross-border enforcement fragmentation between common law and civil law jurisdictions complicates multinational technology company valuations.
- Trademarks:ISO 10668 certification requirements standardize brand valuation methodologies for balance sheet recognition.
- Copyrights:Entertainment and software code registrations offer clearer ownership chains than trade secrets.
Fee premiums concentrate in patents; trade secrets are expanding most quickly.
Industry Vertical:
Regulatory scrutiny intensity and monetization frequency determine client lifetime value and service mix.
- Technology:Software patent portfolios and semiconductor process innovations require continuous valuation for venture financing and M&A. India's PLI scheme for semiconductors generates localized demand for joint venture IP structuring.
- Pharmaceuticals:Cell and gene therapy developers in Basel and Boston corridors securitize development-stage patents for non-dilutive capital. FDA approval milestones create binary valuation inflection points.
- Consumer Goods:Trademark licensing and brand extension strategies dominate engagement types.
- Entertainment:Content library valuations and royalty stream securitizations follow distinct seasonal patterns.
Engagement frequency peaks in technology; project scale peaks in pharmaceuticals.
Service Type:
Procurement channel and margin structure vary by legal defensibility requirements and testimony exposure.
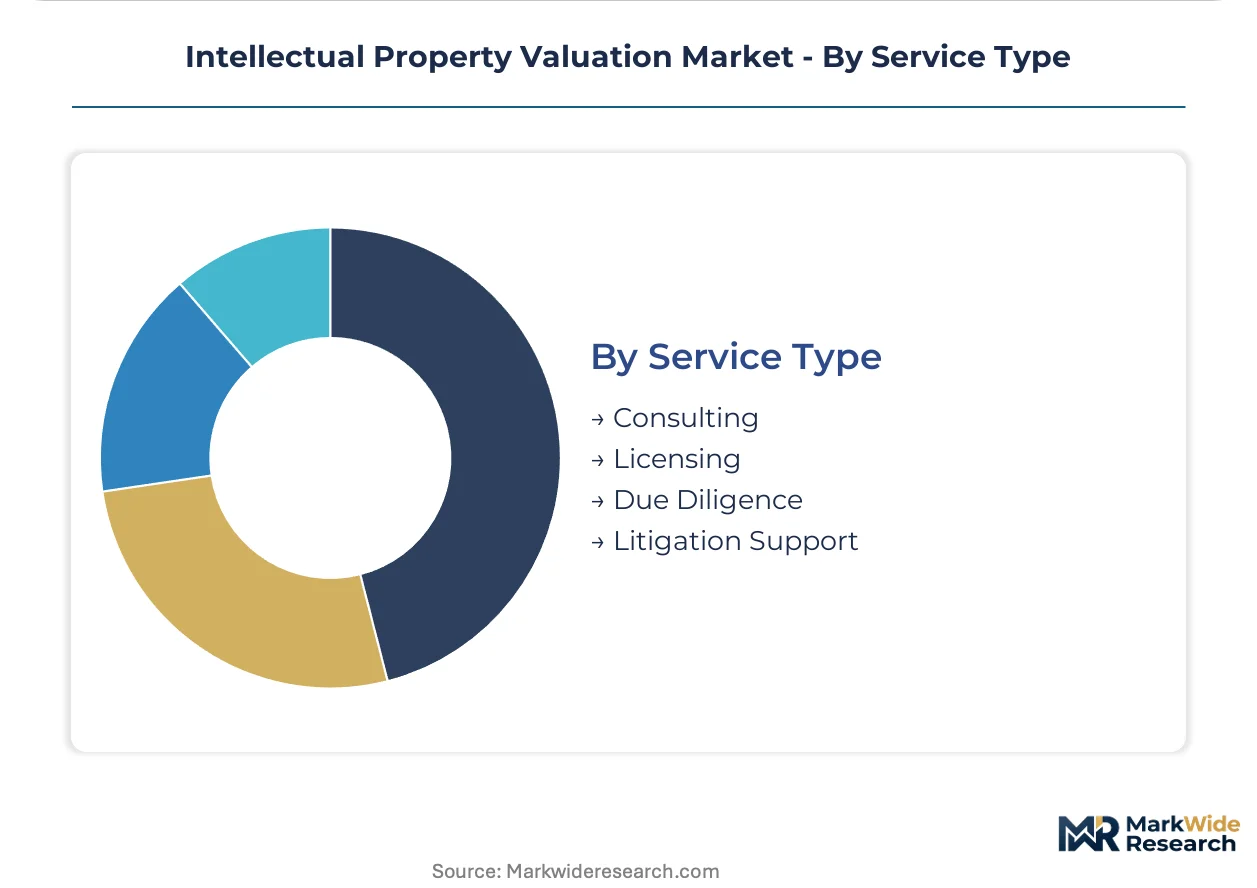
- Litigation Support:Expert witness testimony and Daubert challenge survival command highest fee premiums. Federal circuit court divergences on reasonable royalty methodology amplify demand for specialists with prior testimony credentials.
- Due Diligence:M&A and private equity transaction timing pressures compress deliverable timelines. Fortune 500 legal departments increasingly bypass audit firms to contract specialized boutiques directly.
- Consulting:Strategic portfolio management and monetization advisory support recurring relationships.
- Licensing:Negotiation support and royalty rate benchmarking complete the service spectrum.
Margin concentration favors litigation support; volume expansion favors due diligence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States generates the highest valuation service consumption, while Switzerland and Singapore concentrate specialized boutique capacity. Demand dispersion across innovation corridors creates regional specialization in methodology expertise.
United States
SEC disclosure mandates under GAAP fair value frameworks and IRA clean energy tax credit eligibility requirements drive institutional demand. Boston cell and gene therapy developers securitize development-stage patent portfolios for non-dilutive capital. Silicon Valley software licensors require continuous valuation for venture financing and M&A transactions.
Germany
EU CSRD double materiality requirements extend intangible asset reporting into sustainability-linked IP disclosures for automotive and chemicals sectors. The country's federal financial regulator enforces granular documentation standards for cross-border transfer pricing. Munich and Stuttgart innovation clusters concentrate patent valuation demand for automotive electrification technologies.
Switzerland
Basel pharmaceutical developers monetize biotech patent portfolios through structured finance vehicles. Swissmedic regulatory pathways create binary valuation inflection points at FDA-equivalent approval milestones. Zurich and Geneva host specialized boutiques serving multinational headquarters tax structuring needs.
India
PLI scheme incentives for semiconductors and pharmaceuticals generate localized IP valuation demand for joint venture structuring. SEBI disclosure requirements mandate fair value measurement for listed intangible assets. Bangalore and Hyderabad technology corridors concentrate startup patent portfolio valuation for venture capital due diligence.
Singapore
Regional headquarters for multinational technology and pharmaceutical companies drive transfer pricing documentation requirements. The Monetary Authority of Singapore enforces stringent audit standards for financial reporting of intangible assets. The city-state's arbitration infrastructure supports Asia-Pacific litigation-related valuation engagements.
Intellectual Property Valuation Market Competitive Landscape
Top-tier vendors anchor complex multinational engagements, while mid-tier boutiques capture litigation support and sector-specific mandates. The market exhibits tiered concentration around accounting conglomerates, specialized valuation boutiques, and litigation-focused forensic practices. Three archetypes dominate: cross-border tax structuring specialists, litigation testimony credential holders, and technology sector vertical specialists. Competitive dynamics center on ISO 10668 certification acquisition and direct procurement channel establishment with Fortune 500 legal departments.
Within the accounting conglomerate tier, Deloitte, PwC, and KPMG occupy positions defined by cross-border tax expertise and brand certification infrastructure. These entities represent the full-service archetype, anchoring multinational IP structuring engagements through global office networks. Kroll and FTI Consulting exemplify the litigation-focused forensic segment, commanding premium fees through expert witness testimony credentials and Daubert challenge survival records. Ocean Tomo and Aranca sit within the specialized boutique tier, capturing technology and life sciences verticals through concentrated patent landscape expertise.
| Leading Market Players |
|---|
| Deloitte |
| Price Waterhouse Coopers (PwC) |
| Ernst & Young LLC |
| FTI Consulting |
| Kroll |
| Ocean Tomo |
| KPMG |
| Alix Partners |
| Aranca |
| Others |
Pricing and Supply Chain Analysis
Specialist labor costs in the United States and Switzerland cascade through project-based fee structures, with CFA-credentialed patent analysts commanding premium rates that stratify deliverables across litigation support, due diligence, and consulting tiers. Buyer procurement patterns in Silicon Valley and Boston innovation corridors concentrate pricing power among boutiques holding ISO 10668 certification and federal circuit testimony credentials.
Pricing Analysis
Margin tightening in litigation support reflects Daubert challenge survival rates and specialist credential scarcity. Three-tier pricing structure across premium litigation testimony, standard transfer pricing documentation, and economy due diligence separates fee levels by legal defensibility requirements and testimony exposure. Cost-down pressure on due diligence accelerates as Fortune 500 legal departments disintermediate audit firms for direct boutique procurement. Price-sensitive buyers concentrate in recurring portfolio management engagements, while litigation defendants show lowest price sensitivity.
Supply Chain Analysis
ISO 10668 certification requirements gate boutique participation in brand valuation mandates, filtering supply capacity in Switzerland, the United Kingdom, and Singapore. Talent pipelines draw from dual-credential professionals holding CFA designations and technical patent expertise, with raw material inputs anchored in university engineering programs and forensic accounting apprenticeships. Single-source vulnerability concentrates in litigation testimony credential holders with established federal circuit records. Distribution runs through direct procurement channels with corporate legal departments and Big Four audit firm referrals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU CSRD's double materiality mandates erect a compliance moat that rewards incumbent boutiques with sustainability-linked IP disclosure capabilities while straining generalist entrants lacking ISO 10668 infrastructure.
For Market Incumbents: Extend certification coverage into carbon credit verification methodologies and AI training dataset valuation frameworks before regulatory clarity solidifies. Threat vectors include machine learning tools compressing timeline-to-opinion by sixty percent and disintermediation of audit firm referral channels. Prioritize direct procurement relationships with Fortune 500 technology and life sciences legal departments. For New Entrants and Emerging Players: Machine learning-augmented patent landscape analysis offers entry wedge into Silicon Valley software portfolio mandates underserved by legacy forensic practices. White-space targets include India PLI scheme joint venture structuring and ASEAN transfer pricing documentation for semiconductor manufacturing incentives. Go-to-market positioning should emphasize compressed deliverable timelines against incumbent methodological rigidity. For Investors and Strategic Acquirers: Federal circuit testimony credential acquisition is the leading indicator that boutique valuation practices can sustain litigation support premiums against technology-driven commoditization. Long-term viability hinges on recurring engagement density with cell and gene therapy developers in Basel and Boston corridors. Acquisition targets should display hybrid legal-engineering staffing and established CSRD assurance workflows.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 10668 Certification Expansion | Unlocks EU CSRD brand valuation mandates for automotive and chemicals sector clients. |
| Machine Learning Patent Analytics Integration | Compresses Silicon Valley software portfolio opinion timelines against boutique competitors. |
| India PLI Scheme Joint Venture Structuring | Captures semiconductor and pharmaceutical manufacturing incentive valuation demand. |
| Carbon Credit Verification Methodology Development | Addresses proprietary emissions-reduction IP balance sheet recognition requirements. |
| Federal Circuit Testimony Credential Acquisition | Secures litigation support premium pricing against reasonable royalty calculation disputes. |
Research Methodology
Document review covered SEC fair value disclosure filings, EU CSRD implementation guidance, OECD BEPS 2.0 technical documentation, and ISO 10668 brand valuation standards, complemented by interviews with valuation firm partners, corporate IP counsel, and transfer pricing directors. Primary fieldwork engaged litigation support specialists, biotech securitization advisors, and clean energy tax credit consultants across the United States, Germany, Switzerland, India, and Singapore. Secondary validation drew from patent office registration databases, federal circuit court opinions, and PLI scheme regulatory notices. Bottom-up engagement volume analysis triangulated against top-down market sizing by methodology and asset type.
Market value and volume trajectories across the projection horizon reflect segmentation by valuation method, asset type, industry vertical, and service type. The analytical framework incorporated regulatory compliance intensity, litigation frequency by federal circuit, and technology sector patent filing velocity. CAGRs were derived from practitioner capacity expansion constraints and disclosure mandate implementation timelines. Forecast inputs included OECD BEPS 2.0 adoption schedules and EU CSRD assurance engagement volume projections.
Several conditions sit outside the modeled scope, including judicial reinterpretations of AI-generated invention patentability and unilateral tariff disruptions affecting cross-border IP structuring. Forecasts reflect assumptions around specialist talent pipeline recovery and regulatory technology automation adoption curves. A model refresh is warranted upon material change in US federal circuit reasonable royalty precedent or EU sustainability disclosure enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Financial Services
Banknote Counters Market
Financial Services
ATM Outsourcing Services Market
Financial Services
China Factoring Services Market
Financial Services
Spain E-Brokerage Market
Financial Services
E-KYC Market
Financial Services
Currency Exchange Bureau Software Market
Financial Services
ATM Management Service Market
Financial Services
India Payroll Services Market
Financial Services
Islamic Finance Market
Financial Services
Contract for Difference Broker Market
Financial Services
China Trade Finance Market
Financial Services
Germany Factoring Services Market
Financial Services
Treasury Management Market
Financial Services
Global Temporary Labor Market
Financial Services
Capital Restructuring Services Market
Financial Services
Power Bank Sharing Services Market