
 India Payroll Services Market | 2026-2036
India Payroll Services Market Size, Share, and Industry Trends Forecast 2026-2036
India Payroll Services Market Insights
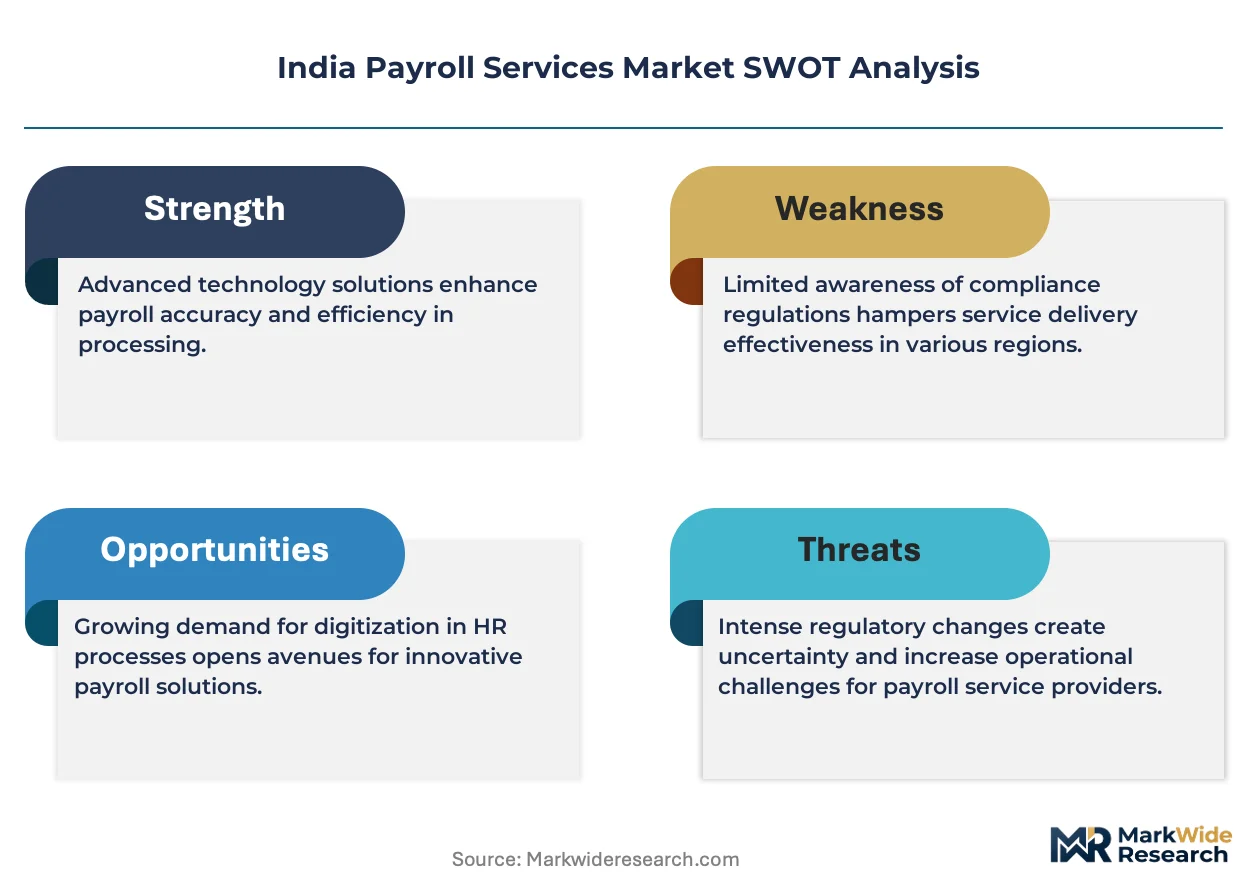
The PLI scheme for IT hardware manufacturing is decoupling payroll complexity from pure headcount metrics as compliance layers multiply. ADP India leverages its multinational protocol library to anchor premium enterprise accounts. Neeyamo specializes in multi-country payroll orchestration for Indian firms expanding overseas. GreytHR competes on native SaaS architecture built for India's statutory variation across states.
Payroll services encompass wage computation, statutory deduction administration, direct deposit execution, and regulatory filing within India's federal labor structure where Provident Fund, Employee State Insurance, and Professional Tax regimes vary by state. Cloud-based payroll deployment is displacing on-premise installations as GST-era audit trails demand real-time data accessibility. Small and medium enterprises represent the fastest-expanding client size tier as UPI-integrated salary disbursement removes legacy banking friction. The IT industry vertical sustains the deepest outsourcing penetration given its distributed workforce and ESOP administration complexity.
India's Ministry of Labour and Employment, the Employees' Provident Fund Organisation, and state-level Professional Tax authorities collectively shape compliance architecture that payroll vendors must encode into software logic. The Code on Wages and Code on Social Security are forcing platform upgrades as centralized definitions replace fragmented state interpretations. Stakeholders must monitor how the proposed National Payroll Portal consolidates reporting obligations and whether it creates public-sector competition or vendor integration opportunity.
Market Dynamics
The Code on Wages and Code on Social Security are forcing payroll vendors to rearchitect software logic as centralized definitions replace fragmented state interpretations, compressing compliance timelines and elevating automation requirements.
Growth Catalysts
- Labour Code Consolidation:The Ministry of Labour and Employment's digitization push accelerates compliance automation demand as enterprises seek platforms encoding centralized wage and social security definitions.
- IT Hardware PLI Scheme:Manufacturing incentives are decoupling payroll complexity from pure headcount metrics as compliance layers multiply for contract and permanent workforces.
- UPI Integration:Real-time payment infrastructure removes legacy banking friction, enabling small and medium enterprises to adopt outsourced salary disbursement at scale previously reserved for large corporations.
Market Restraints
- State-Level Statutory Variation:Provident Fund, Employee State Insurance, and Professional Tax regimes that differ across 28 states force vendors to maintain fragmented compliance engines, elevating platform development costs.
- Legacy System Entrenchment:On-premise payroll installations in established manufacturing and public sector enterprises resist cloud migration despite GST-era audit trail requirements.
- Talent Concentration Risk:Deep payroll compliance expertise clusters in Bengaluru, Mumbai, and the National Capital Region, constraining vendor expansion into tier-2 and tier-3 city markets.
Strategic Opportunities
- National Payroll Portal:The proposed consolidated reporting obligation creates integration opportunities for vendors positioned as official technology partners rather than competitors to public infrastructure.
- ESOP Administration Complexity:Distributed IT workforces with equity compensation structures demand specialized payroll orchestration that generalist providers cannot easily replicate.
- Overseas Expansion Orchestration:Indian firms building multinational presence require multi-country payroll coordination, creating white space for vendors with protocol libraries spanning diverse regulatory environments.
Industry Challenges
- Compliance Engineer Scarcity:Vendors face acute shortages of professionals capable of translating state-level Professional Tax authority variations into executable software logic.
- Platform Integration Friction:Enterprises demand seamless connectivity between payroll systems and existing ERP, HRMS, and accounting software, extending implementation timelines.
- Real-Time Audit Trail Architecture:GST-era data accessibility requirements force expensive reengineering of batch-processed legacy platforms into continuous transaction recording systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Payroll Services Market |
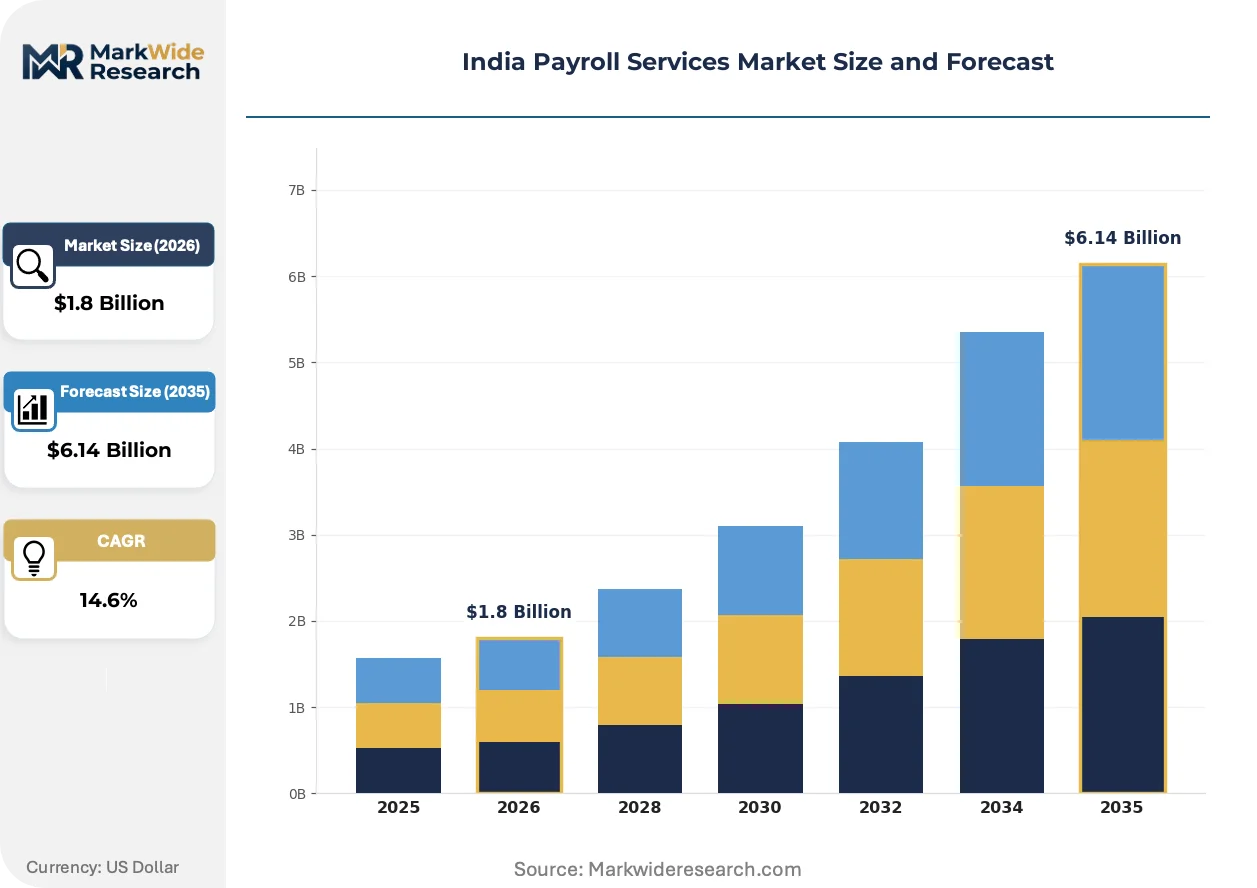
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.14 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Outsourced Payroll, In-house Payroll, Cloud-Based Payroll, Managed Payroll Client Size: Small Enterprises, Medium Enterprises, Large Corporations, Startups Deployment Model: On-Premise, Cloud, Hybrid, Remote Industry Vertical: Information Technology, Healthcare, Retail, Construction |
| Companies Covered | ADP India, Neeyamo, Quess Corp, Aon Hewitt India, Alight Solutions India, GreytHR, Paybooks, Quikchex, PaySquare, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Payroll Services Market Trends and Innovations
Cloud-native architectures are displacing on-premise installations as statutory compliance demands real-time data accessibility, while artificial intelligence applications compress error detection cycles and regulatory interpretation latency.
Machine learning is converging with payroll compliance engines to automate interpretation of state-level statutory variations, reducing manual configuration overhead. Mid-market enterprises adopting these platforms report compressed implementation timelines compared to legacy rule-based systems. The technology is converging with regulatory change management workflows, enabling vendors to push compliance updates without client-side reconfiguration.
The Code on Social Security mandates centralized definitions for wages, bonuses, and social security contributions, replacing decades of fragmented state interpretations. This regulatory compression forces platform upgrades across installed bases, creating upgrade revenue cycles for established vendors. IT and healthcare enterprises with distributed workforces face the steepest compliance recalibration requirements.
Subscription pricing models are displacing perpetual license structures as enterprises prioritize operational expenditure predictability over capital deployment. Small and medium enterprises in Gujarat and Tamil Nadu manufacturing corridors are driving this transition, demanding monthly billing aligned with cash flow cycles. Bengaluru technology clusters exhibit the fastest behavioral shift toward usage-based pricing tied to active employee counts.
India Payroll Services Market Segmentation
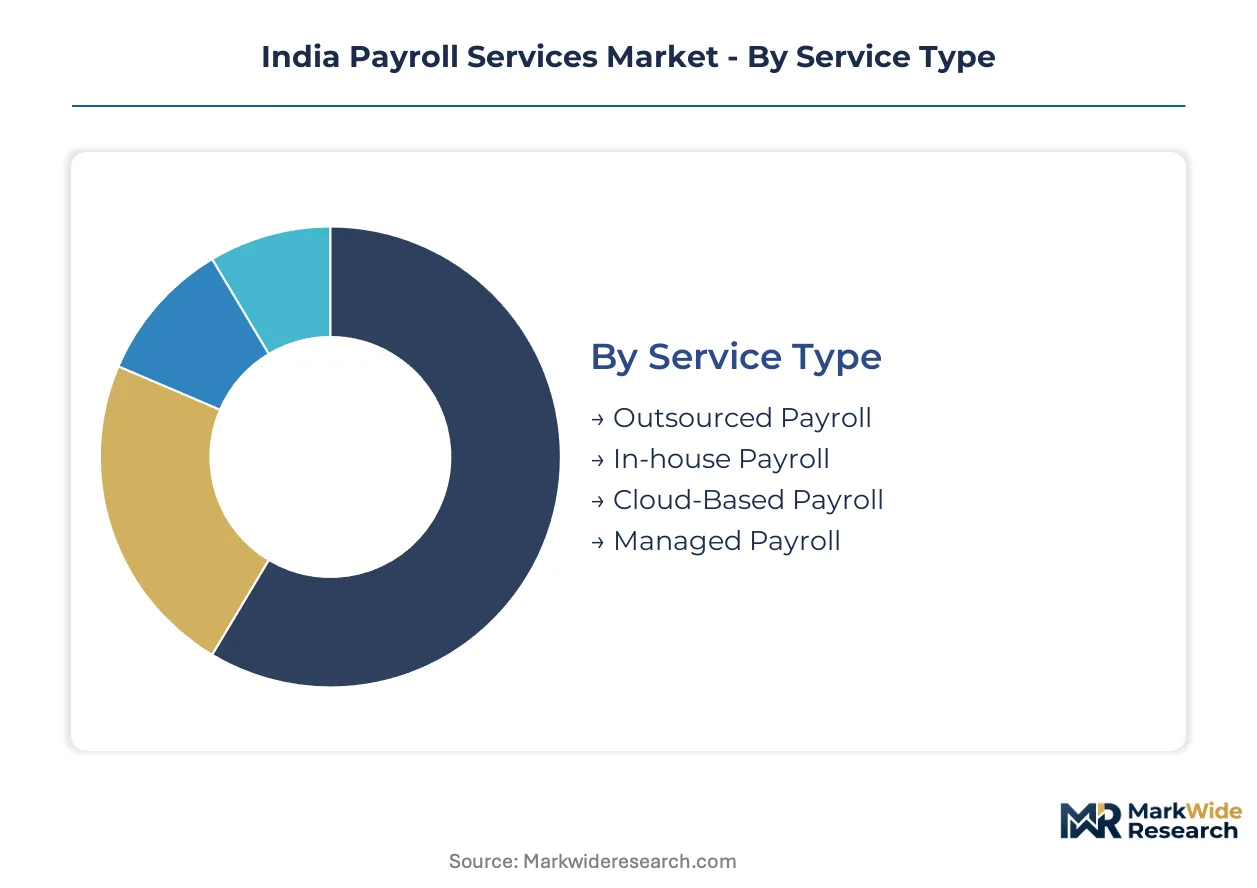
Payroll services in India fragment across four critical dimensions that determine vendor capability requirements and pricing architecture. Service type and deployment model dictate technology infrastructure investments, while client size and industry vertical shape compliance complexity and customization depth.
Service Type:
Capital intensity peaks with managed payroll engagements requiring dedicated compliance engineering teams and multi-state regulatory coverage infrastructure.
- Outsourced Payroll:Third-party vendors assume full wage computation, statutory deduction administration, and regulatory filing obligations. Bengaluru IT clusters and Mumbai financial services hubs concentrate demand as distributed workforces multiply compliance touchpoints.
- Cloud-Based Payroll:Native SaaS architectures deliver real-time accessibility for GST-era audit trails without on-premise hardware depreciation. Medium enterprises in Gujarat and Tamil Nadu manufacturing corridors are displacing legacy installations fastest.
- In-house Payroll:Enterprise-controlled systems retain sensitive compensation data internally, requiring substantial upfront licensing and dedicated IT security staffing.
- Managed Payroll:Comprehensive outsourcing bundles technology platform with dedicated account management and proactive regulatory update implementation.
Outsourced payroll absorbs the bulk of installed capacity; cloud-based payroll is expanding most quickly.
Client Size:
Implementation complexity and account management intensity vary dramatically across organizational scale, with mid-market segments driving platform standardization investments.
- Large Corporations:Multi-entity structures spanning Indian states and overseas jurisdictions demand orchestration protocols for consolidated reporting. ESOP administration and expatriate compensation layers elevate service customization requirements.
- Medium Enterprises:Organizations with 100-1000 employees represent the fastest behavioral shift toward subscription pricing aligned with cash flow cycles. UPI-integrated disbursement removes legacy banking friction that previously blocked outsourcing adoption.
- Small Enterprises:Limited compliance expertise in-house creates vulnerability to state-level Professional Tax variation penalties.
- Startups:Equity-heavy compensation structures and rapid headcount fluctuation demand flexible pricing and accelerated implementation timelines.
Large corporations command the deepest vendor penetration; medium enterprises are climbing the fastest.
Deployment Model:
Physical infrastructure requirements and data sovereignty constraints segment capital deployment and ongoing operational expenditure profiles.
- Cloud:Browser-accessible platforms eliminate server maintenance and enable automatic regulatory update propagation. Real-time accessibility satisfies Employees' Provident Fund Organisation and state Professional Tax authority audit trail demands.
- Hybrid:Sensitive compensation data resides on-premise while disbursement execution leverages cloud connectivity. Manufacturing enterprises in legacy industrial zones favor this architecture for incremental migration.
- On-Premise:Perpetual license models with substantial hardware investment persist in public sector and established manufacturing installations resistant to data externalization.
- Remote:Distributed access architectures supporting work-from-anywhere payroll administration gained structural traction post-pandemic.
Cloud deployment holds the dominant share; hybrid configurations are gaining share fastest.
Industry Vertical:
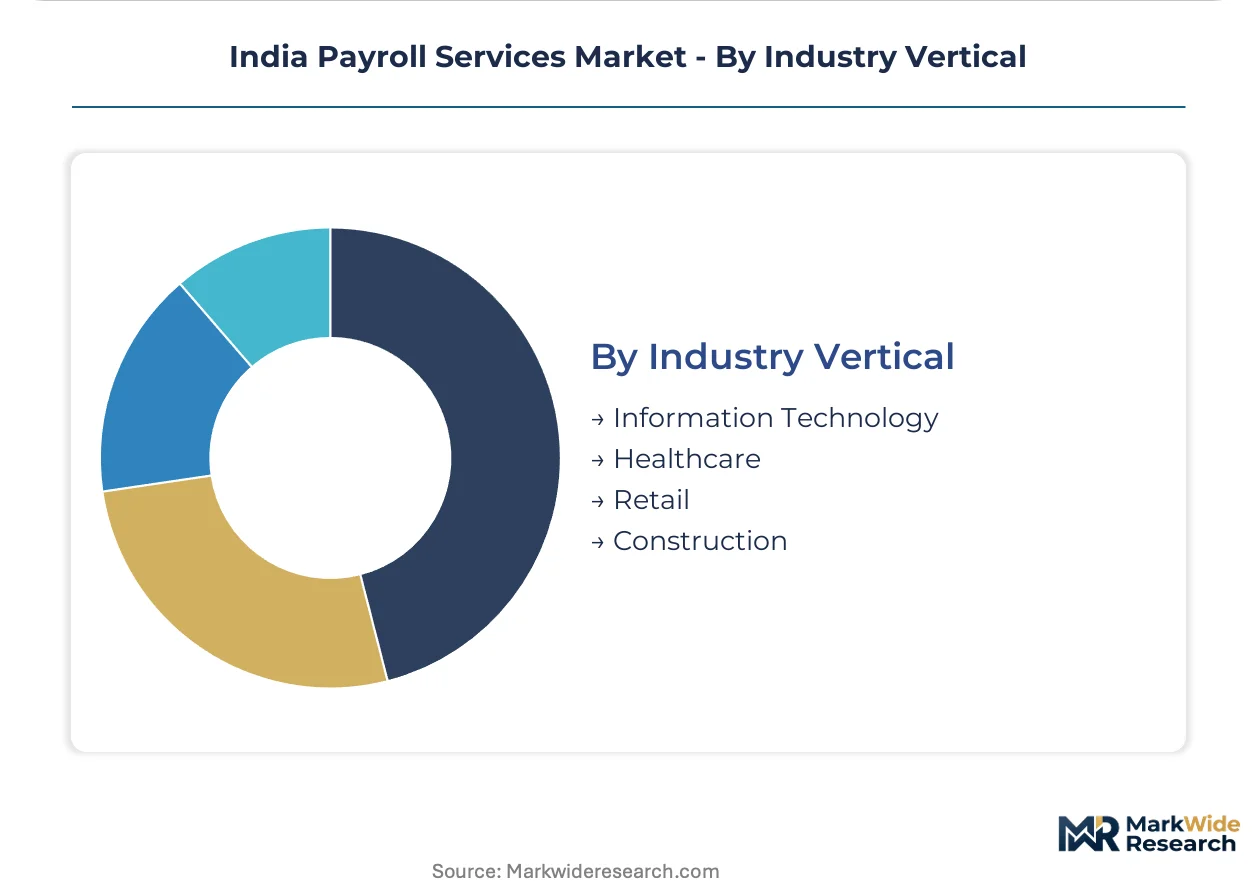
Regulatory exposure and workforce distribution patterns determine compliance automation priorities and platform feature requirements.
- Information Technology:Distributed workforces across Bengaluru, Hyderabad, and Pune clusters combine with ESOP complexity and expatriate administration to sustain deepest outsourcing penetration. PLI scheme incentives for hardware manufacturing are adding contract workforce layers.
- Healthcare:Multi-shift operations and statutory benefit variations across hospital networks drive demand for automated deduction engines. National Capital Region and Chennai medical corridors concentrate implementation activity.
- Retail:High seasonal headcount fluctuation and distributed store networks create payroll frequency complexity.
- Construction:Project-based employment and migrant worker documentation requirements generate unique compliance verification challenges.
Information Technology anchors vendor revenue concentration; healthcare is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Payroll service consumption concentrates in India's commercial corridors while platform development gravitates toward technology clusters. The Ministry of Labour and Employment's digitization mandates are compressing regional adoption timelines unevenly across state-level regulatory environments.
Maharashtra
Mumbai's financial services hub and Pune's manufacturing belt generate concentrated demand for multi-state compliance orchestration. The state's Professional Tax authority maintains among India's most complex deduction schedules, forcing vendors to deploy dedicated engineering resources. Thane and Navi Mumbai industrial zones are accelerating cloud payroll migration as GST audit trail requirements harden.
Karnataka
Bengaluru's technology corridor sustains the deepest payroll outsourcing penetration given distributed workforce complexity and ESOP administration requirements. The state's implementation of Code on Wages centralized definitions is proceeding faster than national averages, compressing vendor upgrade cycles. Whitefield and Electronic City clusters are driving subscription pricing adoption among mid-market enterprises.
Telangana
Hyderabad's pharmaceutical and IT special economic zones are expanding contract workforce layers under PLI scheme incentives, multiplying compliance touchpoints. The state government's integration with Employees' Provident Fund Organisation digital infrastructure is removing legacy filing friction. Cyberabad and Genome Valley industrial areas are attracting vendors with multi-country payroll capabilities for export-oriented enterprises.
Tamil Nadu
Chennai's automotive and healthcare manufacturing corridors are displacing on-premise installations fastest among India's industrial states. The state's Professional Tax variation across corporation boundaries forces granular compliance engine configuration. Sriperumbudur and Oragadam industrial belts are driving UPI-integrated salary disbursement adoption among small and medium enterprises.
Delhi-NCR
The National Capital Region's concentration of corporate headquarters and government liaison offices creates demand for regulatory update anticipation services. Haryana and Uttar Pradesh sub-regions within NCR exhibit divergent Employee State Insurance implementation timelines, complicating unified platform deployment. Gurugram and Noida technology parks are anchoring vendor talent acquisition for compliance engineering roles.
India Payroll Services Market Competitive Landscape
The competitive structure tilts toward SaaS-native specialists challenging legacy multinational protocols. Market concentration remains moderate with no single vendor commanding dominant share, though tiering is visible between enterprise-grade orchestrators and mid-market automation platforms. Two strategic archetypes predominate: multinational protocol libraries serving large corporations with overseas operations, and state-specific compliance engines built for India's statutory fragmentation. Competitive moves center on regulatory update velocity and ERP integration depth rather than price-based displacement.
Within the multinational protocol tier, ADP India anchors premium enterprise positioning through its global compliance infrastructure. Neeyamo occupies a specialized position in multi-country payroll orchestration for Indian firms expanding into Southeast Asian and Middle Eastern markets. Among SaaS-native competitors, GreytHR exemplifies the state-specific compliance engine archetype with architecture purpose-built for India's Professional Tax and Provident Fund variations. These three vendors collectively represent the strategic poles—global scale versus local statutory precision—around which competitive positioning organizes.
| Leading Market Players |
|---|
| ADP India |
| Neeyamo |
| Quess Corp |
| Aon Hewitt India |
| Alight Solutions India |
| GreytHR |
| Paybooks |
| Quikchex |
| PaySquare |
| Others |
Pricing and Supply Chain Analysis
Mid-market enterprises in Gujarat and Tamil Nadu manufacturing corridors concentrate purchasing power, anchoring subscription pricing dominance as UPI-integrated disbursement removes legacy banking friction that previously blocked SaaS adoption at this tier.
Pricing Analysis
Margin tightening in managed payroll tiers reflects compliance engineer scarcity and multi-state regulatory coverage costs. Subscription pricing stratifies across premium orchestration, standard automation, and economy self-service tiers, with differentiation driven by ERP integration depth and dedicated account management. Cost-down pressure accelerates as SaaS-native vendors compress implementation timelines. Small enterprises exhibit highest price sensitivity; large corporations with ESOP complexity show lowest.
Supply Chain Analysis
Freight costs for on-premise server hardware and data center equipment elevate total cost of ownership for legacy installations resistant to cloud migration. Platform development concentrates in India, with compliance engineering talent clustering in Bengaluru, Mumbai, and Delhi-NCR. Cloud infrastructure draws from hyperscaler networks; proprietary compliance engines rest on state-specific statutory interpretation databases. Single-source vulnerability sits with concentrated compliance expertise geography. Distribution runs through direct enterprise sales and channel partners serving tier-2 cities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Labour code consolidation is compressing vendor upgrade cycles, forcing weaker players lacking regulatory update velocity into acquisition or exit.
For Market Incumbents: Acquire compliance engineering talent pools in Bengaluru and Delhi-NCR to defend against SaaS-native entrants with faster statutory interpretation deployment. Deepen ERP integration partnerships with SAP and Oracle to raise switching costs. The threat of Neeyamo's multi-country orchestration for Indian firms expanding overseas demands preemptive capability builds. For New Entrants and Emerging Players: Launch via UPI-integrated salary disbursement partnerships targeting Tamil Nadu and Gujarat manufacturing corridors where medium enterprises show fastest behavioral shift. White space concentrates in tier-2 city markets underserved by talent concentration in metro clusters. Position against legacy on-premise entrenchment in public sector and established manufacturing. For Investors and Strategic Acquirers: The window for entry favors SaaS-native platforms with state-specific compliance engines over multinational protocol libraries vulnerable to localization gaps. Long-term viability hinges on regulatory update velocity as Code on Social Security implementation proceeds. Watch for National Payroll Portal partnership announcements as inflection indicator for vendor integration opportunity versus public-sector competition.| Strategic Initiative | Industry Significance |
|---|---|
| Compliance Engine Acquisition | Absorbs scarce Professional Tax interpretation talent from fragmented regional vendors. |
| UPI Disbursement Partnership | Removes legacy banking friction blocking mid-market SaaS adoption in manufacturing corridors. |
| ERP Integration Certification | Raises switching costs through embedded connectivity with SAP and Oracle installed bases. |
| Multi-Country Protocol Buildout | Captures Indian firm overseas expansion orchestration demand in Southeast Asian markets. |
| National Payroll Portal Positioning | Secures official technology partner status ahead of consolidated reporting obligation launch. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews across payroll operations directors, compliance engineering leads, HR technology procurement officers, and channel sales heads at implementation partners. Ministry of Labour and Employment digitization mandates, EPFO circulars, and state Professional Tax authority schedules provided statutory framework validation. Bottom-up enterprise adoption modeling and top-down market sizing triangulated volume estimates.
Granularity extended to deployment model, client size tier, industry vertical, and state-level regulatory cluster across the projection horizon. CAGRs derived from segment-specific adoption curves and pricing trajectory analysis. Labor code implementation timelines and UPI penetration rates served as payroll-specific forecast inputs alongside cloud infrastructure expansion metrics.
Regulatory delay, labor code judicial challenge, and National Payroll Portal scope revision are the dominant revision risks to modeled assumptions. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Financial Services
South Korea Factoring Services Market
Financial Services
Europe B2C Legal Services Market
Financial Services
Online Lottery Market
Financial Services
Contract for Difference Broker Market
Financial Services
United Kingdom E-Brokerage Market
Financial Services
ATM Management Service Market
Financial Services
Europe E-Brokerages Market
Financial Services
South Korea Trade Finance Market
Financial Services
Saas Escrow Services Market
Financial Services
Global Temporary Labor Market
Financial Services
Virtual Account Management Software Market
Financial Services
Global Financial Consulting Software Market
Financial Services
Africa Lottery Market
Financial Services
Europe Factoring Services Market
Financial Services
Check Cashing Services Market
Financial Services
Canada Credit Cards Market