
 Global Management Consulting Services Market | 2026-2036
Global Management Consulting Services Market Size, Share, and Industry Trends Forecast 2026-2036
Global Management Consulting Services Market Outlook
London's partnership pipeline for advisory talent is hardening as boutiques and global networks compete for the same specialist pools. McKinsey & Company anchors its competitive edge through proprietary knowledge management systems that codify sector expertise across engagements. Bain & Company differentiates via its private equity due-diligence heritage, a capability that now extends into broader corporate strategy mandates.
Management consulting services encompass structured advisory engagements where external experts diagnose organizational problems, design operational or strategic interventions, and oversee implementation through defined methodologies and measurable deliverables. The practice spans four primary service types: strategy consulting guides C-suite decisions on market positioning and portfolio allocation; operations consulting targets cost structures and supply chain reconfiguration; financial advisory structures capital deployment and risk frameworks; human resource consulting redesigns talent architectures and compensation systems. Operations consulting occupies the deepest margin pools because clients pay premium rates for measurable cost reductions, while outcome-based engagement models are gaining traction as procurement functions demand risk-sharing arrangements.
The EU AI Act and GDPR compliance frameworks in Europe, SEC climate disclosure rules in the United States, and RBI governance guidelines for Indian financial institutions are expanding the scope of regulatory advisory work. These frameworks compel clients to seek external expertise on algorithmic accountability, data governance architecture, and ESG reporting infrastructure. Stakeholders must monitor how jurisdictional regulatory divergence creates specialized demand for geographically anchored compliance expertise rather than generic global playbooks.
Market Dynamics
Advisory firms face intensifying pressure to demonstrate measurable client outcomes as procurement functions embed risk-sharing clauses into engagement contracts, compressing traditional time-and-materials billing structures.
Growth Catalysts
- EU AI Act compliance mandates:European enterprises require external expertise to operationalize algorithmic accountability frameworks and governance architecture ahead of enforcement deadlines.
- Healthcare operational transformation:Hospital systems and pharmaceutical manufacturers are expanding advisory budgets to reconfigure supply chains and clinical workflows.
- India:The Reserve Bank of India's governance guidelines for financial institutions are generating specialized demand for regulatory advisory and risk framework design.
Market Restraints
- Talent scarcity in specialized domains:Boutique firms and global networks compete for the same pools of AI ethics and climate risk specialists, inflating compensation costs.
- Regulatory fragmentation:Divergent SEC climate disclosure rules, EU CSRD requirements, and RBI guidelines force firms to maintain geographically anchored expertise rather than deploy generic playbooks.
- Substitution by in-house strategy functions:Large corporations are building internal consulting capabilities, particularly in technology and data analytics, reducing reliance on external advisors.
Strategic Opportunities
- Germany's industrial decarbonization:Mittelstand manufacturers require operational consulting to navigate EU Green Deal compliance and energy transition planning.
- Outcome-based engagement models:Procurement functions in the United States are piloting contracts tying advisory fees to measurable cost reduction or revenue targets.
- Convergence of ESG reporting and data governance:Firms that integrate CSRD disclosure infrastructure with GDPR-compliant data architecture capture cross-selling opportunities.
Industry Challenges
- Knowledge codification bottlenecks:Firms struggle to transfer partner-level expertise into scalable digital assets that junior staff can deploy without senior oversight.
- Client-side implementation gaps:Advisory recommendations often stall due to organizational resistance or insufficient client change-management capacity, damaging renewal rates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Management Consulting Services Market |
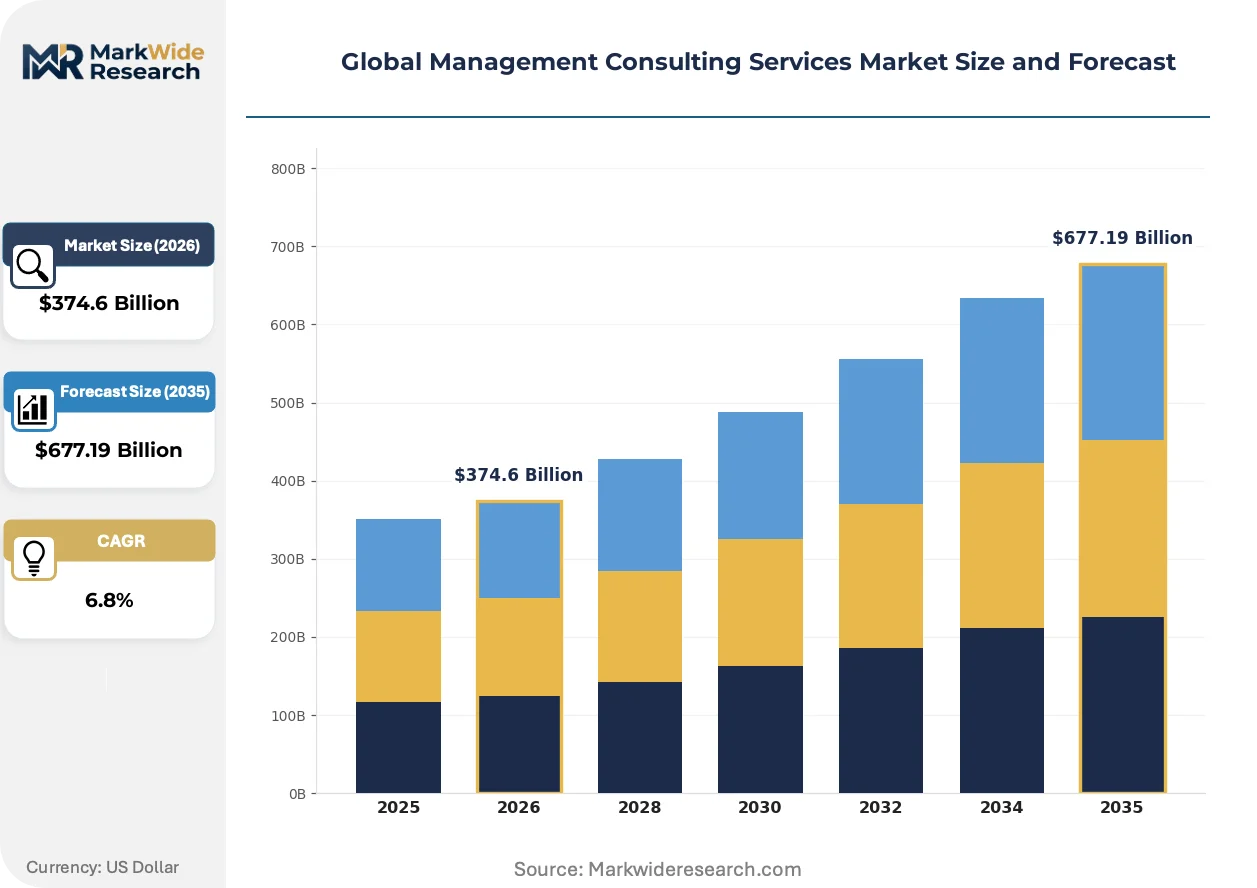
| Market Size in 2026 | $374.6 Billion |
| Market Size in 2035 | $677.19 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Strategy Consulting, Operations Consulting, Financial Advisory, Human Resource Consulting Industry Vertical: Healthcare, BFSI, Technology, Energy Engagement Model: Project-Based, Retainer-Based, Outcome-Based, Advisory Client Size: SMEs, Large Enterprises, Startups, Multinationals |
| Companies Covered | Deloitte Consulting, EY-Parthenon, McKinsey & Company, Oliver Wyman, KPMG Advisory, Boston Consulting Group, PwC Strategy&, Roland Berger, Bain & Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Management Consulting Services Market Strategic Shifts
Generative AI tools are penetrating advisory workflows, forcing firms to reconfigure service delivery models and talent structures around augmented intelligence rather than pure human expertise.
Large language models are automating research synthesis, document generation, and preliminary diagnostic work that previously consumed junior consultant hours. Private equity due-diligence teams and corporate strategy functions are deploying these tools to compress timeline and reduce engagement scope. This compression is automating entry-level task categories and reshaping firm pyramids toward smaller cohorts of senior specialists.
The EU AI Act's risk-based classification system for algorithmic systems is mandating external audits and documentation standards for high-risk applications. Industrial consequence includes expanded advisory mandates for conformity assessment and post-market monitoring. Financial services and healthcare sectors across Germany, France, and the Netherlands are engaging firms to build governance infrastructure ahead of 2025 enforcement.
Buyers are unbundling strategy formulation from implementation support, contracting separate providers for diagnostic and execution phases. This fragmentation disrupts traditional full-service relationships and favors boutiques with deep vertical expertise or technology-enabled delivery platforms. The pattern is most visible in United States technology and healthcare sectors, where procurement functions segment engagements by capability rather than brand.
Global Management Consulting Services Market Segmentation
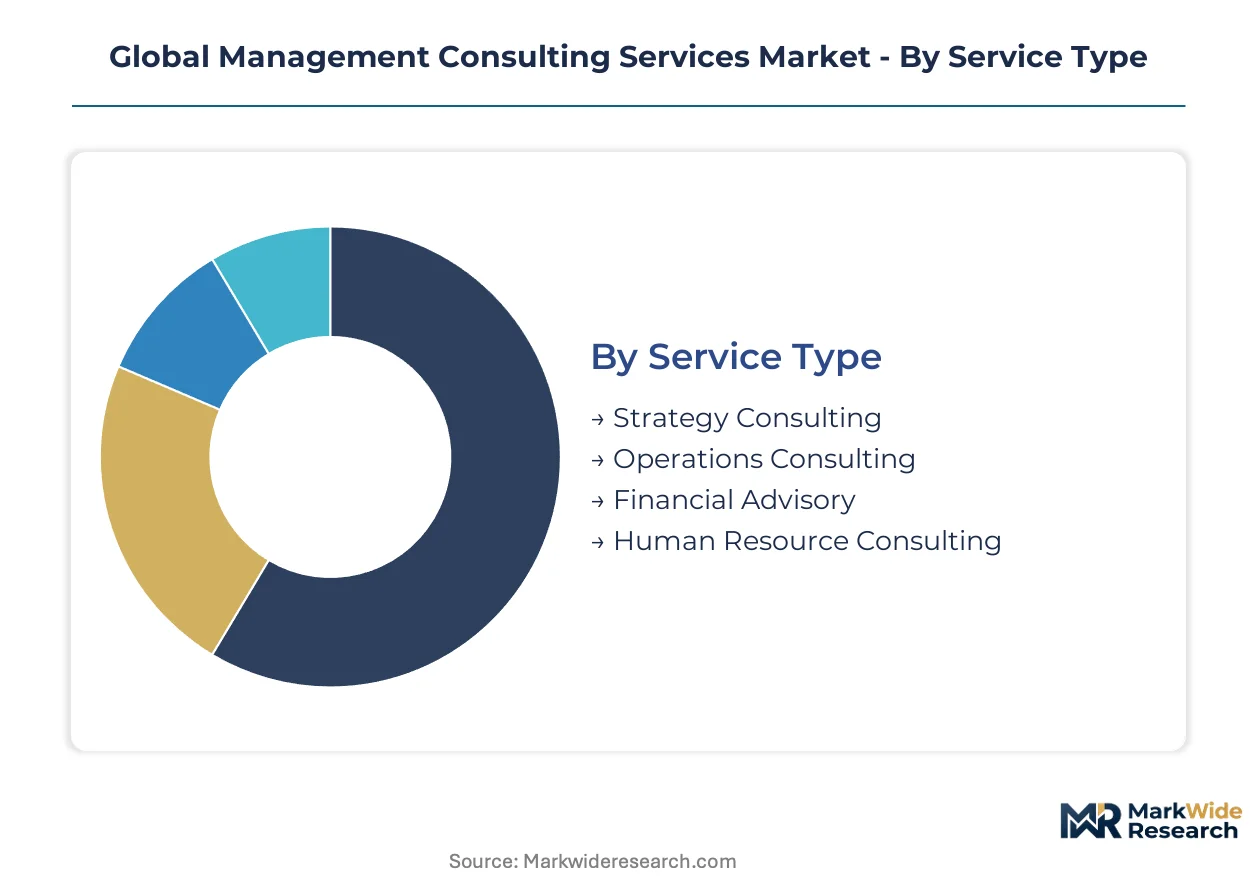
Advisory buyers are unbundling engagements by capability and risk profile, forcing firms to specialize across service lines rather than sell integrated portfolios. Procurement functions now segment contracts by measurable deliverables, reshaping how consultancies structure pricing and talent deployment.
Service Type:
Upgrade cycles in advisory procurement are shortening as clients replace legacy time-and-materials relationships with outcome-defined contracts that demand demonstrable returns.
- Operations Consulting:Engagements target cost structure reconfiguration, supply chain optimization, and process automation with quantified efficiency gains. Hospital systems in the United States and Mittelstand manufacturers in Germany pay premium rates for engagements tied to measurable operational improvements.
- Strategy Consulting:C-suite mandates span market positioning, portfolio allocation, and competitive response design. Private equity firms in London and corporate development teams in Mumbai are expanding due-diligence and merger advisory scopes.
- Financial Advisory:Capital deployment structuring, risk framework design, and regulatory capital optimization. RBI governance guidelines for Indian financial institutions are expanding demand for external risk architecture expertise.
- Human Resource Consulting:Talent architecture redesign, compensation system restructuring, and workforce transformation. Technology firms in Bangalore and pharmaceutical manufacturers in Basel are engaging for post-merger integration support.
Operations Consulting sits at the top of the volume ranking, with Outcome-Based engagement models climbing the fastest.
Industry Vertical:
Cost tier differentiation in advisory procurement separates compliance-mandated spending from discretionary strategic investment.
- Healthcare:Hospital systems and pharmaceutical manufacturers are expanding advisory budgets for supply chain reconfiguration and clinical workflow transformation. FDA regulatory complexity and EU MDR compliance are driving external expertise demand in Boston and Basel clusters.
- BFSI:Banks, insurers, and asset managers require risk framework redesign and digital infrastructure advisory. SEC climate disclosure rules and RBI governance guidelines are expanding regulatory advisory mandates across New York and Mumbai.
- Technology:Software vendors and platform enterprises engage for market entry strategy and operational scaling. EU AI Act compliance is creating specialized demand for algorithmic accountability frameworks in Berlin and Amsterdam.
- Energy:Utilities and renewable developers need decarbonization planning and regulatory navigation support. EU Green Deal compliance and Germany's industrial transformation are expanding advisory scopes in Düsseldorf and Copenhagen.
Healthcare commands the largest advisory spend, with Energy expanding most quickly on decarbonization mandates.
Engagement Model:
Application-specific contracting separates diagnostic advisory from implementation support, fragmenting traditional full-service relationships.
- Project-Based:Defined-scope engagements with fixed deliverables and timeline-bound execution. Large enterprises in the United States segment transformation programs into discrete project phases to manage procurement risk.
- Retainer-Based:Ongoing advisory access for strategic counsel and rapid-response support. Multinationals with complex regulatory footprints maintain retainer relationships for cross-border compliance coordination.
- Outcome-Based:Fee structures tied to measurable cost reduction, revenue targets, or risk mitigation. Procurement functions in Germany and the United States are piloting risk-sharing clauses that compress traditional billing models.
- Advisory:Diagnostic and recommendation-focused engagements without implementation obligation. Startups and SMEs in Bangalore and São Paulo use advisory contracts for board-level strategy validation.
Project-Based engagements retain the highest volume share, with Outcome-Based models gaining share fastest on procurement pressure.
Client Size:
Customer-type segmentation separates enterprise procurement sophistication from mid-market budget constraints and startup agility requirements.
- Large Enterprises:Complex multi-jurisdictional mandates with dedicated procurement functions and formal vendor management. Fortune 500 companies in the United States unbundle strategy and implementation across multiple advisory providers.
- Multinationals:Cross-border regulatory compliance and integrated transformation programs spanning multiple geographies. EU-headquartered firms navigate GDPR, EU AI Act, and CSRD requirements through specialized advisory panels.
- SMEs:Targeted engagements for operational improvement and market expansion with constrained budgets. German Mittelstand manufacturers access advisory through industry association frameworks and subsidized consulting programs.
- Startups:Rapid-scaling support for organizational design, fundraising preparation, and market entry validation. Venture-backed technology firms in Bangalore and Tel Aviv engage boutiques for founder-coaching and investor-readiness.
Large Enterprises dominate advisory spend, with Startups showing the steepest expansion trajectory on venture capital availability.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping advisory procurement patterns as multinational clients migrate transformation budgets toward jurisdictions offering clearer compliance cost visibility. The EU AI Act's enforcement timeline and SEC climate disclosure rules create divergent cost-of-compliance gaps that drive cross-border consulting demand.
United States
Fortune 500 procurement functions unbundle strategy and implementation across multiple advisory providers. SEC climate disclosure rules expand ESG reporting infrastructure mandates. Boston and New York clusters anchor healthcare and financial services advisory demand.
Germany
Mittelstand manufacturers expand operational transformation budgets for EU Green Deal compliance. KBA and ECHA regulations drive industrial decarbonization advisory mandates. Düsseldorf and Stuttgart clusters concentrate energy transition and automotive consulting demand.
India
RBI governance guidelines for financial institutions generate specialized risk framework advisory demand. PLI scheme beneficiaries engage operational consultants for manufacturing scale-up. Mumbai and Bangalore clusters anchor BFSI and technology sector advisory procurement.
United Kingdom
London's partnership pipeline hardens as boutiques and global networks compete for specialist talent pools. FCA regulatory complexity sustains financial services advisory demand. The City and Canary Wharf clusters concentrate private equity due-diligence and merger advisory mandates.
France
ANSM and CNIL enforcement patterns expand healthcare and data governance advisory scopes. EU AI Act risk classification mandates drive algorithmic accountability consulting. Paris and Lyon clusters anchor pharmaceutical and industrial advisory demand.
Global Management Consulting Services Market Competitive Environment
United States-based networks anchor the premium-tier advisory segment; European boutiques hold specialized compliance mandates. The market structures around three tiers: global full-service networks, sector-specialist boutiques, and technology-enabled delivery platforms. Consolidation pressure intensifies as procurement functions demand outcome-based contracts that favor scale. Dominant competitive moves include knowledge codification investments and vertical capability acquisitions.
Within the global network tier, McKinsey & Company and Boston Consulting Group occupy positions defined by proprietary methodologies and partner-level expertise deployment. Among European-origin specialists, Roland Berger exemplifies the regionally anchored compliance advisory archetype. These named entities represent strategic positioning patterns rather than exhaustive market coverage.
| Leading Market Players |
|---|
| Deloitte Consulting |
| EY-Parthenon |
| McKinsey & Company |
| Oliver Wyman |
| KPMG Advisory |
| Boston Consulting Group |
| PwC Strategy& |
| Roland Berger |
| Bain & Company |
| Others |
Value Chain & Pricing Dynamics
Fortune 500 procurement functions unbundle strategy and implementation across multiple advisory providers, compressing traditional time-and-materials billing into outcome-defined contracts with risk-sharing clauses. This buyer concentration reshapes how consultancies structure talent deployment and margin protection.
Pricing Analysis
Partner-level hourly rates anchor the premium tier, while outcome-based engagement models tie fees to measurable cost reduction or revenue targets. Price differentiation stems from sector specialization depth and proprietary methodology access, with healthcare and private equity due-diligence commands attracting premium positioning. Cost compression in mid-market segments intensifies as procurement functions demand fixed-fee arrangements. SMEs exhibit highest price sensitivity, constrained by budget ceilings and competing internal consulting buildouts.
Supply Chain Analysis
Logistics costs for talent mobility and on-site delivery inflate engagement economics, particularly for cross-border mandates spanning regulatory jurisdictions. Advisory capability concentrates in the United States, United Kingdom, and India, with London, New York, and Mumbai anchoring partnership pipelines. Talent acquisition draws from elite business schools, lateral hires from competitor firms, and specialized technical academies. Single-source vulnerability in AI ethics and climate risk expertise forces premium compensation outlays. Distribution runs through direct partner relationships, industry association networks, and technology-enabled delivery platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Management Consulting Services Market functions as a stable compounder, with regulatory complexity across the EU AI Act, SEC climate rules, and RBI governance guidelines generating durable compliance-driven demand.
For Market Incumbents: Deepen knowledge codification investments to transfer partner expertise into scalable digital assets deployable by junior staff. Build outcome-based pricing capabilities to defend margin position against procurement pressure. Vertical integration into implementation support captures execution-phase revenue currently leaking to specialized boutiques. For New Entrants and Emerging Players: Enter via narrow vertical specialization in algorithmic accountability or industrial decarbonization advisory, where global networks lack granular expertise. Target German Mittelstand manufacturers and Indian PLI scheme beneficiaries with compliance-mandated spending and limited incumbent relationships. Lead with technology-enabled delivery platforms that compress timeline and undercut traditional billing models. For Investors and Strategic Acquirers: Private equity firms with portfolio company transformation needs are the most active acquirer in this space, seeking captive advisory capabilities. The market supports a 5-10 year investment horizon anchored by regulatory expansion rather than cyclical demand. Monitor procurement function unbundling patterns as the signal indicating boutique consolidation acceleration versus platform-scale winner-take-all dynamics.| Strategic Initiative | Industry Significance |
|---|---|
| Knowledge Codification Investment | Proprietary digital assets enable junior staff deployment without senior oversight, compressing cost structures. |
| Vertical Capability Acquisition | Specialist boutiques in AI ethics or climate risk deliver regulatory expertise that generalist networks cannot replicate internally. |
| Outcome-Based Contracting Infrastructure | Risk-sharing arrangements align advisory fees with client results, defending renewal rates against procurement pressure. |
| Technology-Enabled Delivery Platform | Generative AI tools automate research synthesis and document generation, reshaping firm pyramids toward senior specialists. |
| Geographic Expansion into Regulatory Growth Markets | EU AI Act enforcement and RBI governance guidelines create specialized demand for locally anchored compliance expertise. |
Study Parameters
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combined with secondary validation. Primary research incorporated interviews with consulting firm partners, procurement executives at Fortune 500 companies, regulatory affairs leads, and private equity operating partners. Secondary sources included SEC filings, EU regulatory documentation, RBI circulars, and industry association expenditure surveys. Bottom-up engagement value estimates triangulated against top-down market sizing from advisory spend disclosures.
Granularity-level modeling operated at service type, industry vertical, engagement model, and client size dimensions, with geographic regulatory clusters as a cross-cutting layer. CAGRs were derived from trend extrapolation anchored to enforcement timelines for the EU AI Act and SEC climate disclosure rules. Forecast inputs incorporated healthcare operational transformation budgets, Mittelstand decarbonization spending, and PLI scheme manufacturing scale-up advisory demand across the projection horizon.
Inputs from regulatory filings and advisory firm disclosures were available through the study window; gaps in private boutique financial data introduce uncertainty bands around market share estimates. Forecasts reflect assumptions regarding enforcement timelines and procurement function evolution. A model refresh is warranted upon material change in EU AI Act implementation patterns or SEC climate rule litigation outcomes.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Financial Services
Qatar Analysis of Key Sectors and Investment Opportunities Market
Financial Services
Benefits Consulting Service Market
Financial Services
China Trade Finance Market
Financial Services
Online Investment Platform Market
Financial Services
Source to Pay Market
Financial Services
Intellectual Property Rights and Royalty Management Market
Financial Services
Outsource Debt Collection Services Market
Financial Services
Italy Gift Card and Incentive Card Market
Financial Services
ATM Management Service Market
Financial Services
Spain E-Brokerage Market
Financial Services
UK Islamic Finance Market
Financial Services
South Korea Factoring Services Market
Financial Services
Europe Factoring Services Market
Financial Services
Broker Affiliate Programs Market
Financial Services
Hong Kong Trade Finance Market
Financial Services
Digital Transformation in BFSI Market