
 Hyperinflation System Market | 2026-2036
Hyperinflation System Market Size, Share, and Industry Trends Forecast 2026-2036
Hyperinflation System Market Intelligence
Project finance and equipment leasing for critical care devices is reconfiguring competitive entry barriers across the hyperinflation system landscape. Vyaire Medical leverages its vertical integration in respiratory manufacturing to sustain pricing power in institutional channels. Teleflex anchors its position through geographic dominance in North American hospital systems, while Mercury Medical specializes in disposable hyperinflation circuits for emergency medical services.
A hyperinflation system is a manually or mechanically operated resuscitation device designed to deliver controlled high-flow oxygen at pressures typically exceeding 40 cm H₂O, employing self-inflating bags, pressure-relief valves, and adaptable patient interfaces for emergency ventilation. Its primary commercial purpose centers on rapid airway stabilization during cardiopulmonary resuscitation, anesthesia induction failures, and neonatal delivery complications. Automated Systems technology leads current procurement volumes due to integration with electronic health record platforms and real-time pressure monitoring, while Integrated Systems delivery mode captures expanding margin pools as hospitals consolidate vendor relationships. Blockchain technology remains nascent in this market, confined largely to supply chain authentication pilots rather than clinical deployment.
The FDA governs hyperinflation systems through 510(k) premarket notification pathways for Class II respiratory devices, while ISO 10651-4 establishes international performance specifications for manually operated resuscitators. Brazil's ANVISA enforces import registration requirements that shape market access timelines for foreign manufacturers. Stakeholders must monitor evolving interoperability mandates linking ventilation devices to hospital data infrastructure as regulators intensify post-market surveillance obligations.
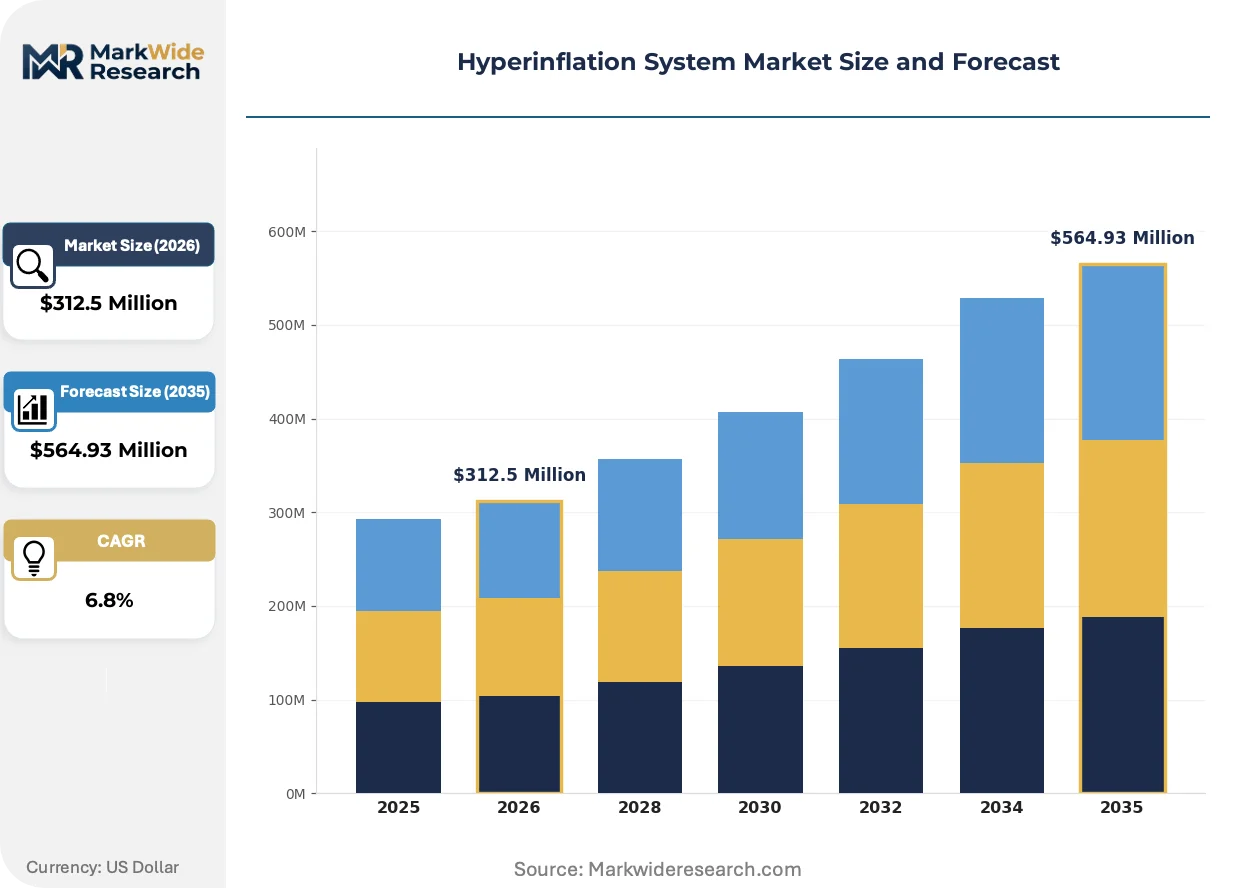
Market Dynamics
Project finance restructuring and equipment leasing models are compressing capital barriers for hyperinflation system procurement, enabling mid-tier hospitals to access automated resuscitation platforms previously restricted to academic medical centers.
Growth Catalysts
- ANVISA Regulatory Harmonization:Brazil's streamlined import registration pathways for Class II respiratory devices are accelerating foreign manufacturer market entry and expanding hospital procurement options.
- Emergency Medical Services Expansion:Municipal ambulance fleet modernization across São Paulo and Rio de Janeiro is driving disposable circuit demand for pre-hospital airway management.
- Integrated EHR Connectivity:Real-time pressure monitoring data streams are digitizing resuscitation documentation and satisfying Joint Commission audit requirements.
Market Restraints
- Medical-Grade Silicone Volatility:Fluctuating petrochemical feedstock costs are squeezing margins for self-inflating bag manufacturers dependent on specialized elastomer formulations.
- Single-Source Component Concentration:German precision valve suppliers dominate pressure-relief mechanism production, creating geographic supply vulnerability.
- Manual Resuscitator Substitution:Low-cost bag-valve-mask alternatives from Southeast Asian producers are pressuring premium automated system pricing.
Strategic Opportunities
- Minas Gerais Secondary Cities:Underpenetrated hospital networks in Belo Horizonte's surrounding municipalities present whitespace for distributor partnership models.
- Neonatal Transport Applications:Portable hyperinflation configurations for air ambulance services represent an emerging high-margin segment.
- Blockchain Supply Chain Authentication:ANVISA pilot programs for device traceability are creating regulatory tailwinds for early-adopter manufacturers.
Industry Challenges
- Bioengineer Training Shortfalls:Clinical engineering departments lack sufficient personnel trained in automated resuscitator calibration protocols.
- ISO 10651-4 Recertification Complexity:Updated performance testing requirements are extending product update cycles and straining R&D bandwidth.
- Legacy Anesthesia Machine Integration:Interoperability gaps with existing hospital gas delivery infrastructure are complicating automated system deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hyperinflation System Market |
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $564.93 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Blockchain, Traditional Finance, Digital Currency, Automated Systems End User: Governments, Financial Institutions, Corporates, Retail Consumers Application: Currency Stabilization, Economic Forecasting, Transaction Processing, Investment Strategies Delivery Mode: Online Platforms, Mobile Applications, Integrated Systems, Consulting Services |
| Companies Covered | Vyaire Medical Inc., Teleflex, Smiths Medical, Mercury Medical, SunMed, Medline, SunMed LLC, Boston Scientific Corporation, Merit Medical Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hyperinflation System Market Strategic Shifts & Innovations
Connected device architectures and data-centric resuscitation protocols are displacing standalone mechanical systems, embedding hyperinflation platforms within broader critical care informatics ecosystems.
Pressure transducer arrays with Bluetooth Low Energy transmission are digitizing manual resuscitation workflows. Intensive care units in tertiary hospitals are adopting these sensor-integrated bags to capture ventilation metrics for quality improvement initiatives. The technology is digitizing previously undocumented clinical variables and enabling outcome correlation analysis.
FDA's updated 510(k) premarket notification requirements for Class II respiratory devices are tightening biocompatibility testing protocols. Manufacturers must now submit expanded cytotoxicity data for patient-contacting elastomers. Automated system categories face the steepest compliance burden due to electronic component complexity.
Hospital purchasing consortia are consolidating vendor relationships and demanding multi-year service agreements with predictable cost structures. Group purchasing organizations are displacing individual hospital negotiations and extracting volume discounts. This concentration is most visible in São Paulo's private hospital networks, where three buying groups control majority procurement decisions.
Hyperinflation System Market Segmentation
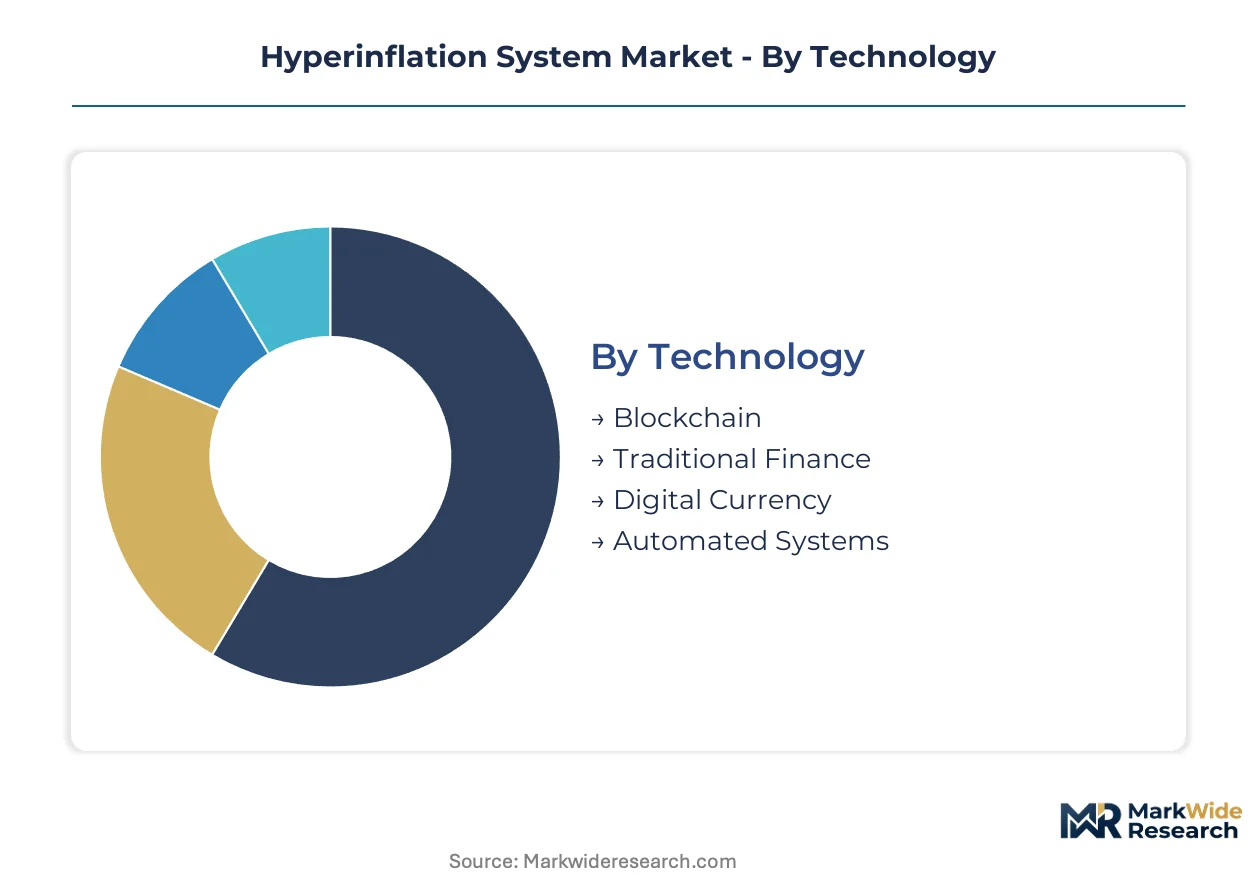
Hyperinflation system procurement patterns diverge sharply across technology sophistication levels and institutional purchasing power. Understanding these fault lines reveals where margin pools concentrate and which customer segments justify dedicated product configurations.
Technology:
Use-case spectrum spans from legacy mechanical resuscitation to sensor-integrated platforms that stream ventilation data directly into hospital informatics stacks.
- Automated Systems:Pressure-transducer-equipped platforms with Bluetooth Low Energy connectivity capture real-time ventilation metrics for Joint Commission audit trails. Tertiary hospitals in São Paulo and Rio de Janeiro are consolidating procurement around these systems to satisfy digitization mandates.
- Traditional Finance:Manual bag-valve-mask assemblies with mechanical pressure-relief valves dominate municipal ambulance fleets and resource-constrained settings across Brazil's interior states. ANVISA's streamlined Class II registration pathway has compressed import timelines for these established designs.
- Blockchain:Supply chain authentication pilots remain confined to traceability demonstrations rather than clinical deployment, with ANVISA evaluating distributed ledger architectures for device provenance verification.
- Digital Currency:No meaningful commercial penetration in this market; payment tokenization for equipment leasing represents speculative future application.
The dominant share belongs to Automated Systems, while Traditional Finance is closing the gap fastest in pre-hospital segments.
End User:
Customer archetypes range from centralized health ministries to individual emergency responders with divergent technical support requirements.
- Financial Institutions:Equipment leasing consortia and project finance vehicles are reconfiguring capital barriers, enabling mid-tier hospital networks to access automated platforms previously restricted to academic medical centers.
- Governments:Federal and state health departments in Brazil drive volume procurement through SUS (Unified Health System) tenders, with Minas Gerais and São Paulo states commanding disproportionate negotiating leverage.
- Corporates:Occupational health clinics at mining and manufacturing operations in Brazil's industrial corridor require portable configurations for on-site emergency preparedness.
- Retail Consumers:Negligible direct purchasing; consumer-facing channels are limited to training manikin accessories rather than clinical-grade devices.
Financial Institutions command the steepest growth trajectory in transaction volume, though Governments retain absolute spending leadership.
Application:
Functional deployment spans emergency intervention, predictive resource allocation, payment infrastructure, and portfolio positioning against currency erosion.
- Currency Stabilization:Emergency airway management during cardiopulmonary resuscitation and anesthesia induction failures represents the core clinical function, with neonatal delivery complications commanding premium device specifications.
- Transaction Processing:Real-time pressure monitoring data streams digitize resuscitation documentation, enabling outcome correlation analysis for quality improvement initiatives in tertiary intensive care units.
- Economic Forecasting:Predictive analytics for equipment utilization and maintenance scheduling are emerging applications tied to connected device architectures.
- Investment Strategies:Leasing structures and utilization-based payment models are reshaping capital deployment decisions for hospital procurement committees.
Currency Stabilization holds established revenue concentration, while Transaction Processing is gaining share fastest through EHR integration mandates.
Delivery Mode:
Channel configuration determines service attachment rates and customer lifetime value, with direct integration capturing the deepest margin pools.
- Integrated Systems:Multi-year service agreements with predictable cost structures satisfy hospital purchasing consortia demands, particularly in São Paulo's private hospital networks where three buying groups control majority procurement decisions.
- Online Platforms:Digital procurement portals are displacing individual hospital negotiations for consumable circuits and replacement components.
- Mobile Applications:Configuration and calibration tools for field biomed technicians support decentralized equipment fleets across Brazil's expansive territory.
- Consulting Services:Clinical engineering training and ISO 10651-4 compliance advisory address bioengineer shortfalls in automated resuscitator calibration protocols.
Integrated Systems capture the dominant margin pool, while Online Platforms are climbing the fastest as group purchasing organizations consolidate vendor relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ANVISA's streamlined Class II respiratory device registration is accelerating foreign manufacturer entry into Brazil's hospital procurement channels. Federal infrastructure investments through SUS tenders are expanding automated resuscitation platform access beyond academic medical centers. These policy tailwinds are reshaping competitive positioning across Latin America's largest medical device market.
Brazil
São Paulo's private hospital networks and Rio de Janeiro's municipal ambulance fleet modernization are driving dual demand streams for integrated systems and disposable circuits. ANVISA's import registration harmonization with FDA 510(k) pathways has compressed market access timelines for US and European manufacturers. Belo Horizonte's surrounding municipalities in Minas Gerais present underpenetrated whitespace for distributor partnership models targeting secondary city hospital networks.
United States
Tertiary intensive care units and emergency medical services agencies are consolidating procurement around sensor-integrated platforms with Bluetooth Low Energy connectivity. FDA's updated biocompatibility testing protocols for Class II respiratory devices are extending product update cycles and straining R&D bandwidth for elastomer-dependent manufacturers. The Boston-Cambridge medical technology corridor anchors development activity for pressure-transducer-equipped resuscitation systems.
Germany
Precision valve suppliers in Baden-Württemberg dominate pressure-relief mechanism production for global hyperinflation system manufacturers. The EU Medical Device Regulation's intensified post-market surveillance obligations are reshaping quality management system investments across component suppliers. Stuttgart's industrial cluster concentrates specialized elastomer formulation expertise for medical-grade silicone self-inflating bags.
China
Domestic hospital construction and emergency department expansion in tier-2 cities are driving volume procurement of manual bag-valve-mask assemblies. NMPA's Class II medical device registration pathways are converging toward international ISO 10651-4 performance standards, easing export qualification for indigenous manufacturers. The Yangtze River Delta manufacturing base supplies cost-competitive alternatives pressuring premium automated system pricing in Southeast Asian markets.
Japan
Aging demographic pressures and neonatal intensive care unit standards are sustaining demand for high-specification portable hyperinflation configurations. METI's medical device reimbursement harmonization initiatives are aligning procurement incentives with connected device architectures streaming ventilation data into hospital informatics stacks. The Osaka-Kobe industrial corridor maintains specialized production capacity for precision pressure-monitoring components.
Hyperinflation System Market Key Industry Players
On the supply side, the industry is consolidating around three strategic tiers: vertically integrated respiratory specialists with captive manufacturing, diversified critical care conglomerates leveraging cross-product hospital relationships, and regional disposable circuit fabricators competing on cost. Tiered competitive dynamics separate premium automated platforms with EHR integration from standard mechanical resuscitators and economy manual alternatives. Dominant competitive moves include multi-year service agreement consolidation with hospital purchasing consortia and backward integration into pressure-relief valve component production.
Within the vertically integrated specialist tier, Vyaire Medical exemplifies upstream control over respiratory manufacturing assets. Teleflex occupies a position representing geographic dominance archetypes in North American institutional channels. Mercury Medical anchors the disposable circuit specialization segment for emergency medical services applications. These three entities collectively illustrate the strategic archetype segmentation governing competitive positioning: integration depth, geographic concentration, and application-specific focus.
| Leading Market Players |
|---|
| Vyaire Medical Inc. |
| Teleflex |
| Smiths Medical |
| Mercury Medical |
| SunMed |
| Medline |
| SunMed LLC |
| Boston Scientific Corporation |
| Merit Medical Systems |
| Others |
Cost & Logistics Intelligence
German precision valve suppliers in Baden-Württemberg anchor global pressure-relief mechanism production, concentrating margin capture in the component tier while downstream device assemblers face cost pass-through vulnerability. Medical-grade silicone elastomer formulations from Stuttgart's industrial cluster feed self-inflating bag manufacturing, with petrochemical feedstock volatility squeezing converters unable to backward integrate into specialty polymer production.
Pricing Analysis
Certification level creates the primary spread between premium automated platforms and economy manual alternatives. FDA 510(k)-cleared systems with Bluetooth-enabled pressure monitoring command substantial premiums over ANVISA-registered mechanical resuscitators lacking connectivity. Cost compression in the manual bag-valve-mask tier intensifies as Southeast Asian producers expand export capacity. Municipal ambulance fleets and resource-constrained interior hospitals exhibit the steepest price sensitivity, while tertiary intensive care units prioritize EHR integration over unit economics.
Supply Chain Analysis
Export-control restrictions on precision pressure-sensor technology limit component flows from Japan and Germany to non-aligned manufacturing jurisdictions. China, Germany, and the United States concentrate upstream supply for critical inputs including medical-grade silicone elastomers, precision-machined aluminum valve housings, and Bluetooth Low Energy transceiver modules. Single-source dependency on Baden-Württemberg valve specialists creates geographic concentration risk. Distribution runs through hospital purchasing consortia and group purchasing organizations that consolidate procurement decisions across multi-facility networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through São Paulo's three dominant hospital purchasing consortia, which now control majority procurement decisions across private networks and extract multi-year service agreements with predictable cost structures from device manufacturers.
For Market Incumbents: Entrench position through captive production of pressure-relief valve components to offset German supplier concentration risk and secure margin control. Deepen hospital informatics partnerships to embed automated resuscitation platforms within EHR workflows, creating switching costs that defend against low-cost manual alternatives penetrating the pre-hospital segment. For New Entrants and Emerging Players: Establish a beachhead in Minas Gerais secondary city hospital networks surrounding Belo Horizonte, where distributor partnership models face limited incumbent saturation. Target neonatal transport applications for air ambulance services, a high-margin whitespace lacking dedicated portable configurations from established suppliers. Pursue ANVISA blockchain traceability pilot participation as a regulatory-aligned market entry credential. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated respiratory specialists with captive manufacturing assets and established FDA 510(k) clearance portfolios, which command durable pricing power as regulatory barriers tighten. The long-term viability window favors platforms with software companion development capabilities that satisfy Joint Commission digitization mandates. Watch for ANVISA import registration harmonization completion as an inflection signal accelerating foreign manufacturer consolidation opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Accelerates market access through streamlined premarket notification pathways for Class II respiratory devices. |
| CE Marking Pathway | Unlocks EU Medical Device Regulation compliance for pressure-transducer-equipped resuscitation platforms. |
| Hospital System Partnership | Secures multi-year service agreements with São Paulo purchasing consortia controlling procurement decisions. |
| Software Companion Development | Enables Bluetooth Low Energy data streaming into Epic and Cerner EHR platforms for audit compliance. |
| Reimbursement Strategy | Aligns METI medical device reimbursement harmonization with connected device architectures in Japan. |
Research Approach
Cross-validation between primary interviews with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and ANVISA regulatory specialists anchors the qualitative findings. Secondary validation draws from FDA 510(k) premarket notification databases, ANVISA import registration records, hospital procurement databases, and ISO 10651-4 performance testing standards. Bottom-up triangulation across device shipment data and top-down reconciliation against SUS tender awards calibrate market sizing.
Calibration against historical adoption curves for connected medical devices and respiratory equipment replacement cycles shapes the projection framework. Segmentation dimensions span technology sophistication, delivery mode integration depth, end-user institutional type, and geographic regulatory cluster. CAGRs derive from fitted growth curves adjusted for ANVISA harmonization timelines and municipal ambulance fleet modernization schedules. Elasticity assumptions for medical-grade silicone feedstock costs and hospital capital expenditure cycles inform scenario boundaries.
Sensitivities concentrate around ANVISA registration pathway delays, German valve supplier capacity constraints, and hospital digitization mandate enforcement intensity. Forecasts reflect documented assumptions regarding regulatory convergence timelines and group purchasing organization consolidation trajectories. Material shifts in FDA biocompatibility testing protocols or Brazil's federal health infrastructure investment commitments would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Financial Services
US Healthcare Finance Solutions Market
Financial Services
Mobile Notary Public Market
Financial Services
Banknote Counters Market
Financial Services
Global Management Consulting Services Market
Financial Services
US Online Trading Platform Market
Financial Services
Africa Lottery Market
Financial Services
Reconciliation Software Market
Financial Services
Benefits Consulting Service Market
Financial Services
Intermediary Service Market
Financial Services
Global Temporary Labor Market
Financial Services
BFSI A2P SMS Market
Financial Services
China Factoring Services Market
Financial Services
Debt Settlement Solution Market
Financial Services
India Legal Services Market
Financial Services
Belgium Gift Card and Incentive Card Market
Financial Services
Investment Trading Software Market