
 APAC Data Center Cooling Market | 2026-2036
APAC Data Center Cooling Market Size, Share, and Industry Trends Forecast 2026-2036
APAC Data Center Cooling Market Analysis
Project finance tied to green bond frameworks is narrowing the competitive field for cooling infrastructure vendors. Vertiv Co. leverages its prefabricated modular solutions to compete in fast-deploy edge sites across Southeast Asia. Schneider Electric SE anchors large hyperscale contracts through integrated power and thermal management portfolios. Asetek sustains leadership in direct-to-chip liquid cooling through dense R&D pipelines serving AI training clusters.
Data center cooling encompasses thermal management systems that maintain operating temperatures for IT equipment, typically targeting supply air between 18°C and 27°C per ASHRAE guidelines while dissipating heat loads exceeding 30 kW per rack in high-density configurations. The primary purpose is ensuring server reliability, preventing thermal throttling, and optimizing energy consumption across computing facilities. Liquid cooling segments are capturing the fastest expansion as AI workloads push rack densities beyond air-handling limits, while hybrid architectures bridge legacy and next-generation deployments. Chilled water technology dominates existing enterprise installations but faces margin compression from evaporative and free cooling alternatives in temperate APAC zones.
China's MIIT enforces PUE thresholds below 1.3 for new data centers, directly mandating advanced cooling adoption in Shanghai and Beijing clusters. Singapore's IMDA green data center standards and Japan's METI carbon neutrality roadmaps impose comparable efficiency obligations, shaping procurement specifications across the region. Stakeholders must monitor regulatory tightening on refrigerant choices under evolving F-Gas frameworks and assess whether immersion cooling supply chains can scale beyond niche AI deployments.
Market Dynamics
China's MIIT PUE mandates below 1.3 for new data centers are compressing deployment timelines and forcing immediate technology substitution across Beijing and Shanghai clusters. Singapore's IMDA green standards and Japan's METI carbon roadmaps impose parallel obligations, creating synchronized procurement waves for liquid cooling and hybrid architectures.
Growth Catalysts
- MIIT Energy Efficiency Mandates:China's Ministry of Industry and Information Technology enforces strict PUE thresholds that compel adoption of immersion and direct-to-chip cooling in hyperscale facilities across Beijing and Shanghai.
- AI Training Cluster Expansion:GPU server densities exceeding 30 kW per rack in Singaporean and Indian data centers are exceeding air-cooling thermal limits and forcing liquid infrastructure retrofit cycles.
- Green Bond Financing Structures:Project finance tied to sustainability frameworks is narrowing vendor qualification criteria and accelerating capital flows toward certified efficient cooling deployments.
Market Restraints
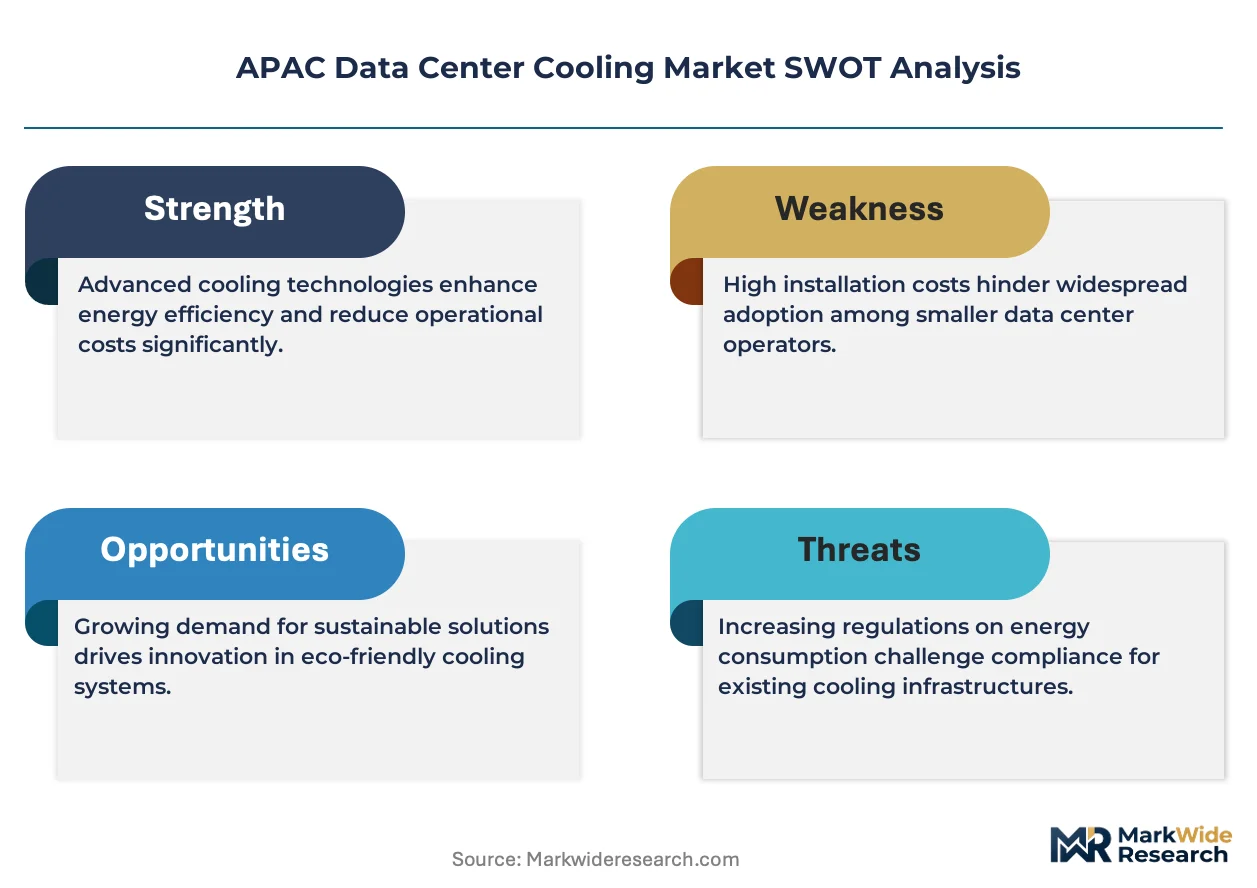
- Fluorinated Gas Supply Constraints:Evolving F-Gas Regulation restrictions in Europe are compressing refrigerant availability and elevating input costs for chiller-dependent facilities across temperate APAC zones.
- Immersion Cooling Supply Bottlenecks:Dielectric fluid production concentrates among specialty chemical suppliers in Japan and South Korea, creating concentration risk for single-source dependency.
- Legacy Infrastructure Lock-In:Existing chilled water plant investments in India's Mumbai-Pune corridor carry sunk-cost barriers that delay hybrid system adoption despite thermal load pressures.
Strategic Opportunities
- Indonesia's Untapped Archipelago Edge:Jakarta and Batam data center developments lack mature cooling infrastructure, creating first-mover positioning for modular liquid-cooled prefabricated units serving latency-sensitive workloads.
- Philippines BPO Facility Retrofit Cycle:Aging enterprise data centers in Manila and Cebu face obsolescence under rising rack densities, opening conversion opportunities for hybrid air-liquid architectures.
- Australia-New Zealand Free Cooling Zones:Temperate climates in Sydney and Auckland enable evaporative and economizer-dominant designs that bypass refrigerant dependency and align with carbon neutrality procurement criteria.
Industry Challenges
- Thermal Engineering Talent Scarcity:Direct-to-chip and immersion cooling system design requires specialized fluid dynamics expertise that remains concentrated among vendors in Japan and Singapore.
- ASHRAE Compliance Certification Delays:Third-party thermal performance validation for non-standard cooling architectures extends procurement cycles by six to twelve months in regulated financial services deployments.
- Legacy Control System Integration:Building management system interoperability gaps between chilled water infrastructure and new liquid cooling loops create commissioning complexity in hybrid retrofit projects.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | APAC Data Center Cooling Market |
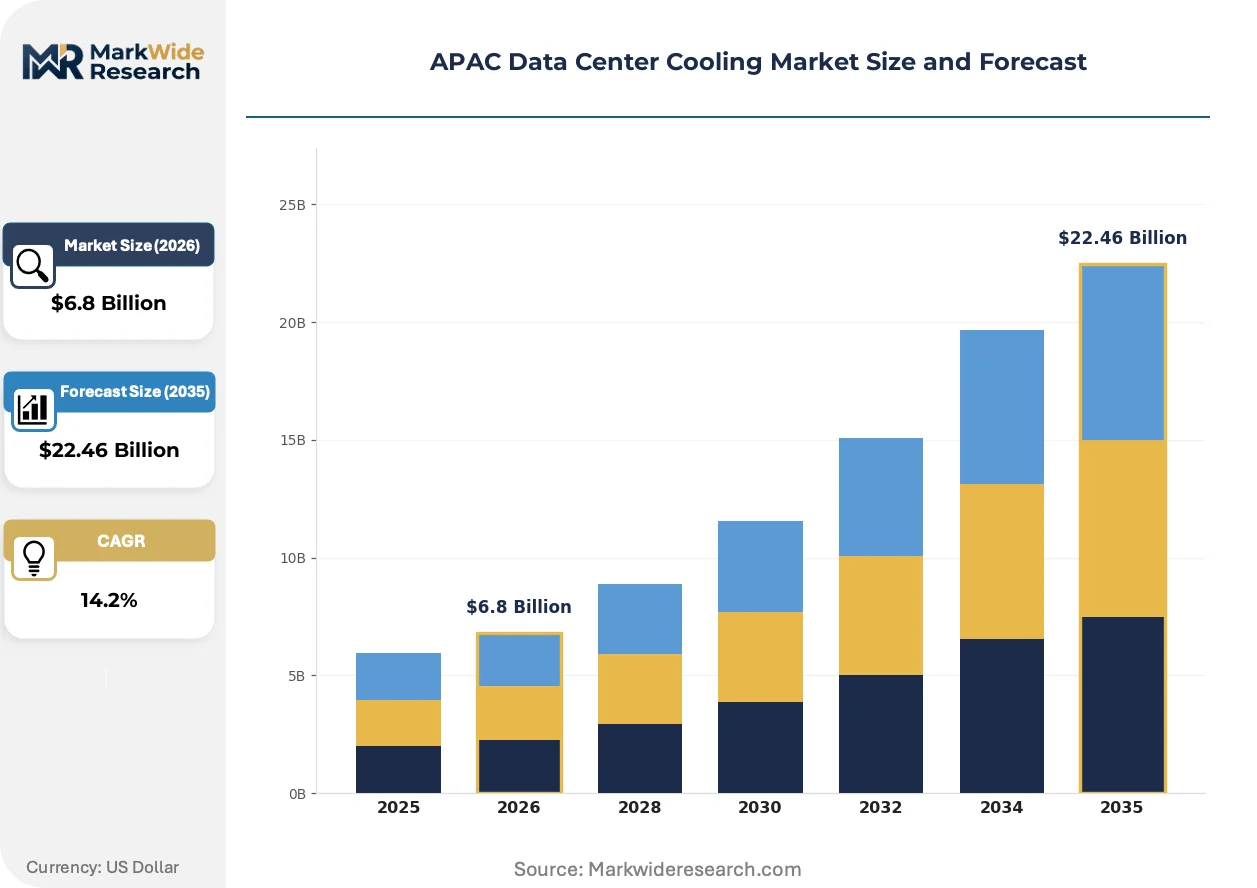
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $22.46 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Cooling Type: AIR, Liquid, Hybrid, Immersion End User: IT & Telecommunications, BFSI, Retail, Education Deployment Type: On-Premises, Colocation, Edge, Cloud Technology: Chilled Water, Direct Expansion, Evaporative Cooling, Free Cooling |
| Companies Covered | Rittal GmbH & Co. KG, Asetek, Vertiv Co., CoolIT Systems, Submer Technologies, Schneider Electric SE, Mitsubishi Electric Hydronics & IT Cooling Systems SpA, Johnson Controls, Stulz GmbH, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
APAC Data Center Cooling Market Emerging Trajectories
Direct liquid cooling architectures are compressing deployment paradigms as AI workload densities render conventional air-handling economics unsustainable. Regulatory tightening on refrigerants and carbon intensity is synchronizing technology roadmaps across national jurisdictions.
Single-phase direct-to-chip liquid cooling is rendering obsolete traditional raised-floor air distribution in high-density AI training facilities. Hyperscale operators in Singapore and South Korea are deploying these systems at rack densities exceeding 50 kW, eliminating the structural ceiling that constrained GPU cluster scaling. The technology is rendering obsolete the mechanical infrastructure investments that anchored previous-generation data center design.
China's MIIT PUE enforcement framework is mandating real-time energy monitoring and annual efficiency audits for all facilities above 3,000 standard racks. The regulation compresses allowable cooling energy overhead and disqualifies conventional chiller-dependent architectures from new project approvals. Shanghai and Beijing municipal authorities are rejecting permits for air-cooled designs, redirecting capital toward immersion and hybrid liquid systems.
Colocation buyers are unbundling thermal performance guarantees from base lease agreements and negotiating outcome-based cooling service tiers. Mumbai-Pune corridor providers face margin compression as enterprise tenants demand SLAs tied to chip-level temperature stability rather than ambient air metrics. This contractual evolution is most visible among Indian financial services and pharmaceutical data center deployments where regulatory data integrity requirements elevate thermal reliability premiums.
APAC Data Center Cooling Market Segmentation
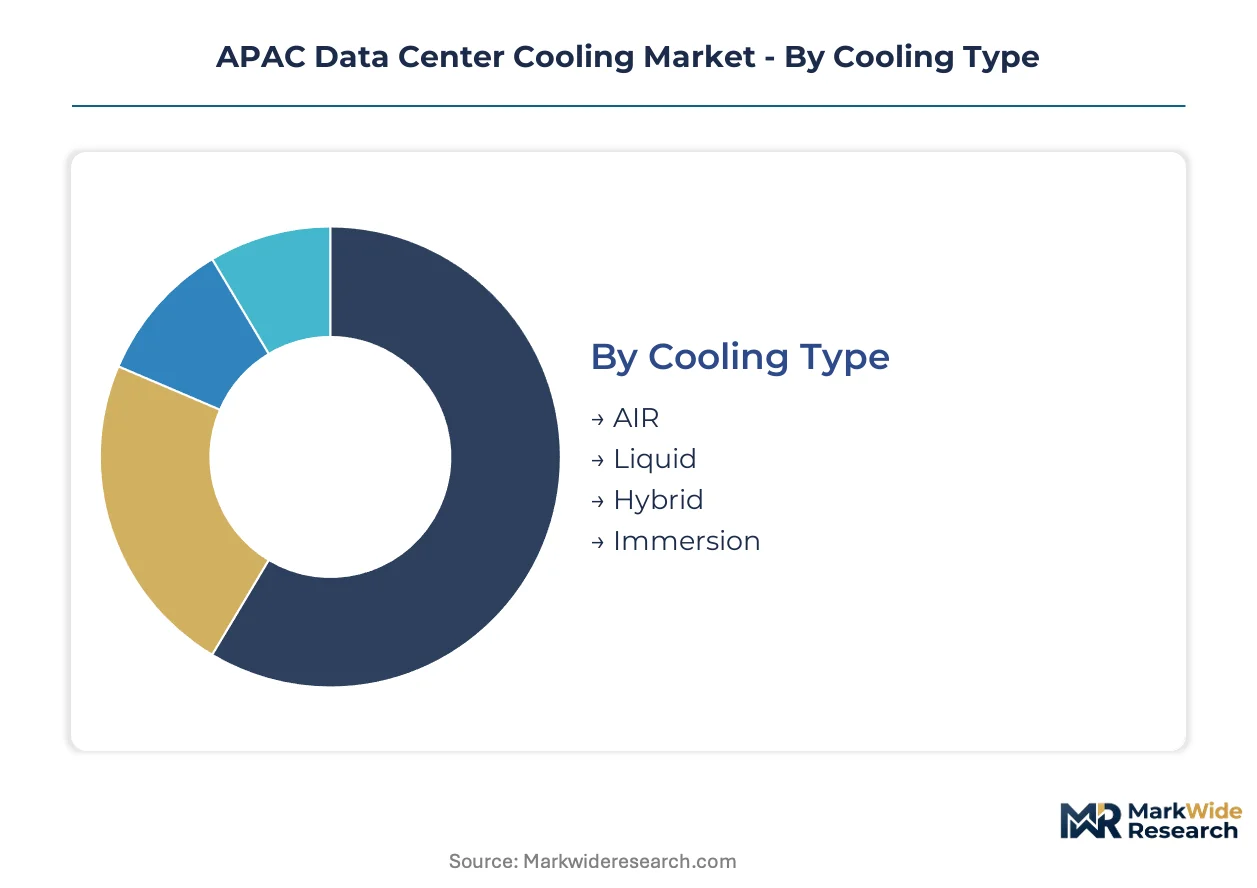
Cooling technology selection in APAC data centers determines service lifecycle economics, with liquid and immersion systems demanding specialized maintenance protocols that reshape vendor-customer relationships. Segmentation by deployment architecture and end-use thermal profiles reveals where infrastructure investments concentrate across Singapore, China, and India.
Cooling Type:
After-sales service intensity varies dramatically across cooling architectures, with liquid and immersion systems requiring fluid chemistry monitoring and specialized technician deployment that air-cooled infrastructure never demands.
- Air:Conventional raised-floor and perimeter CRAC units dominate legacy enterprise installations across India's Mumbai-Pune corridor. Facility managers favor this architecture for its mature technician base and minimal fluid-handling compliance burdens despite thermal ceilings around 15 kW per rack.
- Liquid:Direct-to-chip cold plate systems are capturing hyperscale contracts in Singapore and South Korea where GPU densities exceed 30 kW per rack. These installations demand dielectric fluid management contracts and quarterly cold plate inspection protocols that elevate recurring revenue for system integrators.
- Hybrid:Combined air-liquid architectures bridge retrofit scenarios in China's Beijing and Shanghai clusters where MIIT PUE mandates force partial liquid upgrades without full infrastructure replacement. The dual-mode operation complexity increases commissioning timelines and extends acceptance testing periods.
- Immersion:Single-phase and two-phase tank systems serve niche AI training deployments in Japanese hyperscale facilities. Dielectric fluid procurement from Japanese and South Korean specialty chemical suppliers creates supply concentration risks that complicate multi-site standardization.
Air cooling holds the largest share; momentum sits with liquid cooling.
End User:
Customer procurement sophistication stratifies sharply across sectors, with BFSI and telecommunications operators driving the most demanding thermal performance specifications.
- IT & Telecommunications:Hyperscale cloud operators and carrier-neutral facilities in Singapore specify chip-level temperature stability SLAs rather than ambient air metrics. These buyers unbundle cooling services from base leases and negotiate outcome-based thermal guarantees.
- BFSI:Indian financial services data centers in Mumbai face regulatory data integrity requirements that elevate thermal reliability premiums. RBI oversight of payment infrastructure uptime mandates redundant cooling architectures with sub-60-second failover protocols.
- Retail:E-commerce fulfillment and point-of-sale back-end systems concentrate in China's tier-two cities where cooling investments track warehouse automation deployment cycles. Seasonal demand spikes during shopping festivals stress thermal capacity planning.
- Education:University and research computing clusters in Australia and New Zealand favor free cooling architectures that align with institutional carbon neutrality procurement criteria. Limited capital budgets extend equipment replacement cycles beyond commercial norms.
BFSI commands premium pricing for thermal reliability; education represents the most price-sensitive demand pool.
Deployment Type:
Physical infrastructure ownership models determine cooling technology flexibility and capital recovery timelines.
- On-Premises:Enterprise-owned facilities in Japan's Tokyo-Osaka corridor retain legacy chilled water investments that resist rapid technology substitution despite METI carbon neutrality roadmaps. Sunk-cost barriers compress vendor switching incentives.
- Colocation:Multi-tenant providers in India's Mumbai-Pune corridor face margin compression as tenants demand GPU-ready thermal infrastructure. Retrofit investments concentrate in facilities serving pharmaceutical and financial services verticals.
- Edge:Distributed compute nodes across Indonesia's Jakarta-Batam corridor lack mature cooling infrastructure, creating first-mover positioning for modular liquid-cooled prefabricated units. Deployment speed outweighs energy efficiency in site selection.
- Cloud:Hyperscale self-operated facilities in Singapore and South Korea specify integrated power and thermal management portfolios that eliminate vendor fragmentation. Single-source accountability compresses procurement cycles.
Colocation holds the largest share; edge deployments are climbing the fastest.
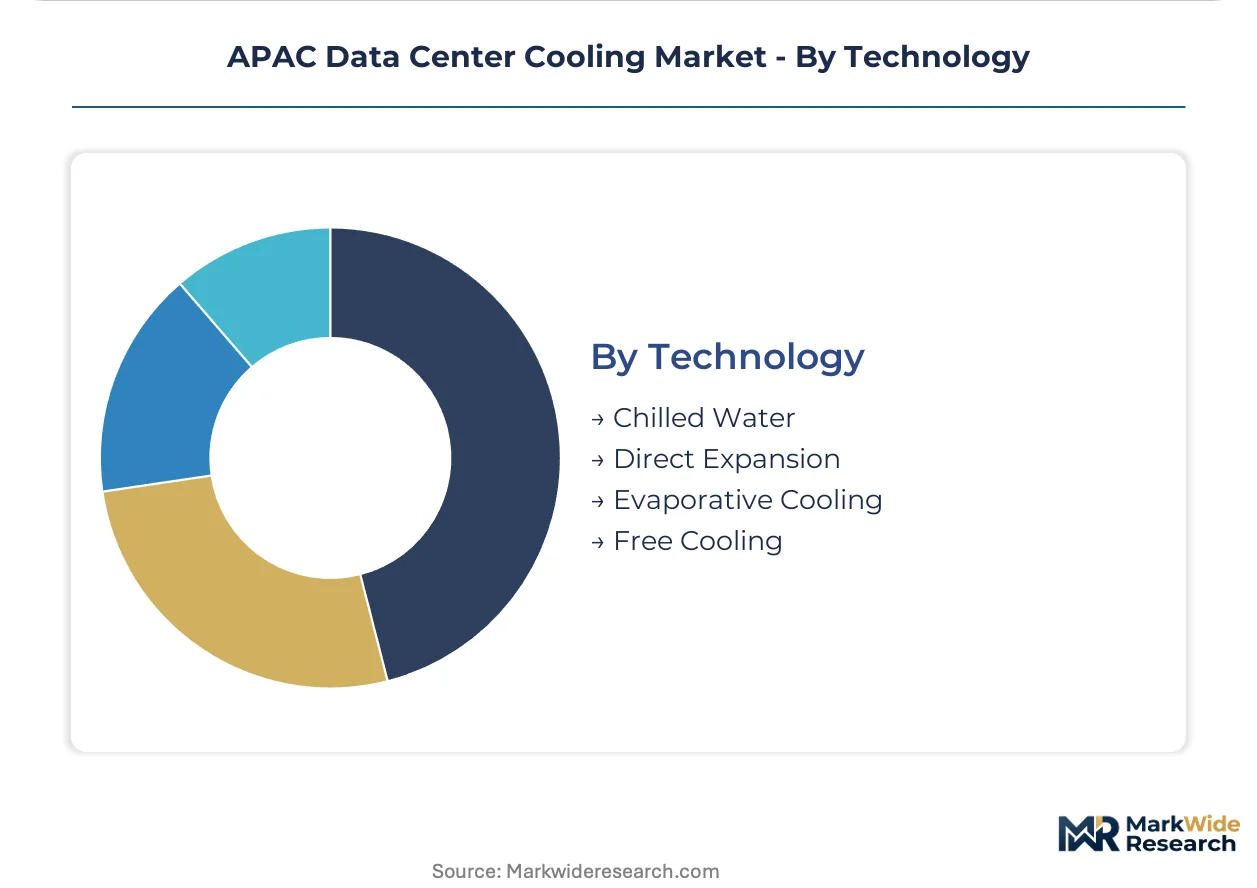
Technology:
Mechanical complexity and refrigerant dependency create diverging regulatory exposure across technology choices.
- Chilled Water:Centralized plant architecture dominates existing enterprise installations but faces margin compression from evaporative alternatives. F-Gas Regulation restrictions in Europe compress refrigerant availability and elevate input costs for chiller-dependent facilities.
- Direct Expansion:Packaged rooftop and split systems serve smaller edge deployments across Southeast Asia where capital constraints limit centralized infrastructure investment. Refrigerant charge sizes fall below regulatory thresholds in many jurisdictions.
- Evaporative Cooling:Adiabatic and wet cooling towers gain traction in Australia's Sydney and Melbourne markets where temperate climates enable water-based heat rejection. Water scarcity risk in some APAC zones constrains deployment geography.
- Free Cooling:Air-side and water-side economizers dominate New Zealand and temperate Australian designs that bypass refrigerant dependency entirely. Seasonal availability limits annual operating hours in tropical APAC climates.
Chilled water retains the largest installed base; free cooling gains share fastest in temperate zones.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cooling equipment trade flows within APAC reflect divergent manufacturing capabilities and import dependency patterns. China and Japan export precision thermal components while Southeast Asian markets rely on foreign system integrators. India's cooling infrastructure buildout attracts component imports from East Asian suppliers.
China
Hyperscale cloud operators in Beijing and Shanghai are retrofitting legacy facilities to meet MIIT's PUE thresholds below 1.3. The ministry's energy efficiency mandates disqualify air-cooled designs from new project approvals. Yangtze River Delta data center clusters are redirecting capital toward immersion and hybrid liquid systems.
Singapore
GPU server densities exceeding 50 kW per rack are forcing liquid cooling adoption among AI training facilities. IMDA green data center standards impose efficiency obligations that synchronize procurement specifications. Tuas and Changi data center zones are seeing concentrated deployment of direct-to-chip architectures.
India
Colocation providers in the Mumbai-Pune corridor face tenant demands for GPU-ready thermal infrastructure. RBI oversight of payment infrastructure uptime mandates redundant cooling with sub-60-second failover protocols. Financial services and pharmaceutical verticals are driving retrofit investments in Navi Mumbai and Pune facilities.
Japan
Hyperscale operators in Tokyo-Osaka corridor are deploying single-phase immersion systems for niche AI training workloads. METI carbon neutrality roadmaps impose efficiency obligations that compress technology replacement timelines. Chubu and Kansai regions retain legacy chilled water investments that resist rapid substitution despite regulatory pressure.
Australia
Temperate climates in Sydney and Melbourne enable evaporative and economizer-dominant designs that bypass refrigerant dependency. Institutional carbon neutrality procurement criteria at universities and research facilities favor free cooling architectures. New South Wales and Victoria data center developments are concentrating water-based heat rejection systems.
APAC Data Center Cooling Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in the thermal management stack. The vendor landscape fragments across three functional layers: integrated infrastructure platforms, precision cooling components, and dielectric fluid supply. European industrial conglomerates and Asian precision manufacturers occupy distinct competitive positions. Consolidation pressure concentrates among mid-scale system integrators facing hyperscale procurement consolidation. Strategic moves center on vertical integration into fluid chemistry and prefabricated modular deployment partnerships.
Among the integrated platform tier, Schneider Electric SE and Vertiv Co. exemplify full-stack thermal and power management positioning. Asetek occupies a specialist position in direct-to-chip liquid cooling architectures. These three anchors represent divergent strategic postures: conglomerate diversification, infrastructure platform breadth, and component specialization depth.
| Leading Market Players |
|---|
| Rittal GmbH & Co. KG |
| Asetek |
| Vertiv Co. |
| CoolIT Systems |
| Submer Technologies |
| Schneider Electric SE |
| Mitsubishi Electric Hydronics & IT Cooling Systems SpA |
| Johnson Controls |
| Stulz GmbH |
| Others |
Supply Flow & Price Mechanics
Yangtze River Delta dielectric fluid production clusters anchor regional supply capacity and transmit pricing power downstream to cooling system integrators serving Beijing and Shanghai hyperscale facilities. MIIT PUE enforcement compresses vendor qualification windows, concentrating procurement leverage among fluid chemistry specialists in Japan and South Korea.
Pricing Analysis
Hyperscale cloud operators anchor project-based pricing structures for integrated liquid cooling deployments across Singapore and South Korea. Pricing stratifies across certification grade and volume scale, with ASHRAE-compliant architectures commanding premiums over standard configurations. Cost compression in air-cooled retrofits is intensifying because legacy chilled water investments face stranded asset risk under regulatory tightening. Colocation providers in India's Mumbai-Pune corridor demonstrate highest price sensitivity due to margin compression from tenant GPU-readiness demands.
Supply Chain Analysis
Export control regimes on advanced semiconductor manufacturing equipment indirectly constrain cooling component flows into Chinese hyperscale facilities. Manufacturing concentrates in Japan, South Korea, and Taiwan for precision cold plates and dielectric fluids. Supply chains draw from specialty chemical feedstocks, copper alloy substrates, and precision machining capacity. Single-source vulnerability concentrates in Japanese and South Korean dielectric fluid suppliers. Distribution runs through direct OEM partnerships and systems integrator channels serving colocation and hyperscale end users.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment. MIIT PUE mandates and Singapore IMDA standards create switching costs that lock in incumbent positions.
For Market Incumbents: Build certification moats by accelerating ASHRAE compliance investments and captive dielectric fluid supply partnerships. Defend against emerging modular prefabrication entrants by embedding thermal performance guarantees into long-term service contracts. Capacity addition in Indonesia's Jakarta-Batam corridor captures edge deployment growth before infrastructure matures.
For New Entrants and Emerging Players: Pursue white-space positioning in Philippines BPO facility retrofits where aging air-cooled infrastructure faces obsolescence. Target hybrid air-liquid architectures as the most penetrable segment for mid-scale system integrators lacking hyperscale credentials. Go-to-market through direct engagement with Manila and Cebu enterprise facilities bypassing established channel relationships.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-capture play because efficiency mandates synchronize procurement specifications across national jurisdictions. Acquisition targets should display vertical integration into fluid chemistry or prefabricated modular deployment partnerships. Watch for MIIT enforcement expansion into tier-two Chinese cities as inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Dielectric Fluid Production | Captive supply from Japanese and South Korean specialty chemical partners insulates against input cost volatility. |
| Prefabricated Modular Deployment Partnership | Vertiv-style fast-deploy units capture Indonesia edge infrastructure buildout before local competition emerges. |
| ASHRAE Compliance Certification Investment | Third-party validation compresses procurement cycles for financial services and pharmaceutical colocation tenants. |
| Hybrid System Commissioning Capability Buildout | Integration expertise between chilled water legacy and liquid cooling loops addresses China's retrofit wave. |
| Direct-to-Chip R&D Pipeline Expansion | Asetek-style dense innovation serving AI training clusters maintains pricing power at densities exceeding 50 kW per rack. |
Methodological Framework
A spread of perspectives from data center facility managers, thermal engineering directors, colocation procurement leads, and hyperscale infrastructure planners converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation against MIIT regulatory filings, IMDA green data center standards documentation, and hyperscaler capex disclosures. Trade data from Japanese and South Korean customs authorities, alongside SEC filings from listed infrastructure vendors, anchored supply-side calibration. Bottom-up installation tracking across Beijing, Shanghai, Singapore, and Mumbai-Pune facilities triangulated against top-down market sizing.
Demand-supply balance dynamics shaped the analytical framework across the analysis window. Segmentation dimensions modeled include cooling architecture type, deployment ownership model, end-use vertical thermal profile, and regional regulatory cluster. CAGRs derived from installed base evolution and replacement cycle compression under AI workload density pressures. Forecast inputs incorporated GPU server deployment trajectories and MIIT enforcement timeline assumptions without specific year anchors.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese state-backed infrastructure consortia would shift outcomes. Material shifts in F-Gas Regulation stringency or dielectric fluid supply concentration would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Cooling
Chile Data Center Cooling Market
Data Center Cooling
Brazil Data Center Cooling Market
Data Center Cooling
Data Center Liquid Cooling Market
Data Center Cooling
Uk Data Center Cooling Market
Data Center Cooling
Indonesia Data Center Cooling Market
Data Center Cooling
Sweden Data Center Cooling Market
Data Center Cooling
Immersion Cooling Market
Data Center Cooling
Denmark Data Center Cooling Market
Data Center Cooling
Vietnam Data Center Cooling Market
Data Center Cooling
New Zealand Data Center Cooling Market
Data Center Cooling
Philippines Data Center Cooling Market
Data Center Cooling
United States Data Center Cooling Market
Data Center Cooling
Hong Kong Data Center Cooling Market
Data Center Cooling
Data Center Liquid Immersion Cooling Market
Data Center Cooling
Malaysia Data Center Cooling Market
Data Center Cooling
Germany Data Center Cooling Market