
 Paper Cup Lids Market | 2026-2036
Paper Cup Lids Market Size, Share, and Industry Trends Forecast 2026-2036
Paper Cup Lids Market Analytics
Subscription-based lid replenishment programs for national café chains is rebalancing procurement economics toward recurring revenue models rather than spot purchasing. Huhtamaki Oyj leverages its European manufacturing footprint to supply coated paper lids under long-term service contracts. Dart Container Corporation anchors North American quick-service demand through dedicated production lines for vented and domed formats. Sabert Corporation specializes in custom lid geometries for premium beverage applications, competing on design flexibility rather than unit cost.
Paper cup lids are thermoformed or die-cut closures manufactured from paperboard substrates ranging from 200 to 400 gsm, often laminated with PLA or aqueous barrier coatings to resist liquid penetration and maintain structural integrity at temperatures exceeding 85°C. Their primary commercial purpose is to prevent spillage, retain heat, and enable straw or sip-port functionality for on-premise and takeaway beverage service. Flat lids dominate high-volume quick-service deployments where cost minimization outweighs aesthetic differentiation, while domed lids command premium positioning in specialty cafés where whipped-cream clearance and visual presentation drive selection. Coated paper substrates currently capture the largest material share, though biodegradable paper grades are gaining fastest as foodservice operators preempt regulatory bans on conventional barrier chemistries.
FDA food-contact substance regulations govern barrier coating approvals in the United States, while the EU Packaging and Packaging Waste Directive mandates recyclability targets that reshape material specifications for lids sold across member states. ECHA restrictions on per- and polyfluoroalkyl substances directly eliminate certain oil-resistant coatings previously standard in paper lid manufacturing, forcing reformulation investments. Stakeholders must monitor evolving state-level extended producer responsibility frameworks and certification requirements for home-compostable packaging to align product development with enforcement timelines.
Market Dynamics
Municipal organic waste mandates across North American cities are forcing material transitions from polystyrene to compostable paper substrates, compressing reformulation timelines for lid manufacturers.
Growth Catalysts
- Extended Producer Responsibility Laws:State-level EPR frameworks in the United States mandate producer accountability for end-of-life packaging, accelerating demand for recyclable and compostable lid designs.
- Quick-Service Restaurant Procurement:National café chains now specify biodegradable substrates under corporate sustainability commitments, creating pull-through volume for coated paper lid suppliers.
- PLA Barrier Coatings:Polylactic acid laminations on 200-400 gsm paperboard enable heat resistance above 85°C, satisfying functional requirements for hot beverage service without conventional plastic barriers.
Market Restraints
- Pulp Input Volatility:Bleached kraft paperboard prices fluctuate with softwood pulp futures, compressing margins for converters locked into annual supply contracts with foodservice distributors.
- Coating Chemistry Constraints:ECHA restrictions on per- and polyfluoroalkyl substances eliminate oil-resistant fluorinated coatings, forcing expensive reformulation cycles without drop-in replacements.
- Domed Lid Cost Premium:Thermoformed domed geometries require 40% more material than flat lids, limiting adoption in price-sensitive quick-service segments despite superior presentation attributes.
Strategic Opportunities
- Subscription Replenishment Models:National café chains are migrating from spot purchasing to recurring service contracts, enabling lid suppliers to capture lifetime value through integrated logistics partnerships.
- Home-Compostable Certification:TÜV Austria and BPI certification for backyard compostability opens premium positioning in municipal markets with curbside organic collection programs.
- Custom Geometry Services:Specialty beverage operators seek differentiated sip-port and venting configurations, rewarding design-flexible converters with margin premiums over commodity flat lids.
Industry Challenges
- Thermoforming Tooling Lead Times:Precision aluminum molds for domed lid production require 16-20 week fabrication cycles, constraining speed-to-market for seasonal promotional designs.
- Multi-Jurisdictional Compliance:FDA food-contact substance approvals, EU Packaging and Packaging Waste Directive recyclability targets, and emerging state compostability standards create fragmented certification burdens.
- Barrier Performance Validation:Aqueous coating chemistries must demonstrate equivalent liquid resistance to legacy polyethylene laminations through accelerated shelf-life testing protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Paper Cup Lids Market |
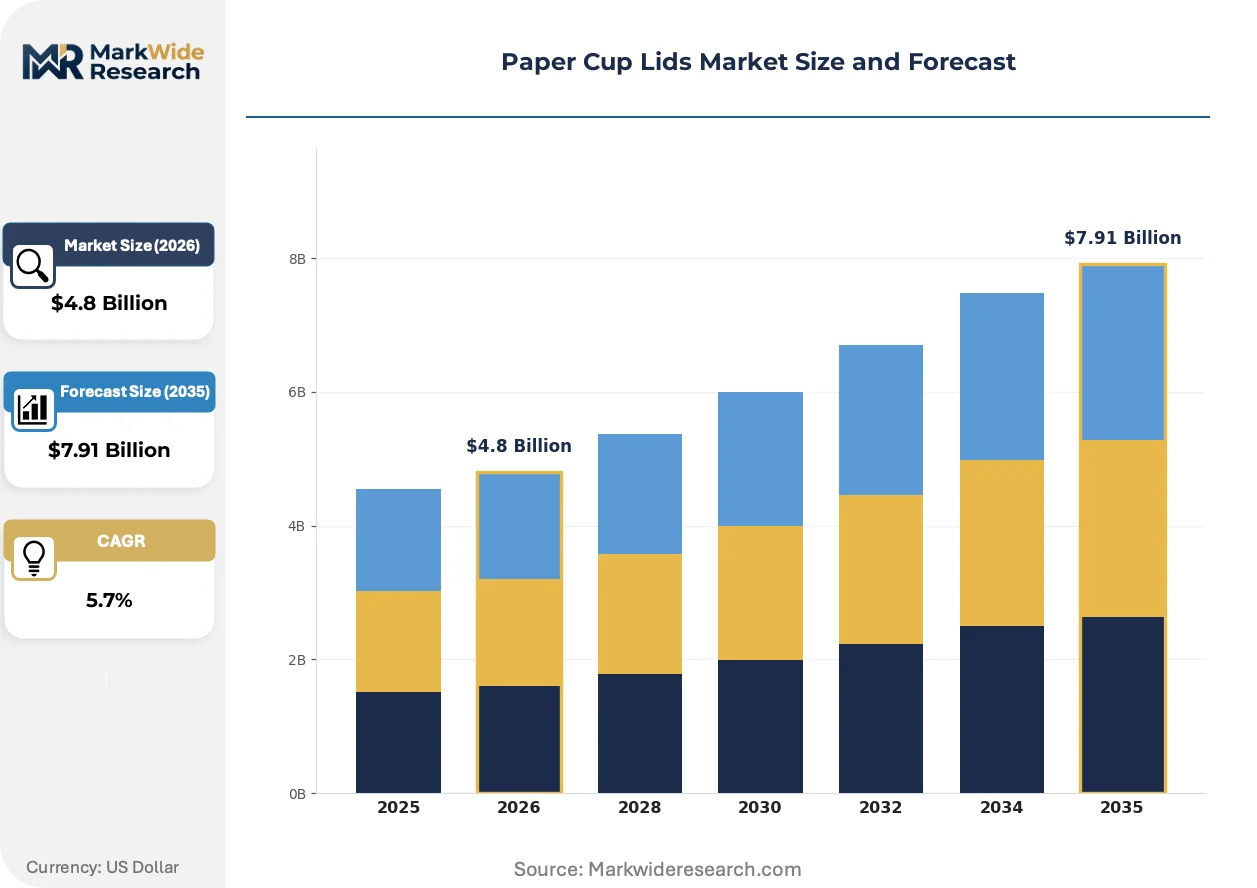
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flat Lids, Domed Lids, Vented Lids, Custom Lids Material: Biodegradable Paper, Recycled Paper, Coated Paper, Others Application: Cafés, Restaurants, Fast Food, Catering End User: Consumers, Food Service Providers, Event Planners, Retailers |
| Companies Covered | Pactiv LLC, Michael Procos S.A., Dart Container Corporation, Genpak, LLC, Tair Chu Enterprise Co., Ltd., Berry Global Group, Inc., Sabert Corporation, Duni AB, Huhtamaki Oyj, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Paper Cup Lids Market Evolving Landscape
Barrier coating chemistry and manufacturing process control are the primary vectors of competitive differentiation as regulatory pressure eliminates incumbent material systems.
Aqueous barrier coatings are converging with precision slot-die application equipment to deliver uniform 5-15 micron film weights on high-speed paperboard lines. Specialty café chains in the Pacific Northwest and Scandinavia specify these systems for their complete elimination of plastic laminates. The convergence is compressing the cost premium between conventional PE-coated lids and next-generation biodegradable alternatives from 35% to under 15% at volume.
REACH restrictions on intentionally added microplastics and ECHA's evolving PFAS guidance are eliminating standard oil-resistant chemistries from the EU market. Manufacturers must reformulate with bio-based wax emulsions or mineral-filled coatings to maintain grease resistance in pastry-accompanied beverage service. Quick-service operators in Germany and France now require written compliance attestations for all lid SKUs, shifting procurement evaluation criteria toward regulatory documentation depth.
Buyer consolidation among national coffeehouse chains is compressing supplier rosters from regional fragmentation to approved-vendor lists under three-year framework agreements. Foodservice distributors are losing procurement influence as direct manufacturer relationships enable chains to standardize lid specifications across corporate and franchised locations. This pattern is most visible in the United States, where the top five café brands account for a disproportionate share of coated paper lid volume.
Paper Cup Lids Market Segmentation
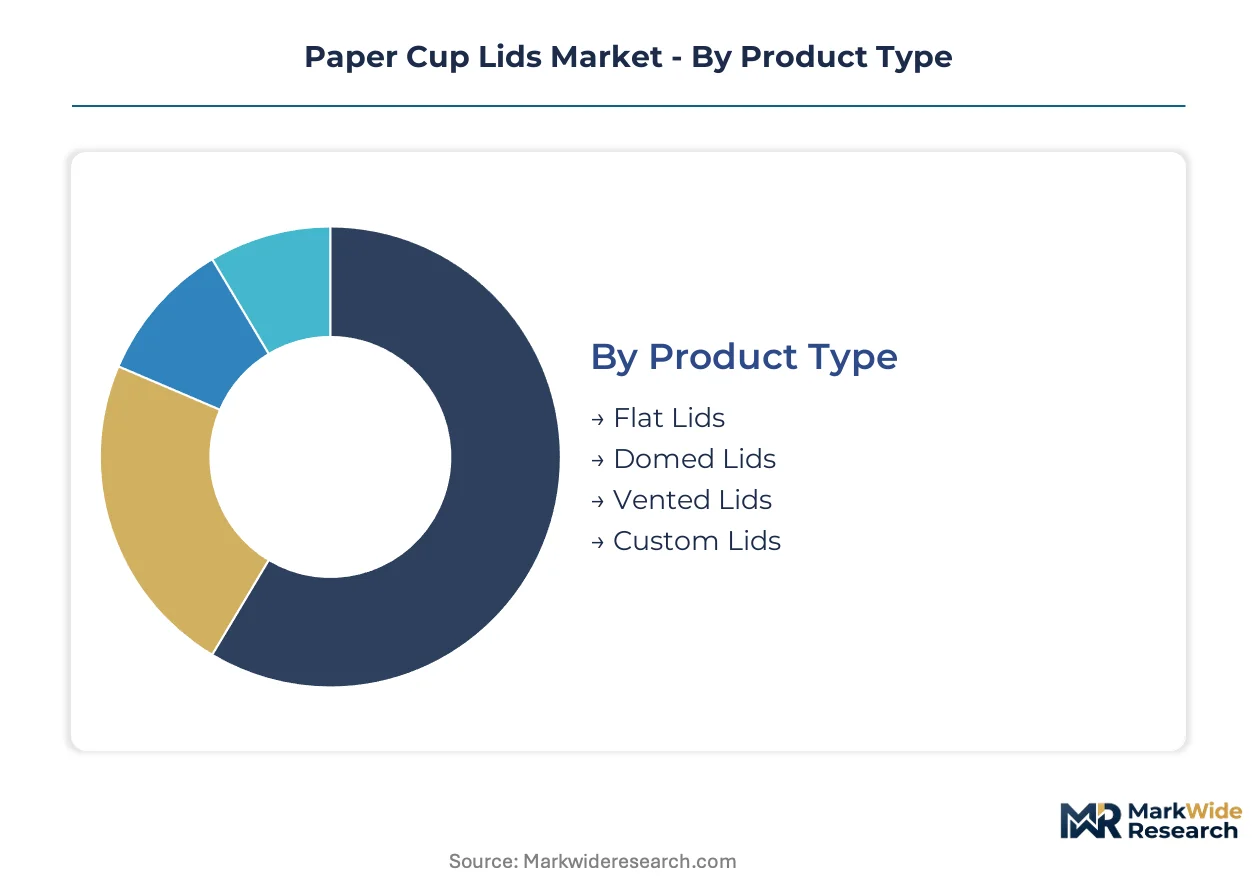
Paper cup lid procurement hinges on thermal performance, regulatory compliance, and presentation requirements that vary sharply across foodservice channels. Segmentation reveals how material specifications and geometry choices map to distinct buyer economics and operational constraints.
Product Type:
Quick-service operators prioritize unit economics and throughput speed when selecting lid geometries, creating divergent demand patterns across flat, domed, vented, and custom formats.
- Flat Lids:Die-cut paperboard closures with minimal vertical profile, typically 200-280 gsm with PLA or aqueous barrier coatings. Demand concentrates in United States quick-service chains where cost minimization overrides aesthetic differentiation, driven by state-level extended producer responsibility mandates that penalize plastic alternatives.
- Domed Lids:Thermoformed geometries providing 25-40mm clearance for whipped toppings and foam art, requiring 300-400 gsm substrates with enhanced structural rigidity. Specialty cafés in Seattle and Portland specify these for Instagram-ready beverage presentation, though material premiums limit penetration in price-sensitive segments.
- Vented Lids:Precision-perforated designs enabling steam release without liquid escape, common in high-throughput drive-thru operations.
- Custom Lids:Proprietary sip-port configurations and branded embossing for premium beverage operators seeking differentiation.
Volume sits with flat lids across quick-service deployments; growth tilts toward domed formats as specialty coffee chains expand premium positioning.
Material:
Regulatory pressure on conventional barrier chemistries is fragmenting substrate procurement across compostable, recycled, coated, and emerging alternatives.
- Biodegradable Paper:Unbleached kraft substrates with bio-based wax or mineral-filled coatings certified for home and industrial composting. Municipal organic waste programs in San Francisco and Vancouver mandate these for curbside collection eligibility, accelerating specification shifts.
- Coated Paper:Bleached paperboard with polyethylene or PLA laminations providing liquid resistance above 85°C. Current volume leader despite ECHA restrictions on fluorinated oil-resistant variants forcing reformulation investments.
- Recycled Paper:Post-consumer fiber content ranging 30-100%, constrained by FDA food-contact substance approval requirements for direct beverage contact surfaces.
- Others:Emerging substrates including agricultural residue pulp and molded fiber blends in pilot production.
Coated paper retains installed base dominance; biodegradable grades are expanding most quickly as EPR laws tighten disposal accountability.
Application:
Service format dictates lid performance requirements across consumption occasions from sit-down cafés to mobile catering.
- Cafés:Specialty coffeehouses emphasizing latte art preservation and sustainable brand alignment, driving domed lid and biodegradable substrate specifications.
- Restaurants:Full-service dining with lower lid attachment rates, typically sourcing flat formats for takeout beverage programs.
- Fast Food:High-volume quick-service with standardized procurement through national distribution networks, favoring flat vented lids for drive-thru efficiency.
- Catering:Event-based demand with seasonal volatility, requiring stock lid availability in multiple sizes without custom tooling investments.
Fast food channels anchor procurement volume; cafés command the steepest expansion trajectory as specialty beverage culture penetrates secondary markets.
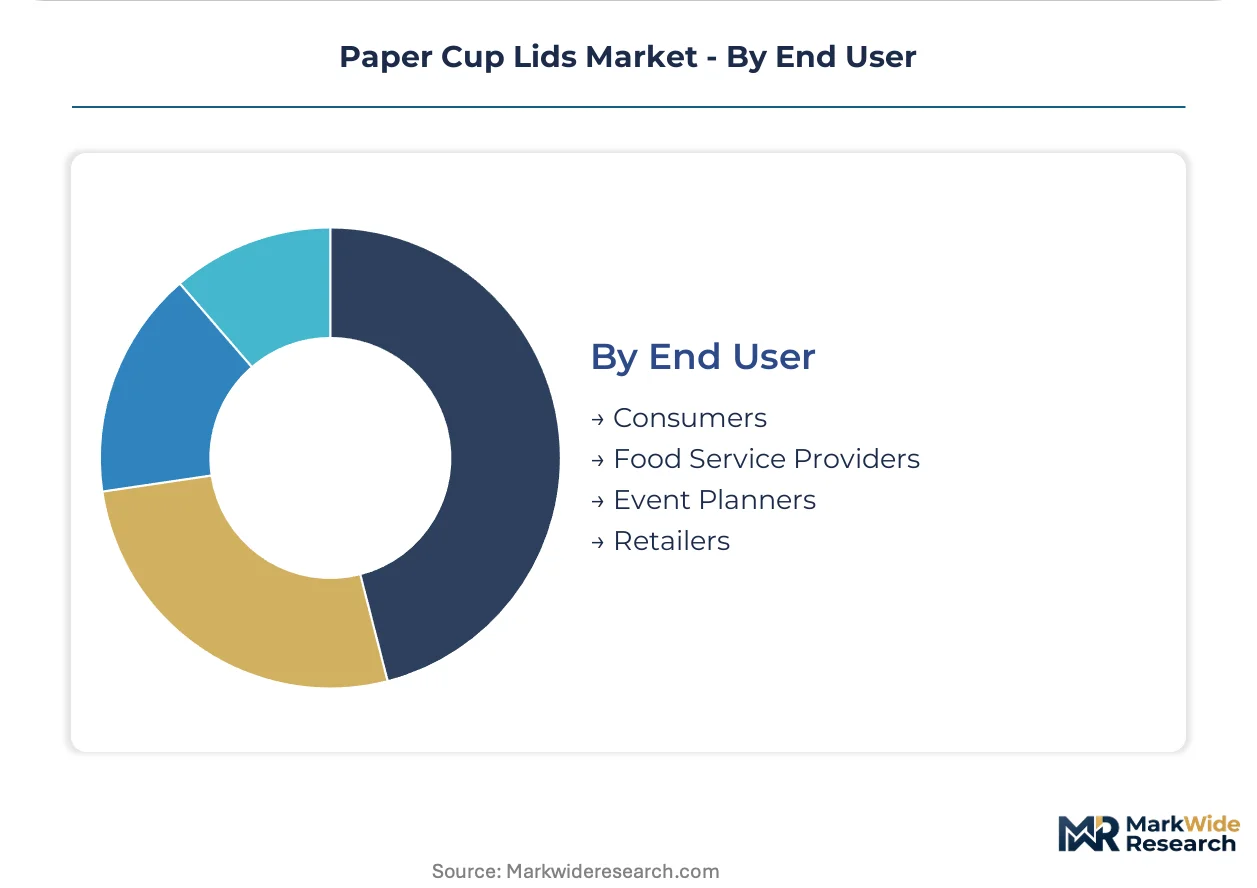
End User:
Purchasing authority and volume scale diverge sharply between institutional buyers and dispersed consumer decision-making.
- Food Service Providers:National distributors and contract foodservice operators with centralized procurement, specifying certified compostable lids under corporate sustainability frameworks.
- Consumers:Individual purchasers through retail channels, price-sensitive and driven by immediate availability rather than material certification.
- Event Planners:Temporary demand spikes for weddings and corporate functions, prioritizing aesthetic coordination over unit cost optimization.
- Retailers:Grocery and convenience store private-label programs, increasingly specifying home-compostable certifications for shelf differentiation.
Food service providers concentrate order volume; retailers are gaining share fastest as private-label beverage programs expand compostable packaging claims.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Seattle's municipal composting mandates have reshaped procurement specifications for quick-service operators across the Pacific Northwest, establishing material standards that diffuse into national supply chains through corporate sustainability frameworks.
United States
State-level extended producer responsibility laws in California and Maine mandate producer accountability for packaging end-of-life, forcing quick-service chains to specify biodegradable substrates. FDA food-contact substance regulations govern barrier coating approvals, creating compliance burdens for imported lid stock. Chicago's foodservice distribution hub concentrates procurement volume for midwestern quick-service networks transitioning from polystyrene.
Germany
Quick-service operators in Berlin and Munich require written compliance attestations for all lid SKUs under ECHA's evolving PFAS guidance, shifting procurement criteria toward regulatory documentation depth. The EU Packaging and Packaging Waste Directive mandates recyclability targets that reshape material specifications for lids sold across member states. Bavaria's industrial corridor hosts converters reformulating with bio-based wax emulsions to maintain grease resistance.
France
Specialty café chains in Paris specify domed lid geometries for visual presentation of whipped toppings and latte art, driving premium substrate demand. ANSM enforces food-contact material safety standards that exceed baseline EU requirements. The Lyon-Grenoble corridor concentrates precision thermoforming capacity for complex lid geometries serving premium beverage operators.
United Kingdom
London's specialty coffee density drives specification of aqueous barrier coatings with complete plastic elimination for brand alignment. The Environment Agency enforces packaging waste regulations that accelerate transitions from conventional polyethylene laminations. Manchester's foodservice manufacturing cluster supplies coated paper lids to national café chains under framework agreements.
Canada
Municipal organic waste programs in Vancouver mandate home-compostable certifications for curbside collection eligibility, accelerating specification shifts among quick-service operators. Health Canada and PMRA govern food-contact substance approvals, creating parallel compliance tracks to FDA requirements. Toronto's foodservice distribution network channels compostable lid volume into national quick-service procurement.
Paper Cup Lids Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the paper cup lid value chain, creating tiered competitive dynamics where integrated converters control substrate supply while specialized designers capture premium geometry specifications. The market structure concentrates around three strategic archetypes: multinational packaging conglomerates with integrated pulp-to-lid operations, regional converters serving quick-service procurement networks, and design-specialized firms competing on custom geometry flexibility. Dominant competitive moves include backward integration into barrier coating formulation and strategic partnerships with national café chains for recurring replenishment contracts.
Among North American-based converters, Dart Container Corporation, Pactiv LLC, and Sabert Corporation exemplify distinct competitive positioning archetypes within this structure. Dart Container anchors high-volume quick-service demand through dedicated production infrastructure. Pactiv LLC occupies a position spanning multiple foodservice packaging categories with procurement leverage. Sabert Corporation represents the design-flexibility vector, competing on custom lid geometries rather than unit cost minimization.
| Leading Market Players |
|---|
| Pactiv LLC |
| Michael Procos S.A. |
| Dart Container Corporation |
| Genpak, LLC |
| Tair Chu Enterprise Co., Ltd. |
| Berry Global Group, Inc. |
| Sabert Corporation |
| Duni AB |
| Huhtamaki Oyj |
| Others |
Value Network & Pricing Analysis
PLA barrier coating adoption on 200-400 gsm paperboard lines compresses unit economics while concentrating procurement leverage among converters with captive coating formulation capabilities. State-level extended producer responsibility laws in the United States and municipal organic waste mandates in Canadian cities simultaneously reshape cost structures and supplier rosters.
Pricing Analysis
Throughput-based pricing anchors lid procurement economics, with national café chains negotiating recurring service contracts that bundle unit supply with logistics integration. Three-tier pricing structure across premium domed geometries, standard flat formats, and economy uncoated grades differentiates by certification level and thermal performance tier. Cost compression in flat lid segments intensifies because pulp input volatility bleeds through annual supply contracts. Quick-service chains exhibit highest price sensitivity, while specialty cafés in Seattle and Portland absorb premiums for home-compostable certification and custom geometries.
Supply Chain Analysis
Single-source vulnerability sits with Scandinavian and German converters for precision thermoforming tooling serving domed lid production. Raw material procurement draws from Canadian bleached kraft pulp, Brazilian eucalyptus fiber, and Chinese PLA resin feedstocks. Tariff exposure on imported barrier coating chemistries compounds reformulation cycle risks under ECHA's evolving PFAS guidance. Distribution runs through Chicago and Toronto foodservice hubs into national quick-service networks, bypassing regional distributor intermediaries as direct manufacturer relationships consolidate.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Thermoforming tooling lead times of 16-20 weeks constrain capacity expansion, propping pricing power for converters with installed precision mold fabrication. This supply bottleneck amplifies returns on backward integration into barrier coating formulation.
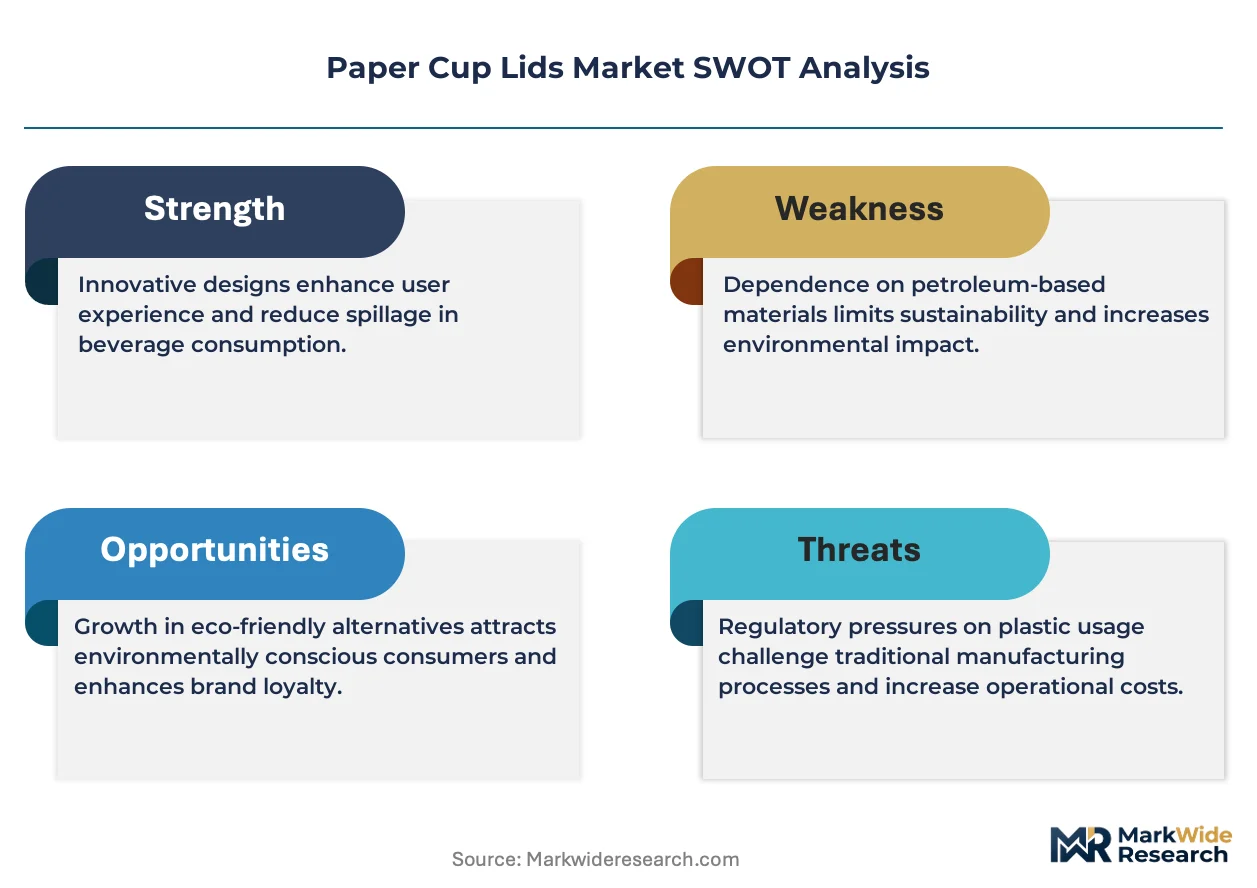
For Market Incumbents: Deepen captive supply of aqueous barrier coating chemistries to offset ECHA restrictions on fluorinated oil-resistant variants. Add thermoforming capacity in the Lyon-Grenoble corridor to capture premium domed lid demand from Paris specialty café chains. Consolidation among national coffeehouse buyers threatens margin compression; defend through exclusive framework agreements with top five café brands. For New Entrants and Emerging Players: California's extended producer responsibility law opens a window for home-compostable certified lid specialists to displace incumbent polystyrene suppliers. Target Vancouver and San Francisco municipal organic waste programs with TÜV Austria and BPI certified biodegradable substrates. Go-to-market through direct relationships with fast-casual chains bypassing traditional foodservice distributor networks. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by multinational packaging conglomerates seeking North American quick-service penetration. Long-term viability hinges on regulatory tailwinds for compostable packaging persisting through enforcement timeline maturation. Watch for FDA food-contact substance approval bottlenecks on novel bio-based wax emulsions as inflection indicator for reformulation investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Barrier Coating Formulation | ECHA PFAS restrictions eliminate standard chemistries, rewarding in-house bio-based wax emulsion development. |
| Home-Compostable Certification Investment | TÜV Austria and BPI certifications unlock Vancouver and San Francisco municipal procurement mandates. |
| Direct Chain Relationship Development | National café buyer consolidation bypasses foodservice distributors, enabling lifetime value capture through recurring contracts. |
| Custom Geometry Design Services | Specialty café expansion in secondary markets rewards design-flexible converters with margin premiums over commodity flat lids. |
| Precision Thermoforming Capacity Addition | Domed lid demand from Paris and Seattle specialty operators outstrips installed tool fabrication lead times. |
Research Methodology
Independent corroboration across foodservice distributor procurement leads, quick-service chain sustainability officers, and thermoforming equipment manufacturers underwrites the qualitative findings. Primary interviews with barrier coating R&D directors, paperboard mill technical sales managers, and municipal waste program administrators combined with secondary validation from FDA food-contact substance filings, ECHA restriction updates, and EU Packaging and Packaging Waste Directive implementation reports. Bottom-up demand modeling from quick-service outlet counts and top-down supply assessment from converter capacity disclosures triangulate volume estimates.
Rate-of-change decomposition across product type, material substrate, application channel, and geographic regulatory cluster structures the analytical framework. Segmentation dimensions include flat versus domed versus vented geometries, biodegradable versus coated versus recycled paper grades, café versus fast food versus catering end uses, and United States versus Germany versus France versus United Kingdom versus Canada regulatory frameworks. CAGRs derive from elasticity-adjusted demand projections and capacity-constrained supply growth assumptions. Forecast inputs incorporate PLA resin price trajectories and municipal organic waste program expansion schedules.
The model assumes a particular technology adoption path; alternative pathways for aqueous barrier coating performance validation would alter the outlook. Forecasts reflect assumptions about EPR law enforcement timelines and home-compostable certification standardization. Pulp futures volatility, thermoforming tooling fabrication bottlenecks, and multi-jurisdictional compliance fragmentation present specific revision risks. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
Asia-Pacific Coated Paper Market
Paper & Paperboard Packaging
Countertop Paper Napkin Dispenser Market
Paper & Paperboard Packaging
Global Paper Bags Market
Paper & Paperboard Packaging
Tea Filter Paper Market
Paper & Paperboard Packaging
Paperboard Bowl Market
Paper & Paperboard Packaging
Canada Paper Packaging Market
Paper & Paperboard Packaging
Kraft Paper SOS Bag Market
Paper & Paperboard Packaging
Paper Bottles Market
Paper & Paperboard Packaging
Europe Paper Packaging Market
Paper & Paperboard Packaging
Cardboard Tubs Market
Paper & Paperboard Packaging
Waxing Base Paper Market
Paper & Paperboard Packaging
Disposable Paper Plates Market
Paper & Paperboard Packaging
Stationery Films Packaging Market
Paper & Paperboard Packaging
Coated Recycled Paperboard Market
Paper & Paperboard Packaging
Mottled Test Liner Market
Paper & Paperboard Packaging
Sublimation Paper Market