
 Freezer Paper Market | 2026-2036
Freezer Paper Market Size, Share, and Industry Trends Forecast 2026-2036
Freezer Paper Market Foresight
The capital-intensity gap between integrated pulp-to-coating producers and merchant converters is collapsing as coating technology becomes more accessible. Reynolds Consumer Products leverages captive resin supply and national retail distribution to sustain margin structures smaller rivals cannot match. Hangzhou Hongchang Paper Products anchors its position through concentrated exports to Southeast Asian seafood processors. Mansfield Paper differentiates via specialty formulations for pharmaceutical cold-chain applications.
Freezer paper comprises a bleached or unbleached kraft base sheet laminated with polyethylene, wax, or proprietary polymer barriers to achieve moisture-vapor transmission rates below specified thresholds for frozen food preservation. The coating layer prevents freezer burn by creating a sealed microenvironment around protein and dairy products during storage durations extending to twelve months. Plastic coated paper dominates current volume owing to established supply chains and converter familiarity, though grease resistant paper represents the fastest-expanding category as clean-label and reduced-plastic packaging mandates intensify across European retail channels. Roll formats lead packaging type demand because automated meat-processing lines in Brazil and Australia run continuous-feed operations that sheets cannot accommodate efficiently.
FDA food-contact substance notifications govern coating chemistry approvals for U.S.-bound freezer paper, while REACH compliance in the European Union restricts certain phthalate-based plasticizers previously common in polyethylene coatings. China's GB standards for food packaging materials impose additional migration testing protocols that export-oriented mills must satisfy for market access. Stakeholders should monitor regulatory divergence between jurisdictions as coating reformulation costs and compliance documentation requirements increasingly determine supplier selection criteria and contract renewal outcomes.
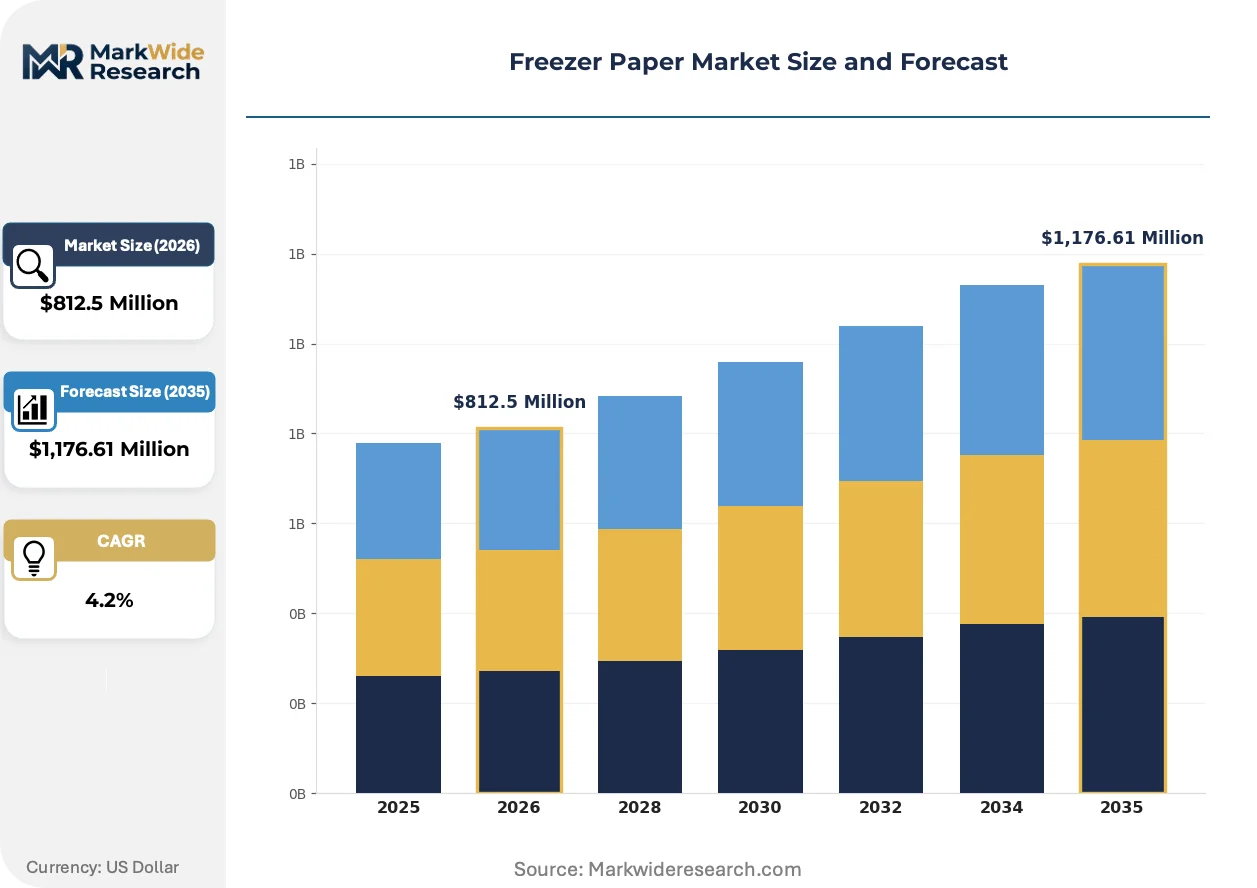
Market Dynamics
Coating chemistry accessibility is collapsing the capital barrier between integrated pulp producers and merchant converters, redistributing competitive advantage toward distribution scale and formulation specialization rather than asset ownership.
Growth Catalysts
- REACH plasticizer restrictions:European regulators have phased out phthalate-based additives in polyethylene coatings, compelling mills to develop compliant barrier formulations that command premium positioning in clean-label retail channels.
- Automated meat-processing lines:Continuous-feed operations in Brazil and Australia generate insatiable demand for roll-format freezer paper that sheet formats cannot accommodate, locking in format preferences.
- FDA food-contact substance notifications:The approval pathway for novel coating chemistries creates first-mover advantages for mills that invest early in migration testing and documentation infrastructure.
Market Restraints
- Resin supply concentration:Captive polyethylene supply chains at integrated producers like Reynolds Consumer Products disadvantage merchant converters exposed to spot resin volatility.
- GB standards compliance costs:China's migration testing protocols impose documentation burdens that small export-oriented mills struggle to absorb without dedicated regulatory staff.
- Plastic-coated paper lock-in:Established converter familiarity with incumbent barrier technologies slows adoption of grease-resistant alternatives despite performance parity.
Strategic Opportunities
- Pharmaceutical cold-chain expansion:Specialty formulations for temperature-sensitive biologics represent a high-margin white space beyond protein and dairy preservation.
- Southeast Asian seafood processing:Concentrated export demand from Vietnamese and Indonesian processors offers volume growth independent of mature North American markets.
- EU Green Deal packaging mandates:Reduced-plastic directives accelerate grease-resistant paper substitution, rewarding early movers with certified recyclable barrier technologies.
Industry Challenges
- Coating chemist talent scarcity:Formulation expertise spanning polymer science and food-contact compliance commands premium compensation that mid-tier mills struggle to match.
- Dual-jurisdiction certification timelines:Simultaneous FDA notification and REACH compliance documentation extends product launch cycles by 18-24 months.
- Legacy equipment retrofit costs:Converting lines optimized for polyethylene lamination require substantial capex to handle water-based grease-resistant coatings.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Freezer Paper Market |
| Market Size in 2026 | $812.5 Million |
| Market Size in 2035 | $1,176.61 Million |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Kraft Freezer Paper, Plastic Coated Paper, Wax Coated Paper, Grease Resistant Paper Application: Food Packaging, Pharmaceutical Packaging, Industrial Wrapping, Retail Packaging Packaging Type: Rolls, Sheets, Bags, Foil Laminated Sheets End User: Frozen Food Manufacturers, Meat Processors, Seafood Suppliers, Dairy Producers |
| Companies Covered | Mansfield Paper, Hangzhou Hongchang Paper Products, Reynolds Consumer Products, Zhuji Fred Packaging, Shandong Zhongrong Paper Products, Komar Alliance, Guangzhou Jieshen Paper, Zhejiang Heyi Tianze Industry and Trade, Intercon Paper, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Freezer Paper Market Shifts & Advancements
Barrier technology diversification is fragmenting the once-standardized coating landscape, while regulatory divergence between jurisdictions and procurement consolidation among protein processors are rewriting supplier selection criteria.
Water-based grease-resistant coatings are fragmenting the polyethylene-dominated barrier market by eliminating plastic layers while maintaining moisture-vapor transmission performance. European retail chains facing EU Green Deal mandates have accelerated qualification timelines for these formulations. The technology is fragmenting converter relationships as mills with in-house formulation capabilities bypass traditional coating suppliers.
REACH Annex XVII restrictions on phthalate plasticizers have forced wholesale reformulation of polyethylene coating recipes for European-bound production. Mills without dedicated regulatory affairs teams face exclusion from tender processes requiring comprehensive migration documentation. The pharmaceutical cold-chain segment has responded fastest, prioritizing compliant suppliers to secure biologics packaging contracts.
Consolidated procurement by integrated meatpackers is compressing supplier rosters and extending contract durations in exchange for volume commitments. Direct mill relationships are displacing distributor intermediaries in the U.S. Great Lakes corridor. This concentration is most visible in Wisconsin and Michigan processing facilities, where three buyers account for the majority of regional freezer paper consumption.
Freezer Paper Market Segmentation
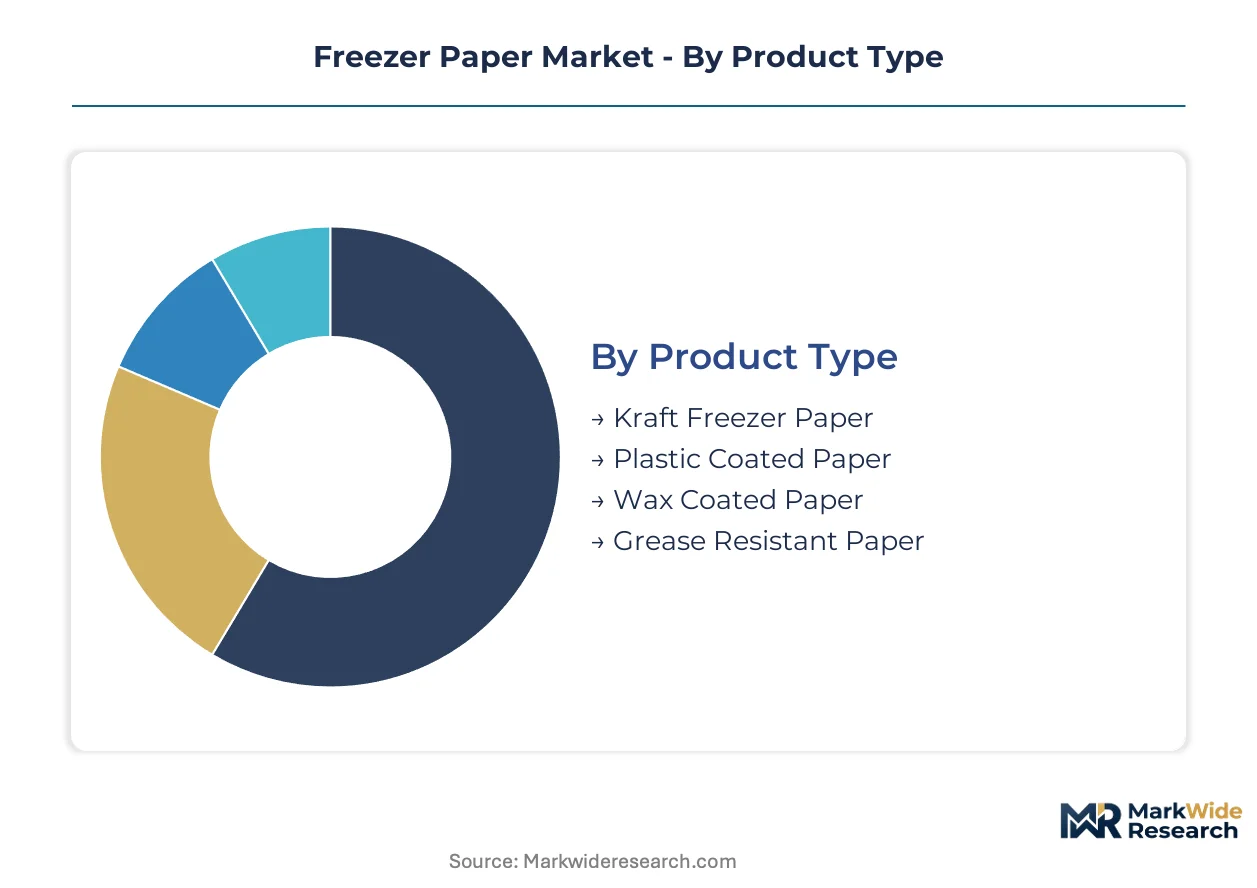
Freezer paper segmentation reveals how coating chemistry, format specifications, and end-use requirements fragment procurement patterns. Margin pools concentrate in barrier formulations that satisfy multiple regulatory jurisdictions simultaneously.
Product Type:
Plastic-coated paper commands the widest margin spread due to converter familiarity and established FDA notification pathways, while grease-resistant formulations capture premium positioning from clean-label mandates.
- Plastic Coated Paper:Polyethylene-laminated kraft substrate delivers moisture-vapor transmission rates below thresholds for twelve-month frozen storage. Automated meat-processing lines in Brazil and Australia run continuous-feed operations that lock in polyethylene specifications despite plastic-reduction pressures.
- Grease Resistant Paper:Water-based barrier coatings eliminate plastic layers while maintaining performance parity. EU Green Deal packaging mandates in Germany and France accelerate qualification timelines, rewarding mills with in-house formulation capabilities.
- Kraft Freezer Paper:Unbleached or bleached base sheet serves cost-sensitive applications with minimal barrier requirements.
- Wax Coated Paper:Paraffin-based formulations retain niche demand in artisanal and small-batch processing segments.
The dominant share belongs to plastic-coated paper, while grease-resistant paper is closing the gap fastest.
Application:
Food packaging absorbs the majority of volume throughput, though pharmaceutical cold-chain specifications generate the highest per-unit margins through compliance documentation requirements.
- Food Packaging:Protein and dairy preservation drives standardized procurement with twelve-month storage duration specifications. The U.S. Great Lakes corridor concentrates demand from integrated meatpackers running direct mill relationships.
- Pharmaceutical Packaging:Temperature-sensitive biologics require migration-tested barriers with comprehensive documentation. REACH-compliant suppliers secure premium positioning as European cold-chain networks expand.
- Industrial Wrapping:Metal and machinery protection applications tolerate lower barrier specifications.
- Retail Packaging:Consumer-facing formats face clean-label and recyclability mandates from European retail chains.
Food packaging retains volume leadership, with pharmaceutical packaging expanding most quickly on margin contribution.
Packaging Type:
Format selection follows processing line automation levels, with roll configurations dominating industrial procurement and sheet formats serving intermittent or manual operations.
- Rolls:Continuous-feed formats align with automated meat-processing infrastructure. Brazilian and Australian processors specify roll diameters and core dimensions that optimize line changeover intervals.
- Sheets:Pre-cut formats suit small-batch processors and retail butcher counters with intermittent demand patterns.
- Bags:Pre-formed configurations reduce labor in high-volume seafood processing operations.
- Foil Laminated Sheets:Multi-layer barriers target premium protein segments requiring extended storage with minimal freezer burn.
Rolls dominate procurement volumes, while foil-laminated sheets gain share fastest in premium protein segments.
End User:
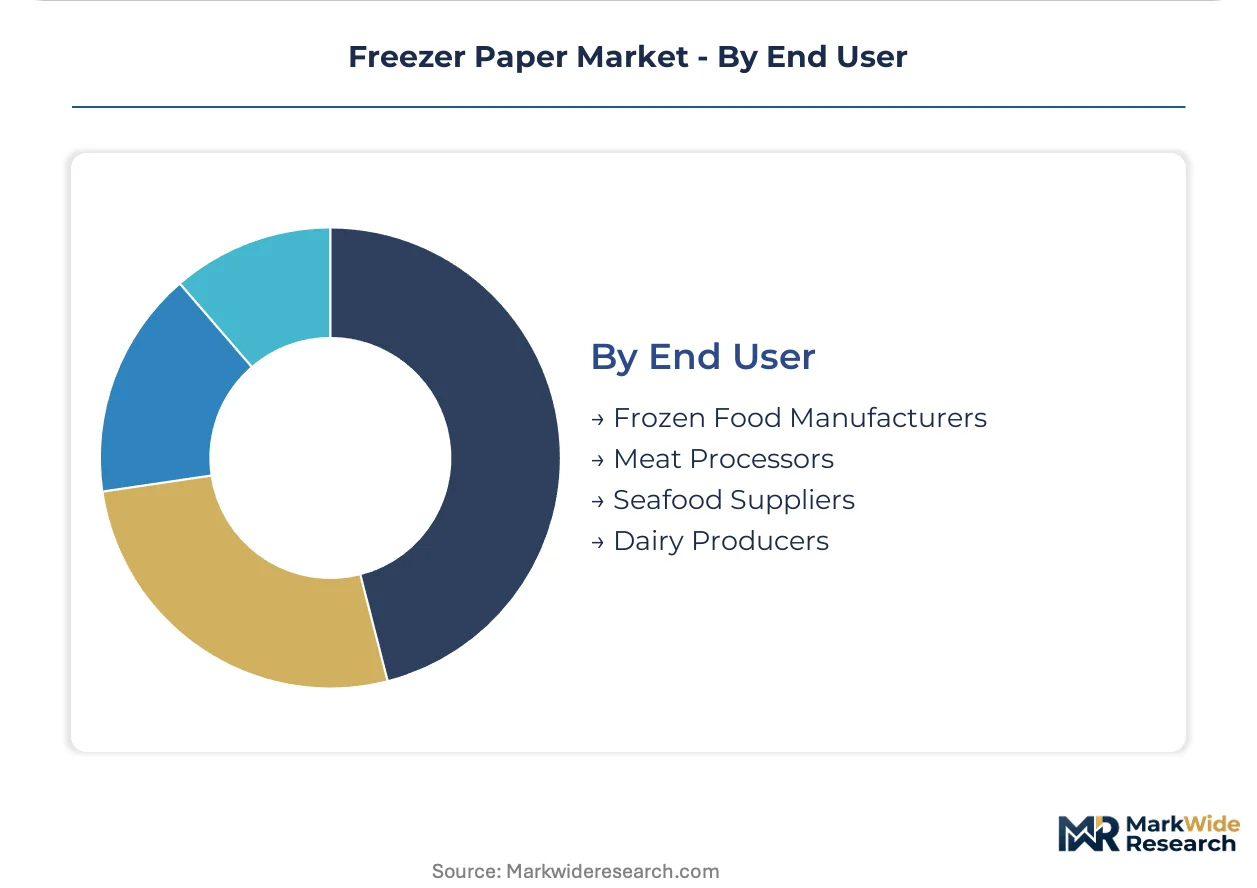
Consolidated procurement by integrated meatpackers compresses supplier rosters and extends contract durations in exchange for volume commitments.
- Meat Processors:Wisconsin and Michigan facilities account for concentrated regional consumption. Three buyers drive the majority of Great Lakes corridor procurement through direct mill relationships displacing distributors.
- Seafood Suppliers:Vietnamese and Indonesian processors generate export demand independent of mature North American markets. Hangzhou-based mills anchor supply relationships through concentrated export volumes.
- Frozen Food Manufacturers:Diversified protein and prepared meal portfolios require flexible barrier specifications across product lines.
- Dairy Producers:Cheese and butter preservation applications prioritize moisture-vapor transmission performance over grease resistance.
Meat processors command the largest procurement volumes, with seafood suppliers climbing fastest on Southeast Asian processing expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United States where integrated meatpackers command volume discounts, while European mills extract premiums through REACH-compliant barrier formulations. Regional procurement patterns diverge sharply between automated processing corridors and artisanal segments.
United States
The Great Lakes meat-processing corridor drives concentrated demand from Wisconsin and Michigan facilities running continuous-feed operations. FDA food-contact substance notifications govern coating chemistry approvals for domestic-bound production. Three integrated buyers in the region account for the majority of procurement through direct mill relationships displacing traditional distributors.
Germany
EU Green Deal packaging mandates accelerate qualification timelines for water-based grease-resistant coatings across retail channels. REACH Annex XVII restrictions on phthalate plasticizers force wholesale reformulation of polyethylene coating recipes. Mills in Baden-Württemberg and North Rhine-Westphalia anchor supply relationships with cold-chain logistics providers serving temperature-sensitive biologics.
China
GB standards for food packaging materials impose migration testing protocols that export-oriented mills must satisfy for market access. The country's national food safety regulator enforces documentation burdens favoring mills with dedicated regulatory affairs teams. Hangzhou-based producers concentrate exports to Vietnamese and Indonesian seafood processors seeking volume growth independent of mature Western markets.
Brazil
Automated meat-processing lines generate insatiable demand for roll-format freezer paper specifications that sheet formats cannot accommodate. The national health surveillance agency oversees food-contact material compliance through port-of-entry inspection protocols. São Paulo and Minas Gerais processing facilities specify roll diameters and core dimensions optimizing line changeover intervals.
Australia
Continuous-feed operations in protein processing lock in polyethylene specifications despite plastic-reduction pressures from retail chains. The Therapeutic Goods Administration coordinates with food safety regulators on cold-chain packaging standards for pharmaceutical applications. Queensland and New South Wales seafood processors drive specialized demand for extended-duration barrier performance in tropical storage conditions.
Freezer Paper Market Competitive Landscape
Concentration sits with integrated pulp-to-coating producers who leverage captive resin supply and national retail distribution to sustain margin structures smaller rivals cannot match. Merchant converters face collapsing capital barriers as coating technology becomes more accessible, redistributing competitive advantage toward formulation specialization and distribution scale. Three strategic archetypes dominate: integrated producers with backward resin control, export-focused specialists serving Southeast Asian seafood processors, and pharmaceutical cold-chain formulators. Dominant competitive moves include strategic partnerships with automated meatpackers for direct mill relationships and portfolio diversification into grease-resistant barrier technologies.
Among United States-based integrated producers, Reynolds Consumer Products and Mansfield Paper exemplify divergent positioning archetypes. Reynolds represents scale-driven supply integration with captive polyethylene chains, while Mansfield occupies the specialty formulation tier targeting pharmaceutical cold-chain applications. Hangzhou Hongchang Paper Products anchors the export-specialist vector, concentrating relationships with Southeast Asian seafood processors. Chinese fabricators including Shandong Zhongrong Paper Products and Zhejiang Heyi Tianze Industry and Trade sit within the volume-export tier serving procurement consolidation in Vietnamese and Indonesian processing facilities.
| Leading Market Players |
|---|
| Mansfield Paper |
| Hangzhou Hongchang Paper Products |
| Reynolds Consumer Products |
| Zhuji Fred Packaging |
| Shandong Zhongrong Paper Products |
| Komar Alliance |
| Guangzhou Jieshen Paper |
| Zhejiang Heyi Tianze Industry and Trade |
| Intercon Paper |
| Others |
Supply & Pricing Matrix
Long-term offtake contracts between integrated meatpackers and coating mills lock in polyethylene supply access while freezing price visibility across multi-year procurement cycles. These arrangements concentrate pricing power with Reynolds Consumer Products and similar integrated producers in the U.S. Great Lakes corridor, where captive resin supply buffers spot volatility that merchant converters cannot absorb.
Pricing Analysis
The customization-premium spread separates standard polyethylene-laminated rolls from configured-to-order grease-resistant formulations with REACH-compliant documentation. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and volume scale, with pharmaceutical cold-chain specifications commanding the widest spreads. Price differentiation stems from dual-jurisdiction FDA and REACH compliance costs rather than raw material inputs alone. Cost compression in standard plastic-coated tiers is intensifying because coating chemistry accessibility erodes converter switching costs, while meat processors in Brazil and Australia show least price sensitivity due to automation lock-in.
Supply Chain Analysis
Inventory buffers and lead-time compression vary sharply between captive resin producers and merchant converters dependent on spot polyethylene markets. Supply concentrates in the United States, China, and Germany, with coating formulation expertise clustering in Baden-Württemberg and the U.S. Midwest. Raw material dependencies center on bleached kraft pulp, polyethylene resin, and proprietary polymer barriers. Single-source vulnerability in phthalate-free plasticizer supply chains threatens REACH-compliant production lines. Distribution runs through direct mill relationships displacing traditional intermediaries in protein processing corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Freezer paper demand tracks protein processing capacity cycles, with automated line investments in Brazil and Australia signaling recovery-phase procurement acceleration.
For Market Incumbents: Shield margin structures by deepening captive resin supply and securing exclusive formulation partnerships with FDA-pre-notified coating chemists. The collapse of capital barriers threatens integrated producers' historical advantage, making backward integration into barrier R&D essential for differentiation. Prioritize capacity reservation contracts with Great Lakes meatpackers to lock out merchant converter competition. For New Entrants and Emerging Players: Anchor in pharmaceutical cold-chain specifications where compliance documentation requirements create defendable moats against scale players. Southeast Asian seafood processing offers the most penetrable geography, with Vietnamese and Indonesian processors seeking alternatives to Hangzhou-centric supply. Lead with REACH-certified grease-resistant formulations to bypass polyethylene converter lock-in. For Investors and Strategic Acquirers: Capital is best deployed toward mid-tier mills with in-house coating formulation capabilities and existing dual-jurisdiction certification infrastructure. Long-term viability over the coming decade hinges on regulatory agility rather than asset scale. Monitor EU Green Deal packaging mandate enforcement timelines as the critical inflection signal for grease-resistant paper substitution velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Barrier R&D | In-house formulation capabilities bypass traditional coating suppliers and capture premium positioning in clean-label retail channels. |
| Dual-Jurisdiction Certification Investment | Simultaneous FDA notification and REACH compliance documentation extends product launch cycles but locks in tender eligibility. |
| Direct Mill Relationship Establishment | Integrated meatpackers in Wisconsin and Michigan increasingly displace distributor intermediaries for volume procurement. |
| Grease-Resistant Coating Scale-Up | Water-based barrier production requires legacy equipment retrofit capex that filters out undercapitalized competitors. |
| Southeast Asian Export Concentration | Vietnamese and Indonesian seafood processors generate demand growth independent of mature North American market saturation. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with coating chemists, protein processing procurement directors, cold-chain logistics specialists, and regulatory affairs managers at export-oriented mills. Secondary validation drew from FDA food-contact substance notification databases, ECHA REACH Annex XVII restriction updates, Chinese GB standards compliance records, and customs trade flow data for polyethylene-laminated kraft shipments. Bottom-up volume estimates from mill capacity utilization rates were triangulated against top-down protein processing line expansion announcements.
Across the analysis window, projections incorporate coating chemistry substitution curves, automated meat-processing line installation schedules, and regulatory divergence between FDA notification pathways and REACH reformulation timelines. Segmentation modeling spans product type, application, packaging format, and end-user procurement consolidation patterns. CAGRs were derived from elasticity-adjusted demand functions tied to frozen food preservation volume growth and pharmaceutical cold-chain network expansion.
Material uncertainties — sudden phthalate-ban enforcement scope changes, resin supply disruptions, or coating chemist talent scarcity intensification — sit outside the modeled envelope. Forecasts reflect documented assumptions about regulatory compliance cost trajectories and processor automation adoption rates. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
Australia Paper and Paperboard Packaging Market
Paper & Paperboard Packaging
Honeycomb Mailers Market
Paper & Paperboard Packaging
Italy Paper Packaging Market
Paper & Paperboard Packaging
Russia Paper Packaging Market
Paper & Paperboard Packaging
Converting Paper Market
Paper & Paperboard Packaging
Retail Paper Bags Market
Paper & Paperboard Packaging
North America Paper Cone Market
Paper & Paperboard Packaging
Wax-Coated Paper Market
Paper & Paperboard Packaging
Postal Tubes Market
Paper & Paperboard Packaging
Coated Sack Kraft Paper Market
Paper & Paperboard Packaging
Push-Pull Slip Sheets Market
Paper & Paperboard Packaging
Global Corrugated Board Packaging Market
Paper & Paperboard Packaging
Kraft Envelopes Market
Paper & Paperboard Packaging
Recycled Paper Packaging Market
Paper & Paperboard Packaging
France Paper Packaging Market
Paper & Paperboard Packaging
Box Liners Market