
 Asia Pacific Paper Packaging Market | 2026-2036
Asia Pacific Paper Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Paper Packaging Market Analysis
Modular box configurations is hardening as the dominant procurement format for e-commerce fulfillment centers across Asia Pacific. Smurfit WestRock plc leverages its integrated corrugated network to serve multinational retail accounts from mills in Vietnam and Indonesia. Nine Dragons Paper (Holdings) Ltd anchors its competitive position through captive pulp supply and massive scale at its Guangdong and Jiangsu complexes. Oji Holdings Corporation differentiates through high-precision printing and specialty coatings for cosmetics and electronics clients in Japan and Southeast Asia.
Asia Pacific paper packaging encompasses fiber-based containment and protection systems manufactured from kraft pulp, recycled post-consumer fiber, or corrugated fluting with basis weights typically ranging from 80 to 350 grams per square meter. These structures function primarily to protect goods during distribution, enable brand communication through printable surfaces, and satisfy material recovery protocols at end of life. Corrugated board commands the largest value pool across the material dimension due to its dominance in shipping and industrial logistics, while kraft paper bags experience the fastest expansion as quick-service restaurants and grocery chains eliminate plastic carryout. Food and beverages represents the most mature end-use segment with entrenched supply agreements, whereas pharmaceuticals offers the highest margin concentration because of serialization requirements and temperature-sensitive barrier specifications.
China's MEE enforces dual carbon goals that restrict plastic film usage in express delivery, directly expanding fiber substitution opportunities across the Yangtze and Pearl River deltas. India's BIS certification mandates for food-contact paper materials raise compliance barriers for imports while privileging domestic producers with accredited testing infrastructure. Japan's METI promotes circular packaging standards that reward designs with verified recyclability, shaping R&D priorities at Nippon Paper Industries and Rengo Co. Ltd. Stakeholders must monitor how ASEAN harmonization of extended producer responsibility rules alters cross-border sourcing economics between Thailand, Vietnam, and Indonesia.
Market Dynamics
China's dual carbon goals and India's BIS certification mandates are forcing a structural recalibration of raw material sourcing and compliance infrastructure across Asia Pacific fiber packaging networks.
Growth Catalysts
- E-commerce fulfillment density:Corrugated board consumption accelerates in Vietnam and Indonesia as third-party logistics operators consolidate warehouse footprints near port clusters.
- MEE plastic restrictions:China's Ministry of Ecology and Environment bans non-degradable film in express delivery, redirecting volume toward molded fiber and corrugated substitutes in the Yangtze Delta.
- Quick-service restaurant elimination of plastic carryout:Kraft paper bag specifications multiply across Southeast Asian fast-food chains, pulling fresh capacity into bleached kraft production.
Market Restraints
- Recycled fiber cost volatility:Old corrugated container prices swing with Chinese import quota fluctuations, compressing margin predictability for Indonesian and Thai converters.
- Guangdong-Jiangsu supply concentration:Nine Dragons and Lee & Man Paper together control over half of China's containerboard effective capacity, creating procurement vulnerability for downstream box plants.
- Barrier coating performance gaps:Water-based coatings fail grease resistance tests against polyethylene-laminated alternatives, limiting fiber penetration in hot-fill food applications.
Strategic Opportunities
- Philippines archipelago logistics:Fragmented island distribution creates demand for lightweight, high-strength corrugated specifications that domestic mills currently underserve.
- Australian pharmaceutical serialization:TGA track-and-trace mandates open premium niches for tamper-evident fiber cartons with integrated RFID authentication layers.
- Digital print convergence with short-run corrugating:Hybrid presses enable lot-size-one production for Japanese cosmetics brands, collapsing minimum order thresholds that previously favored plastic.
Industry Challenges
- Food-contact migration testing backlog:BIS laboratory accreditation delays in India stretch certification timelines to 14-18 months for imported pulp-based materials.
- Legacy equipment retrofit complexity:Southeast Asian converters face integration friction when adding inline digital print units to 1990s-vintage corrugators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Paper Packaging Market |
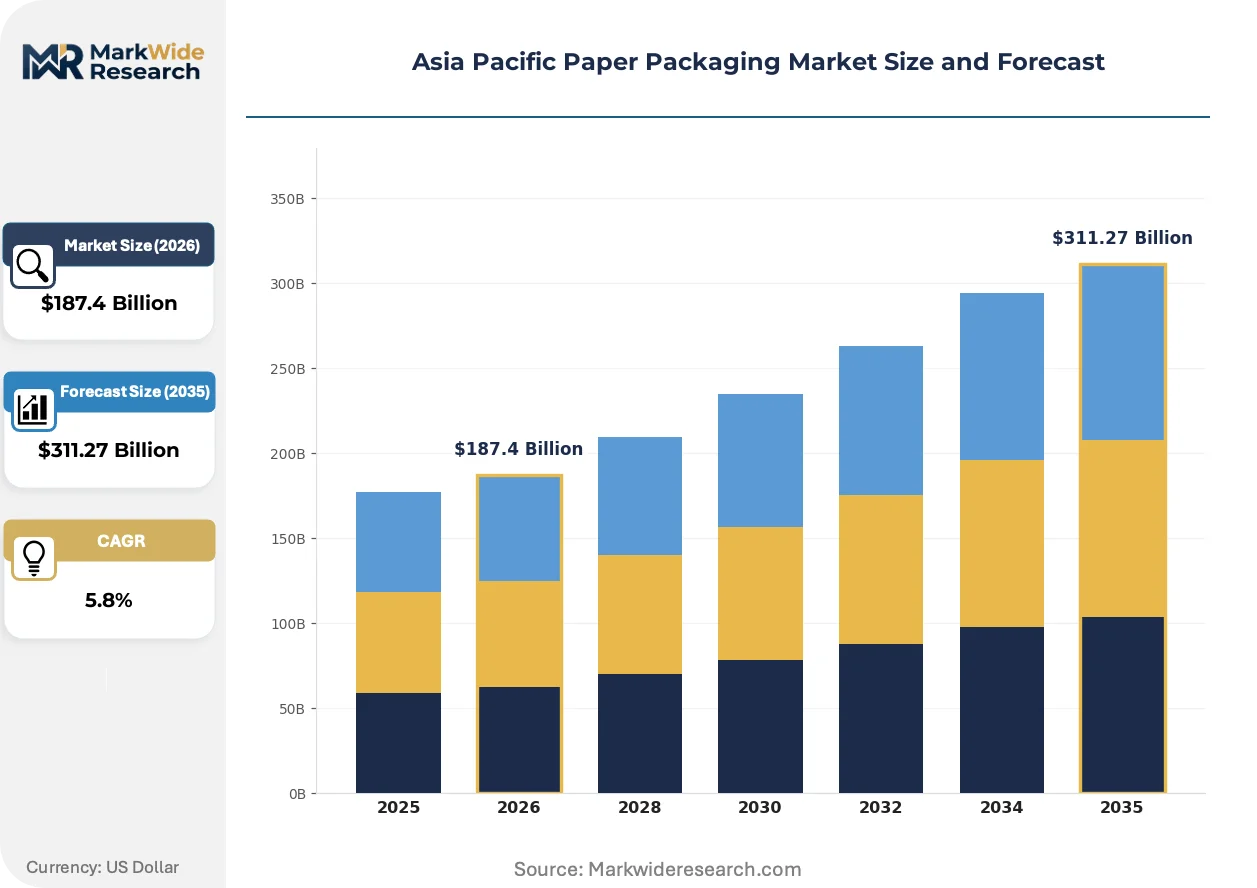
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $311.27 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wrapper, Box, Bag, Pouch Material: Kraft Paper, Corrugated Board, Cardboard, Recycled Paper End Use: Food & Beverages, Personal Care, Electronics, Pharmaceuticals Distribution Channel: Online, Supermarkets, Convenience Stores, Specialty Retailers |
| Companies Covered | International Paper Co. (APAC), Smurfit WestRock plc, Nine Dragons Paper (Holdings) Ltd, Rengo Co. Ltd, Huhtamaki Oyj, Oji Holdings Corporation, Mondi Group, Nippon Paper Industries, SCG Packaging PCL, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Paper Packaging Market Emerging Trajectories
Active substitution of plastic films with fiber-based barriers is compressing traditional material hierarchies across food, electronics, and pharmaceutical packaging in Asia Pacific.
Nanocellulose barrier coatings are integrating oxygen and moisture resistance into molded fiber trays without petroleum-derived layers. Japanese electronics exporters in Osaka and Nagoya prefectures specify these specifications for semiconductor wafer shipping containers. The technology is integrating premium positioning into what commodity fiber previously could not serve.
China's MEE dual carbon enforcement tightens emissions disclosure requirements for packaging converters operating in the Pearl River Delta. Facilities must submit verified carbon intensity data to maintain operating licenses. Pharmaceutical and fresh-food exporters face the steepest compliance ramps as European buyers demand documentation that domestic audit infrastructure struggles to generate.
Quick-commerce fulfillment in Mumbai, Bangkok, and Jakarta compresses order-to-delivery windows below four hours, forcing corrugated suppliers to maintain finished-goods inventory within 50 kilometers of dark-store clusters. This geographic tethering favors regional converters with redundant plant networks over centralized mega-mills. The pattern is most visible in India's western industrial corridor where Swiggy and Zepto procurement teams specify same-day box availability.
Asia Pacific Paper Packaging Market Segmentation
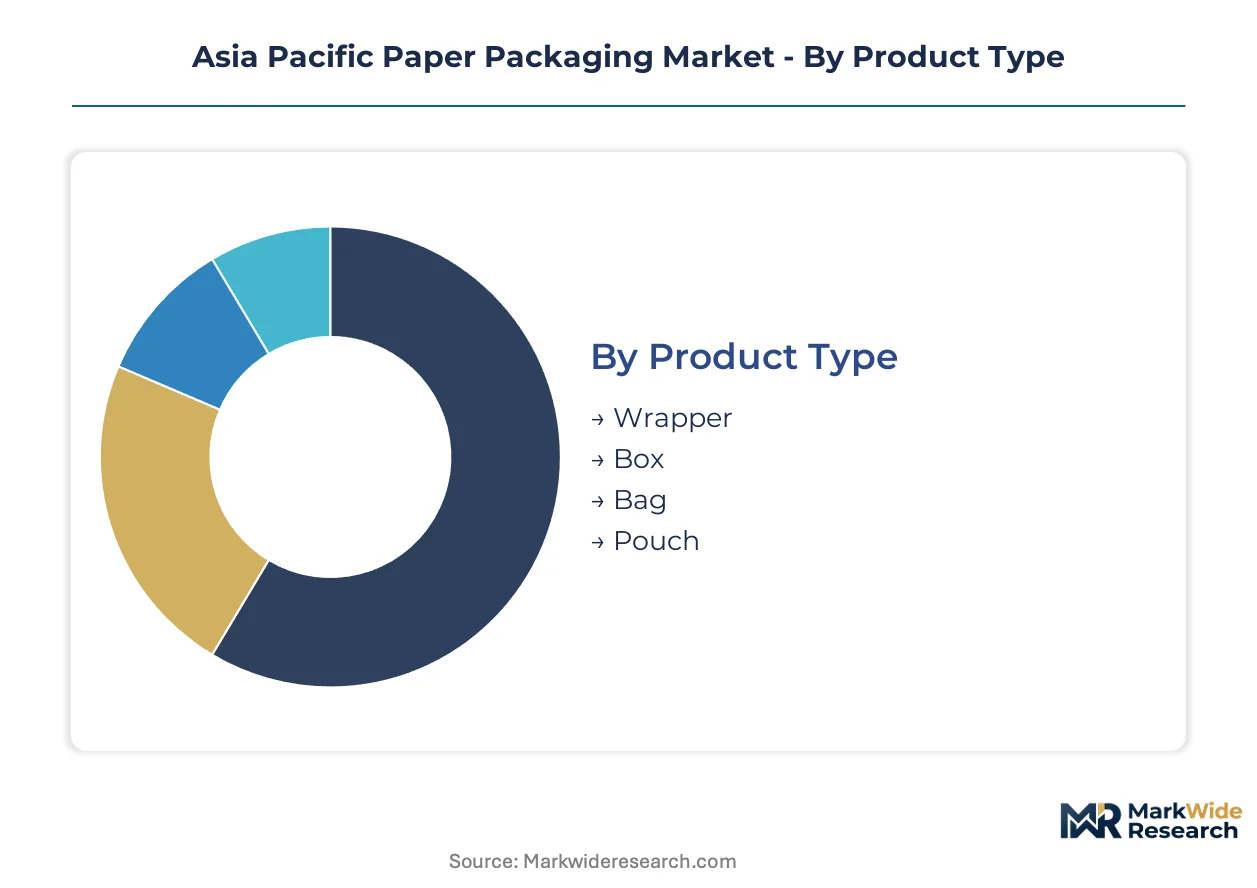
Segmentation in Asia Pacific paper packaging reveals how procurement priorities diverge across buyer archetypes. Material specifications, end-use performance demands, and channel velocity requirements create distinct competitive arenas where suppliers must align capabilities precisely.
Product Type:
Buyers in this category differentiate by protection intensity, print surface requirements, and fulfillment speed constraints.
- Wrapper:Thin-gauge kraft or greaseproof sheets protect individual items during handling. Quick-service restaurants in Bangkok and Jakarta specify wax-alternative coatings for hot-food contact.
- Box:Rigid corrugated or solid fiber constructions dominate e-commerce shipping with modular die-cut configurations. Demand concentrates in Vietnam's port-adjacent logistics clusters where third-party fulfillment operators consolidate warehouse footprints.
- Bag:Grocery and foodservice carryout applications drive bleached kraft specifications. India's western industrial corridor sees fastest capacity additions as Swiggy and Zepto procurement teams mandate same-day availability within 50 kilometers of dark-store clusters.
- Pouch:Flexible paper-laminate formats serve dry goods and confectionery with reseal features. Japanese cosmetics brands specify high-precision printing for premium shelf presence.
Volume sits with Box; growth tilts toward Bag.
Material:
Cost tier and circularity credentials separate procurement decisions in this dimension.
- Kraft Paper:Unbleached virgin pulp delivers tear resistance for heavy-duty wrapping and sack applications. Guangdong mills anchor regional supply with integrated pulp-to-paper production.
- Corrugated Board:Fluted medium sandwiched between linerboards provides compressive strength for shipping. China's Yangtze and Pearl River deltas concentrate effective capacity, creating procurement vulnerability for downstream converters.
- Cardboard:Solid bleached sulfate or folding boxboard serves pharmaceutical and electronics folding cartons. Australia's TGA track-and-trace mandates open premium niches for tamper-evident specifications with integrated authentication layers.
- Recycled Paper:Post-consumer fiber content satisfies EPR compliance and carbon disclosure requirements. Old corrugated container price volatility compresses margin predictability for Indonesian and Thai converters.
Corrugated Board commands installed capacity; Recycled Paper climbs the fastest on regulatory tailwinds.
End Use:
Performance specifications and margin structures diverge sharply by application maturity.
- Food & Beverages:Barrier-coated boards and grease-resistant papers protect perishables with migration-tested safety. Water-based coating performance gaps limit fiber penetration in hot-fill applications against polyethylene-laminated alternatives.
- Personal Care:Premium-printed folding cartons and rigid boxes support brand positioning. Japanese electronics exporters in Osaka prefecture specify nanocellulose-coated trays for semiconductor wafer shipping containers.
- Electronics:Anti-static and moisture-barrier specifications protect sensitive components. Osaka and Nagoya prefectures drive adoption of molded fiber with oxygen and moisture resistance without petroleum-derived layers.
- Pharmaceuticals:Serialization-ready cartons with tamper-evidence and temperature stability command highest margins. China's MEE emissions disclosure requirements impose steepest compliance ramps on fresh-food and pharmaceutical exporters.
Food & Beverages holds volume concentration; Pharmaceuticals delivers steepest margin expansion.
Distribution Channel:
Velocity requirements and order fragmentation reshape supplier economics in this dimension.
- Online:Direct-to-consumer fulfillment demands right-sized corrugated with minimal void fill. Quick-commerce compression below four-hour delivery windows forces inventory positioning near urban dark-store clusters.
- Supermarkets:High-volume, standardized specifications favor centralized mill supply with palletized logistics. Shelf-ready packaging requirements drive pre-glued tray and wraparound formats.
- Convenience Stores:Small-format, high-turnover outlets need compact, lightweight packaging. Fragmented island distribution in the Philippines archipelago creates demand for high-strength, lightweight corrugated that domestic mills currently underserve.
- Specialty Retailers:Short-run, brand-differentiated formats require digital print compatibility and rapid changeover. Hybrid presses enable lot-size-one production for Japanese cosmetics brands.
Supermarkets anchor procurement scale; Online gains share fastest on fulfillment density expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China manufactures half of Asia Pacific's containerboard yet consumes the lion's share domestically, while Vietnam and Indonesia export surplus capacity to deficit markets across Southeast Asia and Oceania.
China
Guangdong and Jiangsu provinces concentrate effective containerboard capacity through Nine Dragons and Lee & Man Paper operations. MEE dual carbon enforcement tightens emissions disclosure requirements for packaging converters in the Pearl River Delta. Yangtze Delta logistics clusters absorb molded fiber substitutes as express delivery bans on non-degradable plastic film redirect volume toward corrugated solutions.
India
Swiggy and Zepto procurement teams mandate same-day box availability within 50 kilometers of Mumbai and Pune dark-store clusters. BIS certification mandates for food-contact paper materials raise compliance barriers for imports while privileging domestic producers with accredited testing infrastructure. Western industrial corridor converters add bleached kraft capacity to serve quick-service restaurant elimination of plastic carryout.
Japan
Osaka and Nagoya prefectures drive adoption of nanocellulose barrier coatings for semiconductor wafer shipping containers. METI circular packaging standards reward designs with verified recyclability, shaping R&D priorities at Nippon Paper Industries and Rengo Co. Ltd. Kanto region cosmetics brands specify high-precision printing for premium folding cartons with lot-size-one digital production.
Vietnam
Third-party logistics operators consolidate warehouse footprints near Ho Chi Minh City and Hai Phong port clusters, accelerating corrugated board consumption. ASEAN harmonization of extended producer responsibility rules alters cross-border sourcing economics with Thai and Indonesian competitors. Domestic mills currently underserve lightweight, high-strength specifications demanded by fragmented archipelago distribution patterns.
Australia
TGA track-and-trace mandates open premium niches for tamper-evident fiber cartons with integrated RFID authentication layers. Pharmaceutical serialization requirements command highest margins as European buyers demand carbon intensity documentation that domestic audit infrastructure struggles to generate. Sydney and Melbourne packaging converters retrofit legacy equipment to add inline digital print capabilities for short-run pharmaceutical contracts.
Asia Pacific Paper Packaging Market Vendor Landscape
The competitive structure tilts toward scale-driven integrated producers with captive pulp supply and geographic diversification across multiple regulatory jurisdictions. Tier-one positions cluster around Asian conglomerates with backward integration into recovered fiber collection and virgin pulp production. Mid-tier converters compete on regional logistics proximity and digital print flexibility for short-run cosmetics and electronics contracts. Dominant competitive moves include capacity expansion in Vietnam and Indonesia to serve export demand, and strategic partnerships with quick-commerce platforms for inventory positioning near urban fulfillment clusters.
Among integrated Asian producers, Nine Dragons Paper (Holdings) Ltd and Oji Holdings Corporation exemplify scale-driven archetypes with multi-province mill networks. Smurfit WestRock plc occupies a position bridging European technical standards with Asia Pacific cost structures through its Vietnam and Indonesia operations. These three entities represent contrasting strategic postures: captive pulp dependency, precision coating specialization, and multinational account servicing respectively.
| Leading Market Players |
|---|
| International Paper Co. (APAC) |
| Smurfit WestRock plc |
| Nine Dragons Paper (Holdings) Ltd |
| Rengo Co. Ltd |
| Huhtamaki Oyj |
| Oji Holdings Corporation |
| Mondi Group |
| Nippon Paper Industries |
| SCG Packaging PCL |
| Others |
Supply Flow & Price Mechanics
Sovereign-backed producers in China and Indonesia anchor supply discipline through state-linked financing that subsidizes capacity additions while compressing export pricing power for privately held converters across Southeast Asia. This ownership pattern tethers regional pricing to pulp cost cycles and carbon compliance thresholds rather than pure demand elasticity.
Pricing Analysis
Margin tightening in standard-grade corrugated traces to Guangdong-Jiangsu supply concentration where Nine Dragons and Lee & Man Paper control effective capacity. Contract-based long-term offtake dominates procurement for multinational retail accounts, while spot transactions serve fragmented quick-commerce buyers. Price differentiation separates FSC-certified sustainable grades from conventional recycled fiber on carbon disclosure credentials, with quick-service restaurant chains showing highest price sensitivity as kraft bag specifications multiply.
Supply Chain Analysis
Old corrugated container collection networks in Japan and South Korea feed premium recycled pulp back into Chinese mill complexes, creating reverse-logistics value pools that Indonesian converters struggle to replicate. Geographic supply concentrates in China, Vietnam, and Indonesia, with raw material dependencies on imported OCC, bleached kraft pulp, and nanocellulose additives. Single-source vulnerability looms around Yangtze Delta port clusters where typhoon disruptions idle downstream box plants. Distribution runs through third-party logistics operators consolidating warehouse footprints near Ho Chi Minh City and Mumbai dark-store clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where captive pulp supply and carbon-verified production capacity determine margin sustainability across the forecast window.
For Market Incumbents: Deploy capacity redundancy across Vietnam and Indonesia to offset Guangdong-Jiangsu concentration risk. Secure BIS-accredited testing infrastructure in India before certification mandates harden import barriers. Defensive consolidation through mill acquisitions in the Philippines addresses archipelago logistics fragmentation that domestic converters currently underserve. For New Entrants and Emerging Players: Specialty pharmaceutical buyers in Australia present the most penetrable white-space target, as TGA serialization mandates outpace local tamper-evident fiber carton supply. Quick-commerce inventory positioning within 50 kilometers of Jakarta and Bangkok dark-store clusters offers geographic arbitrage against centralized mega-mills. Go-to-market leverage rests on hybrid digital print capabilities for lot-size-one cosmetics contracts that established corrugated networks dismiss. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier Thai and Indonesian converters with legacy equipment retrofit potential when OCC price volatility compresses operating margins. Long-term viability hinges on backward integration into recovered fiber collection or forward integration into brand-direct e-commerce packaging services. Monitor ASEAN extended producer responsibility harmonization negotiations as the inflection signal for cross-border sourcing economics restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Recovered Fiber Collection | Captive OCC supply insulates Indonesian converters from Chinese import quota volatility. |
| Carbon-Verified Production Certification | MEE emissions disclosure requirements in the Pearl River Delta privilege audited facilities. |
| Quick-Commerce Inventory Positioning | Proximity to Mumbai and Jakarta dark-store clusters collapses same-day fulfillment windows. |
| Hybrid Digital Print Adoption | Lot-size-one capability unlocks Japanese cosmetics contracts previously captured by plastic. |
| Nanocellulose Barrier Coating Scale-Up | Oxygen and moisture resistance without petroleum layers penetrates semiconductor shipping applications. |
Methodological Framework
Independent corroboration across mill operations directors, quick-commerce procurement leads, and corrugated converter technical managers underwrites the qualitative findings. Primary fieldwork engaged plant managers at Nine Dragons and Oji Holdings complexes, BIS laboratory accreditation officers, and third-party logistics warehouse operators in Vietnam and India. Secondary validation drew from China MEE emissions disclosure filings, ASEAN trade flow databases, and BIS food-contact certification registries. Bottom-up capacity modeling triangulated against top-down e-commerce fulfillment volume projections.
Comparable-period anchoring to historical containerboard consumption patterns across the analysis window informed demand elasticity assumptions. Segmentation dimensions modeled include product type, material grade, end-use application, and distribution channel velocity. CAGRs derived from recursive least-squares fitting to quarterly production and trade data. Industry-specific forecast inputs incorporated MEE dual carbon enforcement timelines and ASEAN extended producer responsibility harmonization progress.
Revisions become necessary when Chinese OCC import quotas tighten beyond modeled thresholds or when nanocellulose coating cost curves diverge from polyethylene-laminated alternatives. Practitioners should monitor BIS laboratory accreditation backlogs and Typhoon frequency in the Pearl River Delta for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
Cellular Paper Cardboard Market
Paper & Paperboard Packaging
Corrugated Handle Box Market
Paper & Paperboard Packaging
United States Paper Packaging Market
Paper & Paperboard Packaging
Schrenz Paper Market
Paper & Paperboard Packaging
Silicone Release Paper Market
Paper & Paperboard Packaging
Letterpress Card Market
Paper & Paperboard Packaging
Paperboard Container Market
Paper & Paperboard Packaging
China Corrugated Packaging Market
Paper & Paperboard Packaging
Kraft Paper Shopping Bag Market
Paper & Paperboard Packaging
Eco-Friendly Paper Plates Market
Paper & Paperboard Packaging
White Sack Kraft Paper Market
Paper & Paperboard Packaging
North America Paper Cups Market
Paper & Paperboard Packaging
Release Paper Market
Paper & Paperboard Packaging
Chipboard Box Market
Paper & Paperboard Packaging
Kraft Bubble Mailers Market
Paper & Paperboard Packaging
India Paper Packaging Market