
 Shredded Paper Filler Market | 2026-2036
Shredded Paper Filler Market Size, Share, and Industry Trends Forecast 2026-2036
Shredded Paper Filler Market Outlook
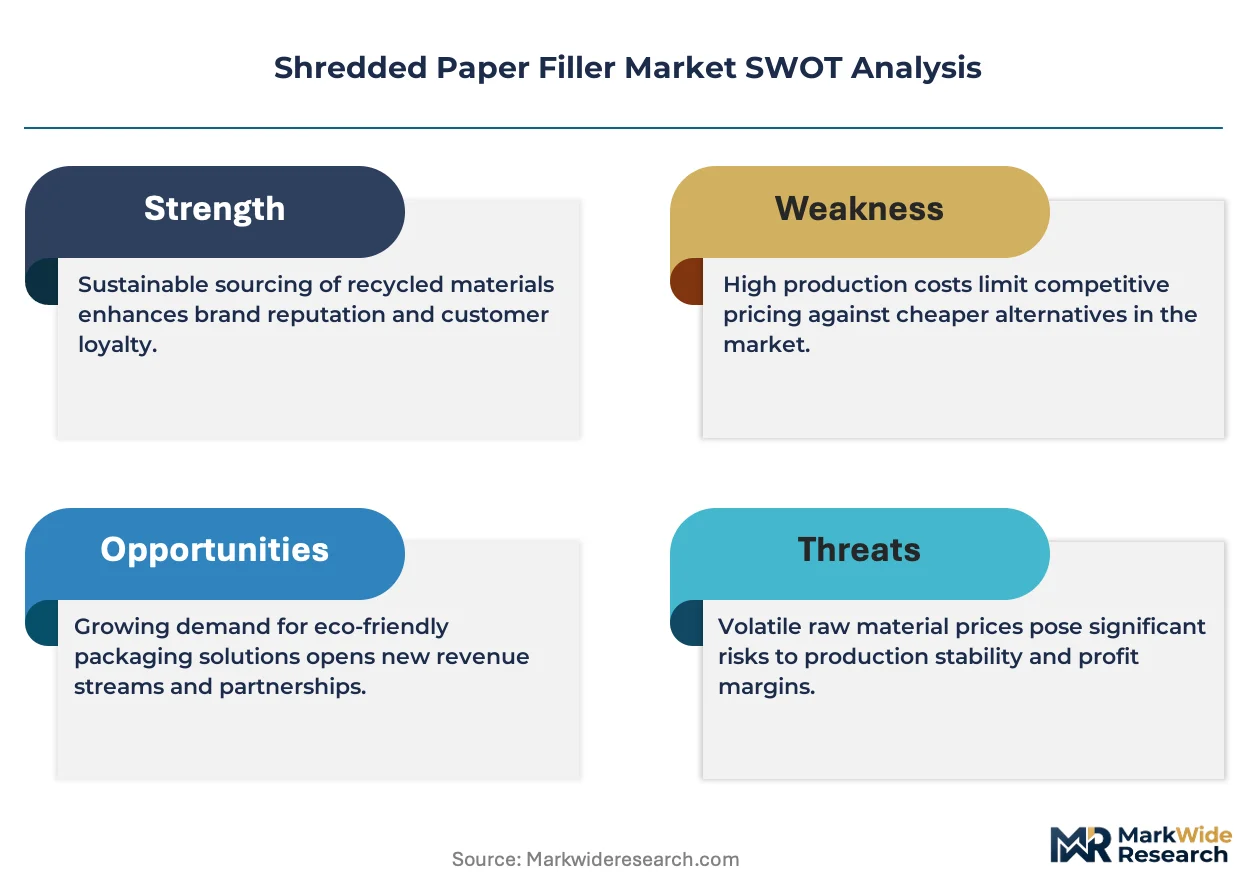
E-commerce fulfillment channels is narrowing as direct-to-consumer brands consolidate supplier lists around certified sustainable packaging partners. Ranpak Holdings Corp. leverages its automated paper-based cushioning systems to anchor North American e-commerce accounts. Mondi plc competes through integrated pulp-to-paper operations that sustain margin control across European retail supply chains. Smurfit Kappa Group Plc dominates corrugated-adjacent filler distribution, extending its reach through on-site shredding services at major logistics hubs.
Shredded paper filler consists of mechanically cut or torn paper strips, typically ranging from 2 mm to 8 mm in width, manufactured from kraft, newsprint, or recycled post-consumer fiber stock and used primarily as protective void-fill and presentation cushioning within shipping containers. The manufacturing process involves cross-cut shredding, dust extraction, and anti-static treatment to ensure clean handling in automated packing lines. Recycled shredded paper occupies the largest volume position across grade tiers, while biodegradable shredded paper captures the fastest expansion as compostability certifications become a procurement filter for major retailers. Premium grade material commands the widest margin pool, particularly in cosmetics and gift-box applications where visual presentation drives purchasing decisions.
The EPA's recycled content guidelines for federal procurement, the EU Packaging and Packaging Waste Regulation, and ISO 14021 environmental labeling standards collectively shape product specifications and market access requirements for shredded paper filler manufacturers. REACH compliance and FSC chain-of-custody certification now function as baseline qualifiers rather than differentiators in European retail procurement. Stakeholders must monitor evolving extended producer responsibility schemes and compostability testing protocols to anticipate which material grades will retain commercial viability across major consumer markets.
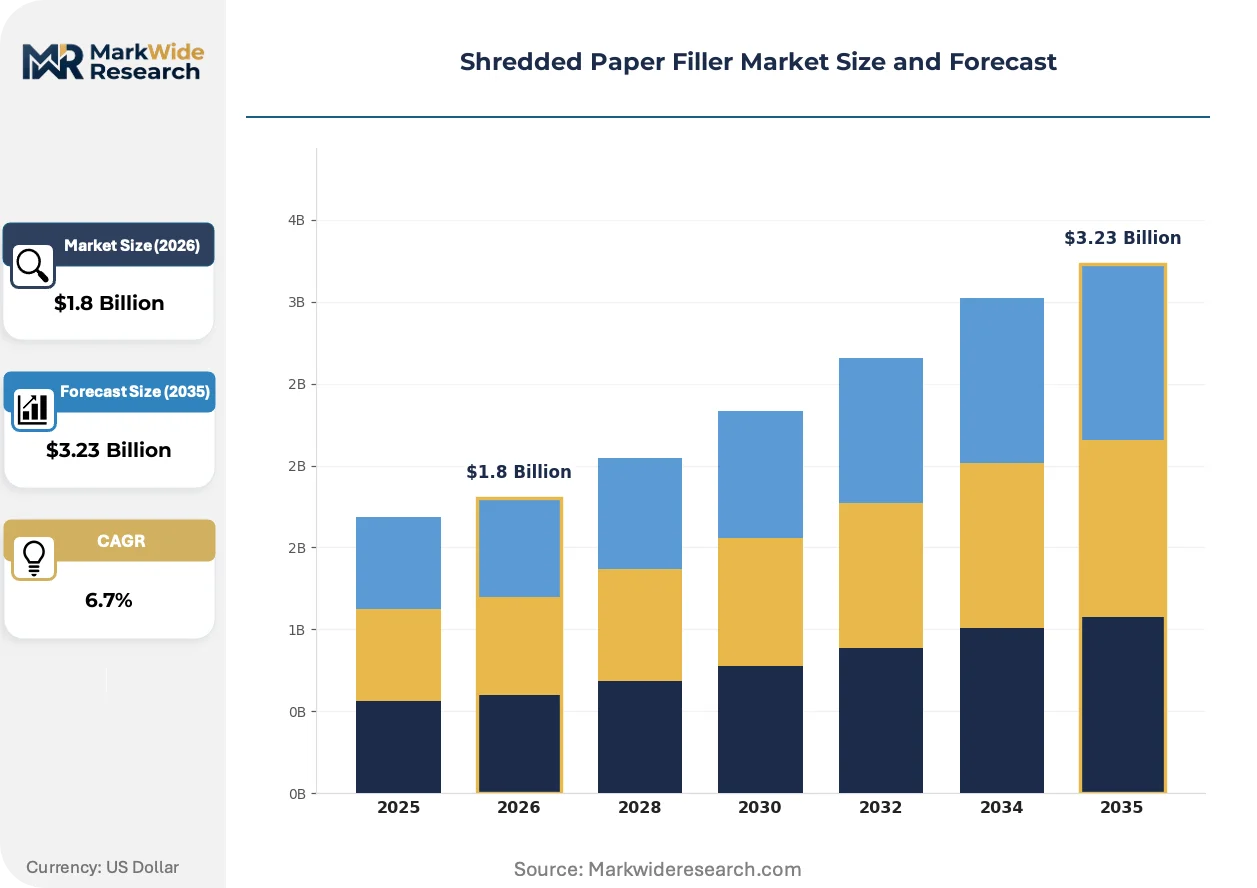
Market Dynamics
E-commerce fulfillment centers are consolidating supplier lists around certified sustainable packaging partners, compressing the vendor base while elevating procurement standards for void-fill materials across North American and European logistics networks.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Mandates for recycled content minimums are pulling converters toward post-consumer fiber grades and accelerating certification investments.
- Automated packing lines:Fulfillment centers deploying high-speed void-fill systems require anti-static, dust-extracted shredded paper that feeds reliably through robotic dispensers.
- Germany:The country's extended producer responsibility scheme imposes strict packaging waste fees, driving brand owners toward biodegradable filler grades that reduce compliance costs.
Market Restraints
- Old corrugated container (OCC) price volatility:Pulp input costs swing with recycling collection rates and export demand, squeezing converter margins unpredictably.
- Midwest US supply concentration:A handful of integrated paper mills controls kraft pulp availability, creating bottleneck risk for independent shredded paper producers.
- Polystyrene foam substitution threat:Lightweight synthetic void-fill retains cost advantage in bulk industrial shipping where presentation requirements are minimal.
Strategic Opportunities
- India:E-commerce penetration in tier-2 cities remains underpenetrated for sustainable packaging, creating first-mover positioning for certified exporters.
- Cosmetics unboxing experience:Premium colored and scented shredded paper variants command margin premiums in direct-to-consumer beauty subscriptions.
- Compostability certification convergence:ASTM D6400 and EN 13432 alignment is opening dual-market access for biodegradable grades in US and EU retail procurement.
Industry Challenges
- FSC chain-of-custody audit complexity:Small converters struggle with documentation rigor required by major retail accounts, extending sales cycles.
- Legacy warehouse management system integration:Automated paper dispensing equipment requires API connectivity that older fulfillment software lacks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Shredded Paper Filler Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Colored Shredded Paper, Brown Shredded Paper, Recycled Shredded Paper, Biodegradable Shredded Paper End User: E-commerce, Retail, Packaging Industry, Arts & Crafts Grade: Premium, Standard, Bulk, Custom Packaging Type: Bags, Boxes, Bales, Rolls |
| Companies Covered | The Packaging Company, Sealed Air Corporation, Ranpak Holdings Corp., Smurfit Kappa Group Plc, Mondi plc, Seaman Paper Company, DS Smith, International Paper Company, EcoEnclose LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Shredded Paper Filler Market Strategic Shifts
Mechanical shredding technology and certification standards are converging to redefine competitive positioning, with automation and compliance now inseparable from commercial viability in void-fill supply chains.
Cross-cut shredding with integrated dust extraction and anti-static treatment is rendering obsolete traditional strip-cut methods that jam automated dispensers. Tier-1 fulfillment centers in the US and Germany are adopting these systems at replacement cycle pace. The technology is compressing the supplier base toward equipment-integrated service providers who control both material and dispensing hardware.
REACH compliance and the EU Green Deal are forcing reformulation of optical brighteners and sizing agents used in decorative shredded paper grades. Chemical suppliers must register alternatives under ECHA timelines. Cosmetic and gift-box segments in France and Germany are absorbing these compliance costs fastest, passing them through as certified-grade premiums.
Subscription box merchants are unbundling void-fill from logistics contracts and sourcing directly from certified converters. This disintermediation is fragmenting procurement volumes previously captured by 3PLs. The pattern is most visible in US coastal metro fulfillment clusters serving direct-to-consumer apparel and beauty brands.
Shredded Paper Filler Market Segmentation
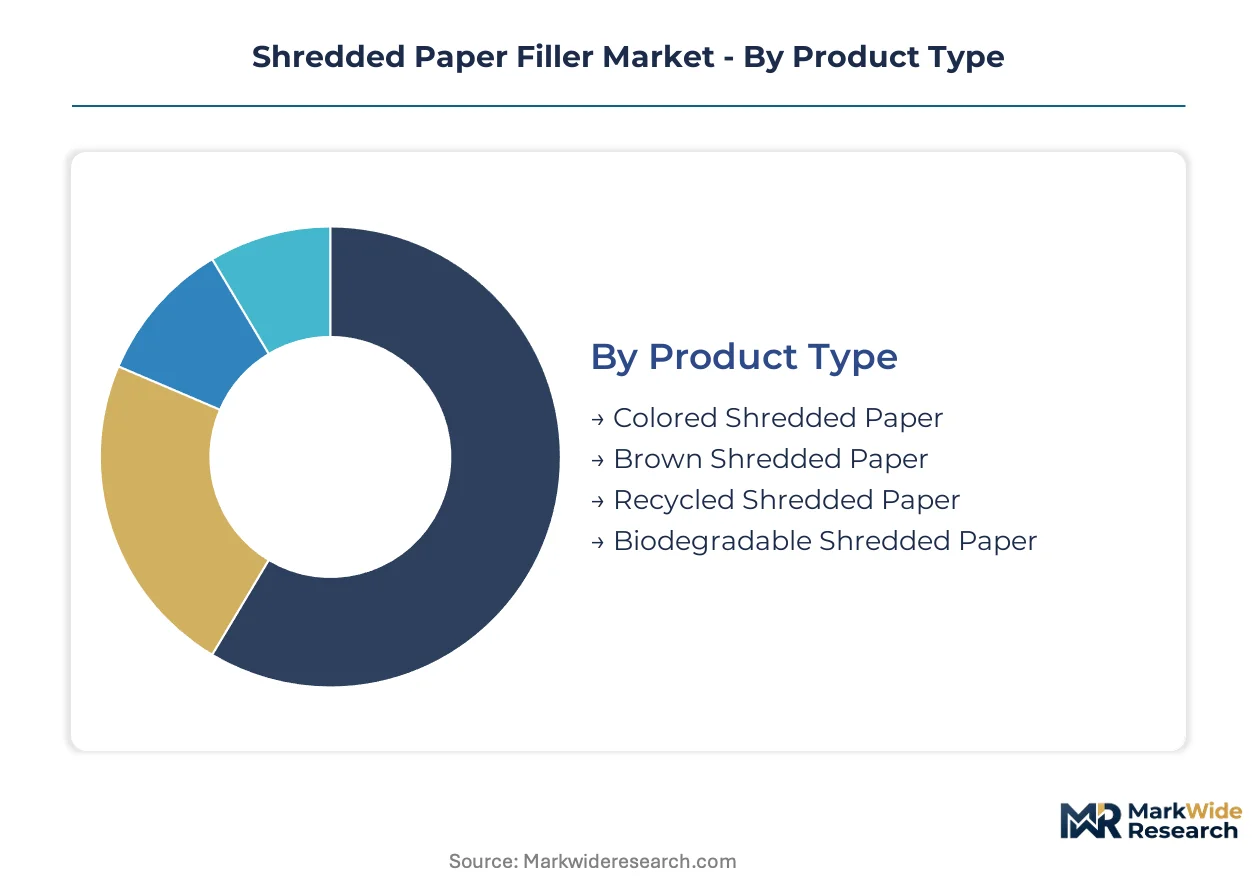
Product differentiation in shredded paper filler hinges on fiber sourcing, visual presentation, and compostability certification. Procurement teams segment suppliers by performance tier and automated handling compatibility rather than commodity pricing alone.
Product Type:
Cost tier stratification separates decorative presentation grades from functional void-fill commodities, with sustainability premiums widening the spread between virgin and certified biodegradable variants.
- Colored Shredded Paper:Dyed kraft or sulfite fiber processed through aqueous pigment systems, typically specified in Pantone-matched shades for cosmetics unboxing experiences. Demand concentrates in French and German direct-to-consumer beauty subscriptions where visual presentation drives social media shareability. REACH-compliant dye formulations now add certification costs that filter smaller converters from premium accounts.
- Recycled Shredded Paper:Post-consumer OCC and newsprint mechanically pulped without deinking, retaining gray-brown hue and variable fiber length. E-commerce fulfillment centers in Germany and the Netherlands specify this grade for volume void-fill where anti-static treatment matters more than aesthetics. EPA recycled content guidelines for federal procurement in the US and EU Packaging and Packaging Waste Regulation minimums are pulling converters toward this tier.
- Brown Shredded Paper:Unbleached virgin kraft with natural lignin content providing structural resilience for heavier product cushioning.
- Biodegradable Shredded Paper:Certified compostable grades meeting ASTM D6400 and EN 13432 protocols for industrial composting facilities.
Recycled shredded paper holds installed capacity. Biodegradable shredded paper is rotating up the share rankings.
End User:
Application-driven segmentation reflects divergent performance requirements across fulfillment velocity, presentation standards, and regulatory exposure.
- E-commerce:High-velocity fulfillment centers requiring dust-extracted, anti-static shredded paper that feeds reliably through Ranpak and comparable automated dispensing systems. Demand clusters in German logistics hubs serving pan-European retail networks where extended producer responsibility fees penalize non-biodegradable void-fill. Robotic packing line integration now filters supplier qualification beyond material specification alone.
- Retail:Brick-and-mortar merchandising applications including gift basket assembly and point-of-sale display cushioning. Demand concentrates in US specialty food and wine retail where FSC chain-of-custody certification functions as a baseline procurement filter.
- Packaging Industry:Corrugated box manufacturers and contract packagers sourcing filler as a component of integrated protective packaging systems.
- Arts & Crafts:Hobbyist and educational market segments prioritizing color variety and small-format packaging over bulk logistics efficiency.
E-commerce commands the volume base. Retail is climbing the fastest as unboxing experience investments spread beyond cosmetics into gourmet food and subscription apparel.
Grade:
Margin structure separates certified premium positioning from undifferentiated bulk commodity supply, with custom specifications capturing project-based pricing power.
- Premium:FSC-certified, dye-matched, and scent-infused shredded paper specified for luxury cosmetics and high-end gift applications. French and German beauty brands absorb compliance premiums for REACH-registered optical brighteners and sizing agents. Visual consistency and batch-to-batch color stability justify pricing spreads that standard grades cannot command.
- Standard:Consistent-cut kraft or recycled fiber meeting basic anti-static and dust-extraction thresholds for automated handling. German retail supply chains specify this tier for mid-market e-commerce where biodegradable certification suffices without decorative upgrades.
- Bulk:Uncertified, variable-width shredded paper sold by weight for industrial void-fill where presentation requirements are minimal.
- Custom:Specification-grade production including proprietary cut widths, branded color matching, and co-packaged dispensing equipment.
Premium grade holds installed capacity. Custom is rotating up the share rankings as direct-to-consumer brands unbundle void-fill from 3PL contracts.
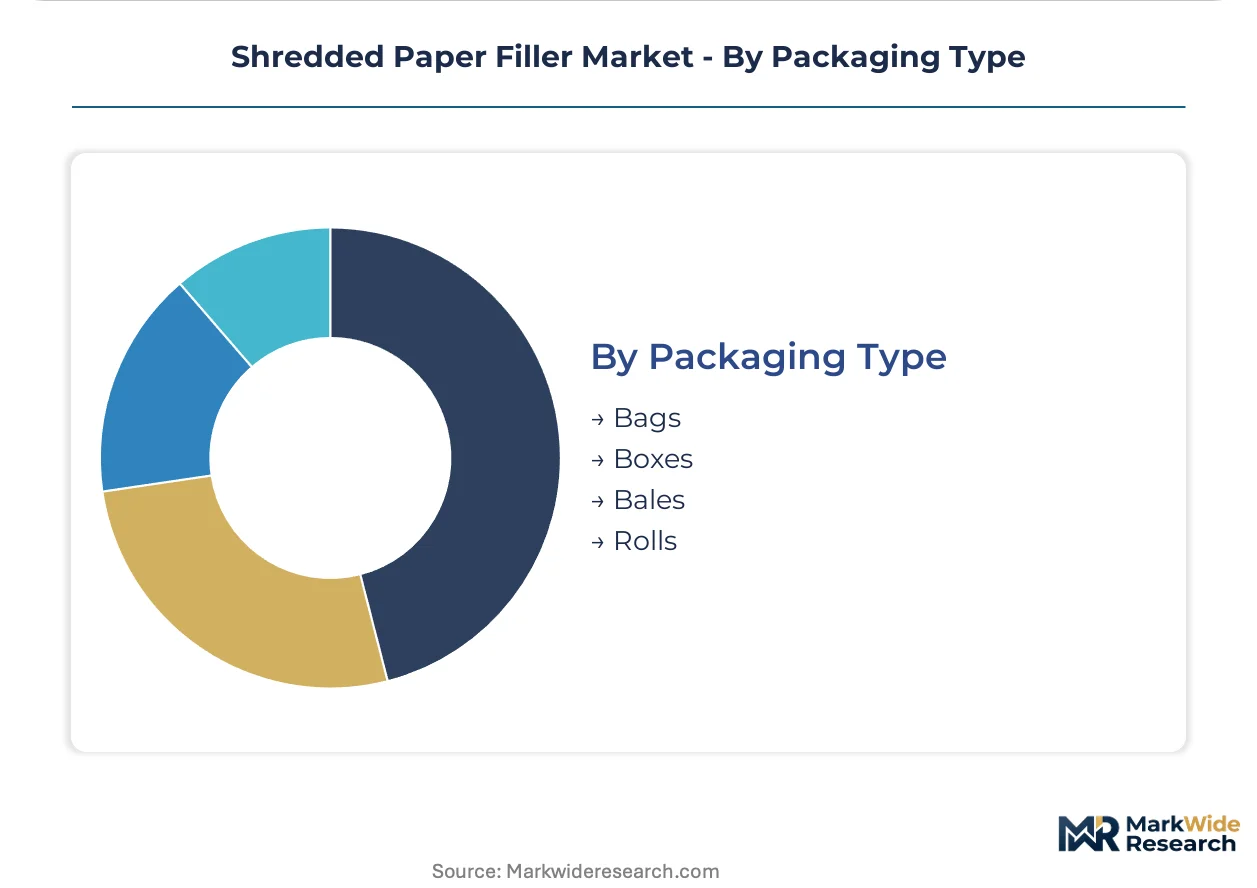
Packaging Type:
Volume and handling efficiency dictate format selection across automated fulfillment, retail replenishment, and artisan-scale consumption patterns.
- Bales:High-density compressed units weighing 500-1000 kg for automated unpacking at major fulfillment centers. German and Dutch logistics hubs specify bale format for direct-to-press feeding into high-speed void-fill systems. Container shipping efficiency and reduced handling labor justify capital investment in bale-breaking equipment.
- Bags:Pre-measured polyethylene or paper sacks ranging from 5 kg retail sizes to 25 kg industrial units. US coastal metro fulfillment clusters serving subscription box merchants favor bagged formats for manual packing stations and mixed-SKU operations where dispensing automation remains uneconomical.
- Boxes:Corrugated containers with dispenser-compatible apertures for mid-volume operations.
- Rolls:Continuous-sheet shredded paper on cores for specialized cushioning applications and custom cutting operations.
Bales hold installed capacity. Bags are rotating up the share rankings as mid-tier fulfillment centers delay automation investments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's container throughput infrastructure underwrites the Netherlands' role as the primary distribution gateway for shredded paper filler entering European e-commerce fulfillment networks.
Germany
Extended producer responsibility fees under the Verpackungsgesetz drive brand owners toward biodegradable filler grades that reduce compliance costs. The EU Packaging and Packaging Waste Regulation mandates recycled content minimums that pull converters toward post-consumer fiber grades. The Rhine-Ruhr logistics corridor concentrates automated fulfillment centers specifying dust-extracted, anti-static shredded paper for robotic dispensing systems.
United States
EPA recycled content guidelines for federal procurement shape product specifications for government-adjacent supply chains. The Inflation Reduction Act's clean manufacturing incentives indirectly favor domestic fiber processing over imported alternatives. Chicago and Dallas-Fort Worth logistics hubs anchor Midwest distribution networks where OCC price volatility squeezes independent converter margins unpredictably.
France
Cosmetics unboxing experience investments spread visual presentation requirements beyond luxury into mid-market beauty subscriptions. REACH compliance forces reformulation of optical brighteners and sizing agents used in decorative grades, adding certification costs that filter smaller converters. The Île-de-France region concentrates direct-to-consumer beauty brands absorbing these premiums for batch-to-batch color stability.
Netherlands
Pan-European retail networks route through Dutch distribution centers where extended producer responsibility schemes impose strict packaging waste tracking. The EU Green Deal pushes converters toward biodegradable grades certified under EN 13432 protocols. Rotterdam's port infrastructure enables just-in-time bale deliveries to automated fulfillment centers serving German and French markets.
India
E-commerce penetration in tier-2 cities remains underpenetrated for sustainable packaging, creating positioning opportunities for certified exporters. The PLI scheme for manufacturing incentives supports domestic paper processing capacity expansion. Mumbai and Bengaluru logistics clusters develop supplier qualification frameworks around FSC chain-of-custody documentation for international retail accounts.
Shredded Paper Filler Market Competitive Environment
On the supply side, the industry is consolidating around equipment-integrated service providers who control both material and dispensing hardware. Tier-1 fulfillment centers in Germany and the United States compress the vendor base while elevating procurement standards. Three strategic archetypes dominate: integrated pulp-to-paper operators sustaining margin control, corrugated-adjacent distributors extending through on-site shredding services, and automated cushioning system providers anchoring e-commerce accounts. Capacity expansion and certification investments function as the dominant competitive moves.
Within the integrated operator tier, Mondi plc and Smurfit Kappa Group Plc exemplify archetypes that leverage captive pulp supply and corrugated network density respectively. Ranpak Holdings Corp. occupies a position representing the equipment-integrated service model. These three entities anchor the competitive structure through their control of upstream fiber access, downstream logistics integration, or automated dispensing technology.
| Leading Market Players |
|---|
| The Packaging Company |
| Sealed Air Corporation |
| Ranpak Holdings Corp. |
| Smurfit Kappa Group Plc |
| Mondi plc |
| Seaman Paper Company |
| DS Smith |
| International Paper Company |
| EcoEnclose LLC |
| Others |
Value Chain & Pricing Dynamics
Midwest US kraft pulp concentration hands pricing leverage to integrated mills serving independent shredded paper converters, compressing margin pools toward equipment-integrated service providers who bundle material with automated dispensing hardware. OCC price volatility transmits directly through converter cost structures, while REACH compliance costs for decorative grades widen spreads between certified and uncertified supply tiers.
Pricing Analysis
Volume-discount tiering structures separate bale-format procurement for German automated fulfillment centers from bagged shipments for US subscription box merchants. Three-tier pricing structure across premium, standard, and economy levels reflects FSC certification status, dye-matched color consistency, and anti-static treatment grades. Cost compression in standard recycled tiers is intensifying because OCC collection rate fluctuations and export demand swings squeeze independent converter margins. E-commerce fulfillment centers demonstrate lowest price sensitivity due to robotic dispensing integration requirements, while bulk industrial shippers remain most price-sensitive as polystyrene foam retains cost advantage.
Supply Chain Analysis
Export-control regimes on pulping technology limit equipment flows to emerging market converters, constraining capacity expansion outside established manufacturing clusters. Supply concentrates in Germany, the Netherlands, and the United States, with fiber sourcing drawing from domestic OCC collection networks and imported kraft pulp. Raw material dependencies rest on old corrugated container availability, optical brightener formulations, and anti-static coating chemicals. Single-source vulnerability runs through Midwest US integrated mills controlling kraft pulp supply. Distribution runs through Rotterdam port infrastructure for European pan-regional fulfillment, with bale-breaking equipment investments filtering supplier qualification at major logistics hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution defense imperatives as polystyrene foam and air cushion systems erode addressable void-fill demand in bulk industrial applications. Polystyrene cost advantages in non-presentation shipping threaten volume tiers.
For Market Incumbents: Insulate margin pools through backward integration into OCC collection networks and captive pulping capacity near Chicago and Dallas-Fort Worth logistics corridors. Anchor e-commerce accounts by bundling Ranpak-compatible dispensing equipment with long-term material supply contracts. Certification investments in ASTM D6400 and EN 13432 alignment create switching costs against foam substitutes penetrating cosmetics and gift-box segments. For New Entrants and Emerging Players: Build out FSC chain-of-custody documentation capabilities to qualify for international retail procurement frameworks developing in Mumbai and Bengaluru logistics clusters. Target tier-2 Indian cities where e-commerce penetration remains underpenetrated for sustainable packaging. Lead with compostability certification as the go-to-market wedge against incumbent commodity suppliers lacking dual-market EN 13432 and ASTM D6400 alignment. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed corrugated distributors extending through on-site shredding services at major logistics hubs. Long-term viability hinges on automation lock-in effects and regulatory tailwinds from extended producer responsibility schemes. Watch compostability certification convergence between US and EU protocols as the inflection signal for biodegradable grade margin expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into OCC Collection | Captive fiber supply insulates margin pools from export demand swings and collection rate volatility. |
| Dual Certification Investment (ASTM D6400/EN 13432) | Alignment opens procurement access to US federal and EU retail accounts simultaneously. |
| Automated Dispensing Equipment Bundling | Ranpak-compatible system integration creates technical switching costs at tier-1 fulfillment centers. |
| On-Site Shredding Service Expansion | Logistics hub proximity reduces transport costs and captures bale-breaking equipment economics. |
| REACH-Compliant Dye Formulation Reformulation | Optical brightener registration maintains cosmetics segment access under ECHA timelines. |
Study Parameters
A spread of perspectives from plant managers at integrated paper mills, procurement leads at German e-commerce fulfillment centers, distribution channel partners serving Dutch logistics hubs, and technical R&D directors at anti-static coating suppliers converged on the working assumptions. Primary interview insights combined with secondary validation from SEC filings of publicly traded packaging companies, customs and trade data on OCC and kraft pulp flows, EU Packaging and Packaging Waste Regulation implementation tracking, and FSC chain-of-custody certification databases. Bottom-up demand modeling across end-use segments triangulated against top-down capacity assessments from pulp-to-paper operators.
Demand-supply-balance framing anchored the analytical framework across the analysis window, with segmentation dimensions spanning product type tiers, end-use velocity requirements, grade certification levels, and packaging format efficiency. CAGRs derived from installed capacity utilization rates, replacement cycle timing for automated dispensing equipment, and regulatory compliance cost pass-through elasticity. Industry-specific forecast inputs incorporated extended producer responsibility fee structures in Germany and the Netherlands, plus e-commerce penetration trajectories in Indian tier-2 cities.
Stress conditions across OCC price volatility bands, REACH registration timeline delays, and automation adoption rate scenarios were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on regulatory enforcement intensity and substitution elasticity between paper and foam void-fill. Material shifts in EU Packaging and Packaging Waste Regulation recycled content mandates or compostability testing protocol harmonization would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
Greyboard Market
Paper & Paperboard Packaging
Plywood Box Market
Paper & Paperboard Packaging
Wax-Coated Paper Market
Paper & Paperboard Packaging
Transfer Paper Market
Paper & Paperboard Packaging
Sublimation Paper Market
Paper & Paperboard Packaging
Cushioned Mailer Market
Paper & Paperboard Packaging
Poly Coated Paperboard Market
Paper & Paperboard Packaging
Paperboard Mailer Market
Paper & Paperboard Packaging
Commercial Paper Bags Market
Paper & Paperboard Packaging
Cellular Paper Cardboard Market
Paper & Paperboard Packaging
Paper Cups Market
Paper & Paperboard Packaging
Fast Food Wrapping Paper Market
Paper & Paperboard Packaging
Japan Paper Packaging Market
Paper & Paperboard Packaging
Machine Glazed Paper Market
Paper & Paperboard Packaging
Paper Cone Cup Market
Paper & Paperboard Packaging
Retail Paper Bags Market