
 China Copper Market | 2026-2036
China Copper Market Size, Share, and Industry Trends Forecast 2026-2036
China Copper Market Insights
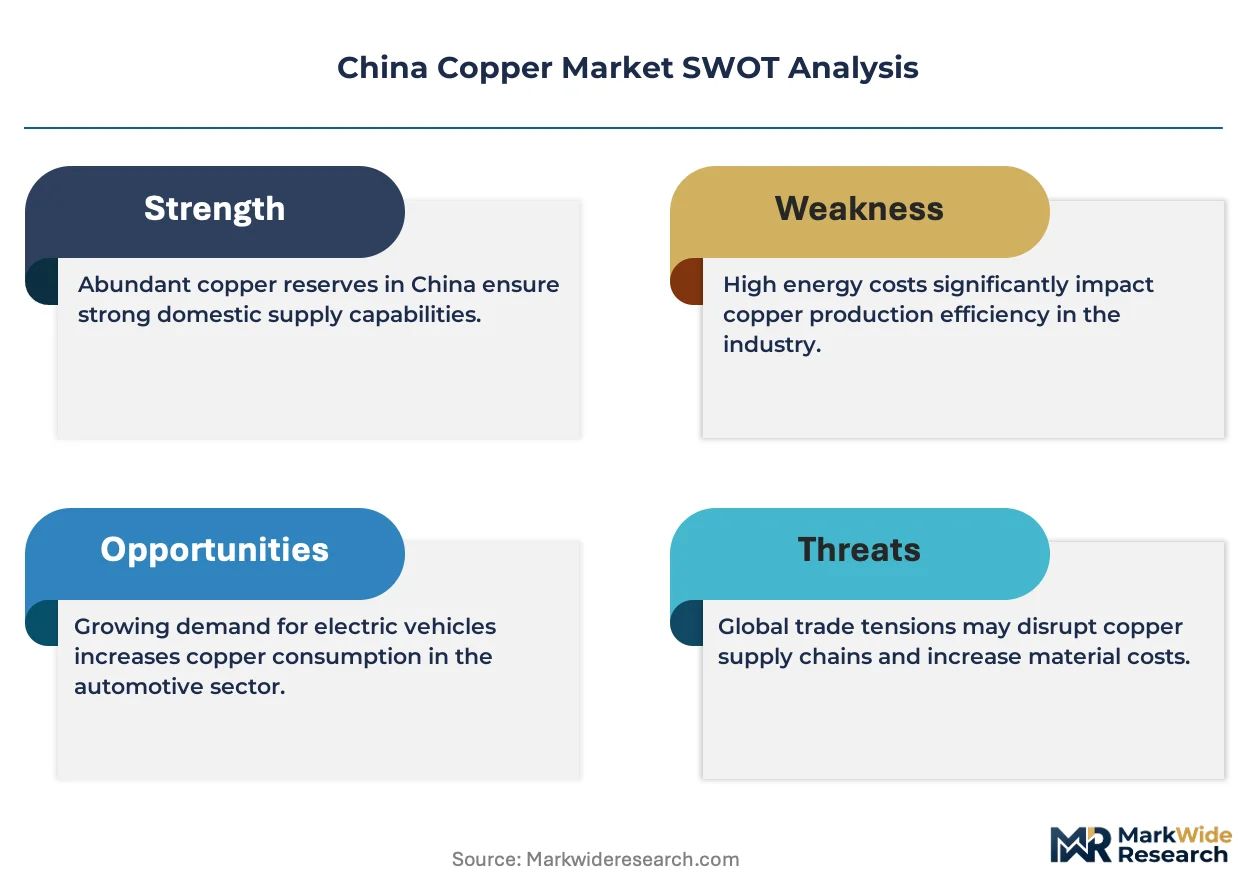
The gap between premium oxygen-free copper and standard cathode-grade material is repositioning procurement strategies across Chinese manufacturing. Jiangxi Copper Company leverages captive mine-to-smelter integration to secure concentrate supply during volatile concentrate markets. Zijin Mining Group anchors its position through overseas resource control in Africa and Central Asia. Ningbo Jintian Copper differentiates via precision alloy development for semiconductor lead frames and high-frequency connectors.
Copper in the China context denotes a base metal with electrical conductivity of 100% IACS in pure annealed form, produced through pyrometallurgical smelting, electrolytic refining, or secondary remelting of scrap, serving as the backbone conductor for power transmission, thermal exchange systems, and electromagnetic applications. Wires and tubes command the largest volume shares, though sheets for EV battery current collectors and semiconductor heat spreaders are capturing faster expansion. Smelting technology faces margin compression from concentrate treatment charges, while recycling and alloying segments attract capital as scrap availability rises and downstream specifications tighten.
MEE emissions standards, GB quality classifications for copper products, and SAMR market supervision frameworks collectively shape production quotas, import licensing, and product certification pathways for domestic and imported material. The central bank's green credit guidance and provincial industrial policies in Jiangsu and Anhui further steer capital toward lower-carbon refining routes. Stakeholders must track how concentrate import dependency interacts with scrap circularity mandates to calibrate long-term feedstock strategies.
Market Dynamics
China's dual carbon goals under MEE oversight are compressing smelter margins while redirecting capital toward scrap-fed refining and precision alloy capacity in Jiangsu and Zhejiang cable manufacturing clusters.
Growth Catalysts
- Grid-scale battery storage buildout:Utility-scale projects in Jiangsu and Anhui are absorbing higher volumes of high-conductivity wire rod for DC busbar and interconnection systems.
- MEE emissions thresholds:Tighter smelter emissions standards are accelerating investments in secondary remelting capacity and closed-loop scrap processing infrastructure.
- Semiconductor heat spreader demand:Precision alloy development for EV battery current collectors and high-frequency connectors is expanding premium oxygen-free copper applications.
Market Restraints
- Concentrate import dependency:Treatment charge volatility in international concentrate markets squeezes pyrometallurgical smelter margins and limits feedstock security.
- Chilean-Peruvian supply concentration:Over half of China's copper concentrate imports originate from two countries, creating geopolitical and logistics exposure.
- Aluminum substitution in HVAC tubing:Cost-driven specification changes in residential air conditioning are displacing copper in heat exchange coils.
Strategic Opportunities
- Scrap circularity mandates:SAMR quality classifications and provincial industrial policies in Anhui are incentivizing integrated smelter-recycler operations with lower carbon intensity.
- EV battery current collector sheet:Rolled copper foil specifications for lithium-ion anode substrates represent underpenetrated demand within domestic battery supply chains.
- High-frequency connector alloys:5G base station and data center buildouts are creating specification premiums for precision-drawn wire with controlled oxygen content.
Industry Challenges
- Smelter technical retrofit timelines:MEE compliance deadlines for SO2 and particulate capture require simultaneous capital deployment across multiple facilities.
- Alloy certification complexity:GB standards for semiconductor-grade material demand extended qualification cycles with downstream electronics manufacturers.
- Scrap feedstock quality variance:Inconsistent grading across domestic collection networks complicates secondary refining yield optimization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Copper Market |
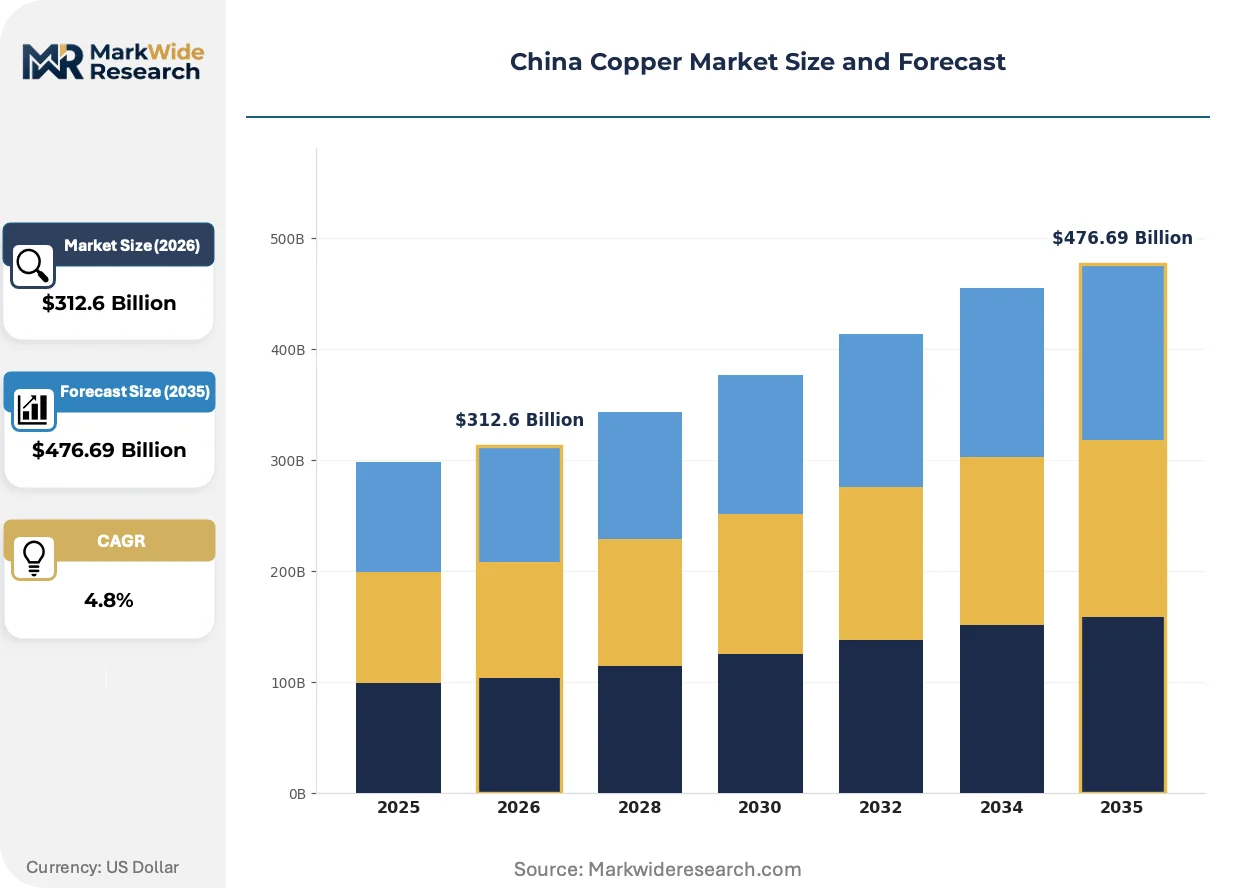
| Market Size in 2026 | $312.6 Billion |
| Market Size in 2035 | $476.69 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Electrical, Construction, Automotive, Electronics Product Type: Wires, Tubes, Sheets, Bars End User: Manufacturers, Contractors, Distributors, Retailers Technology: Smelting, Refining, Recycling, Alloying |
| Companies Covered | Jiangxi Copper Company, Zijin Mining Group, China Nonferrous Mining Corp, Tongling Non-ferrous Metals Group Holding, Jinchuan Group, Ningbo Jintian Copper, Guangdong Jiayuan Technology, Ningbo Boway Alloy Material Company, China Minmetals, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Copper Market Trends and Innovations
Electrification intensity across power transmission and battery manufacturing is reshaping copper product specifications and procurement priorities in Chinese industrial markets.
Continuous casting and rolling technology for oxygen-free copper rod is overtaking traditional batch-based hot rolling in wire rod production. Cable manufacturers in Jiangsu are adopting these lines for 8mm diameter high-conductivity feedstock. The shift is compressing capital requirements per ton of finished rod while tightening diameter tolerances for downstream drawing operations.
MEE oversight of smelter emissions is tightening SO2 discharge limits and accelerating installation of acid plant tail gas scrubbing systems. Pyrometallurgical operators face simultaneous pressure on treatment charges and environmental compliance capital. Facilities in Jiangxi and Anhui are prioritizing flash smelting retrofits over conventional reverberatory furnace upgrades to meet 2025 thresholds.
Long-term offtake contracting is displacing spot concentrate procurement for major smelters. Buyers are securing multi-year concentrate supply agreements directly with overseas miners to hedge treatment charge volatility. This pattern concentrates most visibly among integrated producers with captive mine assets in Africa and Central Asia seeking guaranteed feedstock for domestic refining capacity.
China Copper Market Segmentation
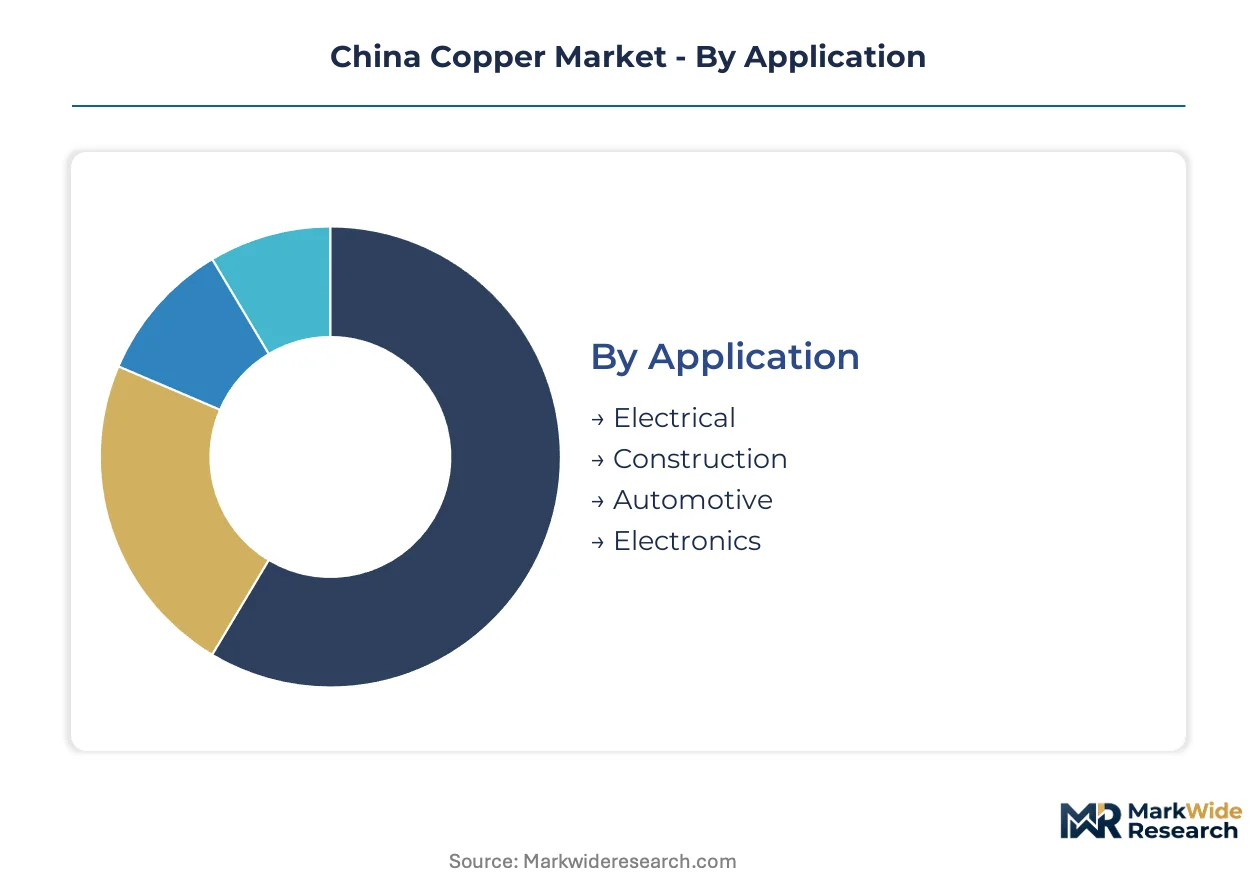
Copper's functional diversity across conductivity, thermal transfer, and mechanical properties creates distinct procurement channels in China. Each segment carries unique specification requirements, pricing mechanisms, and regulatory exposure that shape supplier selection and inventory strategies.
Application:
Standalone infrastructure applications operate independently within fixed installations, while embedded applications integrate into downstream equipment manufacturing with tighter specification control.
- Electrical:High-conductivity wire rod and busbar material for power transmission and distribution networks. Jiangsu and Anhui grid-scale battery storage projects are absorbing elevated volumes of oxygen-free copper for DC interconnection systems as MEE emissions standards tighten smelter feedstock requirements.
- Construction:Plumbing tube, roofing sheet, and architectural cladding serving commercial and residential building stock. Specification changes in HVAC tubing are accelerating aluminum displacement in residential heat exchange coils despite copper's superior thermal performance.
- Automotive:Wiring harness conductor, thermal management tubing, and electric motor winding feedstock. Battery electric vehicle manufacturing in Jiangsu and Zhejiang is expanding demand for high-purity cathode-grade material in charging infrastructure and onboard power electronics.
- Electronics:Rolled copper foil for printed circuit boards, semiconductor lead frames, and connector pins. Precision alloy development for 5G base stations and data center interconnects is commanding specification premiums for controlled oxygen content material.
Volume placements concentrate in Electrical; the faster expansion belongs to Electronics.
Product Type:
Long product formats dominate tonnage movements, while flat and precision shapes capture value-added premiums through downstream processing intensity.
- Wires:Drawn rod and cable conductor spanning power transmission, telecommunications, and magnet wire applications. Continuous casting and rolling technology in Jiangsu cable clusters is displacing traditional batch hot rolling for 8mm diameter high-conductivity feedstock.
- Tubes:Seamless and welded product for plumbing, HVAC, and industrial heat exchange. Cost-driven specification shifts in residential air conditioning are compressing standard tube demand even as commercial refrigeration maintains material loyalty.
- Sheets:Rolled plate and foil for electrical equipment shielding, architectural cladding, and battery current collectors. Lithium-ion anode substrate specifications for EV battery supply chains represent underpenetrated domestic capacity.
- Bars:Extruded and drawn solid sections for electrical busbar, architectural elements, and machined components. Busbar fabrication for data center power distribution is absorbing higher conductivity grades with tight dimensional tolerances.
Primary tonnage flows through Wires; the steepest value expansion trajectory runs through Sheets.
End User:
Direct manufacturing integration creates specification control advantages, while arm's-length distribution channels fragment pricing transparency.
- Manufacturers:Cable producers, component fabricators, and original equipment builders consuming semi-finished copper directly. Jiangsu and Zhejiang manufacturing clusters have expanded drawing and extrusion capacity under provincial industrial policy support.
- Contractors:Electrical and mechanical installation firms procuring material for project-specific deployment. Spot purchasing patterns expose this segment to treatment charge volatility and concentrate import dependency risk.
- Distributors:Wholesale metal service centers holding inventory across multiple grades and formats. GB standards compliance and SAMR quality classifications shape stocking decisions and customer certification requirements.
- Retailers:Hardware and building material outlets serving maintenance, repair, and small-scale construction. Scrap-fed refining investments are improving secondary material availability in this price-sensitive channel.
Manufacturers command the largest volume pull; Distributors are gaining share fastest through inventory consolidation.
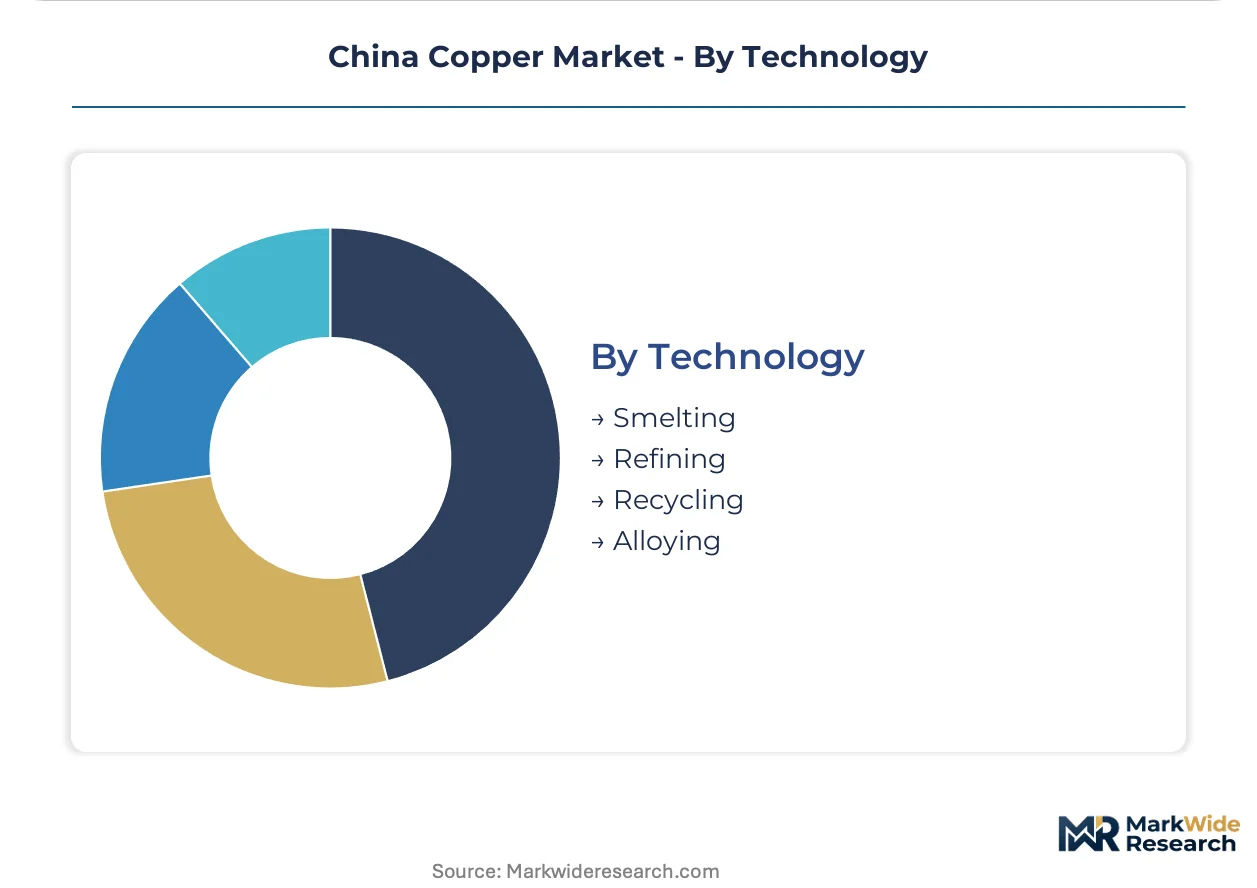
Technology:
Primary extraction routes face margin compression and regulatory pressure, while secondary and precision processing segments attract capital reallocation.
- Smelting:Pyrometallurgical concentrate processing through flash and reverberatory furnace configurations. MEE SO2 discharge limits are forcing simultaneous capital deployment across multiple facilities for acid plant tail gas scrubbing retrofits.
- Refining:Electrolytic purification of blister copper to cathode-grade specifications. Long-term offtake contracting with overseas miners is displacing spot concentrate procurement to hedge treatment charge volatility.
- Recycling:Secondary remelting and refining of scrap feedstock. SAMR circularity mandates and provincial policies in Anhui are incentivizing integrated smelter-recycler operations with lower carbon intensity.
- Alloying:Precision addition of tin, silver, or other elements for semiconductor lead frames and high-frequency connectors. GB certification complexity demands extended qualification cycles with downstream electronics manufacturers.
Smelting retains the dominant volume position; Alloying is climbing the fastest on specification premium capture.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Jiangsu and Zhejiang provinces anchor China's copper demand through cable manufacturing clusters and grid-scale battery storage deployment. Provincial industrial policies in these coastal regions channel capital toward precision alloy capacity and secondary refining infrastructure.
Jiangsu Province
Grid-scale battery storage projects in Jiangsu absorb elevated volumes of high-conductivity wire rod for DC busbar systems. MEE emissions standards tighten smelter feedstock requirements across the province. Continuous casting and rolling technology in Jiangsu cable clusters displaces traditional batch hot rolling for 8mm diameter oxygen-free copper feedstock.
Zhejiang Province
Electric vehicle manufacturing expansion in Zhejiang drives demand for high-purity cathode-grade material in charging infrastructure and onboard power electronics. Provincial industrial policies support expanded drawing and extrusion capacity under green credit guidance from the central bank. Ningbo-based fabricators concentrate precision alloy development for semiconductor lead frames and high-frequency connectors.
Anhui Province
Utility-scale energy storage buildout in Anhui creates procurement pull for oxygen-free copper in DC interconnection systems. SAMR circularity mandates and provincial policies incentivize integrated smelter-recycler operations with lower carbon intensity. Hefei and surrounding industrial zones attract secondary remelting investments to meet tightening MEE SO2 discharge limits.
Jiangxi Province
Captive mine-to-smelter integration in Jiangxi secures concentrate supply during volatile international markets. MEE compliance deadlines for acid plant tail gas scrubbing force simultaneous capital deployment across multiple pyrometallurgical facilities. Flash smelting retrofits in Jiangxi prioritize environmental thresholds over conventional reverberatory furnace upgrades.
Guangdong Province
Electronics manufacturing in Guangdong commands rolled copper foil for printed circuit boards and lithium-ion battery current collectors. GB standards compliance shapes stocking decisions across wholesale metal service centers in the Pearl River Delta. Shenzhen and Dongguan clusters drive specification premiums for precision-drawn wire with controlled oxygen content in 5G base station applications.
China Copper Market Competitive Landscape
Premium-margin players sit above commodity-margin players across feedstock security and alloy specification dimensions. The vendor base concentrates around integrated mining-smelting groups, mid-scale precision alloy specialists, and state-backed resource traders. Three archetypes dominate: captive resource holders with overseas mine assets, scrap-fed refiners with circularity credentials, and precision alloy developers serving semiconductor and EV battery specifications. Competitive moves center on long-term concentrate offtake contracting and flash smelting retrofits to meet MEE compliance deadlines.
Within the integrated mining-smelting tier, Jiangxi Copper Company and Zijin Mining Group occupy positions defined by captive concentrate supply. Among precision alloy specialists, Ningbo Jintian Copper exemplifies the specification-driven segment targeting semiconductor and high-frequency connector applications. These three entities represent distinct competitive vectors: backward resource integration, overseas asset control, and downstream specification capture.
| Leading Market Players |
|---|
| Jiangxi Copper Company |
| Zijin Mining Group |
| China Nonferrous Mining Corp |
| Tongling Non-ferrous Metals Group Holding |
| Jinchuan Group |
| Ningbo Jintian Copper |
| Guangdong Jiayuan Technology |
| Ningbo Boway Alloy Material Company |
| China Minmetals |
| Others |
Pricing and Supply Chain Analysis
Sovereign-backed producers with captive mine assets in Africa and Central Asia anchor supply discipline through long-term offtake contracting, compressing spot market liquidity and reinforcing premium capture for cathode-grade material with guaranteed feedstock security.
Pricing Analysis
Value-based pricing anchored to conductivity yield and dimensional tolerance governs premium oxygen-free copper segments. Three-tier pricing structure across premium, standard, and economy levels separates semiconductor-grade alloy from cable conductor and secondary remelt material. Cost compression in standard cathode-grade tier is intensifying because treatment charge volatility squeezes pyrometallurgical smelter margins. Contractors exhibit highest price sensitivity through spot purchasing patterns, while semiconductor fabricators accept specification premiums for controlled oxygen content.
Supply Chain Analysis
Regional distribution centers in Jiangsu and Zhejiang provinces operate hub-and-spoke patterns feeding cable manufacturing clusters with 8mm diameter wire rod. Chilean and Peruvian concentrate dominates raw material inflows, while Zambian and Indonesian mine output diversifies sourcing. Logistics exposure concentrates in Pacific shipping lanes serving smelter complexes. Distribution runs through integrated producer-direct channels for major manufacturers, with wholesale metal service centers holding inventory for fragmented contractor demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China's copper market functions as a cost-of-compliance story where MEE emissions thresholds and SAMR circularity mandates erect capital barriers that protect incumbent positions and redirect new entrant strategies toward scrap-fed and precision alloy segments.
For Market Incumbents: Hedge concentrate import dependency through backward integration into African and Central Asian mine assets with multi-year offtake contracting. Flash smelting retrofits in Jiangxi and Anhui facilities meet 2025 MEE SO2 discharge deadlines while aluminum substitution in HVAC tubing threatens standard tube demand. Prioritize captive scrap collection networks to secure circularity credentials under provincial industrial policies.
For New Entrants and Emerging Players: SAMR circularity mandates in Anhui open a window for integrated smelter-recycler operations with lower carbon intensity positioning. Rolled copper foil for EV battery current collectors represents the most penetrable white-space target, with lithium-ion anode substrate specifications underpenetrated in domestic supply chains. Pursue qualification partnerships with Jiangsu battery manufacturers to secure first-offtake agreements.
For Investors and Strategic Acquirers: Distressed-cycle entries favor scrap-fed refiners with circularity credentials in Anhui and Jiangsu provinces as MEE compliance capital burdens strain pyrometallurgical operators. Long-term viability hinges on feedstock security and specification premium capture across the analysis window. Monitor treatment charge volatility and Chilean-Peruvian supply disruption risk as inflection indicators for asset repricing.
| Strategic Initiative | Industry Significance |
|---|---|
| Flash Smelting Retrofit | Jiangxi and Anhui facilities meet MEE SO2 discharge limits ahead of 2025 compliance deadlines. |
| Long-term Concentrate Offtake | Zijin Mining Group secures African and Central Asian feedstock against treatment charge volatility. |
| Scrap Circularity Integration | Anhui smelter-recycler operations capture SAMR incentives with lower carbon intensity positioning. |
| Precision Alloy Development | Ningbo Jintian Copper commands specification premiums for semiconductor lead frame applications. |
| Continuous Casting Adoption | Jiangsu cable clusters compress capital requirements per ton of 8mm oxygen-free copper rod. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with smelter operations managers, cable manufacturer procurement leads, scrap recycler technical directors, and MEE compliance officers combined with MEE emissions disclosures, SAMR quality classification databases, and China Customs import statistics. Bottom-up capacity and consumption estimates triangulated against top-down macroeconomic indicators across the analysis window.
Data-stream reconciliation integrated production capacity surveys, treatment charge indices, and downstream demand tracking from grid-scale battery storage project pipelines. Segmentation modeling covered application type, product format, end-user channel, and technology route. CAGRs derived from trend extrapolation with scenario weighting for regulatory compliance timelines and concentrate market volatility. EV battery current collector specifications and 5G base station buildout schedules served as industry-specific demand inputs.
Caveats apply where MEE enforcement intensity, Chilean-Peruvian supply disruptions, or aluminum substitution acceleration could materially shift the outlook. Forecasts reflect documented assumptions around dual carbon goal implementation pacing and scrap collection network development. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Aluminum Slugs Market
Metals
Seamless Stainless Steel Products Market
Metals
Global Welding Powder Market
Metals
Metallurgical Coal Market
Metals
Metallurgical Silicon Market
Metals
High Purity Iron Powder Market
Metals
Lithium Tungstate Market
Metals
Global Flat Carbon Steel Market
Metals
Huntite Market
Metals
Stainless Steel Panels Market
Metals
United States Aluminum Extrusion Market
Metals
GCC Metal Forging Market
Metals
Zinc Dust Market
Metals
Aluminum Sheet Market
Metals
Copper Powder Market
Metals
Ferrochrome Market