
 Canada in-Vitro Diagnostics Market | 2026-2036
Canada in-Vitro Diagnostics Market Size, Share, and Industry Trends Forecast 2026-2036
Canada in-Vitro Diagnostics Market Outlook
Hospital and clinical laboratory demand is recalibrating toward molecular and point-of-care platforms. Abbott Laboratories leverages its broad immunoassay portfolio across Canadian hospital networks. Siemens Healthineers anchors its position through advanced imaging-integrated diagnostics. bioMérieux specializes in microbiology automation for reference laboratories serving provincial health systems.
In-vitro diagnostics encompasses medical tests performed on biological specimens outside the living organism, utilizing reagent-based chemical reactions, immunological assays, or nucleic acid amplification to detect diseases, monitor therapy, or assess patient health status. Reagents and consumables capture the largest revenue share due to recurring purchase cycles tied to instrument installed bases. Molecular diagnostics represents the fastest-expanding application segment as Canadian laboratories adopt PCR and next-generation sequencing platforms for infectious disease and oncology profiling.
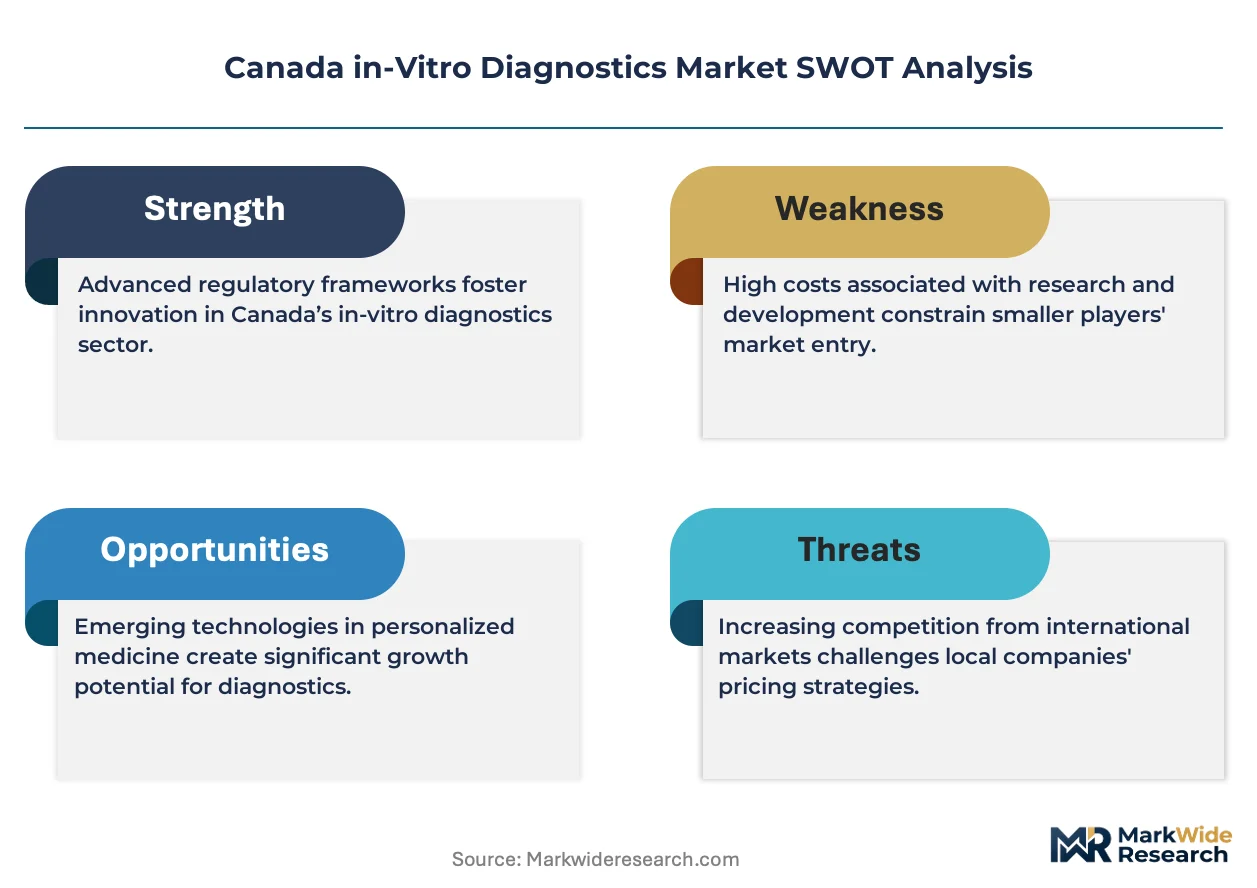
Health Canada and the Canadian Standards Association govern medical device licensing and quality management systems, while provincial health authorities direct procurement and reimbursement frameworks that shape vendor access. The Medical Devices Regulations under the Food and Drugs Act mandate clinical evidence standards that filter market entrants. Stakeholders must monitor evolving provincial laboratory consolidation strategies and Health Canada's transition toward international harmonization of device approval pathways.
Market Dynamics
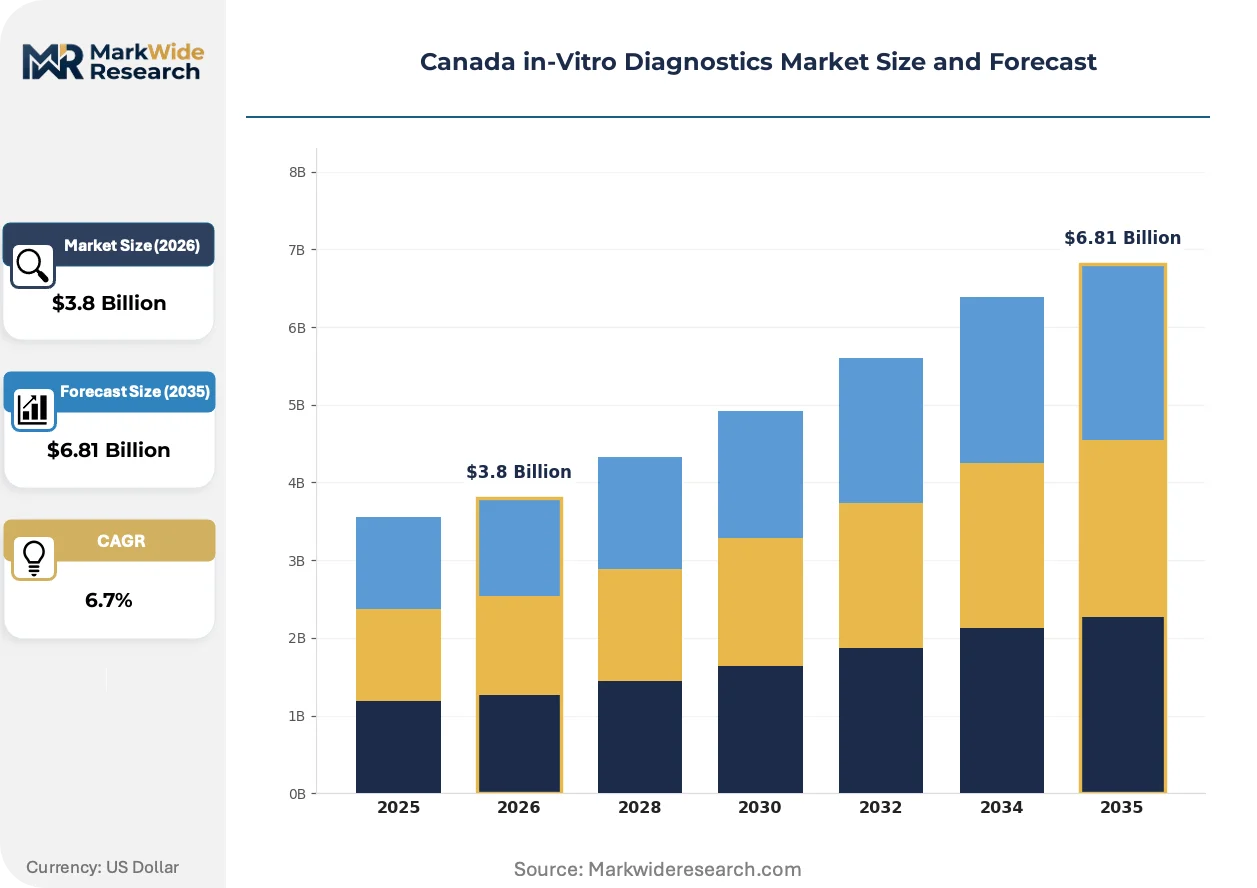
Provincial laboratory consolidation is compressing vendor access windows while Health Canada's Medical Devices Regulations accelerate compliance investments across molecular diagnostics platforms.
Growth Catalysts
- Health Canada licensing harmonization:The regulator's transition toward international approval pathways reduces redundant clinical evidence submissions for IVD manufacturers.
- PCR platform expansion:Hospital laboratories in Ontario's Greater Toronto Area are scaling nucleic acid amplification capacity for infectious disease surveillance.
- Point-of-care decentralization:Community health centers across Alberta and British Columbia are deploying rapid immunoassay instruments outside centralized lab networks.
Market Restraints
- Reagent supply concentration:Critical enzymes and oligonucleotides for molecular diagnostics flow through a narrow base of North American specialty chemical suppliers.
- Clinical evidence thresholds:Health Canada's Medical Devices Regulations mandate prospective studies that extend time-to-market for novel biomarker assays.
- Capital intensity barriers:Automated microbiology systems require seven-figure instrument investments that freeze out mid-tier hospital laboratories.
Strategic Opportunities
- Atlantic Canada penetration gap:Reference laboratory networks remain underdeveloped in Newfoundland and Labrador, creating whitespace for regional hub-and-spoke models.
- Next-generation sequencing convergence:Oncology profiling platforms are integrating with liquid biopsy workflows in Quebec's research hospital networks.
- Provincial procurement centralization:Ontario Health's consolidated purchasing frameworks reward vendors with integrated reagent-instrument service bundles.
Industry Challenges
- Bioinformatics talent scarcity:Molecular diagnostics laboratories face acute shortages of computational biologists capable of interpreting variant calls from NGS pipelines.
- Legacy LIS integration friction:Hospital IT departments struggle to interface new automated platforms with entrenched laboratory information systems from the 1990s.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada in-Vitro Diagnostics Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reagents, Instruments, Software, Accessories Application: Clinical Diagnostics, Blood Testing, Molecular Diagnostics, Pathology End User: Hospitals, Reference Laboratories, Clinical Laboratories, Research Institutions Delivery Mode: Point-of-Care, Centralized, Home-Based, Laboratory-Based |
| Companies Covered | Abbott Laboratories, Siemens Healthineers, F. Hoffmann-La Roche Ltd, Becton, Dickinson and Company, Bio-Rad Laboratories, Danaher, bioMérieux, Thermo Fisher Scientific, QIAGEN, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada in-Vitro Diagnostics Market Strategic Shifts
Canadian IVD infrastructure is pivoting from batch-processing central labs toward distributed, digitally connected testing nodes. This reconfiguration compresses turnaround times while amplifying data interoperability demands.
Multiplexed respiratory panels is modularizing infectious disease testing workflows. Hospital emergency departments in Vancouver and Toronto are adopting syndromic screening platforms that detect twenty-plus pathogens from single nasopharyngeal swabs. This consolidation is collapsing the traditional sequential testing cascade into a single automated run.
Health Canada's transition toward ISO 13485:2016 quality management harmonization is streamlining audit burdens for manufacturers already certified under EU MDR. The regulator's recognition of foreign inspection reports reduces redundant facility audits. Small and mid-size IVD developers with existing European certifications are accelerating Canadian market entry.
Consolidated service contracting is reshaping how hospital networks acquire diagnostics capacity. Ontario Health's provincial laboratory services are unbundling instrument placement from per-test reagent commitments. Quebec's university hospital centers are piloting utilization-based pricing models that shift capital risk onto vendors while retaining operational control.
Canada in-Vitro Diagnostics Market Segmentation
IVD segmentation in Canada reflects divergent compliance pathways and procurement economics. Health Canada's device classification tiers impose distinct clinical evidence burdens across product categories, while provincial purchasing frameworks reward scale in some segments and agility in others.
Product Type:
Health Canada applies escalating scrutiny tiers: Class II reagents require 510(k)-style submissions, Class III instruments demand prospective clinical studies, and software-as-medical-device triggers algorithm validation protocols.
- Reagents:Enzyme and antibody formulations consumed per test cycle dominate recurring revenue streams. Ontario Health's consolidated procurement favors vendors with captive reagent production tied to installed instrument bases.
- Instruments:Automated analyzers for immunoassay and molecular platforms carry seven-figure capital tags. Reference laboratories in Quebec and British Columbia concentrate demand for high-throughput systems that amortize across provincial test volumes.
- Software:Laboratory information system modules and AI-assisted diagnostic algorithms face Health Canada's emerging SaMD framework. Alberta's precision health initiatives are piloting cloud-based variant interpretation tools.
- Accessories:Consumable peripherals including pipette tips, reaction vessels, and calibration materials flow through group purchasing organizations. Atlantic Canada hospital networks rely on distributor-stocked accessories to offset supply chain latency.
Reagents sit at the top of the volume ranking, with software climbing the fastest as laboratories digitize interpretation workflows.
Application:
Application segments map to distinct technology readiness levels and reimbursement certainty. Provincial fee schedules vary coverage density across testing categories.
- Clinical Diagnostics:Routine chemistry and immunoassay panels form the backbone of hospital laboratory output. The Greater Toronto Area diagnostic cluster processes the highest per-capita clinical test volumes nationally.
- Blood Testing:Hematology and coagulation assays serve transfusion services and anticoagulation clinics. Canadian Blood Services' network standardizes instrument platforms across regional blood centers.
- Molecular Diagnostics:Nucleic acid amplification and sequencing platforms are expanding most quickly. Ontario's public health laboratories scaled PCR capacity for respiratory pathogen surveillance, while Quebec's oncology centers integrate liquid biopsy profiling.
- Pathology:Histology and cytology workflows are digitizing through whole-slide imaging systems. University hospital centers in Vancouver and Toronto pilot computational pathology algorithms for cancer subtyping.
Clinical diagnostics commands the largest revenue base, though molecular diagnostics gains share fastest as precision medicine penetrates provincial cancer care programs.
End User:
End-user concentration determines contract structure and service intensity. Consolidated buyers extract pricing leverage while fragmented sites prioritize instrument flexibility.
- Hospitals:Acute care facilities operate 24-hour stat laboratories with diverse test menus. Ontario's hospital laboratory consolidation into regional hubs compresses vendor access to fewer procurement decision-makers.
- Reference Laboratories:Provincial and commercial reference labs handle esoteric testing beyond hospital capabilities. LifeLabs and Dynacare anchor national networks with centralized molecular and microbiology platforms.
- Clinical Laboratories:Community-based labs serve outpatient and long-term care populations. Fee-for-service models in Alberta and British Columbia sustain independent clinical laboratory entrepreneurship.
- Research Institutions:University-affiliated centers and biotechnology incubators pilot preclinical assay development. Montreal and Toronto research hospital networks attract IVD developers seeking clinical validation partnerships.
Hospitals anchor the installed instrument base, with reference laboratories expanding capacity most aggressively through provincial outsourcing contracts.
Delivery Mode:
Delivery configuration shapes regulatory classification and reimbursement mechanics. Decentralized testing triggers point-of-care exemption pathways distinct from centralized laboratory oversight.
- Point-of-Care:Rapid immunoassay and nucleic acid instruments deploy in emergency departments and community health centers. Alberta's rural health zones deploy POCT to reduce specimen transport delays.
- Centralized:High-volume automated platforms in regional reference laboratories achieve lowest per-test costs. Ontario Health's laboratory services consolidation accelerates centralized testing rationalization.
- Home-Based:Self-collection kits for infectious disease and chronic condition monitoring bypass clinical infrastructure. Health Canada's interim order pathways enabled accelerated authorization during public health emergencies.
- Laboratory-Based:Traditional hospital and commercial laboratory workflows remain the default for complex multi-analyte panels. Quality management under ISO 15189 accreditation governs laboratory-based output.
Laboratory-based delivery retains the dominant volume position, while home-based testing expands fastest as digital health infrastructure matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ontario's Greater Toronto Area diagnostic cluster anchors Canadian IVD demand through consolidated hospital laboratory networks and provincial procurement centralization. Health Canada and provincial health authorities shape vendor access through licensing harmonization and outsourcing frameworks.
Ontario
Hospital laboratory consolidation into regional hubs concentrates instrument purchasing decisions among fewer procurement officers. Ontario Health's consolidated purchasing frameworks reward vendors with integrated reagent-instrument service bundles. The Greater Toronto Area processes the highest per-capita clinical test volumes nationally, driving molecular diagnostics platform expansion.
Quebec
University hospital centers pilot next-generation sequencing convergence with liquid biopsy workflows for oncology profiling. The province's public health system directs reference laboratory outsourcing contracts toward centralized molecular and microbiology platforms. Montreal's research hospital networks attract IVD developers seeking clinical validation partnerships for precision medicine applications.
British Columbia
Community health centers deploy rapid immunoassay instruments outside centralized lab networks, accelerating point-of-care decentralization. Provincial health authorities standardize instrument platforms across regional health zones to reduce specimen transport delays. Vancouver hospital emergency departments adopt multiplexed respiratory panels for syndromic pathogen screening.
Alberta
Rural health zones deploy point-of-care testing to offset geographic barriers to centralized laboratory access. Fee-for-service models sustain independent clinical laboratory entrepreneurship serving outpatient populations. The province's precision health initiatives pilot cloud-based variant interpretation tools for molecular diagnostics workflows.
Atlantic Canada
Reference laboratory networks remain underdeveloped in Newfoundland and Labrador, creating whitespace for regional hub-and-spoke distribution models. Hospital networks rely on distributor-stocked consumables to offset supply chain latency for peripheral accessories. Provincial health authorities explore consolidated service contracting to rationalize diagnostic capacity across dispersed populations.
Canada in-Vitro Diagnostics Market Competitive Environment
Consolidated service contracting dominates the current landscape as hospital networks unbundle instrument placement from per-test reagent commitments. The vendor base organizes around three strategic archetypes: diversified multinational conglomerates with captive reagent production, specialized microbiology automation developers, and precision molecular platform innovators. Competitive intensity concentrates on M&A activity for complementary assay portfolios and strategic partnerships for provincial outsourcing contracts.
Within the diversified multinational tier, Abbott Laboratories and Siemens Healthineers exemplify scale-driven positioning through broad immunoassay and imaging-integrated diagnostics portfolios. bioMérieux occupies a specialized position representing microbiology automation developers serving reference laboratories. These three anchors reflect the market's segmentation between generalist hospital network suppliers and targeted provincial health system specialists.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Siemens Healthineers |
| F. Hoffmann-La Roche Ltd |
| Becton, Dickinson and Company |
| Bio-Rad Laboratories |
| Danaher |
| bioMérieux |
| Thermo Fisher Scientific |
| QIAGEN |
| Others |
Value Chain & Pricing Dynamics
Ontario Health's consolidated procurement frameworks for hospital laboratory networks are compressing vendor margins and forcing reagent suppliers toward integrated service bundling that reshapes cost recovery across the value chain.
Pricing Analysis
Enzyme and oligonucleotide input costs pass through directly to molecular diagnostics pricing, with polymerase chain reaction reagents bearing the steepest volatility. Three-tier pricing structure across premium, standard, and economy levels separates Health Canada Class III instruments from Class II reagents and commodity consumables. Price differentiation hinges on ISO 13485 certification tier and captive reagent production scale. Cost compression in the standard tier is intensifying because provincial group purchasing organizations extract volume leverage. Community clinical laboratories exhibit highest price sensitivity; reference laboratories with provincial outsourcing contracts show lowest.
Supply Chain Analysis
Thermostable polymerase and fluorescent probe supply rests on concentrated North American specialty chemical producers, with critical enzymes flowing from United States and German fermentation facilities. Raw material dependencies span synthetic oligonucleotides, recombinant proteins, and optical-grade plastics for reaction vessels. Single-source vulnerability concentrates in Taq polymerase master mix formulations. Distribution runs through Health Canada-authorized medical device distributors with provincial warehousing infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through reagent annuity streams and precision medicine premium tiers, as oncology profiling and infectious disease surveillance deepen per-patient testing intensity.
For Market Incumbents: Acquire liquid biopsy assay portfolios to anchor molecular diagnostics growth in Quebec's university hospital networks. Consolidate regional reference laboratory service contracts before Ontario Health completes its hub-and-spoke restructuring. Defend against point-of-care decentralization by embedding connectivity modules that feed data back to centralized laboratory information systems. For New Entrants and Emerging Players: Cloud-based laboratory information system modules offer the lowest barrier-to-entry pathway for Atlantic Canada hospital networks struggling with legacy IT infrastructure. Target Newfoundland and Labrador's underdeveloped reference laboratory whitespace with hub-and-spoke logistics models. Pursue Health Canada SaMD fast-track authorization for AI-assisted variant interpretation tools. For Investors and Strategic Acquirers: Asymmetric upside sits with precision molecular platform innovators holding ISO 13485:2016 certification and existing EU MDR market access. Five-to-ten year viability favors developers with companion diagnostic partnerships in immuno-oncology. Watch Health Canada's international harmonization progress as inflection indicator for accelerated market entry timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Health Canada Licensing Harmonization | Reduces redundant clinical evidence submissions for manufacturers with EU MDR certification. |
| Reagent-Instrument Service Bundling | Ontario Health's consolidated procurement rewards vendors with captive consumable production. |
| Point-of-Care Connectivity Integration | Emergency departments in Vancouver and Toronto demand bidirectional data flow to laboratory information systems. |
| Next-Generation Sequencing Convergence | Quebec's oncology centers integrate liquid biopsy workflows for precision medicine profiling. |
| Atlantic Canada Hub-and-Spoke Expansion | Newfoundland and Labrador's underdeveloped networks create whitespace for regional service models. |
Study Parameters
Direct dialogue with hospital laboratory directors, Health Canada regulatory affairs specialists, provincial procurement officers, and biomedical engineers grounded the qualitative foundation. Secondary validation drew from Health Canada Medical Devices Regulations filings, Ontario Health consolidated purchasing disclosures, ISO 13485 certification databases, and provincial laboratory service annual reports. Bottom-up instrument placement and reagent consumption estimates triangulated against top-down provincial health expenditure allocations.
Segment-level outputs across product type, application, end user, and delivery mode dimensions were generated through the projection horizon. CAGRs were derived from instrument installed base expansion rates and per-test reagent consumption trajectories. Forecast inputs incorporated Health Canada's transition toward international approval pathway recognition and provincial laboratory consolidation timelines.
The model assumes a particular technology adoption path; alternative pathways for next-generation sequencing platform penetration would alter the outlook. Forecasts reflect assumptions about regulatory harmonization pace and provincial outsourcing contract awards. Health Canada SaMD framework evolution, bioinformatics talent availability, and legacy laboratory information system replacement cycles warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
HDL Cholesterol Kits Market
Diagnostics
Immunoassay Interference Blocker Market
Diagnostics
France in-Vitro Diagnostics Market
Diagnostics
Vibrio Diagnostics Market
Diagnostics
Companion Animal Diagnostic Services Market
Diagnostics
Tissue Transglutaminase Test Market
Diagnostics
Sweden in-Vitro Diagnostics Market
Diagnostics
UAE in Vitro Diagnostics Market
Diagnostics
Total Iron Binding Capacity Reagents Market
Diagnostics
Glucose Tolerance Test Market
Diagnostics
Veterinary Diagnostic Services Market
Diagnostics
Middle East and Africa Syndromic Multiplex Diagnostic Market
Diagnostics
Clostridium Diagnostics Market
Diagnostics
Middle East and Africa Lung Cancer Diagnostics Market
Diagnostics
Global Paper Diagnostics Market
Diagnostics
Europe Autoimmune Disease Diagnostics Market