
 Chile Bariatric Surgery Market | 2026-2036
Chile Bariatric Surgery Market Size, Share, and Industry Trends Forecast 2026-2036
Chile Bariatric Surgery Market Outlook
Leasing arrangements for robotic surgical suites is fragmenting competitive dynamics among Chilean healthcare providers. Medtronic PLC leverages its integrated surgical ecosystem to anchor supply relationships with major hospital networks. Johnson and Johnson sustains broad device portfolios across stapling and energy platforms. Intuitive Surgical Inc dominates the robotic-assisted procedure segment through its da Vinci system placements in elite Santiago clinics.
Bariatric surgery encompasses metabolic and gastrointestinal interventions that reduce stomach volume or alter nutrient absorption to treat morbid obesity, typically performed via laparoscopic ports with insufflation pressures of 12-15 mmHg and specialized stapling devices. Sleeve gastrectomy now leads procedural volume among product types due to its lower complication profile and absence of intestinal rerouting. Robotic surgery represents the fastest-expanding procedure type as capital costs decline and precision metrics improve, while post-operative care captures concentrated margin pools through extended nutritional monitoring and complication management protocols.
Chile's Ministry of Health enforces AUGE/GES guaranteed-access regulations that mandate timely bariatric intervention coverage, directly shaping patient eligibility and provider reimbursement rates. The national pharmaceutical regulator, ISP, imposes device registration and clinical evidence requirements that filter market entrants. Stakeholders must monitor pending adjustments to AUGE benefit schedules and ISP cybersecurity directives for connected surgical platforms as these will determine competitive positioning and capital deployment priorities.
Market Dynamics
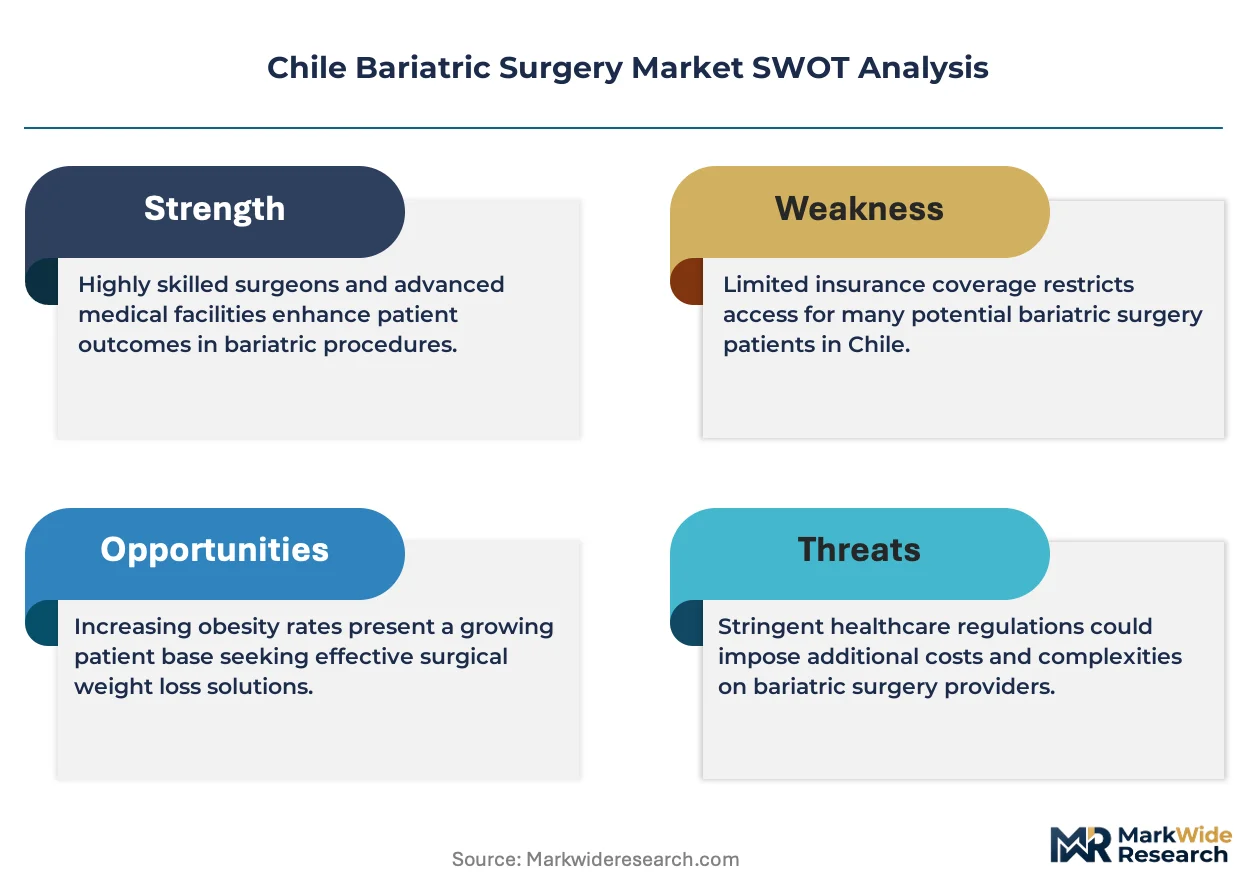
Leasing arrangements for robotic surgical suites are fragmenting competitive dynamics among Chilean healthcare providers, forcing mid-tier hospitals to choose between capital-intensive ownership and third-party platform access.
Growth Catalysts
- AUGE/GES Coverage Mandates:Chile's Ministry of Health guarantees timely reimbursement for morbid obesity interventions, eliminating financial barriers that previously delayed surgical access for eligible patients.
- Metropolitan Provider Clustering:Specialized bariatric centers concentrate near tertiary hospitals in Santiago and Valparaíso, creating referral networks that accelerate patient throughput and procedural standardization.
- Laparoscopic Technique Maturation:Widespread adoption of minimally invasive approaches with standardized insufflation protocols reduces operative risk profiles and shortens hospital stays.
Market Restraints
- Capital Equipment Concentration:Robotic surgical platforms require substantial upfront investment, limiting deployment to elite private hospital chains and excluding public sector facilities from precision surgery capabilities.
- ISP Registration Friction:Chile's national pharmaceutical regulator imposes stringent device registration and clinical evidence requirements that extend market entry timelines for novel surgical technologies.
- Geographic Access Disparity:Surgical capacity concentrates in Santiago and Valparaíso metropolitan zones, leaving northern mining regions and southern agricultural provinces underserved.
Strategic Opportunities
- Robotic-Assisted Procedure Expansion:Declining capital costs and improved precision metrics position robotic platforms to capture share from conventional laparoscopic approaches in high-volume centers.
- Post-Operative Care Unbundling:Extended nutritional monitoring and complication management protocols create concentrated margin pools separate from surgical procedure revenue.
- Regional City Penetration:Concepción and La Serena present underdeveloped demand for metabolic surgery as obesity prevalence rises outside metropolitan cores.
Industry Challenges
- Specialized Surgical Talent Scarcity:Fellowship-trained bariatric surgeons remain concentrated in Santiago, constraining procedure volume growth in provincial facilities attempting service expansion.
- Connected Platform Cybersecurity Compliance:Pending ISP directives for networked surgical devices will require hardware and software upgrades across installed robotic system bases.
- Legacy Equipment Integration Complexity:Hybrid operating environments combining conventional laparoscopic towers with robotic platforms create workflow friction and staff training burdens.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chile Bariatric Surgery Market |
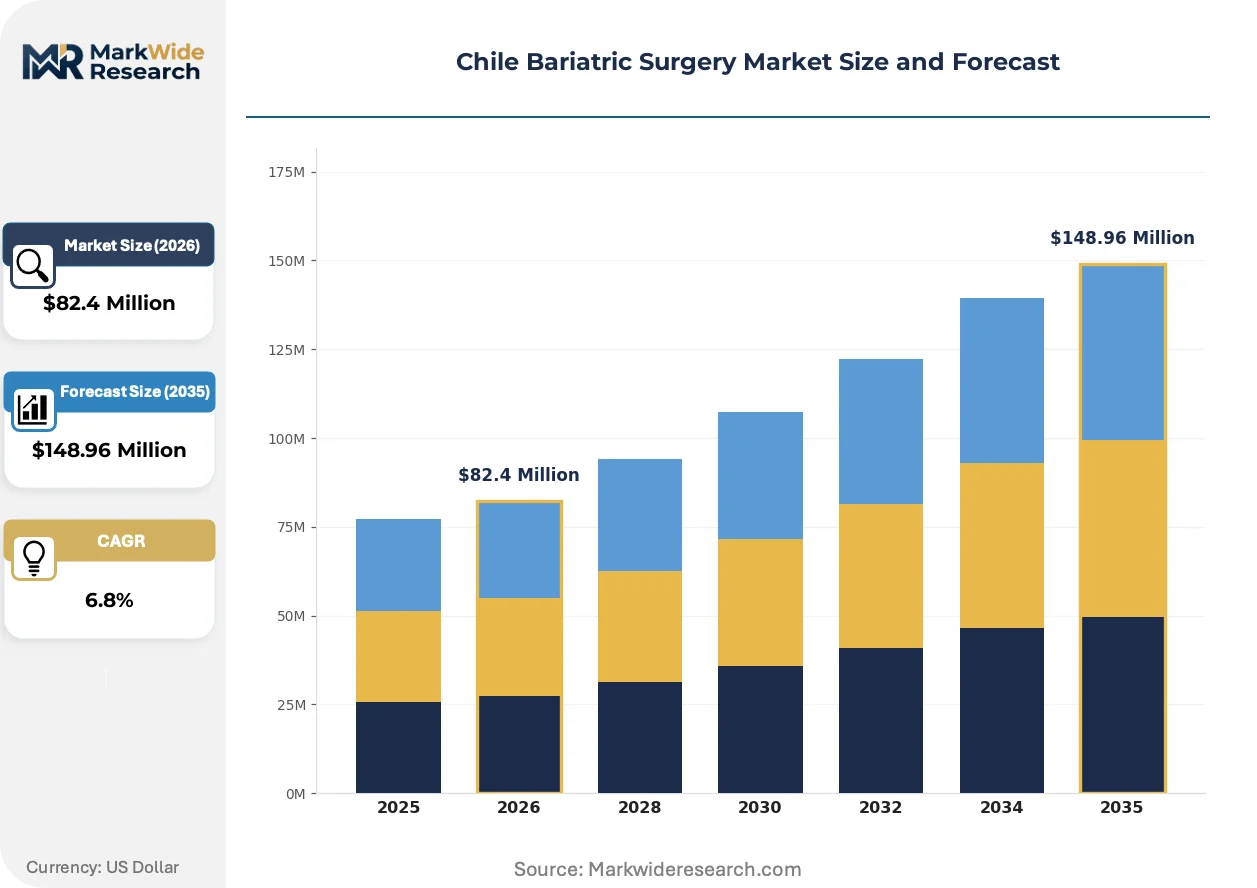
| Market Size in 2026 | $82.4 Million |
| Market Size in 2035 | $148.96 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gastric Bypass, Sleeve Gastrectomy, Adjustable Gastric Band, Biliopancreatic Diversion End User: Hospitals, Surgical Centers, Clinics, Patient Homes Procedure Type: Laparoscopic Surgery, Open Surgery, Robotic Surgery, Endoscopic Surgery Service Type: Pre-operative Consultation, Surgical Procedure, Post-operative Care, Nutritional Support |
| Companies Covered | Medtronic PLC, Johnson and Johnson, Olympus Corporation, Apollo Endosurgery Inc, B. Braun Melsungen AG, Intuitive Surgical Inc, Conmed Corporation, AbbVie Inc, Cook Medical, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chile Bariatric Surgery Market Strategic Shifts
Technological substitution in surgical instrumentation is compressing procedure times while regulatory pressure on connected medical devices is elevating compliance costs. These forces are reshaping capital deployment priorities across Chilean healthcare networks.
Single-use powered stapling devices with integrated tissue sensing are rendering obsolete reusable mechanical staplers in high-volume bariatric centers. Santiago's elite private clinics have adopted these platforms for sleeve gastrectomy procedures, reducing leak rates and operative variability. The shift is compressing margins for conventional instrument suppliers while locking hospitals into proprietary cartridge ecosystems.
Chile's ISP is advancing cybersecurity registration requirements for networked surgical platforms that transmit patient data or receive software updates. The regulatory trajectory mirrors EU MDR and FDA guidance on connected device integrity, forcing manufacturers to revalidate platform architectures. Robotic-assisted surgery vendors face the steepest compliance burden given their reliance on cloud-based analytics and remote system monitoring.
Patients are demanding bundled care pathways that integrate surgical intervention with multi-year nutritional and psychological support. This behavioral shift pressures standalone surgical centers to partner with multidisciplinary metabolic clinics or lose referrals to integrated hospital networks. The transformation is most visible in Santiago's competitive private insurance market, where payers increasingly preference comprehensive obesity management contracts over discrete procedure reimbursement.
Chile Bariatric Surgery Market Segmentation
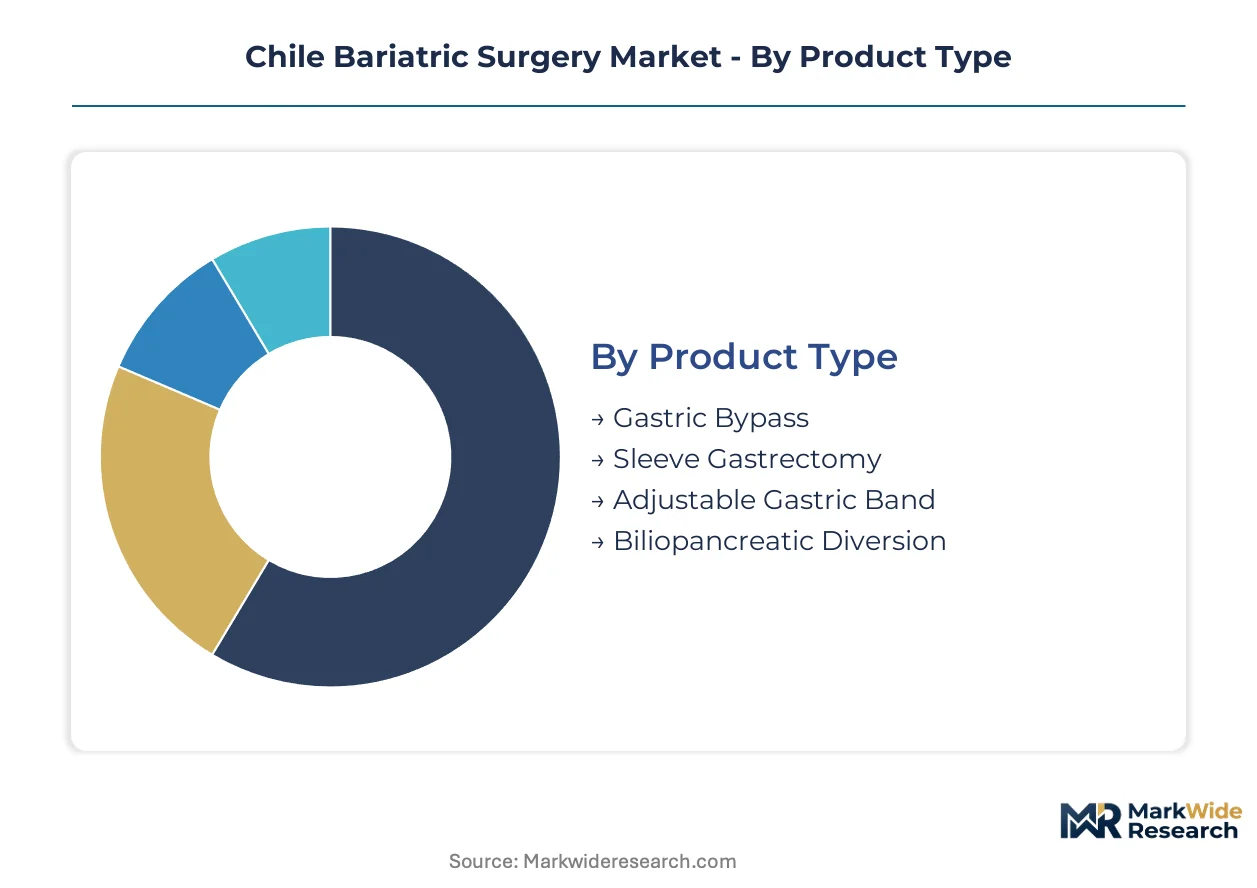
Chile's bariatric surgery market segments along four functional dimensions that shape procurement patterns and capital allocation. Procedure type and product type classifications determine reimbursement rates under AUGE/GES protocols, while end user and service type distinctions reveal where margin pools concentrate across the care continuum.
Product Type:
Mature laparoscopic approaches anchor procedural volume while emerging techniques reshape surgeon training priorities and device procurement.
- Sleeve Gastrectomy:This procedure removes approximately 80% of the stomach along the greater curvature, creating a tubular gastric reservoir. Santiago's tertiary hospitals concentrate demand here due to lower leak rates and reduced nutritional complication profiles compared to intestinal bypass procedures. The absence of foreign body implantation eliminates long-term device surveillance costs.
- Gastric Bypass:Roux-en-Y reconstruction creates a small gastric pouch with jejunal limb anastomosis, delivering superior long-term weight loss through malabsorptive and restrictive mechanisms. Valparaíso metropolitan clinics favor this approach for patients with severe metabolic comorbidities given its documented remission rates for type 2 diabetes.
- Adjustable Gastric Band:Silicone prosthetic devices encircle the proximal stomach with subcutaneous port access for saline adjustment. This segment has contracted sharply as reoperation rates and patient dissatisfaction eroded clinical acceptance.
- Biliopancreatic Diversion:Extensive small bowel bypass with duodenal switch modification produces the most aggressive malabsorptive effect. This approach serves a narrow super-obese patient subset in specialized Santiago centers equipped for intensive metabolic monitoring.
Sleeve gastrectomy handles the majority of throughput; robotic-assisted sleeve procedures are expanding most quickly on share.
End User:
Facility type determines capital equipment access, surgeon credentialing requirements, and AUGE/GES reimbursement pathway eligibility.
- Hospitals:Tertiary institutions with 24-hour anesthesia coverage and intensive care capabilities manage high-risk patients and complex revisional procedures. Santiago's public hospital networks depend on AUGE-mandated coverage to serve insured populations.
- Surgical Centers:Ambulatory facilities with streamlined preoperative protocols target low-BMI patients without significant cardiopulmonary comorbidities. These centers concentrate in affluent Santiago suburbs where private insurance penetration supports cash-pay models.
- Clinics:Office-based practices provide initial consultation, medical weight management, and long-term follow-up. Concepción and La Serena clinics are expanding metabolic surgery referral networks as provincial demand rises.
- Patient Homes:Remote monitoring platforms and telehealth consultations support postoperative dietary adherence and complication screening. ISP cybersecurity requirements for connected devices are elevating compliance costs for home-based service providers.
Hospitals retain the dominant patient share; surgical centers are climbing the fastest as private insurers preference outpatient settings.
Procedure Type:
Technology intensity stratifies across this category, with capital requirements and training demands determining facility eligibility.
- Laparoscopic Surgery:Multiport or single-incision techniques with 12-15 mmHg pneumoperitoneum insufflation dominate Chilean procedural volume. Standardized trocar placement and stapling protocols enable efficient throughput in high-volume Santiago centers.
- Robotic Surgery:Da Vinci system platforms provide wristed instrumentation and three-dimensional visualization for precise suturing in confined spaces. Leasing arrangements are fragmenting competitive dynamics among private hospital chains seeking precision surgery capabilities without capital ownership burdens.
- Open Surgery:Midline laparotomy approaches persist for revisional cases with extensive adhesions or super-obese patients exceeding standard laparoscopic equipment limits. This segment concentrates in academic medical centers with fellowship-trained surgeons.
- Endoscopic Surgery:Incisionless techniques including gastric plication and intragastric balloon placement serve patients seeking reversible, lower-risk interventions. ISP registration friction for novel endoluminal devices constrains market entry timelines.
Laparoscopic surgery commands the volume base; robotic platforms are gaining share fastest as capital costs decline and precision metrics improve.
Service Type:
Margin distribution across the care continuum reveals where unbundling creates specialized revenue opportunities.
- Surgical Procedure:Operative intervention with anesthesia, instrumentation, and facility fees captures the largest absolute revenue per episode. Bundled payment pressures from private insurers are compressing standalone procedure margins.
- Post-operative Care:Extended monitoring for anastomotic leaks, nutritional deficiencies, and wound complications generates concentrated margin pools separate from index admission revenue. Santiago's elite private clinics have unbundled these services into multi-year contracts.
- Pre-operative Consultation:Multidisciplinary evaluation including psychological screening, nutritional assessment, and cardiopulmonary risk stratification determines AUGE eligibility. These services face downward reimbursement pressure as administrative overhead.
- Nutritional Support:Long-term micronutrient supplementation, dietary counseling, and metabolic monitoring prevent deficiency complications. Patient demand for bundled care pathways is elevating the strategic importance of this segment.
Surgical procedure generates the dominant revenue share; post-operative care is expanding most quickly as payers preference comprehensive obesity management contracts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Metropolitan Santiago commands pricing premiums 40% above Concepción rates for identical robotic-assisted procedures, while La Serena surgical centers struggle to match even public hospital reimbursement benchmarks. This geographic asymmetry concentrates specialist talent and capital equipment in Chile's central corridor.
Santiago Metropolitan Region
Elite private hospital chains cluster in Las Condes and Providencia, driving demand for da Vinci system placements and single-use powered stapling platforms. AUGE/GES mandates guarantee coverage for morbid obesity interventions, expanding insured patient access. Tertiary hospitals near Universidad de Chile medical campus anchor the country's densest concentration of fellowship-trained bariatric surgeons.
Valparaíso Region
Viña del Mar and Valparaíso metropolitan clinics favor gastric bypass approaches for severe metabolic comorbidity cases. ISP registration requirements for novel surgical devices filter market entry timelines for endoluminal platforms. Specialized bariatric centers concentrate near Hospital Carlos Van Buren, creating referral networks that accelerate patient throughput.
Biobío Region
Concepción's underdeveloped metabolic surgery infrastructure leaves rising provincial obesity prevalence unaddressed. The national pharmaceutical regulator's cybersecurity directives for connected devices elevate compliance costs for remote monitoring platforms. Concepción clinics are expanding referral partnerships with Santiago tertiary hospitals to capture spillover demand.
Coquimbo Region
La Serena presents untapped demand as mining sector employees seek surgical obesity interventions closer to northern work sites. AUGE benefit schedules determine reimbursement rates that lag metropolitan benchmarks by 25-30%. Limited laparoscopic tower availability constrains procedure volume growth in regional public hospitals.
Araucanía Region
Temuco serves southern agricultural provinces where obesity prevalence rises among sedentary rural populations. ISP clinical evidence requirements for device registration extend market entry timelines for novel stapling technologies. Public hospital networks depend on AUGE-mandated coverage to serve Mapuche communities with limited private insurance penetration.
Chile Bariatric Surgery Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in the supply chain. The vendor base concentrates around three strategic layers: integrated surgical ecosystem providers, precision robotics manufacturers, and disposable instrumentation specialists. Consolidation pressures favor players with bundled device portfolios over single-product suppliers. Dominant competitive moves include leasing arrangement expansion for capital-intensive robotic platforms and backward integration into proprietary cartridge ecosystems.
Among integrated surgical ecosystem providers, Medtronic PLC and Johnson and Johnson occupy positions that span stapling, energy, and monitoring platforms. Intuitive Surgical Inc exemplifies the precision robotics archetype through its da Vinci system presence in elite Santiago clinics. Olympus Corporation represents the visualization and endoluminal device specialist tier. These three anchors illustrate how supply relationships fragment between capital equipment owners and disposable component suppliers.
| Leading Market Players |
|---|
| Medtronic PLC |
| Johnson and Johnson |
| Olympus Corporation |
| Apollo Endosurgery Inc |
| B. Braun Melsungen AG |
| Intuitive Surgical Inc |
| Conmed Corporation |
| AbbVie Inc |
| Cook Medical |
| Others |
Value Chain & Pricing Dynamics
US-based precision instrumentation manufacturers anchor the upstream supply base for Chilean bariatric centers, concentrating margin capture in robotic platform leasing arrangements and disposable cartridge ecosystems downstream. Santiago's elite private hospitals absorb premium pricing for configured-to-order surgical suites while regional facilities face standard-equipment cost compression.
Pricing Analysis
Configured-to-order robotic surgical suites command substantial premiums over standard laparoscopic tower configurations in Santiago metropolitan facilities. Pricing stratifies across premium, standard, and economy tiers based on equipment generation and service bundling intensity. Cost compression in standard laparoscopic instrumentation is intensifying as single-use powered stapling platforms displace reusable mechanical devices. Public hospital networks exhibit highest price sensitivity due to AUGE reimbursement rate constraints, while cash-pay surgical centers in affluent suburbs absorb premium positioning.
Supply Chain Analysis
Contract manufacturing for surgical stapling and energy platforms concentrates with US and Irish medical device CMs holding FDA-registered facilities. Supply draws from precision-machined components sourced from Germany, polymer feedstocks from Belgium, and electronic control systems from Taiwan. Single-source vulnerability persists for robotic console optical assemblies and proprietary instrument cartridges. Distribution runs through exclusive hospital system partnerships rather than open medical device distribution channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Chile's bariatric surgery market is positioned for cyclical recovery as AUGE/GES reimbursement protocols stabilize post-pandemic surgical backlogs and metropolitan capacity expansion resumes.
For Market Incumbents: Insulate installed base relationships by embedding proprietary cartridge ecosystems and securing multi-year leasing extensions ahead of ISP cybersecurity compliance deadlines. Backward integration into surgical stapling manufacturing reduces exposure to supply disruption from Irish contract manufacturers. Prioritize certification investment for cloud-connected robotic platforms to preempt regulatory friction. For New Entrants and Emerging Players: Pursue white-space opportunities in Concepción and La Serena metropolitan zones where surgical capacity lags rising obesity prevalence. Target ambulatory surgical centers with streamlined laparoscopic tower configurations that bypass capital-intensive robotic platform competition. Deploy direct clinical specialist teams rather than distributor-dependent models to accelerate hospital credentialing. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed surgical center chains in Santiago's suburban corridor seeking platform consolidation. Long-term viability centers on post-operative care unbundling and multi-year metabolic management contracts rather than discrete procedure revenue. Watch ISP cybersecurity directive implementation timelines as inflection indicator for compliance cost burdens and competitive shakeout.| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Secures AUGE-eligible referral networks and robotic platform placement commitments in Santiago tertiary centers. |
| ISP Cybersecurity Compliance Investment | Preempts registration delays for cloud-connected surgical platforms under pending national pharmaceutical regulator directives. |
| Post-Operative Care Unbundling | Captures concentrated margin pools through multi-year nutritional monitoring contracts separate from surgical procedure revenue. |
| Regional City Expansion | Addresses underserved demand in Concepción and La Serena as provincial obesity prevalence rises. |
| Disposable Cartridge Ecosystem Lock-In | Creates recurring revenue streams and raises switching costs for competitor platform displacement. |
Study Parameters
Desk research of ISP registration databases, AUGE/GES benefit schedules, and hospital procurement records preceded structured interviews with bariatric surgeons, biomedical engineering directors, GPO contracts managers, and private insurance medical directors. Primary fieldwork across Santiago, Valparaíso, and Concepción facilities was cross-validated against secondary trade data and regulatory filings. Bottom-up procedure volume estimates and top-down market sizing were triangulated to reconcile demand signals.
Assumptions around AUGE reimbursement stability, ISP cybersecurity directive implementation pace, and robotic platform cost decline curves were held fixed across the modeling period while obesity prevalence trajectories and private insurance penetration rates were stress-tested. Segmentation dimensions included procedure type, product type, end-user facility class, and service type. CAGRs were derived from logistic diffusion curves fitted to historical adoption patterns and metropolitan capacity expansion timelines.
Macroeconomic conditions sit as an overlay; deviation in Chilean peso exchange rates, mining sector employment levels, or public health budget allocations would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory continuity and technology substitution rates. Quarterly review of ISP directive publication schedules and AUGE benefit schedule revision announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bariatric Surgery
Bariatric Transport Wheelchairs Market
Bariatric Surgery
Bariatric Medical Chairs Market
Bariatric Surgery
India Bariatric Surgery Market
Bariatric Surgery
Bariatric Rollator Walkers Market
Bariatric Surgery
Spain Bariatric Surgery Market
Bariatric Surgery
Italy Bariatric Surgery Market
Bariatric Surgery
France Bariatric Surgery Market
Bariatric Surgery
Global Bariatric Walking Aids Market
Bariatric Surgery
South Africa Bariatric Surgery Market
Bariatric Surgery
Australia Bariatric Surgery Market
Bariatric Surgery
UAE Bariatric Surgery Market
Bariatric Surgery
Bariatric Patient Room Market
Bariatric Surgery
Sweden Bariatric Surgery Market
Bariatric Surgery
United States Bariatric Surgery Market
Bariatric Surgery
India Bariatric Surgery Devices Market
Bariatric Surgery
Bariatric Surgery Devices Market