
 Bariatric Surgery Devices Market | 2026-2036
Bariatric Surgery Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Bariatric Surgery Devices Market Analysis
The hospital procurement channel for bariatric surgery devices is narrowing as integrated delivery networks consolidate vendor lists around fewer full-line suppliers. Johnson & Johnson leverages its broad endomechanical portfolio to sustain preferred vendor status across multiple IDN frameworks. Medtronic anchors its position through deep entrenchment in energy-based vessel sealing systems used in sleeve gastrectomy. Intuitive Surgical competes by extending robotic platform placements into mid-tier hospitals previously served by pure laparoscopic approaches.
Bariatric surgery devices encompass specialized instruments, stapling systems, gastric bands, and energy platforms designed to alter gastrointestinal anatomy for weight reduction, typically constructed from implant-grade stainless steel, titanium, or silicone polymers and sterilized for single or limited reuse. Sleeve gastrectomy instruments command the largest procedure volume among product type segments, while robotic surgery technology captures the fastest expansion as capital costs amortize across higher surgical throughput. Laparoscopic surgery maintains mature, high-volume economics in emerging hospital systems where robotic infrastructure remains capital-constrained.
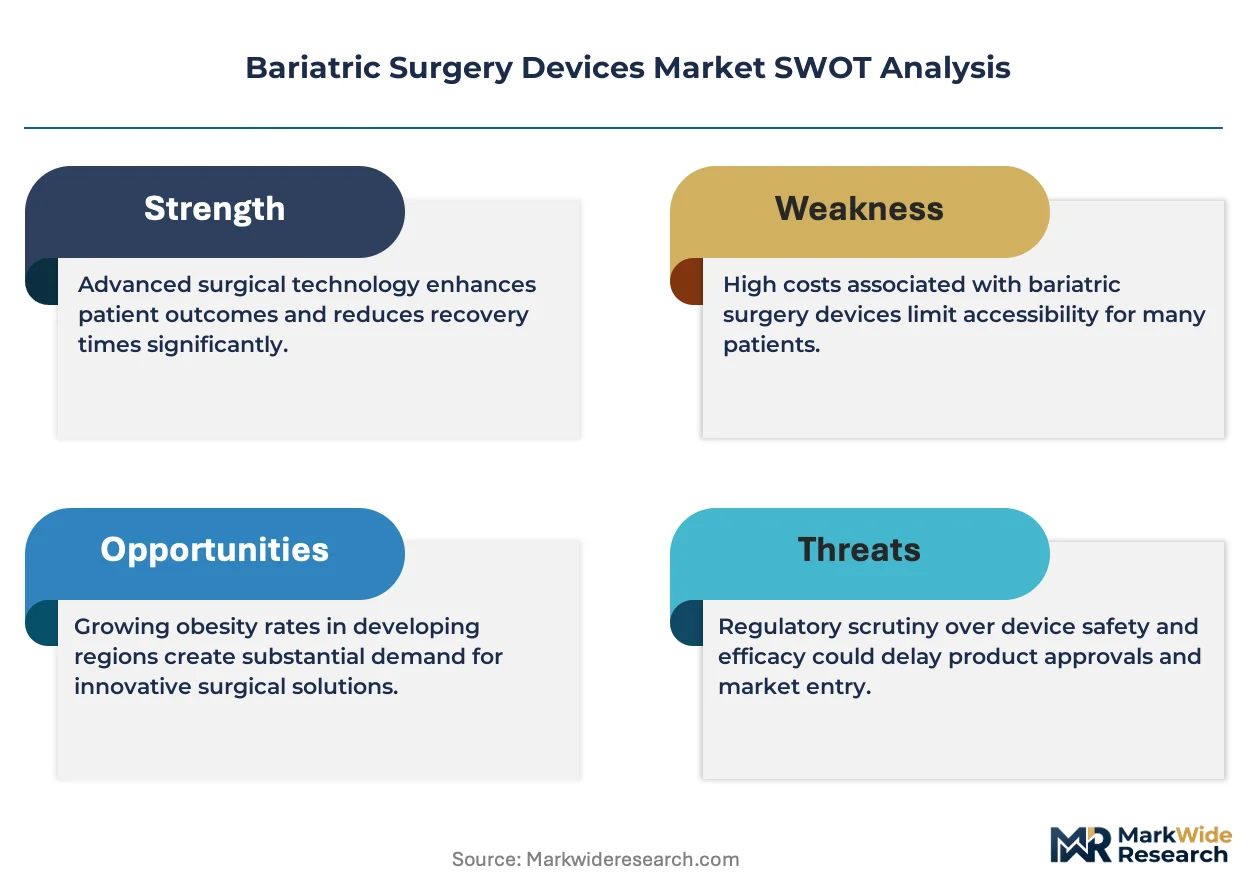
FDA 510(k) clearance requirements and the EU MDR conformity assessment process govern device commercialization, with both frameworks intensifying clinical evidence demands for implantable components such as adjustable gastric bands. The EU AI Act introduces emerging oversight considerations for surgical robotics incorporating autonomous tissue recognition algorithms. Stakeholders must monitor reimbursement coding revisions for endoscopic bariatric procedures, as these determinations will redirect R&D investment toward minimally invasive platforms or conventional surgical systems.
Market Dynamics
Integrated delivery network consolidation is compressing vendor lists around full-line suppliers, forcing device manufacturers to bundle stapling, energy, and visualization systems into single-source contracts that lock out specialty instrument competitors.
Growth Catalysts
- US bundled payment expansion:Medicare's Comprehensive Care for Joint Replacement model now extends to metabolic surgery, reducing out-of-pocket exposure and accelerating procedure volumes in previously underserved hospital systems.
- Robotic platform throughput economics:Capital cost amortization across higher case volumes is migrating mid-tier hospitals from pure laparoscopic approaches toward da Vinci installations.
- EU MDR recertification pressure:Stricter clinical evidence requirements for implantable gastric bands are clearing marginal competitors from the market, consolidating share among established manufacturers with robust quality management systems.
Market Restraints
- Titanium alloy price volatility:Staple line reinforcement materials face input cost swings tied to aerospace demand cycles, squeezing margin on high-volume sleeve gastrectomy consumables.
- FDA 510(k) evidentiary burden:Predicate device pathway tightening for implantable components extends clearance timelines and elevates clinical trial expenditure for novel adjustable band designs.
- Endoscopic bariatric substitution:Intragastric balloons and endoscopic sleeve gastroplasty capture pre-surgical candidates, diverting patients from permanent anatomical alterations.
Strategic Opportunities
- Brazilian public health system penetration:ANVISA streamlined registration for previously approved US and EU devices creates first-mover advantage in Latin America's largest metabolic surgery market.
- AI-integrated tissue recognition:Convergence of autonomous segmentation algorithms with robotic stapling platforms enables real-time perfusion assessment and leak risk prediction.
- Direct-to-hospital consumable subscriptions:Per-procedure pricing models bypass distributor markups and capture recurring revenue streams from high-volume bariatric centers.
Industry Challenges
- Robotic surgery credentialing bottlenecks:Fellowship-trained bariatric surgeons remain scarce relative to installed base expansion, constraining platform utilization rates and capital return timelines.
- EU MDR technical documentation backlog:Notified body capacity constraints delay recertification of legacy adjustable gastric bands, forcing inventory write-downs for distributors with expiring CE marks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bariatric Surgery Devices Market |
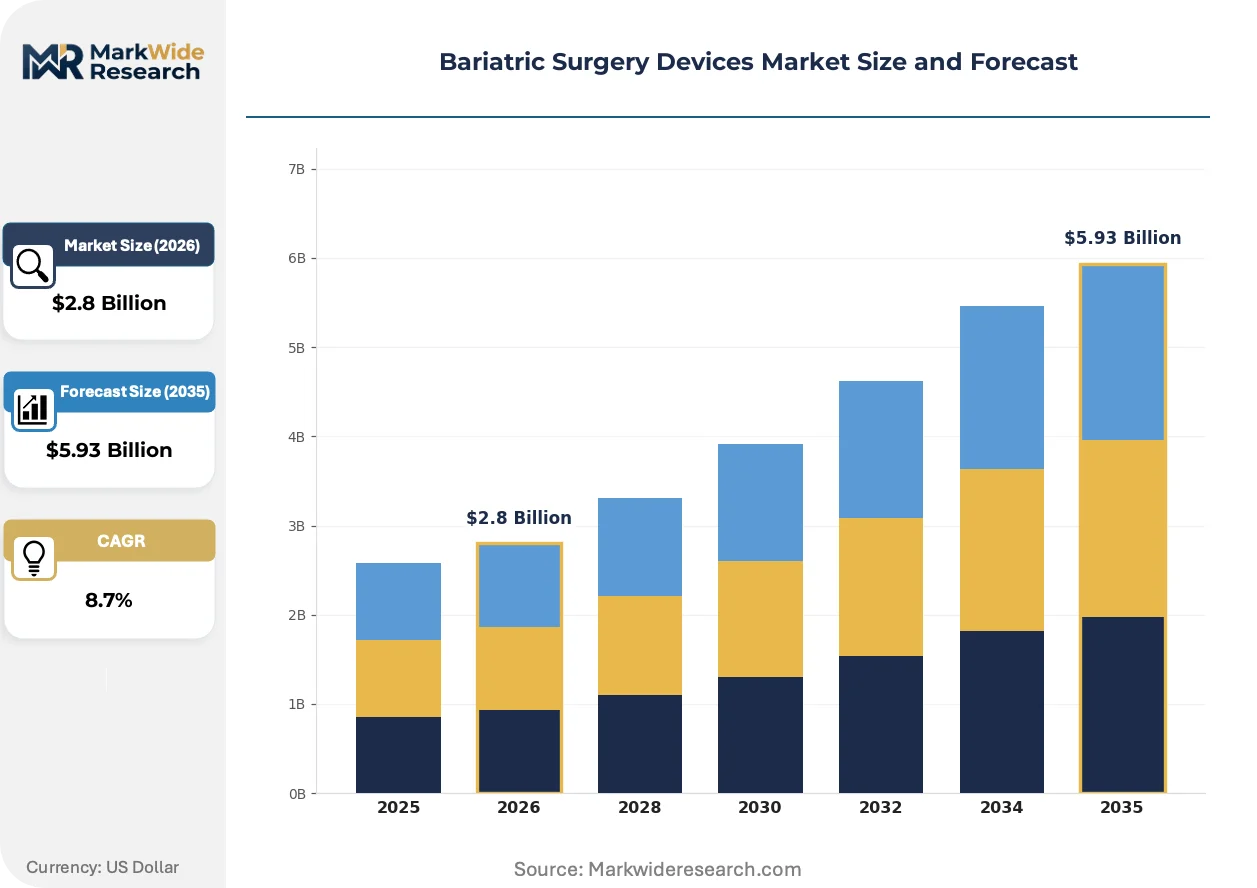
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.93 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gastric Bypass, Sleeve Gastrectomy, Adjustable Gastric Band, Biliopancreatic Diversion Technology: Laparoscopic Surgery, Robotic Surgery, Endoscopic Technique, Traditional Surgery End User: Hospitals, Surgery Centers, Clinics, Home Care Procedure Type: Elective Surgery, Revision Surgery, Emergency Surgery, Outpatient Surgery |
| Companies Covered | Olympus Corporation, Stryker Corporation, Johnson & Johnson, Standard Bariatrics, Conmed Corporation, Medtronic, Boston Scientific Corporation, ReShape Lifesciences, Intuitive Surgical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bariatric Surgery Devices Market Emerging Trajectories
Surgical instrumentation is undergoing platform-level transformation as energy delivery systems, stapling mechanics, and visualization modalities converge into integrated ecosystems that redefine procedural workflow and capital allocation priorities.
Powered stapling technology is migrating from conventional manual firing systems toward battery-driven, controlled-compression platforms that standardize tissue thickness accommodation across variable gastric wall anatomy. Community hospitals with emerging bariatric programs are adopting these systems at accelerated pace to reduce staple line leak rates and mitigate litigation exposure. The technology is enabling mid-tier facilities to achieve outcomes comparable to academic centers, compressing the historical performance gap between high- and low-volume surgical sites.
The EU AI Act introduces risk-classification requirements for surgical robotics incorporating autonomous tissue recognition capabilities, mandating conformity assessment procedures that exceed traditional medical device software validation. European manufacturers must now document algorithmic decision pathways and bias mitigation protocols for machine learning components used in real-time anatomical identification. Sleeve gastrectomy platforms with integrated fluorescence perfusion assessment face the steepest compliance burden, as these systems fall under high-risk AI system definitions requiring notified body intervention.
Hospital supply chain directors are consolidating instrument sourcing around single-platform contracts that bundle capital equipment, disposables, and preventive maintenance into unified spend categories. Integrated delivery networks in the United States are displacing traditional distributor relationships with direct manufacturer partnerships that guarantee volume commitments in exchange for price transparency and inventory consignment. This restructuring is most visible in the southeastern US, where IDN mergers have concentrated purchasing power across formerly independent community hospital systems.
Bariatric Surgery Devices Market Segmentation
Device procurement patterns diverge sharply across bariatric procedure types, with capital-intensive robotic platforms commanding multi-year amortization cycles while stapling consumables turn over within single surgical episodes. Manufacturers must align inventory velocity and clinical support resources to these mismatched replacement rhythms.
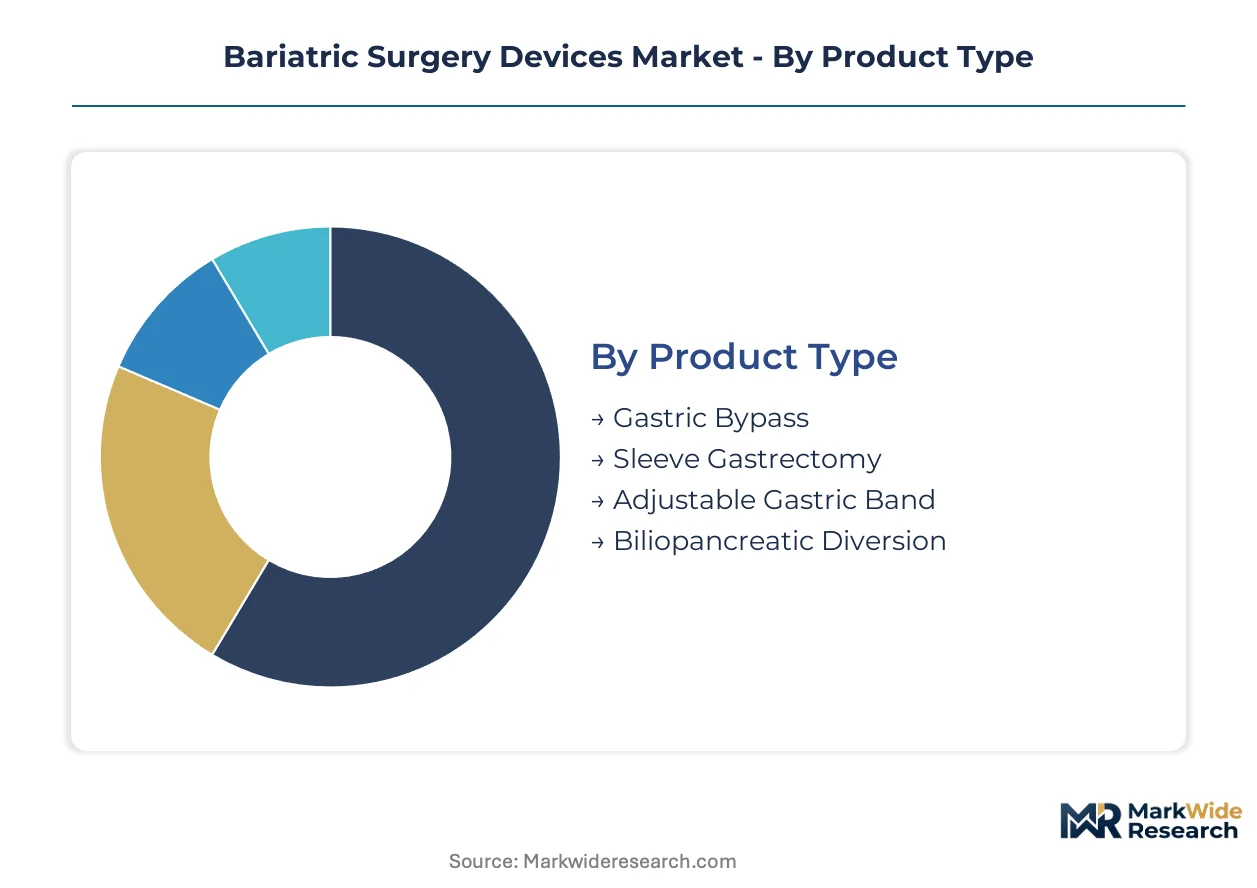
Product Type:
Sleeve gastrectomy consumables rotate fastest through hospital supply chains, while implantable gastric bands sit on shelves awaiting patient qualification workflows that stretch across quarters.
- Sleeve Gastrectomy:Stapling cartridges and energy devices comprise the procedural core, with titanium-reinforced staple lines addressing leak risk in high-volume US metabolic surgery centers. Academic medical centers in Texas and Florida drive specification standards that cascade into community hospital purchasing.
- Gastric Bypass:Anastomotic staplers and circular stapling heads require precise calibration across variable jejunal wall thickness. Demand clusters in established bariatric programs where fellowship-trained surgeons maintain open Roux-en-Y capacity alongside laparoscopic approaches.
- Adjustable Gastric Band:Silicone polymer construction with subcutaneous port systems faces declining placement volumes amid long-term erosion complications. EU MDR recertification delays are compressing available supplier options.
- Biliopancreatic Diversion:Specialized limb-measuring devices and extended stapling platforms serve niche malabsorptive indications. Procedure volume concentrates in European centers with deep experience managing nutritional deficiency protocols.
Sleeve gastrectomy dominates installed base. Adjustable gastric band is where contraction concentrates most severely.
Technology:
Capital deployment intensity separates these modalities, with robotic installations requiring decade-long depreciation schedules against laparoscopic instrument sets that refresh annually.
- Laparoscopic Surgery:Mature trocar, grasper, and clip applier ecosystems deliver cost-efficient access across budget-constrained hospital systems. Brazilian public hospitals and Indian tertiary centers rely on this modality for metabolic surgery program initiation.
- Robotic Surgery:Multi-arm platforms with wristed instrumentation enable single-docking sleeve gastrectomy workflows. da Vinci installations in mid-tier US hospitals are climbing fastest as procedural volume thresholds justify capital commitment.
- Endoscopic Technique:Intragastric balloon delivery systems and endoscopic suturing devices target pre-surgical candidates and failed band patients. Regulatory coding uncertainty in US reimbursement frameworks constrains manufacturer investment.
- Traditional Surgery:Open retractor sets and hand-sewn anastomotic instruments persist for revision cases and super-obese patient populations. Demand localizes to safety-net hospitals without minimally invasive fellowship coverage.
Laparoscopic surgery anchors current procedure volume. Robotic surgery is gaining share fastest among new platform placements.
End User:
Capital access and case complexity stratify purchasing authority across these settings, with integrated delivery networks centralizing high-value contract negotiations.
- Hospitals:Comprehensive metabolic surgery programs bundle stapling, energy, and visualization systems through IDN procurement frameworks. Southeastern US health systems have displaced distributor relationships for direct manufacturer partnerships.
- Surgery Centers:Ambulatory settings with limited overnight capacity focus on low-complexity sleeve gastrectomy in selected BMI ranges. Medicare site-of-service differentials are redirecting eligible cases from inpatient admission.
- Clinics:Preoperative evaluation and postoperative monitoring drive demand for band adjustment needles and nutritional supplementation protocols. Urban multi-specialty groups in California integrate these services with primary care obesity management.
- Home Care:Wound care supplies and enteral nutrition delivery systems support early discharge pathways. Remote patient monitoring integration is emerging in Dutch and Danish reimbursement models.
Hospitals command capital equipment decisions. Surgery centers are where volume expansion is redirecting fastest.
Procedure Type:
Scheduling predictability and resource allocation intensity vary dramatically, with elective workflows enabling supply chain optimization against emergency interventions that strain instrument availability.
- Elective Surgery:Scheduled sleeve gastrectomy and bypass procedures allow just-in-time staple cartridge replenishment and robotic platform block scheduling. US bundled payment models concentrate these cases within designated centers of excellence.
- Revision Surgery:Complex reoperative anatomy demands specialized adhesiolysis instruments and contingency stapling systems. Tertiary referral centers in Germany and Sweden accumulate expertise that attracts cross-border patient flows.
- Emergency Surgery:Staple line leak repair and band erosion interventions require expedited access to compatible revision instrumentation. Overnight courier logistics and consignment inventory arrangements mitigate availability risk.
- Outpatient Surgery:Same-day discharge protocols for selected sleeve gastrectomy patients drive demand for disposable trocar systems and simplified instrument trays. ANVISA-registered devices are penetrating Brazilian ambulatory surgery networks.
Elective surgery dominates scheduled capacity. Outpatient surgery is where same-day discharge protocols are expanding fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA bundled payment models and EU MDR recertification timelines are compressing product launch cycles across the dominant geographies, while emerging hospital systems in Latin America and Asia-Pacific accelerate metabolic surgery program initiation.
United States
Medicare's Comprehensive Care for Joint Replacement model extension to metabolic surgery is reducing patient out-of-pocket exposure and accelerating procedure volumes in previously underserved hospital systems. The FDA 510(k) pathway governs commercialization timelines for implantable components such as adjustable gastric bands. Texas and Florida academic medical centers drive specification standards for sleeve gastrectomy consumables that cascade into community hospital purchasing frameworks.
Germany
Tertiary referral centers in Germany accumulate revision surgery expertise that attracts cross-border patient flows from neighboring European markets. The EU MDR conformity assessment process intensifies clinical evidence demands for implantable devices, clearing marginal competitors from distribution channels. Bavaria and North Rhine-Westphalia host concentrated metabolic surgery capacity where fellowship-trained surgeons manage complex reoperative anatomy.
Brazil
ANVISA streamlined registration pathways for previously approved US and EU devices create first-mover advantage in Latin America's largest metabolic surgery market. The Brazilian public health system is expanding metabolic surgery access through SUS coverage determinations. São Paulo and Rio de Janeiro anchor private hospital network expansion where laparoscopic program initiation outpaces robotic infrastructure deployment.
Japan
PMDA marketing authorization requirements maintain rigorous clinical evidence standards for implantable bariatric devices that filter market entry to established manufacturers. METI industrial policy supports domestic production of surgical instrumentation through targeted supply chain incentives. Tokyo and Osaka metropolitan areas concentrate high-volume metabolic surgery centers where sleeve gastrectomy dominates procedural mix.
India
CDSCO medical device registration timelines are compressing as the regulator harmonizes with IMDRF standards for previously approved innovations. Private tertiary hospitals in Delhi-NCR and Maharashtra are initiating metabolic surgery programs using laparoscopic platforms before robotic capital commitment. Mumbai and Bangalore surgical clusters drive demand for cost-optimized stapling consumables suited to high-volume, price-sensitive procurement frameworks.
Bariatric Surgery Devices Market Vendor Landscape
Diversified conglomerates and specialized surgical technology developers split the market into distinct capability tiers. The vendor base concentrates around full-line suppliers capable of bundling stapling, energy, and visualization systems into single-source IDN contracts. Two strategic archetypes dominate: integrated medical device conglomerates leveraging broad endomechanical portfolios, and focused surgical robotics specialists capturing premium positioning through platform ecosystem control. Competitive moves center on direct-to-hospital consumable subscription models and AI-integrated tissue recognition capabilities that extend platform differentiation.
Among diversified medical technology conglomerates, Johnson & Johnson and Medtronic exemplify the full-line supplier archetype that sustains preferred vendor status across consolidated procurement frameworks. Intuitive Surgical occupies a distinct position as the dedicated surgical robotics platform developer extending installations into mid-tier hospitals previously served by pure laparoscopic approaches. Olympus Corporation and Stryker Corporation sit within the visualization and surgical instrumentation tier where energy delivery and imaging modalities anchor competitive positioning.
| Leading Market Players |
|---|
| Olympus Corporation |
| Stryker Corporation |
| Johnson & Johnson |
| Standard Bariatrics |
| Conmed Corporation |
| Medtronic |
| Boston Scientific Corporation |
| ReShape Lifesciences |
| Intuitive Surgical |
| Others |
Supply Flow & Price Mechanics
Trans-Pacific container freight corridors linking East Asian manufacturing hubs to US West Coast ports transmit titanium alloy cost volatility directly into staple line reinforcement pricing, concentrating margin pressure on high-volume sleeve gastrectomy consumables while enabling full-line suppliers to extract premiums through configured-to-order robotic platform bundles.
Pricing Analysis
The customization-premium spread separates standard laparoscopic instrument sets from configured robotic platform subscriptions that bundle capital equipment, disposables, and preventive maintenance. Three-tier pricing structure across premium, standard, and economy levels reflects FDA 510(k) clearance tier and hospital IDN volume scale as primary differentiation drivers. Cost compression in standard laparoscopic consumables intensifies as Brazilian and Indian procurement frameworks prioritize price over brand. Community hospital systems exhibit highest price sensitivity; academic medical centers with bundled payment contracts show lowest.
Supply Chain Analysis
Supplier-financing facilities extended by Japanese and German precision instrument manufacturers enable mid-tier hospitals to amortize robotic platform capital costs across multi-year deployment schedules. Manufacturing concentration centers on Japan, Germany, and the United States for high-precision stapling mechanisms, while China and India supply cost-optimized trocar and grasper components. Titanium alloy feedstock from aerospace supply chains creates single-source vulnerability for staple line reinforcement materials. Distribution runs through consolidated IDN procurement frameworks that displace traditional distributor relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment: FDA 510(k) clearance timelines and EU MDR recertification requirements create structural barriers that compound over successive product generations.
For Market Incumbents: Entrench position through backward integration into titanium alloy processing to mitigate aerospace demand cycle exposure, while accelerating AI-integrated tissue recognition capabilities to extend platform differentiation against emerging powered stapling competitors. Deepen hospital system partnerships through direct consumable subscription models that lock out specialty instrument vendors from IDN procurement frameworks. For New Entrants and Emerging Players: Brazilian public health system expansion through SUS coverage determinations represents the most penetrable entry point for previously approved US and EU devices seeking ANVISA streamlined registration. Endoscopic bariatric substitution segments—intragastric balloons and endoscopic suturing platforms—offer secondary white-space opportunity amid reimbursement coding uncertainty constraining incumbent investment. Pursue per-procedure pricing models that bypass distributor markups and capture recurring revenue from high-volume ambulatory surgery centers. For Investors and Strategic Acquirers: EU MDR recertification deadlines reshape the acquisition landscape by forcing inventory write-downs among distributors with expiring CE marks, creating distressed asset opportunities. Target manufacturers with robust quality management systems and notified body relationships capable of navigating high-risk AI system conformity assessments. Monitor FDA premarket notification pathway tightening for implantable components as the signal indicating further consolidation pressure on adjustable gastric band specialists.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Recertification Pathway | Notified body capacity constraints filter marginal competitors from implantable device distribution channels. |
| Hospital System Partnership | Direct manufacturer relationships with southeastern US IDNs displace traditional distributor markups. |
| Software Companion Development | Autonomous tissue recognition algorithms trigger EU AI Act high-risk system compliance requirements. |
| Reimbursement Strategy | Medicare bundled payment expansion redirects eligible cases toward designated centers of excellence. |
| CE Marking Pathway | Stricter clinical evidence demands for implantable gastric bands extend clearance timelines for novel designs. |
Methodological Framework
A standing panel of bariatric surgeons, hospital purchasing committee chairs, biomedical engineers, and GPO contracts managers provided ongoing calibration against secondary validation from FDA 510(k) filings, EU MDR technical documentation, hospital procurement databases, and CMS Medicare reimbursement data. Bottom-up procedure volume estimates triangulated with top-down manufacturer shipment data across product type, technology modality, and end-user setting dimensions.
Scenario-bracketing framed projections across the analysis window, with segmentation modeling spanning procedure type, technology platform, and geographic regulatory cluster. CAGRs derived from weighted average of historical volume trajectories and forward-looking reimbursement policy assumptions, incorporating titanium alloy price indices and robotic platform installation rates as industry-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in freight costs, aerospace demand cycles, or healthcare reimbursement policy would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory pathway stability and IDN consolidation pace. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bariatric Surgery
Italy Bariatric Surgery Market
Bariatric Surgery
Global Bariatric Surgery Market
Bariatric Surgery
India Bariatric Surgery Market
Bariatric Surgery
United States Bariatric Surgery Market
Bariatric Surgery
Netherlands Bariatric Surgery Market
Bariatric Surgery
Bariatric Patient Room Market
Bariatric Surgery
Chile Bariatric Surgery Market
Bariatric Surgery
US Medical Weight Loss Clinics Market
Bariatric Surgery
Germany Bariatric Surgery Market
Bariatric Surgery
Bariatric Medical Chairs Market
Bariatric Surgery
South Africa Bariatric Surgery Market
Bariatric Surgery
Sweden Bariatric Surgery Market
Bariatric Surgery
Bariatric Lifts Market
Bariatric Surgery
Canada Bariatric Surgery Market
Bariatric Surgery
Brazil Bariatric Surgery Market
Bariatric Surgery
Bariatric Transport Wheelchairs Market