
 India Bariatric Surgery Devices Market | 2026-2036
India Bariatric Surgery Devices Market Size, Share, and Industry Trends Forecast 2026-2036
India Bariatric Surgery Devices Market Foresight
Domestic surgical instrument clusters in Gujarat and Tamil Nadu is broadening component sourcing for device assemblers. Medtronic India Pvt. Ltd. leverages its Mumbai-based distribution network to anchor premium stapler sales across western India. Johnson and Johnson Ltd competes through sustained R&D spending on ergonomic laparoscopic platforms. Apollo Endosurgery India specializes in endoluminal devices, occupying a narrow but defensible niche in non-invasive revision procedures.
Bariatric surgery devices encompass stapling systems, gastric bands, and suturing instruments engineered from surgical-grade stainless steel and biocompatible polymers, designed to reduce stomach volume or alter digestive pathways for morbid obesity management. Gastric bypass and sleeve gastrectomy devices dominate current volume, while robotic delivery modes capture expanding margin pools as hospital capital expenditure shifts toward precision platforms. Adjustable gastric band demand plateaus amid surgeon preference migration toward irreversible metabolic procedures, concentrating aftermarket service revenue with original equipment manufacturers.
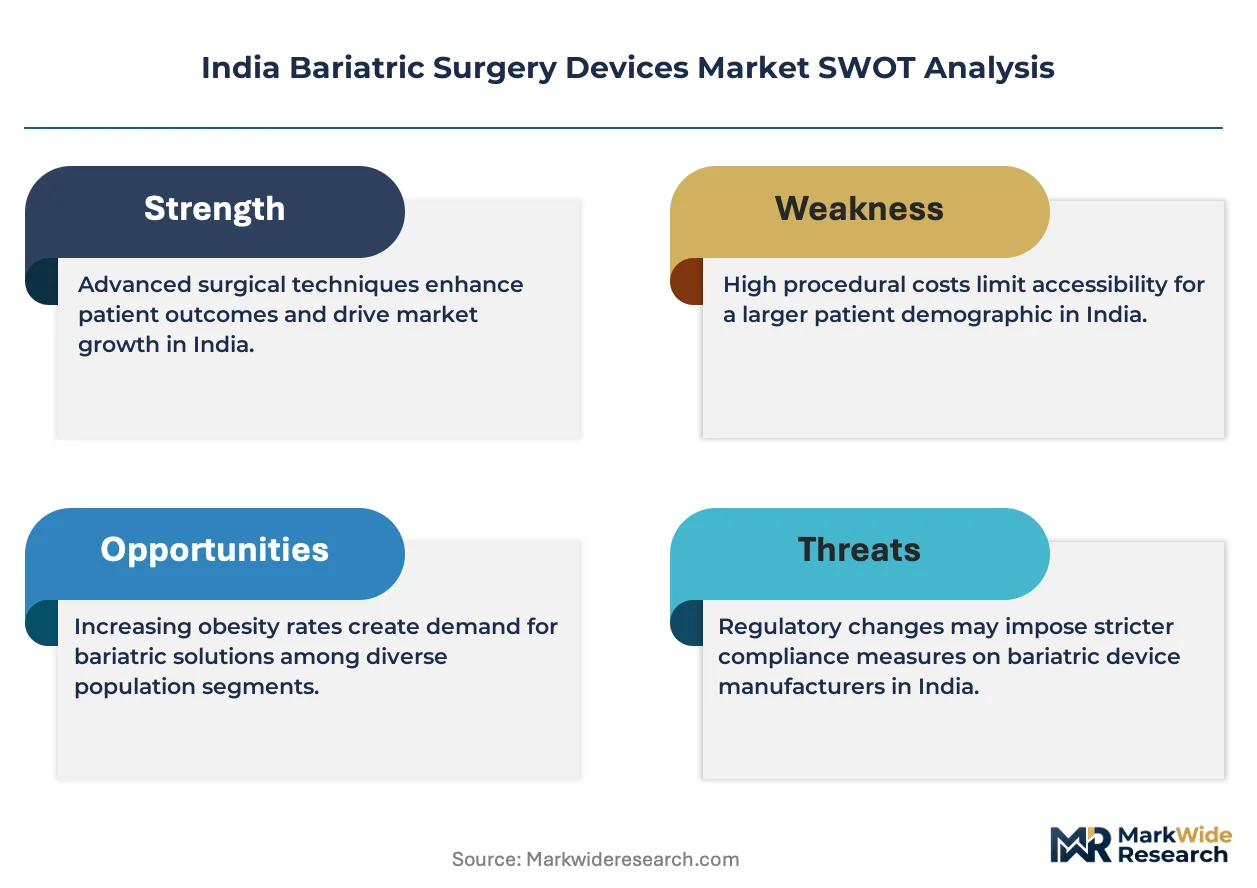
CDSCO's medical device rules and BIS certification requirements govern product registration, while the PLI scheme incentivizes local production of high-value surgical consumables. CDSCO's phased risk-based classification tightens clinical evidence standards for novel implantable devices, extending approval timelines for foreign manufacturers. Stakeholders must monitor state-level hospital procurement tenders and evolving reimbursement stance under Ayushman Bharat as these determine addressable patient volumes more than device innovation cycles alone.
Market Dynamics
CDSCO's risk-based medical device classification is compressing approval timelines for domestic manufacturers while extending scrutiny cycles for foreign implantable staplers, reshaping competitive entry patterns across Maharashtra and Karnataka hospital networks.
Growth Catalysts
- PLI scheme incentives:Domestic production of high-value surgical consumables receives 4-6% value-linked rewards, drawing Gujarat and Tamil Nadu instrument clusters into bariatric component supply chains.
- Metabolic surgery department expansion:Tier-I hospitals in Mumbai and Delhi are building dedicated bariatric centers in response to obesity-linked diabetes caseloads.
- Ayushman Bharat reimbursement stance evolution:State-level procurement tenders for metabolic procedures are expanding addressable patient volumes beyond private-pay segments.
Market Restraints
- BIS certification complexity:Surgical-grade stainless steel instruments face extended testing protocols at designated laboratories, delaying product launches by 8-14 months.
- Import dependence for precision polymers:Biocompatible suturing materials concentrate in German and US chemical suppliers, exposing assemblers to currency volatility and shipping disruptions.
- Surgeon training pipeline constraints:Fellowship-qualified bariatric surgeons number under 400 nationwide, capping procedure volume growth irrespective of device availability.
Strategic Opportunities
- Robotic platform penetration:Hospital capital expenditure is shifting toward precision surgical systems, creating aftermarket service revenue pools for stapler and suturing attachments.
- Endoluminal revision procedures:Non-invasive gastric outlet reduction devices address failed primary surgeries, opening a narrow but defensible niche outside standard metabolic pathways.
- Tamil Nadu component ecosystem:Domestic surgical instrument manufacturing clusters can backward-integrate into high-margin stapler cartridge production under CDSCO's streamlined Class B approval track.
Industry Challenges
- CDSCO clinical evidence standards:Novel implantable devices require prospective trial data, forcing foreign manufacturers to sponsor expensive Indian cohort studies before registration.
- Legacy laparoscopic platform integration:Robotic delivery systems must interface with existing tower configurations in Delhi and Mumbai hospitals, complicating capital sales cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Bariatric Surgery Devices Market |
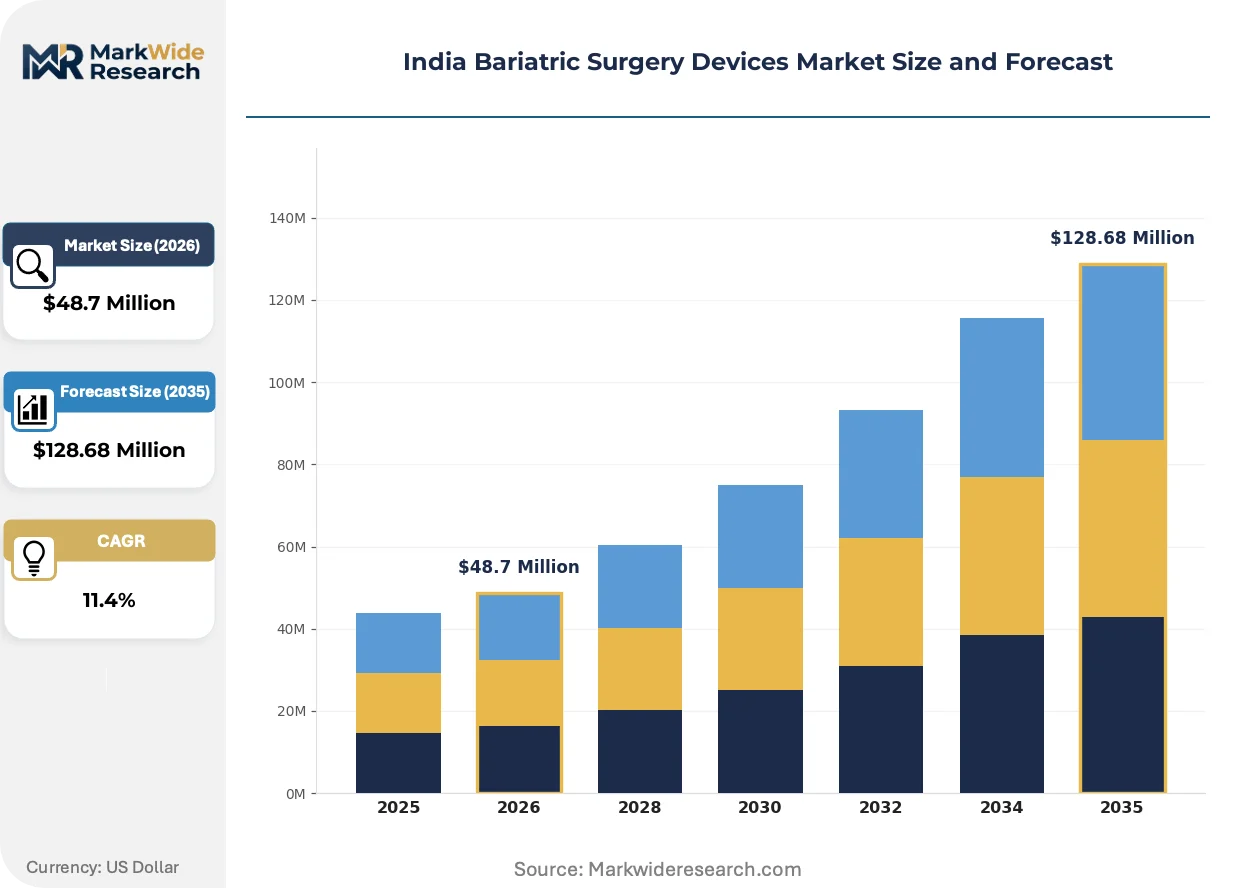
| Market Size in 2026 | $48.7 Million |
| Market Size in 2035 | $128.68 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Gastric Bypass, Sleeve Gastrectomy, Adjustable Gastric Band, Biliopancreatic Diversion Delivery Mode: Inpatient, Outpatient, Laparoscopic, Robotic End User: Hospitals, Surgical Centers, Clinics, Research Institutions Procedure Type: Elective Surgery, Emergency Surgery, Revision Surgery, Minimally Invasive |
| Companies Covered | Medtronic India Pvt. Ltd., Johnson and Johnson Ltd, Apollo Endosurgery India, B. Braun India, Becton Dickinson India Pvt Ltd., Stryker India Pvt. Ltd., Dolphin Surgicals Industries, Western Trading Company, Staan Bio-Med Engineering Private Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Bariatric Surgery Devices Market Shifts & Advancements
Device architecture is pivoting from mechanical stapling toward energy-based tissue sealing, while regulatory data requirements and procurement centralization simultaneously reshape how manufacturers reach hospital buyers.
Articulating stapler platforms are converging with real-time tissue impedance feedback to enable consistent staple line integrity across variable gastric wall thickness. Apollo Hospitals and Max Healthcare are piloting these systems in Mumbai and Delhi bariatric units. This convergence is compressing revision surgery rates and shifting surgeon preference toward integrated platforms over standalone mechanical devices.
CDSCO's 2023 amendment to Medical Device Rules mandates Unique Device Identification for all implantable surgical equipment, effective for new registrations. Foreign manufacturers must reconfigure labeling and traceability systems for the Indian market. Class C stapling systems face the steepest compliance burden, with several European suppliers delaying launches pending clarification on barcode granularity requirements.
State-level hospital procurement is consolidating metabolic surgery device tenders under centralized purchasing authorities in Maharashtra and Karnataka. Single-source contracts for stapling systems are displacing multi-vendor arrangements that prevailed through 2022. This concentration is most visible in Bengaluru's private hospital chain networks, where annual framework agreements now lock in 36-month supply commitments with exclusive service terms.
India Bariatric Surgery Devices Market Segmentation
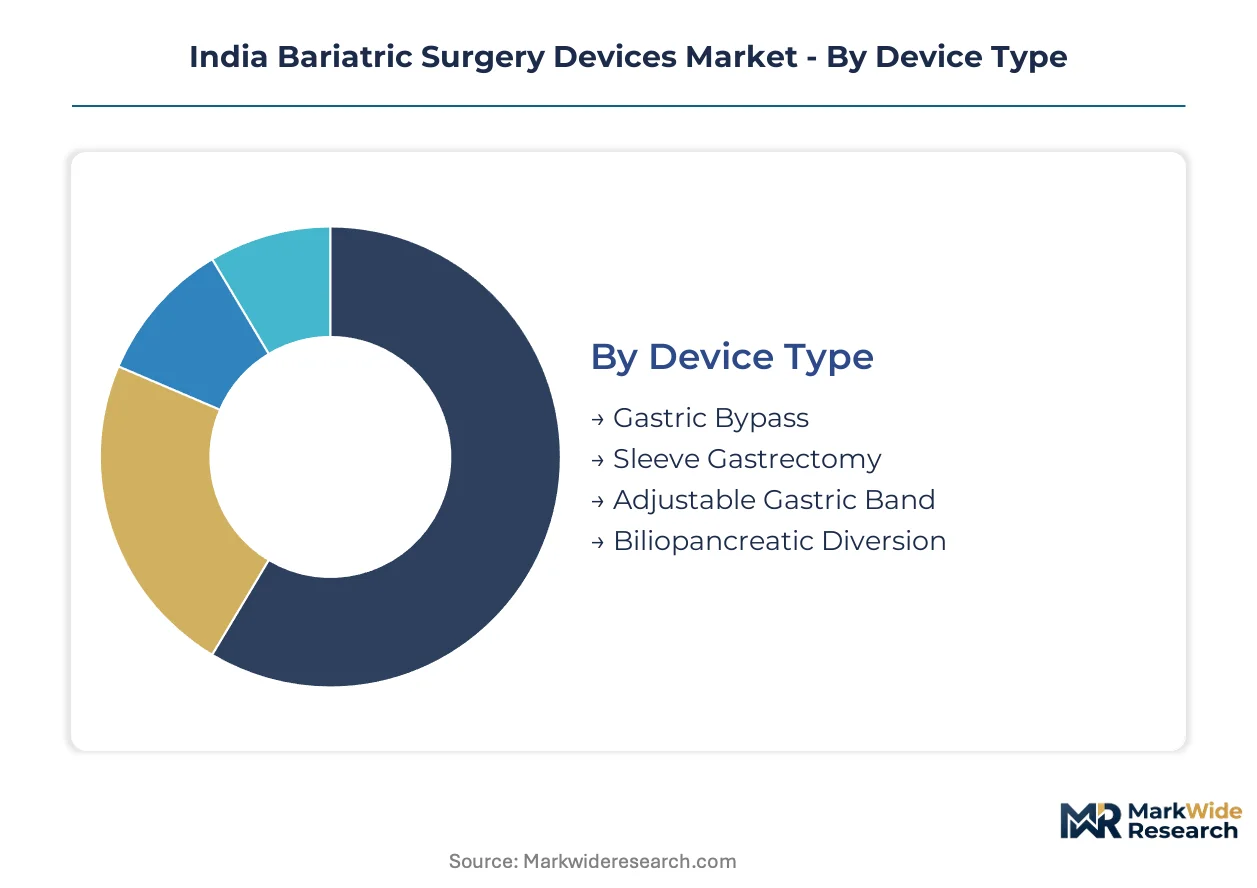
Device segmentation in the India bariatric surgery devices market reveals distinct procurement patterns across hospital tiers and surgical settings. Understanding how procedure complexity, reimbursement pathways, and capital expenditure cycles align with specific device categories determines vendor positioning and pricing power.
Device Type:
Surgeon preference and metabolic outcome data differentiate device selection across Maharashtra and Karnataka hospital networks.
- Gastric Bypass:Gold-standard Roux-en-Y configurations utilize circular and linear stapling systems with anastomotic reinforcement. Demand concentrates in Mumbai's Tier-I hospitals where fellowship-trained surgeons manage complex diabetic cases. CDSCO's Class C implantable classification extends approval timelines for novel bypass staplers.
- Sleeve Gastrectomy:Greater curvature resection devices dominate current volumes through simpler technical execution and lower complication profiles. Bengaluru's private hospital chains are standardizing sleeve-specific instrument trays across their bariatric centers. The procedure's irreversibility aligns with metabolic surgery department expansion strategies.
- Adjustable Gastric Band:Port and band systems face declining surgeon adoption amid revision surgery concerns and inferior long-term weight loss outcomes.
- Biliopancreatic Diversion:Malabsorptive device configurations serve niche super-obese patient populations in Delhi's specialized metabolic units.
Gastric bypass leads volumes today; sleeve gastrectomy is gaining share fastest.
Delivery Mode:
Capital intensity and reimbursement eligibility separate inpatient from outpatient procedure economics.
- Inpatient:Traditional hospital admission models support complex multi-anastomotic procedures requiring extended monitoring. Maharashtra's state procurement tenders favor inpatient bundled payment structures for metabolic surgeries.
- Outpatient:Ambulatory surgical centers in Tamil Nadu are piloting same-day discharge protocols for select sleeve gastrectomy candidates.
- Laparoscopic:Tower-based minimally invasive platforms constitute the installed base across Delhi and Mumbai hospitals, with reusable instrument depreciation cycles shaping replacement demand.
- Robotic:Da Vinci and comparable systems command premium stapler attachment pricing through proprietary instrument interfaces. Apollo Hospitals' Mumbai network is expanding robotic bariatric capacity amid surgeon recruitment competition.
Laparoscopic delivery dominates current procedure counts; robotic platforms show the steepest expansion trajectory.
End User:
Procurement autonomy and patient volume scale determine device pricing tiers across care settings.
- Hospitals:Multi-specialty institutions with dedicated metabolic surgery departments negotiate framework agreements for stapling system supply. Max Healthcare's Delhi-NCR facilities are consolidating vendor relationships under single-source 36-month contracts.
- Surgical Centers:Focused ambulatory facilities in Gujarat prioritize cost-optimized laparoscopic platforms with standardized instrument sets.
- Clinics:Pre-operative consultation and post-operative monitoring sites drive demand for patient selection and nutritional support devices rather than surgical instruments.
- Research Institutions:Academic medical centers in Karnataka sponsor clinical trials for novel endoluminal devices under CDSCO's streamlined investigation protocol pathway.
Hospitals absorb the majority of device procurement value; surgical centers are expanding capacity most quickly.
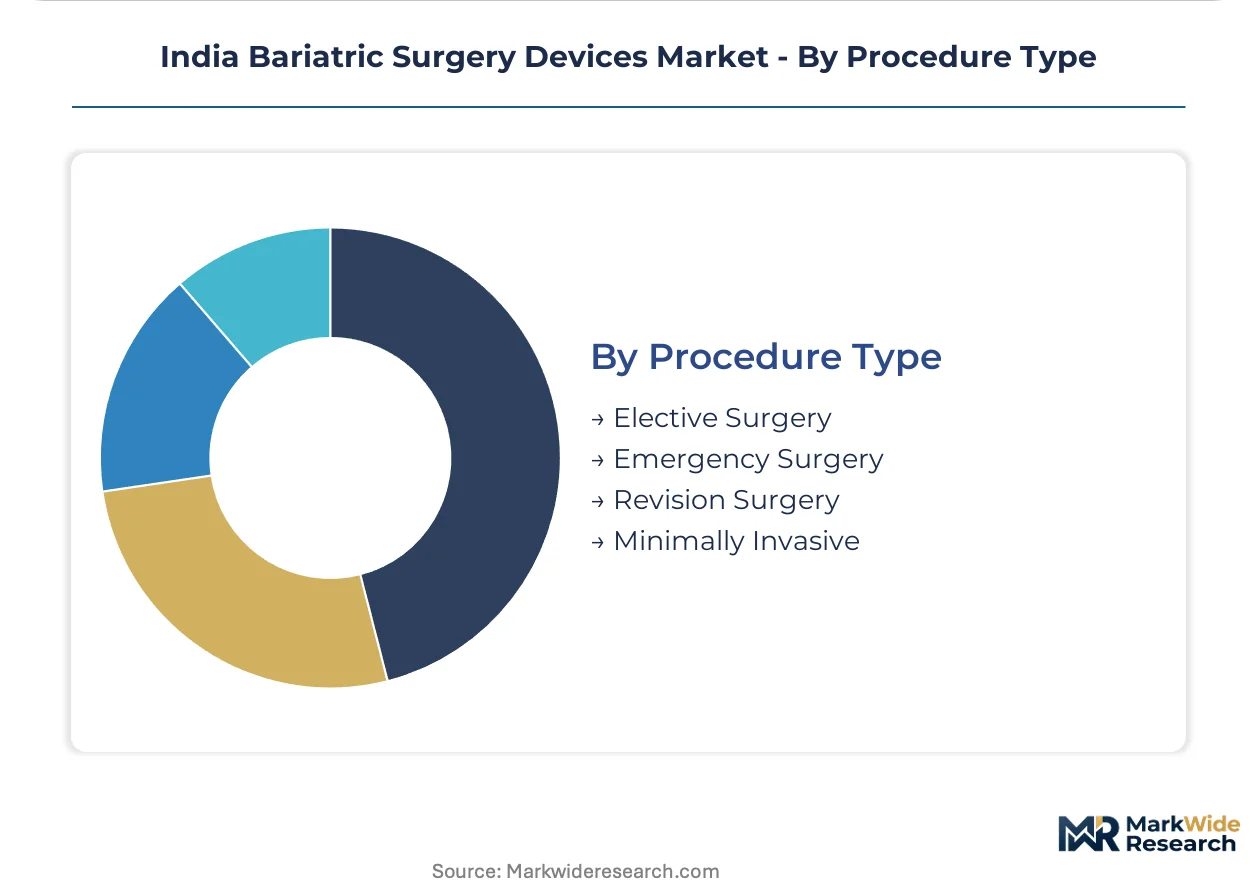
Procedure Type:
Reimbursement certainty and clinical urgency reshape device inventory requirements across surgical schedules.
- Elective Surgery:Scheduled metabolic procedures allow advance instrument sterilization and vendor technical support coordination. Ayushman Bharat's evolving coverage stance is expanding elective case volumes beyond private-pay segments.
- Emergency Surgery:Acute complications from prior bariatric interventions require rapid-access stapling and suturing inventory in tertiary care emergency departments.
- Revision Surgery:Secondary procedures addressing failed primary surgeries command premium device pricing through technical complexity and scar tissue management requirements. Apollo Endosurgery India's endoluminal platforms target this specific indication.
- Minimally Invasive:Reduced-port and single-incision techniques are gaining traction in Bengaluru's competitive private hospital market as differentiation tools.
Elective procedures generate the largest device revenue base; revision surgery commands the highest per-case instrument spend.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Domestic manufacturers in Gujarat and Tamil Nadu exploit CDSCO's streamlined Class B approval pathway to compress time-to-market versus foreign implantable stapler producers facing extended clinical evidence requirements.
Maharashtra
Mumbai's Tier-I hospitals are expanding dedicated metabolic surgery departments to address obesity-linked diabetes caseloads. CDSCO's risk-based classification concentrates premium stapler procurement within accredited tertiary care centers. Max Healthcare's facilities in the Mumbai-Pune corridor are consolidating vendor relationships under single-source framework agreements.
Karnataka
Bengaluru's private hospital chains are standardizing sleeve-specific instrument trays across bariatric centers. State-level procurement consolidation under centralized purchasing authorities is displacing multi-vendor arrangements. Apollo Hospitals' network is expanding robotic bariatric capacity amid surgeon recruitment competition.
Delhi-NCR
Specialized metabolic units in Delhi hospitals serve niche super-obese patient populations requiring complex malabsorptive procedures. Ayushman Bharat's evolving reimbursement stance is expanding addressable patient volumes beyond private-pay segments. Legacy laparoscopic tower configurations complicate capital sales cycles for robotic delivery systems.
Gujarat
Domestic surgical instrument clusters in Ahmedabad and Surat are broadening component sourcing for device assemblers. PLI scheme incentives of 4-6% value-linked rewards draw local manufacturers into bariatric stapler cartridge production. Cost-optimized laparoscopic platforms dominate ambulatory surgical center procurement in the state.
Tamil Nadu
Surgical instrument manufacturing clusters in Chennai and Coimbatore are backward-integrating into high-margin stapler cartridge assembly. CDSCO's streamlined Class B approval track accelerates domestic production timelines versus foreign competitors. Same-day discharge protocols for select sleeve gastrectomy candidates are piloting in ambulatory surgical centers.
India Bariatric Surgery Devices Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue component supply and regional distribution partnerships. The vendor base stratifies across three tiers: multinational subsidiaries with Mumbai-based distribution networks, domestic instrument assemblers leveraging Tamil Nadu and Gujarat manufacturing clusters, and niche endoluminal specialists. Consolidation pressures concentrate procurement decisions within hospital chain central purchasing authorities. Dominant competitive moves include framework agreement lock-ins with 36-month exclusive service terms and backward integration into stapler cartridge production.
Among multinational subsidiaries, Medtronic India Pvt. Ltd. and Johnson and Johnson Ltd exemplify the premium-tier positioning anchored in western India distribution infrastructure. Apollo Endosurgery India occupies a narrow but defensible niche representing the endoluminal specialist archetype focused on non-invasive revision procedures. Domestic fabricators including Dolphin Surgicals Industries and Staan Bio-Med Engineering Private Limited sit within the component supply tier serving assemblers in Tamil Nadu and Gujarat clusters.
| Leading Market Players |
|---|
| Medtronic India Pvt. Ltd. |
| Johnson and Johnson Ltd |
| Apollo Endosurgery India |
| B. Braun India |
| Becton Dickinson India Pvt Ltd. |
| Stryker India Pvt. Ltd. |
| Dolphin Surgicals Industries |
| Western Trading Company |
| Staan Bio-Med Engineering Private Limited |
| Others |
Supply & Pricing Matrix
Centralized hospital procurement authorities in Maharashtra and Karnataka anchor pricing power through multi-year framework agreements that compress distributor margins and lock in volume commitments. This buyer concentration forces manufacturers to compete on bundled service terms rather than standalone device pricing.
Pricing Analysis
Distributor margins on imported stapling systems face sustained compression as hospital chains consolidate purchasing under single-source contracts. Three-tier pricing structure across premium robotic attachments, standard laparoscopic platforms, and economy-grade reusable instruments reflects certification grade and after-sales service bundling. Pricing pressure stems from CDSCO's streamlined Class B approval track enabling domestic assemblers to undercut premium imports. Tier-I hospitals in Mumbai exhibit lowest price sensitivity due to outcome-based procurement criteria, while ambulatory surgical centers in Gujarat prioritize cost-optimized instrument sets.
Supply Chain Analysis
Biocompatible polymer supply rests on German and US specialty chemical producers, exposing device assemblers to currency volatility and shipping disruptions. Surgical-grade stainless steel feeds from domestic mills in Gujarat and Tamil Nadu, while precision-machined components concentrate in Chennai and Coimbatore instrument clusters. Single-source vulnerability in suturing material supply chains amplifies risk during geopolitical trade friction. Distribution runs through Mumbai-based logistics hubs serving western India hospital networks, with regional stockholding agreements ensuring rapid instrument availability for scheduled metabolic procedures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The India bariatric surgery devices market functions as a stable compounder anchored by irreversible metabolic disease prevalence and government reimbursement expansion under Ayushman Bharat.
For Market Incumbents: Lock in exclusive service contracts with Apollo Hospitals and Max Healthcare networks before procurement centralization completes. Backward integration into stapler cartridge production in Tamil Nadu clusters defends margin position against CDSCO-favored domestic entrants. Monitor endoluminal revision platforms as substitute technology threatening open surgical device volumes. For New Entrants and Emerging Players: Capture component supply relationships with Gujarat instrument assemblers seeking Class B certification under PLI scheme incentives. Bengaluru's private hospital chains represent the most penetrable geography given robotic platform expansion and surgeon recruitment competition. Pursue technical partnership route with established distributors holding Mumbai-based logistics infrastructure. For Investors and Strategic Acquirers: Domestic hospital chains with captive device distribution arms are the most active acquirer in this space. Five-to-ten year viability rests on metabolic surgery department buildout pace and reimbursement policy continuity. Watch CDSCO risk-classification amendments as inflection indicator for foreign manufacturer competitive positioning.| Strategic Initiative | Industry Significance |
|---|---|
| CDSCO Class B Registration Pathway | Domestic manufacturers in Tamil Nadu compress approval timelines versus foreign implantable stapler producers. |
| Hospital System Partnership | Framework agreements with Max Healthcare and Apollo Hospitals lock in 36-month exclusive supply commitments. |
| Backward Integration Program | Gujarat instrument clusters capture stapler cartridge assembly margins previously retained by multinational subsidiaries. |
| Reimbursement Strategy | Ayushman Bharat state-level tender participation expands addressable patient volumes beyond private-pay segments. |
| Software Companion Development | Real-time tissue impedance feedback integration differentiates articulating stapler platforms in Mumbai bariatric units. |
Research Methodology
Bottom-up hospital procurement modeling reconciled against top-down manufacturing cluster tracking forms the analytical core of this study. Primary interviews with bariatric surgeons, hospital purchasing committee members, biomedical engineers, and GPO contracts managers combined with secondary validation from CDSCO registration databases, state tender documentation, and PLI scheme disclosure filings. Triangulation across these sources ensures procedure volume estimates align with device shipment patterns from Tamil Nadu and Gujarat production facilities.
Historical trendline analysis of metabolic surgery department expansion and robotic platform adoption rates informed the projection framework. Segmentation modeling spans device type, delivery mode, end user, and procedure category across the analysis window. CAGRs derive from fitted growth curves applied to hospital capital expenditure cycles and surgeon training pipeline constraints. Forecast inputs incorporate CDSCO regulatory amendment timelines and Ayushman Bharat reimbursement stance evolution.
Regulatory reclassification, supply chain disruption in biocompatible polymers, and surgeon workforce constraints are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions about procurement centralization pace and domestic manufacturing scale-up under PLI incentives. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bariatric Surgery
Bariatric Surgery Devices Market
Bariatric Surgery
Saudi Arabia Bariatric Surgery Market
Bariatric Surgery
South Korea Bariatric Surgery Market
Bariatric Surgery
Bariatric Rollator Walkers Market
Bariatric Surgery
India Bariatric Surgery Market
Bariatric Surgery
Global Bariatric Walking Aids Market
Bariatric Surgery
Netherlands Bariatric Surgery Market
Bariatric Surgery
Brazil Bariatric Surgery Market
Bariatric Surgery
UAE Bariatric Surgery Market
Bariatric Surgery
United Kingdom Bariatric Surgery Market
Bariatric Surgery
Spain Bariatric Surgery Market
Bariatric Surgery
Bariatric Transport Wheelchairs Market
Bariatric Surgery
China Bariatric Surgery Market
Bariatric Surgery
Global Bariatric Surgical Devices Market
Bariatric Surgery
Australia Bariatric Surgery Market
Bariatric Surgery
Bariatric Patient Room Market