
 Autotransfusion Devices Market | 2026-2036
Autotransfusion Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Autotransfusion Devices Market Analysis
EU MDR is shifting the cost-of-entry calculus for autotransfusion device manufacturers seeking European market access. Medtronic plc leverages its broad perfusion portfolio to sustain service contracts across major hospital systems. Haemonetics Corporation anchors its position through specialized blood management workflows that integrate with cell salvage hardware. Beijing ZKSK Technology competes on manufacturing scale, supplying vacuum-assisted systems to cost-sensitive procurement channels.
Autotransfusion devices recover and reinfuse a patient's own blood during or after surgery, typically processing shed blood through centrifugal washing at rotational speeds exceeding 5,000 RPM to produce washed red cell concentrates with hematocrit levels of 50-60%. Cell salvage systems dominate installed base value due to their central role in intraoperative blood recovery, while automated systems represent the fastest-expanding technology segment as hospitals seek reduced operator dependency and standardized wash protocols. Orthopedic surgery applications are deepening penetration as enhanced recovery after surgery protocols prioritize hemoglobin conservation.
FDA 510(k) clearance requirements and EU MDR conformity assessments shape product development timelines and clinical evidence burdens for autotransfusion manufacturers. The EPA regulates waste blood handling downstream, influencing device design for effluent containment. Stakeholders must monitor evolving reimbursement policies for intraoperative autologous transfusion as bundled payment models expand in surgical care.
Market Dynamics
Autotransfusion device procurement is consolidating around integrated delivery networks that negotiate system-wide contracts, compressing vendor margins while demanding standardized service protocols across multi-hospital footprints.
Growth Catalysts
- EU MDR compliance deadlines:The Medical Device Regulation's 2024-2026 transition window is accelerating hospital replacement cycles for legacy cell salvage hardware ahead of stricter post-market surveillance requirements.
- Enhanced Recovery After Surgery protocols:Orthopedic surgery departments in tertiary hospitals are embedding autotransfusion into standardized blood conservation pathways to reduce allogeneic transfusion dependency.
- Centrifugal washing automation:Next-generation systems incorporating closed-loop hematocrit monitoring are reducing operator training burdens and expanding deployment into mid-tier surgical centers.
Market Restraints
- Capital equipment intensity:Per-unit system costs exceeding $150,000 for automated cell salvage platforms restrict procurement authority to centralized supply committees rather than individual surgical departments.
- Single-use consumable dependency:Proprietary wash sets and suction collection reservoirs lock hospitals into recurring expenditure streams that resist budget optimization during contract renegotiations.
- FDA 510(k) pathway complexity:Blood-processing device submissions now require expanded clinical validation datasets, extending premarket clearance timelines and elevating development burn rates for novel entrants.
Strategic Opportunities
- Ambulatory surgery center penetration:Freestanding orthopedic and spine facilities in the United States represent an underpenetrated channel for compact, cart-based autotransfusion systems with reduced footprint requirements.
- Perioperative blood management integration:Convergence of cell salvage hardware with real-time hemoglobin monitoring and predictive analytics platforms is creating bundled service propositions.
- EPA waste handling incentives:Regulatory pressure on liquid medical waste disposal is positioning closed-system autotransfusion devices as compliance tools for effluent reduction in surgical suites.
Industry Challenges
- Perfusionist workforce scarcity:Specialized operators capable of managing intraoperative blood recovery protocols are concentrated in academic medical centers, limiting deployment scalability.
- Legacy EMR integration friction:Proprietary data formats from cell salvage systems require custom interface development for seamless documentation within electronic health record workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Autotransfusion Devices Market |
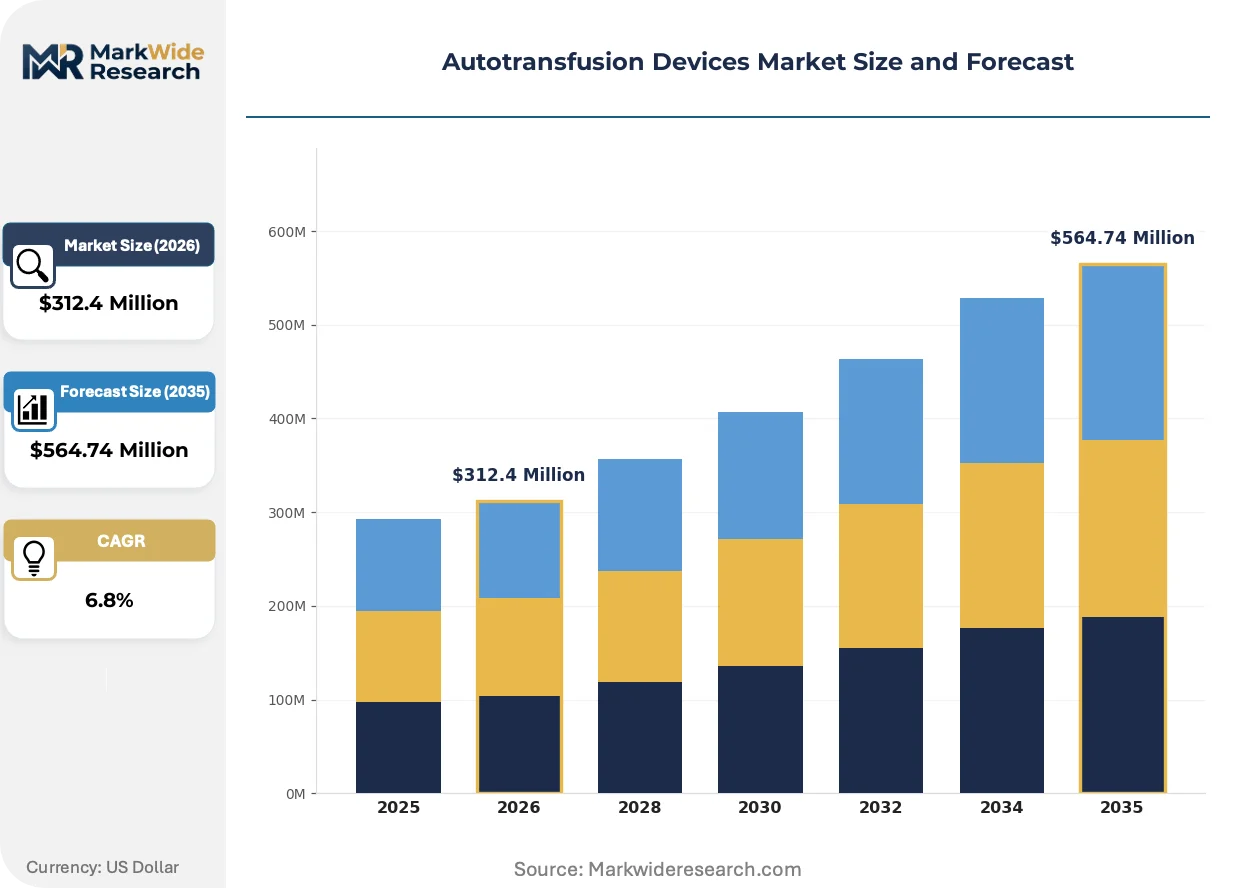
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cell Salvage Systems, Blood Filters, Surgical Suction Devices, Autotransfusion Pumps Application: Cardiac Surgery, Orthopedic Surgery, Trauma Surgery, Transplant Surgery End User: Hospitals, Clinics, Surgical Centers, Blood Banks Technology: Gravity-Based Systems, Vacuum-Assisted Systems, Static Systems, Automated Systems |
| Companies Covered | Medtronic plc, Teleflex Incorporated, Haemonetics Corporation, Braile Biomedica, Beijing ZKSK Technology, LivaNova PLC, Becton, Dickinson and Company, Redax, Fresenius Kabi AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Autotransfusion Devices Market Emerging Trajectories
Device architecture is fragmenting from monolithic platforms toward configurable subsystems that hospitals mix based on surgical volume and specialty mix, disrupting traditional bundled equipment sales.
Continuous-flow washing technology is modularizing the cell salvage process by separating blood concentration, washing, and reinfusion into discrete, upgradeable components. Mid-tier hospitals in the United States are adopting two-stage configurations initially, then expanding to full automation as cardiac surgery volumes justify capital deployment. This modularization is compressing replacement cycles and enabling vendors to capture recurring revenue through staged capability unlocks rather than single-unit transactions.
EU MDR's Unique Device Identification mandates are forcing manufacturers to reengineer labeling and traceability systems across entire product portfolios. The regulation's economic operator requirements are disqualifying distributors lacking qualified regulatory personnel, consolidating channel access for established suppliers with European infrastructure. Class IIb blood-processing devices face the steepest compliance burden, with notified body capacity constraints extending technical documentation review timelines.
Hospital supply committees are unbundling autotransfusion service contracts from equipment procurement, separating preventive maintenance, disposable supply, and clinical training into competitively bid components. Integrated delivery networks in the United States are driving this disintermediation, using purchasing scale to force vendors into transparent cost-plus pricing for consumables. Orthopedic surgery service lines show the most aggressive unbundling behavior, treating cell salvage as a commodity utility rather than integrated platform sale.
Autotransfusion Devices Market Segmentation
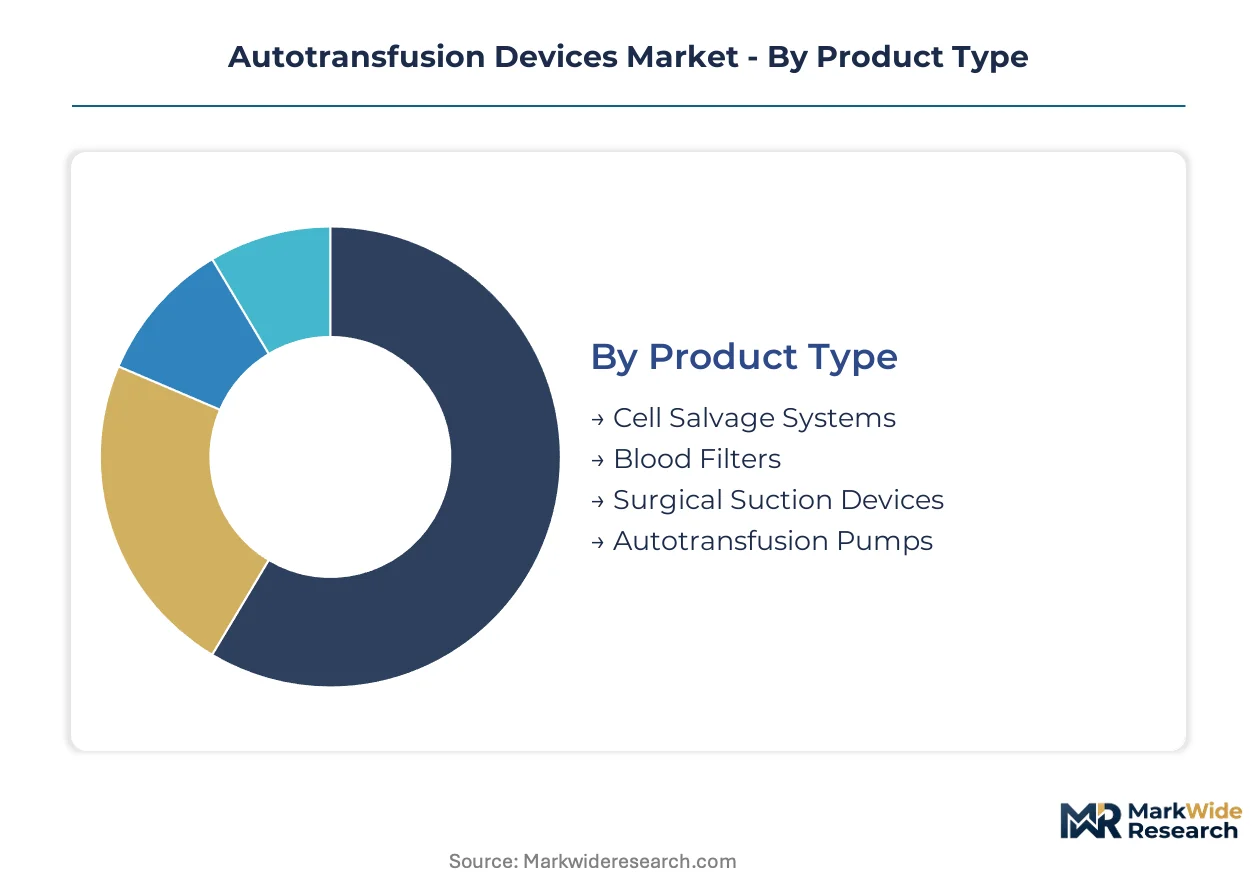
Autotransfusion device procurement varies sharply by surgical setting and capital intensity, with hospital supply committees applying distinct evaluation criteria across cardiac versus orthopedic service lines. Technology sophistication and consumable economics drive divergent adoption patterns between academic medical centers and freestanding surgical facilities.
Product Type:
Capital allocation authority determines which hardware categories penetrate specific hospital tiers, with automated platforms requiring centralized committee approval while consumables flow through departmental budgets.
- Cell Salvage Systems:Centrifugal washing platforms process shed blood at rotational speeds exceeding 5,000 RPM to yield washed red cell concentrates with hematocrit levels of 50-60%. Demand concentrates in United States tertiary hospitals expanding cardiac surgery programs to reduce allogeneic blood exposure amid tightening FDA 510(k) validation requirements.
- Blood Filters:Leukocyte depletion and microaggregate filtration devices serve as downstream processing components in reinfusion circuits. Orthopedic surgery departments in integrated delivery networks deploy these as lower-cost alternatives to full cell salvage for procedures with moderate blood loss profiles.
- Surgical Suction Devices:Vacuum-assisted collection systems capture shed blood from surgical fields for subsequent processing.
- Autotransfusion Pumps:Controlled reinfusion mechanisms deliver processed blood back to the patient at regulated flow rates.
Volume sits with cell salvage systems; growth tilts toward autotransfusion pumps as ambulatory surgery centers seek compact reinfusion solutions.
Application:
Surgical specialty dictates device configuration complexity, with open-chest procedures requiring full centrifugal washing while arthroscopic applications tolerate simpler filtration-based recovery.
- Cardiac Surgery:Cardiopulmonary bypass and valve replacement procedures generate substantial shed blood volumes requiring intraoperative recovery. United States academic medical centers anchor demand as perfusionist-staffed programs expand autotransfusion protocols to reduce transfusion-related complications.
- Orthopedic Surgery:Joint replacement and spine procedures increasingly embed blood conservation into enhanced recovery after surgery protocols. Tertiary hospitals in the United States are standardizing cell salvage deployment across high-volume arthroplasty service lines to support hemoglobin conservation targets.
- Trauma Surgery:Emergency settings with unpredictable bleeding patterns require rapid-deployment autotransfusion capability.
- Transplant Surgery:Organ procurement and implantation procedures utilize patient-specific blood recovery to preserve allogeneic inventory.
Revenue concentrates in cardiac applications; orthopedic surgery is gaining share fastest as bundled payment models incentivize transfusion reduction.
End User:
Facility scale determines whether autotransfusion operates as capital equipment purchase or outsourced service contract, reshaping vendor go-to-market economics.
- Hospitals:Multi-specialty institutions with cardiac surgery programs maintain in-house perfusion capabilities and dedicated cell salvage infrastructure. Integrated delivery networks in the United States negotiate system-wide equipment and consumable contracts, compressing vendor margins while demanding standardized service protocols.
- Surgical Centers:Freestanding orthopedic and spine facilities represent an underpenetrated channel seeking compact, cart-based systems with reduced footprint and operator dependency.
- Clinics:Limited surgical volume restricts autotransfusion deployment to referral relationships with hospital-based programs.
- Blood Banks:Collection and processing facilities utilize autotransfusion technologies for donor blood management rather than intraoperative recovery.
Installed base dominance rests with hospitals; surgical centers are climbing the fastest as outpatient migration accelerates.
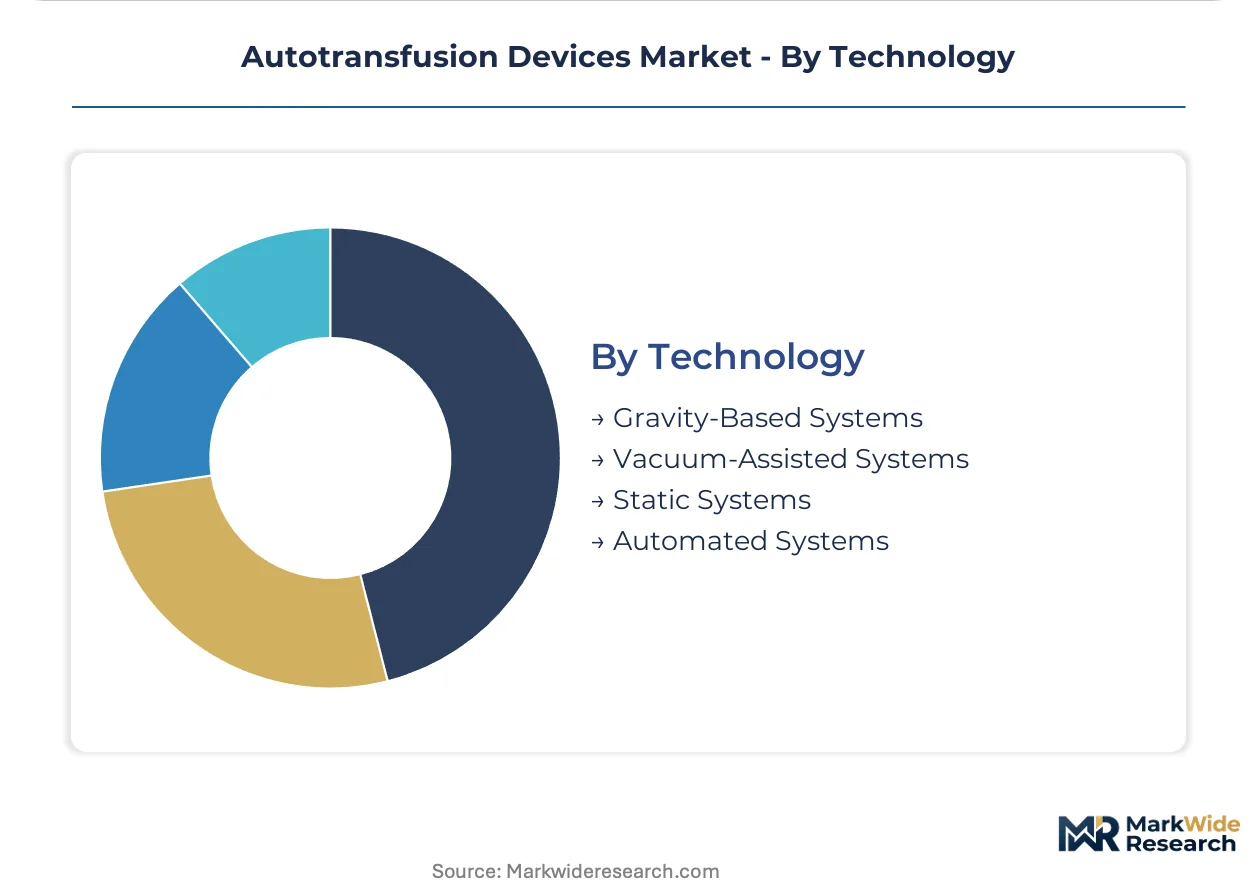
Technology:
Automation intensity separates premium platforms from commodity alternatives, with closed-loop monitoring commanding price premiums in high-complexity settings.
- Automated Systems:Closed-loop hematocrit monitoring and standardized wash protocols reduce operator training burdens and enable deployment beyond specialized perfusionist staff. Mid-tier United States hospitals are adopting these platforms to expand cell salvage into general surgery service lines previously dependent on allogeneic transfusion.
- Vacuum-Assisted Systems:Negative pressure collection mechanisms enable rapid blood recovery from surgical fields without centrifugal processing. Cost-sensitive procurement channels in manufacturing-scale supply regions favor these systems for their lower capital intensity and reduced consumable lock-in.
- Gravity-Based Systems:Passive collection relies on height differentials for blood transfer without mechanical pumping.
- Static Systems:Non-continuous processing holds collected blood for batch washing or direct reinfusion.
Deployment volume favors vacuum-assisted systems; automated platforms are expanding most quickly as labor scarcity drives capital substitution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special Economic Zones in China's Jiangsu and Guangdong provinces concentrate autotransfusion device manufacturing capacity through tax incentives and streamlined customs processing for medical device exporters.
United States
Integrated delivery networks in Texas and California negotiate system-wide autotransfusion contracts that compress vendor margins while mandating standardized service protocols across multi-hospital footprints. FDA 510(k) clearance timelines for blood-processing devices now require expanded clinical validation datasets, elevating regulatory barriers for novel entrants. The Cleveland Clinic and Mayo Clinic anchor demand in Ohio and Minnesota as academic medical centers expand perfusionist-staffed cardiac surgery programs.
Germany
EU MDR conformity assessments for Class IIb blood-processing devices extend technical documentation review timelines as notified body capacity constraints persist through the 2024-2026 transition window. The country's national pharmaceutical regulator enforces stricter post-market surveillance requirements that accelerate hospital replacement cycles for legacy cell salvage hardware. Industrial concentration clusters around Munich and Stuttgart where precision engineering capabilities support centrifugal washing platform manufacturing.
China
Manufacturing-scale supply regions in Jiangsu and Zhejiang provinces export vacuum-assisted autotransfusion systems to cost-sensitive procurement channels across Southeast Asia and Latin America. The National Medical Products Administration tightens premarket validation requirements for blood-processing devices under revised medical device registration rules. Beijing ZKSK Technology anchors production in the capital region, supplying domestic hospitals and export markets with reduced-capital-intensity platforms.
Japan
Specialized perfusionist training programs at Tokyo and Osaka academic medical centers concentrate intraoperative blood recovery expertise, limiting deployment scalability to community hospitals. The Ministry of Economy, Trade and Industry promotes domestic manufacturing of critical medical devices through supply chain resilience initiatives. Kansai region hospitals in Osaka and Kyoto standardize autotransfusion protocols for aging population joint replacement volumes.
United Kingdom
NHS England bundled payment models for orthopedic surgery incentivize hemoglobin conservation through cell salvage deployment across high-volume arthroplasty service lines. The Medicines and Healthcare products Regulatory Agency aligns post-Brexit device regulations with EU MDR standards, maintaining conformity assessment complexity. London and Manchester tertiary hospitals anchor demand as cardiac surgery programs expand autotransfusion adoption to reduce allogeneic transfusion dependency.
Autotransfusion Devices Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across a tiered vendor structure where scale advantages clash with service responsiveness. The market fragments across three strategic layers: diversified medical technology portfolios spanning perfusion and blood management, specialized hematology workflow providers, and manufacturing-scale suppliers from cost-competitive production regions. Consolidation pressure intensifies as integrated delivery networks demand transparent cost-plus pricing, while technology licensing agreements proliferate for centrifugal washing automation.
Among diversified medical technology conglomerates, Medtronic plc and LivaNova PLC exemplify portfolio breadth that sustains service contract penetration across major hospital systems. Haemonetics Corporation occupies a specialist position within blood management workflow integration. Beijing ZKSK Technology represents the manufacturing-scale archetype, leveraging production economics to supply vacuum-assisted platforms to price-sensitive procurement channels.
| Leading Market Players |
|---|
| Medtronic plc |
| Teleflex Incorporated |
| Haemonetics Corporation |
| Braile Biomedica |
| Beijing ZKSK Technology |
| LivaNova PLC |
| Becton, Dickinson and Company |
| Redax |
| Fresenius Kabi AG |
| Others |
Supply Flow & Price Mechanics
Continuous-flow washing technology modularization is compressing equipment replacement cycles while simultaneously fragmenting vendor pricing power and dispersing manufacturing concentration across tiered supplier networks. This production-method transition enables hospitals to stage capital deployment but forces manufacturers into recurring revenue models with compressed upfront margins.
Pricing Analysis
Short lead-time premiums dominate contract negotiations as integrated delivery networks demand rapid deployment for EU MDR compliance deadlines while spot inventory of legacy cell salvage hardware trades at steep discounts. The market operates on a three-tier pricing structure across premium automated platforms, standard centrifugal systems, and economy vacuum-assisted alternatives, with price differentiation driven by FDA 510(k) certification tier and after-sales service bundling. Cost compression in the economy tier is intensifying because Beijing ZKSK Technology and manufacturing-scale suppliers from Jiangsu province are flooding cost-sensitive procurement channels. Orthopedic surgery departments within integrated delivery networks exhibit the highest price sensitivity due to bundled payment constraints, while cardiac surgery programs at academic medical centers show the least sensitivity given perfusionist staffing requirements and outcome-based purchasing mandates.
Supply Chain Analysis
Reverse logistics flows for refurbished cell salvage components and remanufactured centrifugal bowls are gaining traction as EU MDR Unique Device Identification mandates force traceability investments that extend hardware lifecycles. Supply concentrates in Germany for precision-engineered centrifugal washing platforms, China for vacuum-assisted system manufacturing, and the United States for automated platform final assembly. Component sourcing draws from Japanese precision motors, Swiss medical-grade plastics, and Taiwanese electronic control modules. Single-source vulnerability in notified body capacity for Class IIb device conformity assessments presents structural supply chain risk. Distribution runs through integrated delivery network procurement committees in the United States, specialized medical device distributors in Europe, and direct hospital relationships in cost-sensitive Asian markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is becoming a vertical-integration race as manufacturers pursue captive production of proprietary wash sets and suction collection reservoirs to escape consumable margin compression by integrated delivery networks.
For Market Incumbents: Extend service contract penetration through embedded biomedical engineer staffing at major hospital systems, defending against modular subsystem competitors by locking in multi-year preventive maintenance agreements. Backward integration into sterile disposable manufacturing secures margin control as GPO contracts force transparent cost-plus pricing on consumables. Priority certification investment in EU MDR technical documentation preserves European channel access amid notified body capacity constraints. For New Entrants and Emerging Players: Launch via direct-to-hospital sales models targeting freestanding ambulatory surgery centers in Texas and Florida, bypassing integrated delivery network procurement committees that favor incumbent relationships. Orthopedic spine facilities represent the most penetrable segment given their isolation from academic medical center perfusionist networks and appetite for compact cart-based systems. White-space opportunity concentrates in automated platforms with closed-loop hematocrit monitoring for mid-tier community hospitals seeking labor substitution. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to diversified medical technology conglomerates seeking perfusion portfolio breadth, with IPO viability limited by concentrated customer purchasing power. Acquisition target archetype: mid-tier automated system developers with FDA 510(k) clearances and installed bases at regional hospital chains. Watch FDA premarket validation dataset expansion timelines as inflection indicator for development burn rate pressure on emerging players.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Technical Documentation Investment | Accelerates hospital replacement cycles for legacy cell salvage hardware ahead of stricter post-market surveillance. |
| Proprietary Consumable Manufacturing Integration | Captures recurring revenue streams from wash sets and suction reservoirs under transparent GPO pricing pressure. |
| Ambulatory Surgery Center Distribution Partnership | Unlocks underpenetrated freestanding orthopedic facilities seeking compact cart-based deployment. |
| Closed-Loop Hematocrit Monitoring Development | Reduces operator training burdens and expands addressable market beyond specialized perfusionist staff. |
| Hospital System Preventive Maintenance Contracting | Locks in multi-year revenue visibility against modular subsystem competitors fragmenting equipment sales. |
Methodological Framework
Multi-period observation of FDA 510(k) clearance timelines, EU MDR notified body capacity constraints, and integrated delivery network contract structures anchored the trend analysis, supplemented by interviews with perfusionists, hospital purchasing committee directors, biomedical engineers, GPO contracts managers, and cell salvage equipment service technicians. Secondary validation drew from FDA 510(k) database filings, EU MDR technical documentation review records, hospital procurement databases, GPO contract disclosure filings, and CMS Medicare transfusion utilization data. Bottom-up triangulation across surgical volume projections and equipment replacement cycles converged with top-down assessment of blood management workflow expenditure patterns.
Segment-weighting approaches distributed value estimates across product type, application specialty, end-user facility tier, and technology automation intensity, with regional adjustments for regulatory compliance cost differentials. CAGRs were derived from surgical procedure volume elasticity to autotransfusion adoption rates, cross-referenced against capital equipment depreciation schedules and consumable utilization per procedure. Forecast inputs incorporated perfusionist workforce supply constraints, bundled payment model penetration rates, and EPA liquid medical waste disposal regulatory pressure.
The model assumes a particular technology adoption path; alternative pathways for vacuum-assisted system dominance in cost-sensitive procurement channels would alter the outlook toward lower-margin, higher-volume equipment flows. Forecasts reflect assumptions regarding EU MDR transition timeline adherence, integrated delivery network purchasing consolidation trajectories, and orthopedic surgery outpatient migration rates. Practitioners should monitor FDA premarket validation requirement expansions, notified body capacity availability for Class IIb submissions, and integrated delivery network unbundling behavior for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Bare Metal Stents Market
Medical Devices
Continuous Passive Motion Devices Market
Medical Devices
Auto Keratometer Market
Medical Devices
Image-Based Cytometer Market
Medical Devices
Hearing Devices 3D Printing Market
Medical Devices
Spinal Implant Market
Medical Devices
Digital Slit Lamp Market
Medical Devices
Nanomedical Devices Market
Medical Devices
Thoracolumbar Spine Devices Market
Medical Devices
Infertility Treatment Devices Market
Medical Devices
Heating Pads Market
Medical Devices
Saudi Arabia Minimally Invasive Surgery Devices Market
Medical Devices
Sentinel Node Biopsy Market
Medical Devices
Cranial Navigation Systems Market
Medical Devices
Global Tympanostomy Products Market
Medical Devices
Robotic Catheterization Systems Market