
 Chickpea Milk Market | 2026-2036
Chickpea Milk Market Size, Share, and Industry Trends Forecast 2026-2036
Chickpea Milk Market Insights
Barista-grade specification tiers are redrawing competitive boundaries in chickpea milk. Califia Farms leverages its established plant-based beverage infrastructure to extend into premium café channels. Yofiit specializes in high-protein formulations that anchor its position among athletic and wellness-oriented consumers. Danone competes through its global dairy-alternative distribution network, sustaining shelf presence across European retail.
Chickpea milk is an aqueous extraction of Cicer arietinum seed protein and lipid fractions, typically processed through wet milling, enzymatic hydrolysis, and homogenization to achieve emulsion stability between 2.5-4.0% protein content and neutral pH. Its primary commercial purpose is to serve as a functional dairy alternative with superior foaming stability and lower allergenicity profile than nut or soy milks. Unsweetened and barista blend product types occupy the fastest-growing margin pools as consumers prioritize clean-label formulations with minimal additive content. Foodservice operators represent the most concentrated demand channel, while retail consumers drive volume through e-commerce subscription models.
FDA enforcement of dairy identity standards and EFSA novel food authorization requirements shape formulation choices and market entry timelines for new entrants. The EU Green Deal's sustainable protein targets and REACH compliance for processing aids further constrain ingredient sourcing flexibility. Stakeholders must monitor evolving allergen threshold regulations and carbon labeling mandates that will determine which processing locations and supply configurations retain competitive access.
Market Dynamics
Barista-grade formulation specifications are compressing margins for commodity-grade producers while rewarding processors capable of delivering stable foam microstructure and neutral flavor profiles at scale. FDA dairy identity standard enforcement and EFSA novel food authorization timelines are forcing reformulation cycles that favor established players with regulatory affairs infrastructure.
Growth Catalysts
- Specialty coffee channel expansion:Third-wave cafés in Portland, Melbourne, and Berlin are standardizing chickpea milk on their permanent menus, creating predictable offtake volumes that justify dedicated production lines.
- REACH-compliant processing aid innovation:Enzyme suppliers have secured ECHA authorization for novel hydrolases that reduce bitterness without synthetic additives, unlocking cleaner-label positioning in EU retail.
- Clean-label protein diversification:Athletic nutrition formulators are substituting chickpea isolate for whey and soy in ready-to-drink applications, driven by allergen-free positioning and digestibility claims.
Market Restraints
- Chickpea concentrate supply concentration:Over 60% of commercial-grade Cicer arietinum protein isolate originates from processing clusters in Saskatchewan and Punjab, creating geographic vulnerability to climate and trade disruption.
- Novel food authorization friction:EFSA's 18-24 month safety assessment timeline for new extraction methods delays product launches and ties up working capital in regulatory dossiers.
- Oat milk substitution pressure:Established oat-based barista formulations command lower unit costs and deeper retail distribution, compressing chickpea milk's addressable premium segment.
Strategic Opportunities
- South Korean café market penetration:Seoul's specialty coffee density and MFDS's streamlined novel food pathway for legume-derived beverages create faster regulatory clearance than EU or US equivalents.
- Sports nutrition RTD convergence:Formulators combining chickpea protein with tart cherry and electrolyte complexes can access the post-workout recovery segment with dual-function positioning.
- EU Green Deal protein procurement mandates:Public sector foodservice contracts in Germany and the Netherlands now specify domestic sustainable protein sourcing, favoring European chickpea processing investments.
Industry Challenges
- Emulsion stability expertise scarcity:Food technologists capable of optimizing homogenization parameters for 2.5-4.0% protein chickpea emulsions command premium compensation, constraining scale-up timelines for new entrants.
- Dual certification burden:Simultaneous pursuit of USDA Organic and EU organic equivalence requires parallel audit trails and segregated supply chains, multiplying compliance overhead.
- Legacy dairy equipment retrofit complexity:UHT lines designed for cow's milk require substantial modification to handle chickpea emulsion viscosity and fouling profiles, extending capex deployment cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chickpea Milk Market |
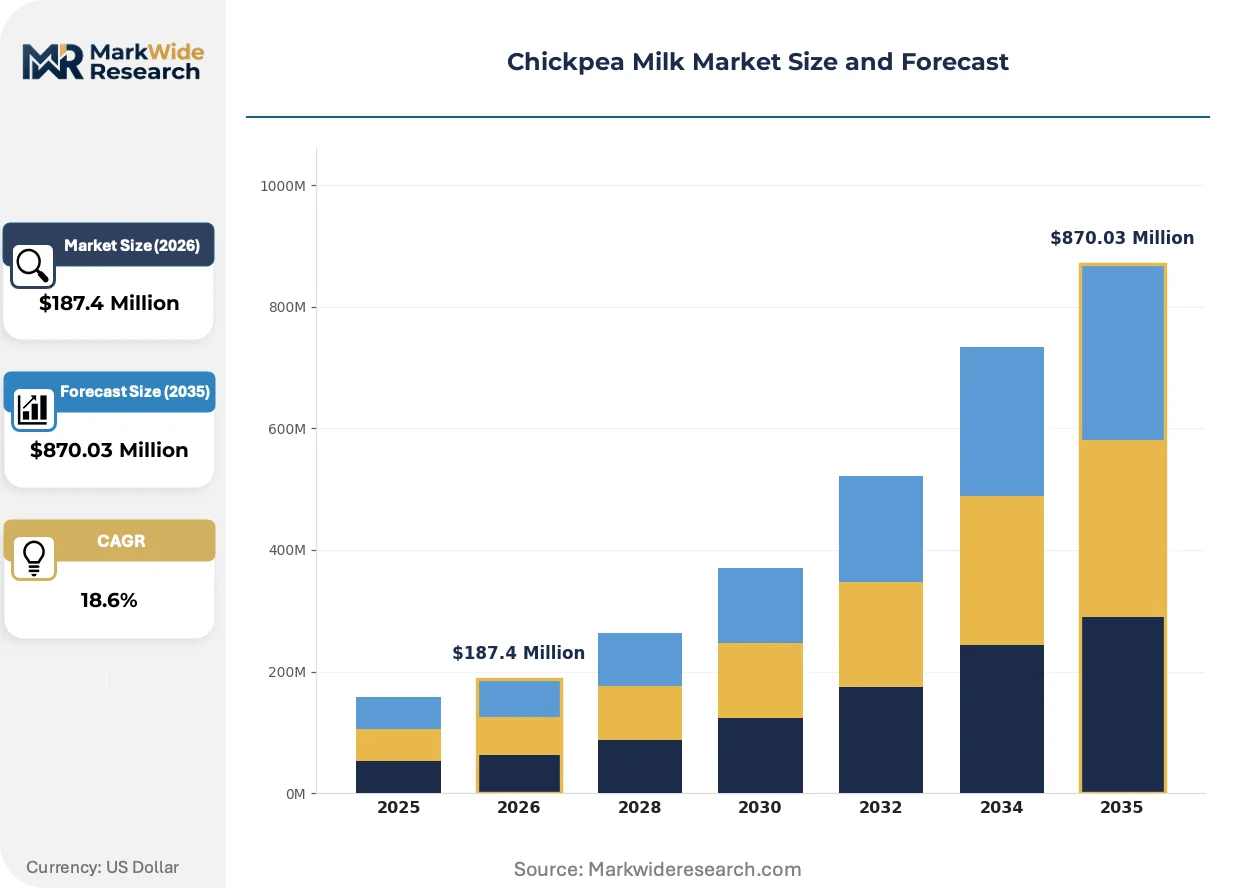
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $870.03 Million |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Original, Vanilla, Chocolate, Unsweetened, Barista Blend Application: Beverages, Baking, Cooking, Dairy Alternatives, Nutritional Supplements Packaging Type: Tetra Pak, Glass Bottle, Plastic Bottle, Carton, Bag-in-Box End User: Retail Consumers, Foodservice Operators, Hospitality Chains, Institutional Buyers |
| Companies Covered | Califia Farms, Yofi, Yofiit, EPIC'C, Tally Foods, Star Plants, Nestlé, Danone, Ripple Foods, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chickpea Milk Market Trends and Innovations
Enzymatic hydrolysis protocols and precision fermentation adjacencies are rewriting the technical frontier for legume-derived beverages. Formulators now prioritize functional performance metrics over ingredient origin storytelling.
High-pressure processing is bifurcating the clean-label segment from conventional UHT-stabilized products. Premium refrigerated brands in California and New South Wales are adopting HPP to eliminate thermal degradation of volatile flavor compounds. This technology is compressing shelf-life expectations to 30-45 days while enabling "raw" positioning that commands 40-60% price premiums over ambient-stable alternatives.
EFSA's updated guidance on legume allergen threshold labeling is forcing disclosure granularity that exceeds FDA requirements. Manufacturers must now quantify residual albumin fractions in finished beverages, not just declare presence. German and Dutch retailers are responding by demanding batch-level allergen certificates that extend supplier qualification timelines by 8-12 weeks.
Direct-to-café subscription models are displacing traditional foodservice distribution in urban density zones. Roasters in London, Toronto, and Sydney are negotiating quarterly chickpea milk supply contracts with processors, bypassing broadline distributors. This channel shift concentrates volume with vertically integrated suppliers capable of managing logistics complexity and quality consistency at 50-200 liter weekly drops.
Chickpea Milk Market Segmentation
Chickpea milk segmentation reflects divergent technical requirements across formulation stability, thermal processing compatibility, and channel-specific certification demands. Each dimension carries distinct margin profiles and regulatory exposure that reshape competitive positioning.
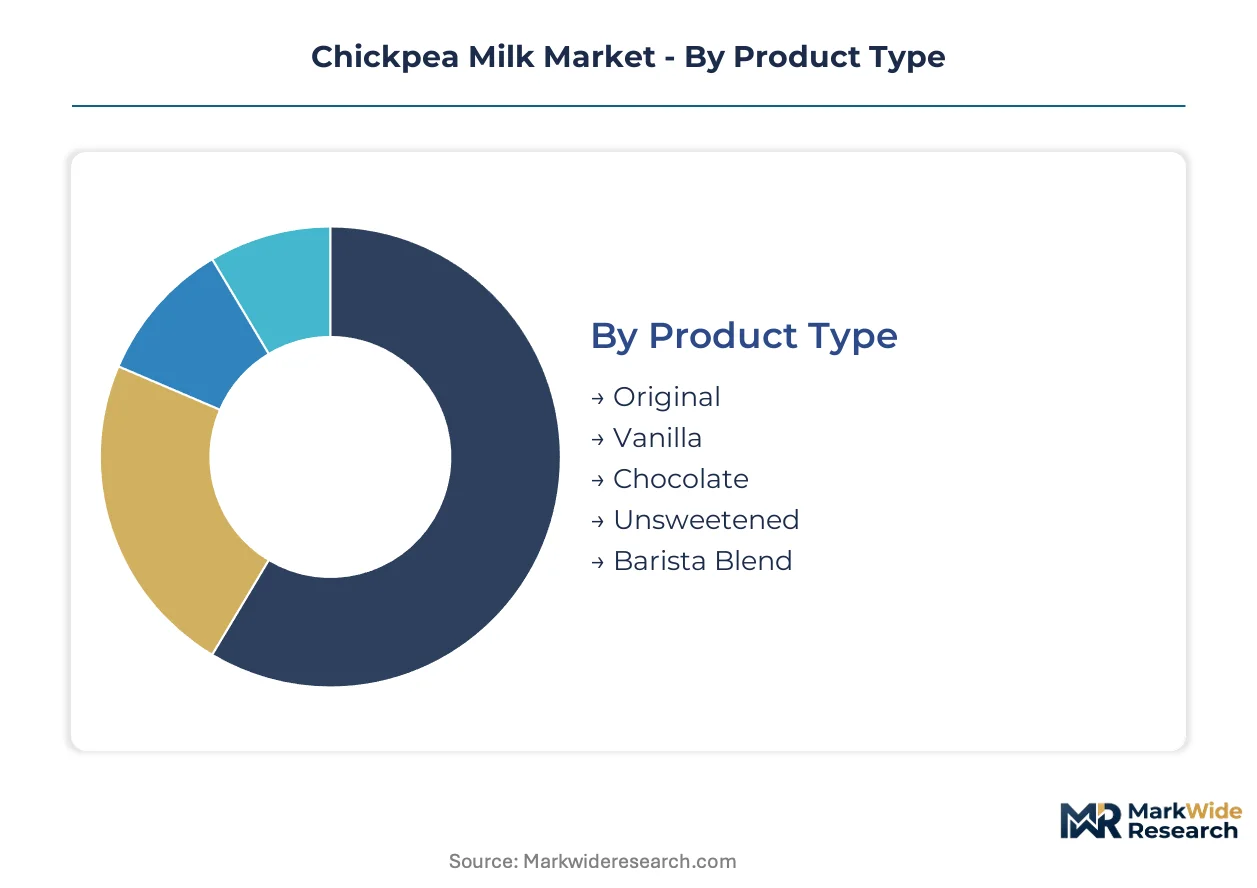
Product Type:
FDA dairy identity standards and EFSA novel food thresholds create divergent formulation burdens across sweetness and functional tiers, with unsweetened variants facing stricter protein content verification.
- Original:Standard formulation with 2.5-3.5% protein content and minimal additive load. Retail consumers in Germany and Australia drive volume through supermarket private-label programs seeking oat milk alternatives.
- Vanilla:Flavored variant with natural vanilla extract and elevated sweetness profile. Foodservice operators in Portland and Melbourne specify this tier for specialty coffee applications where flavor masking improves acceptance.
- Chocolate:Cocoa-fortified formulation targeting pediatric and sports nutrition segments. Athletic nutrition formulators in the United States combine this base with electrolyte complexes for post-workout positioning.
- Unsweetened:Zero-added-sugar formulation with neutral pH and clean-label certification. EFSA allergen disclosure requirements for residual albumin fractions impose batch-level testing burdens that extend supplier qualification timelines.
- Barista Blend:High-protein specification engineered for foam microstructure stability and steam resilience. Third-wave cafés in Berlin and Sydney standardize this tier on permanent menus, creating predictable offtake volumes that justify dedicated production lines.
Established volume favors Original; emerging adoption favors Barista Blend.
Application:
Cost tier differentiation separates commodity ingredient supply from premium functional positioning, with nutritional supplements commanding formulation expertise premiums.
- Beverages:Ready-to-drink format dominating retail and foodservice channels. High-pressure processing adopters in California and New South Wales compress shelf-life to 30-45 days while commanding 40-60% price premiums over UHT alternatives.
- Baking:Viscosity-modified formulations replacing dairy in commercial bakery operations. REACH-compliant enzyme suppliers enable cleaner-label positioning in EU retail through authorized hydrolases that reduce bitterness.
- Cooking:Heat-stable emulsions for sauce and soup applications. Institutional buyers in Germany specify this tier under EU Green Deal protein procurement mandates favoring domestic sustainable sourcing.
- Dairy Alternatives:Direct milk replacement across cereal, smoothie, and culinary use cases. Retail consumers in the United States drive volume through e-commerce subscription models.
- Nutritional Supplements:Protein-isolate base for athletic and clinical nutrition formulations. Formulators combine chickpea protein with tart cherry and electrolyte complexes to access post-workout recovery segments.
Volume concentrates in Beverages; margin expansion concentrates in Nutritional Supplements.
Packaging Type:
Customer type dictates format selection, with foodservice operators prioritizing operational efficiency and retail consumers responding to sustainability signaling.
- Tetra Pak:Aseptic carton format dominating ambient retail distribution. Shelf-stable logistics enable broadline distributor penetration across North American and European grocery networks.
- Glass Bottle:Premium refrigerated format with reuse and recycling credentials. Specialty retailers in Berlin and Sydney specify this tier for clean-label positioning.
- Plastic Bottle:Cost-optimized format for high-volume retail channels. PET compatibility with existing dairy filling lines reduces capex barriers for legacy processors.
- Carton:Gable-top refrigerated format with shorter shelf-life expectations. Direct-to-café subscription models in London and Toronto favor this format for 50-200 liter weekly drops.
- Bag-in-Box:Bulk dispensing format for foodservice and institutional channels. Hospitality chains in the United States adopt this tier for back-of-house operational efficiency.
Tetra Pak holds installed base; Bag-in-Box gains foodservice traction.
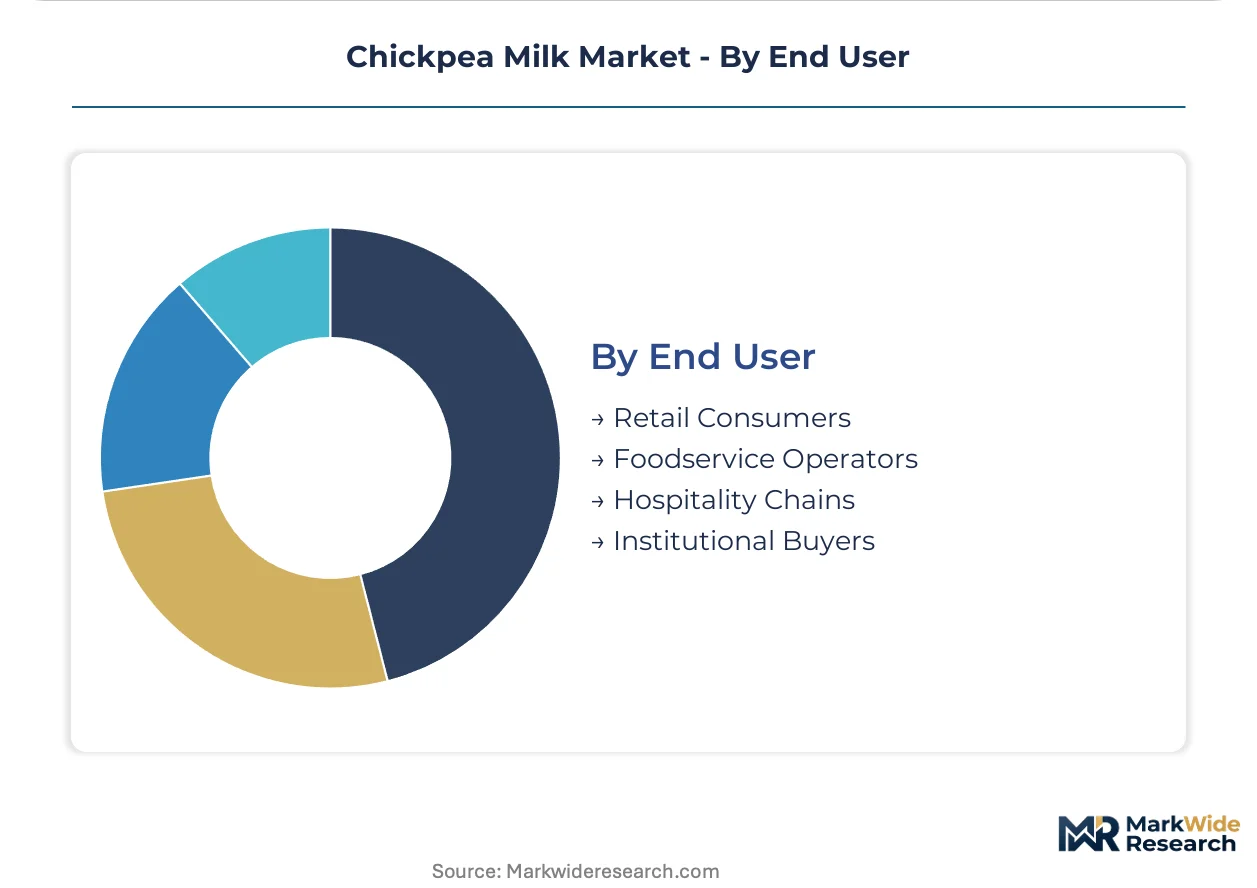
End User:
Supply concentration aligns with processing infrastructure location, with Saskatchewan and Punjab clusters serving divergent customer tiers.
- Retail Consumers:Individual purchasers through supermarkets, specialty stores, and e-commerce platforms. Clean-label preferences in Germany and Australia concentrate adoption clusters.
- Foodservice Operators:Independent cafés, restaurants, and catering operations. Third-wave coffee density in Portland, Melbourne, and Berlin creates predictable demand for barista-grade specifications.
- Hospitality Chains:Multi-unit restaurant and hotel groups with centralized procurement. Quarterly supply contracts bypass broadline distributors, concentrating volume with vertically integrated suppliers.
- Institutional Buyers:Schools, hospitals, and public sector foodservice operations. EU Green Deal procurement mandates in Germany and the Netherlands specify domestic sustainable protein sourcing.
Retail Consumers anchor volume; Institutional Buyers reshape procurement standards.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commercial-grade chickpea protein isolate flows predominantly from processing clusters in Saskatchewan and Punjab, creating geographic vulnerability that shapes procurement strategies across consuming markets. FDA dairy identity standards and EFSA novel food pathways generate divergent compliance burdens that advantage established regulatory affairs infrastructure. Third-wave café density in Portland, Melbourne, and Berlin anchors concentrated demand for barista-grade specifications.
United States
Specialty coffee channel expansion in Portland and Los Angeles drives predictable offtake volumes for barista-grade formulations. FDA enforcement of dairy identity standards forces protein content verification protocols that extend supplier qualification timelines. Clean-label preferences in California and New York concentrate adoption clusters for unsweetened variants through e-commerce subscription models.
Germany
EU Green Deal protein procurement mandates reshape institutional foodservice contracts toward domestic sustainable sourcing. EFSA novel food authorization timelines delay product launches while REACH-compliant enzyme suppliers unlock cleaner-label positioning. Berlin's third-wave café density standardizes chickpea milk on permanent menus, creating dedicated production line economics.
Australia
High-pressure processing adopters in New South Wales compress shelf-life expectations to 30-45 days while commanding premium pricing over UHT alternatives. TGA labeling requirements for allergen disclosures align with EFSA granularity standards. Melbourne's specialty coffee density creates predictable demand for foam-stable formulations.
South Korea
Seoul's specialty coffee density and streamlined MFDS novel food pathway for legume-derived beverages enable faster regulatory clearance than EU equivalents. Domestic processors leverage this regulatory arbitrage to supply adjacent Japanese and Southeast Asian markets. Barista-grade specifications gain traction among independent roasters negotiating direct supply contracts.
United Kingdom
Direct-to-café subscription models in London displace traditional foodservice distribution, concentrating volume with vertically integrated suppliers. EFSA-aligned allergen disclosure requirements extend supplier qualification timelines for continental suppliers. Clean-label preferences drive refrigerated format adoption through specialty retailers.
Chickpea Milk Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with formulation expertise for stable foam microstructure commanding premium positioning while commodity-grade processors compete on scale. The vendor base spans established plant-based beverage infrastructure extenders, high-protein specialists, and global dairy-alternative distribution networks. Three archetypes dominate: premium barista-grade specialists, mass-market retail extenders, and athletic nutrition formulators. Capacity expansion in Saskatchewan and Punjab processing clusters and strategic partnerships with enzyme suppliers for REACH-compliant processing aids represent the dominant competitive moves.
Among plant-based beverage infrastructure extenders, Califia Farms leverages its established production footprint to anchor premium café channel positioning. High-protein specialists Yofiit occupy the athletic and wellness-oriented consumer segment with formulation expertise. Global dairy-alternative networks Danone sustain shelf presence across European retail through existing distribution infrastructure. These three exemplify how regulatory affairs scale, functional formulation depth, and channel access create divergent competitive moats.
| Leading Market Players |
|---|
| Califia Farms |
| Yofi |
| Yofiit |
| EPIC'C |
| Tally Foods |
| Star Plants |
| Nestlé |
| Danone |
| Ripple Foods |
| Others |
Pricing and Supply Chain Analysis
Long-term offtake contracts between Saskatchewan processors and North American beverage manufacturers lock in both chickpea concentrate supply access and eighteen-month price visibility against spot market volatility. These arrangements insulate barista-grade formulators from Punjab crop cycle disruptions while embedding FDA protein verification costs into baseline pricing.
Pricing Analysis
EFSA novel food authorization dictates the pricing tier structure across EU markets, separating REACH-compliant enzyme-processed premiums from standard UHT formulations. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and volume scale, with HPP-treated refrigerated variants commanding the highest tier. Cost compression in commodity-grade ambient cartons is intensifying because oat milk substitutes erode addressable premium segments. Institutional buyers under EU Green Deal mandates exhibit lowest price sensitivity; retail private-label programs in Germany show highest.
Supply Chain Analysis
Strategic stockpile preferences dominate chickpea concentrate procurement, with processors maintaining 90-120 day inventory buffers against Saskatchewan and Punjab climate exposure. Commercial-grade Cicer arietinum protein isolate draws from these two processing clusters, with wet milling equipment and enzymatic hydrolysis capacity as critical inputs. Single-source vulnerability concentrates in Saskatchewan rail corridors connecting to Vancouver export terminals. Distribution runs through vertically integrated suppliers managing direct-to-café logistics in urban density zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Chickpea milk sits in early-cycle expansion, with specialty coffee channel penetration in Portland, Melbourne, and Berlin providing measurable adoption velocity that justifies dedicated production economics.
For Market Incumbents: Consolidate barista-grade formulation expertise through captive supply of Saskatchewan processing capacity, locking in foam stability specifications that oat milk substitutes cannot replicate. Defend against emerging high-pressure processing entrants by securing HPP equipment partnerships in California and New South Wales. Prioritize EFSA regulatory affairs infrastructure to compress novel food authorization timelines relative to new entrants. For New Entrants and Emerging Players: MFDS streamlined novel food pathway offers fastest certification fast-track for legume-derived beverages, enabling Seoul-based market entry before EU or US equivalents. White-space targets include South Korean café market penetration and sports nutrition RTD convergence with tart cherry electrolyte positioning. Direct-to-café subscription models in London and Toronto provide lowest customer acquisition cost entry vector. For Investors and Strategic Acquirers: Enzyme supplier partnerships with REACH authorization represent the acquisition target archetype, capturing margin pools from cleaner-label positioning premiums. Long-term viability frames around sustainable protein procurement mandates hardening across EU public sector contracts. Watch EFSA allergen threshold labeling enforcement granularity as inflection indicator for supplier qualification timeline compression.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Saskatchewan | Captures concentrated Cicer arietinum processing infrastructure before climate vulnerability hardens. |
| REACH-Compliant Enzyme Partnership | Unlocks cleaner-label positioning in EU retail through ECHA-authorized hydrolase supply. |
| Direct-to-Café Distribution Launch | Bypasses broadline distributors in London, Toronto, and Sydney urban density zones. |
| High-Pressure Processing Adoption | Enables 40-60% price premiums in California and New South Wales refrigerated segments. |
| Barista-Grade Formulation R&D | Secures foam microstructure stability specifications demanded by third-wave cafés in Berlin. |
Research Methodology
Two parallel data streams informed the analysis: primary field engagement with foodservice procurement managers, plant-based beverage formulators, regulatory affairs specialists, and enzyme supplier technical directors; and secondary validation through FDA enforcement actions, EFSA novel food authorization databases, EU Green Deal procurement mandate documents, and customs trade flows for chickpea concentrate. Bottom-up volume triangulation across café channel offtake and retail scanner data intersected with top-down protein isolate production capacity estimates.
Across the analysis window, the forecasting framework modeled segmentation dimensions including product type tier, application category, packaging format, and end-user channel, with regional regulatory cluster as an additional industry-specific dimension. CAGRs derived from elasticity-adjusted adoption curves incorporating specialty coffee channel expansion rates and EFSA authorization timeline distributions. Forecast inputs included REACH-compliant enzyme availability and HPP equipment deployment pipelines.
Underlying assumptions cover sustained third-wave café menu standardization, with deviation risk concentrated in oat milk substitution acceleration and chickpea crop yield volatility. Revision becomes warranted when EFSA allergen disclosure granularity crosses thresholds that extend supplier qualification timelines beyond viable product launch windows.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Alternatives
Legumes Plant-Based Milk Market
Dairy Alternatives
Vegan Butter Market
Dairy Alternatives
Organic Milk Replacers Market
Dairy Alternatives
Savory Yogurt Market
Dairy Alternatives
North America Drinkable Yogurt Market
Dairy Alternatives
Soy Milk Market
Dairy Alternatives
Dairy-Free Smoothies Market
Dairy Alternatives
Low-Calorie Cream Market
Dairy Alternatives
Peanut Milk Market
Dairy Alternatives
Soy Milk Powder Market
Dairy Alternatives
Vegan Milk Alternatives Market
Dairy Alternatives
Europe Dairy Alternatives Market
Dairy Alternatives
Vegan Condensed Milk Market
Dairy Alternatives
Dairy-Free Creams Market
Dairy Alternatives
Australia Non-Dairy Milk Market
Dairy Alternatives
Dry Yogurt Market