
 Australia Non-Dairy Milk Market | 2026-2036
Australia Non-Dairy Milk Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Non-Dairy Milk Market Insights
Premium barista-grade formulations and commodity retail variants is decoupling across Australian shelves. Oatly Group AB leverages its café channel dominance to sustain premium positioning in Melbourne and Sydney espresso bars. Blue Diamond Growers anchors almond milk supply through established retail partnerships with Coles and Woolworths. Noumi Ltd differentiates its portfolio across both food service and supermarket segments.
Australia non-dairy milk denotes plant-based fluid beverages formulated from almonds, oats, soy, or coconut through enzymatic processing and homogenization to achieve protein stability and mouthfeel parity with bovine milk, serving lactose-intolerant consumers, vegan households, and commercial beverage applications. Almond milk occupies the largest volume share among product types, reflecting mature consumer familiarity and extensive retail distribution. Oat milk registers the fastest structural expansion, driven by barista-compatible foaming properties and sustainability positioning in food service channels.
FSANZ governs compositional standards and allergen labeling for plant-based beverages, while the ACCC monitors greenwashing claims that affect brand credibility and shelf access. The Health Star Rating system shapes reformulation incentives as manufacturers adjust sugar and calcium fortification to improve scores. Stakeholders must track pending FSANZ consultations on protein content descriptors and emerging ACCC enforcement patterns around environmental marketing claims.
Market Dynamics
Café-grade oat milk formulations are restructuring competitive positioning across Australian retail and food service channels. Barista-compatible foaming properties have created a dual-track market where specialty coffee venues command premium pricing while commodity retail variants compete on shelf placement.
Growth Catalysts
- FSANZ protein fortification standards:Calcium and vitamin D enrichment mandates drive reformulation investment, lifting nutritional parity credentials for plant-based beverages competing against dairy.
- Melbourne-Sydney café corridor density:Specialty coffee culture concentrates demand for barista-grade oat and almond variants, establishing format-specific purchasing patterns that propagate to retail.
- Enzymatic hydrolysis advances:Improved protein stability and mouthfeel engineering reduce sensory gaps with bovine milk, accelerating acceptance among flexitarian households.
Market Restraints
- Almond input cost volatility:California drought cycles and water allocation pressures transmit price instability through Blue Diamond supply contracts into Australian retail pricing.
- Single-origin oat supply concentration:Nordic and Australian domestic milling capacity limits constrain rapid volume scaling for food service expansion beyond metropolitan cores.
- ACCC greenwashing enforcement friction:Environmental marketing claim investigations create compliance uncertainty and shelf-access risk for brands with sustainability-forward positioning.
Strategic Opportunities
- Queensland and Western Australia retail penetration:Underdeveloped supermarket plant-based beverage sections in Brisbane corridors and Perth metro zones offer first-mover reset potential.
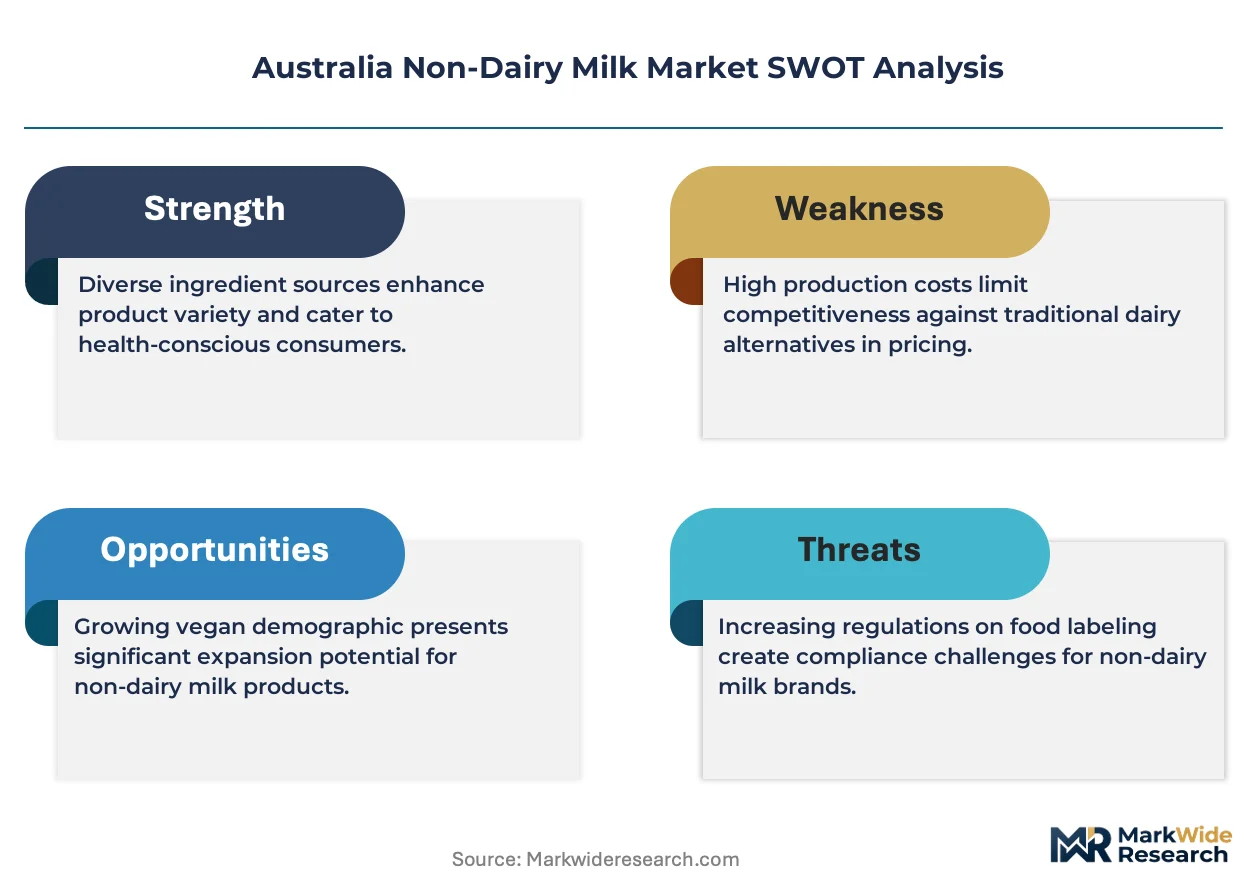
- Health Star Rating optimization:Sugar reduction and calcium fortification adjustments to improve front-of-pack scores unlock preferred shelf positioning in Woolworths and Coles planograms.
- Direct-to-café distribution platforms:Bypassing traditional wholesale intermediaries through refrigerated logistics partnerships with specialty roasters captures margin and relationship depth.
Industry Challenges
- Food technologist talent scarcity:Protein stabilization and emulsion chemistry expertise required for barista-grade formulation remains concentrated among limited specialist consultancies.
- FSANZ consultation timeline uncertainty:Pending protein content descriptor rulings delay label redesign cycles and NPD pipeline commitments.
- Cold chain reconfiguration capex:Refrigerated distribution infrastructure expansion to service café direct-delivery models demands capital deployment ahead of volume guarantees.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Non-Dairy Milk Market |
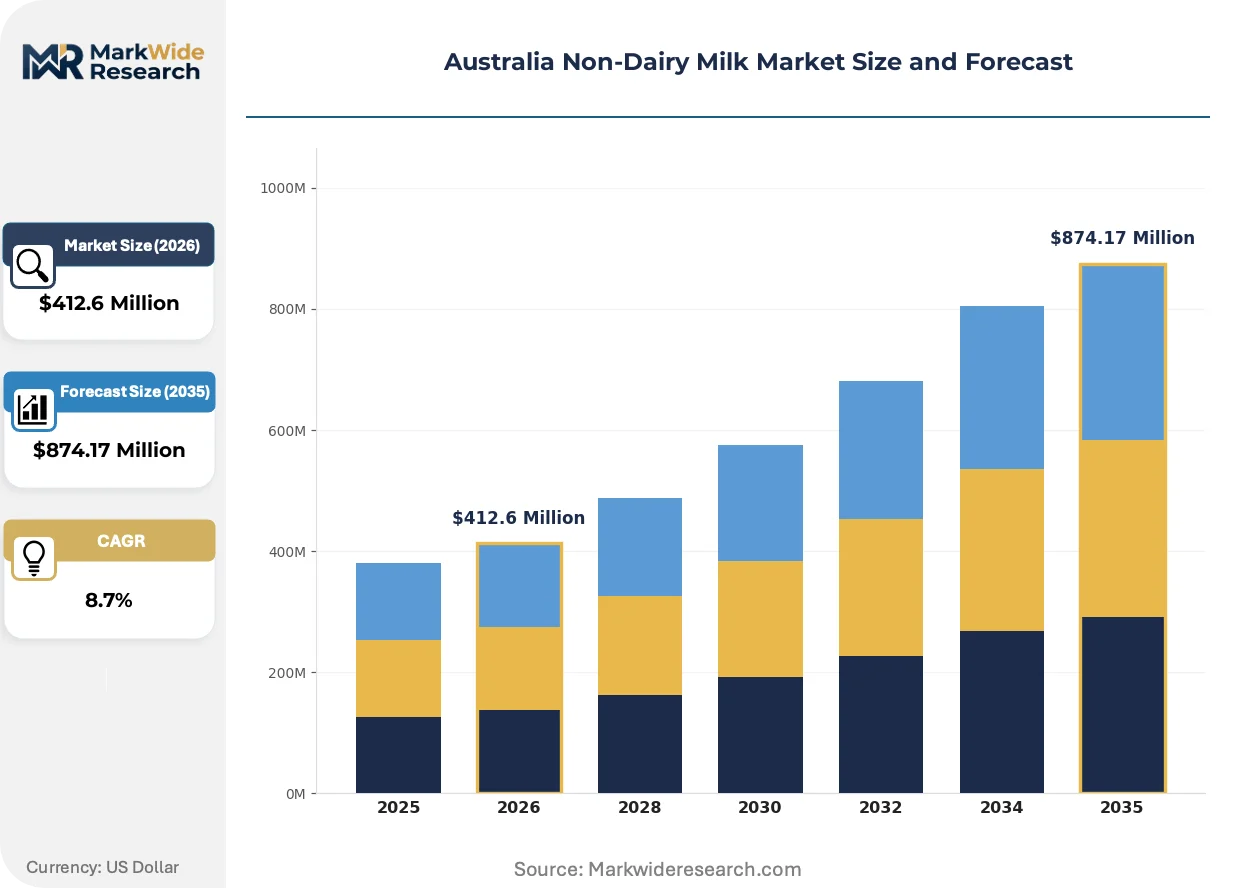
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $874.17 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Almond, Soy, Oat, Coconut Packaging Type: Bottle, Carton, Tetra Pack, Bag End User: Retail Consumers, Food Service, Restaurants, Cafés Distribution Channel: Online, Supermarket, Health Stores, Specialty Shops |
| Companies Covered | Sanitarium Health and Wellbeing Company, Blue Diamond Growers, Oatly Group AB, Vitasoy International Holdings Ltd, Noumi Ltd, Pureharvest Pty Ltd, Danone, Bonsoy, Milkadamia, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Non-Dairy Milk Market Trends and Innovations
Enzymatic processing and precision fermentation are converging to redefine protein quality benchmarks in plant-based beverages. These technical trajectories intersect with regulatory pressure on nutritional claims and shifting procurement patterns among Australian food service operators.
Precision fermentation-derived dairy proteins are expanding into Australian beverage formulation trials. Food technologists at specialty manufacturers are integrating these ingredients at pilot scale to enhance mouthfeel and amino acid completeness. The technology is expanding into premium positioning strategies as brands seek differentiation beyond conventional plant-based sourcing.
FSANZ allergen labeling mandates and Health Star Rating recalibration are tightening compositional transparency requirements. Manufacturers must reformulate sugar profiles and fortification levels to maintain competitive shelf scores. Small-to-mid scale producers with limited R&D bandwidth face disproportionate compliance burden relative to diversified portfolio players.
Café procurement patterns are consolidating around single-source supply partnerships with dedicated barista-grade providers. Independent Melbourne and Sydney espresso bars are locking in refrigerated direct delivery contracts, displacing traditional wholesale distributor relationships. This channel compression is most visible in inner-urban postcodes where specialty coffee density supports dedicated logistics economics.
Australia Non-Dairy Milk Market Segmentation
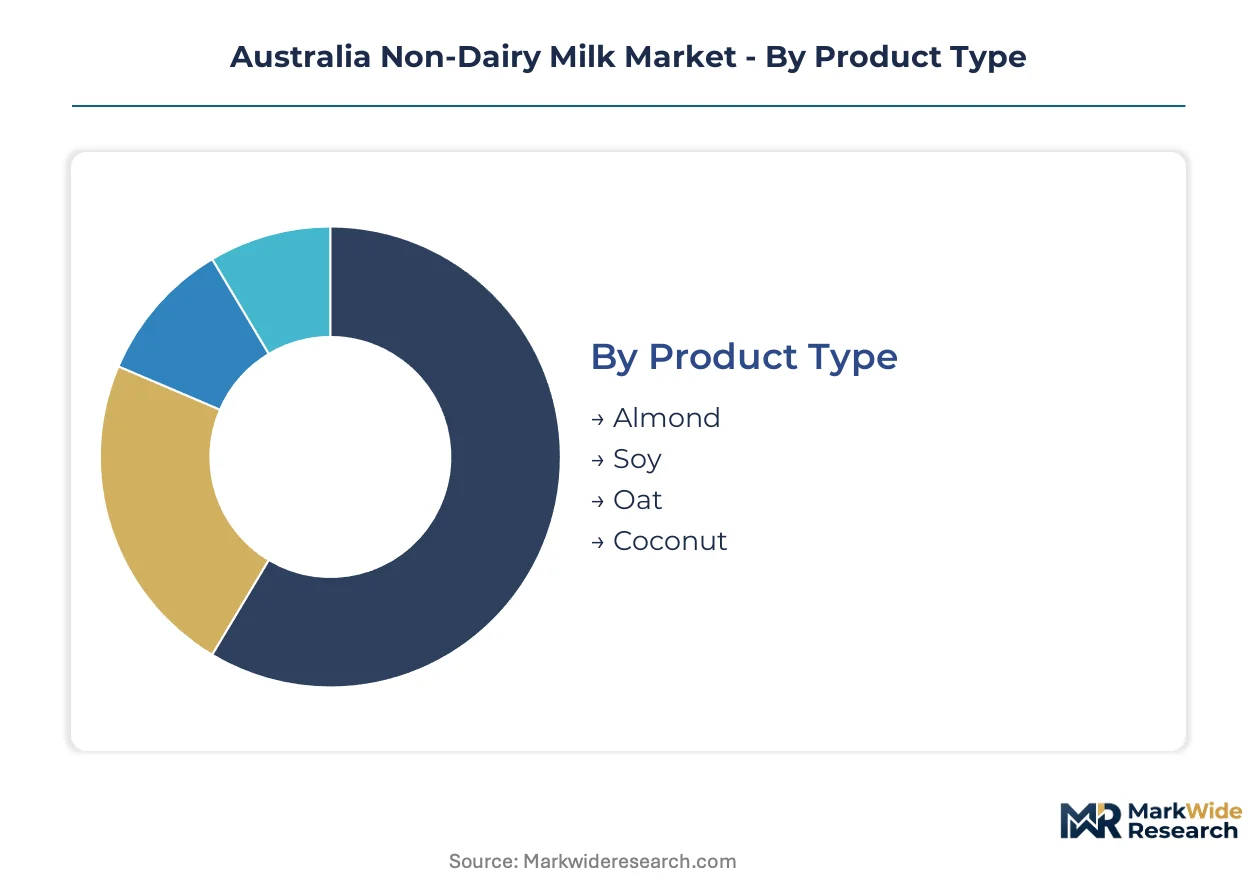
Segmentation in the Australia non-dairy milk market reveals how product formats, packaging economics, and channel access create distinct competitive arenas. Each dimension carries different margin profiles and regulatory exposure, shaping where manufacturers concentrate R&D and distribution investment.
Product Type:
Integration depth varies sharply across plant bases, with some formats engineered specifically for embedded café applications versus standalone retail consumption.
- Almond:Formulated through cold-press extraction and enzymatic stabilization to achieve neutral pH and extended shelf stability. Demand concentrates in Sydney and Melbourne supermarket corridors where retail familiarity drives household replenishment cycles, though California drought cycles transmit input cost volatility through contracted supply chains.
- Oat:Enzymatic hydrolysis of Nordic or domestic Australian milling oats produces beta-glucan-rich emulsions optimized for microfoam stability. Melbourne-Sydney espresso bars command premium pricing for barista-grade formulations, establishing format-specific purchasing patterns that propagate to retail shelves.
- Soy:Longest-established plant base with mature FSANZ compositional precedent and established calcium fortification protocols.
- Coconut:Higher fat content suits dessert applications and tropical-climate consumption preferences in Queensland corridors.
Almond leads volumes today; oat is gaining share fastest.
Packaging Type:
Cost tier differentiation separates premium chilled formats from ambient-stable commodity packaging, with cold chain requirements determining channel accessibility.
- Carton:Aseptic brick packaging dominates Woolworths and Coles ambient shelves, balancing shelf life extension against unit economics. Brisbane and Perth supermarket resets favor carton placement for volume SKUs where refrigerated infrastructure remains limited.
- Bottle:Chilled PET or HDPE formats command premium positioning in health store and specialty shop channels, requiring continuous cold chain maintenance that restricts distribution radius.
- Tetra Pack:Extended shelf-life variants serve export-adjacent production and remote regional penetration where logistics intermittency demands ambient stability.
- Bag:Bulk food service formats reduce per-liter packaging cost for high-volume café and restaurant procurement, though FSANZ allergen labeling requirements complicate refill station compliance.
Carton leads volumes today; bottle formats are climbing the fastest.
End User:
Customer type determines whether products enter standalone household consumption or embedded commercial beverage preparation with technical performance requirements.
- Retail Consumers:Household purchasers prioritize Health Star Rating visibility and price-per-liter efficiency in supermarket environments, with fortification credentials driving selection among lactose-intolerant and flexitarian demographics.
- Cafés:Specialty coffee venues impose exacting microfoam and temperature stability specifications that filter supplier eligibility, creating dedicated barista-grade supply relationships with refrigerated direct delivery.
- Food Service:Broader institutional procurement emphasizes case-level pricing and ambient storage compatibility for hotel and catering applications.
- Restaurants:Menu integration demands neutral flavor profiles that do not dominate dish composition, favoring almond and oat bases over coconut.
Retail consumers lead volumes today; cafés are expanding most quickly.
Distribution Channel:
Geographic concentration of demand shapes channel viability, with metropolitan density enabling specialized formats unavailable in dispersed regional markets.
- Supermarket:Coles and Woolworths planogram placement determines mass-market visibility, with Health Star Rating optimization and sugar reformulation driving shelf access negotiations.
- Online:Direct-to-consumer subscription models bypass retail margin extraction, though cold chain logistics constrain chilled format viability to metropolitan delivery zones.
- Health Stores:Independent retailers in Sydney and Melbourne inner-urban postcodes curate premium and organic-positioned SKUs with higher margin tolerance.
- Specialty Shops:Asian grocery and vegan-specific retailers serve diaspora and committed vegan households with imported or niche domestic brands.
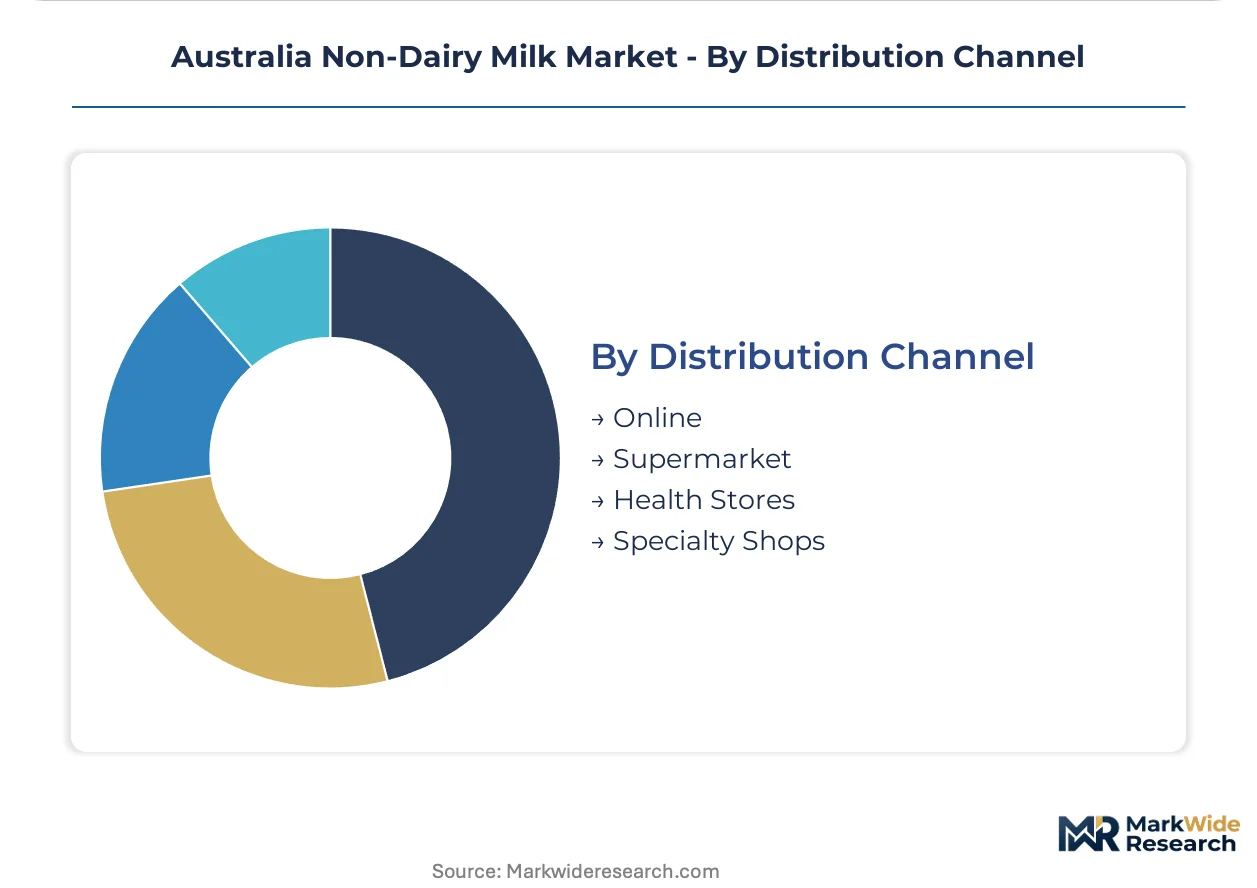
Supermarket leads volumes today; online channels are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Food technologist talent clusters in Melbourne and Sydney anchor Australia's plant-based beverage innovation pipeline, with enzymatic processing expertise concentrated among specialist consultancies serving both domestic brands and Asia-Pacific export operations.
New South Wales
Sydney's specialty coffee corridor drives barista-grade oat milk procurement, with inner-urban espresso bars locking in direct refrigerated delivery contracts. FSANZ headquarters in Canberra shapes national labeling standards that NSW-based manufacturers must navigate. The Parramatta-Western Sydney manufacturing belt hosts blending and packaging facilities supplying Woolworths and Coles distribution centers.
Victoria
Melbourne's café culture density creates the nation's most sophisticated food service demand for microfoam-stable formulations. The Health Star Rating system pressures local producers to reformulate sugar profiles for supermarket shelf access. Brunswick and Collingwood house independent roaster networks that bypass traditional wholesale intermediaries through dedicated logistics partnerships.
Queensland
Brisbane retail corridors show underdeveloped plant-based beverage sections relative to southern states, creating first-mover reset opportunities. Coconut milk demand concentrates in tropical-climate consumption preferences along the Gold Coast and Sunshine Coast. Limited refrigerated infrastructure in regional Queensland constrains chilled format penetration beyond metropolitan cores.
Western Australia
Perth metro zones exhibit lagging supermarket planogram development for premium plant-based SKUs. Domestic oat milling capacity constraints limit rapid volume scaling for food service expansion. The state's isolation from eastern seaboard distribution networks necessitates localized warehousing strategies for ambient-stable carton formats.
South Australia
Adelaide's smaller specialty coffee market generates modest but growing barista-grade demand through independent roasters. Almond input cost volatility from California drought cycles transmits directly into retail pricing sensitivity. Local health store channels curate organic-positioned variants with higher margin tolerance than mass retail.
Australia Non-Dairy Milk Market Competitive Landscape
Capital-heavy producers with captive milling and blending infrastructure compete with asset-light brand architects outsourcing manufacturing to third-party facilities. The market exhibits tiered concentration, with multinational dairy-alternative specialists commanding premium positioning while domestic private-label suppliers compete on shelf placement efficiency. Two strategic archetypes dominate: café-channel specialists leveraging barista-grade formulation credibility, and retail-anchored diversified portfolios spanning multiple plant bases. Competitive moves center on Health Star Rating optimization for supermarket access and direct-to-café distribution platform construction displacing wholesale intermediaries.
Among café-channel specialists, Oatly Group AB and Noumi Ltd occupy positions exemplifying the barista-grade premium tier, with their geographic nomenclature signaling Nordic and domestic Australian operational origins respectively. Blue Diamond Growers represents the agricultural cooperative archetype, with its grower-owned structure anchoring almond supply security. These three entities illustrate how divergent capital structures—venture-backed international expansion, ASX-listed diversified food manufacturing, and farmer-controlled supply integration—converge on the Australian market through distinct channel strategies.
| Leading Market Players |
|---|
| Sanitarium Health and Wellbeing Company |
| Blue Diamond Growers |
| Oatly Group AB |
| Vitasoy International Holdings Ltd |
| Noumi Ltd |
| Pureharvest Pty Ltd |
| Danone |
| Bonsoy |
| Milkadamia |
| Others |
Pricing and Supply Chain Analysis
Captive oat milling infrastructure in Nordic supply zones and domestic Australian processing facilities anchors both raw material security and premium pricing power for barista-grade formulations. This backward integration choice insulates specialized manufacturers from commodity spot volatility while forcing retail-anchored competitors into price-sensitive shelf negotiations.
Pricing Analysis
The bundled-versus-unbundled service split separates refrigerated direct-delivery café contracts from ambient carton supermarket sales. Three-tier pricing structure across premium barista-grade, standard retail, and economy private-label levels stratifies margin capture. Price differentiation hinges on Health Star Rating optimization and cold chain service bundling. Pricing pressure intensifies in retail tiers as California almond input cost volatility transmits through Blue Diamond supply contracts. Supermarket procurement teams exhibit highest price sensitivity, while specialty coffee venues prioritize microfoam performance over per-liter cost.
Supply Chain Analysis
Refrigerated freight cost premiums constrain chilled format distribution radius to metropolitan Sydney, Melbourne, and Brisbane corridors. Raw material sourcing draws from Nordic oat milling zones, California almond orchards, and domestic Australian grain belts. Single-origin oat supply concentration in limited milling capacity creates volume scaling bottlenecks for food service expansion. Distribution runs through Coles and Woolworths centralized DC networks for ambient carton formats, while direct-to-café refrigerated logistics bypass wholesale intermediaries in inner-urban postcodes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Australia non-dairy milk market functions as a regulatory compounder where FSANZ protein fortification standards and Health Star Rating recalibration continuously reshape formulation investment and shelf access economics.
For Market Incumbents: Extend barista-grade formulation credibility into underdeveloped Queensland and Western Australia retail corridors before private-label suppliers capture shelf resets. Deepen captive oat milling capacity to offset Nordic supply concentration risk. Lock in direct refrigerated delivery partnerships with independent Melbourne and Sydney roasters to forestall distributor disintermediation.
For New Entrants and Emerging Players: Begin with Health Star Rating optimization as the fastest shelf-access pathway into Coles and Woolworths planograms. Target Brisbane supermarket corridors where plant-based beverage sections remain underdeveloped relative to southern states. Launch through online subscription models with metropolitan cold chain logistics to bypass retail margin extraction.
For Investors and Strategic Acquirers: Roll-up economics work for diversified food manufacturing platforms because FSANZ compliance burden and R&D scale requirements disproportionately strain small-to-mid scale producers. Acquire targets with established refrigerated logistics networks and Health Star Rating-optimized portfolios. Monitor pending FSANZ consultations on protein content descriptors as the signal for accelerated consolidation timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Health Star Rating Optimization | Sugar reduction and calcium fortification adjustments unlock preferred Coles and Woolworths shelf positioning. |
| Direct-to-Café Distribution Platform | Refrigerated logistics partnerships with specialty roasters capture margin and relationship depth in Melbourne-Sydney corridors. |
| Captive Oat Milling Capacity Expansion | Domestic processing infrastructure reduces Nordic supply concentration risk for food service volume scaling. |
| Queensland Retail Penetration | First-mover reset potential in underdeveloped Brisbane supermarket plant-based beverage sections. |
| Precision Fermentation Integration | Pilot-scale dairy protein trials enhance mouthfeel differentiation beyond conventional plant-based sourcing. |
Research Methodology
Multiple input streams — structured interviews with food technologists and café procurement managers, regulatory filing analysis, and retail audit data — were reconciled to construct market estimates. Primary fieldwork engaged plant-based beverage R&D directors, Coles and Woolworths category buyers, FSANZ regulatory affairs specialists, and specialty coffee roaster owners. Secondary validation drew from FSANZ consultation documents, ACCC enforcement records, Health Star Rating database releases, and Australian Bureau of Agricultural and Resource Economics trade statistics. Bottom-up volume modeling across product type, packaging format, and channel tiers was cross-checked against top-down category value estimates.
Data-stream reconciliation applied across the analysis window incorporated enzymatic processing technology adoption curves, café channel penetration rates, and supermarket planogram reset frequencies. Segmentation dimensions modeled include plant base type, packaging temperature requirements, end-user technical specifications, and metropolitan versus regional distribution economics. CAGRs were derived from trend extrapolation of volume and value trajectories, adjusted for almond input cost cycle impacts and refrigerated infrastructure expansion rates.
Several conditions sit outside the modeled scope, including abrupt California drought intensification, FSANZ protein descriptor ruling outcomes, and ACCC greenwashing enforcement pattern shifts. Forecasts reflect assumptions about Health Star Rating stability and café channel growth continuity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Alternatives
Almond Drink Market
Dairy Alternatives
Plant-Based Cheese Wedges Market
Dairy Alternatives
Global Vegan Sour Cream Market
Dairy Alternatives
Hemp Milk Market
Dairy Alternatives
Coconut Cream Market
Dairy Alternatives
Organic Milk Replacers Market
Dairy Alternatives
Middle East Dairy Alternatives Market
Dairy Alternatives
United Kingdom Dairy Alternatives Market
Dairy Alternatives
Low Fat Coconut Milk Market
Dairy Alternatives
Spelt Milk Market
Dairy Alternatives
North America Non-Dairy Ice Cream Market
Dairy Alternatives
Coconut Yogurt Market
Dairy Alternatives
Dairy-Free Chocolate Market
Dairy Alternatives
Soy Milk Powder Market
Dairy Alternatives
Sesame Milk Market
Dairy Alternatives
Camel Milk Products Market