
 Peanut Milk Market | 2026-2036
Peanut Milk Market Size, Share, and Industry Trends Forecast 2026-2036
Peanut Milk Market Analytics
Southeast Asian peanut processors is repositioning toward value-added extraction infrastructure as raw commodity margins compress. Elmhurst 1925 leverages its hydroponic sourcing network to secure allergen-controlled peanut inputs. Yili Group anchors its distribution through dairy-cold-chain repurposing across provincial Chinese markets. Califia Farms competes on barista-format consistency, a segment where foam stability determines cafe adoption.
Peanut milk denotes an aqueous emulsion produced by mechanical milling, enzymatic hydrolysis, and homogenization of roasted Arachis hypogaea kernels, yielding a lipid-protein suspension with typical solids content of 8-12% designed for direct consumption or beverage formulation. Unsweetened variants dominate household penetration in North American and European markets where sugar-reduction claims drive purchase decisions. Flavored and barista blend categories capture margin concentration in cafe and foodservice channels where operators pay premiums for steam-stable performance. Tetra pack packaging extends ambient shelf life to 9-12 months, unlocking supermarket distribution economics that bottles cannot match.
The FDA governs allergen disclosure and nutritional labeling for plant-based beverages in the United States, while China's SAMR enforces GB standards for protein content claims and additive permissions in peanut-derived drinks. EFSA's novel food assessments shape European market entry timelines for enzymatically modified peanut extracts. Stakeholders must monitor evolving protein fortification rules and allergen threshold regulations as these frameworks determine which formulations achieve cross-border commercial scale.
Market Dynamics
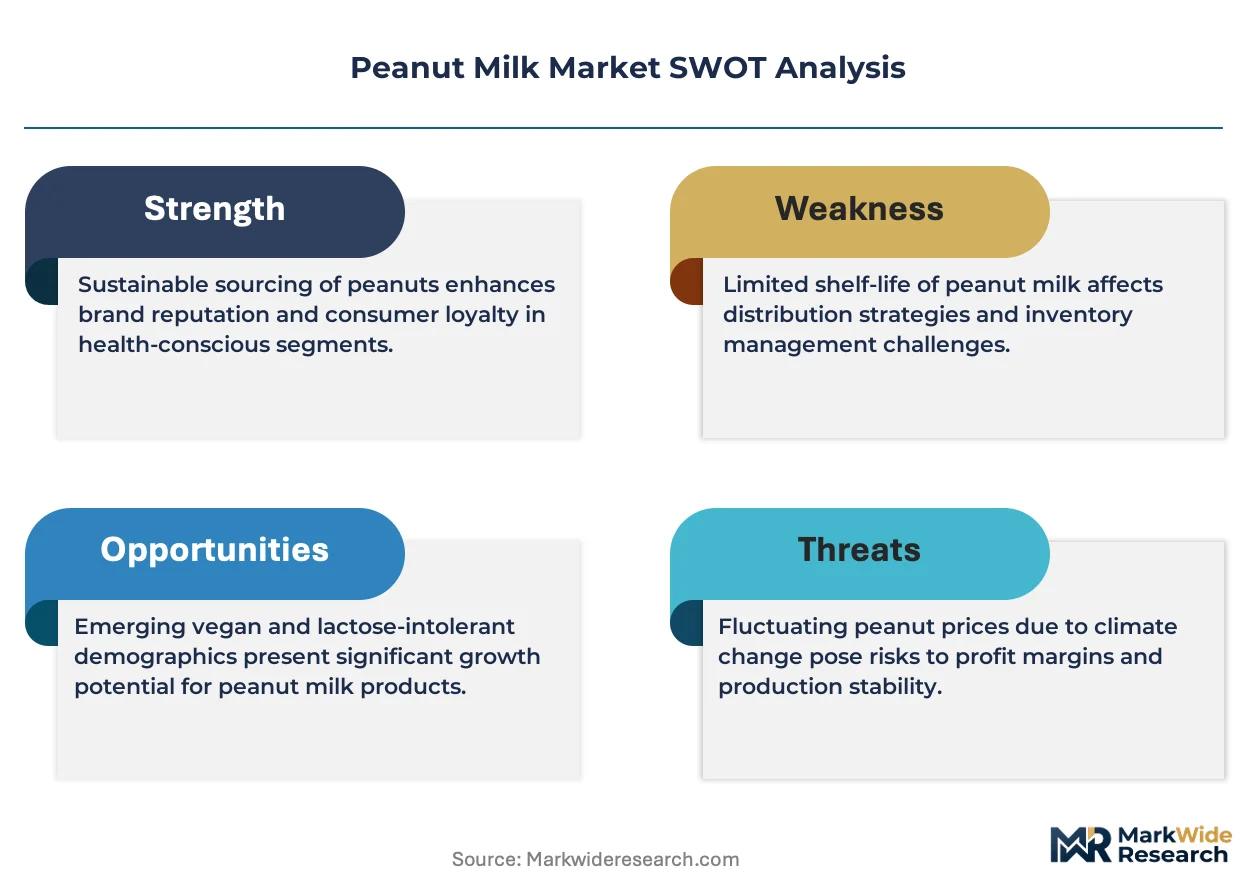
Barista-format standardization is compressing formulation margins while enzymatic hydrolysis patents concentrate among three equipment suppliers, forcing processors to choose between licensing fees and inferior foam stability.
Growth Catalysts
- FDA Plant-Based Beverage Labeling Guidelines:Clarity on nutritional equivalence claims accelerates supermarket placement decisions for peanut milk alternatives in US retail channels.
- Enzymatic Hydrolysis Advancement:Improved protein solubility enables 8-12% solids suspension without sedimentation, matching dairy performance in coffee applications.
- China Tier-One City Premium Channels:Convenience store cold-chain expansion in Shanghai, Beijing, and Shenzhen creates dedicated shelf space for ambient-stable plant beverages.
Market Restraints
- Allergen Threshold Regulations:EFSA's pending novel food assessments for modified peanut extracts delay European market entry timelines by 18-24 months.
- Roasted Kernel Input Volatility:Arachis hypogaea commodity prices fluctuate with Argentine and US harvest cycles, compressing processor margins during drought years.
- Oat Milk Substitution:Established oat alternatives command lower unit costs and broader cafe acceptance, limiting peanut milk price premium capture.
Strategic Opportunities
- India FSSAI Protein Fortification Rules:Pending amendments to plant beverage standards may permit peanut-derived protein claims currently restricted to dairy analogs.
- Tetra Pack Ambient Distribution:Nine-to-twelve month shelf stability unlocks rural Chinese markets beyond cold-chain reach, bypassing dairy infrastructure constraints.
- Specialty Coffee Foodservice:Third-wave roasters in Melbourne, Portland, and Copenhagen seek differentiated milk alternatives for signature beverage programs.
Industry Challenges
- Enzymatic Process Talent Scarcity:Food biochemists with hydrolysis optimization experience command premium salaries, constraining mid-processor scale-up timelines.
- Cross-Contamination Certification:Allergen-controlled facility audits under ISO 22000 require six-to-nine month validation periods, delaying new production line commissioning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Peanut Milk Market |
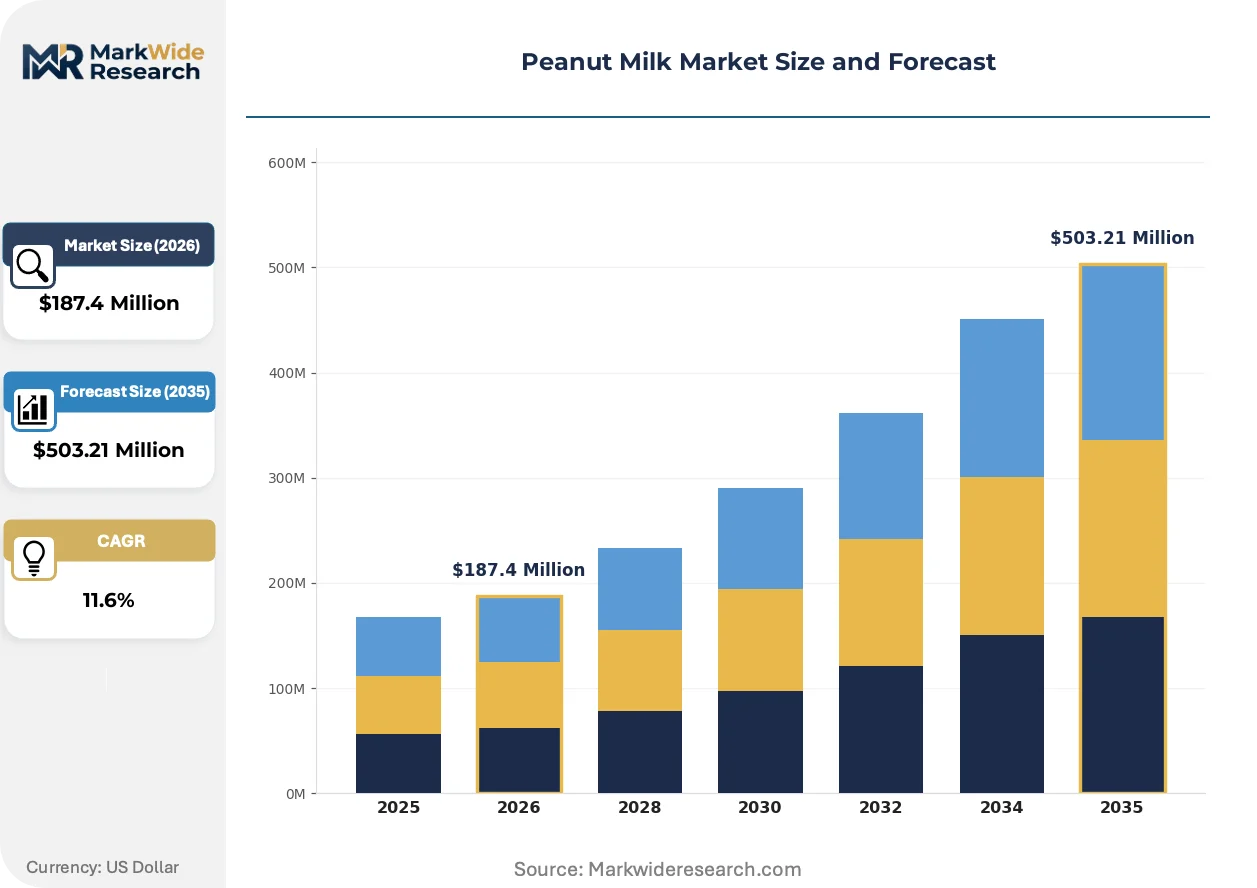
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $503.21 Million |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Unsweetened, Sweetened, Flavored, Barista Blend Distribution Channel: Online Retail, Supermarkets, Health Food Stores, Specialty Shops End User: Households, Cafes, Restaurants, Food Manufacturers Packaging Type: Bottles, Tetra Packs, Cans, Pouches |
| Companies Covered | Elmhurst 1925, Good Karma Foods, Silk, Yili Group, Nestlé (Wunda), Ripple Foods, Vitasoy International, Hebei Chengde Lolo Co.,Ltd, Califia Farms, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Peanut Milk Market Evolving Landscape
Processing equipment modularity and regulatory clarity on protein claims are converging to reshape competitive entry barriers, while cafe channel specifications harden around foam microstructure performance.
High-pressure homogenization systems with swappable rotor-stator configurations are modularizing production line adaptation across batch sizes from 500-liter pilot to 10,000-liter commercial runs. Regional processors in Vietnam and Indonesia adopt these units to shift between peanut, cashew, and blended formulations without dedicated capital expenditure per SKU. This flexibility is compressing minimum viable scale thresholds for new market entrants previously blocked by single-product line economics.
China's SAMR enforcement of GB 7101 beverage additive permissions is tightening emulsifier and stabilizer approval lists, forcing reformulation of legacy peanut milk recipes. Domestic manufacturers face twelve-to-eighteen month re-registration cycles for modified hydrocolloid blends. Export-oriented processors are responding by segregating China-bound production lines from formulations acceptable under FDA GRAS or EFSA additive frameworks.
Cafe operators now specify steam-stability duration and foam collapse rates in procurement contracts, displacing ingredient-cost-only purchasing. Specialty coffee chains in Seoul, London, and Los Angeles require 180-second microfoam retention at 65°C, testing supplier formulation consistency. This specification compression favors processors with in-house barista training programs and direct equipment partnerships, penalizing commodity-grade suppliers lacking technical service depth.
Peanut Milk Market Segmentation
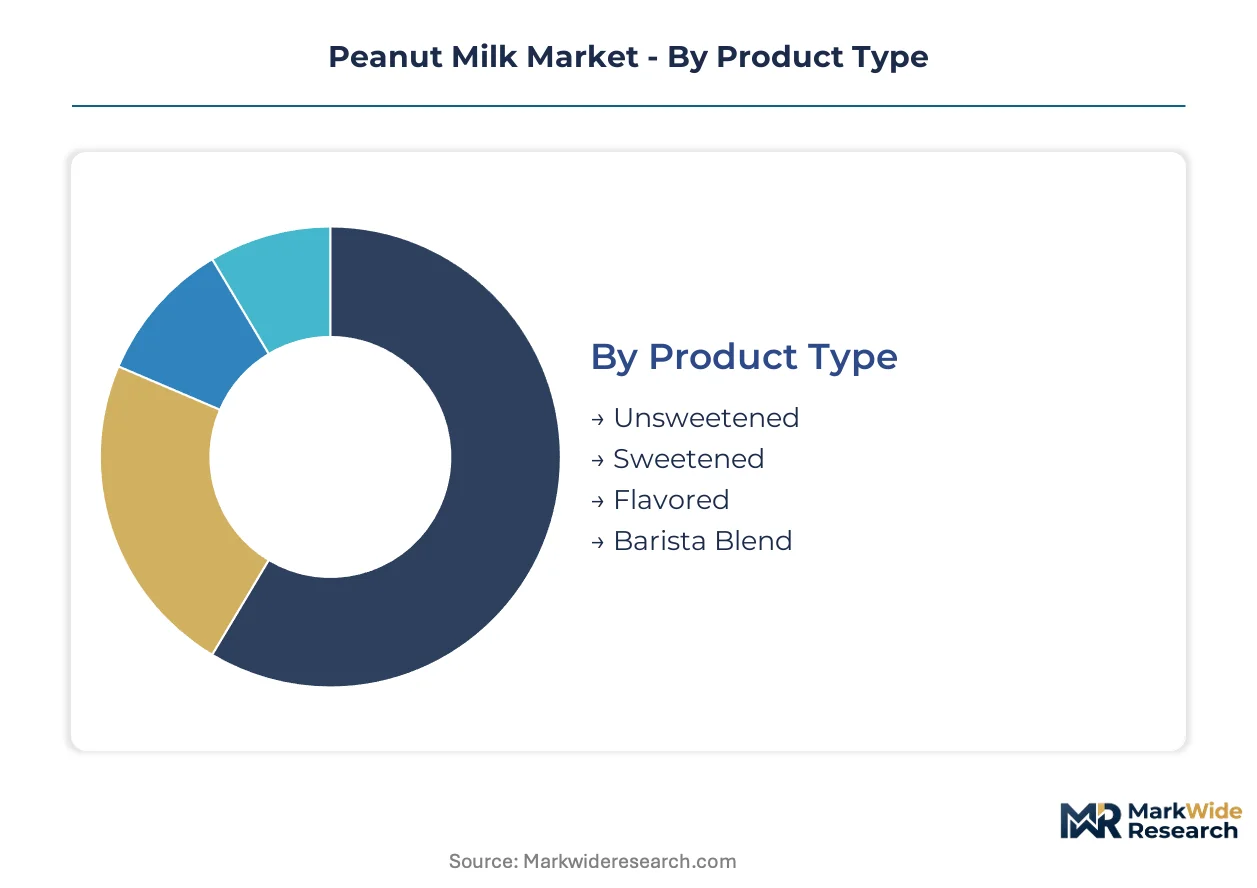
Peanut milk segmentation reveals how formulation choices and channel economics partition value capture across the supply chain. Product type and packaging configurations determine margin structures, while distribution channel selection governs geographic reach and brand positioning.
Product Type:
Supply concentration in enzymatic hydrolysis equipment favors processors with dedicated barista-format lines, while commodity-grade variants face margin compression from oat milk substitution.
- Unsweetened:Aqueous emulsion with 8-12% solids content and zero added sugars, targeting sugar-reduction claim positioning. Household penetration concentrates in North American and European retail channels where nutritional labeling transparency drives purchase decisions.
- Sweetened:Standard formulation with sucrose or alternative sweeteners at 4-6% addition rates. Mass-market retail in China's tier-one cities absorbs volume, though reformulation costs under tightening GB 7101 additive permissions are squeezing domestic manufacturer margins.
- Flavored:Vanilla, chocolate, and regional variants using natural or nature-identical flavor systems. Premium convenience channels in Shanghai and Beijing stock these for impulse purchase occasions.
- Barista Blend:Hydrocolloid-stabilized formulation engineered for 180-second microfoam retention at 65°C steam temperatures. Specialty coffee chains in Seoul, London, and Los Angeles specify this grade exclusively, with foam collapse rates now written into procurement contracts.
Barista Blend absorbs the bulk of installed capacity; Flavored is expanding most quickly.
Distribution Channel:
Channel selection determines cold-chain dependency and pricing power, with ambient-stable formats unlocking supermarket economics that perishable alternatives cannot match.
- Online Retail:Direct-to-consumer and platform-mediated sales with 24-48 hour fulfillment windows. Subscription models in US and European markets build recurring revenue for specialty brands.
- Supermarkets:Mass-market placement requiring 9-12 month shelf stability and case-ready packaging. Tetra pack configurations dominate this channel due to distribution economics.
- Health Food Stores:Curated assortment emphasizing organic certification and allergen-controlled sourcing. Premium pricing tolerates lower throughput for margin preservation.
- Specialty Shops:Independent grocers and regional chains with localized assortment control. These outlets serve as testing grounds for novel formulations before supermarket rollout.
Supermarkets command the greatest volume throughput; Online Retail is climbing the fastest.
End User:
User segmentation separates commodity procurement from technical service relationships, with foodservice operators now demanding formulation support beyond ingredient supply.
- Households:Individual consumers purchasing for direct consumption or home beverage preparation. Unsweetened variants dominate this segment in sugar-conscious markets.
- Cafes:Third-wave and specialty coffee operators with explicit foam performance specifications. Direct equipment partnerships and barista training programs differentiate suppliers in this segment.
- Restaurants:Full-service and fast-casual operators using peanut milk for beverage programs or recipe integration. Consistent supply security outweighs price sensitivity.
- Food Manufacturers:Industrial buyers incorporating peanut milk into finished goods such as ice cream, baked products, or nutritional beverages. Volume contracts and custom formulation capabilities determine supplier selection.
Cafes absorb the bulk of technical service investment; Food Manufacturers are gaining share fastest.
Packaging Type:
Packaging technology governs shelf life extension and distribution radius, with aseptic formats enabling market entry beyond cold-chain infrastructure limits.
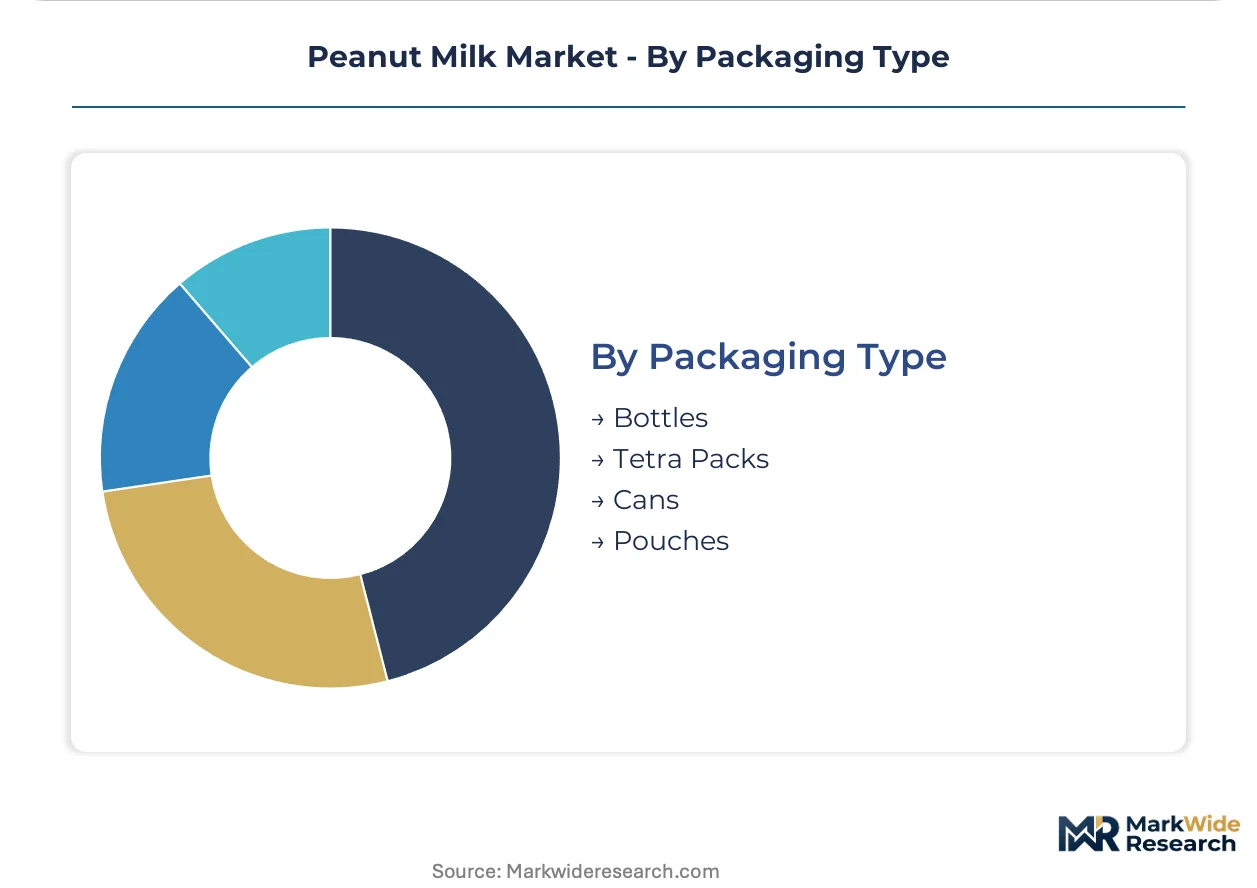
- Bottles:PET or glass containers with 30-45 day refrigerated shelf life. Premium positioning in health food channels justifies higher per-unit packaging costs.
- Tetra Packs:Aseptic carton systems delivering 9-12 month ambient stability. Rural Chinese markets beyond cold-chain reach become accessible through this format.
- Cans:Metal containers for single-serve consumption occasions. Limited adoption due to recycling infrastructure constraints in key markets.
- Pouches:Flexible film packaging for bulk or foodservice volumes. Cost efficiency favors institutional buyers with rapid inventory turnover.
Tetra Packs carry the majority of production line investment; Pouches are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Argentine peanut cultivation zones around Córdoba and southern Santa Fe supply the roasted kernel inputs that processors in Asia and North America convert into beverage-grade emulsions. Harvest volatility in these regions ripples through global commodity pricing, compressing margins for manufacturers dependent on spot-market sourcing.
United States
Specialty coffee chains in Seattle, Portland, and Los Angeles now specify barista-format peanut milk in procurement contracts with foam stability requirements. The FDA's updated plant-based beverage labeling guidelines clarify nutritional equivalence claims, accelerating supermarket placement decisions. Georgia and Alabama processing clusters supply roasted kernel inputs to domestic hydrolysis facilities.
China
Tier-one city convenience stores in Shanghai, Beijing, and Shenzhen dedicate refrigerated shelf space to ambient-stable peanut beverages. SAMR enforcement of GB 7101 additive permissions forces twelve-to-eighteen month reformulation cycles for emulsifier blends. Hebei province anchors domestic production capacity with cold-chain repurposing across provincial markets.
Germany
Third-wave roasters in Berlin and Hamburg trial peanut milk for signature beverage differentiation. EFSA's pending novel food assessments for enzymatically modified peanut extracts delay commercial launch timelines by eighteen-to-twenty-four months. Bavarian food technology clusters develop high-pressure homogenization systems for European processor adoption.
Australia
Melbourne's specialty coffee culture drives demand for steam-stable plant alternatives with explicit microfoam retention specifications. The country's national food standards code governs allergen disclosure thresholds for peanut-derived beverages. Queensland and New South Wales roasting facilities supply kernel inputs to domestic emulsion processors.
Vietnam
Southeast Asian processors reposition toward value-added extraction infrastructure as raw commodity margins compress. Modular homogenization equipment enables batch-size flexibility between peanut, cashew, and blended formulations. Ho Chi Minh City industrial zones host pilot-scale enzymatic hydrolysis operations serving regional export markets.
Peanut Milk Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue barista-format specialization and enzymatic hydrolysis licensing. The market structures around three maturity tiers: legacy dairy-alternative portfolios, dedicated nut-milk specialists, and regional commodity processors upgrading to beverage-grade capacity. Two strategic archetypes dominate: hydroponic sourcing networks securing allergen-controlled inputs, and equipment-integrated processors controlling foam stability through in-house formulation science. Competitive moves concentrate on cold-chain repurposing partnerships and enzymatic process patent licensing.
Within the dedicated specialist tier, Elmhurst 1925 exemplifies hydroponic sourcing integration, while Yili Group anchors multinational dairy-alternative expansion through Chinese distribution infrastructure. Califia Farms occupies a position emphasizing barista-format consistency. Among Asia-Pacific processors, Hebei Chengde Lolo Co.,Ltd represents regional commodity-upgrading archetypes. These three entities illustrate the geographic and capability segmentation shaping procurement decisions.
| Leading Market Players |
|---|
| Elmhurst 1925 |
| Good Karma Foods |
| Silk |
| Yili Group |
| Nestlé (Wunda) |
| Ripple Foods |
| Vitasoy International |
| Hebei Chengde Lolo Co.,Ltd |
| Califia Farms |
| Others |
Value Network & Pricing Analysis
Cafe procurement contracts specifying 180-second microfoam retention at 65°C steam temperatures force processors to absorb enzymatic hydrolysis licensing fees or sacrifice foam stability, compressing formulation margins and widening spreads between commodity-grade and barista-format supply tiers.
Pricing Analysis
Technical service bundling separates barista-format suppliers from unbundled commodity processors, with the former embedding barista training programs and direct equipment partnerships into contract value. Three-tier pricing structure across premium barista blends, standard unsweetened variants, and economy sweetened formulations tracks certification grade and foam performance tier. Cost compression in the standard tier intensifies because oat milk alternatives command lower unit costs and broader cafe acceptance. Food manufacturers represent the most price-sensitive buyer segment, while specialty coffee chains tolerate premiums for steam-stable performance guarantees.
Supply Chain Analysis
Dual-sourcing mandates from major cafe chains and food manufacturers require processors to qualify multiple enzymatic hydrolysis equipment suppliers, extending procurement timelines. Argentine, United States, and Vietnamese cultivation zones supply roasted Arachis hypogaea kernels, with processing equipment drawing from German, Italian, and Chinese fabrication hubs. Single-source vulnerability concentrates in patented hydrolysis enzyme supply, where three equipment licensors control critical foam-stabilization technology. Distribution runs through repurposed dairy cold-chain infrastructure in China and direct-to-cafe technical service networks in North America and Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a cost-of-compliance arena where SAMR's GB 7101 additive permissions and EFSA's novel food assessment timelines erect regulatory moats that favor incumbents with established re-registration capabilities and segregated production lines.
For Market Incumbents: Deepen enzymatic process patent licensing relationships to lock in foam stability differentiation against emerging oat-cashew blend substitutes. Expand allergen-controlled facility capacity in Hebei province to exploit Yili Group's cold-chain repurposing infrastructure before SAMR tightens protein fortification claim permissions further. For New Entrants and Emerging Players: Capture rural Chinese markets beyond cold-chain reach through Tetra pack ambient distribution partnerships with provincial convenience store networks. Target India's pending FSSAI protein fortification rule amendments as the most penetrable regulatory opening, deploying white-label barista-format production for Melbourne and Copenhagen third-wave roasters seeking signature beverage differentiation. For Investors and Strategic Acquirers: The window for entry favors processors with modular homogenization equipment and established enzymatic hydrolysis talent pools, given eighteen-to-twenty-four month validation timelines for allergen-controlled facility audits. Watch EFSA's final novel food assessment determinations for modified peanut extracts as the signal indicating whether European market entry timelines compress or extend.| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Hydrolysis Patent Licensing | Secures foam stability performance that cafe procurement contracts now mandate as table stakes. |
| Allergen-Controlled Facility Expansion | ISO 22000 validation periods create six-to-nine month barriers against commodity processor entry. |
| Barista Training Program Development | Technical service depth displaces ingredient-cost-only purchasing in Seoul and Los Angeles specialty chains. |
| Tetra Pack Ambient Distribution Partnership | Unlocks supermarket economics and rural Chinese markets beyond refrigerated cold-chain infrastructure limits. |
| Dual-Source Equipment Supplier Qualification | Cafe chain procurement mandates reduce single-source vulnerability in patented hydrolysis technology supply. |
Research Methodology
Multi-period observation of enzymatic hydrolysis patent filings, SAMR additive re-registration cycles, and cafe procurement contract specifications anchored the trend analysis, supplemented by interviews with beverage formulation scientists, specialty coffee chain procurement directors, Tetra Pak packaging equipment specialists, and ASEAN commodity processor operations managers. Secondary validation drew from FDA GRAS determinations, EFSA novel food assessment databases, Chinese customs trade data, and SEC filings from publicly traded dairy-alternative portfolios. Bottom-up volume modeling across product type, packaging format, and distribution channel tiers triangulated against top-down macroeconomic absorption rates.
Input-output matrices mapped roasted kernel supply from Argentine and US harvest zones through enzymatic processing capacity to end-use absorption across household, cafe, restaurant, and food manufacturer segments. Modeled dimensions spanned formulation type, packaging technology, channel cold-chain dependency, and regional regulatory cluster. CAGRs were derived from segmented growth trajectory analysis incorporating protein fortification rule amendments, allergen threshold regulatory evolution, and substitution elasticity between peanut and oat milk alternatives.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EFSA novel food assessment timelines, Argentine drought frequency in Córdoba cultivation zones, and SAMR enforcement intensity for GB 7101 additive permissions. Deviation in enzymatic hydrolysis equipment supplier consolidation would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Alternatives
Asia-Pacific Oat Milk Market
Dairy Alternatives
Vegan Coffee Creamer Market
Dairy Alternatives
Dry Yogurt Market
Dairy Alternatives
Vegan Condensed Milk Market
Dairy Alternatives
North America Non-Dairy Ice Cream Market
Dairy Alternatives
Spelt Milk Market
Dairy Alternatives
Asia-Pacific Sour Milk Drinks Market
Dairy Alternatives
Hempseed Milk Market
Dairy Alternatives
Fat Free Yogurt Market
Dairy Alternatives
Asia-Pacific Walnut Milk Market
Dairy Alternatives
Vegan Cheese Market
Dairy Alternatives
Chickpea Milk Market
Dairy Alternatives
China Dairy Alternatives Market
Dairy Alternatives
Macadamia Milk Market
Dairy Alternatives
Oat Drinks Market
Dairy Alternatives
Vegan Milk Alternatives Market