
 Cherry Picker Forklift Market | 2026-2036
Cherry Picker Forklift Market Size, Share, and Industry Trends Forecast 2026-2036
Cherry Picker Forklift Market Outlook
Modular platform configurations is repositioning buyer procurement patterns across the cherry picker forklift landscape. JLG Industries leverages integrated control systems to sustain premium positioning in aerial work platforms. Haulotte Group anchors European supply through specialized manufacturing scale in France. Genie competes aggressively on rental fleet penetration across North American distribution channels.
Cherry picker forklifts are self-propelled elevating work platforms with telescoping or articulating booms, typically rated for platform heights between 30 and 150 feet and load capacities of 200 to 1,000 pounds, designed to position personnel and tools at elevated worksites in construction and maintenance operations. Electric product types now dominate indoor warehousing contracts where zero-emission operation is mandatory, while diesel variants retain structural importance in outdoor construction environments lacking grid access. Medium power rating equipment captures the broadest application base across retail and manufacturing end users, whereas automated operation modes represent the fastest-growing configuration segment as warehouse operators seek labor reduction.
OSHA standards govern operator certification and fall protection requirements for aerial lift equipment in the United States, directly shaping training costs and fleet compliance timelines for rental companies. EPA Tier 4 Final emissions regulations constrain diesel engine configurations, pushing manufacturers toward hybrid development pathways. ISO 16368 certification requirements for mobile elevating work platforms establish baseline structural safety benchmarks accepted across European and Asian export markets. Stakeholders must monitor battery energy density improvements and autonomous navigation maturation as these forces determine which product configurations capture replacement cycles.
Market Dynamics
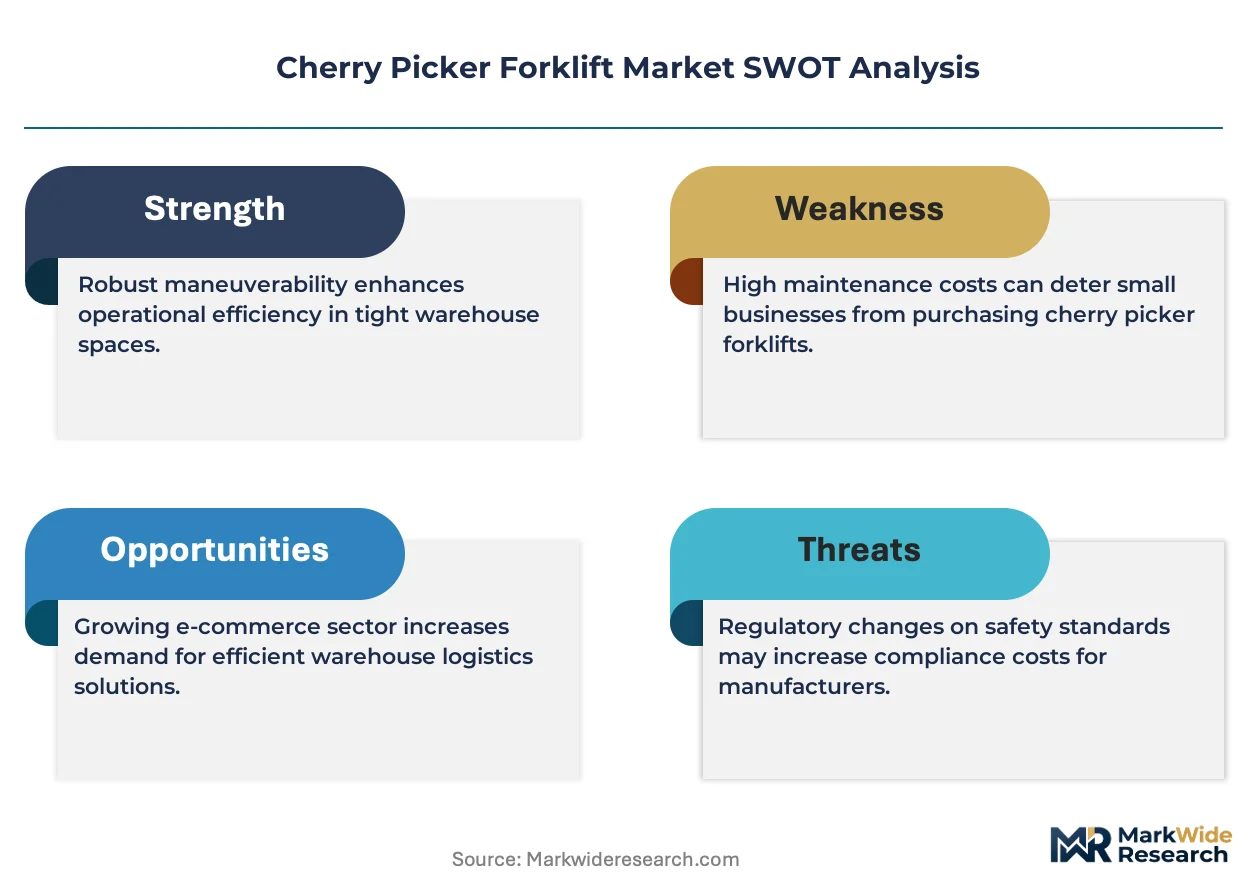
Electrification mandates and warehouse automation imperatives are compressing replacement cycles for cherry picker forklift fleets, forcing rental companies and end-users to accelerate capital deployment toward zero-emission platforms with integrated telematics.
Growth Catalysts
- EPA Tier 4 Final compliance deadlines:Emissions regulations in the United States are accelerating diesel fleet turnover, creating replacement demand for hybrid and electric aerial platforms in construction and logistics.
- E-commerce fulfillment center expansion:Retail distribution networks are scaling vertical storage density, requiring medium-reach electric cherry pickers for inventory management at height.
- ISO 16368 harmonization:Unified structural safety benchmarks across European and Asian export markets are reducing certification friction for manufacturers, streamlining cross-border equipment flows.
Market Restraints
- Lithium-ion battery cost volatility:Raw material price swings for cathode minerals are compressing margins on electric platform configurations, particularly affecting smaller rental fleet operators.
- Steel supply concentration:Boom fabrication relies on specialized high-strength alloy sources concentrated in East Asian foundries, exposing manufacturers to input bottlenecks and tariff exposure.
- OSHA operator certification requirements:Mandatory training timelines and fall protection compliance add fixed costs to fleet deployment, lengthening payback periods for equipment lessors.
Strategic Opportunities
- Autonomous navigation integration:Warehouse operators in Germany are piloting self-positioning platforms that eliminate manual joystick control, reducing labor headcount in high-turnover environments.
- India logistics infrastructure buildout:Cold chain and third-party logistics expansion in Maharashtra and Karnataka is generating first-time aerial platform adoption among domestic warehousing contractors.
- EU Green Deal procurement incentives:Public infrastructure maintenance contracts now specify zero-emission equipment preference, creating mandated demand pull for battery-electric configurations in municipal fleets.
Industry Challenges
- MEWP inspector certification scarcity:Qualified technicians for annual ISO 16368 compliance verification are concentrated in metropolitan service hubs, creating inspection backlogs for distributed rental fleets.
- Legacy fleet telematics integration:Older diesel units lack CAN bus connectivity for unified fleet management platforms, forcing operators to maintain parallel maintenance tracking systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cherry Picker Forklift Market |
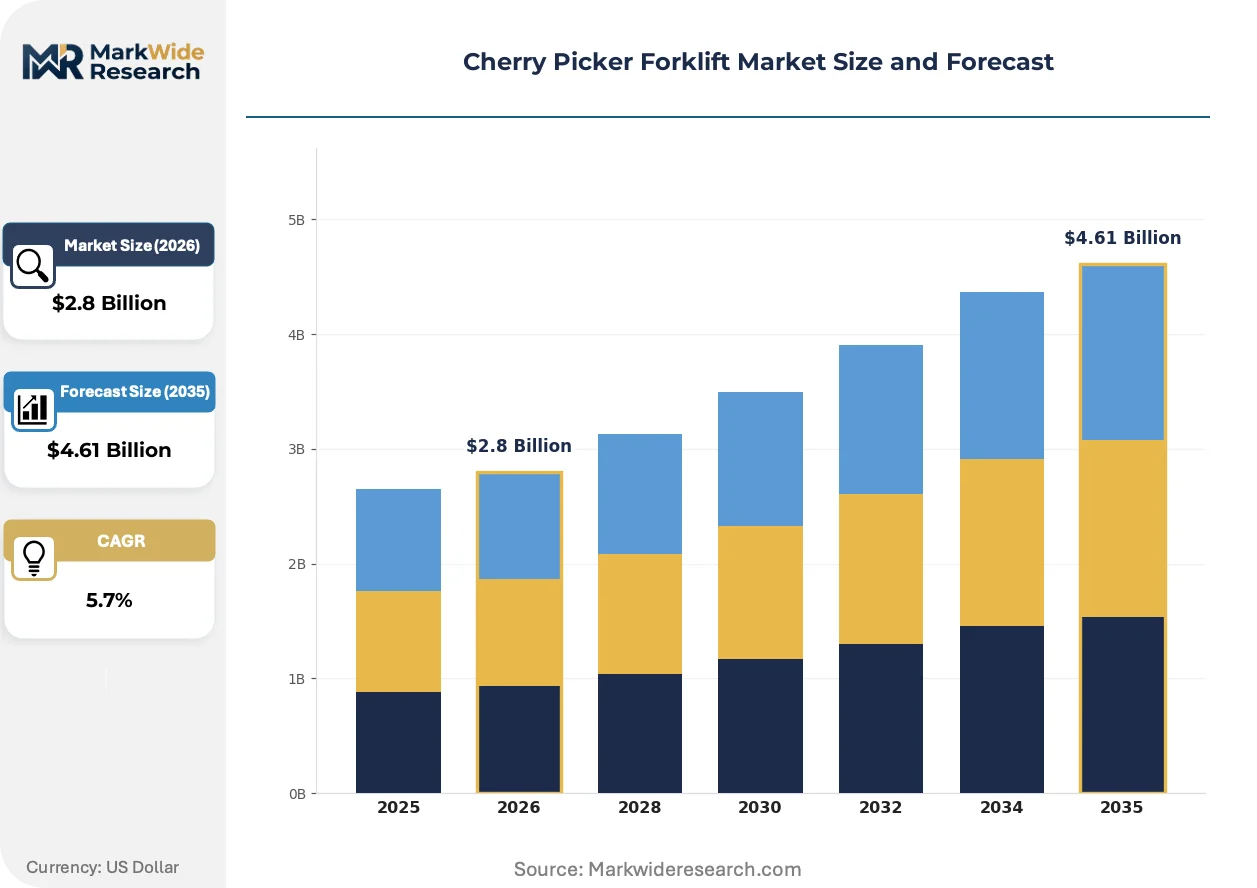
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.61 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric, Diesel, Hybrid, Manual End User: Construction, Warehousing, Retail, Manufacturing Power Rating: Light, Medium, Heavy, Ultra-Heavy Operation Mode: Remote Control, Manual Operation, Automated, Semi-Automated |
| Companies Covered | JLG Industries, Genie, Haulotte Group, Manitou, SkyJack, Snorkel, Niftylift, Terex, Clark Material Handling, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cherry Picker Forklift Market Strategic Shifts
Battery chemistry advances and control system digitization are redefining equipment lifecycle economics, compressing the gap between indoor electric and outdoor diesel performance envelopes while enabling predictive maintenance business models.
Lithium iron phosphate battery packs are expanding into outdoor construction applications previously reserved for diesel powertrains, delivering equivalent duty cycles without refueling infrastructure. Rental companies in the United States are adding these configurations to mixed-use fleets at accelerating rates. The technology is expanding into highway maintenance and telecom infrastructure verticals where emissions restrictions are tightening.
REACH chemical substance restrictions are forcing reformulation of hydraulic fluids and corrosion coatings used in boom assemblies, increasing R&D overhead for European manufacturers. The regulation's industrial consequence is accelerated validation timelines for new material specifications. Aerial platform producers serving EU export markets are responding by consolidating supply base qualification around pre-certified fluid suppliers.
Equipment-as-a-service contracting is displacing traditional capital purchase arrangements among mid-size warehousing operators, unbundling maintenance and uptime guarantees from asset ownership. Third-party logistics providers in China's Yangtze River Delta are driving this shift, preferring per-hour utilization fees over balance sheet equipment loading. The model is compressing supplier-customer relationships toward multi-year performance agreements with penalty clauses for downtime.
Cherry Picker Forklift Market Segmentation
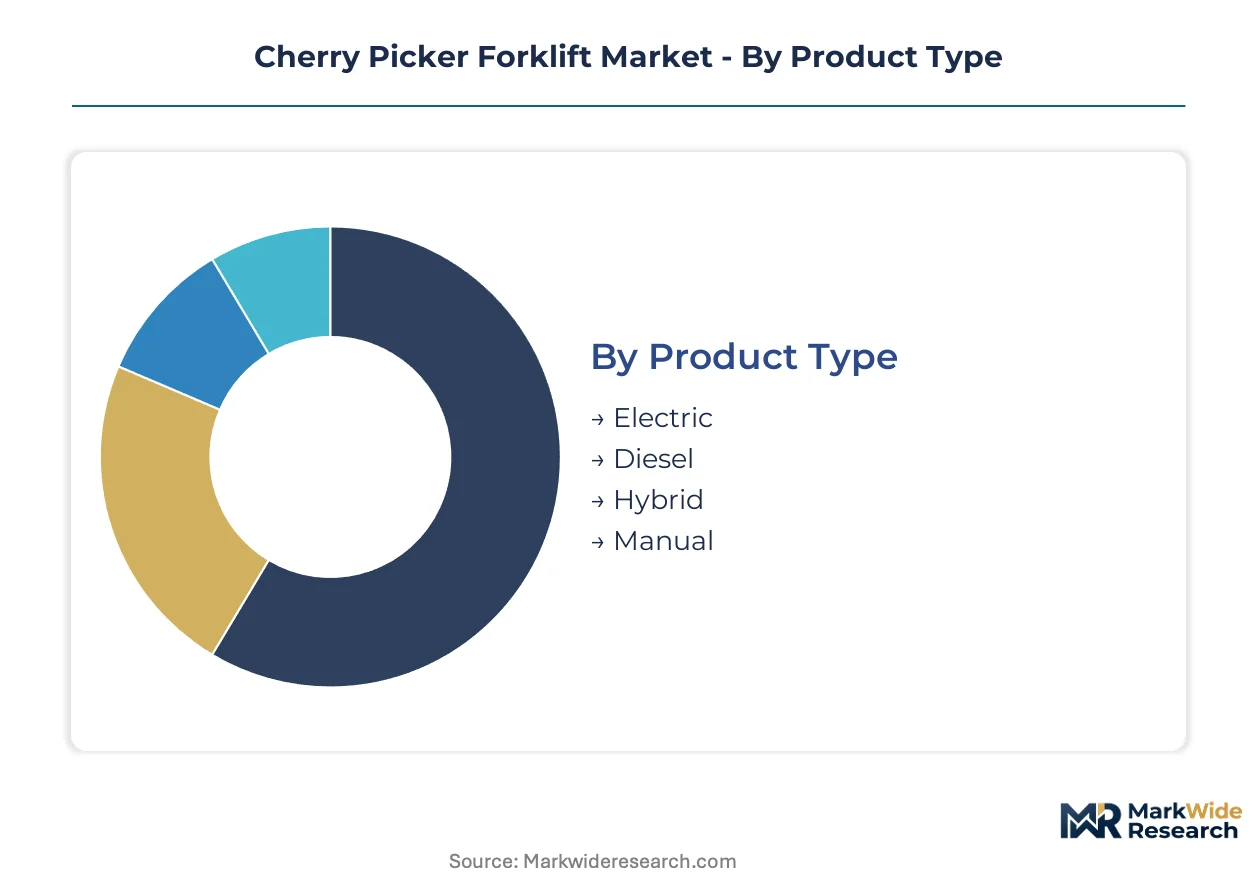
Cherry picker forklift procurement splits sharply between indoor electric platforms and outdoor diesel workhorses, with electrification mandates now forcing rental fleets to rebalance portfolio composition across all four segmentation axes.
Product Type:
Volume concentration sits with electric units in warehousing contracts, while diesel retains premium pricing power in construction verticals lacking grid infrastructure.
- Electric:Zero-emission platforms utilizing lithium iron phosphate battery packs dominate indoor fulfillment center deployments. Amazon and Walmart distribution networks in the United States and Germany specify electric-only fleet standards, compressing payback periods through reduced ventilation and fuel logistics costs.
- Diesel:Compression-ignition engines rated for Tier 4 Final compliance retain structural importance in highway maintenance and telecom infrastructure verticals. Outdoor construction sites in China and India lacking reliable electrical infrastructure continue specifying diesel for platform heights exceeding 80 feet.
- Hybrid:Dual-powertrain configurations combining battery-electric drive with onboard diesel generation bridge grid-limited environments.
- Manual:Non-powered push-around units serve low-frequency maintenance tasks in retail and facility management.
Today's leader: Electric. Tomorrow's challenger: Hybrid.
End User:
Application concentration determines powertrain specification, with warehousing demanding emission compliance and construction prioritizing lift capacity.
- Construction:General contracting and specialty trades drive demand for rough-terrain diesel platforms with four-wheel drive and oscillating axles. Infrastructure stimulus programs in Germany and the United States are accelerating fleet orders for highway bridge maintenance and commercial building envelope work.
- Warehousing:Third-party logistics operators and e-commerce fulfillment networks specify narrow-aisle electric units with non-marking tires. Vertical storage density trends in China's Yangtze River Delta and India's Maharashtra logistics corridors are expanding medium-reach platform adoption.
- Retail:Big-box store operators deploy compact electric units for seasonal signage installation and facility maintenance.
- Manufacturing:Automotive and electronics assembly plants utilize explosion-proof electric configurations for paint booth and cleanroom access.
Construction commands equipment value per unit. Warehousing commands fleet volume.
Power Rating:
Mid-range specifications capture the broadest cross-application utility, while heavy-duty units concentrate in specialized infrastructure verticals.
- Medium:Platforms rated for 500-pound capacity and 40-foot reach serve retail distribution and light manufacturing maintenance. This specification crosses indoor-outdoor boundaries most flexibly, supporting rental fleet standardization across mixed-use contracts.
- Heavy:1,000-pound capacity ratings with 80-foot plus platform heights anchor wind turbine maintenance and industrial chimney inspection workflows. German and Chinese offshore wind installation programs are expanding specialized heavy-lift platform orders.
- Light:Sub-300-pound personnel-only platforms serve facility management and interior finishing trades.
- Ultra-Heavy:Specialized configurations exceeding 2,000-pound capacity address oil refinery turnaround and shipyard applications.
Medium rating anchors rental fleet economics. Heavy rating captures project-specific premiums.
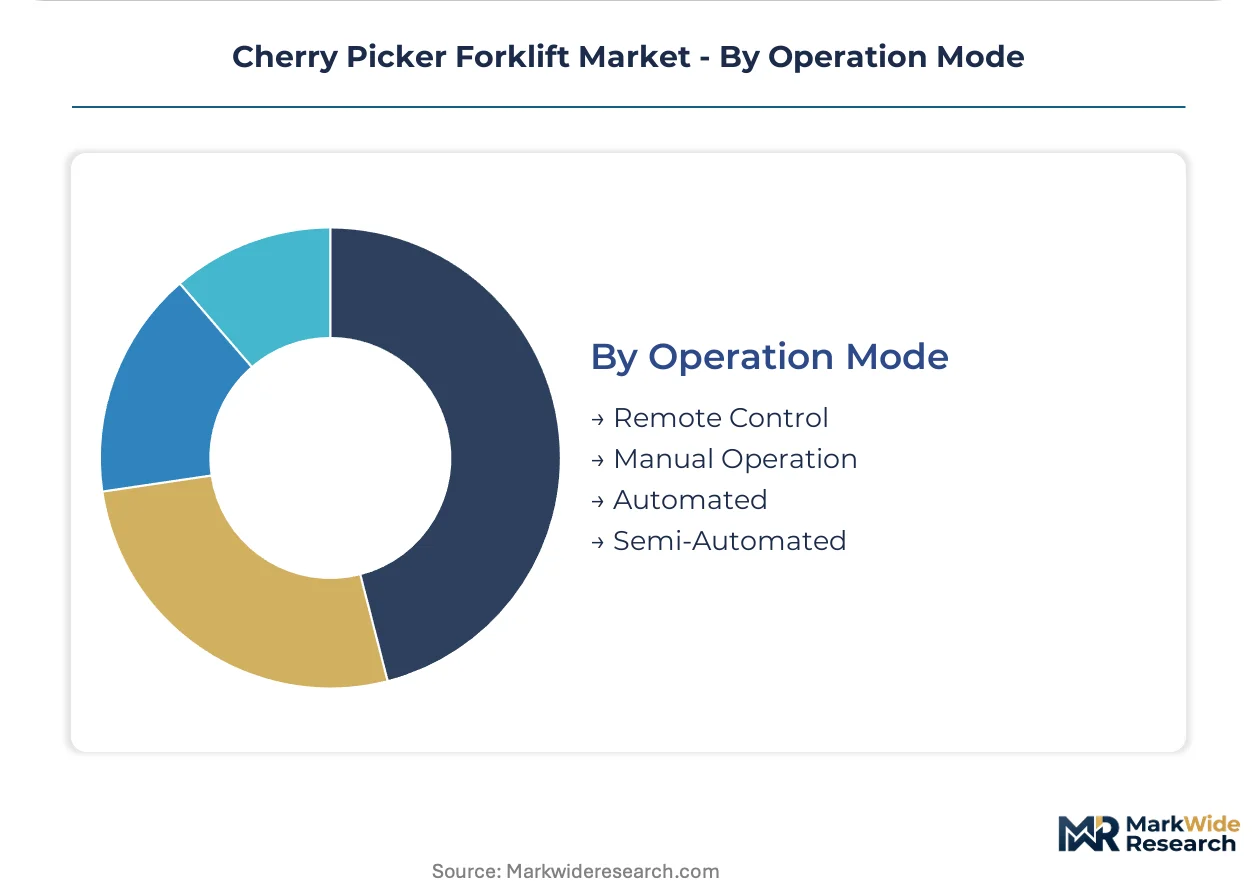
Operation Mode:
Control sophistication separates labor-cost-sensitive warehousing from safety-regulated construction environments.
- Automated:Self-positioning platforms utilizing LiDAR navigation and pre-programmed pathing eliminate manual joystick operation. German automotive parts warehouses in Baden-Württemberg are piloting autonomous units for overnight inventory cycle counting, reducing labor headcount in high-turnover markets.
- Manual Operation:Direct operator control through proportional joysticks remains standard for construction and maintenance applications requiring real-time positioning judgment. OSHA certification requirements in the United States and ISO 16368 compliance across European markets preserve manual operation dominance in outdoor verticals.
- Remote Control:Ground-based wireless operation extends platform utility in hazardous environments including chemical processing and high-voltage electrical work.
- Semi-Automated:Assisted positioning with collision avoidance and height-limiting overrides bridges manual skill gaps in rental fleet deployments.
Manual operation defends construction share. Automated platforms are climbing the fastest in warehousing adoption curves.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The cherry picker forklift industry traces its commercial origins to post-war European construction mechanization, with French and German manufacturers pioneering telescoping boom designs for cathedral restoration and industrial maintenance before global diffusion through American rental channels.
United States
E-commerce fulfillment networks in Dallas-Fort Worth and Phoenix are expanding electric fleet orders for vertical storage operations. OSHA aerial lift certification requirements mandate operator training programs that add fixed compliance costs for rental companies. The Inland Empire logistics corridor in Southern California concentrates warehousing demand for medium-reach electric platforms serving Amazon and Walmart distribution nodes.
Germany
Automotive parts warehouses in Baden-Württemberg are piloting autonomous cherry picker platforms for overnight inventory cycle counting. EU Green Deal procurement specifications now mandate zero-emission equipment preference for municipal infrastructure maintenance contracts. The North Rhine-Westphalia logistics belt around Cologne and Düsseldorf anchors heavy-lift platform demand for wind turbine servicing along the Lower Rhine.
China
Yangtze River Delta third-party logistics providers are driving equipment-as-a-service contracting models that displace traditional capital purchases. National dual carbon goals are accelerating diesel fleet phaseouts in favor of lithium iron phosphate configurations for indoor warehousing. The Shanghai-Ningbo port corridor concentrates cold chain infrastructure buildout requiring medium-reach electric platforms for high-bay racking operations.
India
Cold chain expansion in Maharashtra and Karnataka is generating first-time aerial platform adoption among domestic warehousing contractors. The national logistics infrastructure development program is channeling investment toward automated material handling equipment in tier-one distribution hubs. Mumbai-Pune industrial corridor operators are specifying electric cherry pickers for pharmaceutical manufacturing facilities subject to cleanroom access requirements.
United Kingdom
Telecom infrastructure maintenance contracts for 5G rollout are sustaining diesel platform demand for rural cell tower access lacking grid connectivity. HSE working at height regulations align with ISO 16368 structural safety benchmarks for mobile elevating work platforms. The Midlands distribution triangle around Birmingham concentrates rental fleet deployment for retail logistics operators serving London and Manchester consumption zones.
Cherry Picker Forklift Market Competitive Environment
Premium-margin players sit above commodity-margin players across control system sophistication and fleet telematics integration. The vendor base organizes into three tiers: integrated aerial work platform specialists with full boom fabrication capabilities, regional assemblers sourcing subsystems from Tier-1 suppliers, and rental fleet operators backward-integrating into refurbishment services. Consolidation pressure is intensifying through strategic partnerships for battery supply security and geographic expansion into underpenetrated logistics corridors.
Among established aerial platform fabricators, JLG Industries and Genie occupy positions within the premium-tier control systems segment, while Haulotte Group anchors European supply through French manufacturing scale. These three exemplify divergent strategic archetypes: integrated technology leadership, rental channel penetration, and regional production specialization respectively.
| Leading Market Players |
|---|
| JLG Industries |
| Genie |
| Haulotte Group |
| Manitou |
| SkyJack |
| Snorkel |
| Niftylift |
| Terex |
| Clark Material Handling |
| Others |
Value Chain & Pricing Dynamics
Equipment-as-a-service contracting in China's Yangtze River Delta logistics corridors is forcing manufacturers to restructure pricing around utilization guarantees rather than asset transfer, compressing upfront revenue recognition and demanding supply chain flexibility for rapid fleet reconfiguration.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates integrated telematics platforms from basic electric units and refurbished diesel workhorses. Price differentiation rests on ISO 16368 certification tier and after-sales service bundling. Cost compression in the economy tier is intensifying because lithium iron phosphate battery cost volatility squeezes smaller rental operators. Third-party logistics providers show highest price sensitivity; municipal infrastructure contractors demonstrate lowest sensitivity due to EU Green Deal procurement mandates.
Supply Chain Analysis
ISO 16368 certification gating concentrates qualified boom fabrication among French, German, and Chinese manufacturing hubs with validated weld inspection protocols. High-strength alloy steel for telescoping assemblies draws from East Asian foundries; lithium iron phosphate cells source from Chinese and South Korean cathode producers; hydraulic systems feed from German and Italian component specialists. Single-source vulnerability runs through specialized alloy supply. Distribution runs through regional rental fleet operators with certified maintenance capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play: EU Green Deal procurement premiums in Germany and France contrast with cost-driven diesel retention in India and rural China, creating margin dispersion for manufacturers with flexible production footprints.
For Market Incumbents: Lock in battery supply security through long-term cathode mineral offtakes with Chinese and South Korean producers to defend against lithium cost volatility eroding electric platform margins. Consolidate aftermarket service networks in Germany and the United States to capture recurring revenue as equipment-as-a-service contracts displace capital sales. For New Entrants and Emerging Players: Rental fleet operators in India's Maharashtra cold chain corridor represent the most penetrable channel partner type for first-time market entry. Target autonomous navigation retrofit kits for existing manual fleets in German automotive warehouses. Pursue white-label manufacturing partnerships with established French boom fabricators lacking battery-electric expertise. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-tier regional assemblers possessing ISO 16368 certification but lacking integrated telematics capabilities, positioned for acquisition by premium-tier players seeking European manufacturing scale. Battery chemistry breakthroughs in solid-state or sodium-ion architectures signal inflection points requiring model refresh.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Long-term cathode mineral contracts with Chinese producers secure cost visibility for electric platform margins. |
| Autonomous Navigation Integration | LiDAR-enabled self-positioning platforms reduce labor headcount in German automotive parts warehouses. |
| Equipment-as-a-Service Launch | Per-hour utilization contracts in China's Yangtze River Delta displace balance-sheet equipment loading. |
| Backward Integration into Boom Fabrication | In-house high-strength alloy welding capacity insulates against East Asian foundry tariff exposure. |
| EU Green Deal Certification Program | Zero-emission equipment preference in German municipal contracts creates mandated demand pull. |
Study Parameters
Multiple input streams — fleet manager interviews, OEM procurement director discussions, rental company operations data, and regulatory filing analysis — were reconciled through bottom-up and top-down triangulation. Primary fieldwork engaged maintenance directors at third-party logistics operators, plant engineers at automotive assembly facilities, aftermarket service heads at national rental chains, and OEM procurement teams at JLG Industries, Genie, and Haulotte Group. Secondary validation drew from OSHA enforcement databases, EPA Tier 4 Final compliance filings, ISO 16368 certification registries, and EU Green Deal procurement disclosure records.
Historical shipment trajectories were cross-referenced against expert panel inputs to anchor projections across the analysis window. Segmentation dimensions modeled include powertrain type, end-use vertical, platform height rating, and operation mode sophistication. CAGRs were derived from replacement cycle compression analysis and electrification mandate adoption curves. Industry-specific forecast inputs incorporated battery energy density improvement trajectories and autonomous navigation pilot program expansion rates.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to lithium raw material price regimes and autonomous technology maturation timelines. A model refresh is warranted upon material change in EPA emissions enforcement intensity or breakthrough battery chemistry commercialization.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Silo Bin Activators Market
Material Handling Equipment
Conveyor Sprocket Market
Material Handling Equipment
Global Tension Control Market
Material Handling Equipment
Surface Contact Wire Rope Market
Material Handling Equipment
Dewatering Screen Market
Material Handling Equipment
Flux Spraying Machine Market
Material Handling Equipment
Australia and New Zealand Industrial Fasteners Market
Material Handling Equipment
Electric Stacker Market
Material Handling Equipment
US Forklift Market
Material Handling Equipment
Wood Chipper Market
Material Handling Equipment
Material Handling Equipment Telematics Market
Material Handling Equipment
Global Refuse Compactor Market
Material Handling Equipment
Light Duty Telehandler Market
Material Handling Equipment
Truck Loader Crane Market
Material Handling Equipment
Vibrating Feed Conveyors Market
Material Handling Equipment
Roll Slitting Machines Market