
 Material Handling Equipment Telematics Market | 2026-2036
Material Handling Equipment Telematics Market Size, Share, and Industry Trends Forecast 2026-2036
Material Handling Equipment Telematics Market Intelligence
The scarcity of certified forklift operators is unwinding traditional warehouse staffing models, forcing a shift towards asset optimization. KION GROUP AG leverages its extensive service network to bundle telematics with long-term maintenance contracts. Crown Equipment Corporation differentiates through its proprietary fleet and warehouse management software integration. Toyota Industries Corporation sustains its market position by focusing on forklift-native telematics hardware development.
Material handling equipment telematics involves systems that capture and transmit operational data from industrial vehicles. These systems often integrate directly with a vehicle’s Controller Area Network (CAN bus) to monitor metrics like engine hours, fault codes, and impact events. Forklifts represent the dominant equipment type for both telematics retrofits and new installations. Within applications, Safety Monitoring is growing rapidly, driven by a focus on reducing workplace accidents.
Regulations from the U.S. Occupational Safety and Health Administration (OSHA) on operator accountability directly influence system requirements. In Europe, CE marking and GDPR compliance shape data security and hardware specifications for telematics units. Additionally, ISO 3691-4 standards for driverless industrial trucks create new data logging needs. The critical decision for fleet operators is choosing between OEM-embedded systems and third-party aftermarket solutions.
Market Dynamics
The convergence of operator safety mandates, such as those from the U.S. Occupational Safety and Health Administration (OSHA), and the economic imperative for asset optimization amid skilled labor shortages is the central force driving telematics adoption across industrial vehicle fleets.
Growth Catalysts
- Operator Safety Mandates:U.S. OSHA regulations requiring operator accountability and incident logging compel fleet owners to adopt telematics for compliance, particularly in high-risk warehousing and distribution centers.
- Automotive Manufacturing Efficiency:Intense pressure for just-in-time logistics within automotive clusters in Germany and the midwestern United States drives demand for telematics to maximize forklift uptime and fleet utilization.
- CAN Bus Integration:The standardization of Controller Area Network (CAN bus) systems in modern material handling equipment simplifies the retrofitting and installation of telematics devices, lowering implementation barriers for fleet managers.
Market Restraints
- High Initial Capital Outlay:The significant upfront cost of telematics hardware, coupled with recurring software subscription fees, presents a substantial financial barrier for small to medium-sized fleet operators with limited capital budgets.
- Legacy Fleet Integration:Integrating advanced telematics systems with older, non-CAN bus equipped material handling equipment is technically complex and costly, limiting market penetration in fleets with long asset lifecycles.
- Data Security and Privacy Concerns:Stringent data protection regulations like Europe's GDPR create compliance complexities for transmitting and storing sensitive operational and operator data, particularly for cross-border logistics firms.
Strategic Opportunities
- Predictive Maintenance Services:Leveraging telematics data for AI-driven predictive maintenance offers an opportunity to move beyond basic monitoring and create higher-value service revenue streams for OEMs and service providers.
- Expansion into Adjacent Equipment Markets:Adapting forklift telematics solutions for adjacent markets like construction and agricultural equipment represents an underpenetrated segment with similar needs for asset tracking and safety monitoring.
- Driverless Vehicle Data Logging:The emergence of ISO 3691-4 standards for driverless industrial trucks creates new requirements for specialized data logging, opening a new sub-market for telematics providers.
Industry Challenges
- Actionable Data Interpretation:Fleet managers often struggle to translate the vast amount of collected telematics data into actionable operational improvements, leading to underutilization of the system’s full capabilities.
- Skilled Technician Shortage:A scarcity of technicians skilled in both mechanical repair and telematics diagnostics creates a bottleneck for installation and maintenance, impacting system uptime and return on investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Material Handling Equipment Telematics Market |
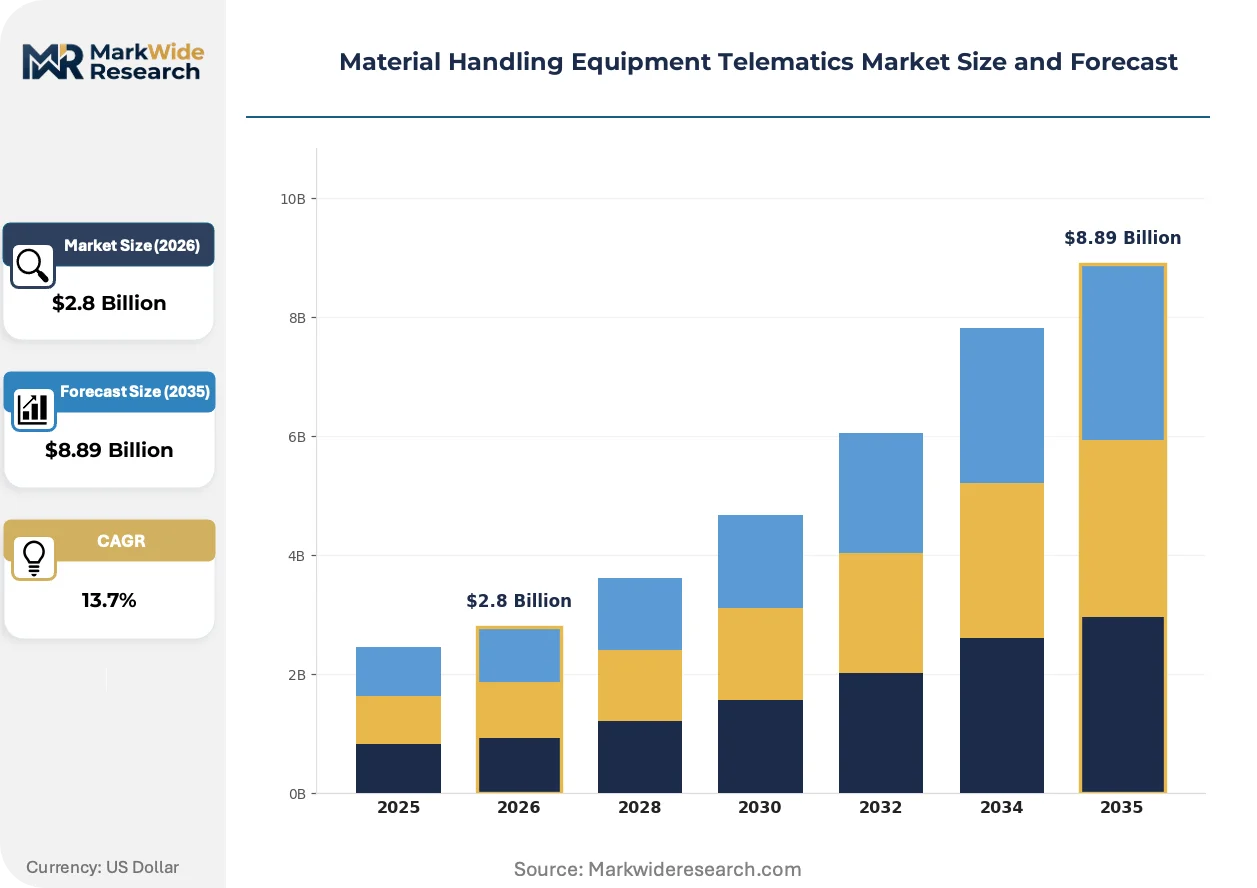
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $8.89 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Equipment Type: Forklifts, Conveyors, Automated Guided Vehicles, Cranes, Pallet Jacks Technology: GPS Tracking, RFID, Bluetooth, Wi-Fi, Telematics Control Units Application: Warehouse Automation, Fleet Management, Inventory Control, Load Optimization, Safety Monitoring End User: Manufacturing Plants, Logistics Providers, Distribution Centers, Third-Party Logistics, Supply Chain Operators |
| Companies Covered | Powerfleet, Toyota Industries Corporation, Crown Equipment Corporation, KION GROUP AG, Jungheinrich AG, Hyster-Yale Materials Handling, Inc., The Raymond Corporation, Caterpillar, MiX Telematics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Material Handling Equipment Telematics Market Strategic Shifts & Innovations
A fundamental shift from basic asset tracking toward integrated, data-driven fleet intelligence is defining the market's evolution. This transition prioritizes software-enabled insights over standalone hardware, altering how value is created and delivered to end-users.
Video-Enhanced Telematics
Video-based telematics, which combine traditional data capture with forward-facing and operator-facing cameras, provide critical visual context for impact events and near-misses. Third-party logistics providers and large retail distribution centers are rapidly adopting this technology to improve accident investigation. The rich, contextual data from video telematics is displacing reliance on simple G-force sensor alerts for safety management.
Automation-Ready Compliance
The ISO 3691-4 standard for driverless industrial trucks and automated guided vehicles establishes stringent requirements for system monitoring and operational data logging. This global standard necessitates the development of specialized telematics capable of validating the autonomous system’s decision-making. Automated warehouse segments are most affected, pushing vendors to engineer solutions that ensure compliance for this new class of equipment.
Bundled Service Models
Fleet operators are increasingly favoring bundled service agreements that combine equipment leases, maintenance contracts, and telematics subscriptions into a single operational expense. This model disrupts the traditional one-time hardware sale, shifting the competitive focus toward long-term service relationships and guaranteed uptime. This trend is most visible among large third-party logistics providers in Europe and North America.
Material Handling Equipment Telematics Market Segmentation
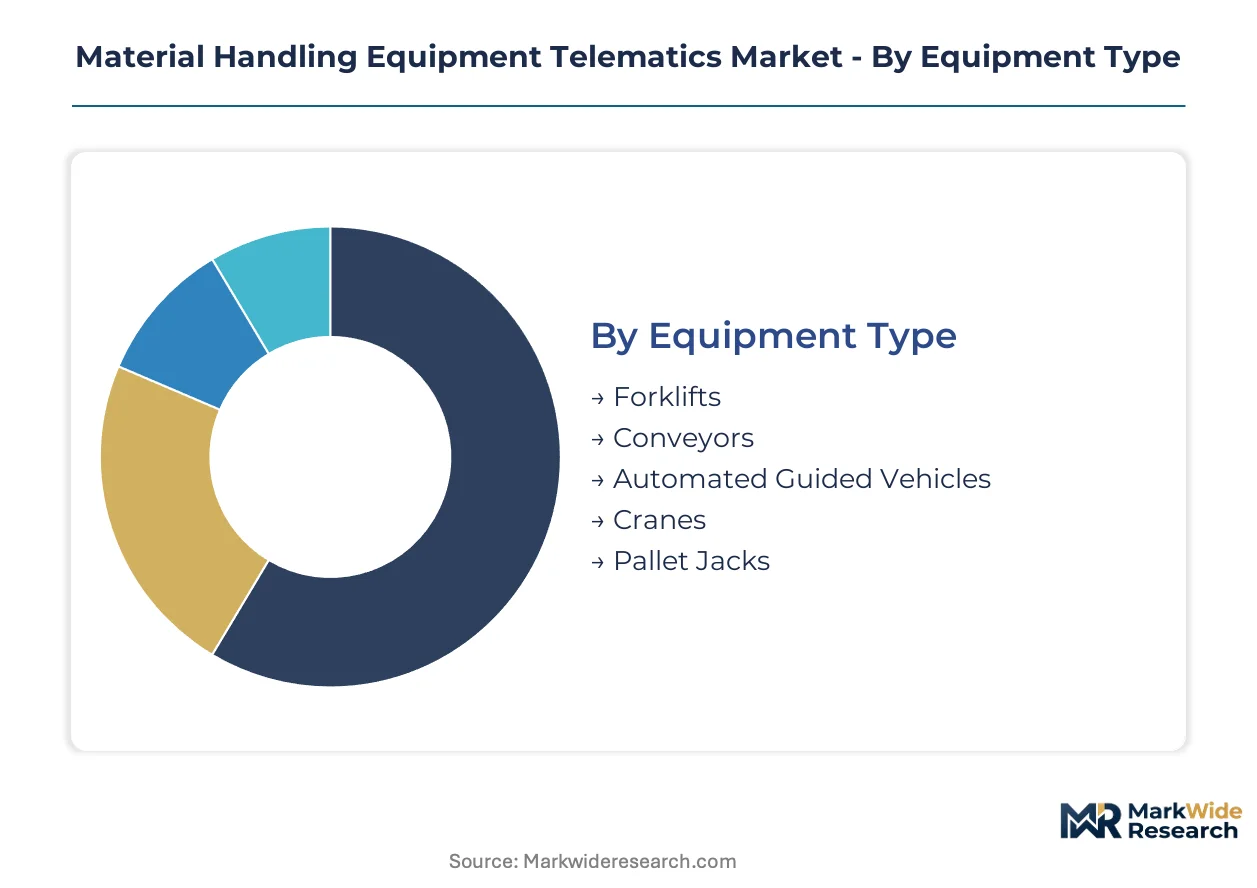
The Material Handling Equipment Telematics Market is meticulously segmented to provide a granular view of its diverse components. This detailed categorization helps stakeholders understand specific demand drivers, technological preferences, and end-user adoption patterns across the industrial landscape. Analyzing these segments reveals where value creation and operational efficiencies are most pronounced.
Equipment Type:
Margin pools within the equipment type category are influenced by equipment complexity, integration requirements, and regulatory compliance needs.
- Forklifts:These industrial trucks are designed for lifting and moving materials over short distances, representing the largest installed base for telematics retrofits and new installations. High volume demand from logistics providers and distribution centers drives widespread adoption for safety monitoring and fleet utilization.
- Automated Guided Vehicles:These driverless vehicles navigate using pre-defined paths or sensors, offering significant automation benefits in structured environments. Telematics for AGVs focuses on validating autonomous decision-making and ensuring compliance with ISO 3691-4 standards for advanced data logging.
- Conveyors:Telematics for conveyors primarily monitors operational uptime, throughput, and energy consumption within automated material flow systems.
- Cranes:Telematics solutions for cranes provide critical data on load handling, operational cycles, and preventative maintenance needs in heavy industrial settings.
- Pallet Jacks:These basic lifting devices benefit from telematics for asset tracking, utilization rates, and basic impact detection in smaller warehouse operations.
The dominant share belongs to Forklifts, while Automated Guided Vehicles is closing the gap fastest.
Technology:
Different technologies cater to varying operational scales and data requirements for material handling fleets.
- Telematics Control Units:These dedicated hardware devices serve as the central hub for data acquisition, processing, and transmission from material handling equipment. They integrate directly with the vehicle’s CAN bus to capture detailed operational metrics and fault codes.
- GPS Tracking:This technology provides real-time location data for material handling equipment, enabling geofencing, route optimization, and asset recovery across large operational areas. Fleet managers utilize GPS for enhanced visibility and operational control.
- RFID:Radio-Frequency Identification systems offer precise asset and inventory tracking within defined zones, often used for automated inventory management and access control.
- Bluetooth:This short-range wireless technology facilitates local data transfer, operator authentication, and proximity-based safety alerts on industrial equipment.
- Wi-Fi:Wi-Fi connectivity enables high-bandwidth data offloading and real-time communication for telematics systems within warehouse and distribution center networks.
Customer preferences lean towards Telematics Control Units for robust data collection, while GPS Tracking offers essential location intelligence.
Application:
The volume of data generated and processed varies significantly across different telematics applications, reflecting their specific functional demands.
- Safety Monitoring:This application focuses on detecting impacts, enforcing operator accountability, and tracking compliance with regulations from bodies like the U.S. Occupational Safety and Health Administration (OSHA). It provides critical data for accident investigation and prevention programs.
- Fleet Management:This broad application encompasses optimizing equipment utilization, scheduling maintenance, and improving overall operational efficiency across an entire fleet. It integrates data from various telematics sources to provide a holistic view of fleet performance.
- Warehouse Automation:Telematics data supports automated material flow, equipment coordination, and task assignment within highly structured warehouse environments.
- Inventory Control:Integrating telematics with inventory systems provides real-time visibility into material locations and movement, minimizing stockouts and improving accuracy.
- Load Optimization:This application uses telematics data to ensure proper load distribution, prevent overloading, and enhance equipment stability during material handling operations.
Operational efficiency gains are primarily driven by Fleet Management, with Safety Monitoring providing critical compliance and risk mitigation.
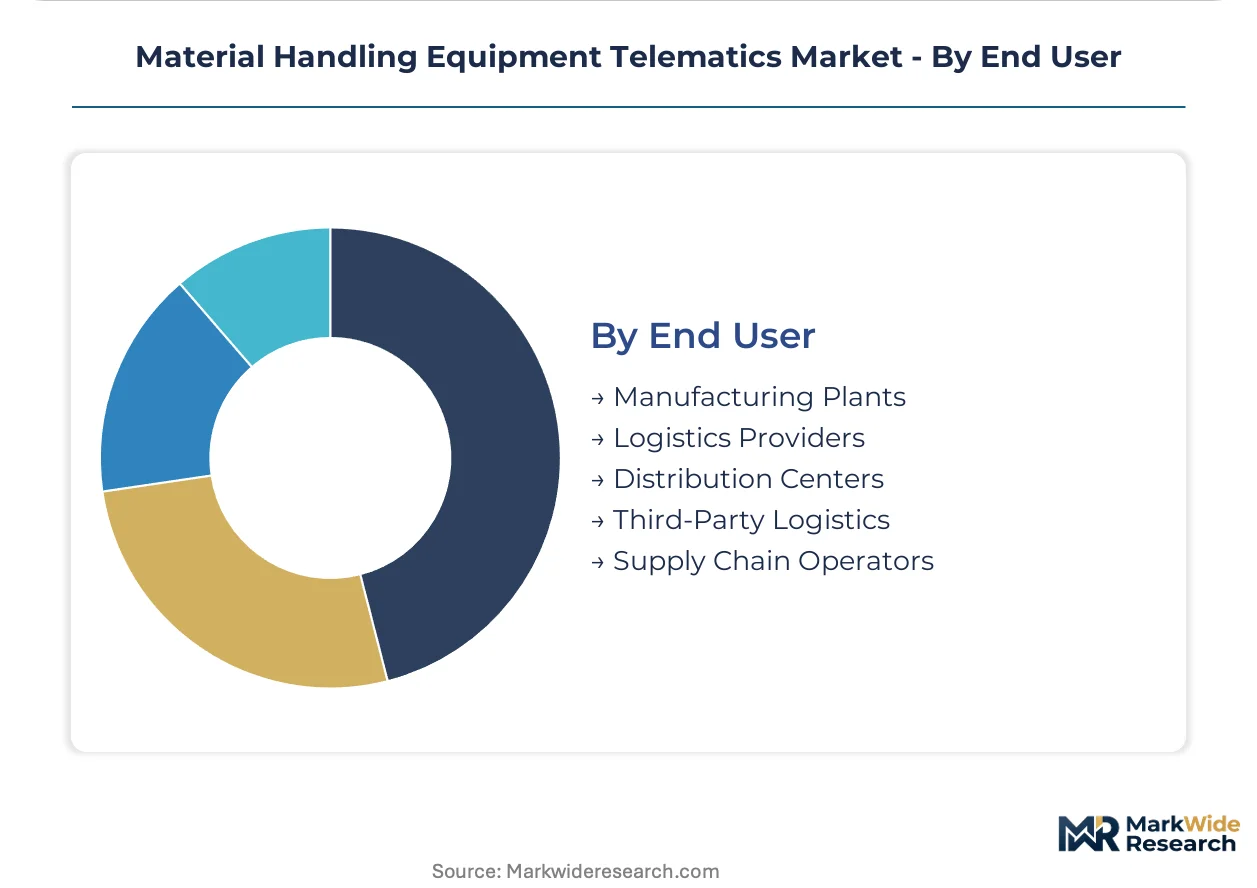
End User:
The maturity of telematics adoption varies across different end-user types, reflecting their specific operational complexities and investment priorities.
- Third-Party Logistics:These providers manage extensive fleets for multiple clients, making telematics essential for optimizing asset utilization, ensuring compliance, and delivering efficient service. Their focus is on maximizing throughput and minimizing downtime across diverse operational sites.
- Distribution Centers:High-volume distribution centers rely on telematics for managing large fleets of material handling equipment, enhancing safety, and improving order fulfillment accuracy. They prioritize real-time data for operational visibility and bottleneck identification.
- Manufacturing Plants:Telematics in manufacturing plants supports just-in-time logistics, line-side material delivery, and equipment maintenance scheduling.
- Logistics Providers:These entities utilize telematics for route optimization, driver performance monitoring, and asset tracking across their varied material handling operations.
- Supply Chain Operators:Telematics offers end-to-end visibility across the supply chain, from inbound logistics to outbound distribution, enhancing coordination and efficiency.
Large-scale adoption is spearheaded by Third-Party Logistics, as Distribution Centers integrate telematics into complex operational workflows.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
U.S. Occupational Safety and Health Administration (OSHA) mandates for operator safety anchor demand for material handling equipment telematics. These regulations compel fleet owners to adopt monitoring systems, particularly for forklifts and other industrial vehicles. This regulatory push, combined with efficiency needs, drives market expansion across key global regions.
United States
Demand in the United States is driven by stringent operator safety mandates and the imperative for asset optimization. U.S. OSHA regulations requiring operator accountability directly influence system requirements for telematics. Automotive manufacturing clusters across the Midwestern United States intensely adopt telematics to maximize forklift uptime and fleet utilization.
Germany
Germany exhibits strong demand for telematics, particularly within its highly efficient automotive manufacturing sector. CE marking and GDPR compliance shape data security and hardware specifications for telematics units across the country. Major automotive production hubs in Southern Germany leverage telematics for precise just-in-time logistics and fleet management.
China
China's material handling telematics market expands with rapid warehouse automation and vast e-commerce logistics operations. National GB standards for industrial equipment increasingly incorporate data logging and safety monitoring requirements. The Yangtze River Delta, a major logistics and manufacturing hub, sees significant investment in advanced telematics solutions.
Japan
Japan's market for material handling telematics benefits from its advanced manufacturing base and focus on operational precision. JIS standards for industrial machinery often integrate telematics compatibility for enhanced safety and efficiency. High-tech production facilities in the Kanto region utilize telematics for meticulous inventory control and predictive maintenance strategies.
United Kingdom
The United Kingdom shows robust adoption, driven by its extensive third-party logistics sector and large distribution centers. GDPR compliance significantly influences data handling and privacy requirements for telematics systems operating in the UK. The Midlands region, a critical logistics nexus, increasingly deploys telematics for fleet optimization and safety monitoring.
Material Handling Equipment Telematics Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier within the material handling equipment telematics market. This tiered structure reflects the diverse needs of fleet operators, from large OEMs offering bundled services to niche providers focusing on specific technologies. Strategic archetypes include equipment manufacturers integrating telematics, dedicated telematics solution providers, and software specialists. Market players consistently pursue portfolio diversification and strategic partnerships to expand their service offerings.
On the premium-tier vector, KION GROUP AG and Crown Equipment Corporation represent established material handling equipment manufacturers. KION GROUP AG exemplifies a strategy of leveraging an extensive service network to bundle telematics with long-term maintenance contracts, reinforcing customer loyalty. Crown Equipment Corporation occupies a position focused on differentiating through proprietary fleet and warehouse management software integration, enhancing operational control for users. Toyota Industries Corporation, another major OEM, anchors its market presence by concentrating on forklift-native telematics hardware development, ensuring seamless vehicle integration.
| Leading Market Players |
|---|
| Powerfleet |
| Toyota Industries Corporation |
| Crown Equipment Corporation |
| KION GROUP AG |
| Jungheinrich AG |
| Hyster-Yale Materials Handling, Inc. |
| The Raymond Corporation |
| Caterpillar |
| MiX Telematics |
| Others |
Cost & Logistics Intelligence
High asset utilization in material handling equipment telematics underwrites competitive pricing across large fleet operators, driving supply concentration among established OEMs. This dynamic ensures that cost efficiencies achieved through scale production are partially passed on to high-volume buyers, influencing market entry barriers.
Pricing Analysis
Geographic price spreads for telematics solutions vary significantly, influenced by regional regulatory compliance costs like GDPR in Europe versus OSHA mandates in the U.S. The dominant pricing structure is subscription-based SaaS, often tiered by fleet size and feature set. Price differentiation stems from the level of proprietary software integration and after-sales service bundling. Pricing pressure stems from increased competition from third-party aftermarket solutions. Small to medium-sized fleet operators exhibit the highest price sensitivity, while large Third-Party Logistics providers prioritize value and integration.
Supply Chain Analysis
Semiconductor availability for telematics control units (TCUs) remains a critical chokepoint, impacting production timelines. Geographic supply concentration for telematics hardware primarily resides in China and Taiwan, with specialized sensor components sourced globally. Key dependencies include microcontrollers, GPS modules, and CAN bus interface chips. Single-source vulnerability for specific components presents a structural supply chain risk. Distribution runs through OEM channels for embedded systems and specialized integrators for aftermarket solutions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The material handling telematics market faces a significant gap in skilled technicians capable of both mechanical repair and telematics diagnostics. This technical expertise deficit limits system uptime and return on investment for fleet operators.
For Market Incumbents: Shield core OEM market share by deepening integration of telematics with proprietary equipment and maintenance contracts. This defends against rising competition from third-party aftermarket solutions. Invest in advanced AI-driven predictive maintenance platforms, leveraging extensive service networks as a key lever for customer retention. Reinforce brand loyalty through superior customer service and tailored software features.
For New Entrants and Emerging Players: Differentiate on specialized data interpretation services for fleet managers struggling with actionable insights. Target underpenetrated adjacent equipment markets like construction and agriculture, where asset tracking and safety monitoring needs are similar. Offer flexible, cloud-native SaaS models as a go-to-market angle for mid-sized fleets. Focus on compliance-driven solutions for specific regulatory niches.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among providers offering bundled service models that combine hardware, software, and maintenance. Long-term viability for this market remains robust over the next decade, driven by ongoing safety mandates and automation trends. Target specialized software analytics firms with strong data science capabilities for acquisition. The signal to watch is the increasing adoption rate of video-enhanced telematics across new installations.
| Strategic Initiative | Industry Significance |
|---|---|
| Expand Predictive Maintenance AI | Leverages telematics data to create higher-value service revenue streams for OEMs. |
| Vertical Integration into Sensor Manufacturing | Secures critical component supply and reduces dependency on external semiconductor vendors. |
| Develop Automation-Ready Telematics | Addresses ISO 3691-4 standards for driverless industrial trucks, opening a new sub-market. |
| Strategic Partnership with Robotics Firms | Integrates telematics solutions directly into emerging automated guided vehicles (AGVs) platforms. |
| Global Certification for Data Security | Ensures compliance with diverse regional regulations like GDPR and national GB standards for cross-border logistics. |
Research Approach
Findings reconcile primary fieldwork against secondary review of regulatory documents, corporate financial reports, and industry association publications. Primary interviews engaged material handling equipment manufacturers, fleet managers, telematics solution providers, and logistics executives. This approach ensured bottom-up market sizing complemented by top-down validation, integrating diverse perspectives on adoption drivers and technological shifts.
Segmentation dimensions modeled include equipment type, technology, application, end-user, and regional adoption patterns across the analysis window. The analytical framework incorporates historical data analysis and projected growth rates, deriving compound annual growth rates (CAGRs) from demand-side indicators and supply-side capacity expansions. Key forecast inputs include industrial production indices and e-commerce growth projections.
Material uncertainties — including unforeseen macroeconomic downturns, rapid regulatory shifts, or disruptive technological advancements — sit outside the modeled envelope. Forecasts reflect assumptions about market stability and technology evolution. Revision becomes warranted when significant shifts in global trade policies or skilled labor availability cross critical thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Industrial Hose Assemblies Market
Material Handling Equipment
Bulk Material Handling Products and Technologies Market
Material Handling Equipment
High Pressure Grinding Rollers Market
Material Handling Equipment
Crane Mats Market
Material Handling Equipment
Cherry Picker Crane Market
Material Handling Equipment
Bale Clamp Intensive Market
Material Handling Equipment
Hot-Rolling Mill and Cold-Rolling Mill Market
Material Handling Equipment
High-Density Racks Market
Material Handling Equipment
Global Mechanical Seals Market
Material Handling Equipment
Enclosed Belt Conveyors Market
Material Handling Equipment
Carry Deck Crane Market
Material Handling Equipment
Lump Breaker Machines Market
Material Handling Equipment
India Automated Material Handling (AMH) Market
Material Handling Equipment
Trencher Attachments Market
Material Handling Equipment
Global Tension Control Market
Material Handling Equipment
Swivel Coupler Market