
 Cherry Picker Crane Market | 2026-2036
Cherry Picker Crane Market Size, Share, and Industry Trends Forecast 2026-2036
Cherry Picker Crane Market Outlook
Multi-source procurement for boom assemblies and hydraulic systems is recalibrating how OEMs manage supplier relationships across the cherry picker crane supply base. Terex Corporation leverages captive manufacturing for its Genie brand to control boom fabrication quality and delivery schedules. JLG Industries anchors its competitive stance through intensive R&D spending on electrified drive systems for urban jobsites. Haulotte Group differentiates through specialized articulating designs for confined-space European construction zones.
A cherry picker crane is a mobile elevated work platform comprising a hydraulically actuated boom with a personnel basket, typically offering working heights from 9 to 56 meters and load capacities up to 450 kilograms, designed to position workers safely at height for installation, repair, or inspection tasks. Self-propelled units lead product type demand due to their maneuverability on congested urban projects where truck-mounted alternatives face access constraints. Electric operation mode categories are gaining structural share as city-center contractors face emissions restrictions and noise ordinances that penalize diesel-hydraulic alternatives. Trailer-mounted segments occupy a mature niche serving seasonal landscaping and small-scale maintenance where capital budgets limit fleet investment.
FAA regulations govern cherry picker crane use near airport approach zones, while OSHA standards mandate fall protection and annual inspection protocols that shape equipment specification and training service demand. The EU Machinery Directive and CE marking requirements enforce design safety integration and conformity assessment procedures for market access across member states. Stakeholders must monitor how evolving carbon border adjustments and battery-electric infrastructure investments reshape total cost of ownership calculations for fleet operators weighing diesel against electrified platform investments.
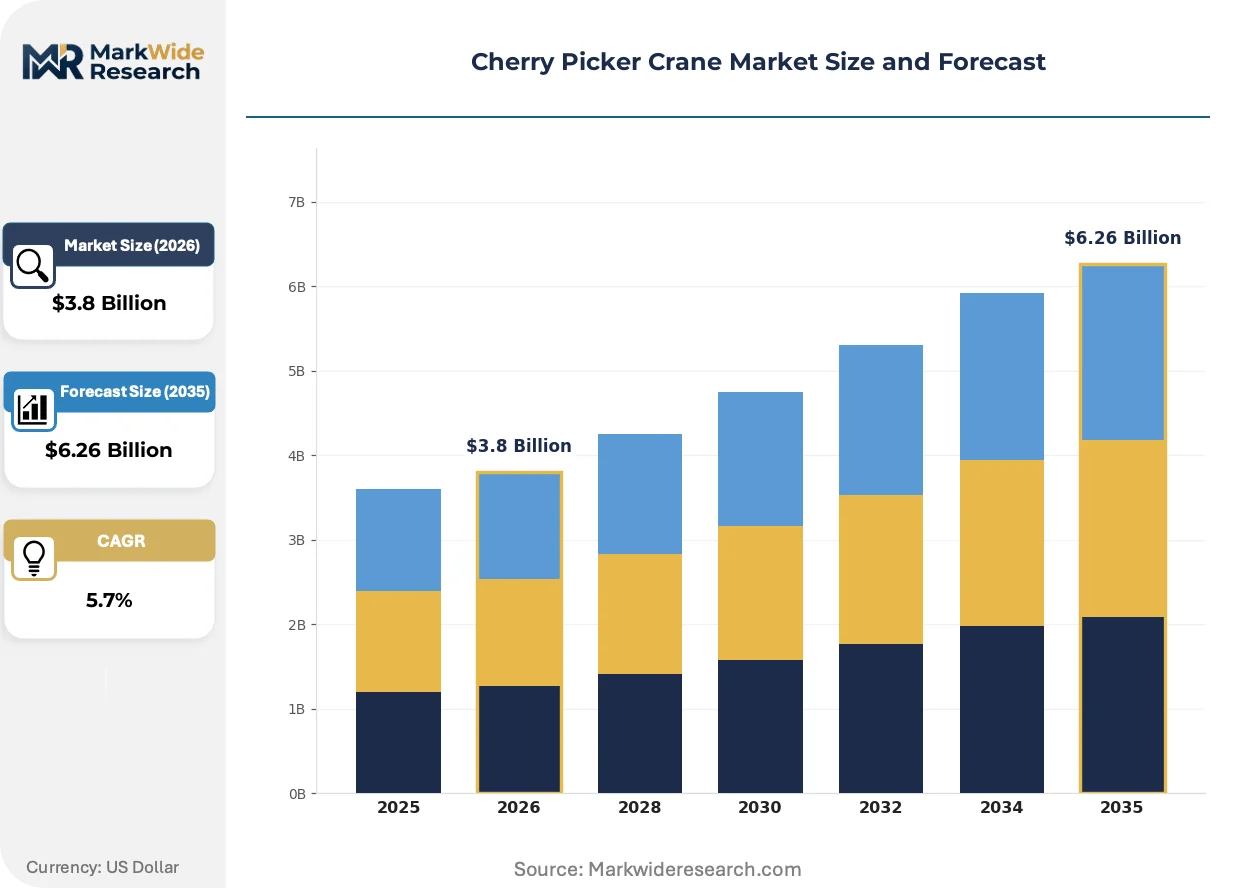
Market Dynamics
Electrification mandates across urban construction zones are compressing replacement cycles for diesel-hydraulic fleets as contractors face emissions penalties and noise ordinances that disqualify conventional units from city-center contracts.
Growth Catalysts
- OSHA Aerial Lift Standards:Tightened operator certification requirements in the United States are expanding training service markets and driving equipment upgrades to compliant platforms with integrated fall protection.
- Telecom 5G Infrastructure:Network densification projects across Germany are accelerating boom lift utilization for antenna installation at height, creating sustained fleet demand from rental providers.
- Lithium-Ion Battery Platforms:Zero-emission operation capabilities are unifying indoor-outdoor application flexibility, allowing single units to serve manufacturing facilities and exterior maintenance without equipment swaps.
Market Restraints
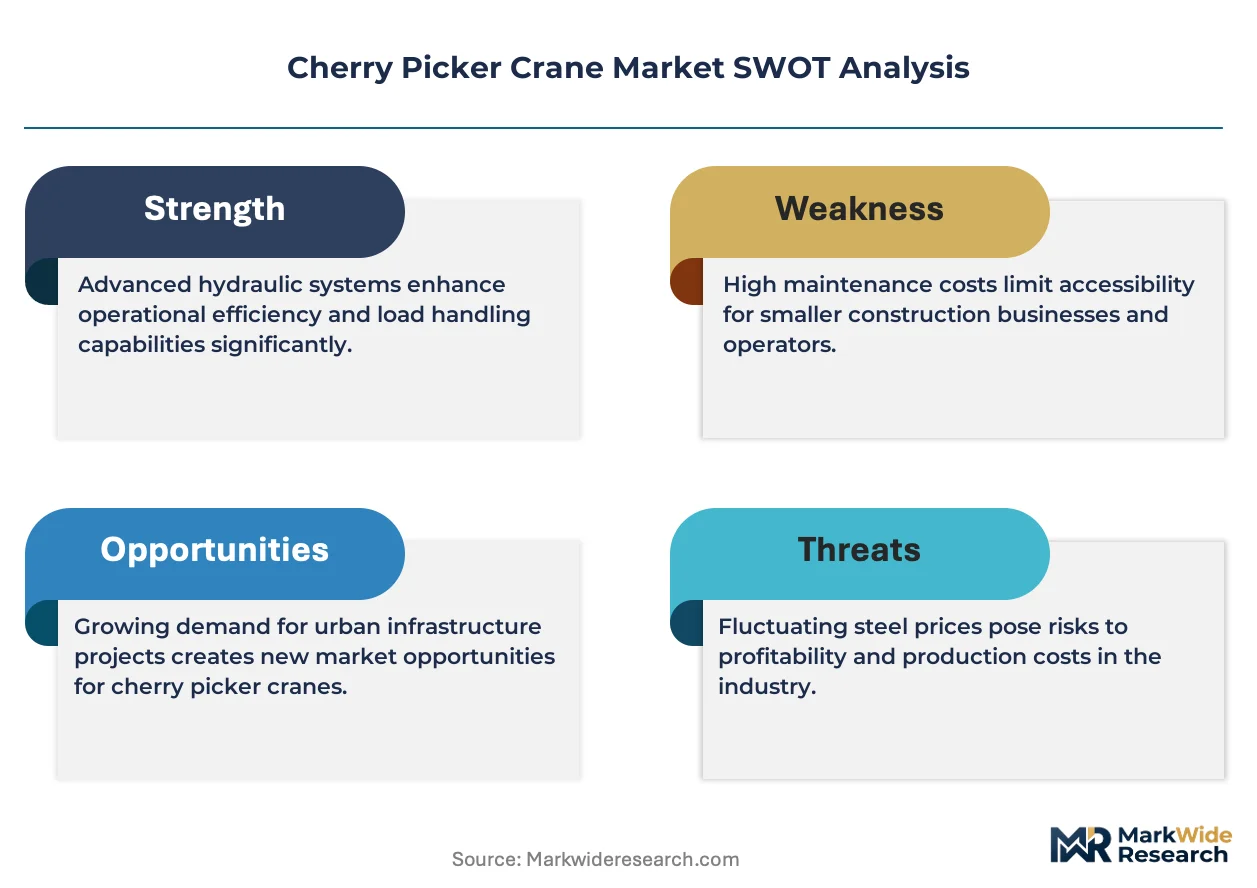
- Steel and Aluminum Input Volatility:Boom fabrication costs fluctuate with commodity metal pricing, squeezing OEM margins on fixed-price municipal contracts.
- Hydraulic Component Concentration:Precision valve and pump sourcing clusters in German and Italian supplier networks, creating vulnerability to regional logistics disruptions.
- Scaffold Substitution:Fixed scaffolding systems retain cost advantage for long-duration facade projects, limiting cherry picker penetration in commercial building construction.
Strategic Opportunities
- India Urban Infrastructure:Smart city initiatives and metro rail expansion are opening fleet procurement channels previously dominated by manual access methods.
- EU Carbon Border Adjustment:Import tariff mechanisms are creating cost advantages for European-manufactured electric platforms over Asian diesel competitors.
- Telematics-Rental Convergence:IoT-enabled utilization tracking is enabling outcome-based equipment subscriptions that shift capital burden from contractors to rental houses.
Industry Challenges
- Certified Technician Scarcity:Hydraulic diagnostics and boom geometry calibration require specialized training that outpaces vocational program output in key markets.
- CE Conformity Assessment Timelines:EU Machinery Directive compliance documentation delays product launches by 4-8 months, compressing competitive windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cherry Picker Crane Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Truck-mounted, Self-propelled, Trailer-mounted, Mini Application: Construction, Maintenance, Telecommunication, Tree Care End User: Contractors, Facilities Management, Public Utilities, Landscaping Operation Mode: Manual, Electric, Hydraulic, Pneumatic |
| Companies Covered | Terex Corporation (Genie), JLG Industries, Skyjack, Haulotte Group, Zhejiang Dingli Machinery, Teupen Maschinenbau, Aichi Corporation, J.C. Bamford Excavators, Altec, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cherry Picker Crane Market Strategic Shifts
Digitalization of fleet management and powertrain electrification are converging to redefine equipment lifecycle economics, with connectivity platforms now treated as standard rather than premium specifications.
Lithium-ion battery systems with opportunity charging capability are unifying intermittent-duty urban workflows, allowing rental fleets to deploy identical units across construction sites and facility maintenance contracts without refueling infrastructure. Municipal contractors in Paris and Amsterdam are specifying all-electric minimums for public works tenders, accelerating OEM investment in thermal management and fast-charge architectures. This unification is compressing the traditional product stratification between diesel outdoor units and electric indoor machines.
CE marking requirements under the EU Machinery Directive are mandating design safety integration and third-party conformity assessment for all new platform introductions. OEM engineering teams must embed risk analysis documentation and fail-safe hydraulic circuits earlier in development cycles. German rental houses report 15-20% longer product development timelines but reduced field liability exposure.
After-sales service unbundling is disrupting traditional equipment-rental bundles as large facility management teams insource maintenance using manufacturer training programs. JCB and Skyjack have responded with certified technician academies that transfer diagnostic capability to buyer organizations. This pattern is most visible in the United Kingdom, where institutional property portfolios exceed 10,000 units and downtime costs justify captive repair investment.
Cherry Picker Crane Market Segmentation
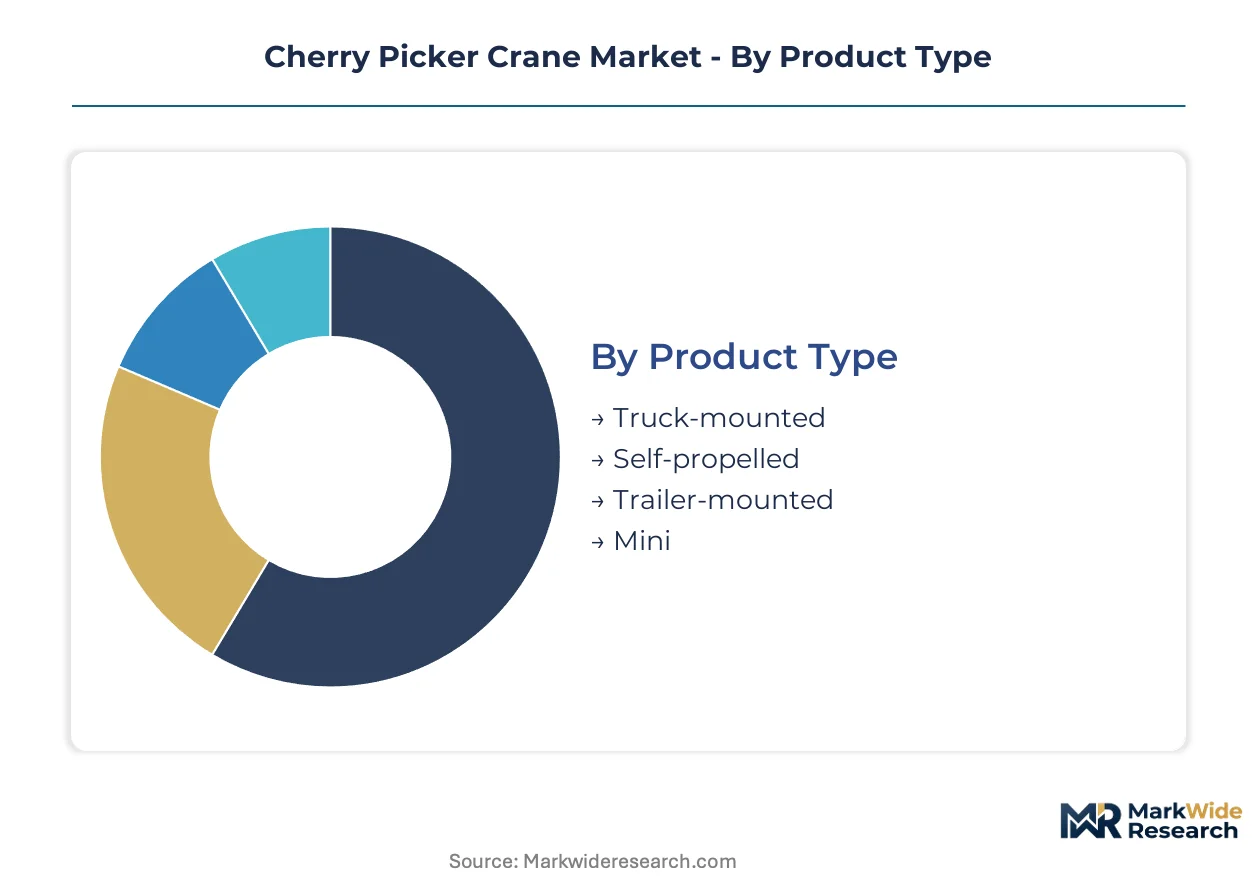
Segmentation in the cherry picker crane market reveals how equipment specification directly shapes procurement patterns across rental fleets and contractor operations. Understanding these divisions clarifies why electrified self-propelled units command premium positioning while trailer-mounted alternatives serve cost-constrained seasonal demand.
Product Type:
Working height capability and transport logistics define how OEMs allocate engineering resources across mobility architectures.
- Self-propelled:These units integrate drive systems and stabilizers into a single chassis, enabling 360-degree rotation and precise positioning on congested urban jobsites. Demand concentrates in Germany and France where municipal contractors face emissions restrictions that disqualify truck-mounted alternatives from city-center tenders.
- Truck-mounted:Highway-speed mobility suits rapid deployment across dispersed infrastructure networks, particularly for utility maintenance crews covering wide service territories. Fleet procurement here clusters with public utilities in the United States where OSHA aerial lift standards mandate integrated fall protection systems.
- Trailer-mounted:Compact towable designs serve landscaping contractors and small maintenance operations with intermittent height access needs.
- Mini:Narrow-width platforms access interior atriums and retail spaces where standard units cannot maneuver.
Mature deployment sits with truck-mounted configurations. Newer deployment is concentrated in self-propelled electric variants.
Application:
Project duration and height specifications determine rental rate structures and fleet composition strategies.
- Construction:Multi-month building projects demand robust boom cycles and heavy load ratings for material handling alongside personnel positioning. Activity concentrates in India where smart city initiatives and metro rail expansion are displacing manual scaffolding methods.
- Maintenance:Recurring facility service contracts favor standardized platforms with telematics integration for utilization tracking. European facilities management teams are expanding fleet purchases as building maintenance cycles compress.
- Telecommunication:Antenna installation at height requires precise boom articulation for 5G network densification projects.
- Tree Care:Seasonal demand patterns and rough terrain capability shape equipment specification for arborist contractors.
Long-cycle deployment dominates construction applications. Fastest-expanding deployment is concentrated in maintenance contracts.
End User:
Capital availability and technical staffing determine whether organizations purchase outright, rent, or subscribe to equipment-as-a-service models.
- Facilities Management:Large property portfolios justify captive technician training and insourced maintenance programs, particularly in the United Kingdom where institutional owners exceed 10,000-unit fleets. Procurement patterns here favor telematics-enabled platforms that integrate with building management systems.
- Contractors:Project-based cash flows drive rental dependency, with preference for electric units that qualify for urban emissions-compliant tenders in Amsterdam and Paris.
- Public Utilities:Rate-regulated capital budgets support multi-year fleet replacement cycles with extended warranty requirements.
- Landscaping:Seasonal revenue limits equipment investment to trailer-mounted or mini configurations.
Volume concentration sits with contractors. Margin expansion is concentrated in facilities management accounts.
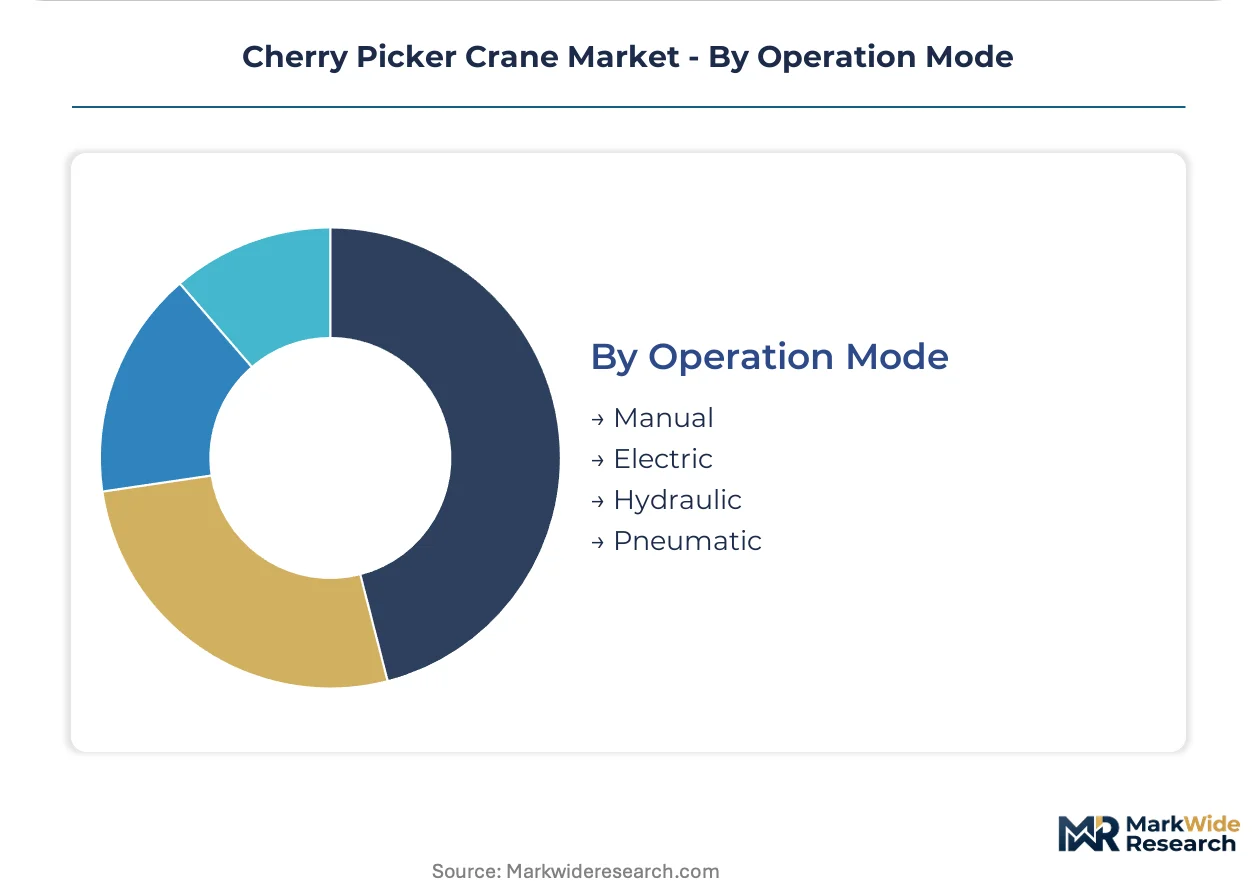
Operation Mode:
Powertrain selection now determines market access rather than merely operational cost, with regulatory thresholds reshaping technology deployment.
- Electric:Lithium-ion battery systems with opportunity charging unify indoor-outdoor workflows, eliminating equipment swaps between manufacturing facilities and exterior maintenance. Municipal tenders in Paris and Amsterdam now specify all-electric minimums, compressing demand for diesel alternatives.
- Hydraulic:Diesel-hydraulic platforms retain dominance in remote infrastructure projects lacking charging infrastructure, though face carbon border adjustment disadvantages in European procurement.
- Manual:Push-around units serve confined maintenance tasks with minimal height requirements.
- Pneumatic:Compressed air operation addresses explosive atmosphere applications in specific industrial settings.
Established deployment sits with hydraulic systems. Steepest expansion trajectory is concentrated in electric platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Steel mills in Duisburg and Dortmund supply boom-grade high-strength alloy to German fabricators, anchoring European cherry picker crane production geography.
United States
Utility infrastructure renewal and telecom tower maintenance drive fleet replacement demand across the Midwest and Southeast. OSHA aerial lift standards mandate annual inspections and operator certification that shape procurement specifications. Dallas-Fort Worth rental houses report accelerated electrification of municipal contractor fleets to meet urban emissions thresholds.
Germany
5G network densification and wind turbine servicing compress replacement cycles for aging boom lift fleets. CE marking requirements under the EU Machinery Directive enforce design safety integration and third-party conformity assessment. Bavarian rental providers concentrate equipment procurement for Munich's construction zone electrification mandates.
China
Metro rail expansion and smart city infrastructure projects displace manual scaffolding methods in tier-one urban corridors. GB standards and MIIT industrial equipment regulations govern platform safety certification and manufacturing quality. Yangtze River Delta fabricators in Shanghai and Suzhou scale electric platform output for domestic facilities management demand.
India
Urban metro construction and airport modernization projects open fleet procurement channels previously dominated by ladder-based access methods. BIS certification requirements and CEA electrical safety codes shape equipment import and local assembly decisions. Maharashtra contractors in Mumbai and Pune expand mechanized platform adoption for high-rise facade maintenance contracts.
United Kingdom
Institutional property portfolios exceeding 10,000 units justify insourced maintenance programs and captive technician training investment. HSE work-at-height regulations mandate documented risk assessment and platform selection protocols. London facilities management teams specify telematics-enabled platforms that integrate with building management systems for utilization tracking.
Cherry Picker Crane Market Competitive Environment
Global majors compete with regional champions across electrification technology and rental service network density. The vendor base stratifies into three tiers: integrated multi-brand conglomerates with captive manufacturing, specialized European articulating boom designers, and scale-focused Asian fabricators serving price-sensitive emerging markets. Dominant competitive moves include M&A to secure telematics platforms and geographic expansion through rental house partnerships rather than direct sales force investment.
Within the integrated multi-brand tier, Terex Corporation and JLG Industries exemplify archetypes combining captive boom fabrication with intensive R&D allocation toward electrified drive systems. Zhejiang Dingli Machinery represents the scale-focused Asian fabrication model. These three anchors illustrate how competitive positioning diverges across technology leadership, manufacturing integration depth, and regional market access strategies.
| Leading Market Players |
|---|
| Terex Corporation (Genie) |
| JLG Industries |
| Skyjack |
| Haulotte Group |
| Zhejiang Dingli Machinery |
| Teupen Maschinenbau |
| Aichi Corporation |
| J.C. Bamford Excavators |
| Altec |
| Others |
Value Chain & Pricing Dynamics
Paris municipal electrification mandates gate qualified supply and premium-tier pricing access for cherry picker crane procurement, filtering OEM participation to manufacturers with certified battery-electric platforms and EU conformity documentation. Contractors bidding city-center tenders face dual qualification barriers: equipment emissions compliance and OEM service network density.
Pricing Analysis
Warranty and service bundling separates premium-tier OEM offerings from unbundled economy alternatives, with extended coverage and certified technician training commanding substantial markups. Pricing stratifies across premium, standard, and economy tiers based on CE marking tier and telematics integration level. Cost compression in economy segments is intensifying because Asian fabricators compete on bare-equipment pricing. Facilities management teams show lowest price sensitivity due to downtime cost exposure, while seasonal landscaping contractors drive hardest bargain.
Supply Chain Analysis
Direct-to-rental-house channels handle fleet-scale procurement volumes, bypassing distributor markups for municipal and contractor buyers. Boom-grade high-strength steel draws from German and Chinese mill networks, while precision hydraulic components rest on Italian and German supplier clusters. Single-source vulnerability concentrates in German valve and pump manufacturers. Distribution runs through rental house networks with regional service depots.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized hydraulic technician training capacity acts as the binding constraint propping equipment pricing and service margins across European markets.
For Market Incumbents: Acquire telematics platform capabilities to defend against rental-house insourcing trends and outcome-based subscription models. Secure captive supply of lithium-ion battery modules through backward integration or long-term offtake with Korean cell manufacturers. Capacity addition in India addresses emerging smart city demand before local fabricators scale. For New Entrants and Emerging Players: Begin with trailer-mounted electric configurations for Indian landscaping contractors, where manual ladder methods still dominate and capital constraints limit fleet investment. Target Maharashtra state metro rail maintenance contracts as the most penetrable segment, leveraging BIS certification pathways faster than CE marking timelines. Pursue rental house partnership rather than direct sales force buildout. For Investors and Strategic Acquirers: Munich construction zone electrification enforcement is the leading indicator that German rental fleet replacement cycles will accelerate toward battery-electric platforms. Over the coming decade, acquisition targets should prioritize European OEMs with integrated CE marking capabilities and established technician training academies. Watch for carbon border adjustment implementation as the signal for European-manufactured platform cost advantage crystallization.| Strategic Initiative | Industry Significance |
|---|---|
| Technician Training Academy Expansion | JCB and Skyjack models transfer diagnostic capability to buyer organizations, reducing rental dependency. |
| Battery Supply Agreement | Korean cell manufacturer partnerships secure lithium-ion module allocation for electric platform scaling. |
| CE Marking Fast-Track Investment | Third-party conformity assessment pre-positioning compresses product launch timelines by 4-8 months. |
| Telematics Platform Acquisition | IoT utilization tracking enables outcome-based equipment subscriptions shifting capital burden. |
| India Manufacturing Footprint | Local assembly addresses BIS certification requirements and metro rail procurement channels. |
Study Parameters
Independent corroboration across OEM product managers, rental fleet directors, and facilities maintenance executives underwrites the qualitative findings in this study. Primary fieldwork engaged boom lift procurement leads at German municipal contractors, Indian metro project engineers, and UK property portfolio managers. Secondary validation drew from OSHA enforcement databases, EU Machinery Directive conformity assessment registries, and BIS certification filings. Bottom-up equipment shipment tallies and top-down construction spending aggregates were reconciled.
Comparable-period anchoring to historical fleet replacement cycles and maintenance contract renewal patterns shaped the projection horizon. Segmentation modeling spanned product type, operation mode, application, and end-user archetype. CAGRs were derived from equipment unit economics and regional construction output trajectories. Forecast inputs incorporated electrification mandate adoption curves and carbon border adjustment implementation schedules.
Underlying measurement precision varies by segment; electric platform forecasts carry tighter precision than hydraulic alternatives due to policy visibility. Forecasts reflect assumptions about battery cost trajectories and charging infrastructure buildout. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Low-Level Order Picker Pallet Truck Market
Material Handling Equipment
Electric Wire Rope Hoist Market
Material Handling Equipment
Global Metal Expansion Joints Market
Material Handling Equipment
Global Lifting Columns Market
Material Handling Equipment
Hydraulic Cylinder Rod Market
Material Handling Equipment
Europe Port Equipment Market
Material Handling Equipment
Japan Conveyor Belt Market
Material Handling Equipment
Hose Pipe Market
Material Handling Equipment
Can Racks Market
Material Handling Equipment
Global Refuse Compactor Market
Material Handling Equipment
Level Loader Market
Material Handling Equipment
Crawler Crane Market
Material Handling Equipment
ASEAN Conveyor System Market
Material Handling Equipment
Sorting Machines Market
Material Handling Equipment
Port Equipment Market
Material Handling Equipment
Tree Milling Machine Market