
 Electric Stacker Market | 2026-2036
Electric Stacker Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Stacker Market Foresight
Multi-source procurement for battery packs and drive motors is shifting toward vertically integrated supply chains among top-tier electric stacker manufacturers. KION Group AG leverages in-house controller development to secure margin on 48V platforms. Toyota Material Handling anchors its competitive stance through captive production of AC induction motors across Asian and North American assembly plants. Jungheinrich AG differentiates via specialization in narrow-aisle reach stackers for high-density European warehousing configurations.
An electric stacker is a battery-powered pedestrian or rider-operated material handling machine designed to lift, transport, and stack palletized loads at heights typically ranging from 2.5 to 6 meters, utilizing mast assemblies with hydraulic lift cylinders and load backrests for stability. The machine serves warehousing and manufacturing facilities where forklift access is restricted by aisle width, floor loading, or emission constraints. Reach stackers and straddle stackers command premium positioning in narrow-aisle applications where footprint efficiency directly correlates to storage density economics. Counterbalanced stackers retain volume leadership across general warehousing end users due to lower acquisition cost and broader operator familiarity.
OSHA mandates operator training certification and equipment inspection protocols that shape fleet purchase decisions toward models with integrated safety interlocks and overload protection systems. The EU F-Gas Regulation and national carbon reduction frameworks in Germany and France accelerate phase-out of internal combustion equipment in indoor logistics environments. Stakeholders must weigh total cost of ownership calculations against acquisition price as battery chemistry transitions and energy pricing volatility reshape operating economics across fleet replacement cycles.
Market Dynamics
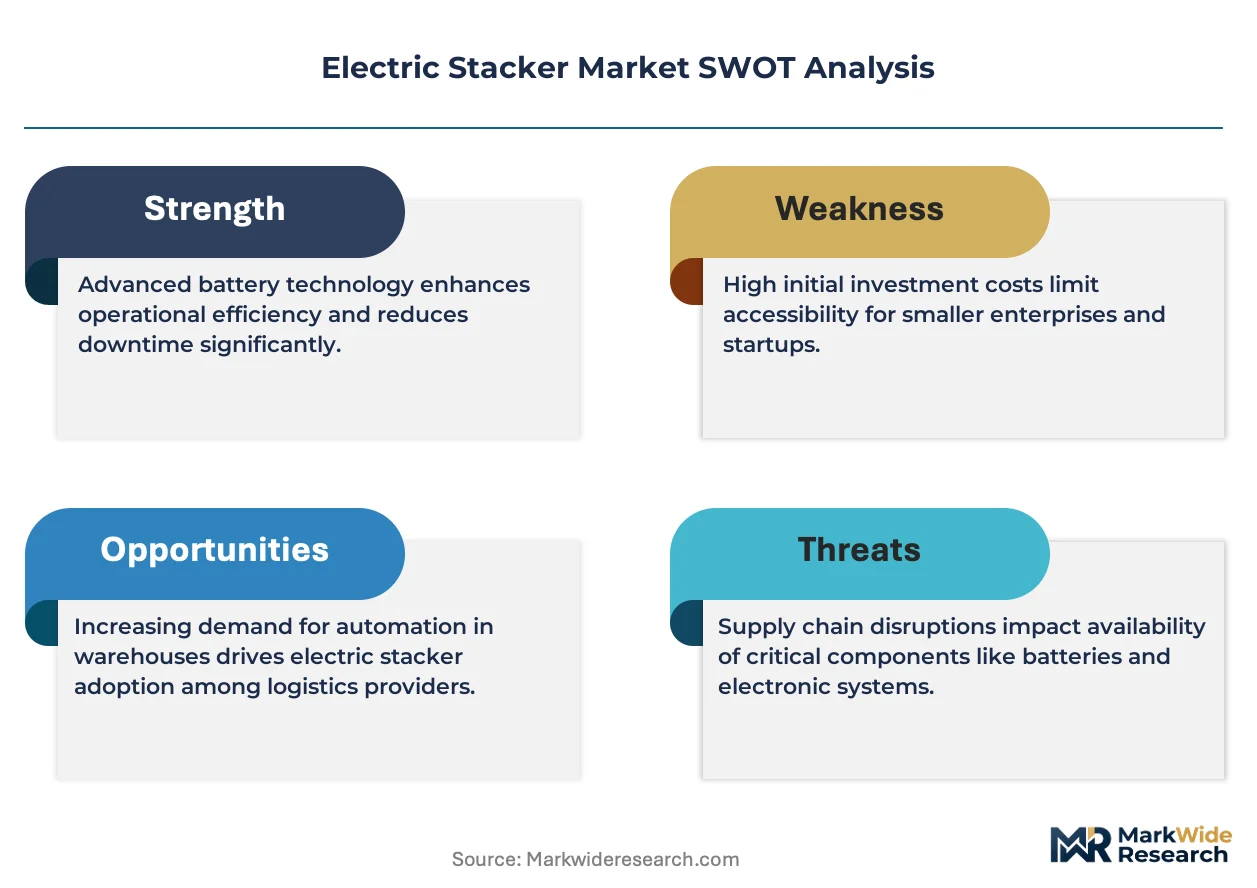
Lithium-ion battery platforms are compressing total cost of ownership curves and forcing fleet operators to accelerate replacement cycles ahead of scheduled lead-acid phase-outs. This chemistry transition is restructuring competitive advantage toward manufacturers with captive cell sourcing or long-term offtake agreements.
Growth Catalysts
- EU Green Deal carbon targets:Warehouse operators in Germany face binding emission reduction mandates that eliminate internal combustion equipment from indoor logistics environments by statutory deadlines.
- Lithium-ion energy density gains:Battery pack gravimetric improvements enable longer duty cycles and opportunity charging, reducing fleet size requirements for equivalent throughput.
- China domestic manufacturing scale:Mid-capacity straddle and reach stacker production concentrates in Jiangsu and Zhejiang provinces, driving unit cost compression through localized supply chains.
Market Restraints
- Lithium carbonate price volatility:Raw material input costs for cathode active materials fluctuate with spot market conditions, compressing margin predictability for battery pack assemblers.
- Controller semiconductor supply concentration:Power electronics fabrication for 48V motor controllers depends on Taiwanese and South Korean foundry capacity, creating single-source vulnerability.
- Lead-acid infrastructure lock-in:Existing charging infrastructure and maintenance technician training represents sunk investment that slows fleet electrification timelines.
Strategic Opportunities
- India warehousing modernization:Organized retail and e-commerce fulfillment center buildouts in Maharashtra and Karnataka create first-mover positioning for lithium-native equipment suppliers.
- Autonomous navigation convergence:Integration of LiDAR and machine vision with electric stacker platforms enables dark warehouse operations without operator labor.
- EU F-Gas Regulation phase-down:Hydrofluorocarbon restrictions on industrial refrigeration create co-location demand for zero-emission material handling in cold chain facilities.
Industry Challenges
- High-voltage technician certification:Maintenance workforce gaps in 48V and 80V system diagnostics limit service network expansion and extend equipment downtime.
- Legacy warehouse management system integration:Telematics data exchange between new electric fleet assets and existing ERP platforms requires custom middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Stacker Market |
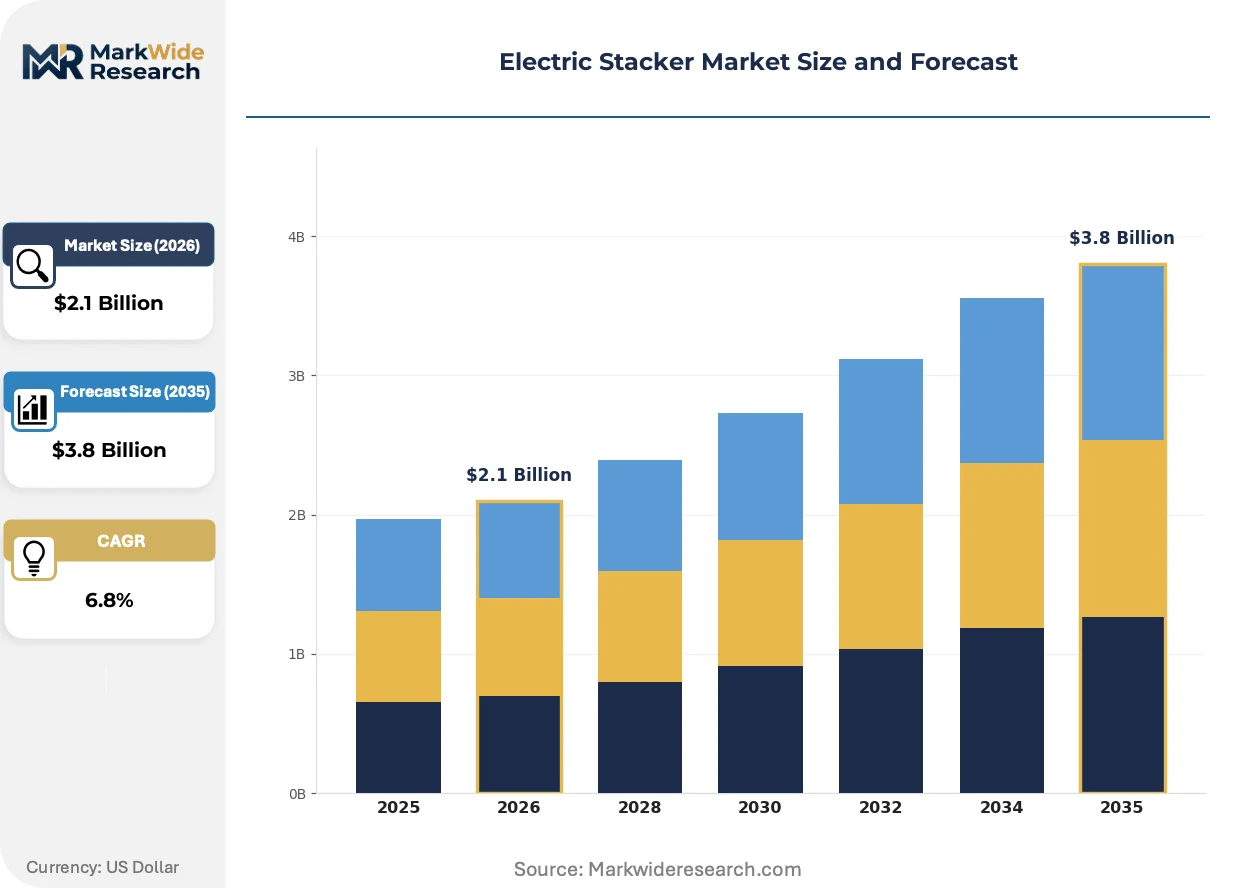
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.8 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Counterbalanced Stacker, Reach Stacker, Straddle Stacker, Pallet Stacker End User: Warehousing, Manufacturing, Retail, Logistics Capacity: 1 Ton, 2 Ton, 3 Ton, 4 Ton Power Rating: 24V, 36V, 48V, 80V |
| Companies Covered | Mitsubishi Logisnext Co., Ltd., KION Group AG, Crown Equipment Corporation, Liebherr Group, Toyota Material Handling, Jungheinrich AG, EP Equipment Co., Ltd., Hangcha Forklift, Hyster-Yale Materials Handling, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Stacker Market Shifts & Advancements
Modular battery architectures and predictive maintenance algorithms are compressing equipment lifecycle economics and enabling new service revenue models. These developments are shifting competitive differentiation from hardware specifications to data-enabled uptime guarantees.
Solid-state battery chemistries are decentralizing energy storage risk profiles by eliminating thermal runaway failure modes inherent in liquid electrolyte systems. Cold storage operators in Northern Europe are piloting these platforms for continuous-duty applications where safety certification thresholds are most stringent. The technology is decentralizing fleet standardization decisions by allowing mixed-voltage operations without segregated charging infrastructure.
The EU F-Gas Regulation mandates progressive hydrofluorocarbon phase-down through 2030, eliminating refrigerant-dependent equipment from indoor logistics environments. Cold chain operators must retrofit or replace internal combustion backup systems with electric alternatives to maintain facility certification. Reach stacker configurations with heated operator cabins face accelerated replacement demand in Benelux and Scandinavian distribution hubs.
Equipment-as-a-service contracting is fragmenting traditional capital expenditure procurement patterns among mid-size third-party logistics providers. Fixed monthly payments bundled with maintenance and energy management displace outright purchase decisions in German and French warehousing sectors. This shift concentrates vendor selection criteria on total cost predictability rather than acquisition price, favoring manufacturers with integrated telematics and remote diagnostic capabilities.
Electric Stacker Market Segmentation
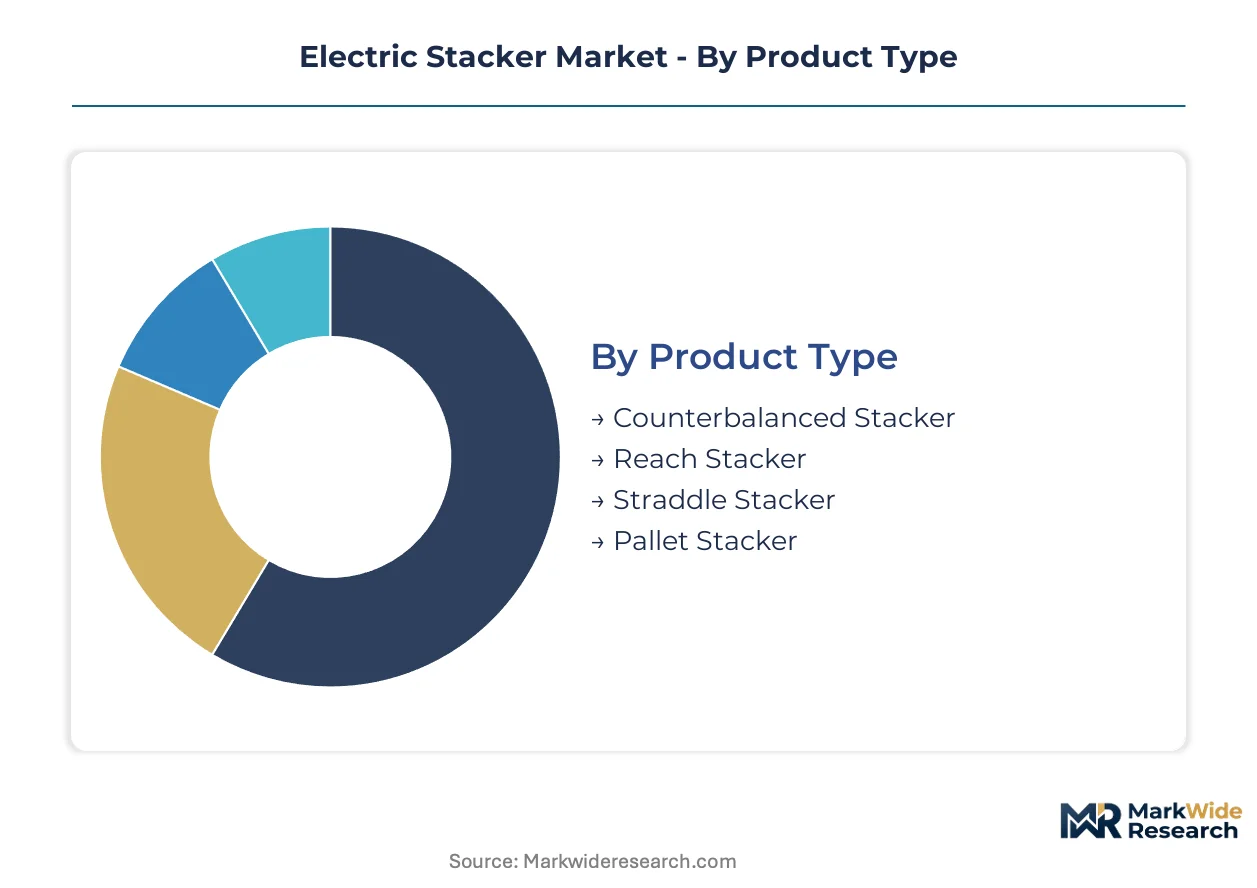
Electric stacker procurement decisions hinge on facility constraints, duty cycles, and infrastructure compatibility. Segment-level specification mismatches drive downtime costs and stranded asset risk in fleet operations.
Product Type:
Electrification architectures diverge sharply across mast configurations and stability mechanisms.
- Reach Stacker:Telescoping mast assemblies extend load handling beyond wheelbase footprint, enabling single-deep and double-deep racking penetration. Narrow-aisle warehousing in Germany and the Netherlands concentrates procurement here, driven by cubic meter optimization mandates under EU Green Deal carbon budgets.
- Counterbalanced Stacker:Rear-mounted battery packs provide ballast stability without outrigger arms, preserving maneuverability in mixed-traffic aisles. General warehousing across France and Italy favors this configuration for operator retraining efficiency and lower capital commitment per unit.
- Straddle Stacker:Outrigger legs straddle pallet loads for enhanced stability in high-lift applications. Cold storage facilities in Belgium deploy this variant for frozen goods stacking where floor loading limits exclude heavier counterbalanced units.
- Pallet Stacker:Compact pedestrian-operated units handle ground-level pallet transport and low-height stacking. Small-format retail distribution centers in Spain specify these for back-of-store operations with limited dock door access.
Mature deployment sits with Counterbalanced Stacker. Newer deployment is concentrated in Reach Stacker.
End User:
Facility throughput intensity and shift patterns reshape voltage and capacity specifications.
- Warehousing:Multi-shift fulfillment centers with 24-hour operations demand lithium-native platforms with opportunity charging capability. E-commerce hubs in Maharashtra and Karnataka are expanding fastest here.
- Manufacturing:Just-in-time production lines require synchronized material delivery with minimal buffer inventory. Automotive suppliers in Stuttgart and Wolfsburg prioritize reach configurations for line-side feeding.
- Retail:Seasonal volume spikes and constrained backroom footprints favor compact pallet stackers with rapid battery swap systems. Hypermarket chains in Poland and Czech Republic dominate procurement.
- Logistics:Third-party providers with multi-client contracts need fleet flexibility across divergent customer specifications. Port-centric 3PLs in Rotterdam and Hamburg anchor demand for 3-ton and 4-ton capacity ranges.
Procurement volume concentrates in Warehousing. Margin expansion is strongest in Logistics.
Capacity:
Load rating determines mast cylinder sizing, frame reinforcement, and battery pack mass allocation.
- 2 Ton:Mid-weight specification balances palletized goods density with maneuverability in standard 2.8-meter aisles. European third-party logistics providers standardize fleets around this rating for cross-client deployment flexibility.
- 1 Ton:Lightweight platforms serve retail backrooms and light manufacturing where single-pallet handling dominates. Urban logistics operators in Mumbai and Bangalore specify these for constrained freight elevator access.
- 3 Ton:Heavy-duty applications include beverage distribution and building materials handling. Brewery logistics in Bavaria and Baden-Württemberg drive replacement demand as lead-acid fleets phase out.
- 4 Ton:Maximum capacity rating requires reinforced masts and extended wheelbases for industrial goods stability. Steel and automotive component logistics in the Ruhr region represent concentrated end-use.
2 Ton captures the steepest expansion trajectory as fleet standardization reduces spare parts complexity.
Power Rating:
Voltage selection constrains motor controller architecture, charging infrastructure, and technician certification requirements.
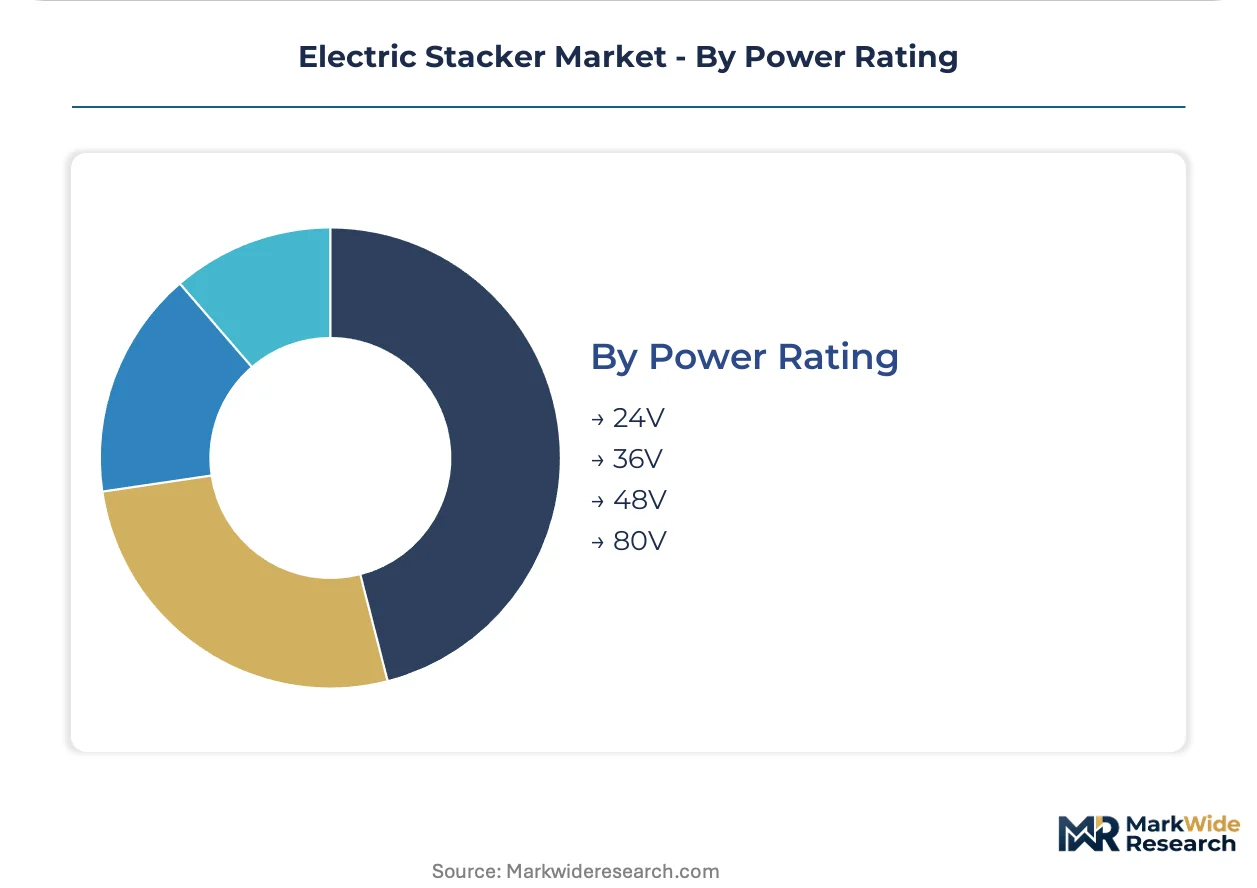
- 48V:Dominant mid-voltage platform balances power density with safety classification thresholds. KION Group and Jungheinrich anchor European production around this specification for general warehousing substitution of lead-acid fleets.
- 24V:Entry-level pedestrian stackers and compact pallet trucks utilize this rating for indoor safety compliance. Retail and light commercial applications in Southern Europe standardize here.
- 36V:Transitional rating serving mid-capacity rider stackers with moderate duty cycle demands. Legacy fleet replacements in Eastern European markets concentrate procurement.
- 80V:High-voltage architecture enables continuous heavy-duty operation with reduced charging intervals. Cold storage and multi-shift manufacturing in Northern Europe pilot this specification for lithium-ion native platforms.
48V commands current installed base. 80V is climbing the fastest as high-throughput facilities eliminate lead-acid infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Lithium carbonate mining in South America and hard-rock spodumene extraction in Western Australia anchor the upstream battery material geography for electric stacker electrification. Cell production clusters in Jiangsu province and cathode active material refining in Germany's industrial heartland shape downstream cost structures. Fleet procurement decisions concentrate where warehouse carbon regulations intersect with dense logistics infrastructure.
Germany
Bavarian automotive suppliers and Ruhr region steel logistics drive heavy-capacity stacker demand for multi-shift operations. The EU Green Deal mandates binding emission reductions that phase out internal combustion equipment from indoor environments by statutory deadlines. Stuttgart and Wolfsburg automotive clusters prioritize reach stacker configurations for line-side feeding efficiency.
China
E-commerce fulfillment center buildouts in Jiangsu and Zhejiang provinces concentrate mid-capacity straddle and reach stacker procurement. National dual carbon goals under MEE supervision accelerate fleet electrification timelines for domestic logistics operators. Yangtze River Delta manufacturing hubs capture production scale advantages through localized lithium-ion supply chains.
United States
OSHA mandates operator training certification and equipment inspection protocols that favor models with integrated safety interlocks. Midwest distribution corridors spanning Illinois and Ohio anchor demand for counterbalanced stackers in general warehousing applications. California's warehouse emissions regulations under CARB jurisdiction drive lithium-native fleet replacements in Los Angeles and Inland Empire logistics hubs.
India
Organized retail and e-commerce fulfillment center development in Maharashtra and Karnataka creates first-mover positioning for lithium-native equipment suppliers. The PLI scheme for advanced chemistry cell manufacturing reduces import dependency for battery pack assemblers. Mumbai and Bangalore urban logistics operators specify lightweight 1-ton units for constrained freight elevator access.
Netherlands
Rotterdam port-centric third-party logistics providers anchor European demand for 3-ton and 4-ton capacity ranges in multi-client contract environments. The EU F-Gas Regulation eliminates hydrofluorocarbon-dependent equipment from cold chain facilities co-located with material handling operations. Benelux distribution hubs face accelerated replacement demand for reach stackers with heated operator cabins.
Electric Stacker Market Competitive Landscape
Backward integration into battery cell sourcing dominates the current landscape as manufacturers secure margin predictability against lithium carbonate volatility. The vendor base separates into three tiers: integrated industrial conglomerates with captive powertrain production, specialized material handling firms with regional assembly footprints, and emerging Asian fabricators competing on unit cost. Strategic archetypes include chemistry-agnostic platform builders, narrow-aisle specialization houses, and scale-driven volume producers. M&A activity and long-term offtake agreements constitute the dominant competitive moves as firms lock in cathode active material supply.
Among German-based industrial groups, KION Group AG and Jungheinrich AG exemplify the integrated archetype with in-house controller development and narrow-aisle specialization respectively. Japanese industrial conglomerates represented by Toyota Material Handling occupy positions anchored through captive AC induction motor production across Asian and North American assembly plants. These three entities represent divergent strategic vectors: vertical integration depth, application-specific engineering focus, and geographic production diversification.
| Leading Market Players |
|---|
| Mitsubishi Logisnext Co., Ltd. |
| KION Group AG |
| Crown Equipment Corporation |
| Liebherr Group |
| Toyota Material Handling |
| Jungheinrich AG |
| EP Equipment Co., Ltd. |
| Hangcha Forklift |
| Hyster-Yale Materials Handling |
| Others |
Supply & Pricing Matrix
Lithium-ion battery platform transitions simultaneously compress manufacturing cost curves and concentrate procurement leverage among manufacturers with captive cell sourcing or long-term offtake agreements. This chemistry shift restructures both component economics and supplier power dynamics across electric stacker production networks.
Pricing Analysis
Warranty and service bundling separates premium-tier manufacturers from value-oriented competitors, with integrated uptime guarantees commanding substantial premiums over unbundled equipment-only transactions. Pricing stratifies across premium, standard, and economy tiers based on battery chemistry certification grade and after-sales service coverage depth. Cost compression in the standard tier is intensifying because Chinese domestic manufacturers are scaling mid-capacity production in Jiangsu and Zhejiang provinces. Third-party logistics providers with multi-client contracts exhibit highest price sensitivity due to fleet standardization mandates, while cold chain operators in Northern Europe show lowest sensitivity given safety certification requirements.
Supply Chain Analysis
Lithium carbonate feedstock rests on South American mining operations and Western Australian hard-rock spodumene extraction, with downstream cell production concentrating in China's Jiangsu province and cathode active material refining in Germany's industrial heartland. Power electronics fabrication for 48V motor controllers draws from Taiwanese and South Korean foundry capacity. Single-source vulnerability in semiconductor controller supply creates structural risk exposure for European and North American assembly plants. Distribution runs through OEM-direct channels for large fleet operators and specialized material handling distributors for mid-size warehousing end users.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The electric stacker market sits in a lithium-ion chemistry transition phase, with solid-state battery platforms beginning to displace liquid electrolyte systems in safety-critical cold storage applications.
For Market Incumbents: Acquire cathode active material refining capacity or secure long-term lithium carbonate offtake agreements to defend margin predictability against raw material spot market volatility. Deepen backward integration into battery pack assembly to reduce dependency on Taiwanese foundry capacity for 48V motor controllers. Prioritize certification investment for 80V high-voltage platforms as multi-shift manufacturing facilities eliminate lead-acid infrastructure. For New Entrants and Emerging Players: Direct-to-fleet digital sales channels bypass established distributor networks and enable rapid penetration of mid-size third-party logistics providers in India's Maharashtra and Karnataka warehousing corridors. Target the 1-ton lightweight segment for urban logistics operators in Mumbai and Bangalore with constrained freight elevator access. Lead with lithium-native equipment positioning to avoid legacy lead-acid infrastructure lock-in. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to integrated industrial conglomerates seeking captive powertrain production capabilities. Five-to-ten year viability hinges on battery chemistry platform standardization decisions across major fleet operators. Watch for lithium carbonate price stabilization signals as inflection indicators for margin predictability recovery in battery pack assembly.| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Supply Agreement | Secures lithium carbonate feedstock from South American mining operations against spot volatility. |
| Backward Integration | Captures margin in cathode active material refining within Germany's industrial heartland. |
| Capacity Expansion | Scales 80V high-voltage platform production for Northern European multi-shift manufacturing demand. |
| Joint Venture | Combines Taiwanese semiconductor controller expertise with European assembly plant proximity. |
| Green Certification Program | Aligns fleet offerings with EU Green Deal binding emission reduction mandates for German warehouse operators. |
Research Methodology
Independent corroboration across fleet procurement managers at third-party logistics providers, maintenance directors at automotive manufacturing plants, and aftermarket service heads at material handling distributors underwrites the qualitative findings. Secondary validation draws from customs and trade data, SEC filings of listed industrial conglomerates, and EU regulatory filings under F-Gas Regulation and EU Green Deal frameworks. Bottom-up unit shipment estimates triangulate against top-down market value reconstructions across product type, capacity rating, and power voltage segmentation.
Historical reference periods anchor the projection horizon through verified fleet replacement cycle data and documented lithium-ion chemistry adoption curves in European material handling markets. The analytical framework models demand across reach stacker, counterbalanced stacker, straddle stacker, and pallet stacker configurations; 1-ton through 4-ton capacity tiers; and 24V through 80V power architectures. CAGRs derive from regression analysis of battery cost decline trajectories and carbon regulation enforcement timelines. Forecast inputs include lithium carbonate spot price indices and EU member state warehouse emission audit frequencies.
Inputs from fleet operator procurement databases and OEM production disclosures were available through the study window; gaps in solid-state battery pilot program performance data introduce uncertainty bands around technology adoption timelines. Forecasts reflect documented assumptions regarding EU Green Deal enforcement consistency and lithium-ion cell manufacturing scale-up in Jiangsu province. A small set of triggers—lithium carbonate price volatility spikes, Taiwanese foundry capacity constraints, and 80V technician certification pipeline expansion—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Chain-Driven Roller Conveyors Market
Material Handling Equipment
Elevator Component Market
Material Handling Equipment
Middle East Conveyor Belts Market
Material Handling Equipment
United States Conveyor Belt Market
Material Handling Equipment
Pneumatic Equipment Market
Material Handling Equipment
Water Hose Market
Material Handling Equipment
Steel Coil Handling Equipment Market
Material Handling Equipment
Autonomous Warehouse Equipment Market
Material Handling Equipment
Conveying Equipment Market
Material Handling Equipment
Middle East and Africa Automated Material Handling Market
Material Handling Equipment
Europe Conveyors Market
Material Handling Equipment
Industrial Elevator Market
Material Handling Equipment
Global Large Conveyor Chain Market
Material Handling Equipment
Jaw Crushers Market
Material Handling Equipment
Global Loading Dock Lifts Market
Material Handling Equipment
Fork Lift Attachments Market