
 South America Specialty Fertilizer Market | 2026-2036
South America Specialty Fertilizer Market Size, Share, and Industry Trends Forecast 2026-2036
South America Specialty Fertilizer Market Analytics
Soil testing and prescription blending services is reconfiguring margin pools away from commodity nitrogen traders toward agronomic advisory platforms. Yara International ASA leverages its coastal Brazilian terminals to dominate water-soluble urea distribution. SQM S.A. anchors the potassium nitrate segment through Caliche ore processing in northern Chile. Nutrien Ltd. competes via its proprietary micronutrient coating technology tailored to acidic tropical soils.
South America specialty fertilizers are formulated products engineered for controlled nutrient release, typically incorporating polymer-coated granules, chelated micronutrients, or stabilized nitrogen compounds with specified release curves measured in weeks or growing-degree days; their primary purpose is to match nutrient availability with crop phenological stages while minimizing leaching losses in high-rainfall tropical zones. Macronutrient-coated formulations occupy the dominant revenue position given their compatibility with mechanized broadacre farming, while micronutrient blends represent the fastest-expanding margin pool as Brazilian citrus and coffee producers address documented zinc and boron deficiencies. Biofertilizer adoption remains structurally constrained by shelf-life logistics and the limited refrigerated distribution infrastructure reaching Mato Grosso and Paraná farm gates.
ANVISA regulates maximum heavy-metal content in imported fertilizers under Brazil's national fertilizer policy, while Argentina's Senasa enforces phytosanitary certification for biological inoculant products crossing Mercosur borders. REACH-equivalent chemical registration requirements in Chile and Peru are lengthening product approval timelines for European suppliers. Stakeholders must monitor how Brazil's forthcoming carbon market mechanisms credit reduced-emission fertilizer practices against conventional urea benchmarks.
Market Dynamics
Precision agriculture platforms are displacing blanket fertilizer application across Brazil's Cerrado corridor, forcing reformulation of product portfolios toward fertigation-compatible controlled-release compounds and remote-sensing-calibrated dosing systems.
Growth Catalysts
- ANVISA contaminant thresholds:Tightened heavy-metal limits on imported inputs are accelerating domestic blending capacity expansion and premium formulation demand among compliance-focused growers.
- Fertigation infrastructure:Center-pivot and drip irrigation adoption in Mato Grosso soybean operations is pulling water-soluble potassium nitrate and stabilized nitrogen into standard input bundles.
- Zinc and boron deficiency mapping:Documented micronutrient gaps in Brazilian citrus and coffee soils are driving prescription micronutrient blend penetration faster than macronutrient growth rates.
Market Restraints
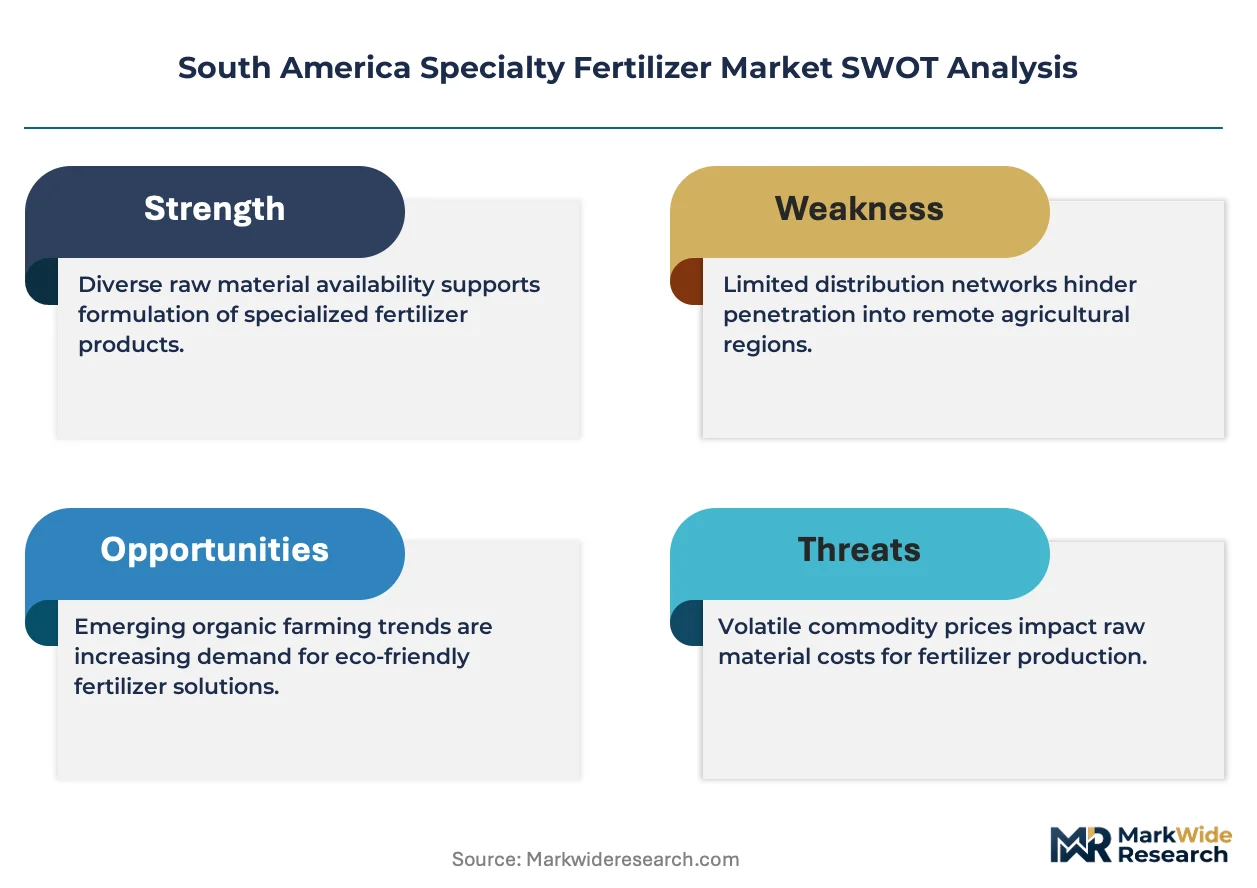
- Caliche ore concentration:Potassium nitrate supply depends on northern Chile extraction, creating single-source vulnerability for water-soluble formulations across the continent.
- Refrigerated distribution gaps:Biofertilizer shelf-life requirements exceed cold-chain reach to Paraná and Mato Grosso farm gates, structurally capping biological product addressable market.
- REACH-equivalent registration:Chile and Peru chemical approval timelines extend 18-24 months for European suppliers, delaying product launch windows versus domestic competitors.
Strategic Opportunities
- Carbon market mechanisms:Brazil's forthcoming emissions trading system will credit reduced-nitrogen-oxide practices, positioning stabilized and slow-release formulations for preferential farmer economics.
- Soil testing service integration:Prescription blending tied to agronomic advisory platforms captures margin pools previously held by commodity nitrogen traders in São Paulo state.
- Biological inoculant cross-border flows:Argentina's Senasa phytosanitary certification requirements create first-mover advantage for Mercosur-registered biological suppliers versus extra-regional entrants.
Industry Challenges
- Agronomic advisory talent scarcity:Precision agriculture platform deployment outpaces trained prescription agronomist supply in Brazil's interior states, constraining advisory-led sales conversion.
- Polymer coating capex intensity:Controlled-release granule manufacturing requires sulfur and polymer infrastructure investments that mid-scale blenders cannot finance without strategic partnerships.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Specialty Fertilizer Market |
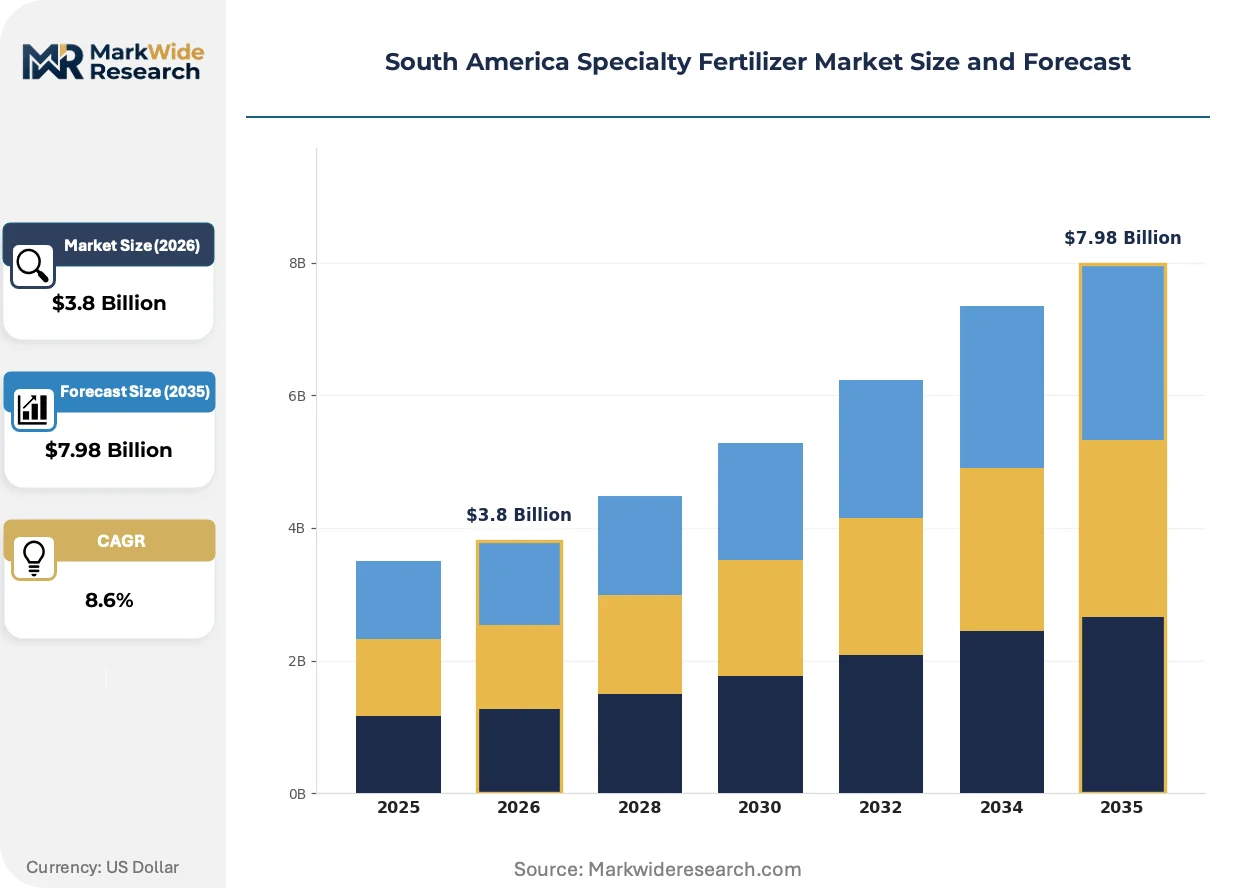
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.98 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Macronutrients, Micronutrients, Biofertilizers, Organic Fertilizers Application: Crop Production, Horticulture, Lawn & Garden, Turf Management End User: Agricultural Producers, Greenhouses, Nurseries, Retailers Distribution Channel: Direct Sales, E-commerce, Wholesale, Farm Supply Stores |
| Companies Covered | Yara International ASA, SQM S.A., The Mosaic Company, Nutrien Ltd., ICL Group Ltd., K+S Aktiengesellschaft, EuroChem Group, Haifa Group, Sociedad Química y Minera S.A., Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Specialty Fertilizer Market Evolving Landscape
Remote sensing and variable-rate application hardware are collapsing the information lag between soil condition detection and nutrient intervention, compressing traditional seasonal ordering cycles into continuous calibration workflows.
Polymer-coated urea and sulfur-encapsulated formulations are virtualizing the nutrient release curve, replacing calendar-based application schedules with growing-degree-day responsive availability. Soybean and corn operators in Goiás and Mato Grosso are adopting these products at twice the rate of conventional growers. The technology is virtualizing inventory planning for distributors, shifting from bulk seasonal procurement to just-in-time granule-specific logistics.
ANVISA's progressive tightening of cadmium and lead maximum thresholds in imported fertilizers is forcing reformulation of phosphate and micronutrient sources toward domestically processed or certified-low-contaminant origins. Blenders serving Brazil's export-oriented fruit and coffee sectors are absorbing compliance costs into premium positioning rather than passing through to price-sensitive grain operators. The regulatory pressure is most acute in São Paulo's citrus belt, where European supermarket chain audit requirements compound national standards.
Buyers are consolidating procurement decisions through integrated farm management software platforms that embed fertilizer recommendations directly into planting and irrigation execution workflows. Traditional distributor agronomist relationships are ceding influence to API-connected input marketplaces in Brazil's southern states. This channel compression is most visible among mid-scale operators in Paraná, where cooperatives are centralizing input purchasing through shared digital procurement systems.
South America Specialty Fertilizer Market Segmentation
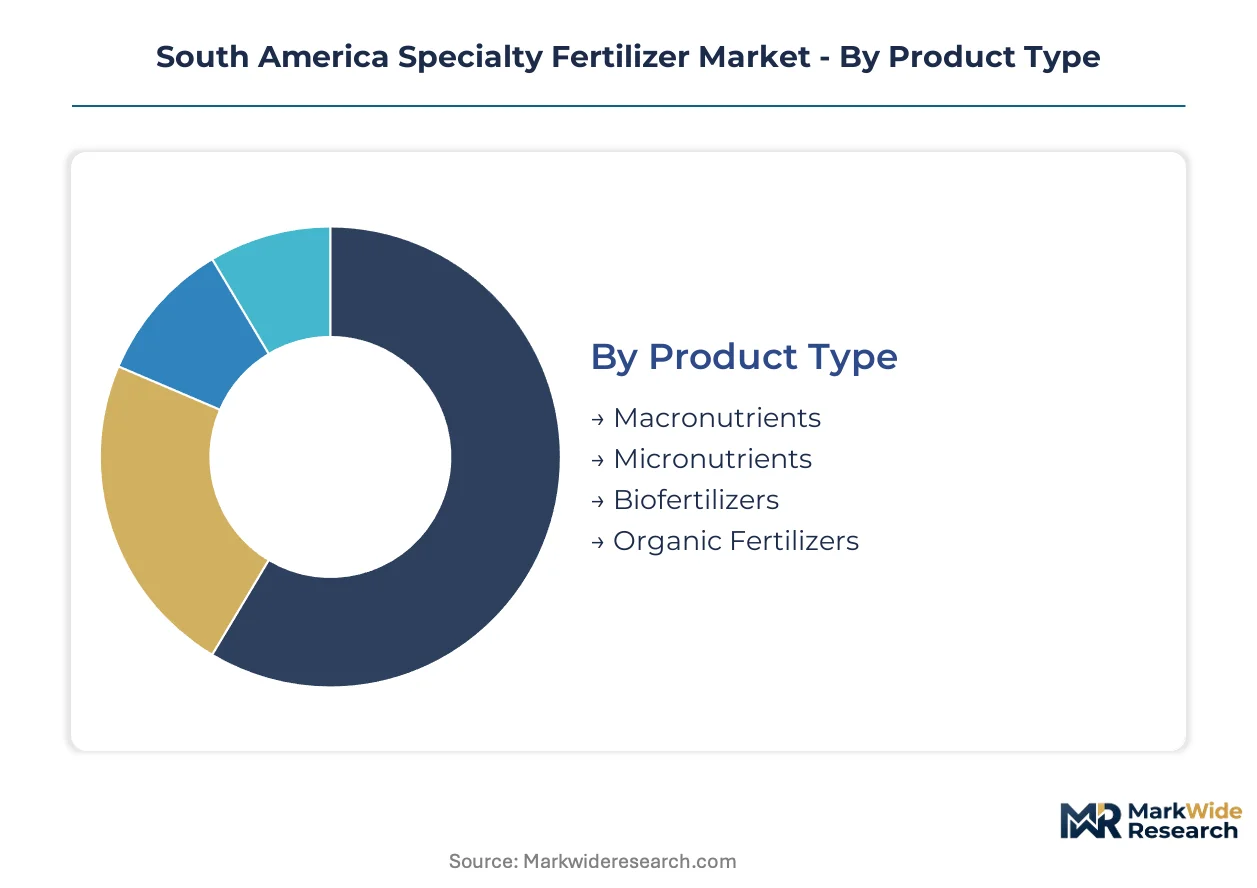
Specialty fertilizer segmentation in South America reflects divergent agronomic requirements across Brazil's Cerrado grain belt, Chilean fruit valleys, and Argentine soybean provinces. Product formulation, application method, and channel structure each configure distinct margin pools and competitive dynamics.
Product Type:
Formulation chemistry spans synthetic precision compounds to biological alternatives, with cost tiers separating commodity-compatible from premium-positioned inputs.
- Macronutrients:Polymer-coated urea and sulfur-encapsulated nitrogen formulations enable growing-degree-day responsive release curves. Brazilian soybean operators in Mato Grosso and Goiás deploy these products at twice the adoption rate of conventional growers, driven by fertigation infrastructure expansion and ANVISA compliance requirements for reduced heavy-metal content.
- Micronutrients:Chelated zinc, boron, and manganese blends address documented deficiency mapping in São Paulo citrus belts and Minas Gerais coffee zones. Prescription blending tied to soil testing services is capturing margin pools previously held by commodity nitrogen distributors, with citrus export sectors absorbing premium pricing for certified-low-contaminant formulations.
- Biofertilizers:Microbial inoculant products face structural shelf-life constraints from refrigerated distribution gaps reaching Paraná and Mato Grosso farm gates.
- Organic Fertilizers:Composted and processed organic matter formulations serve certified organic fruit and vegetable operations in Chile's Central Valley and Brazil's southern states.
The dominant share belongs to macronutrients, while micronutrients is closing the gap fastest.
Application:
Crop-specific nutrient delivery methods range from precision fertigation to broadcast soil amendment, with volume concentration in broadacre mechanized operations.
- Crop Production:Soybean and corn operations across Brazil's Cerrado corridor drive bulk demand for controlled-release nitrogen and potassium nitrate applied through center-pivot systems. Remote sensing integration is collapsing traditional seasonal ordering into continuous calibration workflows calibrated to crop phenological stages.
- Horticulture:High-value fruit and vegetable producers in Chile's Atacama and Coquimbo regions require water-soluble formulations with specified electrical conductivity and pH stability for drip irrigation systems.
- Lawn & Garden:Consumer-facing specialty blends serve urban landscaping demand in São Paulo, Buenos Aires, and Santiago metropolitan markets.
- Turf Management:Sports field and golf course maintenance in Brazil's southeastern states consumes stabilized nitrogen products with extended release curves measured in weeks.
Crop production commands the volume lead, though horticulture generates the steepest per-hectare margin premiums.
End User:
Customer scale and technical sophistication determine service intensity, with advisory integration deepest among export-oriented operations.
- Agricultural Producers:Large-scale grain and oilseed operators in Mato Grosso, Goiás, and Buenos Aires provinces consolidate procurement through integrated farm management software platforms. API-connected input marketplaces are displacing traditional distributor agronomist relationships among cooperative-affiliated growers in Paraná.
- Greenhouses:Controlled-environment vegetable and flower operations in Colombia's Bogotá savanna and Brazil's Campinas region require precision nutrient solutions with guaranteed analysis and batch traceability.
- Nurseries:Ornamental plant propagation facilities demand specialized rooting and establishment formulations with low salt indices.
- Retailers:Farm supply cooperatives and independent dealers in southern Brazil and Argentina's Pampas region intermediate between manufacturers and smaller-scale producers.
Agricultural producers anchor absolute demand, while greenhouse operations are expanding most quickly on a percentage basis.
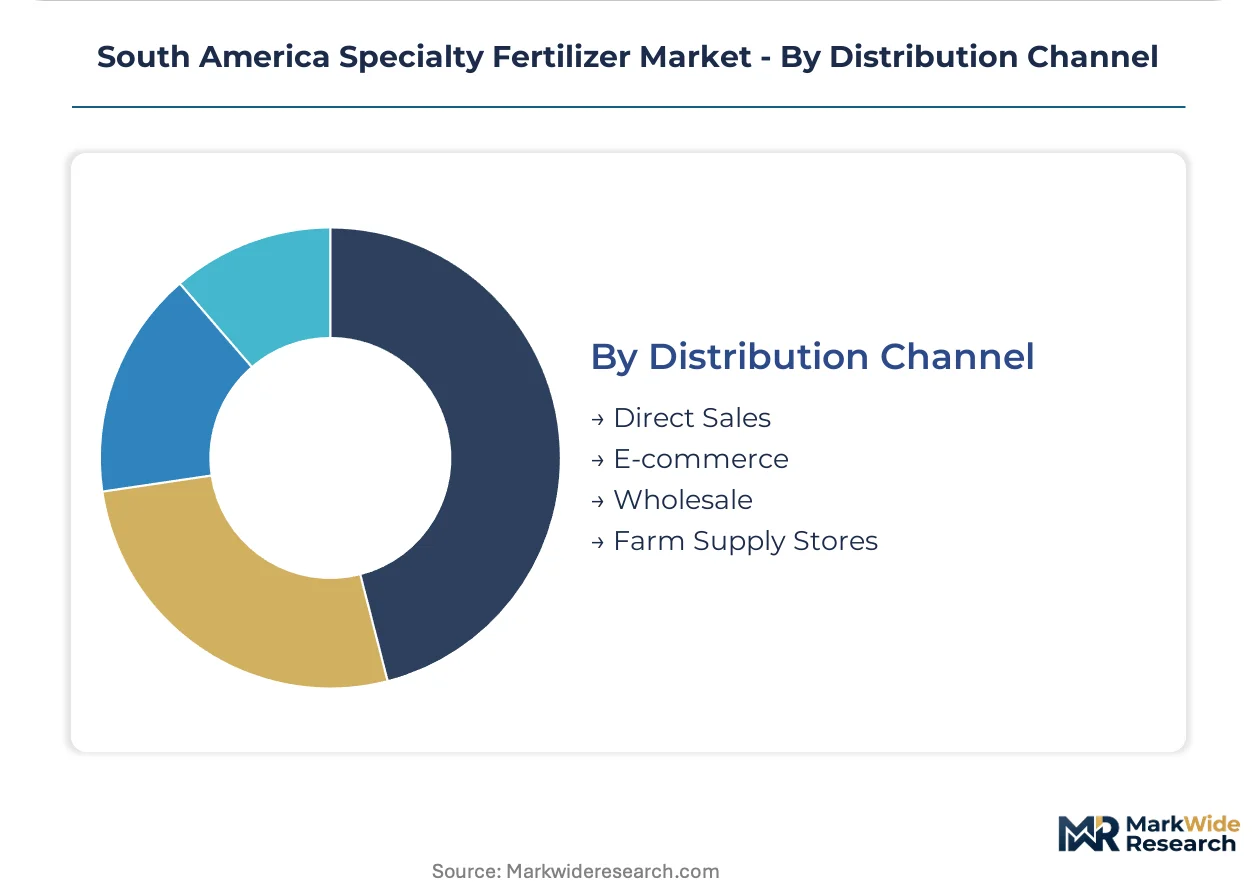
Distribution Channel:
Channel structure reflects customer scale, technical service requirements, and logistics infrastructure density across South American agricultural regions.
- Direct Sales:Manufacturer agronomists engage large-scale operators with prescription blending and soil testing integration, particularly in São Paulo state where advisory-led sales conversion captures margin pools from commodity traders.
- E-commerce:Digital procurement platforms are centralizing input purchasing among mid-scale cooperative members in Paraná, embedding fertilizer recommendations directly into planting and irrigation execution workflows.
- Wholesale:Regional distributors serve secondary markets with bulk formulation and blending services, constrained by polymer coating capex requirements that limit mid-scale blender participation.
- Farm Supply Stores:Local retail points provide last-mile access for smaller operators and emergency replenishment, though their influence is compressing as digital channels penetrate southern states.
Direct sales holds the revenue concentration, yet e-commerce is gaining share fastest among younger, digitally equipped producer cohorts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Caliche ore extraction in northern Chile concentrates water-soluble potassium nitrate supply for the continent, while Brazilian blending capacity expands to meet ANVISA contaminant compliance. Distribution networks radiate from coastal terminals to interior farm gates across Mercosur trade corridors.
Brazil
Soybean and corn operators in Mato Grosso and Goiás deploy polymer-coated urea at twice conventional adoption rates through expanding center-pivot infrastructure. ANVISA progressive tightening of cadmium and lead thresholds forces phosphate source reformulation toward certified-low-contaminant origins. São Paulo's citrus belt absorbs premium pricing for compliance-heavy micronutrient blends serving export-oriented fruit sectors.
Argentina
Pampas grain producers consolidate procurement through cooperative digital platforms displacing traditional distributor relationships. Senasa phytosanitary certification requirements for biological inoculants crossing Mercosur borders create registration advantages for regional suppliers. Buenos Aires province anchors soybean input demand with precision agriculture platform penetration accelerating in Santa Fe and Córdoba corridors.
Chile
Caliche ore processing in the Atacama Desert anchors continental potassium nitrate supply for water-soluble formulations. REACH-equivalent chemical registration timelines extend product approval windows for European suppliers versus domestic competitors. Fruit valleys in Atacama and Coquimbo regions demand precision nutrient solutions with specified electrical conductivity for drip irrigation systems.
Colombia
Controlled-environment vegetable and flower operations in the Bogotá savanna require guaranteed analysis and batch traceability for greenhouse nutrient solutions. Coffee producers in the Zona Cafetera address documented micronutrient deficiencies through prescription zinc and boron applications. National agricultural agencies enforce import certification standards that lengthen approval timelines for non-Andean suppliers.
Peru
High-altitude potato and quinoa operations in the Sierra region drive demand for stabilized nitrogen formulations resistant to leaching in irregular rainfall patterns. Coastal asparagus and avocado export sectors absorb premium pricing for certified-low-contaminant micronutrient blends meeting European supermarket audit requirements. REACH-equivalent registration protocols extend chemical product approval timelines to 18-24 months.
South America Specialty Fertilizer Market Competitive Landscape
Integrated nutrient majors and regional mining-chemical specialists split the market along formulation complexity and raw material access vectors. Coastal terminal control and caliche ore reserves concentrate margin capture among vertically positioned players, while mid-scale blenders face polymer coating capex barriers. Norwegian and Chilean corporate groups anchor water-soluble and potassium nitrate supply chains respectively. Dominant competitive moves include coastal logistics infrastructure expansion and proprietary micronutrient coating technology licensing.
Among the integrated majors, Yara International ASA and Nutrien Ltd. exemplify terminal-advantaged distribution models, with the former leveraging coastal Brazilian infrastructure and the latter deploying acidic tropical soil coating technologies. SQM S.A. occupies a distinct position as the caliche-anchored potassium nitrate specialist. These three corporate groups represent the strategic archetypes dividing competitive terrain: coastal logistics integrators, technology-differentiated formulators, and mineral-reserve-based specialty chemical suppliers.
| Leading Market Players |
|---|
| Yara International ASA |
| SQM S.A. |
| The Mosaic Company |
| Nutrien Ltd. |
| ICL Group Ltd. |
| K+S Aktiengesellschaft |
| EuroChem Group |
| Haifa Group |
| Sociedad Química y Minera S.A. |
| Others |
Value Network & Pricing Analysis
Undercapacity in Brazilian domestic blending facilities is tightening supplier bargaining power and compressing margin capture for mid-scale distributors dependent on imported phosphate rock. This utilization squeeze propagates through the value chain as ANVISA compliance costs concentrate among formulators with certified-low-contaminant sourcing capabilities.
Pricing Analysis
Agronomic advisory service bundling drives lifetime value capture beyond commodity product margins. Three-tier pricing structure across premium compliance-grade, standard certified, and economy bulk formulations separates export-oriented fruit producers from price-sensitive grain operators. Cost compression in economy nitrogen tiers is intensifying because European suppliers face extended REACH-equivalent registration timelines in Chile and Peru. Citrus and coffee growers in São Paulo state demonstrate lowest price sensitivity due to European supermarket audit requirements, while Mato Grosso soybean operators negotiate aggressively on volume.
Supply Chain Analysis
Caliche ore extraction in northern Chile, phosphate rock mining in Peru, and coastal terminal processing in Brazil anchor raw material flows for water-soluble formulations. Potassium nitrate supply rests on Atacama Desert operations, urea sourcing draws from regional petrochemical complexes, and polymer coating feedstocks import from Asian chemical manufacturers. Single-source vulnerability for potassium nitrate concentrates risk exposure to Atacama logistics disruptions. Distribution runs through coastal terminals controlled by integrated majors, with last-mile delivery to interior farm gates via cooperative networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward large-scale agricultural producers consolidating procurement through integrated farm management platforms, fragmenting traditional distributor influence across Brazil's southern states.
For Market Incumbents: Harden coastal terminal control against API-connected marketplace encroachment by embedding proprietary soil testing services into direct sales relationships. Expand backward integration into certified-low-contaminant phosphate processing to capture ANVISA compliance premiums. Prioritize polymer coating capacity additions in São Paulo state to defend margin position against mid-scale blender partnerships. For New Entrants and Emerging Players: Paraná's refrigerated distribution gaps for biofertilizers represent the most penetrable white-space opportunity. Target greenhouse operations in Colombia's Bogotá savanna with guaranteed-analysis nutrient solutions requiring lower cold-chain infrastructure investment. Deploy prescription agronomist talent scarcity in Brazil's interior as the go-to-market angle, offering soil testing integration that incumbent distributors cannot staff. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across controlled-release manufacturing as sulfur and polymer infrastructure requirements exclude mid-scale competitors. Five-to-ten-year viability favors vertically integrated players with captive caliche ore or coastal terminal access. Acquire domestic blending assets with ANVISA certification pathways rather than greenfield capacity. Monitor Brazil's carbon market mechanism implementation as the signal for preferential economics shifting toward stabilized nitrogen formulations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Certified-Low-Contaminant Phosphate | ANVISA threshold tightening in Brazil rewards domestic processing investments with compliance premium capture. |
| Prescription Agronomist Talent Acquisition | São Paulo citrus belt demand for advisory-led sales conversion outpaces trained specialist supply. |
| Coastal Terminal Capacity Expansion | Water-soluble urea distribution control in Brazilian ports anchors margin capture against marketplace disintermediation. |
| Polymer Coating Infrastructure Partnership | Mid-scale blender participation constraints create licensing opportunities for technology-differentiated formulators. |
| Carbon Market Mechanism Positioning | Brazil's emissions trading system will credit stabilized nitrogen practices against conventional urea benchmarks. |
Research Methodology
A spread of perspectives from fertilizer formulators, agronomic advisory platform operators, cooperative procurement managers, and ANVISA regulatory affairs specialists converged on the working assumptions driving this analysis. Primary interviews with coastal terminal logistics directors and micronutrient coating R&D heads combined with secondary validation from customs trade data, national fertilizer policy filings, and SEC disclosures from listed nutrient majors. Bottom-up volume modeling across product formulation tiers triangulated against top-down macroeconomic agricultural input demand projections.
Demand-supply balance modeling anchored forecast outputs across the analysis window, with segmentation dimensions spanning macronutrient versus micronutrient chemistry, fertigation versus broadcast application methods, and direct sales versus digital procurement channels. CAGRs derived from weighted average of historical growth patterns and forward-looking capacity expansion announcements. Key inputs included center-pivot irrigation adoption rates in Mato Grosso and documented zinc deficiency mapping in São Paulo citrus soils.
Practitioners should monitor ANVISA cadmium threshold revisions and Brazil carbon market implementation schedules for early signals requiring forecast reassessment. Cross-checking against national agricultural agency fertilizer consumption statistics is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fertilizers
Water Soluble NPK Fertilizers Market
Fertilizers
Global Controlled Release Fertilizer Market
Fertilizers
Nitrogen Fertilizer Additives Market
Fertilizers
Global Nitrogenous Fertilizer Market
Fertilizers
Vietnam Organic Fertilizer Market
Fertilizers
Sulfur Fertilizer Market
Fertilizers
United States Specialty Fertilizer Market
Fertilizers
North America Organic Fertilizers Market
Fertilizers
Biochar Fertilizer Market
Fertilizers
South Africa Fertilizer Market
Fertilizers
Ammonium Thiosulfate Fertilizer Market
Fertilizers
Fertilizer Tester Market
Fertilizers
Controlled and Slow Release Fertilizers Market
Fertilizers
Europe Organic Fertilizer Market
Fertilizers
Sulphur Coated Urea Market
Fertilizers
North America Fertilizers Market