
 Central Nervous System (CNS) Biomarkers Market | 2026-2036
Central Nervous System (CNS) Biomarkers Market Size, Share, and Industry Trends Forecast 2026-2036
Central Nervous System (CNS) Biomarkers Market Analysis
The EU Green Deal's push for sustainable diagnostics manufacturing is decoupling European procurement from conventional reagent supply chains. Thermo Fisher Scientific leverages its proteomics platform breadth to anchor high-throughput CNS biomarker workflows across contract research networks. F. Hoffmann-La Roche sustains competitive position through integrated companion diagnostic development tied to neurology therapeutic pipelines. Bio-Rad Laboratories specializes in analytical instrument precision for cerebrospinal fluid protein quantification, occupying a defensible niche in reference laboratory settings.
Central Nervous System biomarkers comprise measurable biological indicators—encompassing cerebrospinal fluid proteins, circulating nucleic acids, and neuroimaging signatures—that reflect pathophysiological processes within the brain and spinal cord. These indicators typically require validated assay sensitivity thresholds below picogram-per-milliliter concentrations to detect neurodegenerative changes prior to symptomatic onset. Proteomic biomarkers, particularly phosphorylated tau and neurofilament light chain assays, dominate current clinical utility owing to established analytical validation frameworks and regulatory qualification pathways. Imaging biomarkers, including amyloid PET and volumetric MRI protocols, represent the fastest-expanding segment as pharmaceutical sponsors integrate these endpoints into adaptive trial designs for disease-modifying therapies.
The FDA's Biomarker Qualification Program and EMA's qualification opinion pathway jointly shape the evidentiary standards required for CNS biomarker incorporation in drug approval dossiers. CLIA laboratory certification and CAP accreditation requirements further constrain which diagnostics laboratories can return patient-specific biomarker results for clinical decision-making. Stakeholders must monitor evolving FDA guidance on surrogate endpoint acceptability for accelerated approvals in neurodegeneration, as qualification precedents established in Alzheimer's disease will likely propagate to Parkinson's disease and multiple sclerosis programs.
Market Dynamics
Pharmaceutical sponsors are compressing clinical trial timelines through adaptive biomarker-guided protocols, forcing diagnostic laboratories to reconfigure assay validation workflows around real-time endpoint qualification rather than retrospective analytical validation.
Growth Catalysts
- FDA Accelerated Approval Pathways:The FDA's surrogate endpoint framework for neurodegeneration therapies creates immediate demand for qualified CNS biomarkers in Phase II-III transitions, pulling phosphorylated tau and neurofilament light chain assays into regulatory dossiers.
- NIH Neurodegeneration Research Consortia:Federally funded biomarker standardization initiatives in the United States establish analytical validation precedents that reduce commercial assay development risk for cerebrospinal fluid protein quantification platforms.
- Single-Molecule Array Technology:Simoa and Ella platforms achieve femtomolar detection thresholds for plasma-based NfL measurement, enabling blood-draw alternatives to lumbar puncture collection and expanding addressable patient populations for longitudinal monitoring.
Market Restraints
- Reference Material Scarcity:Certified reference standards for phosphorylated tau isoforms remain concentrated at two European metrology institutes, creating supply bottlenecks for assay manufacturers seeking analytical traceability.
- Reimbursement Code Fragmentation:CMS Local Coverage Determinations and MolDX program variability across Medicare Administrative Contractors create patchwork payment landscapes that delay commercial adoption of novel CNS biomarker panels.
- Lumbar Puncture Access Limitations:Neurologist workforce concentration in academic medical centers restricts cerebrospinal fluid collection capacity, constraining biomarker test volume growth outside major metropolitan hospital systems.
Strategic Opportunities
- Blood-Based Biomarker Substitution:Plasma p-tau217 and p-tau181 assays calibrated against amyloid PET status enable community neurology practices to screen for Alzheimer's pathology without specialized imaging infrastructure.
- Parkinson's Disease Biomarker Qualification:The FDA's emerging qualification pathway for alpha-synuclein seed amplification assays creates first-mover advantages for diagnostic developers establishing analytical validation packages ahead of therapeutic pipeline maturation.
- EU Green Deal Sustainable Manufacturing:European procurement mandates for reduced reagent packaging waste and solvent recovery systems favor regional assay manufacturers with closed-loop production capabilities.
Industry Challenges
- Cross-Platform Harmonization Complexity:Inter-laboratory coefficient of variation for p-tau assays remains above 15% across Lumipulse, Elecsys, and Simoa platforms, complicating multi-site clinical trial data aggregation and regulatory submission integrity.
- CAP Proficiency Testing Gaps:No external quality assurance programs currently cover emerging plasma biomarker combinations, forcing laboratories to develop costly in-house validation protocols without peer benchmarking mechanisms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Central Nervous System (CNS) Biomarkers Market |
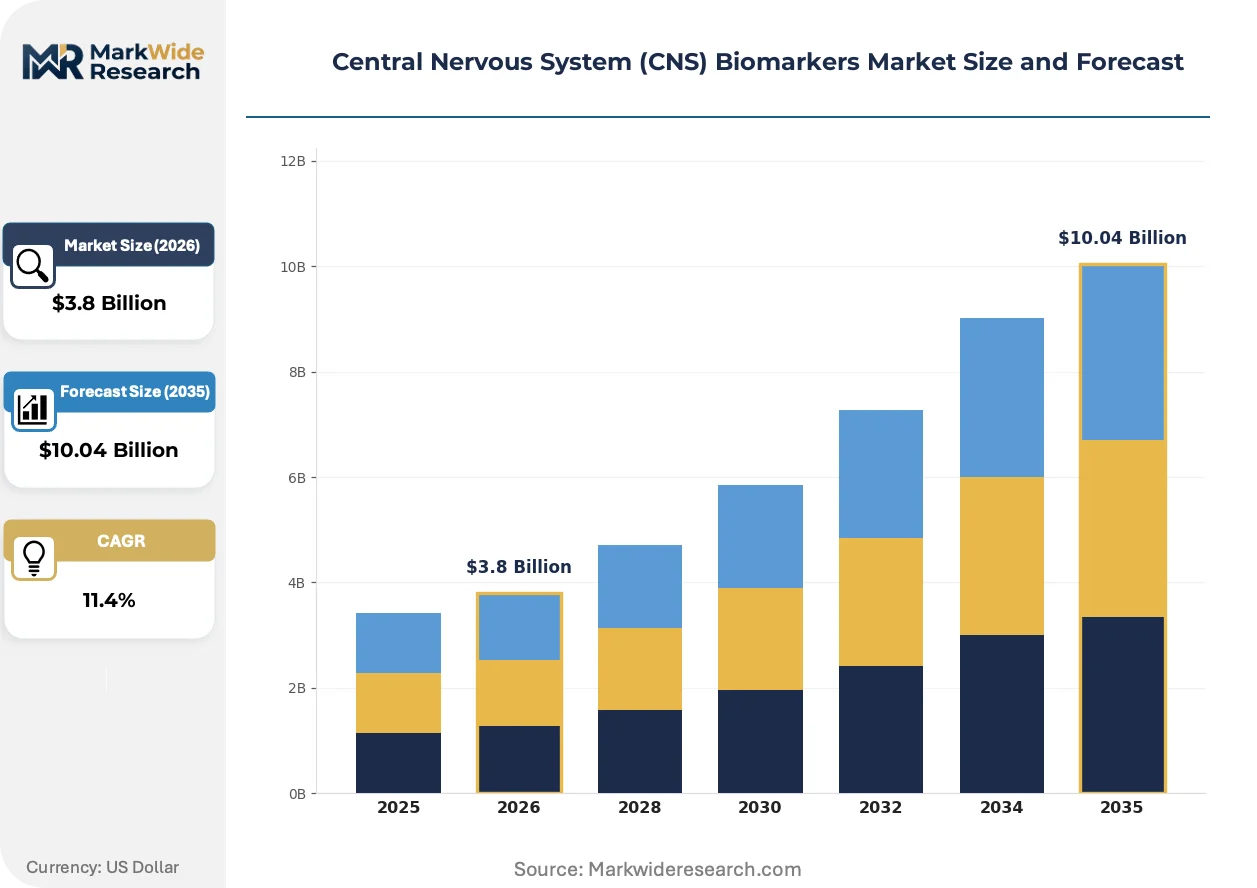
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Biomarker Type: Genetic, Epigenetic, Proteomic, Imaging Application: Disease Diagnosis, Drug Development, Prognosis, Clinical Trials End User: Pharmaceutical Companies, Research Institutions, Hospitals, Diagnostics Laboratories Technology: Next-Generation Sequencing, Mass Spectrometry, MRI, Biomarker Platforms |
| Companies Covered | Thermo Fisher Scientific, F. Hoffmann-La Roche, Bio-Rad Laboratories, Merck KGaA, Siemens Healthineers, Abbott Laboratories, QIAGEN, PerkinElmer, Charles River Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Central Nervous System (CNS) Biomarkers Market Emerging Trajectories
Multiplexed proteomic detection platforms are collapsing the cost-per-analyte economics of CNS biomarker testing, while regulatory qualification precedents established in Alzheimer's disease propagate to adjacent neurodegenerative indications.
Simoa technology is absorbing the analytical workload previously handled by enzyme-linked immunosorbent assays in reference laboratory settings. Academic medical center core facilities and contract research organizations are adopting single-molecule detection for longitudinal neurofilament light chain monitoring in multiple sclerosis therapeutic trials. This platform transition is compressing sample volume requirements from milliliters to microliters while extending dynamic range across four orders of magnitude.
EMA's qualification opinion pathway for novel methodologies is reshaping evidentiary standards for CNS biomarker incorporation in European marketing authorization applications. The pathway requires prospective analytical and clinical validation studies that parallel rather than follow therapeutic development programs. Plasma biomarker developers targeting Parkinson's and frontotemporal dementia indications are structuring qualification packages to mirror precedents established for CSF Aβ42/tau ratios in Alzheimer's disease.
Hospital laboratory procurement committees are unbundling biomarker assay contracts from historical instrument-locked reagent rental agreements. Independent reference laboratories and health system outreach programs now negotiate direct assay supply contracts with multiplex platform manufacturers. This purchasing pattern shift is most visible in United States integrated delivery networks consolidating neurology service lines under centralized laboratory management.
Central Nervous System (CNS) Biomarkers Market Segmentation
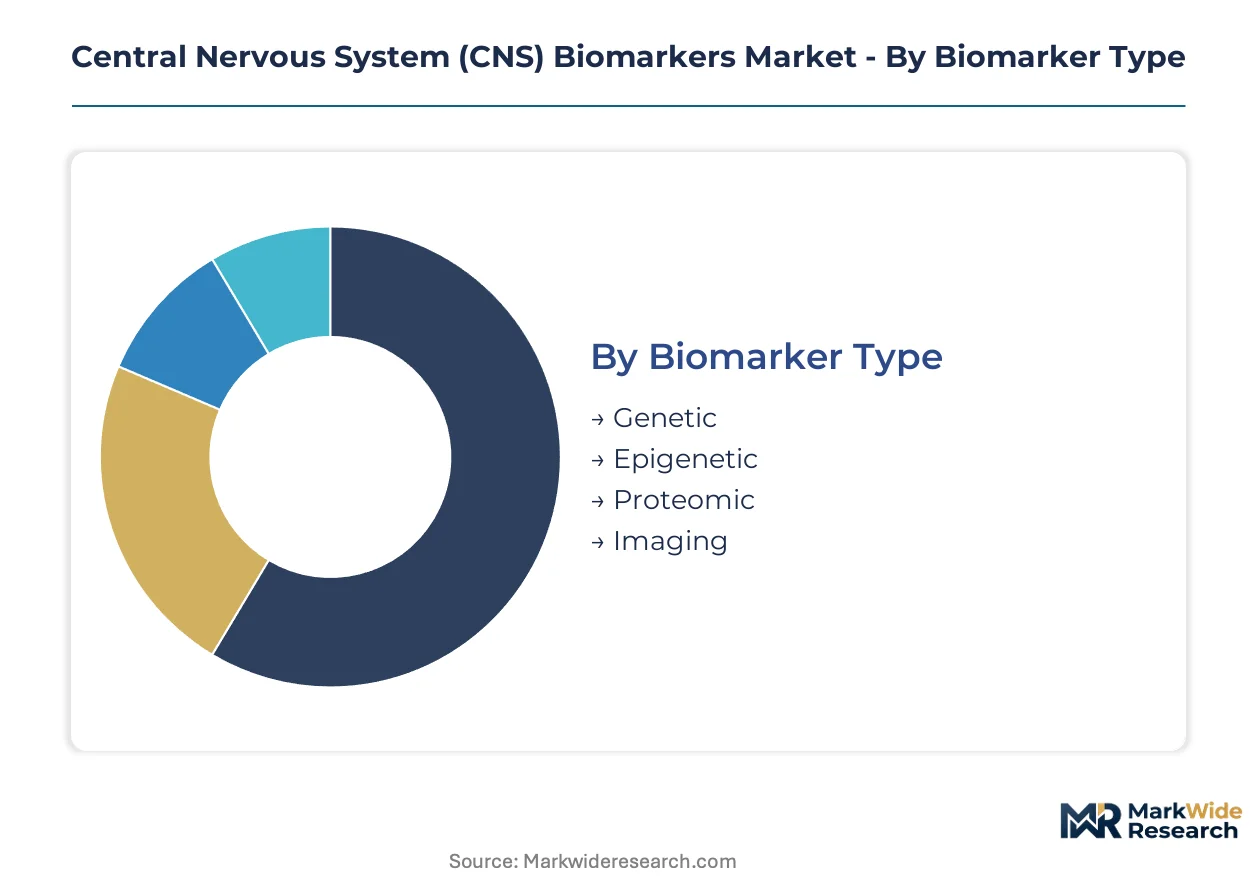
CNS biomarker segmentation reflects dual-use pressures: standalone diagnostic assays for clinical decision-making versus embedded systems integrated into pharmaceutical development pipelines. Category boundaries blur as proteomic platforms migrate from research-only deployment into FDA-qualified companion diagnostics.
Biomarker Type:
Proteomic and imaging biomarkers anchor embedded therapeutic development workflows, while genetic and epigenetic assays remain predominantly standalone research tools with limited regulatory qualification.
- Proteomic:Phosphorylated tau isoforms and neurofilament light chain assays dominate current clinical utility through established analytical validation frameworks. Pharmaceutical sponsors in the United States integrate these biomarkers into adaptive trial designs for Alzheimer's disease-modifying therapies, pulling demand toward high-throughput platforms.
- Imaging:Amyloid PET and volumetric MRI protocols represent the fastest-expanding segment as pharmaceutical companies embed these endpoints into regulatory submission dossiers. Academic medical centers in Boston and San Francisco concentrate deployment capacity for multicenter therapeutic trials.
- Genetic:APOE genotyping and polygenic risk scores remain research-stage tools with limited reimbursement coverage.
- Epigenetic:DNA methylation signatures for neurodegeneration show promise but lack standardized assay platforms for clinical translation.
Proteomic biomarkers lead volumes today; imaging biomarkers are gaining share fastest.
Application:
Cost tier separation distinguishes high-margin drug development services from lower-reimbursement clinical diagnostic applications.
- Drug Development:Biomarker-guided patient stratification commands premium pricing in pharmaceutical sponsor contracts. Contract research organizations in the United States and Germany configure dedicated CNS biomarker core facilities to support Phase II-III transitions under FDA accelerated approval pathways.
- Disease Diagnosis:Clinical laboratory services face reimbursement compression from CMS Local Coverage Determination variability across Medicare Administrative Contractors.
- Clinical Trials:Real-time biomarker endpoint qualification demands 24-hour turnaround capabilities that concentrate in specialized reference laboratories.
- Prognosis:Longitudinal monitoring applications for multiple sclerosis progression tracking show emerging utility in integrated delivery networks.
Drug development commands revenue concentration today; disease diagnosis is expanding most quickly into community neurology settings.
End User:
Customer type determines assay format requirements: pharmaceutical sponsors demand batch flexibility, while hospital laboratories prioritize automated throughput.
- Pharmaceutical Companies:Sponsor-driven biomarker adoption concentrates spending on qualification-grade assay platforms with full analytical traceability. Roche and Thermo Fisher anchor multi-year service contracts across top-20 neurology therapeutic developers.
- Diagnostics Laboratories:Independent reference laboratories and health system outreach programs negotiate direct supply contracts unbundled from instrument-locked reagent rental agreements.
- Research Institutions:NIH-funded neurodegeneration consortia establish analytical validation precedents that reduce commercial assay development risk.
- Hospitals:Neurologist workforce concentration in academic medical centers restricts cerebrospinal fluid collection capacity outside major metropolitan systems.
Pharmaceutical companies dominate spending today; diagnostics laboratories are climbing the fastest as procurement patterns shift.
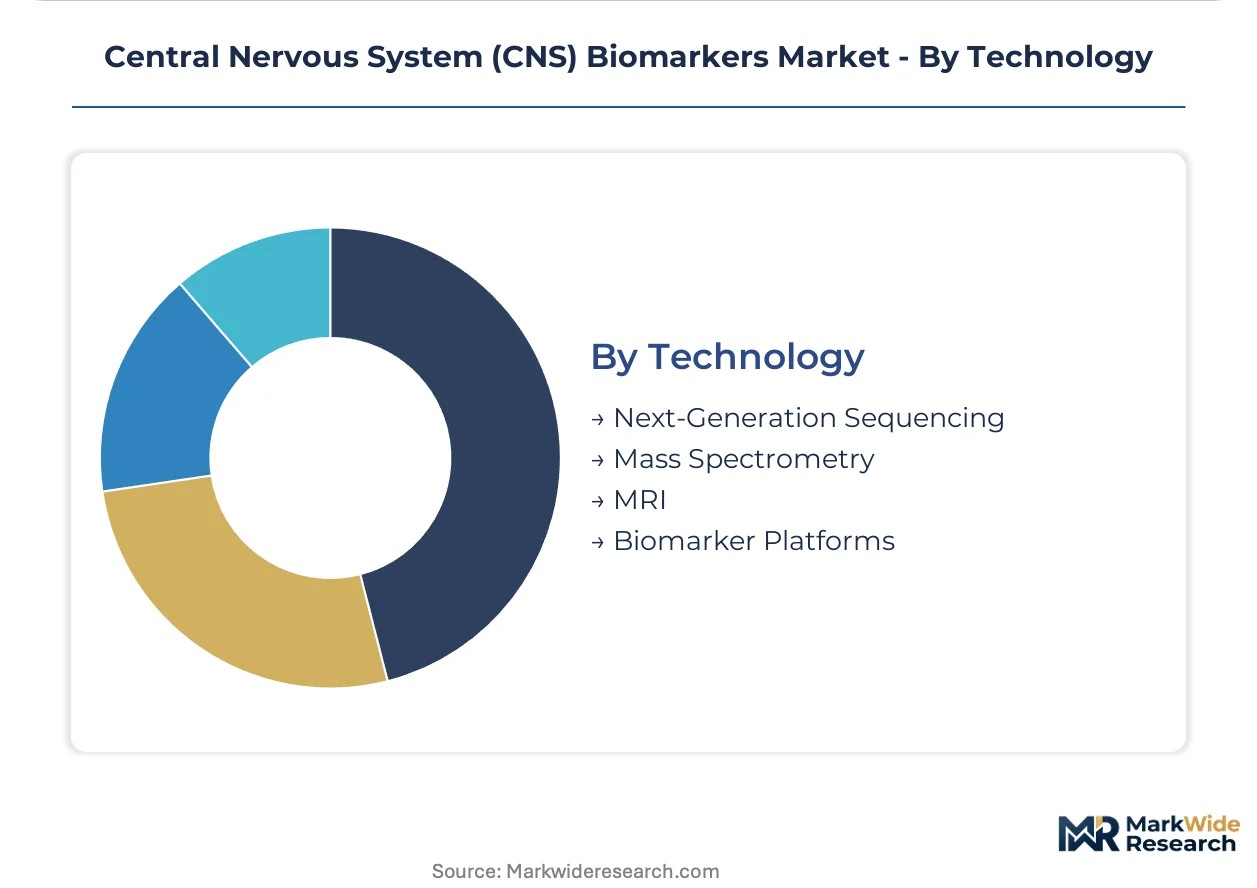
Technology:
Platform maturity separates established clinical workflows from emerging methodologies seeking regulatory qualification.
- Biomarker Platforms:Simoa and Ella single-molecule array systems achieve femtomolar detection thresholds that displace legacy ELISA workflows. Contract research organizations adopt these platforms for longitudinal neurofilament light chain monitoring with microliter sample volumes.
- Mass Spectrometry:High-resolution proteomic quantification remains concentrated in specialized reference laboratories with limited point-of-care translation.
- Next-Generation Sequencing:CNS applications focus on cerebrospinal fluid cell-free DNA for central nervous system lymphoma and leptomeningeal disease monitoring.
- MRI:Volumetric and functional imaging protocols require specialized neuroradiology interpretation that constrains deployment to academic medical centers.
Biomarker platforms anchor installed base today; mass spectrometry shows steepest expansion trajectory in precision neurology applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The CNS biomarkers industry traces its commercial origins to post-war European analytical chemistry traditions, with Swiss and German precision instrumentation firms establishing the foundational assay platforms that now dominate neurodegeneration diagnostics worldwide.
United States
NIH-funded neurodegeneration research consortia in Bethesda and Boston generate the analytical validation precedents that reduce commercial assay development risk for phosphorylated tau platforms. FDA accelerated approval pathways for Alzheimer's therapies pull biomarker demand into Phase II-III trial transitions. The San Francisco Bay Area concentrates specialized contract research infrastructure for longitudinal neurofilament light chain monitoring.
Germany
Reference material scarcity for tau isoform certification concentrates at two German metrology institutes, creating supply bottlenecks that constrain assay manufacturer analytical traceability. EMA qualification opinion pathways require parallel biomarker validation studies that mirror therapeutic development timelines. Munich and Heidelberg anchor high-throughput proteomics core facilities serving European pharmaceutical sponsors.
Switzerland
Integrated companion diagnostic development tied to neurology therapeutic pipelines sustains premium-margin service contracts across Basel and Zurich pharmaceutical clusters. Swissmedic maintains alignment with FDA biomarker qualification standards for accelerated neurodegeneration therapy approvals. The Lake Geneva region concentrates precision diagnostics manufacturing with closed-loop solvent recovery systems.
United Kingdom
London academic medical centers deploy amyloid PET and volumetric MRI protocols for multicenter therapeutic trials under MHRA oversight. NHS England's diagnostic procurement frameworks increasingly unbundle biomarker assay contracts from instrument-locked reagent rental agreements. The Oxford-Cambridge arc hosts specialized reference laboratories for cerebrospinal fluid protein quantification.
Japan
PMDA's emerging alignment with FDA surrogate endpoint frameworks creates regulatory convergence for blood-based biomarker substitution in community neurology settings. METI funding for single-molecule array technology adoption accelerates platform transitions from legacy ELISA workflows. Tokyo and Osaka metropolitan areas concentrate neuroradiology interpretation capacity for volumetric MRI protocols.
Central Nervous System (CNS) Biomarkers Market Vendor Landscape
Premium-margin players sit above commodity-margin players across qualification-grade assay platforms versus research-use-only reagents. The market structure consolidates around three strategic tiers: integrated life science conglomerates with proteomics platform breadth, specialized analytical instrument manufacturers with cerebrospinal fluid precision capabilities, and contract research organizations with dedicated CNS biomarker core facilities. Dominant competitive moves include strategic partnerships for companion diagnostic co-development and geographic expansion through multi-year service contracts with top-20 neurology therapeutic developers.
Among integrated diagnostic-platform conglomerates, Thermo Fisher Scientific and F. Hoffmann-La Roche exemplify the premium-tier archetype through proteomics platform breadth and companion diagnostic integration respectively. Bio-Rad Laboratories occupies a defensible specialist position in analytical instrument precision for reference laboratory settings. These three entities anchor the competitive structure that shapes assay validation workflows and procurement committee negotiations across pharmaceutical sponsor and hospital laboratory customer segments.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| F. Hoffmann-La Roche |
| Bio-Rad Laboratories |
| Merck KGaA |
| Siemens Healthineers |
| Abbott Laboratories |
| QIAGEN |
| PerkinElmer |
| Charles River Laboratories |
| Others |
Supply Flow & Price Mechanics
Qualification-grade assay platforms versus research-use-only reagent tiers split the CNS biomarker market into divergent pricing architectures, with FDA-qualified companion diagnostics commanding premium service contracts while commodity ELISA workflows face procurement unbundling from instrument-locked agreements. This bifurcation concentrates pricing power with integrated platform conglomerates in Switzerland and Germany, while reference material scarcity at European metrology institutes constrains supply chain flexibility for analytical traceability.
Pricing Analysis
Three-tier pricing structure across qualification-grade, clinical-laboratory, and research-use-only levels anchors the dominant model, with certification tier and volume scale serving as primary differentiation drivers. Pricing pressure stems from CMS Local Coverage Determination variability across Medicare Administrative Contractors, compressing reimbursement for novel biomarker panels. Pharmaceutical sponsors exhibit lowest price sensitivity given qualification requirements, while community hospital laboratories face acute margin constraints from capitated diagnostic budgets.
Supply Chain Analysis
CLIA certification and CAP accreditation requirements gate entry for diagnostics laboratories returning patient-specific biomarker results, concentrating qualified supply capacity in the United States, Germany, and Switzerland. Raw material dependencies center on certified reference standards for phosphorylated tau isoforms, recombinant antibody production, and single-molecule array consumables. Single-source vulnerability at two German metrology institutes creates structural risk for assay manufacturer analytical traceability. Distribution runs through specialized reference laboratories and contract research organizations with dedicated CNS biomarker core facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage opportunities emerge between United States premium pricing for qualification-grade platforms and European sustainable manufacturing mandates under EU Green Deal procurement frameworks, with reagent packaging waste reduction requirements creating cost differentials for regional assay manufacturers.
For Market Incumbents: Anticipate blood-based biomarker substitution disrupting cerebrospinal fluid collection workflows by securing exclusive supply contracts for plasma p-tau217 and p-tau181 assay platforms ahead of community neurology adoption curves. Deepen backward integration into recombinant antibody production to mitigate reference material scarcity risks at European metrology institutes.
For New Entrants and Emerging Players: Begin with Parkinson's disease alpha-synuclein seed amplification assays as the most penetrable white-space target, given FDA's emerging qualification pathway and limited incumbent analytical validation packages. Target integrated delivery networks consolidating neurology service lines under centralized laboratory management as the primary go-to-market channel.
For Investors and Strategic Acquirers: Consolidation pressure builds where cross-platform harmonization complexity exceeds 15% inter-laboratory coefficient of variation for p-tau assays, favoring acquisition of specialized reference laboratories with proprietary validation protocols. Watch FDA guidance on surrogate endpoint acceptability for Parkinson's disease and multiple sclerosis as the critical inflection signal for platform valuation repricing.
| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Co-Development | Locks in multi-year service contracts with top-20 neurology therapeutic developers under FDA accelerated approval pathways. |
| Blood-Based Biomarker Platform Transition | Captures community neurology volume expansion as plasma assays displace lumbar puncture-dependent workflows. |
| Reference Laboratory Network Consolidation | Centralizes 24-hour turnaround capabilities for real-time biomarker endpoint qualification in adaptive trials. |
| Sustainable Manufacturing Certification | Qualifies for EU Green Deal procurement mandates favoring closed-loop solvent recovery systems. |
| Cross-Platform Harmonization Investment | Reduces inter-laboratory variability below 15% threshold for multi-site clinical trial data integrity. |
Methodological Framework
Bottom-up pharmaceutical sponsor and diagnostics laboratory demand modeling reconciled against top-down proteomics platform shipment tracking forms the analytical core of this study. Primary interviews with drug development executives, regulatory affairs leads, CLIA laboratory directors, and hospital procurement managers combined with secondary validation against FDA Biomarker Qualification Program filings, EMA qualification opinion records, ClinicalTrials.gov protocol registries, and CMS Local Coverage Determination databases.
Historical trendline analysis across biomarker type, application, end user, and technology segmentation dimensions informed projection framework construction over the forecast period. CAGRs derived from weighted average growth contributions across proteomic, imaging, genetic, and epigenetic biomarker categories, with specific inputs from NIH neurodegeneration research consortium funding trajectories and pharmaceutical pipeline biomarker integration rates.
Several conditions sit outside the modeled scope, including regulatory qualification timeline delays, reimbursement code establishment failures, and unforeseen platform technology obsolescence. Deviation in FDA surrogate endpoint acceptability standards for neurodegeneration indications would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
North America Alopecia Market
Specialty Medicine
Global Chronic Lymphocytic Leukemia Therapeutics Market
Specialty Medicine
Chemotherapy Induced Peripheral Neuropathy Treatment Market
Specialty Medicine
Cutaneous Radiation Injury Treatment Market
Specialty Medicine
Blastomycosis Treatment Market
Specialty Medicine
Ovarian Cysts Market
Specialty Medicine
Papillary Thyroid Cancer Market
Specialty Medicine
Achondroplasia Treatment Market
Specialty Medicine
Cholangiocarcinoma (CCA) Therapeutics Market
Specialty Medicine
Non-Alcoholic Steatohepatitis Treatment Market
Specialty Medicine
Global Plasma Therapeutics Market
Specialty Medicine
Musculoskeletal System Disorders Market
Specialty Medicine
Global Amyotrophic Lateral Sclerosis (ALS) Treatment Market
Specialty Medicine
Cystic Fibrosis Therapeutics Market
Specialty Medicine
Global Vasculitis Treatment Market
Specialty Medicine
Hypophosphatasia Treatment Market