
 Global Green and Bio-Based Plastic Additives Market | 2026-2036
Global Green and Bio-Based Plastic Additives Market Size, Share, and Industry Trends Forecast 2026-2036
Global Green and Bio-Based Plastic Additives Market Foresight
Petroleum-derived plasticizers is pivoting toward epoxidized soybean oil and citrate esters as resin compounders absorb cost volatility in fossil feedstocks. Clariant AG leverages its Swiss manufacturing base to supply halogen-free flame retardant concentrates for electrical housing grades. BASF SE anchors European demand through bio-based antioxidant masterbatches tailored to polyolefin recyclers. Evonik Industries AG competes with specialized processing aids that reduce energy intensity in extrusion lines.
Green and bio-based plastic additives comprise functional compounds derived from renewable biomass—vegetable oils, starch, lignin, or microbial fermentation—that impart process stability, durability, or safety to polymer matrices without relying on fossil carbon; typical specifications include bio-carbon content exceeding 20 percent per ASTM D6866 and thermal stability thresholds above 200 degrees Celsius for extrusion-grade plasticizers. These additives primarily enable converters to meet regulatory thresholds for recycled and renewable content while preserving mechanical performance in reprocessed resins. Plasticizers and antioxidants dominate current revenue pools as mature categories with established supply chains, while UV stabilizers from lignin-derived platforms represent the fastest-expanding segment as agricultural film producers seek photodegradation control without synthetic benzotriazoles. Processing aids in masterbatch form capture concentrated margins where compounders pay premiums for dust-free handling and precise dosing in automated lines.
REACH restrictions on SVHC candidate substances and the EU F-Gas Regulation constrain conventional additive chemistries across European compounding operations, while FDA food-contact notifications and EPA Safer Choice labeling shape product qualification pathways in North American packaging. China's GB standards and dual carbon goals from MEE pressure domestic resin producers to certify bio-carbon content in export-bound formulations. Stakeholders must monitor evolving compostability certifications from ISO and national regulators, as misalignment between industrial composting infrastructure and additive degradation claims threatens market access for single-use applications.
Market Dynamics
REACH restrictions on SVHC candidate substances and FDA food-contact rule tightening are forcing compounders to abandon phthalate plasticizers faster than bio-based alternatives can scale, creating a structural supply-demand mismatch that concentrates purchasing power among European converters with advance certification.
Growth Catalysts
- EU Green Deal recycled-content quotas:Mandatory targets under EU Green Deal implementation are compelling German and French packaging converters to source bio-derived stabilizers that maintain mechanical performance in reprocessed polyolefins.
- Agricultural film sector:Photodegradation control requirements without synthetic benzotriazoles are pulling lignin-derived UV stabilizers into high-volume mulching and greenhouse applications.
- Epoxidized soybean oil:Cost volatility in fossil feedstocks is accelerating resin compounder pivot toward vegetable-oil plasticizers with thermal stability thresholds above 200 degrees Celsius.
Market Restraints
- Feedstock concentration risk:Soybean and corn supply chains cluster in US Midwest and Brazilian agricultural belts, exposing additive producers to crop yield volatility and trade policy friction.
- Technical performance gaps:Bio-based antioxidants currently fail to match phenolic stabilizer efficacy in long-duration outdoor applications exceeding five-year service life.
- Compostability certification misalignment:Divergent industrial composting infrastructure standards between ISO 17088 and national regulators threaten market access for single-use packaging formulations.
Strategic Opportunities
- India packaging conversion:BIS standards evolution and FSSAI food-contact pathways remain underdeveloped for bio-based additives, creating first-mover positioning for certified suppliers.
- Processing aid masterbatches:Dust-free handling and precise dosing requirements in automated extrusion lines command concentrated margins where compounders pay premiums for formulation integration.
- Japan electrical housing:METI energy-efficiency mandates and JIS flame-retardant standards are opening halogen-free concentrate demand that Swiss and German suppliers currently underserve.
Industry Challenges
- ASTM D6866 certification backlog:Third-party bio-carbon verification timelines stretch six to nine months, delaying product qualification for converters facing immediate compliance deadlines.
- Extrusion line reconfiguration:Legacy equipment optimized for petroleum-derived additives requires screw design and temperature profile modifications to process bio-based plasticizers without output loss.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Green and Bio-Based Plastic Additives Market |
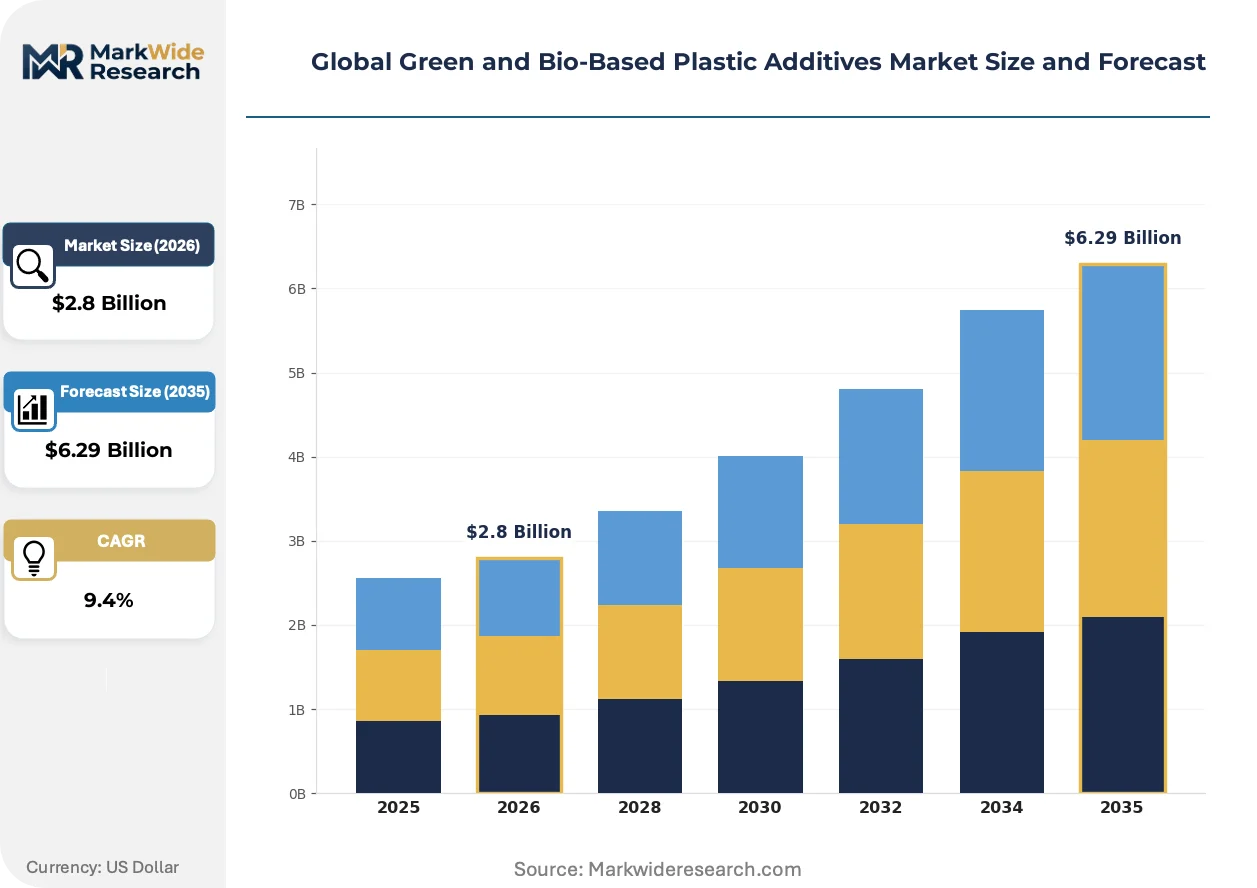
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $6.29 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antioxidants, Plasticizers, UV Stabilizers, Processing Aids, Flame Retardants Application: Packaging Films, Automotive Components, Consumer Goods, Electrical Devices, Agricultural Films End User Industry: Food & Beverage, Electronics Manufacturing, Packaging Industry, Automotive Manufacturing, Construction Sector Form: Powders, Granules, Liquids, Masterbatches, Pellets |
| Companies Covered | Clariant AG, Emery Oleochemicals, Cargill Inc, Avient Corporation, BASF SE, Evonik Industries AG, DIC Corporation, LANXESS, ADEKA Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Green and Bio-Based Plastic Additives Market Shifts & Advancements
Formulation science is fragmenting toward modular, application-specific additive packages that compounders can tune by resin type and end-use performance threshold rather than purchasing standardized commodity blends.
Lignin-derived UV stabilizer technology is modularizing around depolymerization processes that fractionate agricultural waste into photodegradation-control compounds with tunable absorption spectra. Agricultural film producers in Spain and Italy are piloting these platforms for mulching applications where synthetic benzotriazole replacement determines contract renewal. The technology is modularizing supplier-compounder relationships, enabling converters to specify performance tiers rather than accepting fixed-formula masterbatches.
REACH candidate list expansion to include additional phthalate esters is eliminating conventional plasticizer pathways for food-contact articles across European compounding operations. German converters are accelerating citrate ester and epoxidized vegetable oil qualification to maintain supply contracts with multinational brand owners. The regulation is compressing formulation development cycles from eighteen months to six months for packaging sector suppliers.
Automotive tier-one suppliers are unbundling additive procurement from resin purchasing, establishing direct relationships with bio-based stabilizer producers to secure documentation for recycled-content claims. This disintermediation is displacing traditional distributor channels in German and US Midwest automotive clusters. The shift is most visible in polypropylene interior trim applications where OEM sustainability scorecards determine supplier selection.
Global Green and Bio-Based Plastic Additives Market Segmentation
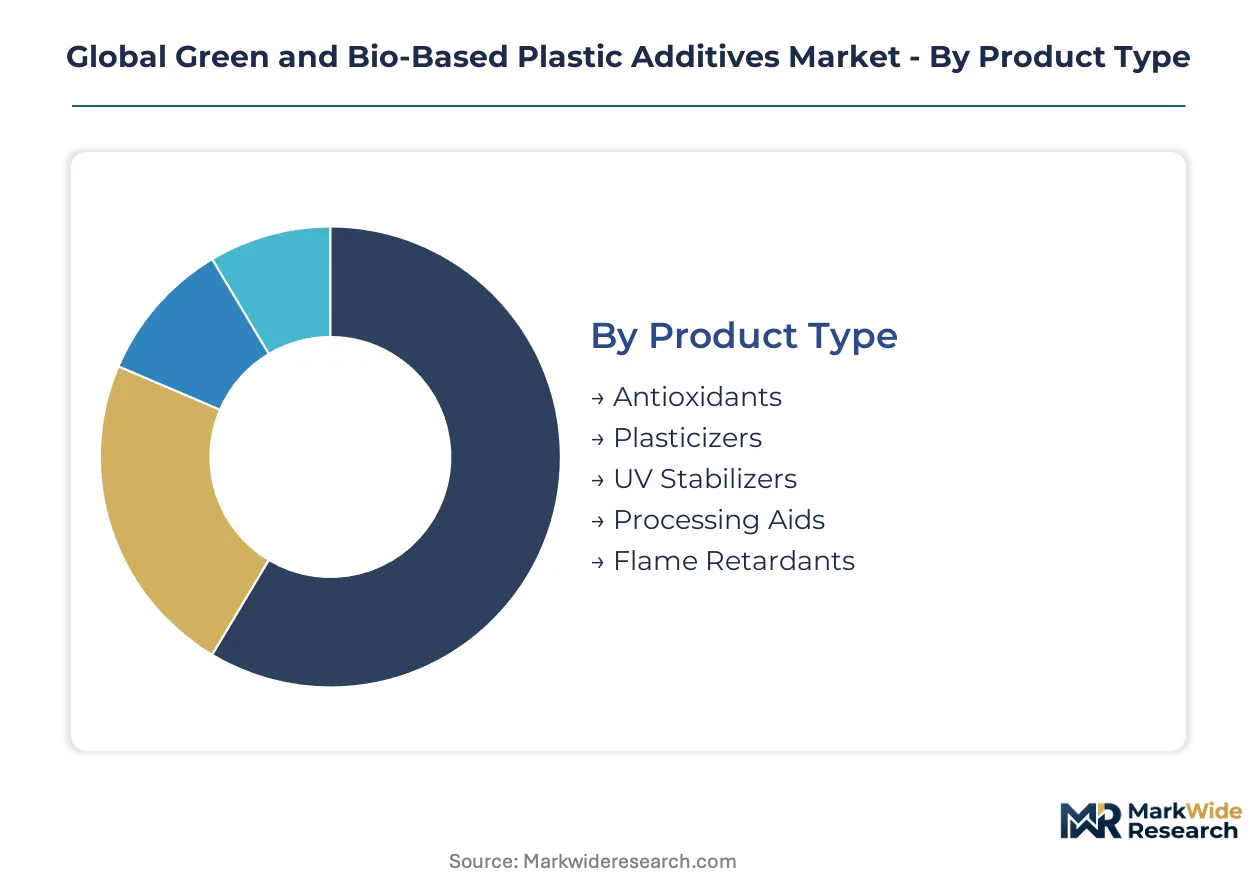
Segmentation in green and bio-based plastic additives reflects divergent certification burdens across product categories. Regulatory pathways from FDA, REACH, and BIS create tiered qualification timelines that reshape procurement priorities for compounders.
Product Type:
ASTM D6866 bio-carbon verification applies universally, yet REACH SVHC restrictions and FDA food-contact notifications impose segment-specific documentation loads that stretch six to nine months for plasticizers and antioxidants.
- Antioxidants:Phenolic and phosphite formulations derived from lignin or tocopherol platforms protect polyolefins during reprocessing. German packaging converters absorb the highest certification volumes under EU Green Deal recycled-content quotas.
- Plasticizers:Epoxidized soybean oil and citrate esters deliver thermal stability above 200 degrees Celsius for extrusion-grade applications. Resin compounders in the US Midwest and Brazil face feedstock concentration risk from clustered soybean supply chains.
- UV Stabilizers:Lignin-derived photodegradation control compounds from agricultural waste fractionation. Spanish and Italian agricultural film producers pilot these for mulching applications.
- Processing Aids:Masterbatch concentrates reduce energy intensity in extrusion lines. Automated dosing systems command premium positioning.
- Flame Retardants:Halogen-free concentrates for electrical housing grades. Swiss manufacturing bases supply European demand.
Leading the category by volume: Antioxidants. Expanding most quickly: UV Stabilizers.
Application:
Application segments stratify by performance threshold and regulatory exposure, with food-contact pathways imposing the steepest documentation requirements on packaging films.
- Packaging Films:Bio-derived stabilizers maintain mechanical integrity in reprocessed polyolefins for flexible food packaging. French and German converters face mandatory recycled-content thresholds.
- Automotive Components:Polypropylene interior trim applications where OEM sustainability scorecards determine supplier selection. Tier-one suppliers disintermediate traditional distributor channels.
- Consumer Goods:Durable applications with lower regulatory burden than food-contact segments. Performance gaps in long-duration outdoor use constrain bio-based antioxidant adoption.
- Electrical Devices:Halogen-free flame retardant concentrates meeting JIS standards in Japan and CE marking in Europe.
- Agricultural Films:Photodegradation control without synthetic benzotriazoles drives lignin-derived UV stabilizer uptake in greenhouse and mulching applications.
Highest certification density: Packaging Films. Steepest expansion trajectory: Agricultural Films.
End User Industry:
End user concentration determines margin structure, with food and electronics manufacturing segments absorbing premium pricing for qualified supply.
- Food & Beverage:FSSAI and FDA food-contact notifications shape additive qualification. REACH phthalate restrictions compress formulation development cycles to six months.
- Electronics Manufacturing:RoHS and CE marking requirements for electrical housing grades. METI energy-efficiency mandates in Japan open halogen-free concentrate demand.
- Packaging Industry:EU Green Deal implementation drives bio-derived stabilizer procurement across German and French compounding hubs.
- Automotive Manufacturing:Recycled-content documentation requirements reshape procurement relationships in German and US Midwest clusters.
- Construction Sector:Long-duration outdoor applications exceeding five-year service life expose bio-based antioxidant performance gaps.
Deepest margin pool: Food & Beverage. Fastest procurement restructuring: Packaging Industry.
Form:
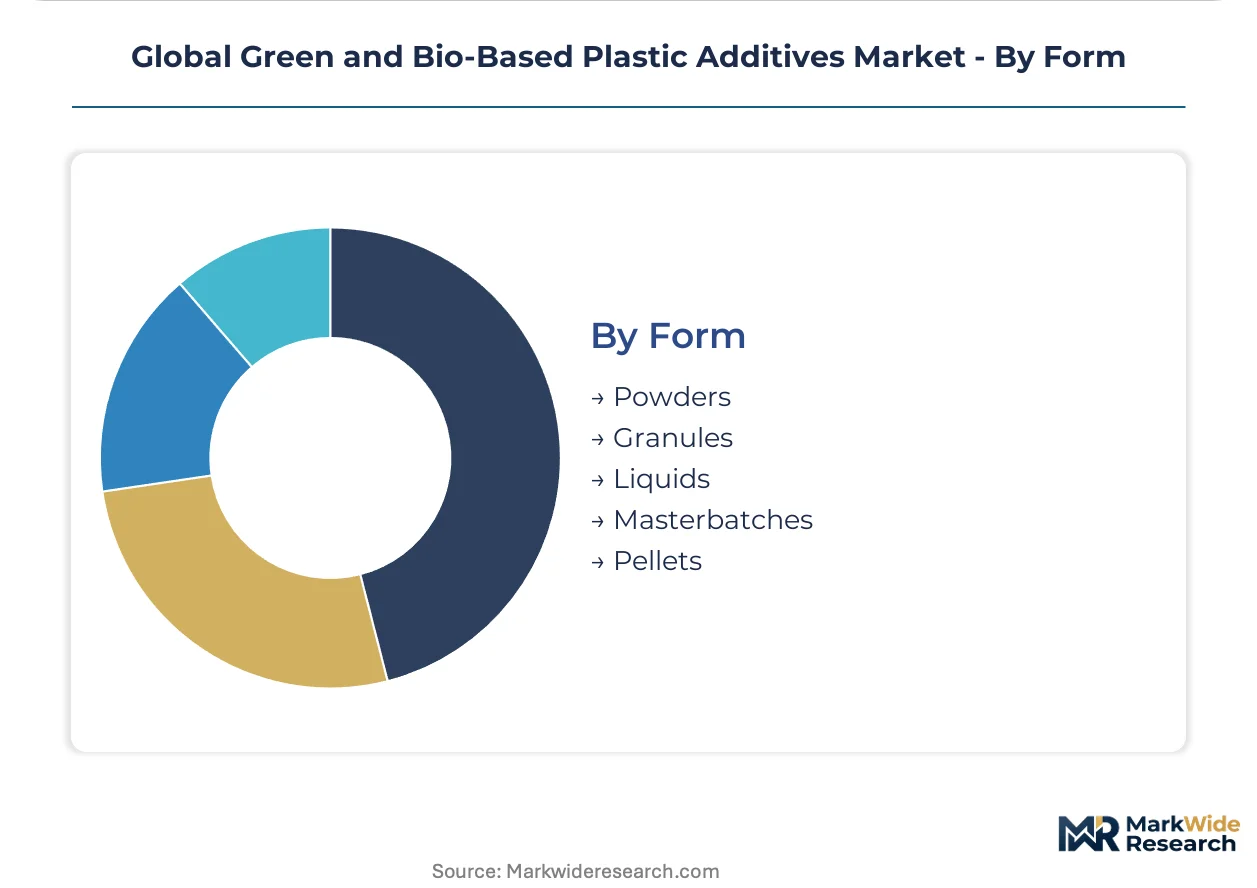
Physical form determines supply chain configuration, with masterbatches capturing concentrated margins through dust-free handling and precise dosing integration.
- Powders:Legacy format requiring dust control infrastructure. Declining share in automated extrusion environments.
- Granules:Intermediate handling characteristics for mid-scale compounders.
- Liquids:Epoxidized vegetable oil plasticizers in bulk tank delivery for high-volume converters.
- Masterbatches:Concentrated additive carriers enabling precise dosing in automated lines. Compounders pay premiums for formulation integration and reduced handling costs.
- Pellets:Standardized format for resin compounders with legacy equipment configurations.
Premium positioning: Masterbatches. Volume concentration: Liquids for plasticizer applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Packaging converters in Germany, China, and the United States absorb the highest procurement volumes for bio-derived stabilizers and plasticizers as regulatory deadlines compress qualification timelines.
Germany
REACH restrictions on phthalate esters are eliminating conventional plasticizer pathways for food-contact articles across North Rhine-Westphalia compounding operations. The EU Green Deal recycled-content quotas compel converters in the Ruhr industrial belt to source bio-derived antioxidants that maintain mechanical integrity in reprocessed polyolefins. Bavarian automotive clusters are disintermediating traditional distributor channels to secure direct additive supply with recycled-content documentation.
China
Resin producers in the Yangtze River Delta face MEE dual carbon goals and GB standards pressure to certify bio-carbon content in export-bound formulations. The country's national chemical regulator enforces tightening emissions controls on petroleum-derived additive production. Shenzhen and Dongguan electronics manufacturing hubs are accelerating halogen-free flame retardant qualification for electrical housing grades.
United States
Midwest resin compounders pivot toward epoxidized soybean oil plasticizers as fossil feedstock cost volatility disrupts conventional supply economics. FDA food-contact notifications and EPA Safer Choice labeling shape additive qualification pathways for flexible packaging producers in the Chicago industrial corridor. Agricultural film manufacturers in Iowa and Illinois are piloting lignin-derived UV stabilizers for mulching applications.
India
BIS standards evolution and FSSAI food-contact pathways remain underdeveloped for bio-based additives, creating first-mover positioning opportunities for certified suppliers. The national standards body is drafting bio-carbon verification protocols aligned with ASTM D6866 methodologies. Maharashtra and Gujarat packaging conversion clusters are initiating supplier qualification programs ahead of anticipated regulatory mandates.
Japan
METI energy-efficiency mandates and JIS flame-retardant standards are opening halogen-free concentrate demand that European suppliers currently underserve. The Kanto region's electrical device manufacturers are reformulating housing grades to eliminate brominated compounds. Osaka-based automotive tier-one suppliers are unbundling additive procurement from resin purchasing to secure sustainability scorecard documentation.
Global Green and Bio-Based Plastic Additives Market Competitive Landscape
Capacity expansion dominates the current landscape as established chemical conglomerates scale bio-based additive production to capture procurement restructuring in packaging and automotive sectors. The vendor base stratifies into three tiers: integrated petrochemical majors with renewable feedstock divisions, mid-scale oleochemical specialists with vegetable oil processing heritage, and regional compounders with masterbatch formulation capabilities. M&A activity and strategic partnerships represent the dominant competitive moves as players secure feedstock access and certification expertise.
Within the integrated chemical major tier, BASF SE and Evonik Industries AG exemplify archetypes leveraging European manufacturing bases to supply antioxidant masterbatches and specialized processing aids. Among oleochemical specialists, Emery Oleochemicals and Cargill Inc occupy positions anchored by captive vegetable oil supply chains and agricultural feedstock processing infrastructure. These players represent the feedstock-integrated model that compounders favor for supply security amid crop yield volatility.
| Leading Market Players |
|---|
| Clariant AG |
| Emery Oleochemicals |
| Cargill Inc |
| Avient Corporation |
| BASF SE |
| Evonik Industries AG |
| DIC Corporation |
| LANXESS |
| ADEKA Corporation |
| Others |
Supply & Pricing Matrix
Soybean oil feedstock costs transmit directly through epoxidized plasticizer pricing tiers, with US Midwest crop yields and Brazilian export flows determining baseline input economics before certification premiums stratify downstream buyer segments.
Pricing Analysis
Volume concentration in commodity-grade epoxidized soybean oil separates from margin-rich masterbatch concentrates where automated dosing integration commands premium positioning. Price differentiation hinges on ASTM D6866 bio-carbon verification tier and REACH SVHC documentation completeness. Cost compression in standard-grade antioxidants is intensifying as phenolic stabilizer incumbents defend share against lignin-derived alternatives. Tier-one automotive suppliers exhibit lowest price sensitivity due to sustainability scorecard requirements, while mid-scale packaging converters in India and Southeast Asia absorb highest budget pressure.
Supply Chain Analysis
Vegetable oil supply rests on US Midwest soybean crushing capacity, Brazilian agricultural belt exports, and Malaysian palm oil processing infrastructure. Key inputs span epoxidized soybean oil, lignin fractions from pulp mills, and citric acid fermentation streams. Single-source vulnerability concentrates in specialty phosphite antioxidant precursors where German and Swiss producers dominate technical-grade output. Distribution runs through regional compounding hubs that qualify masterbatch formulations for converter-specific extrusion line configurations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ASTM D6866 certification backlog stretching six to nine months props pricing power among qualified suppliers, constraining rapid supply response despite accelerating procurement from packaging converters facing EU Green Deal deadlines.
For Market Incumbents: Deploy captive feedstock sourcing through long-term offtake agreements with Brazilian soybean processors and US Midwest crushing facilities to neutralize crop yield volatility. Accelerate lignin-derived UV stabilizer capacity in European compounding hubs before agricultural film contract renewals consolidate around synthetic benzotriazole replacements. Channel control through direct technical service relationships with automotive tier-one suppliers displaces distributor intermediation in sustainability documentation procurement. For New Entrants and Emerging Players: The premium-to-economy gap in REACH-compliant plasticizer supply opens positioning for citrate ester producers with accelerated FDA food-contact notification pathways. White-space concentration sits in India packaging conversion ahead of BIS bio-carbon verification mandate finalization, and in Japan electrical housing where METI energy-efficiency compliance remains undersupplied by European halogen-free concentrate producers. Go-to-market execution should anchor on dust-free masterbatch formulation partnerships with automated extrusion line integrators. For Investors and Strategic Acquirers: MEE dual carbon goal acceleration in China is the leading indicator that export-bound formulation certification demand will outpace domestic bio-based additive capacity expansion. Long-term viability frames around feedstock-integrated oleochemical specialists with vegetable oil processing heritage and established ASTM D6866 verification workflows. Acquisition screening should prioritize mid-scale compounders with masterbatch formulation capabilities in underpenetrated Asian markets. The signal to monitor is REACH candidate list expansion velocity compressing conventional plasticizer qualification timelines below twelve months.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feedstock Supply | Captive soybean oil sourcing from Brazilian agricultural belts neutralizes crop yield volatility exposure. |
| Masterbatch Capacity Expansion | Dust-free concentrate production for automated extrusion lines captures premium positioning in German compounding hubs. |
| ASTM D6866 Certification Investment | Accelerated bio-carbon verification timelines secure converter qualification ahead of EU Green Deal recycled-content mandates. |
| Long-term Supply Agreement with Automotive Tier-Ones | Direct stabilizer procurement relationships secure sustainability documentation for OEM scorecard compliance. |
| Joint Venture in India Packaging Conversion | First-mover positioning ahead of BIS standards finalization captures Maharashtra and Gujarat converter qualification programs. |
Research Methodology
Independent corroboration across customs and trade flow databases, SEC and European chemical industry association filings, and REACH registration dossiers underwrites the qualitative findings. Primary interviews with plant managers at European compounding facilities, procurement leads at German automotive tier-one suppliers, distribution channel partners in Asian packaging conversion clusters, and technical R&D directors at oleochemical specialists combined with secondary validation from FDA food-contact notification records, ECHA SVHC candidate list updates, and ASTM certification registry data. Bottom-up volume builds from additive consumption rates by resin type and application crossed with top-down market sizing from trade value flows.
Historical reference periods anchored the forecast window to pre-pandemic baseline demand patterns and post-regulatory-shift procurement acceleration phases across the projection horizon. Segmentation modeling spanned product type, application end-use, physical form, and regional production hub concentration. CAGRs derived from regression analysis against macro drivers including fossil feedstock price volatility indices and regulatory deadline clustering. Industry-specific forecast inputs incorporated EU Green Deal recycled-content quota implementation schedules and MEE dual carbon goal enforcement intensity trajectories.
Underlying measurement precision varies by segment; REACH-compliant plasticizers and antioxidant masterbatches carry tighter precision than emerging lignin-derived UV stabilizer categories where pilot-scale production confounds volume estimation. Forecasts reflect assumptions regarding crop yield stability, certification timeline standardization, and compounding equipment reconfiguration rates. A small set of triggers including REACH candidate list expansion velocity, ASTM D6866 accreditation backlog duration, and industrial composting infrastructure deployment warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bioplastics
Bio-Degradable Polymers Market
Bioplastics
Brazil Bioplastics Market
Bioplastics
Polyhydroxy Butyrate Market
Bioplastics
Global Bio-Polylactic Acid (PLA) Market
Bioplastics
Bio-PET Market
Bioplastics
Canada Bioplastics Market
Bioplastics
Global Bio-Based PET Market
Bioplastics
Global Bio-Plasticizers Market
Bioplastics
Bioplastics and Biopolymers Market
Bioplastics
Polylactic Acid (PLA) Straws Market
Bioplastics
Starch Blended Biodegradable Polymer Market
Bioplastics
Global Synthetic and Bio Based Polypropylene Market
Bioplastics
Biodegradable Plastics Market
Bioplastics
Southeast Asia Bioplastics Market
Bioplastics
Biodegradable Superabsorbent Materials Market
Bioplastics
Middle East and Africa Polylactic Acid (PLA) Market