
 Canada Bioplastics Market | 2026-2036
Canada Bioplastics Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Bioplastics Market Insights
Advanced fermentation pathways for polyhydroxyalkanoate (PHA) production is reconfiguring how Canadian compounders source raw materials without petrochemical feedstocks. NatureWorks LLC leverages its Blair, Nebraska proximity to supply PLA resin into Ontario's packaging converting corridor. BASF SE anchors its position through certified compostable ecovio formulations tailored to Health Canada's food-contact requirements. TERRAVERDAE BIOWORKS INC specializes in novel microbial strains that convert agricultural waste into PHA biopolymers at its Alberta pilot facility.
Bioplastics are polymers derived from renewable biomass sources including corn starch, sugarcane, cellulose, and microbial fermentation products, designed to biodegrade under industrial composting conditions or maintain durable performance comparable to conventional plastics. Polylactic Acid dominates current Canadian volume due to mature supply chains and established thermoforming infrastructure for food packaging trays and cold-drink cups. Starch-based Bioplastics compete aggressively on price in disposable cutlery and agricultural mulch film segments where performance tolerances are less stringent. Cellulose-based Bioplastics occupy premium positioning in medical supplies and high-barrier food packaging where oxygen transmission rates must meet exacting specifications.
Health Canada regulates food-contact bioplastics under the Food and Drugs Act while the Canadian Food Inspection Agency oversees agricultural mulch film biodegradability claims in field applications. Environment and Climate Change Canada's single-use plastics prohibition regulations are reshaping demand by banning conventional plastic checkout bags, cutlery, and foodservice ware, forcing converters toward certified compostable alternatives. Provincial extended producer responsibility frameworks in British Columbia and Ontario further tighten post-consumer recovery requirements. Stakeholders must monitor how forthcoming federal plastic registry rules will alter accountability for bioplastic end-of-life performance claims.
Market Dynamics
Health Canada's single-use plastics prohibition regulations are compressing substitution timelines across Ontario and Quebec packaging corridors, forcing compounders to certify compostable alternatives ahead of original compliance schedules.
Growth Catalysts
- Extended Producer Responsibility Frameworks:British Columbia and Ontario regulations mandate post-consumer recovery quotas that favor certified compostable materials over conventional plastics in foodservice applications.
- PHA Fermentation Scale-Up:Novel microbial strain development at Alberta pilot facilities is converting agricultural waste streams into bio-based resin feedstocks without petrochemical dependency.
- Retail Procurement Mandates:Major Canadian grocery chains are adopting compostable packaging specifications that cascade through Ontario's converting corridor.
Market Restraints
- PLA Feedstock Concentration:Corn starch and sugarcane supply chains concentrate in US Midwest and Brazilian agricultural belts, exposing Canadian compounders to cross-border price volatility and currency risk.
- Industrial Composting Infrastructure Gaps:Fewer than twelve commercial composting facilities nationwide accept certified compostable food packaging, creating end-of-life performance gaps between certification and actual diversion rates.
- Performance Specification Ceilings:Polylactic acid exhibits limited heat resistance above fifty-five degrees Celsius, restricting adoption in hot-fill beverage and microwaveable food tray segments where polypropylene maintains technical dominance.
Strategic Opportunities
- Atlantic Canada Underpenetration:Nova Scotia and New Brunswick lack established bioplastic converting infrastructure, creating first-mover positioning for regional compounders targeting maritime food processing clusters.
- Agricultural Mulch Film Conversion:Canadian Food Inspection Agency field biodegradability protocols are opening substitution pathways for starch-based formulations in Prairie province row-crop applications.
- Medical-Grade Cellulose Positioning:Oxygen transmission rate specifications for sterile barrier packaging favor cellulose-based biopolymers in Health Canada-regulated device and pharmaceutical segments.
Industry Challenges
- Composting Certification Timeline Compression:Biodegradable Products Institute and TÜV Austria industrial composting certifications require eighteen-to-twenty-four month validation cycles that lag behind retailer procurement deadlines.
- Thermoforming Equipment Retrofit Costs:Conventional polystyrene and PET processing lines require screw geometry and cooling system modifications to handle PLA's distinct shear sensitivity and crystallization kinetics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Bioplastics Market |
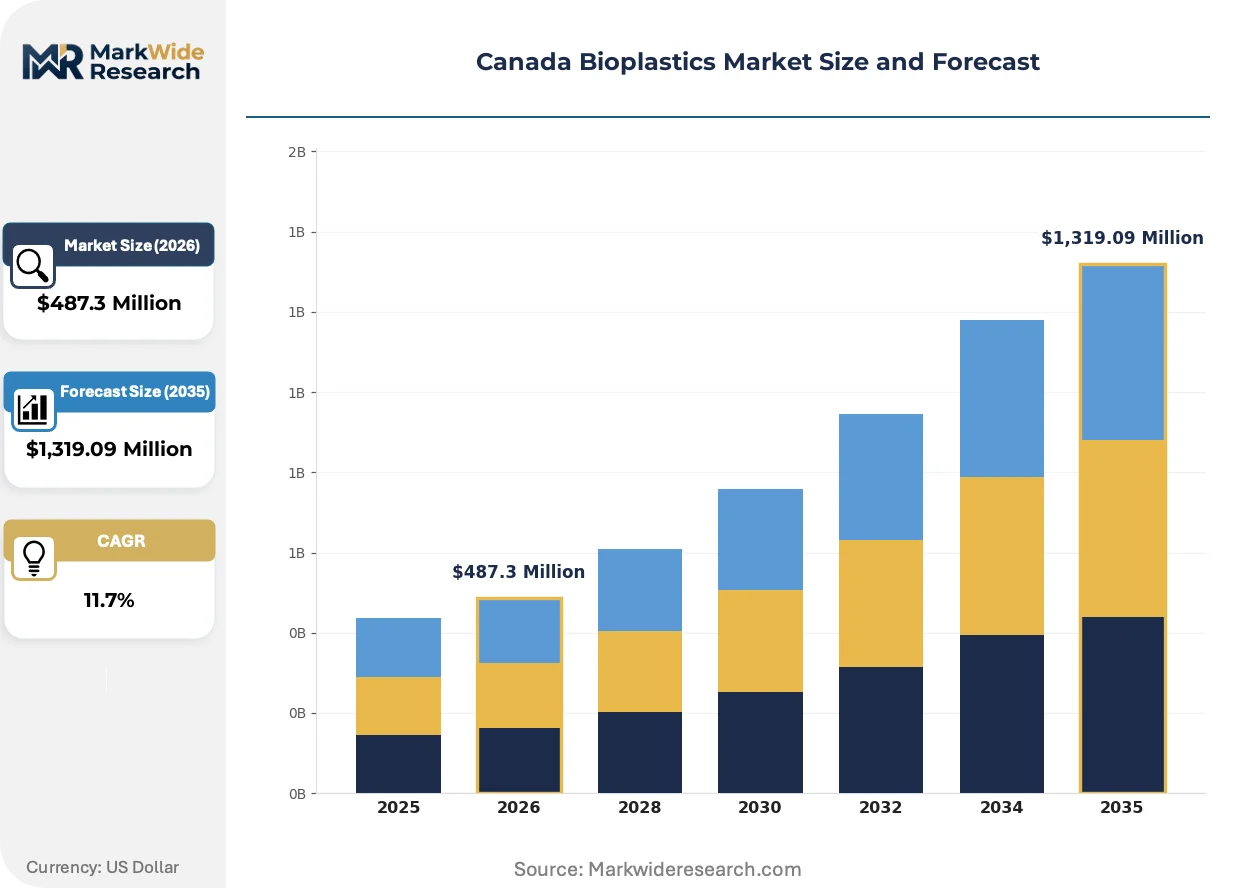
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,319.09 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyhydroxyalkanoates, Starch-based Bioplastics, Polylactic Acid, Cellulose-based Bioplastics End Use Industry: Packaging, Agriculture, Consumer Goods, Automotive Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Direct Sales Application: Food Packaging, Disposable Cutlery, Mulch Film, Medical Supplies |
| Companies Covered | Biome Bioplastics Inc, BASF SE, Novamont SpA, Braskem, TERRAVERDAE BIOWORKS INC, BOSK Bioproducts Inc, NatureWorks LLC, Arkema, Total Corbion PLA, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Bioplastics Market Trends and Innovations
Active fermentation pathway development and regulatory compliance acceleration are reconfiguring how Canadian compounders source, formulate, and certify bio-based alternatives to conventional polymers.
Polyhydroxyalkanoate production technology is migrating from pilot-scale batch fermentation to continuous processing architectures. Alberta-based microbial strain developers are adopting cell-recycle systems that lift PHA titers above seventy grams per liter. This concentration threshold is enabling compounders to displace petroleum-derived polypropylene in durable goods applications previously closed to bioplastics.
Environment and Climate Change Canada's federal plastic registry rules are forcing supply chain documentation upgrades. Converters must now trace polymer origin through to post-consumer recovery verification. Food packaging segments face the steepest compliance burden, with multi-layer laminate structures requiring disassembly protocols that exceed current sorting infrastructure capabilities.
Buyers in Ontario's retail corridor are consolidating supplier relationships around vertically integrated resin-to-converter partnerships. Single-source accountability for certification, performance, and end-of-life claims is displacing fragmented multi-vendor procurement. This concentration is most visible in quick-service restaurant supply chains, where national franchise operators demand unified compostable cutlery and foodservice ware specifications.
Canada Bioplastics Market Segmentation
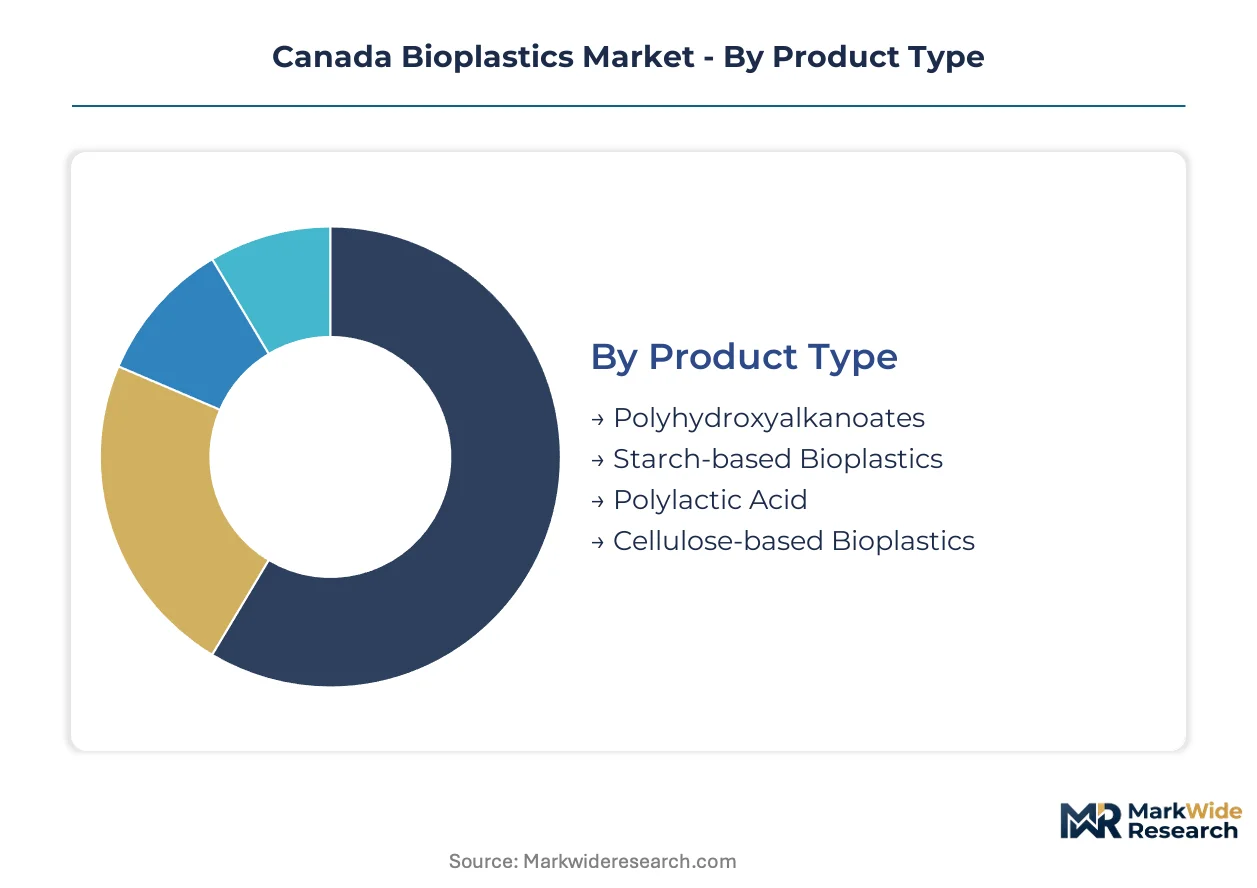
Segmentation reveals how Health Canada's regulatory timelines and provincial waste policies concentrate demand across distinct material grades and converting corridors. Understanding these splits exposes where compounders must prioritize certification investments versus capacity expansion.
Product Type:
After-sales technical support intensity varies sharply across resin categories, with fermentation-derived materials demanding sustained strain optimization assistance while commodity biopolymers require less intensive compounder engagement.
- Polylactic Acid:Derived from corn starch through ring-opening polymerization, PLA offers crystallinity tunable for thermoforming applications. Demand concentrates in Ontario's retail packaging corridor where grocery chains mandate certified compostable cold-drink cups and deli trays. Health Canada's food-contact compliance requirements favor established PLA suppliers with documented migration testing.
- Starch-based Bioplastics:Thermoplastic starch compounds blended with biodegradable polyesters create cost-competitive formulations for single-use applications. Prairie province agricultural operations drive procurement for biodegradable mulch films under Canadian Food Inspection Agency field protocols. Price positioning enables aggressive substitution in disposable cutlery where performance tolerances accommodate lower mechanical strength.
- Polyhydroxyalkanoates:Microbial fermentation of agricultural waste streams yields fully bio-based polyesters with polypropylene-comparable properties. Alberta pilot facilities are scaling continuous processing to serve durable goods applications.
- Cellulose-based Bioplastics:Regenerated cellulose and cellulose esters deliver premium barrier performance for oxygen-sensitive packaging. Medical device sterilization applications in Quebec and Ontario favor this grade for compliance with stringent Health Canada sterility standards.
Polylactic Acid holds the largest share; momentum sits with Polyhydroxyalkanoates as fermentation titers climb above commercial viability thresholds.
End Use Industry:
Cost tier stratification separates premium-certified food-contact applications from commodity agricultural films where price per hectare dominates procurement decisions.
- Packaging:Food packaging trays, flexible films, and rigid containers constitute the volume anchor. Ontario and Quebec converting corridors process PLA and starch-based resins for quick-service restaurant chains and grocery private labels. Extended producer responsibility frameworks in British Columbia mandate post-consumer recovery quotas that favor certified compostable materials.
- Agriculture:Biodegradable mulch films, plant pots, and twine applications serve Prairie province row-crop operations. Canadian Food Inspection Agency field biodegradability protocols are opening substitution pathways previously blocked by conventional polyethylene dominance.
- Consumer Goods:Disposable cutlery, shopping bags, and personal care packaging face compressed substitution timelines under federal single-use plastics prohibitions.
- Automotive:Interior trim and under-hood applications represent nascent demand as OEMs explore bio-based alternatives for corporate sustainability targets.
Packaging commands the dominant revenue position; Agriculture is gaining share fastest as field biodegradability certification accelerates Prairie adoption.
Distribution Channel:
Volume concentration favors direct resin supply relationships for large compounders, while fragmented converters rely on specialty distributors for technical formulation support and smaller lot sizes.
- Direct Sales:Vertically integrated resin suppliers serve major Ontario packaging converters through dedicated account management. NatureWorks LLC leverages Blair, Nebraska proximity to supply PLA resin directly into the province's thermoforming corridor.
- Specialty Stores:Regional compounders source tailored masterbatch formulations and technical troubleshooting through distributors with fermentation-derived resin expertise.
- Supermarkets:Limited penetration; primarily serves consumer-facing bioplastic products rather than industrial resin procurement.
- Online Retail:Niche channel for small-batch researchers and prototype developers testing novel formulations.
Direct Sales captures the largest volume; Specialty Stores are expanding most quickly as mid-tier compounders seek formulation flexibility without minimum order commitments.
Application:
Application maturity separates established thermoforming infrastructure for cold-fill packaging from emerging segments requiring new certification protocols and processing equipment.
- Food Packaging:Trays, cups, films, and containers for cold and ambient-temperature applications dominate current volume. PLA's fifty-five degree Celsius heat ceiling restricts hot-fill adoption, leaving polypropylene entrenched in microwaveable segments. Retail procurement mandates from major Canadian grocery chains cascade through Ontario's converting corridor.
- Mulch Film:Starch-based formulations serve Prairie province vegetable and row-crop operations where field biodegradability eliminates retrieval labor costs. Canadian Food Inspection Agency protocols validate soil residue claims.
- Disposable Cutlery:Forks, knives, and spoons face immediate substitution pressure under federal single-use plastics bans. Price competition between PLA and starch-based formulations intensifies as procurement volumes scale.
- Medical Supplies:Sterile barrier packaging and disposable devices favor cellulose-based biopolymers for oxygen transmission rate performance. Health Canada device regulations impose stringent documentation requirements that favor established suppliers.
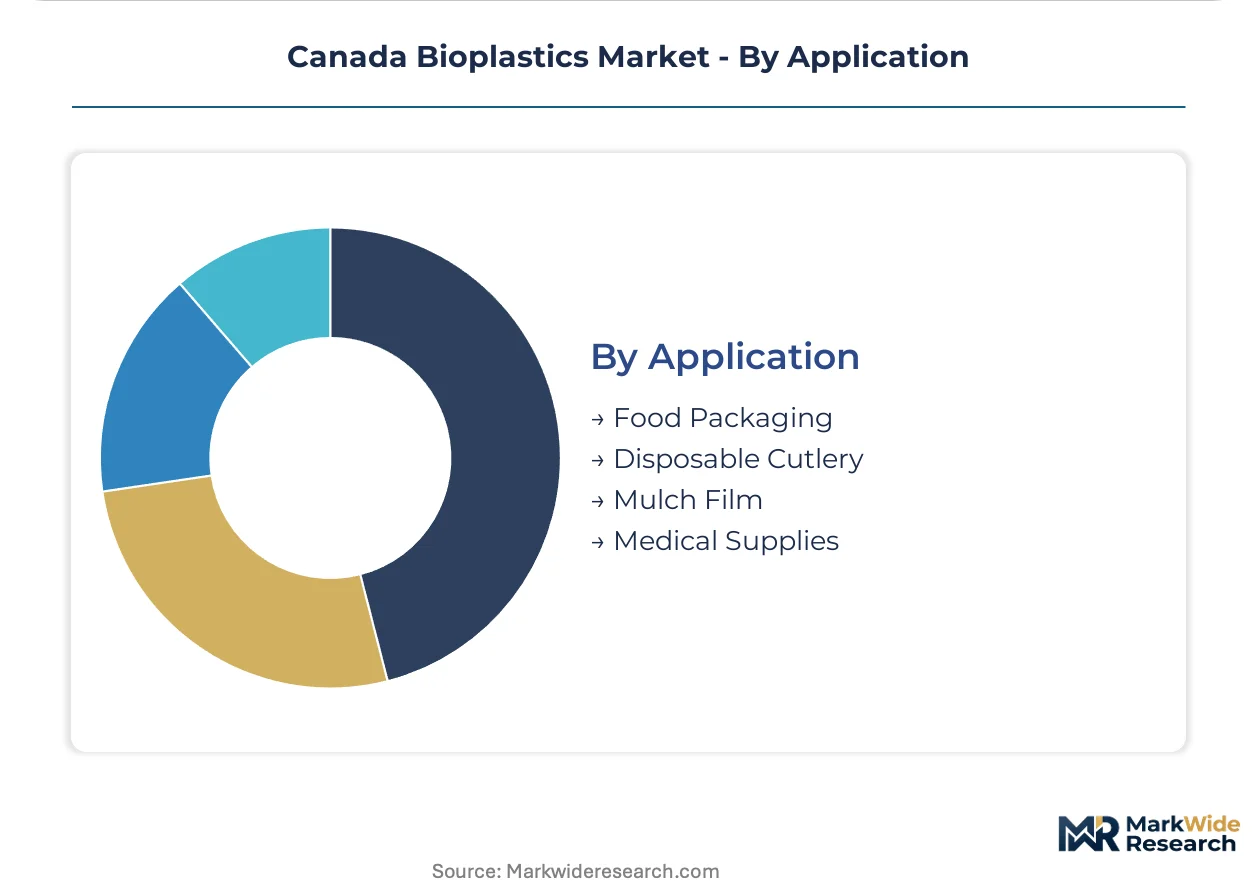
Food Packaging holds the largest share; Mulch Film is climbing the fastest as Prairie agricultural operations convert under regulatory and labor-cost pressure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
US Midwest feedstock corridors supply Ontario and Quebec converting clusters through cross-border resin flows, while Alberta fermentation pilots target Prairie province agricultural demand.
Ontario
Toronto-Windsor packaging corridor processes PLA resin into thermoformed food trays and cold-drink cups for major grocery chains. Extended producer responsibility regulations mandate post-consumer recovery quotas that favor certified compostable materials. Health Canada's food-contact compliance requirements concentrate technical service capabilities in Mississauga and Brampton compounder facilities.
Quebec
Montreal's converting infrastructure serves quick-service restaurant chains with disposable cutlery and foodservice ware under federal single-use plastics prohibitions. Provincial waste diversion policies create procurement pull for bio-based resins in flexible packaging applications. Laval and Longueuil host cellulose-based biopolymer specialists targeting medical device sterilization segments.
Alberta
Calgary-Edmonton corridor anchors microbial fermentation scale-up for PHA production from agricultural waste streams. Canadian Food Inspection Agency field biodegradability protocols open substitution pathways for Prairie province mulch film applications. Red Deer pilot facilities adopt continuous processing architectures to lift fermentation titers above commercial viability thresholds.
British Columbia
Vancouver packaging converters face compressed substitution timelines under provincial extended producer responsibility frameworks. Industrial composting infrastructure gaps in the Lower Mainland create end-of-life performance gaps between certification and actual diversion rates. Kelowna and Victoria serve as testbeds for retail procurement mandates cascading through regional grocery networks.
Atlantic Canada
Nova Scotia and New Brunswick lack established bioplastic converting infrastructure, creating first-mover positioning for regional compounders. Halifax food processing clusters generate latent demand for compostable packaging that outstrips local supply capacity. Provincial waste policies lag Ontario and Quebec, delaying procurement pull for bio-based resins.
Canada Bioplastics Market Competitive Landscape
Channel-controlling players compete with product-specialist players across resin supply, compounder formulation, and converter fabrication tiers. Vertically integrated suppliers with captive fermentation capacity command pricing leverage over distributed compounders sourcing commoditized PLA pellets. Three archetypes dominate: multinational chemical conglomerates with certified compostable portfolios, regional fermentation startups with agricultural waste feedstock integration, and specialty compounders with Health Canada food-contact documentation expertise. Capacity expansion and strategic partnerships constitute the dominant competitive moves, with Alberta-based pilots seeking offtake agreements and Ontario converters consolidating supplier relationships.
Within the multinational chemical tier, BASF SE and NatureWorks LLC anchor positions through established supply relationships into Ontario's converting corridor. Among fermentation specialists, TERRAVERDAE BIOWORKS INC exemplifies the agricultural waste-to-resin archetype at its Alberta pilot facility. These three entities represent distinct strategic positions: petrochemical-incumbent adaptation, incumbent biopolymer scale, and novel microbial strain development.
| Leading Market Players |
|---|
| Biome Bioplastics Inc |
| BASF SE |
| Novamont SpA |
| Braskem |
| TERRAVERDAE BIOWORKS INC |
| BOSK Bioproducts Inc |
| NatureWorks LLC |
| Arkema |
| Total Corbion PLA |
| Others |
Pricing and Supply Chain Analysis
The Great Lakes freight corridor moves PLA resin from Nebraska processing facilities into Ontario's converting corridor, with cross-border logistics costs creating tiered pricing structures that separate volume buyers from regional compounders sourcing smaller lots through specialty distributors.
Pricing Analysis
Fermentation-grade PHA pricing sits at a premium to mature PLA grades, while next-generation continuous-processing PHA targets cost parity with polypropylene. Three-tier pricing structure across premium, standard, and economy levels separates medical-grade cellulose formulations from commodity starch-based compounds. Cost compression in disposable cutlery is intensifying because federal single-use plastics prohibitions are forcing rapid procurement scaling. Agricultural mulch film buyers exhibit highest price sensitivity, while medical device manufacturers absorb premium pricing for oxygen barrier performance.
Supply Chain Analysis
Contract manufacturing for bioplastic compounding concentrates in Ontario and Quebec, with Mississauga and Brampton facilities handling food-contact formulation. Raw material sourcing draws from US Midwest corn starch belts, Brazilian sugarcane regions, and Alberta agricultural waste streams. Single-source vulnerability in industrial composting certification creates bottleneck risk for converters seeking rapid product qualification. Distribution runs through direct resin supply relationships for major compounders, with specialty distributors serving mid-tier buyers requiring technical formulation support.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Canada's bioplastics sector sits in early-cycle expansion as Health Canada's single-use plastics prohibitions compress substitution timelines and force supply chain reconfiguration ahead of infrastructure maturity.
For Market Incumbents: Insulate market position through backward integration into fermentation capacity and captive supply of agricultural waste feedstocks. BASF SE and NatureWorks LLC should expand Health Canada food-contact documentation depth to defend against emerging PHA specialists. Priority investment in industrial composting certification partnerships addresses end-of-life performance gaps threatening brand equity. For New Entrants and Emerging Players: Build out regional compounding presence in Atlantic Canada where Nova Scotia and New Brunswick lack established infrastructure. Maritime food processing clusters generate latent demand exceeding local supply capacity. Target Prairie province agricultural operations with starch-based mulch film formulations certified under Canadian Food Inspection Agency field protocols. For Investors and Strategic Acquirers: Health Canada's federal plastic registry rules reshape the acquisition landscape by privileging vertically integrated suppliers with traceable supply chain documentation. Long-term viability hinges on fermentation scale-up economics and composting infrastructure buildout. Acquisition target archetype: Alberta-based microbial strain developers with continuous processing IP and offtake agreements in place. Watch for industrial composting facility permitting acceleration as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Fermentation Scale-Up | Continuous processing architectures at Alberta pilot facilities lift PHA titers above commercial viability thresholds. |
| Certification Investment | Biodegradable Products Institute and TÜV Austria industrial composting certifications validate end-of-life claims for retail procurement. |
| Feedstock Integration | Agricultural waste stream conversion eliminates petrochemical dependency and insulates against corn price volatility. |
| Regional Capacity Expansion | Atlantic Canada compounders capture first-mover positioning in underserved maritime food processing clusters. |
| Vertical Partnership | Resin-to-converter partnerships consolidate supplier relationships around single-source accountability for certification and performance. |
Research Methodology
Desk research of Health Canada regulatory filings, Environment and Climate Change Canada prohibition schedules, and provincial extended producer responsibility frameworks preceded structured interviews with bioplastic compounder technical directors, packaging converter procurement leads, retail sustainability officers, and industrial composting facility operators. Secondary validation drew from Canadian Food Inspection Agency field trial databases, customs trade data on resin imports, and SEC filings of multinational chemical suppliers. Bottom-up volume modeling across resin grades and converting corridors was triangulated against top-down market sizing from regulatory mandate timelines.
Assumptions held fixed include Health Canada's single-use plastics prohibition enforcement schedules and existing industrial composting facility acceptance rates for certified packaging. Variables stress-tested included fermentation titer improvement rates, Prairie province agricultural adoption curves for mulch film, and Atlantic Canada infrastructure buildout timing. Segmentation modeling spanned material chemistry, end-use application, and geographic converting corridor. CAGRs were derived from regression analysis of substitution elasticity against regulatory compliance deadlines, with cross-validation against resin capacity expansion announcements.
Stress conditions across fermentation scale-up economics, composting infrastructure deployment, and cross-border feedstock pricing were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory timeline adherence and certification throughput capacity. Quarterly review of industrial composting facility permitting data and retail procurement mandate rollouts is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bioplastics
US Bioplastics Market
Bioplastics
Cellulose Plastics Market
Bioplastics
Polylactic Acid (PLA) Straws Market
Bioplastics
Global Bio-Polylactic Acid (PLA) Market
Bioplastics
North America Polylactic Acid (PLA) Market
Bioplastics
Starch-Based Bioplastics Market
Bioplastics
Asia-Pacific Lactic Acid Market
Bioplastics
Asia-Pacific Bio Plasticizers Market
Bioplastics
Brazil Bioplastics Market
Bioplastics
Polyhydroxy Butyrate Market
Bioplastics
Bio-Polyamide, Specialty Polyamide and Precursors Market
Bioplastics
Global Bio-Based PET Market
Bioplastics
North America Bioplastics Market
Bioplastics
Biopolymers Market
Bioplastics
China Bioplastics Market
Bioplastics
Southeast Asia Bioplastics Market