
 Polyhydroxyalkanoate (PHA) Market | 2026-2036
Polyhydroxyalkanoate (PHA) Market Size, Share, and Industry Trends Forecast 2026-2036
Polyhydroxyalkanoate (PHA) Market Analysis
Brand owners in food packaging and consumer goods are reorganizing procurement priorities around certified compostable materials, shifting volume away from conventional converters. Danimer Scientific leverages microbial fermentation platforms to anchor supply for flexible film applications. Kaneka Corporation sustains polymer blending expertise that differentiates its position in medical-grade PHA formulations. Tianjin GreenBio Materials Co., Ltd. dominates granular resin output for Asian processors seeking drop-in biopolymer feedstock.
Polyhydroxyalkanoates comprise linear polyesters biosynthesized by bacterial fermentation of sugars or lipids, accumulating as intracellular carbon reserves with thermoplastic properties comparable to polypropylene. Industrial deployment targets applications where biodegradation in marine, soil, or composting environments delivers functional value beyond mechanical performance. Granules and films command the dominant share of current output, with films capturing accelerating interest from fresh-food packaging designers seeking oxygen barrier compatibility. Medical devices represent a concentrated margin pool where PHA biocompatibility justifies premium positioning against conventional resins.
The EU Green Deal and REACH frameworks restrict persistent microplastics in consumer applications, directly expanding addressable demand for certified biodegradable alternatives. FDA and EMA pathways for implantable and drug-delivery devices establish compliance benchmarks that filter market access for medical-grade suppliers. Stakeholders must monitor fermentation yield improvements and downstream compounding partnerships, as cost-competitive scale rather than laboratory performance will determine which production platforms secure long-term offtake commitments.
Market Dynamics
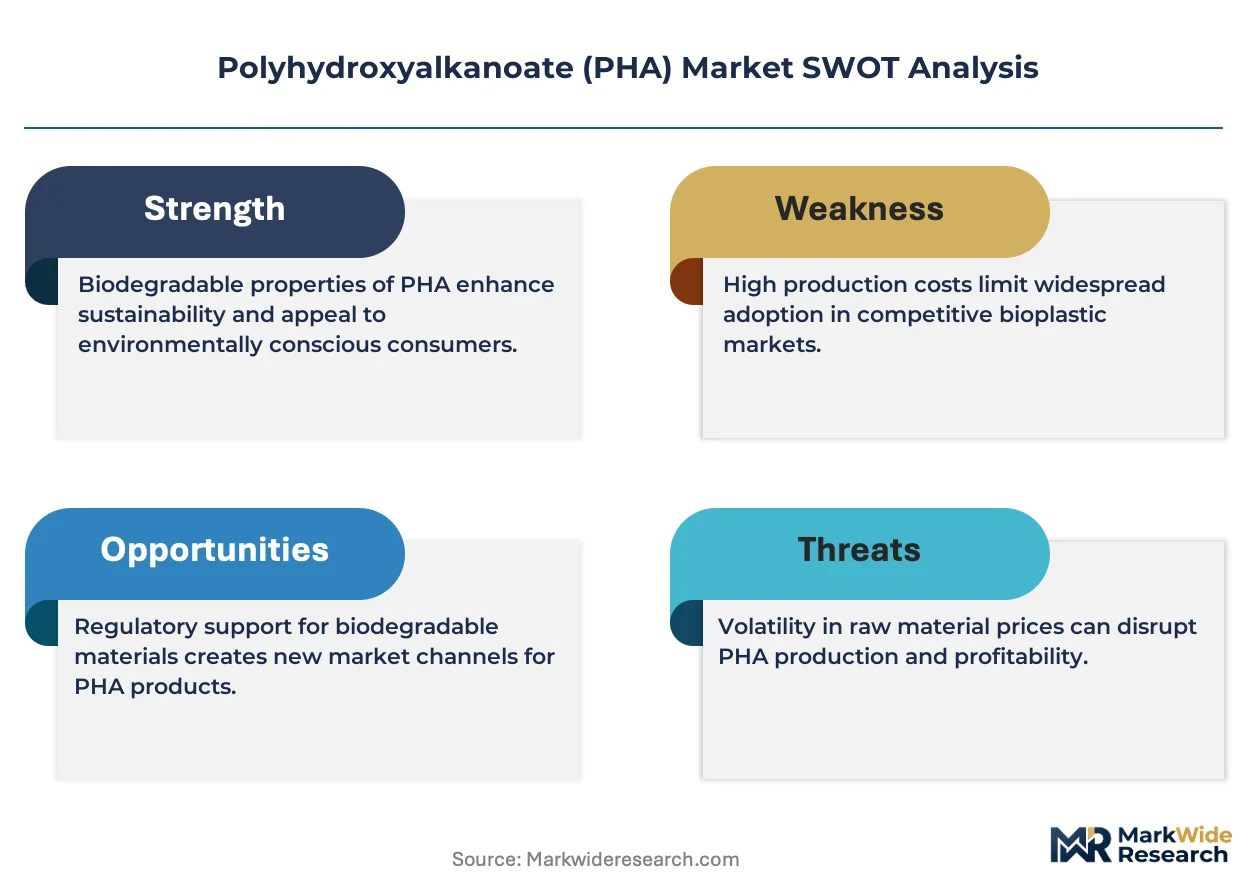
Fermentation yield economics and EU regulatory mandates on single-use plastics are compressing the commercialization timeline for bacterial polyesters, forcing capital allocation toward integrated biopolymer processing rather than standalone resin production.
Growth Catalysts
- EU Green Deal plastics strategy:Mandatory substitution timelines for petroleum-based packaging in member states are creating guaranteed offtake channels for certified compostable materials.
- Marine biodegradation certification:Fresh-food packaging designers are specifying oxygen-barrier films that decompose in ocean environments where mechanical recycling infrastructure is absent.
- German industrial biopolymer clusters:Concentrated processing capacity around Leipzig and Hamburg is reducing logistics costs for compounders serving Central European brand owners.
Market Restraints
- Sugar feedstock price volatility:Corn and cane sugar markets transmit agricultural commodity swings directly into PHA production economics, compressing margin predictability for fermentation operators.
- Asian resin supply concentration:Granular feedstock production clusters heavily around Tianjin and Singapore, creating single-source risk for European compounders lacking backward integration.
- Thermal processing limitations:Narrow melt-temperature windows relative to polypropylene restrict high-speed conversion on legacy extrusion equipment without capital retooling.
Strategic Opportunities
- US medical device pathways:FDA implantable-grade certification for drug-delivery applications commands pricing multiples unavailable in commodity packaging segments.
- Soil-biodegradable agricultural films:Mulch and silage wrap applications in France and Italy are opening volume channels where residue persistence currently triggers regulatory penalties.
- PHA-PLA blending convergence:Hybrid formulations combining bacterial polyesters with polylactic acid are unlocking thermomechanical property sets neither achieves independently.
Industry Challenges
- Fermentation scale-up talent scarcity:Industrial microbiologists with commercial bioprocess experience command premium compensation, constraining production expansion timelines for new market entrants.
- Composting infrastructure certification lag:Industrial composting facility validation for home-compostable claims varies across municipalities, delaying market access for consumer goods launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polyhydroxyalkanoate (PHA) Market |
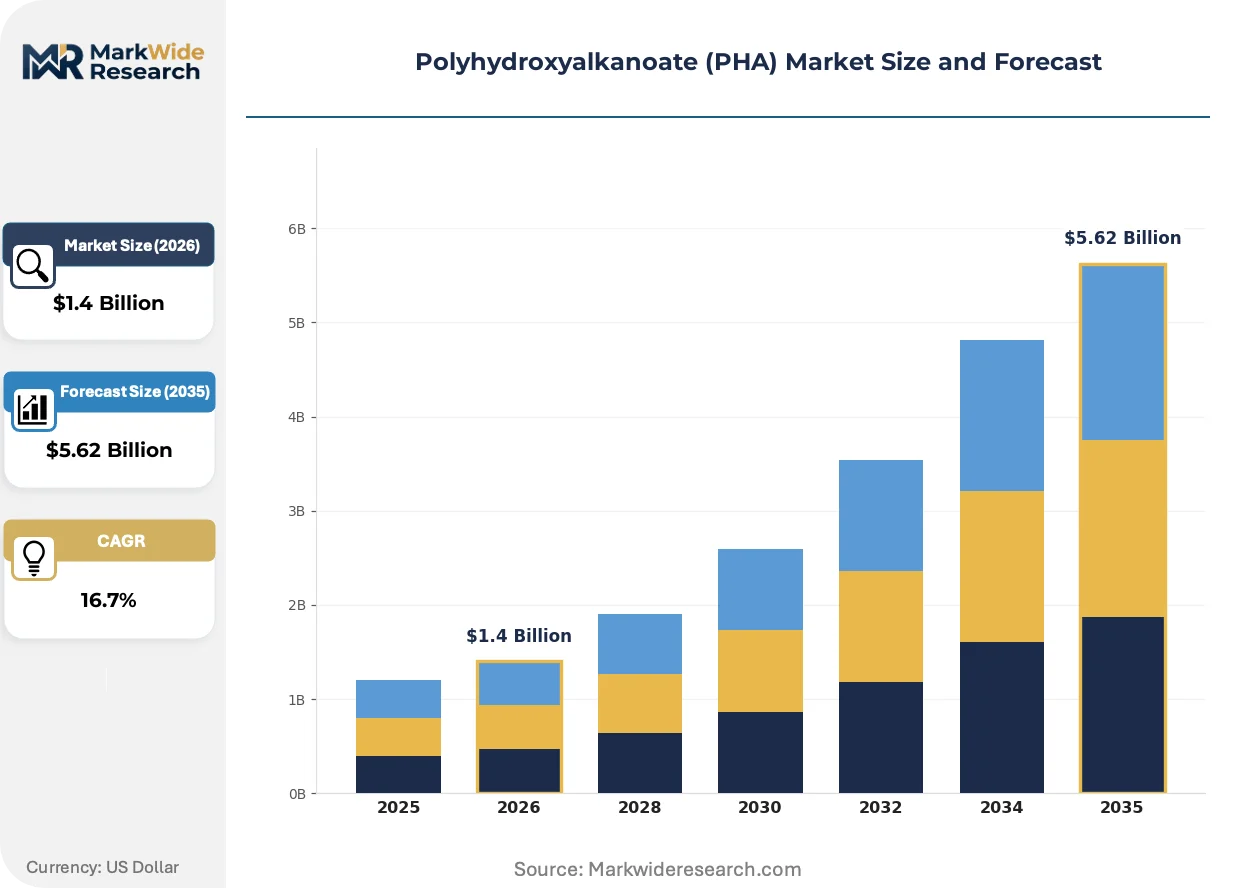
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $5.62 Billion |
| CAGR (2026 – 2036) | 16.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granules, Sheets, Films, Coatings Application: Biodegradable Plastics, Medical Devices, Packaging, Agriculture End User: Pharmaceuticals, Food Industry, Consumer Goods, Automotive Technology: Fermentation, Chemical Synthesis, Bioprocessing, Polymer Blending |
| Companies Covered | RWDC Industries, Ecomann Biotechnology Co., Ltd., Teknor Apex, Tianjin GreenBio Materials Co., Ltd., Newlight Technologies, Inc., Kaneka Corporation, Bluepha Co., Ltd., TerraVerdae Bioworks Inc., Danimer Scientific, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polyhydroxyalkanoate (PHA) Market Emerging Trajectories
Continuous fermentation systems and downstream purification advances are collapsing unit economics for bacterial polyesters, enabling price parity arguments against conventional plastics in select packaging categories.
Halophilic bacterial strains operating in saline environments are supplanting conventional freshwater fermentation platforms, cutting sterilization energy and contamination risk. Food packaging converters in the Netherlands and Denmark are piloting these systems for flexible film supply contracts. The technology is compressing capital intensity thresholds for viable production scale, opening entry paths for mid-size bioprocess operators previously excluded by freshwater infrastructure requirements.
REACH microplastic restriction amendments are forcing cosmetic and agricultural formulation houses to eliminate persistent polymer additives. Industrial consequence includes accelerated R&D allocation toward PHA-based encapsulation and controlled-release matrices. Personal care applications in Germany and France are responding fastest, with brand owners demanding supply-chain documentation proving marine biodegradability within 24-month windows.
Brand-owner direct contracting with fermentation operators is fragmenting traditional distributor channels for biopolymer resins. Packaging procurement teams at major retail chains are negotiating volume commitments that bypass regional compounders, securing price stability through multi-year offtake structures. This pattern is most visible in Scandinavian markets where centralized retail concentration enables consolidated sourcing negotiations.
Polyhydroxyalkanoate (PHA) Market Segmentation
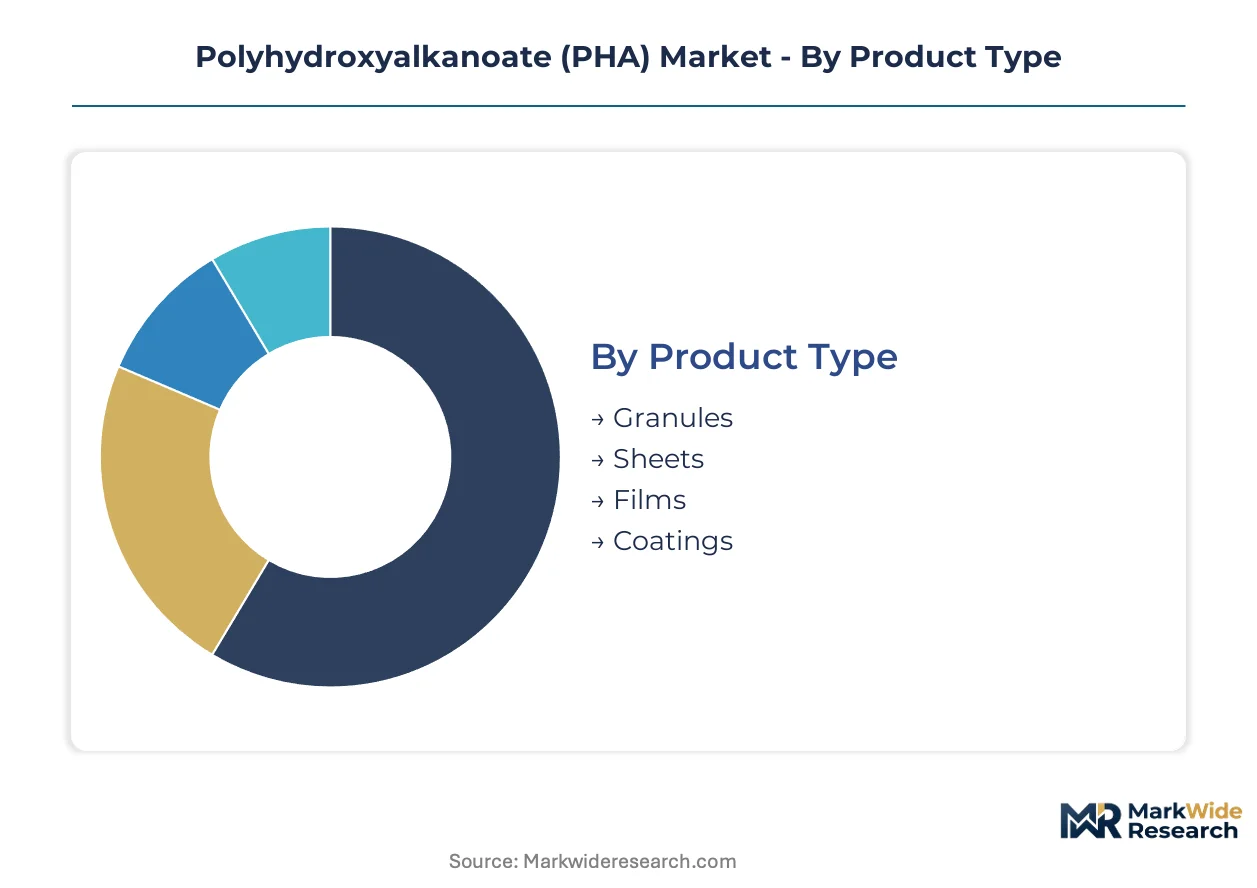
PHA market segmentation reveals where bacterial polyesters displace incumbent materials versus where they compete against other biopolymers. Substitution pressure varies sharply across product formats and end-use specifications, dictating pricing power and capital allocation priorities for fermentation operators.
Product Type:
Granules face the most intense substitution threat from PLA and starch-based resins in commodity packaging, while films command defensive positioning through marine biodegradation certifications that alternatives cannot match.
- Granules:Pelletized resin serves as drop-in feedstock for conventional extrusion and injection molding equipment. German compounders around Leipzig and Hamburg dominate European offtake, though Asian supply concentration around Tianjin creates price volatility that squeezes margin predictability for processors lacking long-term contracts.
- Films:Flexible sheet structures engineered for oxygen barrier performance in fresh-food packaging. Dutch and Danish converters are specifying marine-biodegradable certifications where mechanical recycling infrastructure is absent, creating pricing premiums unavailable to land-compostable alternatives.
- Sheets:Rigid thermoformed substrates for disposable food service applications.
- Coatings:Thin-film barrier layers applied to paper and fiber-based packaging structures.
Granules retain volume leadership; films hold the steepest expansion curve.
Application:
Cost tier stratification separates commodity segments where scale determines survival from specialty niches where regulatory compliance commands pricing multiples.
- Packaging:Flexible films and rigid containers for food and consumer goods. EU Green Deal mandates on single-use plastics are creating guaranteed offtake channels in Germany and France, though sugar feedstock volatility compresses margin predictability for fermentation operators without backward integration into agricultural supply.
- Medical Devices:Implantable scaffolds, drug-delivery matrices, and surgical fixtures where biocompatibility justifies premium positioning. FDA and EMA certification pathways filter market access, creating concentrated margin pools unavailable in commodity segments.
- Biodegradable Plastics:General-purpose disposables and cutlery applications competing directly with PLA and starch blends.
- Agriculture:Mulch films and silage wrap where soil biodegradability eliminates residue penalties under French and Italian regulations.
Packaging captures the dominant revenue share; medical devices deliver the highest margin per kilogram.
End User:
Customer type determines procurement sophistication, with pharmaceutical buyers demanding batch documentation and food industry purchasers prioritizing price stability through multi-year offtake structures.
- Food Industry:Brand owners and retail chains reorganizing procurement around certified compostable materials. Scandinavian retail concentration enables direct contracting with fermentation operators, fragmenting traditional distributor channels and securing volume commitments that bypass regional compounders.
- Pharmaceuticals:Drug-delivery and implantable device manufacturers requiring FDA and EMA compliance documentation. The segment commands pricing multiples three to five times commodity packaging grades, though validation timelines extend commercialization cycles.
- Consumer Goods:Personal care and household product houses responding to REACH microplastic restrictions.
- Automotive:Interior trim and under-hood applications where biodegradability offers limited functional value.
Food industry offtake dominates volume; pharmaceuticals generate the highest value per ton.
Technology:
Supply concentration in fermentation platforms creates entry barriers for alternative production routes, while polymer blending expertise differentiates compounder positioning.
- Fermentation:Bacterial cultivation of sugars or lipids under controlled conditions. Halophilic strains operating in saline environments are supplanting freshwater platforms in Dutch and Danish pilots, cutting sterilization energy and contamination risk while compressing capital intensity thresholds for mid-size operators.
- Polymer Blending:Compounding PHA with PLA or other biopolymers to unlock thermomechanical property sets neither achieves independently. Japanese and German compounders sustain technical leadership in medical-grade formulations.
- Bioprocessing:Downstream purification and recovery of intracellular polymer reserves.
- Chemical Synthesis:Laboratory-scale routes lacking commercial viability against biological production.
Fermentation anchors production scale; polymer blending commands formulation value capture.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's biopolymer cargo terminals anchor European PHA import flows, connecting Asian fermentation output to German compounding clusters via Rhine barge networks.
Germany
Leipzig and Hamburg industrial biopolymer clusters concentrate European compounding capacity, serving food packaging brand owners with certified compostable films. The EU Green Deal's single-use plastics directive mandates substitution timelines that guarantee offtake channels for fermentation operators. Bavarian processors are expanding oxygen-barrier film production for fresh-food applications.
United States
FDA implantable-grade certification pathways attract capital toward medical device applications commanding premium pricing multiples. The EPA's emerging frameworks on marine biodegradable materials are reshaping procurement specifications for coastal state packaging converters. Georgia-based flexible film processors are piloting halophilic fermentation feedstock for retail chain supply contracts.
China
Tianjin's granular resin production clusters dominate Asian feedstock output, supplying drop-in biopolymer pellets to processors across East Asia. The country's dual carbon goals are accelerating capital allocation toward bacterial polyester fermentation platforms. Zhejiang province converters are expanding PHA-PLA blending capacity for export-oriented packaging manufacturers.
Netherlands
Rotterdam-Amsterdam logistics corridors enable just-in-time resin delivery to compounders serving Scandinavian retail procurement teams. Dutch pilot programs for saline-environment fermentation are cutting sterilization energy requirements for mid-size bioprocess operators. Eindhoven region technical universities are anchoring R&D partnerships with packaging designers seeking marine biodegradation certification.
France
Soil-biodegradable agricultural film demand concentrates in French mulch and silage wrap applications where residue persistence triggers regulatory penalties under national waste codes. ANSM oversight of implantable materials creates compliance benchmarks for medical-grade suppliers. Lyon-based formulation houses are responding to REACH microplastic restrictions with PHA-based encapsulation matrices for personal care applications.
Polyhydroxyalkanoate (PHA) Market Vendor Landscape
Concentration sits with fermentation specialists operating integrated biopolymer processing platforms rather than standalone resin producers. The vendor base spans three discernible tiers: multinational chemical conglomerates with polymer blending expertise, venture-backed bioprocess pure-plays scaling saline-environment fermentation, and regional compounders serving localized packaging converters. Dominant competitive moves include backward integration into agricultural feedstock supply and strategic partnerships with retail brand owners for multi-year offtake commitments.
Within the fermentation specialist tier, Danimer Scientific and Tianjin GreenBio Materials Co., Ltd. exemplify scale-driven platform operators, while Kaneka Corporation occupies a position representing polymer blending technical leadership. RWDC Industries and Bluepha Co., Ltd. sit within the venture-backed pure-play archetype, and Newlight Technologies, Inc. anchors the carbon-capture fermentation segment. Ecomann Biotechnology Co., Ltd. represents Chinese bioprocess capability, with TerraVerdae Bioworks Inc. and Teknor Apex occupying positions in regional compounding and technical formulation respectively.
| Leading Market Players |
|---|
| RWDC Industries |
| Ecomann Biotechnology Co., Ltd. |
| Teknor Apex |
| Tianjin GreenBio Materials Co., Ltd. |
| Newlight Technologies, Inc. |
| Kaneka Corporation |
| Bluepha Co., Ltd. |
| TerraVerdae Bioworks Inc. |
| Danimer Scientific |
| Others |
Supply Flow & Price Mechanics
EU Green Deal plastics substitution mandates are redrawing PHA procurement geography while compressing pricing premiums for certified compostable resins. Brand-owner direct contracting with fermentation operators is fragmenting traditional distributor markups, forcing compounders to absorb logistics costs or surrender volume to integrated suppliers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates medical-grade FDA-certified resin from food-packaging compostable grades and commodity biodegradable blends. Premium tiers command multiples based on EMA implantable-device validation and batch documentation, while standard grades compete on sugar-feedstock cost efficiency. Pricing pressure stems from Tianjin granular resin oversupply transmitting Asian spot-market volatility into European compounder margins. Pharmaceutical buyers exhibit lowest price sensitivity due to regulatory compliance lock-in; food industry procurement teams drive hardest volume-discount negotiations through multi-year offtake structures.
Supply Chain Analysis
China and Germany anchor PHA production geography, with Tianjin fermentation clusters supplying drop-in granular feedstock and Leipzig-Hamburg compounding hubs serving Central European brand owners. Raw material dependencies center on corn and cane sugar agricultural commodities, halophilic bacterial strain IP, and oxygen-barrier film additive packages. Single-source vulnerability concentrates around Asian resin supply, exposing European processors to shipping chokepoint risk at Rotterdam biopolymer terminals. Distribution runs through Rhine barge networks connecting port terminals to German industrial clusters, with Scandinavian retail chains increasingly bypassing regional compounders for direct fermentation-operator contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating around Scandinavian retail procurement teams and German food-packaging brand owners, fragmenting traditional distributor channels and forcing supply-chain restructuring among fermentation operators.
For Market Incumbents: Fortify position through backward integration into agricultural sugar supply and captive halophilic fermentation capacity in saline-environment platforms. PLA-PHA blending convergence threatens technical differentiation; defend through polymer compounding IP accumulation and EMA medical-grade certification depth. Channel control via direct retail chain offtake agreements anchors volume stability against distributor disintermediation. For New Entrants and Emerging Players: Differentiate on marine biodegradation certification for flexible film applications where Dutch and Danish converters face specification gaps. Soil-biodegradable agricultural films in France and Italy offer penetrable white space with regulatory tailwinds from residue-penalty frameworks. Go-to-market through Eindhoven technical university partnerships accelerates R&D credibility with packaging designers. For Investors and Strategic Acquirers: The market sits at a scale-up phase that favors integrated biopolymer processors over standalone resin producers. Long-term viability hinges on fermentation yield economics and downstream compounding partnerships rather than laboratory performance alone. Acquisition target archetype: mid-size operators with saline-environment fermentation platforms and established brand-owner offtake structures. Signal to watch: FDA implantable-grade certification timelines for drug-delivery applications as margin-pool inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sugar Feedstock | Corn and cane sugar supply control insulates margin predictability from agricultural commodity swings. |
| Saline-Environment Fermentation Scale-Up | Halophilic bacterial platforms cut sterilization energy and open mid-size operator entry paths in Netherlands pilots. |
| Marine Biodegradation Certification Investment | Ocean-decomposition validation unlocks pricing premiums unavailable to land-compostable alternatives in fresh-food packaging. |
| Direct Retail Chain Offtake Agreements | Scandinavian retail concentration enables volume commitments that bypass regional compounder markups. |
| PHA-PLA Blending Convergence R&D | Hybrid formulations unlock thermomechanical properties neither biopolymer achieves independently. |
Methodological Framework
The analysis maps fermentation platform economics, polymer blending formulation tiers, and end-use application specifications, each validated through fermentation plant managers, food industry procurement leads, medical device regulatory affairs directors, and biopolymer distribution channel partners. Primary interview insights triangulate against customs trade data, EU Green Deal directive filings, FDA 510(k) submission databases, and ACC biopolymer production surveys. Bottom-up capacity modeling and top-down demand segmentation converge through iterative stakeholder cross-checking.
Consistency checks validated volume and value outputs against external benchmarks including ECHA REACH microplastic restriction impact assessments and industrial composting facility certification registries. The analytical framework segments by product format, application cost tier, end-user procurement sophistication, and fermentation technology platform across the projection horizon. CAGRs derive from sugar feedstock cost trajectory modeling, regulatory mandate implementation timelines, and substitution elasticity coefficients for petroleum-based packaging displacement.
Decision-makers should treat outputs as directional under sustained EU Green Deal enforcement and marine biodegradation certification standardization assumptions; material deviation in agricultural commodity volatility or composting infrastructure deployment would warrant model refresh. Recalibration cycles align with material shifts in fermentation yield improvements and downstream compounding partnership formations.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bioplastics
Biodegradable Plastics Market
Bioplastics
Global Synthetic and Bio Based Biodegradable Plastics Market
Bioplastics
Cellulose Bioplastic Market
Bioplastics
Bio-Based Polyolefins Market
Bioplastics
Compostable Phone Cases Market
Bioplastics
Bio-PET Market
Bioplastics
Biodegradable Microbeads Market
Bioplastics
Middle East Biodegradable Plastics Market
Bioplastics
North America Bioplastics Market
Bioplastics
Starch-Based Bioplastics Market
Bioplastics
Global Bioresorbable (Resorbable) Polymers Market
Bioplastics
Brazil Bioplastics Market
Bioplastics
Bioplastics and Biopolymers Market
Bioplastics
Bio-Polyamide, Specialty Polyamide and Precursors Market
Bioplastics
Global Bio-Plasticizers Market
Bioplastics
Bio-Based Succinic Acid Derivatives for Plasticizers Market