
 Bioplastics and Biopolymers Market | 2026-2036
Bioplastics and Biopolymers Market Size, Share, and Industry Trends Forecast 2026-2036
Bioplastics and Biopolymers Market Analysis
ASTM D6400 and EN 13432 certification cycles are reorganizing supplier eligibility, forcing resin producers to validate compostability through third-party labs before qualifying for food-contact applications. Braskem leverages its Brazilian sugarcane feedstock base to anchor global bio-PE output. NatureWorks LLC dominates North American PLA capacity with integrated corn-to-resin operations. BASF SE differentiates through specialty polyamide grades that navigate automotive thermal requirements.
Bioplastics and biopolymers comprise renewable-derived or biodegradable polymers engineered to replace conventional fossil-based plastics in targeted applications, with PLA requiring controlled industrial composting above 55°C to achieve full mineralization within 180 days. Their primary purpose centers on reducing petrochemical dependency while meeting end-of-life targets for packaging and durable goods. Starch blends occupy the volume-led tier in films and loose-fill due to cost proximity to conventional plastics, while PHA commands premium positioning in marine-degradable applications where anaerobic digestion compliance creates margin pools. Cellulose-based materials sustain niche strength in thermoformed trays and coatings where grease resistance and optical clarity prove decisive.
The EU Packaging and Packaging Waste Regulation and REACH chemical compliance frameworks are tightening recyclability and biodegradability thresholds, compelling reformulation of additive packages to maintain market access. The US FDA and EPA coordinate on food-contact notification pathways and microplastic discharge monitoring, shaping how biopolymer producers validate safety profiles. Stakeholders must monitor composting infrastructure buildout rates against resin capacity announcements to avoid feedstock-demand mismatches.
Market Dynamics
The EU Packaging and Packaging Waste Regulation is compressing compliance timelines for compostable materials, forcing resin producers to revalidate formulations through third-party certification labs before qualifying for food-contact applications across European supply chains.
Growth Catalysts
- REACH Chemical Compliance:The European framework mandates biodegradable thresholds that accelerate reformulation of additive packages, creating qualified demand for certified compostable resins in food packaging applications.
- Industrial Composting Infrastructure:Germany, Italy, and the Netherlands are expanding anaerobic digestion capacity, enabling PLA and PHA mineralization above 55°C within regulatory timelines.
- Automotive Thermal Requirements:Specialty polyamide grades engineered for under-hood applications are penetrating electric vehicle battery housings and thermal management systems.
Market Restraints
- Feedstock Cost Volatility:Corn and sugarcane prices fluctuate with agricultural commodity cycles, compressing margin stability for starch-based and bio-PE producers dependent on crop-derived sugars.
- Industrial Composting Access Gaps:Limited municipal composting facilities in mid-sized cities create end-of-life execution failures, undermining brand owner claims and consumer confidence.
- Mechanical Recycling Incompatibility:PLA contamination streams disrupt conventional PET recycling operations, triggering sorting facility rejections and downstream polymer degradation.
Strategic Opportunities
- Marine-Degradable Applications:PHA grades certified for anaerobic digestion compliance command premium positioning in fishing gear, aquaculture equipment, and coastal infrastructure where ocean plastic accumulation drives regulatory scrutiny.
- Cellulose-Based Thermoformed Trays:Grease-resistant coatings and optical clarity specifications in ready-meal packaging create margin pools distinct from commodity film competition.
- US FDA Food-Contact Pathways:Streamlined notification procedures for bio-based polymers reduce time-to-market for packaging innovators targeting CPG brand owner sustainability commitments.
Industry Challenges
- ASTM D6400 and EN 13432 Certification Cycles:Third-party lab validation timelines extend 12-18 months, delaying supplier qualification for time-sensitive procurement windows.
- Composting Infrastructure Buildout Coordination:Resin capacity announcements risk feedstock-demand mismatches where municipal collection and industrial processing scale lags polymer production expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bioplastics and Biopolymers Market |
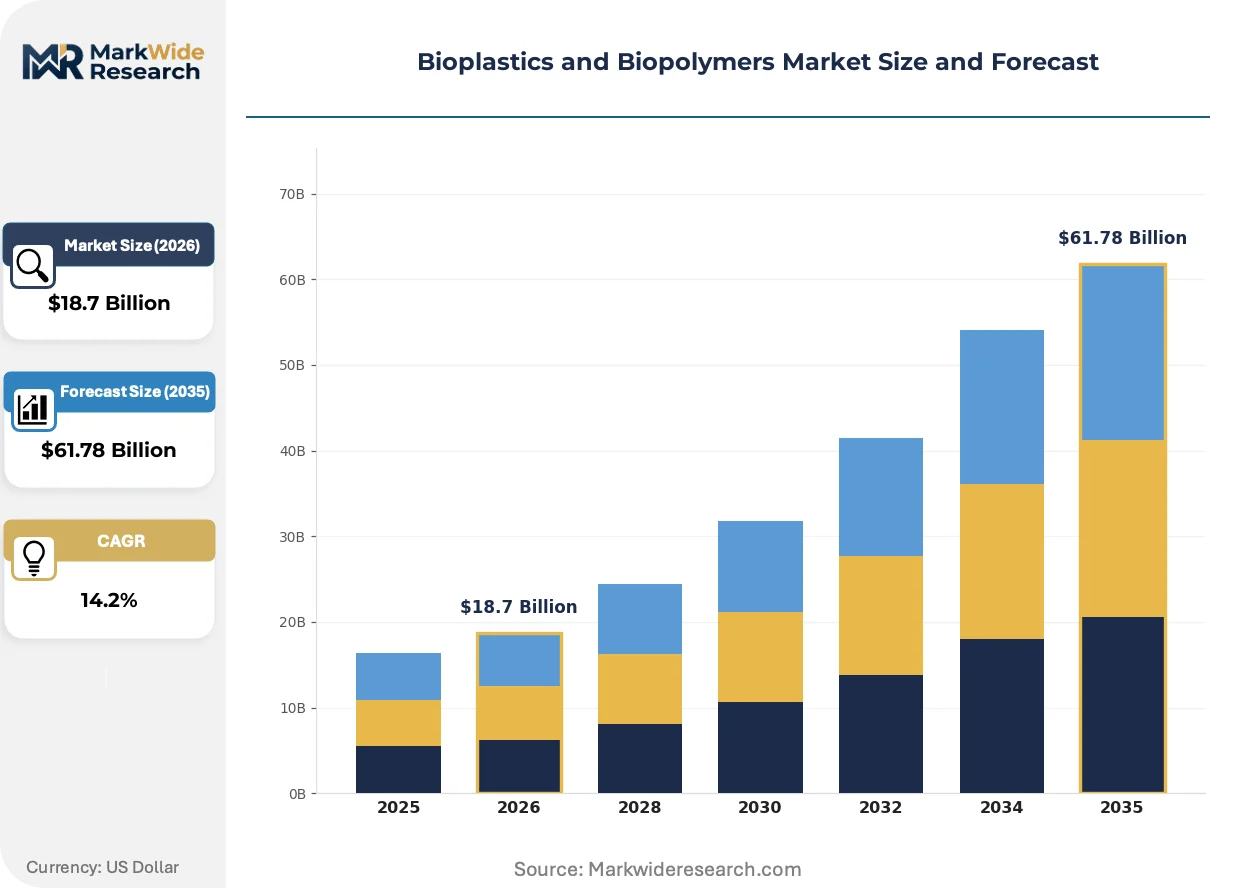
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $61.78 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PLA, PHA, Starch Blends, Cellulose End User: Packaging, Consumer Goods, Healthcare, Automotive Application: Films, Bottles, Bags, Coatings Distribution Channel: Direct Sales, E-commerce, Retail, Wholesale |
| Companies Covered | NatureWorks LLC, Braskem, BASF SE, TotalEnergies Corbion, Novamont, Biome Bioplastics Limited, Mitsubishi Chemical Group Corporation, Biotec Biologische Naturverpackungen GmbH & Co., Toray Industries, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bioplastics and Biopolymers Market Emerging Trajectories
Certification-driven material selection is restructuring supplier eligibility hierarchies, while thermal performance engineering and marine biodegradability open application-specific margin tiers beyond commodity substitution.
PHA fermentation technology is displacing conventional PLA in marine-degradable applications where anaerobic digestion compliance creates non-substitutable performance specifications. Fishing gear manufacturers and aquaculture operators in coastal regions are adopting PHA-based ropes and nets at accelerated procurement cycles. This displacement is compressing PLA's addressable market in saltwater-exposed end-uses while establishing PHA as the default standard for ocean plastic mitigation mandates.
REACH biodegradability thresholds are tightening additive package formulations across European supply chains, compelling resin producers to eliminate conventional plasticizers and stabilizers. The industrial consequence is a reformulation race where only third-party-certified compostable grades maintain market access. Food-contact film applications in Germany and Italy face the most acute compliance pressure, with brand owners accelerating supplier audits to preempt regulatory enforcement.
Certification-driven procurement preferences are consolidating buyer decision criteria around ASTM D6400 and EN 13432 validation marks, displacing price-first sourcing in premium packaging tiers. European retail chains and CPG brand owners are embedding compostability certification as a mandatory gate in supplier scorecards. This shift is most visible in the Netherlands and Germany, where private-label food packaging specifications now exclude non-certified biopolymer alternatives regardless of cost position.
Bioplastics and Biopolymers Market Segmentation
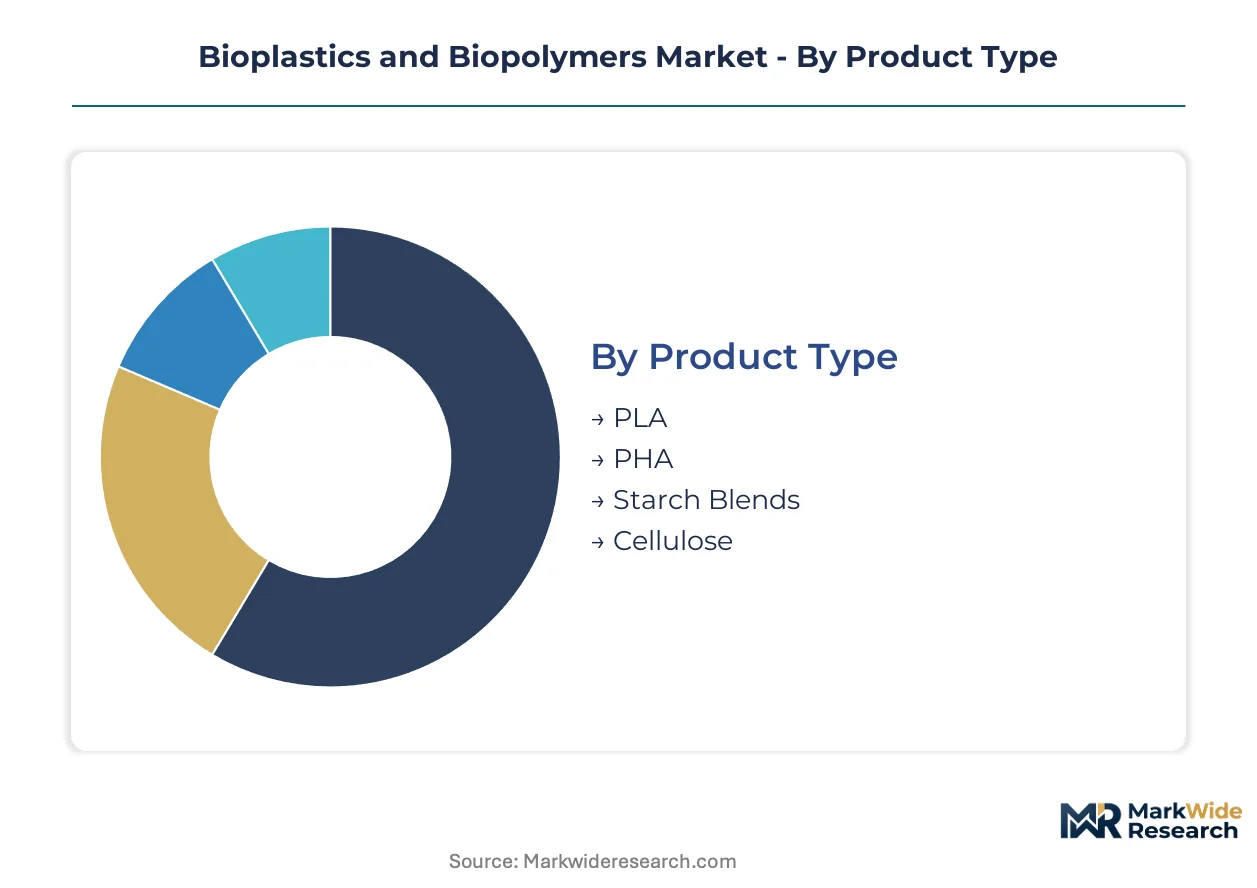
Bioplastics and biopolymers segmentation reveals divergent substitution pressures across material chemistries and end-use specifications. Product type stratification determines which grades face immediate displacement from conventional plastics versus those commanding defensible premium positioning.
Product Type:
Starch blends and PLA confront the most aggressive substitution pressure from fossil-based polyolefins on cost grounds, while PHA and cellulose derivatives occupy protected niches where biodegradability performance justifies structural premiums.
- PLA:Polylactic acid requires controlled industrial composting above 55°C for full mineralization within 180 days. German and Italian packaging converters dominate procurement as EU Packaging and Packaging Waste Regulation compliance tightens film specifications.
- PHA:Polyhydroxyalkanoates achieve anaerobic digestion compliance in marine environments without temperature thresholds. Fishing gear manufacturers in coastal Netherlands and aquaculture operators across Germany are accelerating rope and net procurement at premium pricing.
- Starch Blends:Thermoplastic starch formulations offer the narrowest cost gap to conventional plastics in loose-fill and agricultural mulch films.
- Cellulose:Regenerated cellulose and cellulose esters deliver grease resistance and optical clarity in thermoformed ready-meal trays.
Starch blends retain volume leadership; PHA holds the steepest expansion curve.
End User:
Packaging applications concentrate procurement volume, yet automotive and healthcare segments generate margin premiums through performance-grade specifications that resist commodity substitution.
- Packaging:Food-contact films and rigid containers absorb the majority of certified compostable resin output. REACH biodegradability thresholds are eliminating conventional plasticizers from European supply chains.
- Automotive:Specialty polyamide grades engineered for under-hood thermal management penetrate electric vehicle battery housings. BASF SE and compounders serving German OEMs dominate specification-setting.
- Consumer Goods:Disposable cutlery, tableware, and personal care packaging face acute price competition from conventional plastics.
- Healthcare:Sterilizable single-use devices and pharmaceutical packaging require US FDA food-contact notification pathways.
Packaging commands absolute volume; automotive delivers the highest margin expansion.
Application:
Film applications generate the most contested substitution dynamics, while coatings and bottles reward technical differentiation with pricing power.
- Films:Flexible packaging films for fresh produce and bakery goods face EN 13432 certification mandates across Netherlands retail chains. Brand owners are embedding compostability marks as mandatory supplier scorecard gates.
- Bottles:PLA beverage bottles confront mechanical recycling incompatibility with PET streams, triggering sorting facility rejections.
- Bags:Carrier and organic waste bags compete directly with conventional polyethylene on municipal procurement tenders.
- Coatings:Grease-resistant barriers for paperboard and molded pulp applications command optical clarity specifications.
Films absorb the greatest certification investment; coatings sustain the most defensible margin structure.
Distribution Channel:
Direct sales relationships dominate qualified resin procurement, while e-commerce and retail channels fragment price discovery for commodity grades.
- Direct Sales:Resin producers negotiate multi-year supply agreements with German and Italian compounders, locking in ASTM D6400 and EN 13432 validation documentation. Braskem and NatureWorks LLC anchor volume through captive relationships.
- Wholesale:Distributors aggregate spot demand from mid-sized converters lacking certification expertise.
- E-commerce:Small-batch specialty grades reach research institutions and startup packaging innovators.
- Retail:Branded consumer products reach end-users through supermarket private-label programs.
Direct sales capture specification value; wholesale channels expand geographic reach fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's biopolymer handling infrastructure anchors European supply chain integration for certified compostable resin imports. Germany's Rhine-Ruhr industrial corridor and Italy's Po Valley processing clusters depend on this maritime gateway for feedstock security.
Germany
Automotive thermal management specifications and food-contact film demand drive specialty polyamide and PLA procurement. REACH chemical compliance frameworks mandate additive reformulation, eliminating conventional plasticizers from packaging supply chains. The Rhine-Ruhr corridor concentrates compounder operations serving OEMs and retail private-label programs.
Italy
Ready-meal packaging converters and agricultural mulch film producers anchor starch blend and cellulose resin consumption. EN 13432 certification requirements compress supplier qualification timelines for food-contact applications. The Po Valley processing cluster around Bologna and Milan dominates thermoformed tray manufacturing for European retail chains.
Netherlands
Coastal aquaculture operators and fishing gear manufacturers accelerate PHA-based rope and net procurement. The EU Packaging and Packaging Waste Regulation drives retail chain mandates for compostable carrier bags. Amsterdam-Rotterdam port infrastructure enables biopolymer import logistics for German and Belgian compounders.
United States
Corn-belt integrated biorefineries and CPG brand owner sustainability commitments concentrate PLA demand in food packaging. FDA food-contact notification pathways streamline bio-based polymer market entry. The Midwest manufacturing belt around Nebraska and Iowa anchors NatureWorks LLC's captive corn-to-resin operations.
Brazil
Sugarcane ethanol infrastructure supports bio-PE production scale for export markets. Braskem leverages São Paulo state feedstock access to supply European and Asian packaging converters. The Southeast industrial corridor around Campinas concentrates polymerization capacity for renewable-derived polyethylene output.
Bioplastics and Biopolymers Market Vendor Landscape
Listed leaders compete with private specialists across certification capacity and feedstock integration depth. The vendor base stratifies around three archetypes: integrated agricultural processors with captive sugar or starch supply, specialty chemical conglomerates with polymerization expertise, and fermentation technology specialists commercializing novel biopolymer chemistries. Capacity expansion and third-party certification acquisition constitute the dominant competitive moves as procurement gates tighten.
Within the integrated processor tier, NatureWorks LLC and Braskem exemplify feedstock-backward structures that secure margin stability against agricultural commodity cycles. BASF SE occupies a position among diversified chemical conglomerates leveraging polymerization scale across multiple resin chemistries. These three anchors represent distinct strategic postures: captive crop supply, petrochemical-bio hybrid operations, and specialty grade diversification.
| Leading Market Players |
|---|
| NatureWorks LLC |
| Braskem |
| BASF SE |
| TotalEnergies Corbion |
| Novamont |
| Biome Bioplastics Limited |
| Mitsubishi Chemical Group Corporation |
| Biotec Biologische Naturverpackungen GmbH & Co. |
| Toray Industries, Inc. |
| Others |
Supply Flow & Price Mechanics
Twelve-to-eighteen-month certification cycles for ASTM D6400 and EN 13432 validation compress procurement windows and concentrate pricing power among pre-qualified resin producers serving German and Italian packaging converters. This lead-time rigidity feeds directly into contract structures where multi-year offtake agreements lock in volume commitments before spot-market alternatives can qualify.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates PHA marine-certified grades from commodity PLA and starch blends. Certification tier and volume scale drive differentiation, with PHA commanding structural premiums due to anaerobic digestion compliance. Cost compression in starch blends intensifies as corn price volatility squeezes margin stability for agricultural feedstock dependents. Municipal procurement offices exhibit highest price sensitivity, while automotive compounders accept premium positioning for thermal-grade polyamides.
Supply Chain Analysis
Rotterdam port throughput capacity acts as the critical chokepoint for European biopolymer feedstock security, with German and Italian compounders dependent on this maritime gateway for resin imports. Supply concentration rests on Brazil for bio-PE, the US corn-belt for PLA, and European fermentation facilities for PHA. Corn, sugarcane, and vegetable oil feedstocks anchor raw material dependencies. Single-source vulnerability runs through NatureWorks LLC's captive corn-to-resin integration in Nebraska and Iowa. Distribution runs through direct sales relationships with certified compounders, supplemented by wholesale channels for spot-market demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certification fragmentation across ASTM D6400, EN 13432, and emerging marine-degradable standards creates service-layer niches where specialist validators and regional compounders capture margin pools unreachable by integrated giants.
For Market Incumbents: Secure backward integration into sugarcane or corn feedstock to buffer agricultural commodity cycles compressing starch-based and bio-PE margins. Prioritize EN 13432 certification maintenance as REACH additive reformulation threatens market access for conventional plasticizer-dependent grades. Capacity expansion in the Netherlands and Germany locks in proximity to composting infrastructure buildout.
For New Entrants and Emerging Players: Marine-degradable certification services for PHA grades represent an under-served layer where incumbent resin producers lack in-house anaerobic digestion validation expertise. Target coastal Netherlands fishing gear manufacturers and German aquaculture operators with bundled certification-consulting offerings. Partner with third-party labs to compress 12-18 month validation timelines for time-sensitive procurement windows.
For Investors and Strategic Acquirers: Long-term, this sits as a feedstock-integration play because captive agricultural supply determines margin stability against commodity volatility. Acquisition targets center on mid-cap fermentation technology specialists with commercialized PHA platforms and existing marine-degradable certifications. Watch municipal composting facility commissioning rates as the inflection signal—resin capacity announcements outpacing infrastructure buildout trigger feedstock-demand mismatches and pricing softness.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feedstock | Captive sugarcane or corn supply insulates Braskem and NatureWorks LLC from agricultural price cycles. |
| Third-Party Certification Acquisition | EN 13432 and ASTM D6400 validation opens procurement gates with German retail chains and Italian converters. |
| Marine-Degradable Grade Development | PHA formulations certified for anaerobic digestion command premium positioning in Netherlands fishing gear. |
| Regional Compounding Capacity Expansion | Rhine-Ruhr and Po Valley facilities reduce logistics costs for automotive and food-contact applications. |
| Long-Term Supply Agreements | Multi-year offtake contracts with German OEMs and CPG brand owners lock in volume before spot-market qualification. |
Methodological Framework
A spread of perspectives from resin plant managers, packaging converter procurement leads, automotive OEM compounders, and third-party certification lab directors converged on the working assumptions driving this analysis. Primary fieldwork combined structured interviews with secondary validation against SEC 10-K filings, European Bioplastics association statistics, customs and trade data for biopolymer resin flows, and REACH regulatory filings. Bottom-up capacity and demand modeling triangulated against top-down market sizing from production announcements and import-export records.
Segmentation dimensions modeled include product chemistry tier, end-use industry vertical, application format, and regional regulatory cluster across the projection horizon. CAGRs derive from weighted capacity expansion announcements, composting infrastructure buildout trajectories, and substitution elasticity estimates for fossil-based polyolefins. Industry-specific forecast inputs incorporate PLA mineralization temperature requirements and PHA fermentation yield improvements.
Forecasts assume regulatory continuity in EU REACH frameworks and US FDA food-contact pathways; material policy shifts would require re-modeling. Specific risks include municipal composting facility commissioning delays, corn price volatility from drought cycles, and mechanical recycling contamination disputes disrupting PLA market access. Revision becomes warranted when industrial composting capacity utilization crosses thresholds that trigger feedstock-demand imbalances.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bioplastics
Automotive Bioplastic Market
Bioplastics
Southeast Asia Bio-PET Market
Bioplastics
Brazil Bioplastics Market
Bioplastics
Global Bio-Polylactic Acid (PLA) Market
Bioplastics
Starch Blended Biodegradable Polymer Market
Bioplastics
Polyhydroxyalkanoate (PHA) Market
Bioplastics
Bio-Degradable Polymers Market
Bioplastics
Starch-Based Bioplastics Market
Bioplastics
Global Bio-Plasticizers Market
Bioplastics
Biopolymer Films Market
Bioplastics
North America Polylactic Acid (PLA) Market
Bioplastics
Bio-PET Market
Bioplastics
Global Bio-Based PET Market
Bioplastics
Southeast Asia Bioplastics Market
Bioplastics
Bio-Based Succinic Acid Derivatives for Plasticizers Market
Bioplastics
Biobased Biodegradable Plastics Market