
 Polyetherimide (PEI) Market | 2026-2036
Polyetherimide (PEI) Market Size, Share, and Industry Trends Forecast 2026-2036
Polyetherimide (PEI) Market Analysis
Market Context
China is reconfiguring regional supply dynamics through expanded domestic PEI compounding capacity and backward integration into specialty monomer production. SABIC leverages its integrated feedstock position and global resin manufacturing footprint to sustain price competitiveness across automotive and electronics grades. Toray Industries anchors Asian supply for high-tolerance PEI film used in flexible circuit substrates, while Solvay differentiates through medical-grade resin portfolios that meet stringent biocompatibility protocols.
Technical Profile and Segment Structure
Polyetherimide is an amorphous thermoplastic polymer combining ether linkages with imide functional groups, delivering continuous use temperatures up to 170°C, inherent flame resistance without halogenated additives, and dielectric stability across broad frequency ranges. PEI resin dominates volume flows due to established injection molding infrastructure and multi-industry versatility, while PEI film captures premium margin pools in electronics insulation and aerospace laminated composites. Medical device end users represent the fastest-expanding demand channel as sterilization-resistant, transparent PEI replaces traditional polymers in surgical instrument housings and diagnostic equipment.
Regulatory Environment and Strategic Outlook
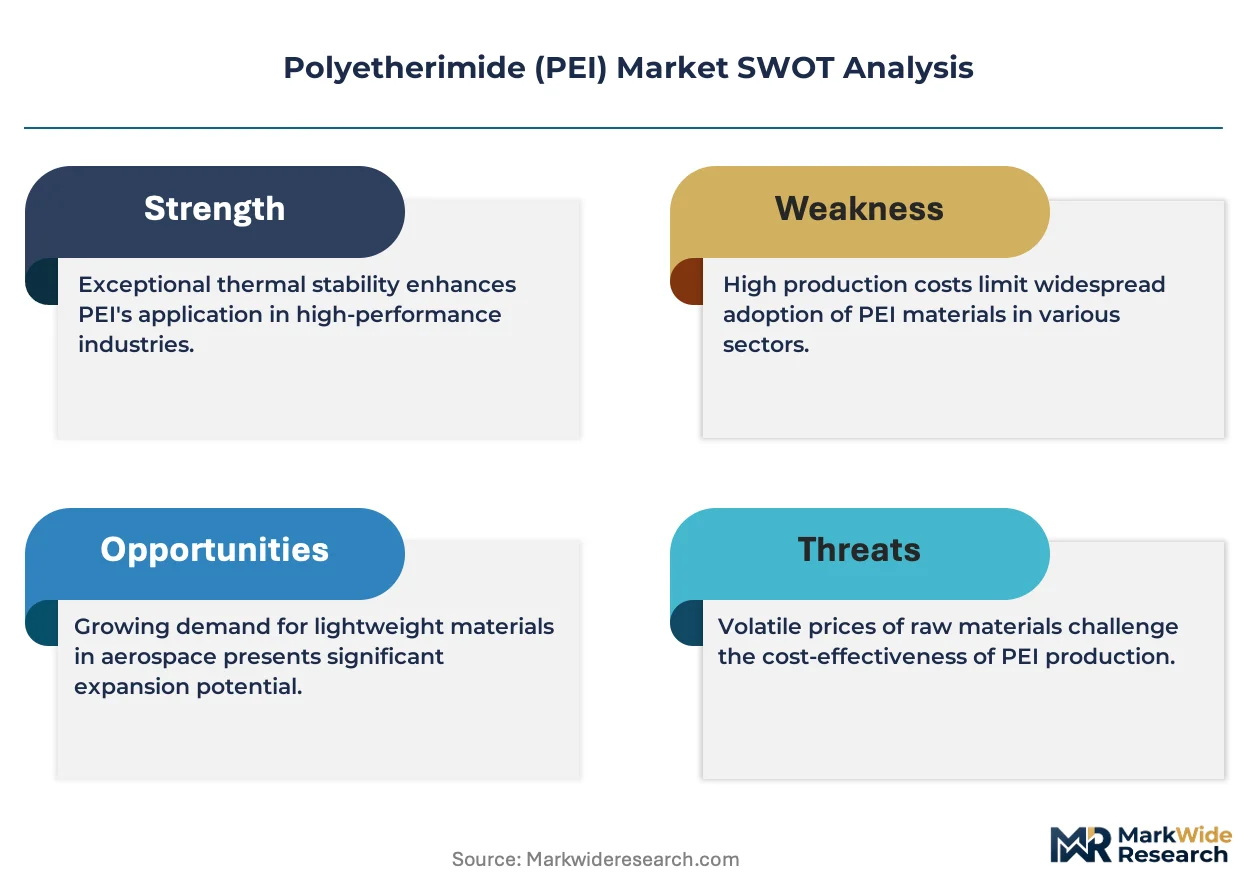
FDA 21 CFR compliance governs US medical device applications, REACH and RoHS frameworks constrain substance composition across European value chains, and China's GB standards for electrical insulation materials shape import substitution trajectories. These overlapping compliance regimes elevate formulation complexity and tighten qualification timelines for new resin grades. Stakeholders must monitor evolving flammability standards in commercial aviation and tightening migration limits for food-contact applications to anticipate specification shifts that will reshape procurement criteria.
Market Dynamics
EU Green Deal F-Gas Regulation and REACH compliance are forcing aerospace and automotive OEMs to abandon halogenated flame retardants, accelerating specification shifts toward PEI's inherent non-halogen fire resistance across laminated composites and injection-molded housings.
Growth Catalysts
- EU F-Gas Regulation phase-down:Aerospace interior manufacturers must eliminate hydrofluorocarbon-based foams and coatings, redirecting laminate specifications toward PEI film-core sandwich panels that satisfy flame-smoke-toxicity requirements without additive burden.
- Medical device sterilization protocols:Steam and gamma sterilization cycles degrade polycarbonate and ABS clarity over repeated exposures, positioning transparent PEI grades as the replacement polymer for surgical instrument handles and fluid management manifolds.
- 5G base station dielectric demands:Millimeter-wave antenna substrates require stable dielectric constants across humidity and temperature swings, pulling PEI resin into radome and connector housing formulations previously served by lower-performance thermoplastics.
Market Restraints
- Specialty monomer supply concentration:M-phenylenediamine and phthalic anhydride derivatives for PEI polymerization originate from a narrow supplier base concentrated in Northeast Asia, exposing compounders to force majeure disruptions and volatile aromatic feedstock pricing.
- High melt viscosity processing constraints:PEI's amorphous structure demands elevated barrel temperatures and prolonged cycle times versus polyamide or PBT, limiting adoption in high-volume automotive exterior applications where cost-per-part economics dominate supplier selection.
- Polyphenylene sulfide substitution threat:PPS resin offers comparable heat resistance at lower raw material cost for non-transparent electrical connectors, constraining PEI expansion in price-sensitive automotive sensor housings and industrial relay bodies.
Strategic Opportunities
- India medical device PLI scheme:Production-linked incentives for domestic surgical equipment manufacturing are attracting molding investments in Gujarat and Karnataka, creating localized demand for medical-grade PEI resin that bypasses import duty exposure.
- Bioprocessing single-use systems:Cell culture bags and filtration manifolds require gamma-stable, extractable-free polymers; PEI film formulations are penetrating this segment as stainless steel replacement accelerates in contract manufacturing organizations.
- Electric vehicle battery module insulation:Cell-to-pack architectures need thin-walled, flame-resistant barriers between lithium-ion cells; PEI's dielectric strength and thermal runaway resistance position it for thermal interface and compression pad applications.
Industry Challenges
- Biocompatibility certification timelines:FDA 21 CFR master file establishment and USP Class VI testing for new medical PEI grades require 18-24 month qualification cycles, delaying revenue realization for compounders targeting surgical robotics OEMs.
- Compounding equipment capex intensity:High-temperature twin-screw extruders with corrosion-resistant barrels and vacuum devolatilization stages represent substantial capital commitments for regional compounders seeking to enter aerospace-qualified resin production.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polyetherimide (PEI) Market |
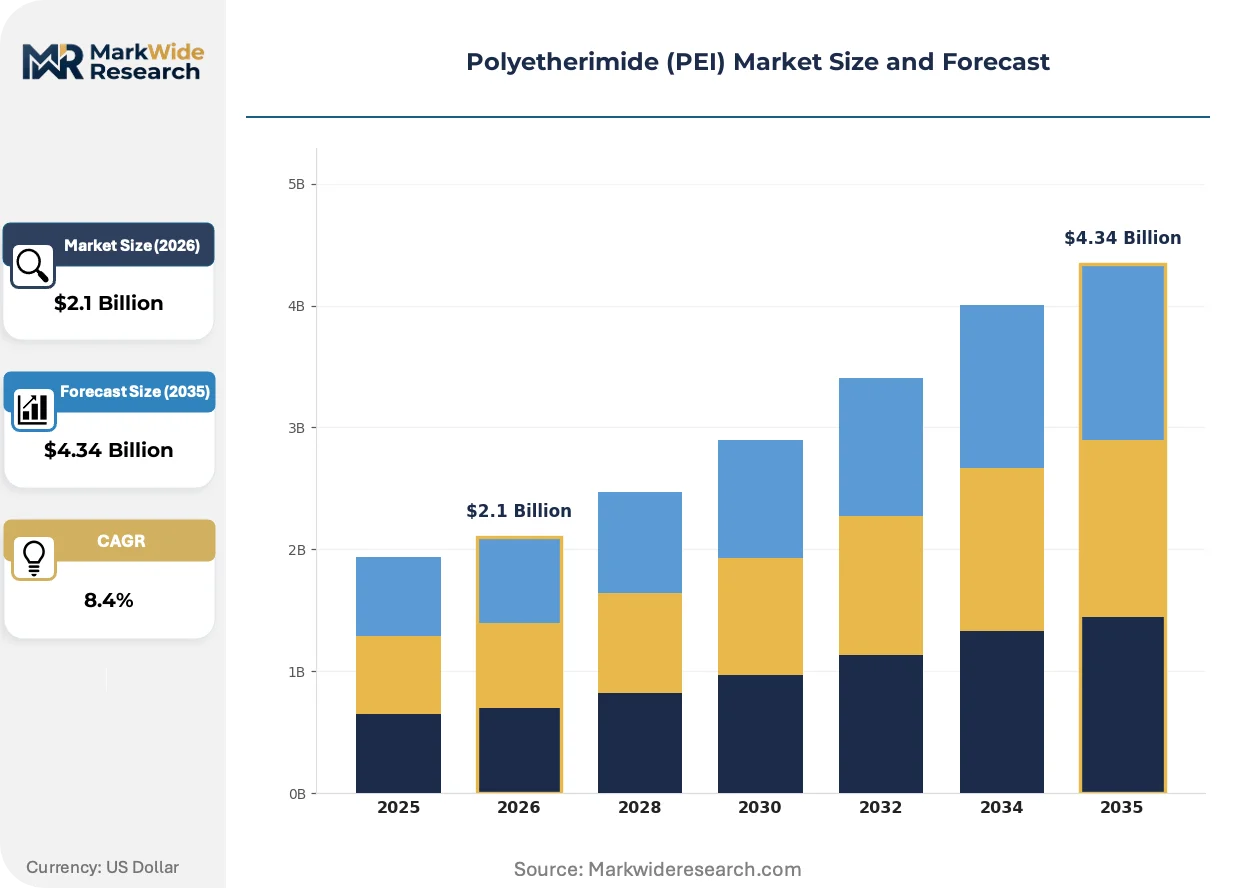
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $4.34 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PEI Resin, PEI Film, PEI Foam, PEI Powder End User: Aerospace, Automotive OEMs, Medical Devices, Electronics Application: 3D Printing, Insulation, Structural Components, Fluid Handling Distribution Channel: Direct Sales, Distributors, Online Retail, Wholesalers |
| Companies Covered | Röchling Group, RTP Company, SABIC, Kuraray Europe, Toray Industries, Mitsubishi Chemical Advanced Materials, Solvay, Honeywell International, Ensinger Plastics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polyetherimide (PEI) Market Emerging Trajectories
Material scientists are fusing PEI with complementary polymers and reinforcements to bridge performance gaps between commodity thermoplastics and aerospace thermosets, while regulatory pressure on halogenated additives intensifies formulation transparency requirements across value chains.
Carbon fiber-reinforced PEI composite tape is hybridizing automated fiber placement processes for commercial aviation secondary structures. Boeing and Airbus tier suppliers are qualifying this material for seat rails and galley frames where metal-to-plastic substitution reduces fuel burn. The hybridizing architecture compresses thermoset pre-preg lead times while maintaining flame-resistance certification without brominated epoxy hardeners.
REACH SVHC candidate list expansion is reshaping polymer additive strategies across European electrical and electronics value chains. ECHA scrutiny of halogenated flame retardants and certain plasticizers is pushing OEMs toward inherently flame-resistant base polymers. Medical device and aerospace cable harness manufacturers in Germany and France are responding by specifying unmodified PEI grades that satisfy RoHS and REACH constraints without formulation complexity.
Medical device OEMs are consolidating resin qualifications around suppliers offering combined FDA master files and ISO 13485 quality system certification. Boston Scientific and Medtronic procurement organizations are narrowing approved vendor lists to compounders with captive analytical laboratories and dedicated medical production lines. This concentration is most visible in Minnesota and Massachusetts medical device clusters, where surgical instrument molders now require resin suppliers to maintain segregated silos and lot traceability through finished device sterilization.
Polyetherimide (PEI) Market Segmentation
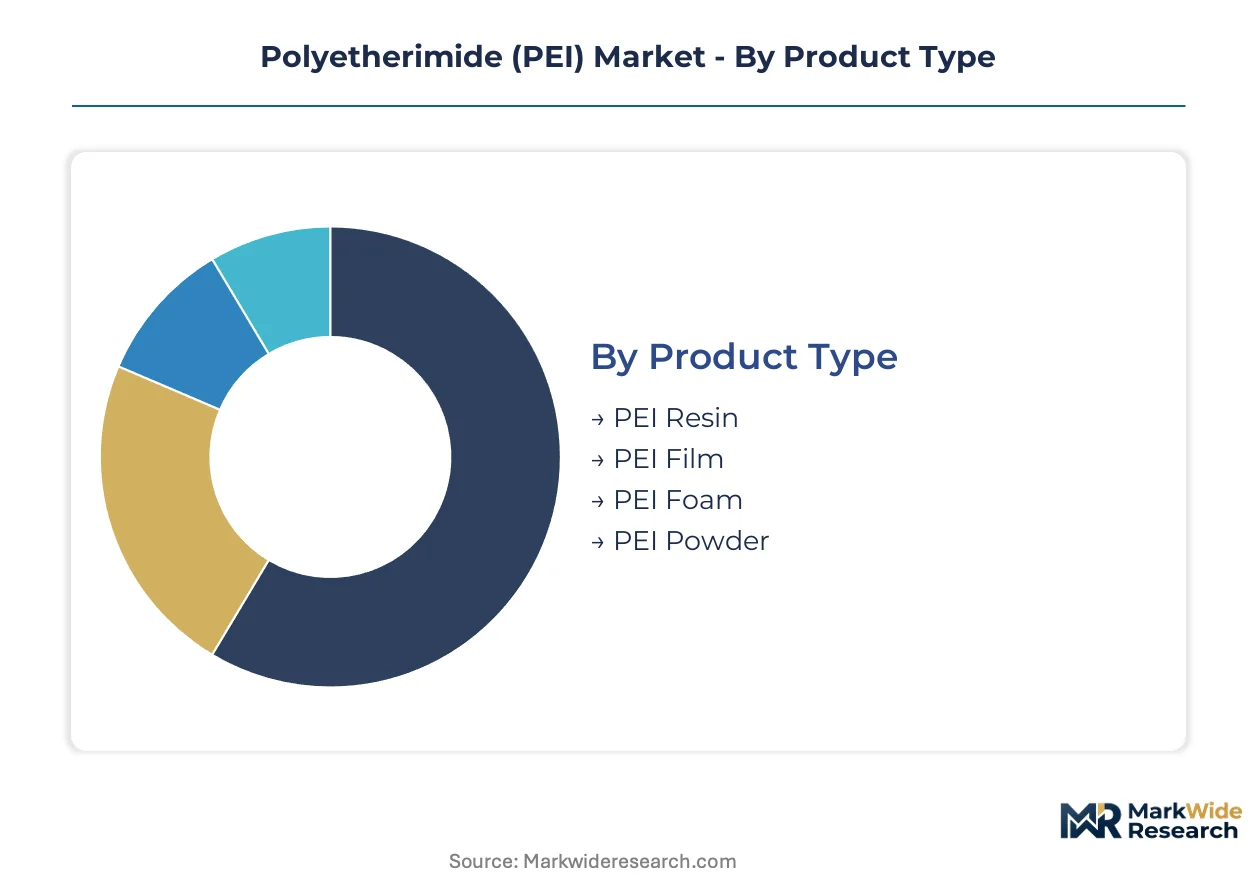
PEI market segmentation reveals divergent margin structures across physical forms and end-use verticals. Cycle times and qualification barriers vary dramatically between commodity resin flows and medical-grade film batches.
Product Type:
Resin grades turn inventory fastest through injection molding channels, while film and foam products endure extended aerospace qualification timelines that stretch working capital cycles.
- PEI Resin:Amorphous thermoplastic pellets serve high-volume automotive and electronics molding operations. German automotive clusters and China's Yangtze River Delta electronics corridors absorb the largest resin volumes, driven by REACH-compliant halogen-free flame retardant mandates.
- PEI Film:Thin-gauge extruded sheets deliver dielectric stability for flexible circuit substrates and aerospace laminated composites. Toray Industries anchors Asian supply for 5G antenna radomes, where millimeter-wave performance requirements displace lower-grade polyimide alternatives.
- PEI Foam:Lightweight cellular structures for aircraft interior sandwich panels. Boeing and Airbus tier suppliers specify these cores for seat rails and galley frames under FAA flame-smoke-toxicity protocols.
- PEI Powder:Fine-ground polymer for selective laser sintering and compression molding compounds. Medical device prototyping labs in Minnesota and Massachusetts consume powder grades for surgical instrument iterative design cycles.
PEI Resin anchors the volume base while PEI Film gains share at the steepest rate.
End User:
Margin tiers separate sterilization-critical medical applications from price-sensitive automotive sensor housings, with aerospace occupying the premium midpoint.
- Aerospace:Cabin interiors and engine components demand FAA-certified flame resistance without halogenated additives. EU F-Gas Regulation phase-down redirects laminate specifications toward PEI film-core panels.
- Automotive OEMs:Underhood electrical connectors and lighting housings specify PEI where PPS substitution threatens in non-transparent applications. High melt viscosity constrains adoption in exterior body panels where cycle time economics dominate.
- Medical Devices:Steam and gamma sterilization cycles degrade polycarbonate clarity, positioning transparent PEI grades for surgical instrument handles and fluid management manifolds. FDA 21 CFR master file establishment requires 18-24 month qualification timelines.
- Electronics:5G base station radomes and antenna substrates require stable dielectric constants across humidity swings. China's GB standards for electrical insulation materials shape import substitution trajectories in domestic compounding.
Medical Devices command the highest per-kilogram pricing while Electronics expands most quickly on 5G infrastructure deployment.
Application:
Processing method determines batch economics, with additive manufacturing commanding premiums over conventional molding.
- 3D Printing:Fused filament fabrication and selective laser sintering of PEI enable complex geometries for aerospace brackets and medical prototyping. Powder bed fusion systems in German automotive R&D centers iterate design cycles without hard tooling investment.
- Insulation:Electric vehicle battery module barriers and high-voltage connector housings leverage PEI's dielectric strength and thermal runaway resistance. Cell-to-pack architectures pull thin-walled PEI films between lithium-ion cells.
- Structural Components:Carbon fiber-reinforced PEI composite tape hybridizes automated fiber placement for aviation secondary structures. Metal-to-plastic substitution reduces fuel burn in seat rails and galley frames.
- Fluid Handling:Bioprocessing single-use systems specify gamma-stable, extractable-free PEI film for cell culture bags and filtration manifolds. Contract manufacturing organizations accelerate stainless steel replacement in drug substance production.
Insulation applications anchor current volume while 3D Printing climbs the fastest on design freedom premiums.
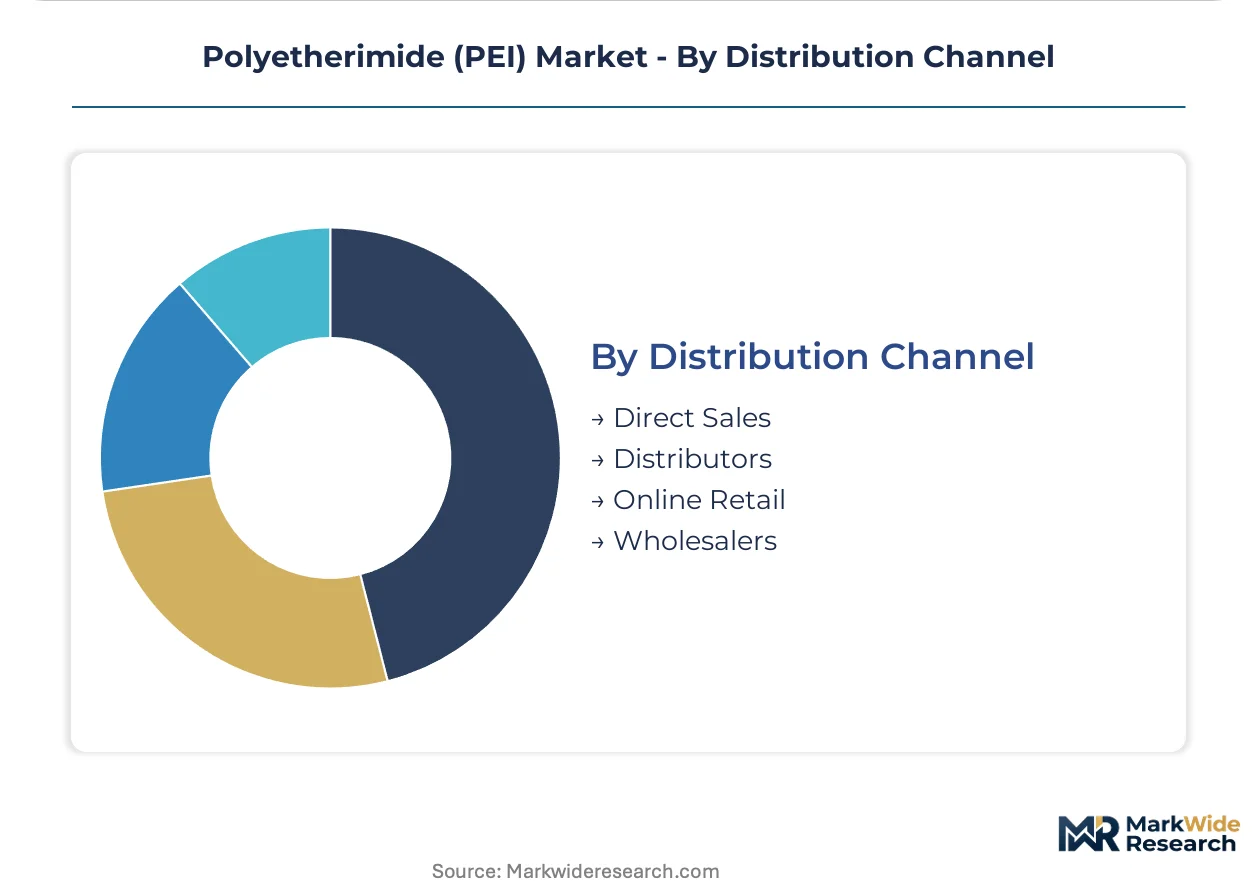
Distribution Channel:
Channel selection reflects customer scale and technical service intensity, with direct relationships dominating qualified aerospace and medical accounts.
- Direct Sales:SABIC and Solvay maintain dedicated technical service teams for automotive Tier 1 and medical device OEMs. FDA master file coordination and lot traceability requirements favor direct channel relationships.
- Distributors:Regional compounders access specialty monomer supply through chemical distribution networks concentrated in Northeast Asia. Inventory buffering mitigates force majeure exposure from narrow m-phenylenediamine supplier bases.
- Online Retail:Small-lot PEI filament and powder grades for prototyping labs and academic research. E-commerce penetration remains limited by material safety data sheet complexity and shipping classification constraints.
- Wholesalers:Volume resin flows through plastics wholesalers serving injection molders without direct polymer producer relationships. Price transparency pressures margin capture in commoditized automotive grades.
Direct Sales captures the premium tier while Distributors handle the broadest geographic spread.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialty monomer supply for PEI polymerization concentrates in Northeast Asian chemical corridors, while compounding and conversion activities distribute across German automotive clusters, US medical device hubs, and China's Yangtze River Delta electronics manufacturing zones.
United States
Medical device OEMs in Minnesota and Massachusetts drive sterilization-grade PEI consumption for surgical instrument housings. FDA 21 CFR master file requirements govern resin qualification timelines. Boston Scientific and Medtronic procurement teams concentrate supplier approvals in these clusters, mandating segregated production lines and lot traceability through finished device sterilization.
Germany
Automotive and aerospace OEMs specify REACH-compliant halogen-free PEI for underhood connectors and cabin interior laminates. EU F-Gas Regulation phase-down redirects laminate specifications toward PEI film-core sandwich panels. Baden-Württemberg's automotive Tier 1 suppliers and Bavaria's aerospace subcontractors absorb the largest European resin volumes.
China
Domestic compounding capacity expansion and backward integration into specialty monomer production reconfigure regional supply dynamics. GB standards for electrical insulation materials shape import substitution trajectories. Yangtze River Delta electronics corridors absorb PEI resin for 5G base station radomes and antenna substrates.
Japan
High-tolerance PEI film production anchors Asian supply for flexible circuit substrates and millimeter-wave antenna applications. METI industrial policy supports advanced materials R&D. Toray Industries maintains production positioning for electronics-grade film serving regional 5G infrastructure deployment.
India
Production-linked incentives for domestic surgical equipment manufacturing attract molding investments in Gujarat and Karnataka. CDSCO medical device regulations and BIS standards constrain import-dependent supply chains. Localized compounding investments aim to bypass import duty exposure for medical-grade resin consumption.
Polyetherimide (PEI) Market Vendor Landscape
Integrated petrochemical conglomerates and specialized engineering plastics compounders split the market between scale-driven resin production and qualification-intensive medical-grade formulations. The vendor base organizes around three strategic archetypes: upstream-integrated resin producers with captive monomer supply, regional compounders serving automotive and electronics molding channels, and medical-grade specialists maintaining FDA master files and dedicated clean production lines. Dominant competitive moves include backward integration into m-phenylenediamine and phthalic anhydride derivatives, plus geographic expansion of medical-grade compounding capacity near FDA-regulated device manufacturing clusters.
Among integrated resin producers, SABIC leverages global manufacturing footprints and feedstock integration to serve automotive and electronics grades across multiple continents. Solvay occupies a position within the medical-grade specialist tier, differentiating through biocompatibility certification and quality system infrastructure. Toray Industries anchors the high-performance film segment, representing the electronics-grade specialization archetype with Asian supply positioning for 5G and aerospace laminated composite applications.
| Leading Market Players |
|---|
| Röchling Group |
| RTP Company |
| SABIC |
| Kuraray Europe |
| Toray Industries |
| Mitsubishi Chemical Advanced Materials |
| Solvay |
| Honeywell International |
| Ensinger Plastics |
| Others |
Supply Flow & Price Mechanics
Single-source dependency on m-phenylenediamine and phthalic anhydride derivatives from Northeast Asian chemical corridors determines both the wide pricing tier spreads between aerospace-qualified and automotive commodity grades and the elongated working capital cycles that characterize PEI value chains.
Pricing Analysis
EU REACH and RoHS compliance dictates the pricing tier structure across the PEI market, separating premium medical-grade resin with FDA master file documentation from standard automotive injection molding pellets and economy electronics grades. Price differentiation rests on certification level—USP Class VI and ISO 13485 quality systems command substantial premiums over industrial grades—and volume scale, with automotive Tier 1 offtake agreements compressing per-kilogram economics. Cost compression in commodity resin tiers is intensifying because PPS substitution threatens non-transparent electrical connector applications. Automotive sensor housing molders exhibit the highest price sensitivity, while surgical robotics OEMs prioritize qualification reliability over unit cost.
Supply Chain Analysis
Phthalic anhydride and m-phenylenediamine feedstock production concentrates in China, South Korea, and Japan, with regional compounders drawing from this narrow supplier base for polymerization inputs. Raw material dependencies extend to high-purity aromatic monomers, corrosion-resistant compounding equipment, and vacuum devolatilization systems for medical-grade resin production. Single-source vulnerability from force majeure disruptions in Northeast Asian chemical corridors exposes European and North American compounders to volatile aromatic feedstock pricing and extended lead times. Distribution runs through direct technical service relationships for qualified aerospace and medical accounts, with regional distributors buffering inventory for automotive molding channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory fragmentation across FDA, REACH, and China's GB standards creates protected niches for compounders with differentiated certification capabilities, as OEM procurement teams narrow approved vendor lists to suppliers offering combined quality system coverage.
For Market Incumbents: Build regulatory certification moats by establishing captive FDA master files and ISO 13485 production lines ahead of Boston Scientific and Medtronic vendor consolidation. Backward integration into specialty monomer production defends against force majeure disruptions from Northeast Asian suppliers. Capacity addition in Gujarat and Karnataka captures India PLI scheme surgical equipment demand before import duty exposure erodes margin. For New Entrants and Emerging Players: India's underpenetrated medical device compounding landscape offers the most penetrable entry point, with production-linked incentives attracting molding investments that bypass existing import-dependent supply chains. Target bioprocessing single-use systems as the fastest-qualifying application segment, where gamma-stable PEI film displaces stainless steel in contract manufacturing organizations. Pursue joint development agreements with regional distributors to overcome lot traceability and segregated production infrastructure barriers. For Investors and Strategic Acquirers: EU F-Gas Regulation phase-down reshapes the acquisition landscape toward compounders with aerospace-qualified film production and halogen-free certification capabilities. Long-term viability centers on suppliers with demonstrated FDA 21 CFR compliance and captive analytical laboratory infrastructure. Monitor ECHA SVHC candidate list expansion as the signal indicating accelerated specification shifts away from halogenated additive formulations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Specialty Monomers | Captive m-phenylenediamine supply insulates SABIC and Solvay from force majeure disruptions in Northeast Asia. |
| Medical-Grade Compounding Capacity Expansion | Segregated production lines near Minnesota and Massachusetts clusters capture FDA-regulated surgical instrument demand. |
| Aerospace Film-Core Laminate Qualification | PEI sandwich panel certification with Boeing and Airbus tier suppliers locks in EU F-Gas Regulation-driven specification shifts. |
| Electric Vehicle Battery Module Insulation Development | Cell-to-pack thermal barrier applications position PEI for lithium-ion cell compression pad growth. |
| 5G Antenna Substrate Partnership | Toray Industries' millimeter-wave film supply anchors radome specifications for China's Yangtze River Delta infrastructure deployment. |
Methodological Framework
Desk research of customs trade data, SEC 10-K filings from integrated resin producers, and ECHA regulatory submissions preceded structured interviews with plant managers at compounding facilities, procurement leads at automotive Tier 1 suppliers, biomedical engineers at medical device OEMs, and technical R&D directors at specialty film manufacturers. Bottom-up demand modeling from injection molding throughput and top-down validation against import-export flows established volume estimates across the analysis window.
Assumptions held fixed include REACH and RoHS regulatory frameworks, FDA 21 CFR master file requirements, and China's GB standards for electrical insulation materials; variables included specialty monomer pricing volatility, aerospace qualification timeline compression, and PPS substitution rates in automotive connectors. Segmentation dimensions spanned physical form, end-use vertical, processing method, and regional production hub. CAGRs derived from fitted growth curves applied to qualified demand segments, with 5G infrastructure deployment schedules and EV battery pack architecture adoption as industry-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in aromatic feedstock pricing, currency volatility affecting Northeast Asian import costs, or trade policy shifts impacting India import duties would shift the trajectory. Cross-checking against IHS Markit plastics pricing indices and Cefic specialty chemicals production data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Materials
Sheath Materials Market
Specialty Materials
Asia Pacific Cellulose Acetate Market
Specialty Materials
Metallised Polyester Films Market
Specialty Materials
Cadmium Sulfide Market
Specialty Materials
Niobium Pentoxide Market
Specialty Materials
UK Lab-Grown Diamonds Market
Specialty Materials
Microwave Absorbing Materials Market
Specialty Materials
Elastic Films Market
Specialty Materials
ePTFE Electronic Film Market
Specialty Materials
Jesmonite Market
Specialty Materials
Semiconductor O-Rings Market
Specialty Materials
Europe Acrylic Sheet Market
Specialty Materials
Colloidal Silica Market
Specialty Materials
Specialty Silicone Market
Specialty Materials
Talc Alternatives Market
Specialty Materials
Asia-Pacific Colloidal Silica Market