
 Retro Reflective Materials Market | 2026-2036
Retro Reflective Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Retro Reflective Materials Market Intelligence
Market Context with Strategic Players
China is tilting the competitive map through expanded domestic production of glass-bead and microprismatic films. 3M leverages its microreplication technology leadership to sustain premium positioning across North American and European safety markets. ORAFOL Europe GmbH anchors its position through vertically integrated manufacturing of reflective sheeting for traffic signage and vehicle marking applications.
Technical Definition and Structural Segments
Retro reflective materials are engineered surfaces that return incident light directly toward its source through embedded glass beads, microprisms, or ceramic elements, typically achieving coefficient of retroreflection values measured in candela per lux per square meter for standardized visibility performance. These materials serve critical safety functions in low-light and nighttime conditions across transportation infrastructure, occupational apparel, and emergency response equipment. Films and tapes command the largest share of product-type value pools, while beads retain cost-driven volume leadership in emerging-market road marking applications. Emergency services and road safety applications concentrate the fastest structural growth, driven by regulatory mandates for first-responder gear visibility and highway infrastructure upgrades.
Regulatory Frame and Forward Outlook
NHTSA governs conspicuity tape requirements for commercial trailers in the United States, while ECE R104 and CE marking shape product compliance across European vehicle and signage markets. China's GB standards and MIIT directives enforce domestic reflective performance thresholds for highway signage and automotive applications, tightening market access for non-compliant imports. Stakeholders must monitor divergence between regional photometric standards and raw material qualification protocols to anticipate compliance-driven sourcing shifts.
Market Dynamics
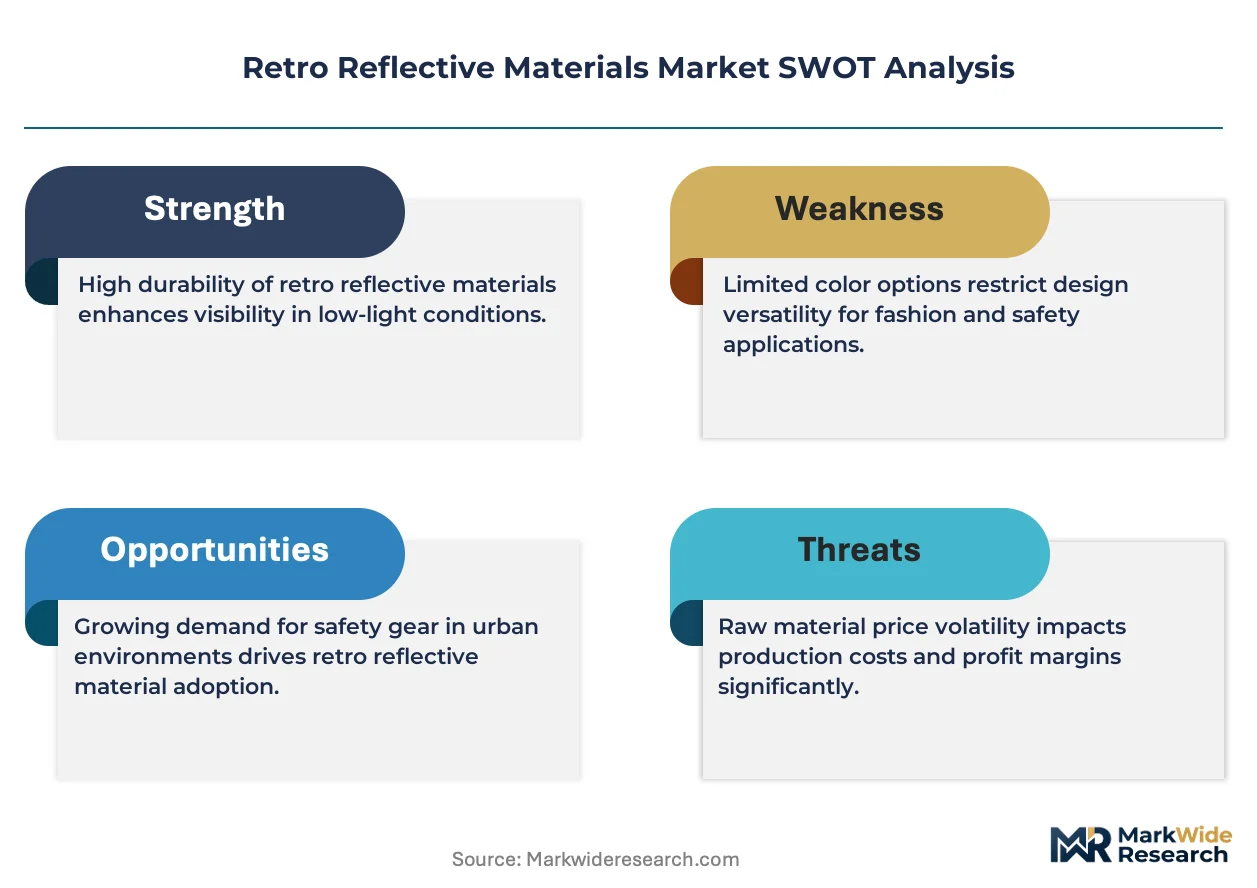
Highway infrastructure agencies are consolidating specifications around microprismatic films with higher coefficient of retroreflection, compressing demand for legacy glass-bead formulations and reshaping supplier qualification protocols.
Growth Catalysts
- ECE R104 vehicle marking mandates:European heavy goods vehicle operators must install certified retro reflective contour markings, creating recurring replacement demand across commercial fleets.
- China's GB highway signage standards:Provincial transportation bureaus are replacing aging signage with high-performance sheeting, pulling volume through domestic film manufacturers.
- Glass-bead road marking applications:Municipal road agencies in emerging markets specify cost-effective thermoplastic markings with embedded beads for lane delineation and pedestrian crossings.
Market Restraints
- Petrochemical input volatility:Acrylic and PVC resin costs fluctuate with propylene feedstock pricing, squeezing film converter margins without long-term supply agreements.
- Prismatic master supplier concentration:Precision microreplication tooling and optical-grade polycarbonate supply cluster with a limited set of Asian and North American equipment vendors.
- Photometric performance ceilings:Existing microprismatic designs approach theoretical retroreflection limits at wide observation angles, constraining differentiation through raw performance gains.
Strategic Opportunities
- India's National Highway expansion:State road development corporations are tendering for high-visibility signage on new expressway corridors with phased installation schedules.
- Smart infrastructure convergence:Retro reflective films integrating RFID or QR codes enable automated asset tracking for maintenance management systems.
- Occupational visibility regulations:Construction and utility sector safety codes in multiple jurisdictions are expanding mandatory high-visibility apparel requirements beyond traffic control personnel.
Industry Challenges
- Photometric testing laboratory capacity:Certification bodies face backlog in coefficient of retroreflection validation for new product submissions, extending time-to-market.
- Multi-standard compliance complexity:Suppliers must maintain parallel inventory for ASTM, EN, and GB testing protocols with divergent observation angle specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Retro Reflective Materials Market |
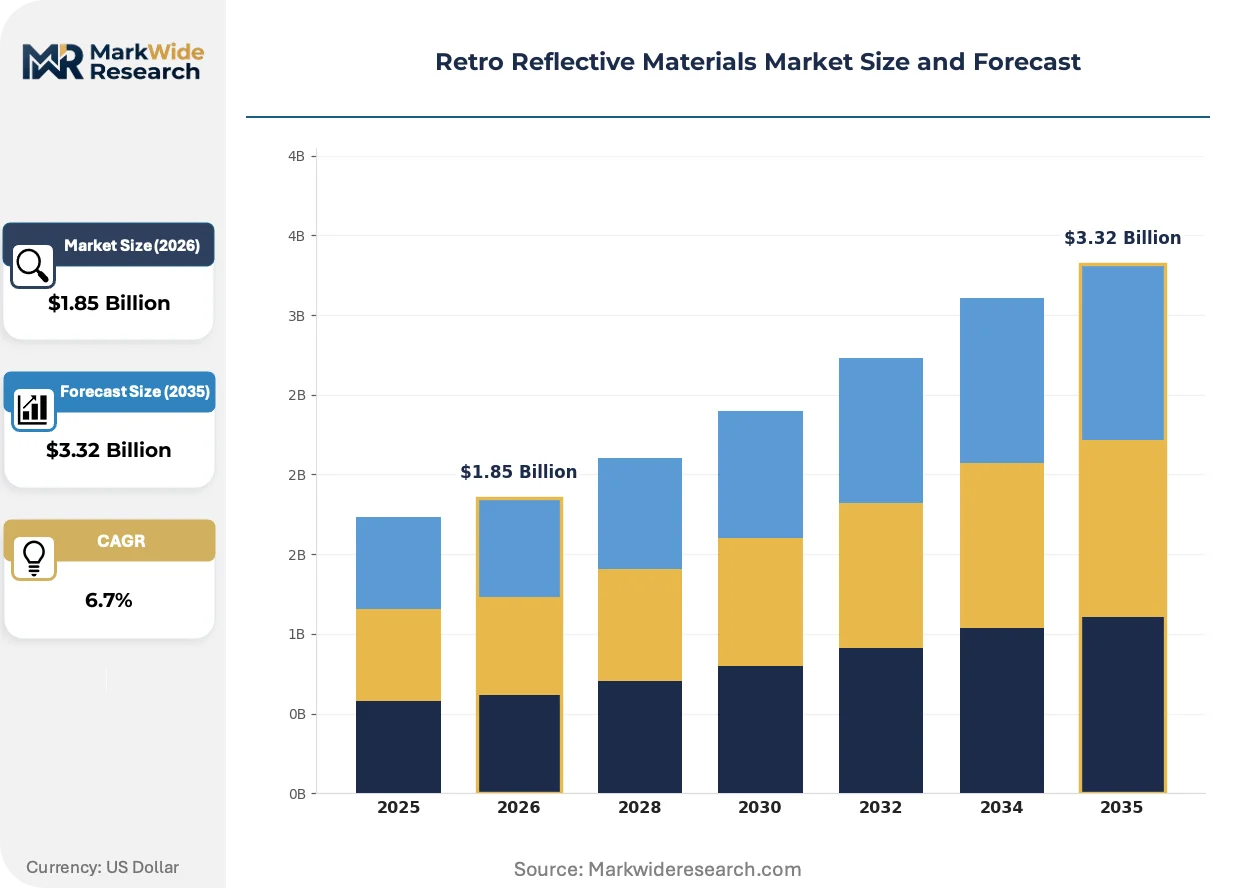
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.32 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Beads, Films, Tapes, Coatings Application: Road Safety, Signage, Apparel, Emergency Services Material: Glass, Plastic, Ceramic, Aluminum End User: Manufacturers, Government, Retailers, Distributors |
| Companies Covered | Nippon Carbide Industries Co., Inc, ALANOD GmbH & Co. KG, 3M, Daoming Reflective Material India Pvt. Ltd., Coats Group Plc, Avery Dennison Corporation, Changzhou Hua R Sheng Reflective Material Co., Ltd, Reflomax, ORAFOL Europe GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Retro Reflective Materials Market Strategic Shifts & Innovations
Material science advances and regulatory precision are elevating performance thresholds while digital integration opens new functional categories beyond passive visibility.
Microprismatic sheeting with optimized cube-corner geometry is rendering obsolete lower-grade glass-bead films in premium traffic signage applications. State departments of transportation in the United States are specifying these materials for interstate guide signs and work zone delineation. The technology is compressing replacement cycles as agencies demand longer-effective service life under warranty terms.
REACH substance restrictions on certain plasticizers and stabilizers are forcing reformulation of PVC-based reflective films across European markets. Manufacturers are accelerating migration to acrylic and polyester carrier systems with alternative additive packages. Traffic signage and vehicle marking segments are absorbing compliance costs through specification upgrades rather than price competition.
Asset management platforms are embedding serialized identification into reflective sheeting at the point of manufacture. Transportation agencies and fleet operators are adopting these solutions to automate inventory tracking and maintenance scheduling. Deployment is most advanced in Nordic markets where public infrastructure digitization programs coordinate signage databases with mobile inspection applications.
Retro Reflective Materials Market Segmentation
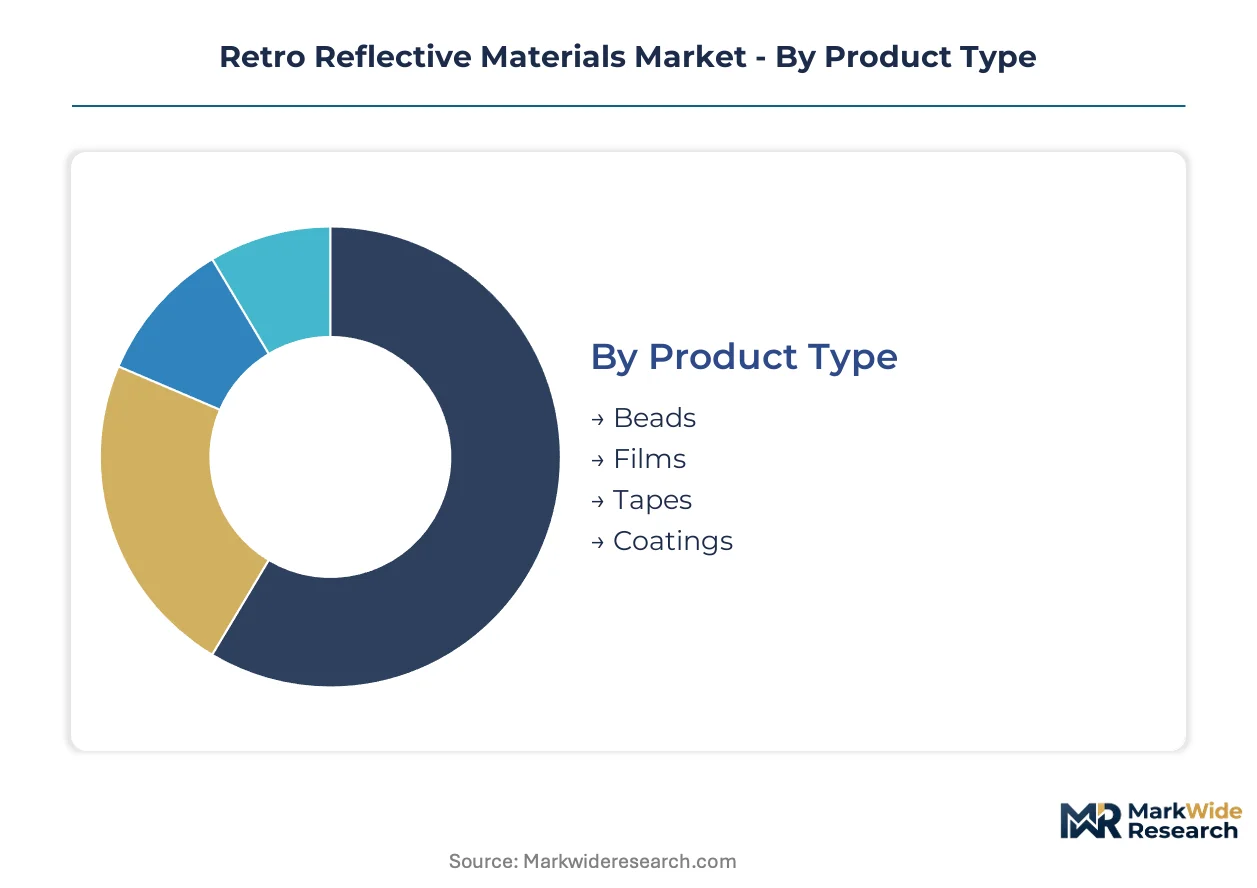
Retro reflective materials serve distinct performance requirements across traffic infrastructure, occupational safety, and emergency response equipment. Product specifications diverge sharply between cost-driven road marking applications and precision-engineered automotive conspicuity systems, necessitating segmented procurement strategies and supplier qualification protocols.
Product Type:
After-sales service intensity varies dramatically across product formats, with films and tapes requiring technical field support for installation certification while beads and coatings operate through commodity distribution channels with minimal ongoing service attachment.
- Films:Microprismatic and glass-bead sheeting deliver standardized coefficient of retroreflection performance for traffic signage and vehicle markings. State departments of transportation in the United States specify these materials for interstate guide signs, while European fleet operators source certified contour marking films under ECE R104 mandates. Demand concentrates in premium traffic signage where warranty terms and photometric longevity drive specification decisions.
- Tapes:Pressure-sensitive adhesive-backed retro reflective materials enable rapid application to vehicle surfaces, temporary traffic control devices, and emergency response equipment. Commercial trailer manufacturers in North America integrate conspicuity tapes during assembly to satisfy NHTSA Federal Motor Vehicle Safety Standards, creating specification-locked supply relationships with qualified converters.
- Beads:Embedded glass spheres provide cost-effective retroreflection for thermoplastic road markings and traffic paint applications. Municipal agencies in emerging markets specify bead-embedded formulations for lane delineation and pedestrian crossings where unit economics dominate procurement criteria.
- Coatings:Liquid-applied retro reflective formulations serve specialized industrial and marine marking requirements. Port authorities and offshore facility operators utilize these materials for bollard, crane, and vessel visibility enhancement in low-light operational environments.
Films hold the largest share; momentum sits with tapes as fleet marking mandates expand across commercial vehicle segments.
Application:
Application segmentation reveals divergent margin structures, with emergency services and road safety commanding specification premiums while apparel operates through volume-driven procurement channels with compressed conversion economics.
- Road Safety:Highway infrastructure applications encompass permanent signage, temporary work zone devices, and pavement markings requiring standardized photometric performance. China's provincial transportation bureaus are replacing aging signage with high-performance sheeting under updated GB standards, pulling substantial volume through domestic manufacturing channels.
- Signage:Regulatory and wayfinding applications demand precise colorfastness and retroreflection coefficients measured across standardized observation angles. European traffic authorities specify EN-compliant materials for urban directional signage and highway guide markers.
- Apparel:High-visibility occupational garments integrate retro reflective trim and segmented tape configurations for worker conspicuity. Construction and utility sector safety codes in multiple jurisdictions are expanding mandatory high-visibility requirements beyond traffic control personnel.
- Emergency Services:First-responder gear and vehicle markings require specialized fluorescent and retro reflective combinations for maximum recognition distance. Fire departments and ambulance operators specify certified materials meeting stringent photometric and durability standards for life-safety applications.
Road Safety dominates current value capture; Emergency Services is climbing the fastest as regulatory mandates tighten for first-responder visibility equipment.
Material:
Raw material selection determines optical performance ceilings, environmental durability, and compliance with substance restriction frameworks across regional markets.
- Glass:Soda-lime and high-index glass beads and microspheres deliver cost-efficient retroreflection through embedded and surface-applied configurations. Glass-bead formulations retain volume leadership in emerging-market road marking applications where procurement prioritizes unit cost over maximum performance.
- Plastic:Acrylic, polycarbonate, and PVC carrier systems support microprismatic films and flexible tape constructions. REACH substance restrictions on certain plasticizers and stabilizers are forcing reformulation of PVC-based reflective films across European markets.
- Ceramic:High-durability ceramic elements provide extended service life in aggressive environmental conditions including marine exposure and industrial chemical contact.
- Aluminum:Metallized reflective layers enhance brightness in specialized applications requiring combined retroreflective and diffuse reflective performance characteristics.
Glass commands the greatest volume; Plastic is gaining share fastest as microprismatic technology displaces legacy bead formulations in premium segments.
End User:
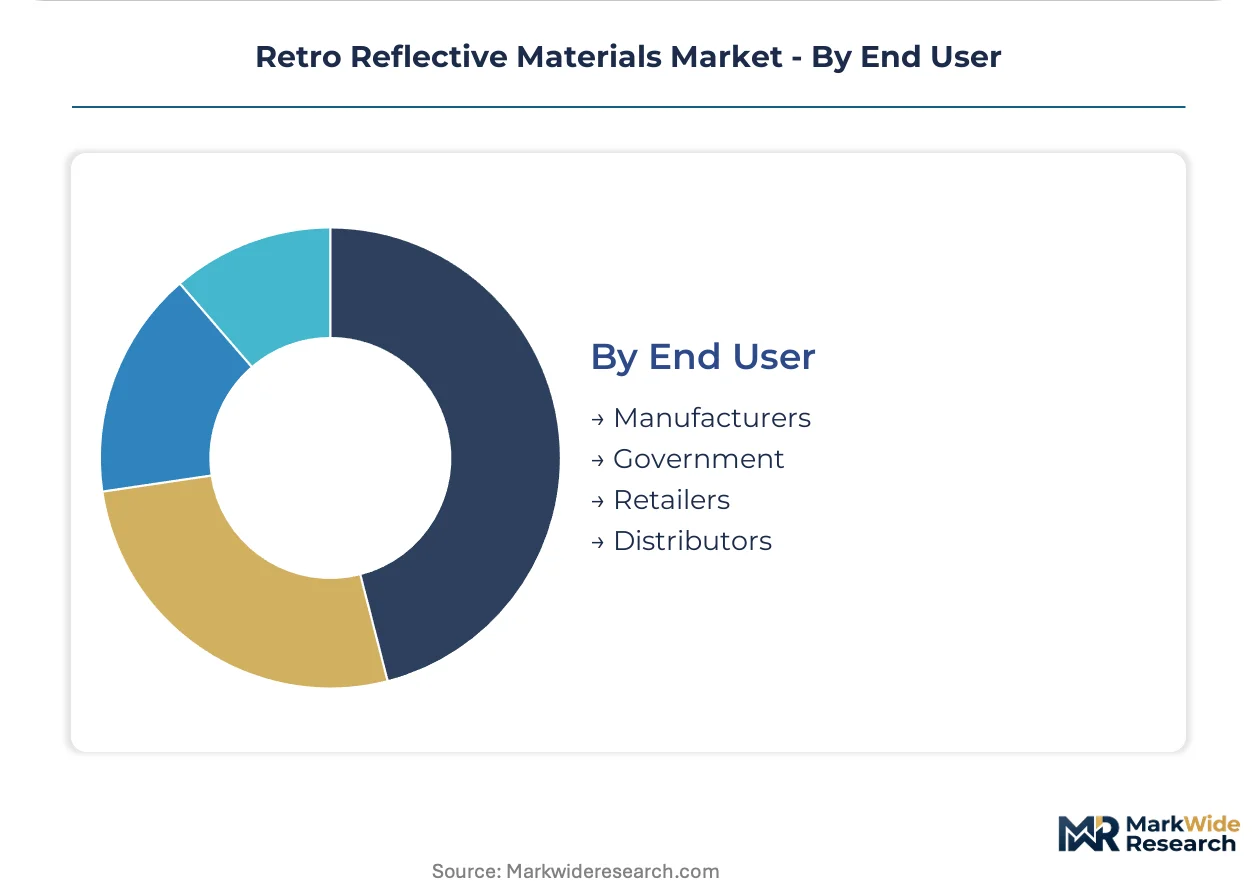
End-user segmentation maps to distinct purchasing behaviors, with government agencies operating through extended tender cycles and technical specification committees while retailers and distributors serve fragmented aftermarket demand.
- Manufacturers:Original equipment manufacturers of vehicles, safety apparel, and traffic control devices specify certified retro reflective materials during product design and assembly. Commercial trailer builders integrate conspicuity tapes to satisfy regulatory mandates before vehicles enter service.
- Government:Highway agencies, transportation departments, and public works authorities procure reflective materials through competitive bidding processes with extended qualification requirements. India's state road development corporations are tendering for high-visibility signage on new expressway corridors.
- Retailers:Commercial distributors and safety equipment suppliers serve fragmented demand from small contractors, municipalities, and individual consumers for replacement and upgrade applications.
- Distributors:Specialized industrial and safety product distributors maintain inventory and technical support capabilities for contractor and institutional accounts requiring rapid fulfillment.
Government holds the largest share; Manufacturers are expanding fastest as regulatory mandates shift specification responsibility upstream to vehicle and equipment builders.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing capacity for microprismatic films clusters with precision tooling vendors in East Asia and North America, while specification authority rests with transportation agencies in Europe and China. Raw material supply for glass beads and optical-grade polymers concentrates near petrochemical hubs in the United States, Germany, and coastal China.
United States
NHTSA mandates conspicuity tape on commercial trailers, sustaining replacement demand across heavy-duty fleets. State departments of transportation specify microprismatic sheeting for interstate guide signs under MUTCD guidelines. Manufacturing clusters in Minnesota and Texas produce reflective films for domestic highway infrastructure procurement.
Germany
ECE R104 vehicle marking regulations drive certified contour film adoption among commercial fleet operators. KBA enforces type-approval protocols for retro reflective automotive components entering European markets. The Rhine-Ruhr industrial corridor hosts precision film converters serving traffic signage and vehicle marking applications.
China
Provincial transportation bureaus are replacing aging highway signage under updated GB standards, pulling volume through domestic manufacturers. MIIT directives enforce reflective performance thresholds for automotive and infrastructure applications. Manufacturing scale concentrates in Jiangsu and Zhejiang provinces, where glass-bead and microprismatic film output supplies domestic and export markets.
India
National Highway expansion programs are tendering high-visibility signage for new expressway corridors with phased installation schedules. BIS certification requirements shape product qualification for road safety applications. State road development corporations in Maharashtra and Gujarat are procuring reflective sheeting for urban arterial upgrades.
Japan
METI industrial standards govern retro reflective performance for traffic safety equipment and occupational apparel. Domestic manufacturers supply precision microprismatic films for export markets and domestic highway maintenance. Manufacturing activity concentrates in the Chubu region around Nagoya, where optical materials processing capabilities support reflective film production.
Retro Reflective Materials Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream in raw materials and precision tooling. The market exhibits tiered concentration, with a handful of multinational corporations dominating premium microprismatic film supply while regional converters serve cost-sensitive road marking segments. Strategic archetypes include: vertically integrated optical materials conglomerates, specialized reflective film converters, and glass-bead processors serving commodity thermoplastic applications. Competitive dynamics center on backward integration into polymer supply and technology licensing arrangements for cube-corner microreplication.
Among Asia-Pacific-based fabricators, Nippon Carbide Industries Co., Inc. and Changzhou Hua R Sheng Reflective Material Co., Ltd. occupy positions within the glass-bead and specialized film tiers. ORAFOL Europe GmbH anchors the European premium segment. These entities exemplify the geographic distribution of manufacturing capability, with Japanese and Chinese companies representing scale-driven production archetypes and German firms occupying specification-sensitive premium positioning.
| Leading Market Players |
|---|
| Nippon Carbide Industries Co., Inc |
| ALANOD GmbH & Co. KG |
| 3M |
| Daoming Reflective Material India Pvt. Ltd. |
| Coats Group Plc |
| Avery Dennison Corporation |
| Changzhou Hua R Sheng Reflective Material Co., Ltd |
| Reflomax |
| ORAFOL Europe GmbH |
| Others |
Cost & Logistics Intelligence
Jiangsu province's concentrated microprismatic film capacity grants domestic Chinese manufacturers substantial leverage over export pricing into Southeast Asian and African markets. ECE R104-certified European converters command premium positioning against this backdrop, while glass-bead processors in emerging economies compete on unit economics for municipal road marking tenders.
Pricing Analysis
ECE R104 dictates the pricing tier structure across European commercial vehicle marking applications, separating certified contour films from uncertified alternatives. Three-tier pricing structure across premium microprismatic, standard glass-bead, and economy uncoated bead tiers reflects certification grade and photometric longevity. Pricing pressure stems from propylene feedstock volatility squeezing acrylic resin costs for film converters. Fleet operators exhibit highest price sensitivity on replacement cycles, while government highway agencies prioritize warranty terms over unit cost.
Supply Chain Analysis
Precision microreplication tooling vendors in Taiwan, Japan, and Germany hold captive capacity for cube-corner master rolls. Raw material flows draw from optical-grade polycarbonate feedstock in South Korea, Germany, and the United States, alongside soda-lime glass sphere supply from China and Egypt. Single-source vulnerability concentrates in specialized embossing equipment for microprismatic geometries. Distribution runs through qualified converter networks for certified films, with commodity beads flowing through industrial chemical distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Retro reflective materials constitute a regulatory-moat market where ECE R104, NHTSA FMVSS, and GB standard compliance creates entrenched supplier relationships with multi-year qualification cycles. Switching costs for transportation agencies and fleet operators elevate incumbent durability.
For Market Incumbents: Entrench through backward integration into optical-grade polymer supply and captive microreplication tooling capacity in East Asian manufacturing clusters. Glass-bead specialists from emerging markets threaten margin compression in road marking segments; defend through specification-engineering partnerships with state departments of transportation and certification body co-development of next-generation photometric protocols. For New Entrants and Emerging Players: India's state road development corporations tendering National Highway signage represent the most penetrable entry point for qualified film converters, given phased installation schedules and BIS certification pathways opening to foreign suppliers. Construction sector high-visibility apparel mandates in Latin American jurisdictions offer secondary white-space with lower regulatory barriers. Go-to-market through technical field-service partnerships with regional safety equipment distributors accelerates specification access. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors precision microprismatic specialists with established cube-corner IP and automotive type-approval portfolios over commodity bead processors. Long-term viability hinges on regulatory convergence toward higher photometric thresholds and smart infrastructure integration capabilities. Monitor ECE R104 revision timelines and China's GB standard update cadence as inflection indicators for certification-driven replacement demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Optical Polymer Supply | Captive polycarbonate sourcing from South Korean petrochemical complexes secures margin control against resin volatility. |
| Microreplication Tooling Capacity Expansion | In-house cube-corner master roll production in Taiwan or Japan reduces dependency on single-source equipment vendors. |
| Smart Infrastructure Certification Partnership | Collaboration with Nordic transportation agencies on RFID-embedded sheeting opens asset-tracking revenue streams. |
| Emerging Market Glass-Bead Processing Scale-Up | Expanded soda-lime sphere capacity in Egypt or India captures municipal thermoplastic marking demand. |
| Multi-Standard Compliance Platform Investment | Parallel ASTM, EN, and GB testing infrastructure accelerates time-to-market across regional procurement channels. |
Research Approach
Desk research of customs trade databases, transportation agency procurement records, and regulatory filing repositories preceded structured interviews with reflective film plant managers, highway agency specification engineers, commercial fleet procurement directors, and certification laboratory technical leads. Primary fieldwork combined with secondary validation against ECE R104 type-approval databases, NHTSA FMVSS compliance listings, and Chinese GB standard revision notices. Bottom-up volume modeling triangulated against top-down macroeconomic indicators across the analysis window.
Forecast assumptions held fixed the regulatory enforcement intensity of ECE R104, NHTSA, and GB mandates while varying infrastructure investment trajectories and petrochemical input cost scenarios. Segmentation dimensions modeled include product format, application vertical, material substrate, and end-user procurement channel. CAGRs were derived from regression analysis of historical procurement volumes against explanatory variables including highway mileage expansion, commercial vehicle fleet turnover rates, and occupational safety code adoption patterns. Photometric performance ceiling constraints and REACH substance restriction timelines informed technology displacement assumptions.
Practitioners should monitor ECE R104 revision consultations, China's MIIT directive updates, and NHTSA rulemaking notices for early signals of compliance-driven demand inflection. Forecasts reflect documented assumptions regarding regulatory enforcement continuity and raw material supply stability. Quarterly review of provincial transportation bureau tender announcements and petrochemical feedstock price indices is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Materials
Specialty Polyamides Market
Specialty Materials
Crusher Backing Materials Market
Specialty Materials
Vegan Wax Market
Specialty Materials
Methyl Silicone Market
Specialty Materials
APAC Fluoroelastomer Market
Specialty Materials
Advanced Green Septa Market
Specialty Materials
Vulcanized Fiber Market
Specialty Materials
Polyimide Films Market
Specialty Materials
Cellulose Derivative Excipient Market
Specialty Materials
Europe Microspheres Market
Specialty Materials
Global Consumer Foam Market
Specialty Materials
Specialty Silicone Market
Specialty Materials
Melamine Foam Market
Specialty Materials
Talc Alternatives Market
Specialty Materials
Shape Memory Polymer Market
Specialty Materials
Asia-Pacific Colloidal Silica Market