
 Oncolytic Adenovirus Market | 2026-2036
Oncolytic Adenovirus Market Size, Share, and Industry Trends Forecast 2026-2036
Oncolytic Adenovirus Market Analytics
The EU Green Deal's pharmaceutical sustainability benchmarks are realigning manufacturing priorities across European biologics production. Amgen leverages its established viral vector infrastructure to sustain commercial-scale supply of engineered adenovirus therapies. Transgene SA anchors its development pipeline in region-specific oncology indications, while Replimune differentiates through systemic delivery platforms that extend beyond intratumoral administration.
Oncolytic adenovirus denotes a genetically modified adenoviral vector engineered to selectively replicate in tumor cells with compromised p53 or Rb pathways, typically featuring E1A or E1B gene deletions that restrict replication to neoplastic tissue. These vectors deliver therapeutic transgenes that stimulate antitumor immunity through dendritic cell activation and cytotoxic T-lymphocyte recruitment. Therapy area segmentation shows pancreatic cancer applications attracting concentrated R&D investment due to limited effective alternatives, while breast cancer indications occupy the most mature clinical trial landscape. Delivery mode segmentation reveals intratumoral injection dominating current approved applications, though intravenous administration platforms represent the fastest-growing vector engineering priority.
FDA oversees investigational new drug applications and biologics license approvals through its Center for Biologics Evaluation and Research, enforcing potency and purity standards that shape manufacturing investment requirements. EMA's Committee for Advanced Therapies coordinates centralized assessments for gene therapy medicinal products across EU member states, creating divergent market access timelines relative to US pathways. China's NMPA has accelerated cell and gene therapy review procedures under its breakthrough therapy designation framework. Stakeholders must monitor evolving comparability protocols for viral vector critical quality attributes as regulatory convergence between FDA, EMA, and NMPA remains incomplete.
Market Dynamics
FDA breakthrough therapy designation pathways compress development timelines for engineered adenovirus candidates, while academic medical centers in the United States expand adoptive cell therapy programs incorporating oncolytic vectors. This regulatory acceleration collides with manufacturing capacity constraints across viral vector production.
Growth Catalysts
- Immuno-oncology infrastructure expansion:Academic medical centers in the United States, China, and Germany are building dedicated oncolytic virus manufacturing suites to support first-in-human trials.
- EMA centralized assessment framework:The Committee for Advanced Therapies streamlines gene therapy medicinal product evaluations across EU member states, reducing redundant national filings.
- Intravenous delivery platform maturation:Systemic administration engineering priorities are attracting venture funding beyond traditional intratumoral injection modalities.
Market Restraints
- Plasmid DNA supply concentration:Critical raw material production clusters in a limited number of contract manufacturing organizations, creating single-source vulnerability for viral vector builders.
- EMA-FDA comparability protocol divergence:Incomplete regulatory convergence on critical quality attributes forces duplicate analytical method development and extended validation timelines.
- Autologous cell therapy competition:CAR-T platforms command overlapping investigator attention and manufacturing slot allocation at academic medical centers.
Strategic Opportunities
- China NMPA accelerated review:The breakthrough therapy designation framework for cell and gene therapies offers compressed approval pathways for multinational sponsors establishing local partnerships.
- Pancreatic cancer indication white space:Limited effective therapeutic alternatives create favorable reimbursement positioning for first-to-market oncolytic adenovirus candidates.
- CRISPR-enhanced vector engineering:Convergence of gene editing precision with adenoviral backbone modification enables next-generation tumor selectivity mechanisms.
Industry Challenges
- Bioprocess engineering talent scarcity:Viral vector upstream and downstream optimization requires specialized expertise that outpaces current training program output.
- Containment facility capex intensity:Biosafety level requirements for replication-competent oncolytic agents demand capital investment levels that strain mid-tier development-stage companies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oncolytic Adenovirus Market |
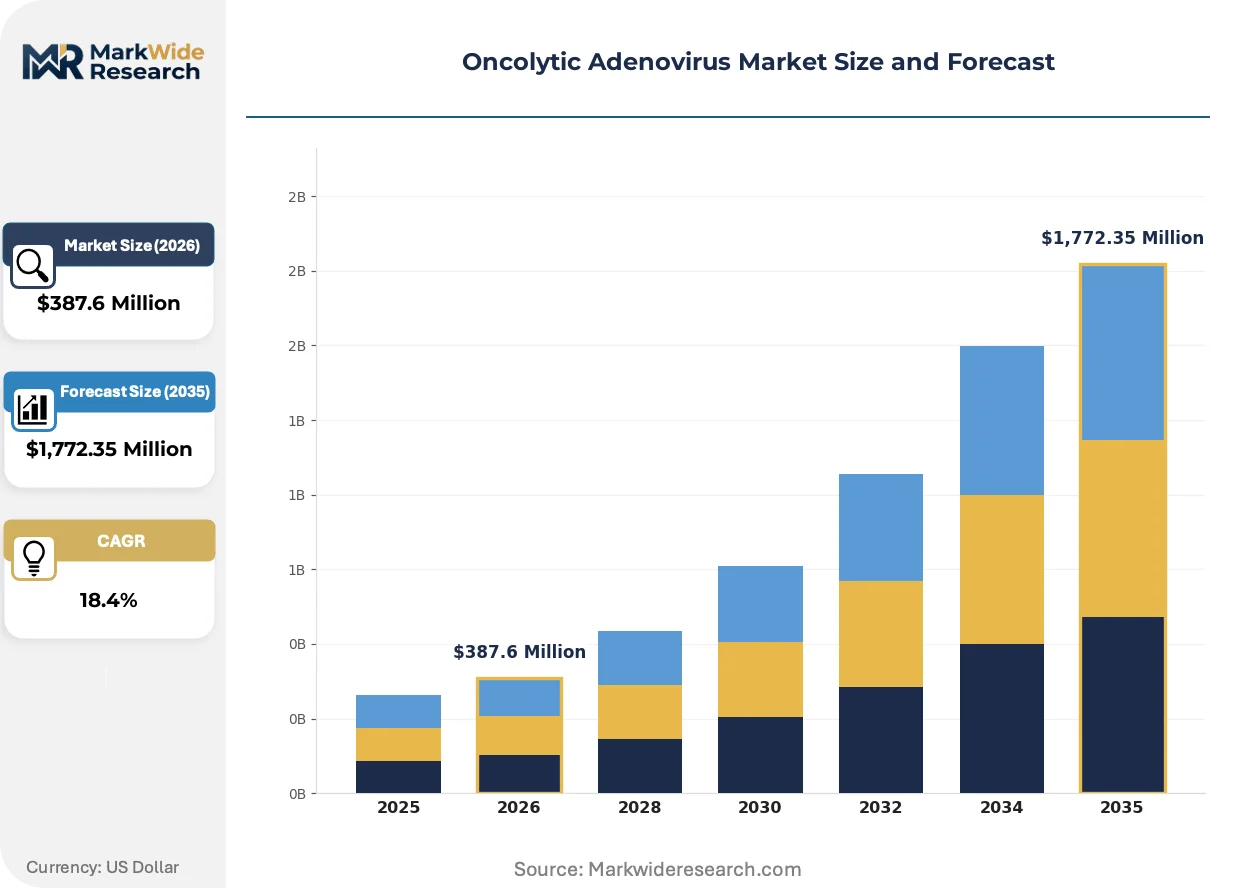
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $1,772.35 Million |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Talimogene LahERparepvec, ONCOS-102, CG0070, Pexa-Vec Therapy Area: Breast Cancer, Colorectal Cancer, Prostate Cancer, Pancreatic Cancer Delivery Mode: Intratumoral Injection, Intravenous Injection, Combination Therapy, Localized Treatment End User: Hospitals, Research Labs, Cancer Treatment Centers, Pharmaceutical Companies |
| Companies Covered | Amgen, Oncolytics Biotech, Sorrento Therapeutics, Transgene SA, Targovax, Replimune, TILT Biotherapeutics, Lokon Pharma, Vyriad, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oncolytic Adenovirus Market Evolving Landscape
Vector engineering priorities are pivoting toward systemic delivery platforms that bypass intratumoral administration limitations. This shift demands new manufacturing scale-up paradigms and analytical characterization methods.
Armed oncolytic adenovirus constructs encoding immunostimulatory cytokines are converging with checkpoint inhibitor combination protocols in late-stage trial design. Immuno-oncology investigators at major academic centers are adopting these vectors as backbone therapies for combination arms. The structural consequence is compression of traditional monotherapy development timelines as sponsors pursue accelerated approval pathways based on early combination data.
EU Green Deal pharmaceutical sustainability benchmarks are realigning manufacturing priorities across European biologics production. EMA's updated environmental risk assessment guidelines for gene therapy medicinal products now require carbon footprint documentation in marketing authorization applications. Viral vector manufacturers with existing single-use disposable infrastructure face retrofit investment decisions to comply with circular economy targets.
Hospital procurement departments are consolidating oncolytic virus sourcing through centralized pharmacy and therapeutics committees. Academic medical centers with established cell therapy programs are negotiating multi-year supply agreements that bundle vector manufacturing with clinical trial participation rights. This concentration is most visible in the United States, where three institutional procurement networks now control a majority of phase I/II site activation decisions for novel oncolytic candidates.
Oncolytic Adenovirus Market Segmentation
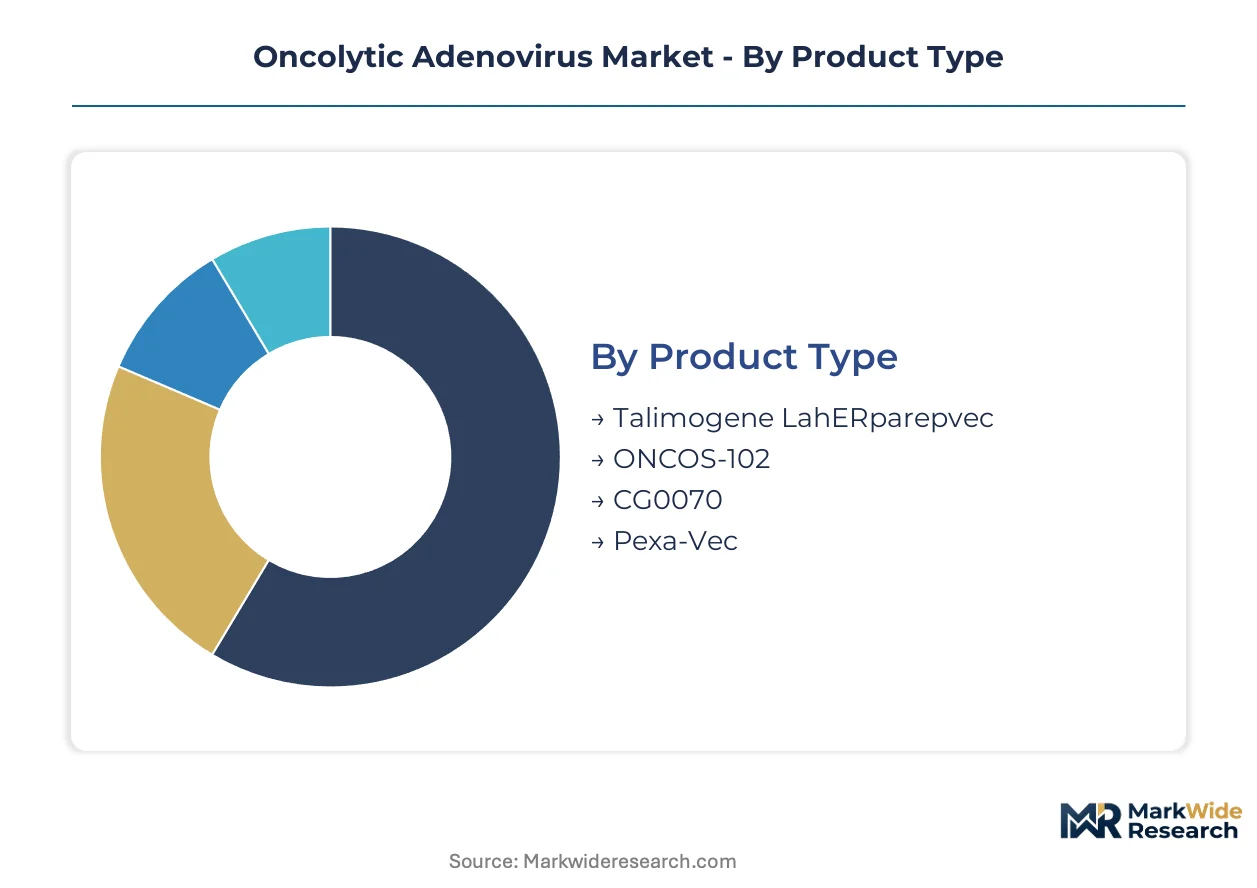
Segmentation in oncolytic adenovirus markets reveals how regulatory pathways, clinical infrastructure, and vector engineering priorities reshape competitive positioning across distinct product configurations. Each dimension carries specific FDA, EMA, or NMPA certification burdens that determine manufacturing investment requirements and market access timelines.
Product Type:
Talimogene LahERparepvec carries FDA breakthrough therapy designation precedent that shapes approval pathway expectations for engineered adenovirus candidates. ONCOS-102, CG0070, and Pexa-Vec each navigate distinct CMC review intensities based on transgene payload complexity and replication competence profiles.
- Talimogene LahERparepvec:The first FDA-approved oncolytic viral therapy establishes manufacturing quality benchmarks that subsequent adenovirus candidates must meet. Demand concentrates in United States melanoma treatment centers where immuno-oncology infrastructure supports intratumoral administration protocols.
- ONCOS-102:An armed adenovirus encoding GM-CSF that stimulates systemic antitumor immunity through dendritic cell maturation. Clinical trial density in Germany and Nordic academic medical centers drives European development prioritization.
- CG0070:Selectively replicates in Rb pathway-deficient tumor cells with E2F-1 promoter control, targeting bladder cancer indications.
- Pexa-Vec:Thymidine kinase-deleted vaccinia-based vector with demonstrated hepatocellular carcinoma activity, though manufacturing complexity limits scale-up.
Talimogene LahERparepvec sits at the top of the volume ranking, with ONCOS-102 climbing the fastest.
Therapy Area:
Clinical indication selection determines trial design complexity, comparator therapy availability, and reimbursement negotiation leverage across oncology subtypes.
- Pancreatic Cancer:Desmoplastic stroma and limited vascular access create unique delivery challenges that favor intratumoral injection platforms. Research investment concentrates at MD Anderson Cancer Center and German Cancer Research Center where dedicated oncolytic virus programs address this high-unmet-need population.
- Breast Cancer:The most mature clinical trial landscape for oncolytic adenovirus with established immunotherapy combination protocols. Trial activation at Dana-Farber Cancer Institute and Memorial Sloan Kettering supports rapid patient enrollment for novel vectors.
- Colorectal Cancer:Microsatellite instability subtyping enables biomarker-driven patient selection for checkpoint inhibitor combinations.
- Prostate Cancer:Bone-dominant metastasis patterns complicate intratumoral delivery, driving systemic administration engineering priorities.
Breast Cancer captures the largest current trial footprint, with Pancreatic Cancer gaining share fastest.
Delivery Mode:
Administration route selection shapes manufacturing scale requirements, analytical characterization methods, and distribution cold chain specifications.
- Intravenous Injection:Systemic delivery platforms require capsid engineering to evade neutralizing antibodies and hepatocyte sequestration. Venture funding from Flagship Pioneering and similar investors targets this modality as the frontier for dose escalation and repeat administration.
- Intratumoral Injection:Dominates approved applications with established interventional radiology workflows at major cancer centers. United States academic medical centers maintain the highest concentration of trained administrators.
- Combination Therapy:Checkpoint inhibitor pairing protocols compress traditional monotherapy development timelines.
- Localized Treatment:Isolated limb perfusion and intravesical instillation address anatomically constrained tumor presentations.
Intratumoral Injection retains the highest procedure volume, with Intravenous Injection expanding most quickly.
End User:
Customer type determines procurement scale, technical support requirements, and vector customization specifications across the value chain.
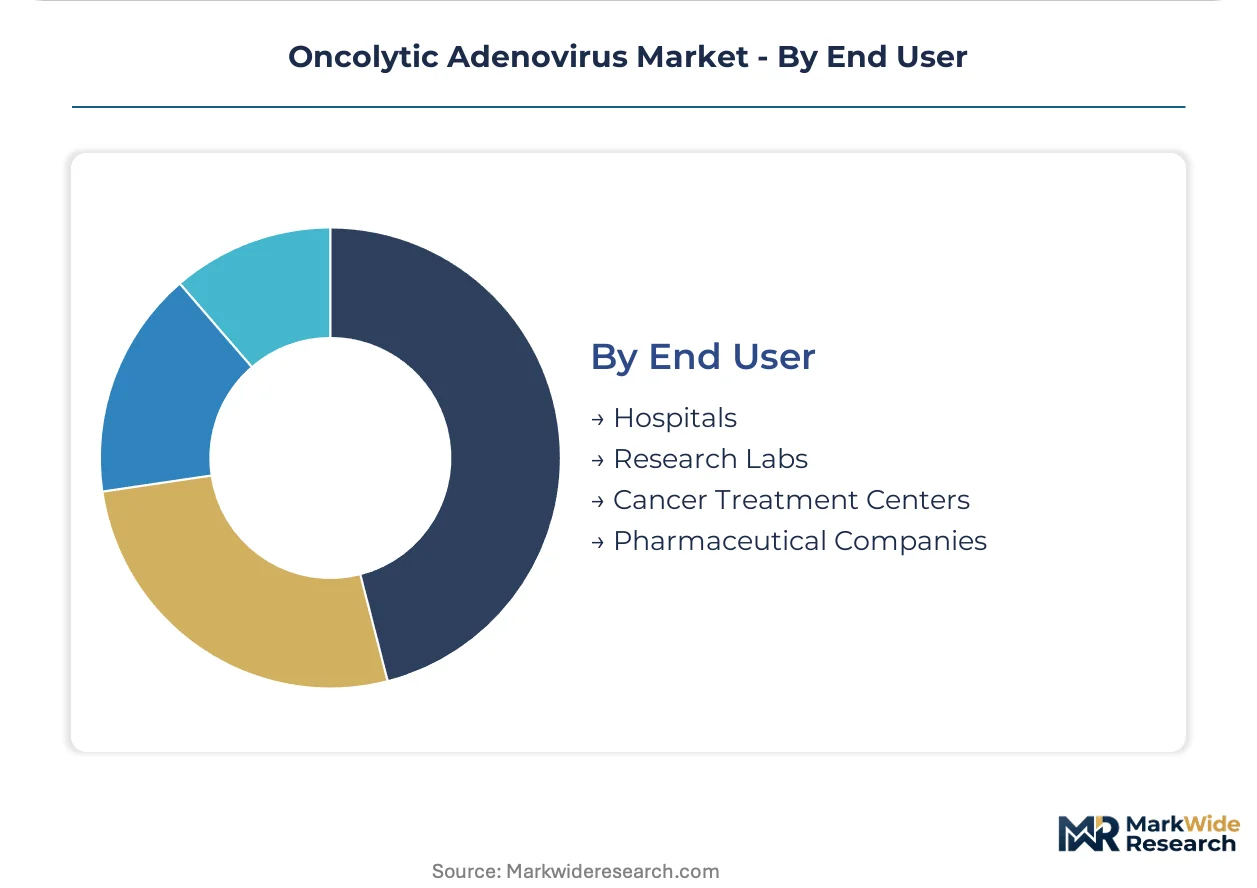
- Cancer Treatment Centers:Dedicated immuno-oncology programs at centers like University of Texas Southwestern and Heidelberg University Hospital negotiate bundled supply agreements that combine vector manufacturing with clinical trial participation rights.
- Hospitals:Centralized pharmacy and therapeutics committees consolidate oncolytic virus sourcing through multi-year procurement frameworks. Three institutional networks in the United States now control majority phase I/II site activation decisions.
- Research Labs:Preclinical vector characterization and mechanism-of-study studies require small-batch, high-titer production.
- Pharmaceutical Companies:In-licensing and partnership structures for late-stage development candidates.
Hospitals anchor procurement volume, with Cancer Treatment Centers accelerating fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized immuno-oncology talent clusters in the United States, Germany, and China anchor the geographic distribution of oncolytic adenovirus development. These workforce concentrations concentrate clinical trial activation, manufacturing investment, and regulatory expertise in distinct metropolitan corridors.
United States
Academic medical centers at MD Anderson Cancer Center, Memorial Sloan Kettering, and Dana-Farber Cancer Institute drive investigator-initiated trial density. FDA breakthrough therapy designation pathways compress development timelines for engineered adenovirus candidates. The Greater Boston corridor hosts Replimune and other vector engineering specialists advancing systemic delivery platforms.
Germany
The German Cancer Research Center and Heidelberg University Hospital anchor European oncolytic virus program concentration. EMA's Committee for Advanced Therapies streamlines centralized assessments for gene therapy medicinal products across EU member states. The Rhine-Main biotech cluster supports Transgene SA's regional development pipeline through dedicated manufacturing partnerships.
China
NMPA accelerated review procedures under the breakthrough therapy designation framework attract multinational sponsor partnerships. Shanghai and Beijing academic medical centers expand adoptive cell therapy programs incorporating oncolytic vectors. Yangtze River Delta biotech parks concentrate viral vector contract manufacturing capacity for domestic and export supply.
United Kingdom
London and Cambridge immuno-oncology research institutes maintain active oncolytic virus investigator networks. MHRA post-Brexit regulatory autonomy enables tailored assessment pathways for advanced therapy medicinal products. The Oxford-Cambridge-London golden triangle concentrates early-stage vector engineering startups and venture funding.
Japan
PMDA's regenerative medicine and gene therapy review framework supports conditional approval pathways for novel oncolytic candidates. Tokyo and Osaka academic medical centers participate in multinational combination therapy protocols with checkpoint inhibitors. Kanto region bioclusters host specialized viral vector analytical testing services for Asia-Pacific market access.
Oncolytic Adenovirus Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the oncolytic adenovirus value chain. Viral vector manufacturing suites demand biosafety containment infrastructure that concentrates production among established biologics players. Three archetypes define competitive positioning: integrated pharmaceutical conglomerates with existing viral vector infrastructure, dedicated oncolytic virus platform companies, and academic spin-outs advancing novel engineering approaches. Dominant competitive moves include strategic partnerships for manufacturing capacity access and in-licensing of regional development rights for late-stage candidates.
Among integrated biopharmaceutical developers, Amgen leverages established viral vector infrastructure to sustain commercial-scale supply. Transgene SA anchors its development pipeline in region-specific oncology indications through European academic partnerships. Replimune occupies a position at the systemic delivery frontier, differentiating through intravenous administration platforms that extend beyond traditional intratumoral injection modalities.
| Leading Market Players |
|---|
| Amgen |
| Oncolytics Biotech |
| Sorrento Therapeutics |
| Transgene SA |
| Targovax |
| Replimune |
| TILT Biotherapeutics |
| Lokon Pharma |
| Vyriad |
| Others |
Value Network & Pricing Analysis
Vector-grade certification divergence between GMP-compliant clinical manufacturing and research-use-only production splits pricing power across supplier tiers, with FDA-inspected facilities commanding premiums that reflect both quality assurance overhead and captive plasmid DNA sourcing requirements. This bifurcation concentrates procurement decisions at academic medical centers that bundle vector manufacturing with trial participation rights, while mid-tier developers face margin compression from biosafety containment capital intensity.
Pricing Analysis
Bundled service contracts that combine vector manufacturing with clinical site activation dominate pricing structures for cancer treatment centers, while unbundled per-batch transactions persist for research laboratories. Price differentiation rests on GMP certification tier and regional delivery logistics, with United States-based production carrying freight and cold-chain premiums. Pricing pressure intensifies as hospital procurement committees consolidate vendor panels and demand multi-year volume commitments. Research laboratories exhibit highest price sensitivity due to grant-funded budget constraints, whereas integrated pharmaceutical developers prioritize supply security over unit cost.
Supply Chain Analysis
Domestic-content mandates under China's NMPA breakthrough therapy framework and United States biosecurity provisions are reshaping viral vector sourcing toward regional manufacturing footprints. Plasmid DNA production concentrates in the United States, China, and Germany, with contract manufacturing organizations anchoring critical raw material supply. The supply chain draws from specialized cell banks, serum-free media formulations, and single-use bioreactor components. Single-source vulnerability in plasmid DNA creates structural risk exposure for developers without captive supply arrangements. Distribution runs through controlled-temperature logistics networks terminating at hospital pharmacy and therapeutics committees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Oncolytic adenovirus markets function as regulatory compounders where FDA breakthrough therapy designation pathways and EMA centralized assessments accelerate demand formation for engineered vector candidates. This regulatory architecture rewards manufacturing readiness and quality system maturity over pure R&D velocity.
For Market Incumbents: Deepen backward integration into plasmid DNA production to neutralize single-source supply vulnerability and capture margin compression from contract manufacturing fee escalation. Fortify GMP facility networks in the United States and Germany to defend against emerging Chinese biosecurity-driven localization requirements. Prioritize biosafety level containment capacity expansion at existing sites rather than greenfield development to preserve capital efficiency. For New Entrants and Emerging Players: Launch via strategic partnerships with established academic medical centers that bundle vector manufacturing with clinical trial participation rights, bypassing capital-intensive captive production requirements. Target pancreatic cancer indications where limited therapeutic alternatives create favorable reimbursement positioning and compressed competitive timelines. Exploit intravenous delivery platform white space through capsid engineering specialization that distinguishes from intratumoral injection incumbents. For Investors and Strategic Acquirers: Consolidation pressure builds where manufacturing scale requirements outpace mid-tier development-stage capital access, particularly for candidates approaching phase I/II transitions. Long-term viability favors platform companies with systemic delivery capabilities and checkpoint inhibitor combination protocols. Acquisition target archetypes include armed adenovirus developers with validated tumor selectivity mechanisms and regional partnership structures in China or Germany. Watch NMPA approval velocity for multinational sponsors as inflection indicator for geographic demand redistribution.| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | GMP facility expansion at Amgen and Replimune secures commercial supply for breakthrough-designated candidates. |
| Regulatory Approval Pathway | FDA breakthrough therapy submissions compress development timelines for ONCOS-102 and CG0070. |
| Licensing Agreement | Transgene SA's European academic partnerships anchor region-specific oncology indication development. |
| Clinical Trial Advancement | Combination therapy protocols with checkpoint inhibitors accelerate patient enrollment at Dana-Farber and MD Anderson. |
| Pipeline Diversification | CRISPR-enhanced vector engineering programs address pancreatic and prostate cancer white spaces. |
Research Methodology
Coverage spans the United States, China, Germany, and the United Kingdom, with primary inputs from each jurisdiction informing demand modeling and regulatory pathway assessment. The analysis combines structured interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and formulary directors with secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov records, and hospital procurement databases. Bottom-up patient population estimates and top-down manufacturer capacity assessments undergo triangulation to anchor volume projections.
Rate-of-change decomposition separates volume drivers from price evolution across the projection horizon, with analytical frameworks modeling therapy area segmentation, delivery mode adoption curves, and end-user procurement consolidation. CAGRs derive from segmented growth rate blending rather than single-point extrapolation. Forecast inputs incorporate regulatory approval velocity assumptions, manufacturing capacity expansion timelines, and immuno-oncology infrastructure buildout rates at academic medical centers.
Forecast precision tightens around the base case; tail outcomes carry wider variance under regulatory divergence scenarios or plasmid DNA supply disruption conditions. Projections reflect assumptions regarding FDA-EMA-NMPA convergence timelines, vector engineering platform maturation rates, and checkpoint inhibitor combination protocol adoption. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cell & Gene Therapy
Cell and Gene Therapy CDMO Market
Cell & Gene Therapy
Oncolytic Virus Immunotherapy Market
Cell & Gene Therapy
Automated and Closed Cell Therapy Processing Systems Market
Cell & Gene Therapy
Oncolytic Virus Therapy Market
Cell & Gene Therapy
Retinal Gene Therapy Market
Cell & Gene Therapy
MRNA Therapeutics Contract Development and Manufacturing Organization Market
Cell & Gene Therapy
T Cell Therapy Market
Cell & Gene Therapy
B Cell Maturation Antigen Targeted Therapy Market
Cell & Gene Therapy
Global Neoantigen Cancer Vaccine Market
Cell & Gene Therapy
Stem Cell Concentration System Market
Cell & Gene Therapy
Gene Delivery Technologies Market
Cell & Gene Therapy
Global Gene Delivery Systems Market
Cell & Gene Therapy
Neoantigen Targeted Therapies Market
Cell & Gene Therapy
Global Dendritic Cell Cancer Vaccines Market
Cell & Gene Therapy
Cell Regeneration Medicine Market
Cell & Gene Therapy
Lentiviral Vector Contract Development and Manufacturing Organizations Market